
 Marine Pump Market | 2026-2036
Marine Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Pump Market Foresight
Modular pump skids is expanding as shipyards and fleet operators standardize pre-integrated packages over standalone component procurement. Alfa Laval leverages its heat-transfer heritage to bundle pumping with thermal-management systems for engine rooms. KSB sustains a broad centrifugal portfolio that anchors its presence in European commercial-ship newbuild programs. DESMI specializes in compact positive-displacement configurations for naval and offshore patrol platforms.
A marine pump is a fluid-handling device engineered to withstand saltwater corrosion, vessel vibration, and space-constrained machinery rooms, typically constructed from duplex stainless steel or nickel-aluminum bronze with pressure ratings exceeding 10 bar for critical bilge and ballast duties. Its primary purpose is to move seawater, fuel, lubricants, or wastewater through a ship's piping network under variable head conditions while meeting classification-society safety margins. Centrifugal pumps occupy the largest installed base across cargo and tanker fleets due to their flow-rate efficiency at moderate pressures. Positive displacement pumps command premium positioning in fuel-transfer and viscous-fluid applications where precise metering overrides energy optimization. Submersible configurations represent the fastest-growing installation type as shipyards adopt below-deck immersion to save machinery-space footprint and reduce cavitation risk.
Classification societies including Lloyd's Register, DNV, and the American Bureau of Shipping enforce pump-performance testing and material-certification rules that gate market access for unapproved suppliers. The International Maritime Organization's MARPOL Annex VI and the EU MRV regulation shape demand for energy-recovery and variable-speed pump drives that cut fuel consumption. The US Coast Guard and EPA jointly regulate bilge-water treatment discharge limits, pushing owners toward higher-specification oily-water separator pumps. Stakeholders must weigh retrofit-cycle timing against pending efficiency mandates when sizing inventory and service-network investments.
Market Dynamics
The IMO 2023 Energy Efficiency Existing Ship Index is compressing pump replacement cycles as owners retrofit vessels to avoid carbon-intensity penalties, forcing capital allocation toward high-efficiency variable-speed drives and integrated thermal-management packages.
Growth Catalysts
- Commercial vessel newbuild programs:China, South Korea, and Japan dominate shipbuilding output, concentrating demand for centrifugal and positive-displacement pumping systems in Asian yards.
- MARPOL Annex VI enforcement:The International Maritime Organization's sulfur and carbon regulations tighten operational margins, compelling fleet operators to upgrade to energy-recovery pump drives.
- Submersible pump immersion:Below-deck installation configurations save machinery-space footprint and reduce cavitation risk, accelerating adoption across tanker and cargo fleets.
Market Restraints
- Nickel-aluminum bronze price volatility:Raw material costs for corrosion-resistant pump housings fluctuate with mining output and trade policy, compressing margins for European and Asian fabricators.
- Classification society concentration:Lloyd's Register, DNV, and the American Bureau of Shipping control certification gates, creating bottlenecks for unapproved suppliers seeking market entry.
- Positive-displacement energy penalty:These pumps sacrifice efficiency for metering precision, limiting their addressable market against advancing centrifugal designs in moderate-pressure applications.
Strategic Opportunities
- EU Green Deal vessel retrofits:European Union decarbonization incentives fund pump upgrades on existing fleets, opening service-contract revenue for integrated thermal-management providers.
- Modular skid standardization:Pre-integrated pump packages displace standalone component procurement, allowing suppliers to capture margin from shipyard labor outsourcing.
- Offshore patrol platform specialization:Naval and coast-guard contracts for compact positive-displacement configurations offer premium pricing insulated from commercial-ship cyclicality.
Industry Challenges
- Classification certification timelines:Lloyd's Register and DNV testing protocols extend product launch schedules, delaying revenue recognition for new pump designs.
- Legacy piping integration:Retrofit installations must mate with existing vessel architectures, raising engineering costs and failure-risk exposure for pump OEMs.
- Specialized metallurgy skills:Duplex stainless steel and nickel-aluminum bronze welding expertise concentrates in mature maritime labor markets, constraining production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Pump Market |
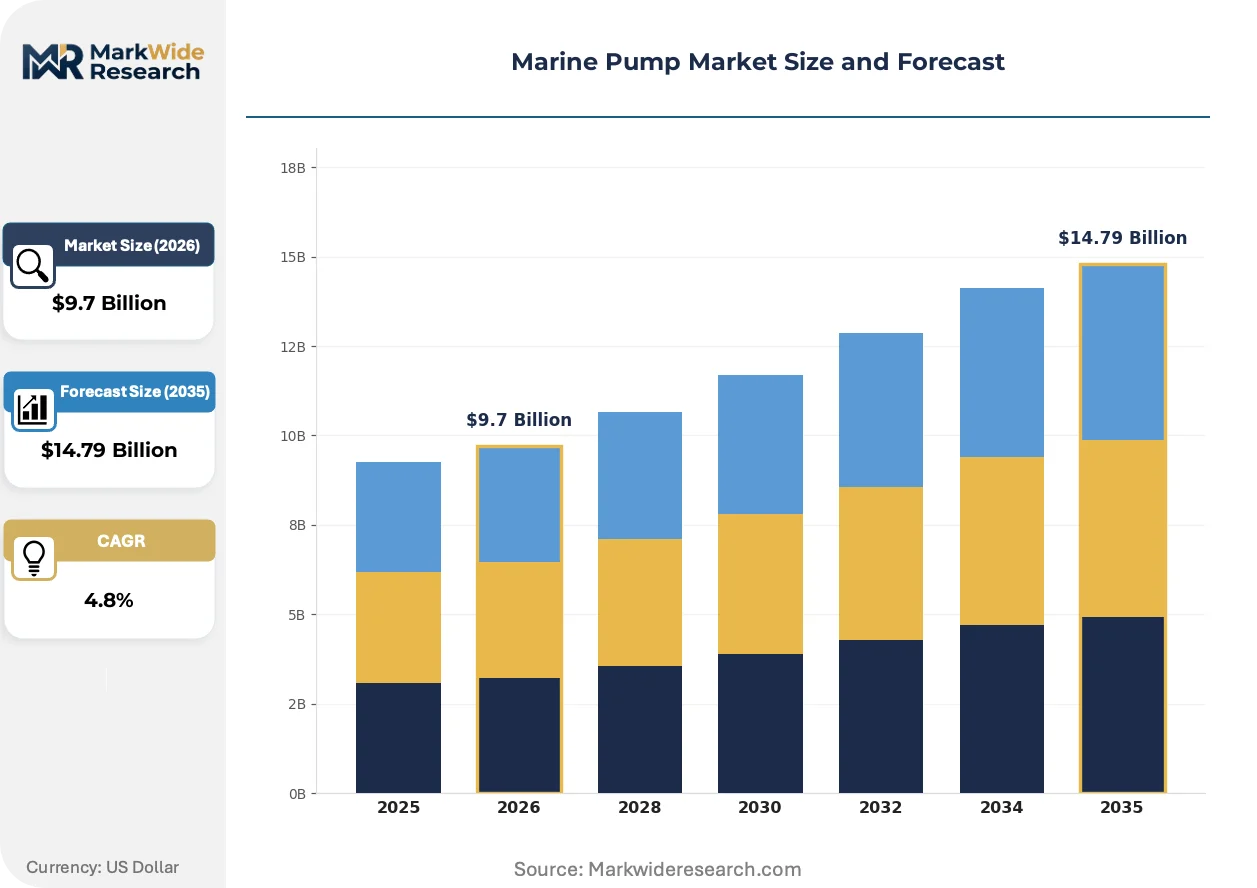
| Market Size in 2026 | $9.7 Billion |
| Market Size in 2035 | $14.79 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Positive Displacement Pumps, Submersible Pumps, Bilge Pumps Application: Ballast, Fuel Transfer, Sewage, Fire Fighting End User: Commercial Vessels, Recreational Boats, Oil Tankers, Navy Ships Installation Type: Onboard, Offshore, Dry Dock, Modular |
| Companies Covered | Grundfos, DESMI, KSB, Sulzer, Flowserve, WILO, Ebara, Pentair, Alfa Laval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Pump Market Shifts & Advancements
Digital pump monitoring and variable-frequency drive integration are compressing the performance gap between mechanical and electronically controlled fluid-handling systems across commercial fleets.
Variable-frequency drive technology is consolidating control over pump motor speed to match real-time demand curves, cutting energy consumption in ballast and cooling circuits. Container-ship operators in North European trades are retrofitting existing centrifugal installations with VFD packages to meet EU MRV reporting thresholds. This consolidation is marginalizing fixed-speed pump configurations in newbuild specifications.
The International Maritime Organization's carbon-intensity indicator framework tightens annually, compelling owners to document pump energy consumption as part of vessel efficiency ratings. Shipyards in South Korea now bundle pump performance data into digital twin deliverables for classification review. Tanker fleets operating on long-haul routes face the steepest compliance gradients and are prioritizing pump upgrades in retrofit schedules.
Fleet operators are unbundling pump procurement from shipyard turnkey contracts, establishing direct supplier relationships for lifecycle service and spare-part availability. This disintermediation shifts margin from yard integrators to component OEMs with global service networks. The pattern is most advanced among German and Greek tanker owners managing dispersed vessel portfolios.
Marine Pump Market Segmentation
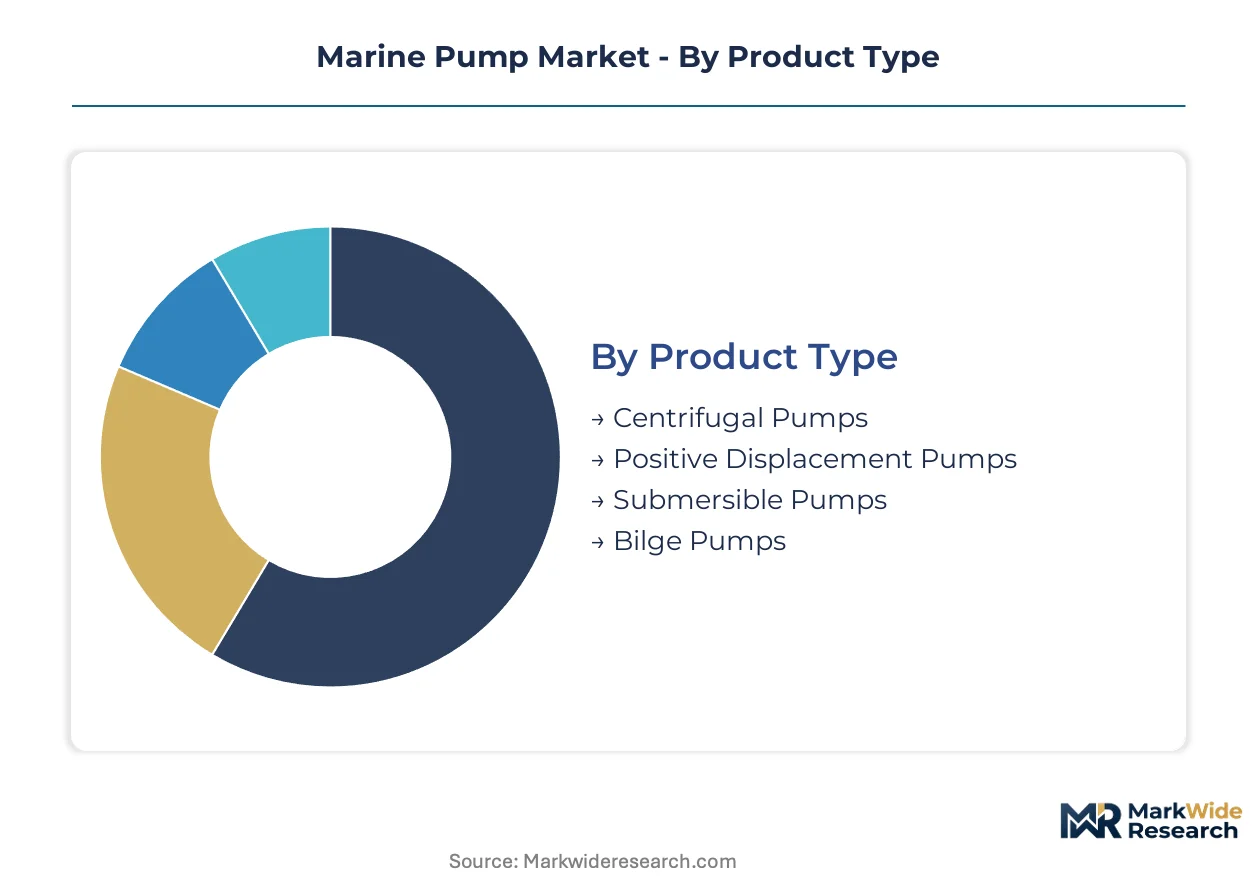
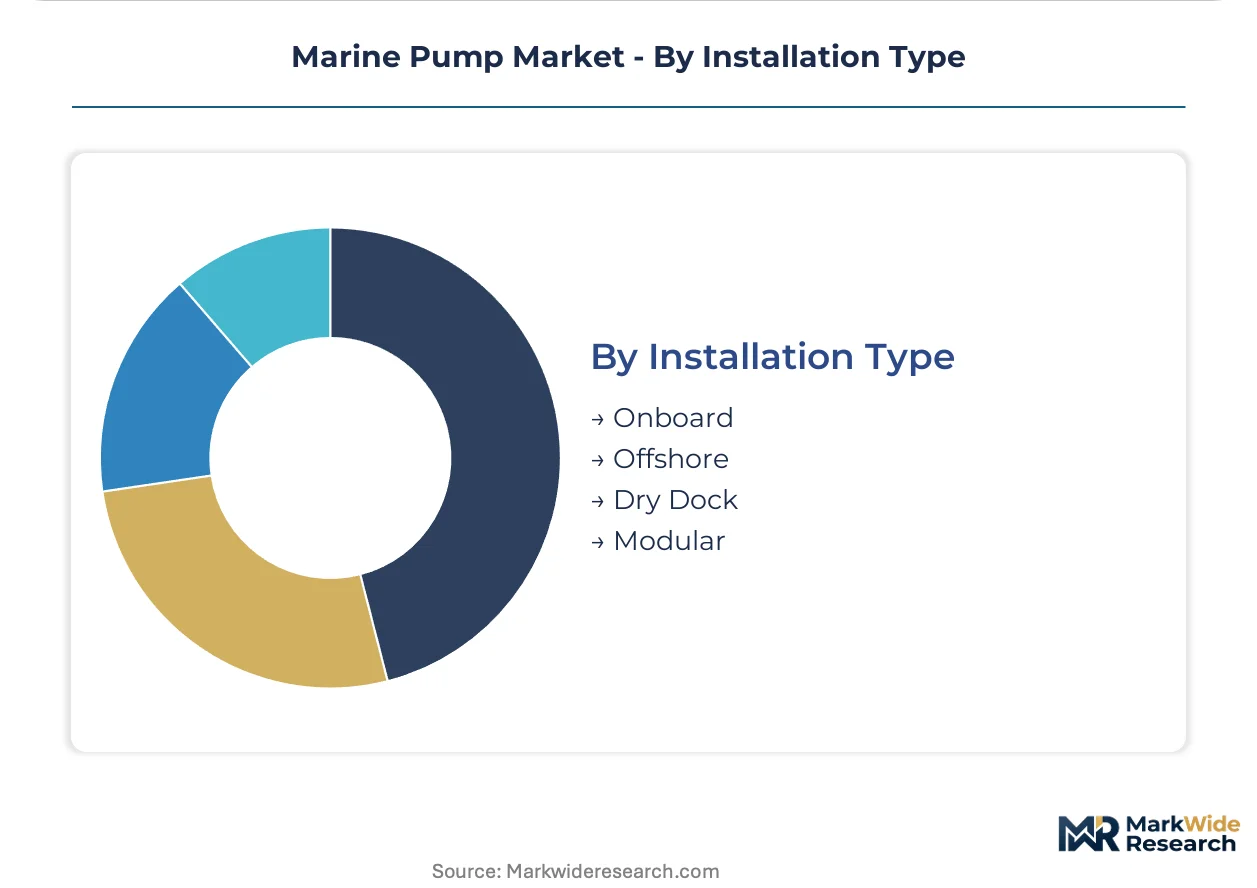
Marine pump segmentation reveals distinct procurement patterns between standalone component sales and pre-integrated system packages. Shipyards in South Korea and Japan increasingly specify bundled configurations that compress installation timelines and reduce interface risk.
Product Type:
Centrifugal pumps dominate standalone replacement demand, while positive-displacement and submersible variants embed more frequently into thermal-management skids supplied as complete engine-room modules.
- Centrifugal Pumps:These units employ impeller rotation to generate velocity head conversion for moderate-pressure seawater circulation. Demand clusters in Chinese bulk-carrier newbuilds where flow-rate efficiency outweighs precise metering requirements. Lloyd's Register certification timelines for high-speed variants extend delivery schedules by four to eight weeks.
- Positive Displacement Pumps:Gear, screw, or vane mechanisms trap and displace fixed fluid volumes per revolution for viscous fuel and lubricant transfer. German tanker operators specify these for heavy-fuel-oil bunkering where metering accuracy prevents regulatory penalties under MARPOL Annex VI. The energy-efficiency penalty limits retrofit penetration against advancing centrifugal designs.
- Submersible Pumps:Below-deck immersion configurations from South Korean suppliers eliminate suction lift limitations and reduce machinery-room footprint.
- Bilge Pumps:Compact corrosion-resistant units handle wastewater accumulation in machinery spaces and cargo holds.
Volume placements concentrate in Centrifugal Pumps; the faster expansion belongs to Submersible Pumps.
Application:
Cost-tier stratification separates mission-critical applications commanding premium metallurgy from utility functions tolerating standard duplex stainless specifications.
- Ballast:Seawater intake and discharge systems stabilize vessel trim and structural loading across cargo operations. Chinese shipyards specify high-capacity centrifugal units for Very Large Crude Carriers where rapid ballast exchange cuts port turnaround times. IMO ballast-water management conventions mandate treatment-system integration that elevates pump specification thresholds.
- Fuel Transfer:Precision metering of marine diesel and heavy fuel oil between storage tanks and engine injection systems. Greek tanker fleets prioritize positive-displacement screw pumps for viscous residual fuel handling where thermal tracing maintains flow characteristics. The US Coast Guard inspects fuel-system integrity during port state control examinations.
- Sewage:Macerator and vacuum pump configurations process black and grey water for compliant discharge or holding.
- Fire Fighting:High-pressure centrifugal or positive-displacement units deliver seawater or foam concentrate to deck monitors and sprinkler networks.
Ballast applications anchor replacement volumes; Fuel Transfer commands the steepest specification escalation.
End User:
Customer-type segmentation distinguishes cyclical commercial-fleet procurement from stable naval contracting with divergent payment terms and certification requirements.
- Commercial Vessels:Container ships, bulk carriers, and general cargo operators form the largest addressable base for standard centrifugal and bilge pump configurations. Japanese shipowners operating Panamax fleets have unbundled pump procurement from yard contracts to secure direct OEM service relationships. EU MRV carbon-reporting obligations elevate variable-speed drive penetration in this segment.
- Oil Tankers:Crude and product carriers demand explosion-proof positive-displacement pumps for cargo and tank-cleaning operations. South Korean yards integrate submersible cargo pumps into double-hull tank designs that eliminate deck machinery. Classification society rules for hazardous-zone electrical equipment constrain supplier qualification.
- Recreational Boats:Yacht and small-craft builders source compact DC-powered bilge and freshwater pumps through marine-distribution channels.
- Navy Ships:National defense procurement prioritizes shock-resistant, low-acoustic-signature configurations with extended qualification cycles.
Commercial Vessels generate the highest unit volumes; Oil Tankers drive margin concentration through specialized metallurgy.
Installation Type:
Maturity-stage differentiation separates established onboard replacement practices from emerging modular skid formats that displace field assembly labor.
- Onboard:Traditional machinery-space mounting of standalone pumps with dedicated motor drives and local control panels. European retrofit specialists execute these replacements during scheduled dry-docking in Hamburg and Rotterdam facilities. Legacy piping geometry often necessitates custom adapter fabrication that extends project timelines.
- Modular:Pre-integrated pump skids with mounted motors, controls, and piping manifolds delivered as complete subsystems. Alfa Laval packages these with heat exchangers for engine-room thermal loops, capturing margin from shipyard labor outsourcing. South Korean yards now specify modular ballast-system skids to compress build schedules.
- Offshore:Platform-based installation for floating production and drilling support vessels.
- Dry Dock:Scheduled maintenance-window replacements requiring compressed project execution.
Onboard installation retains volume dominance; Modular formats are climbing the fastest as shipyards outsource integration labor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipbuilding output concentrates in East Asian yards while European and North American demand pulls systems through retrofit channels. This production-consumption divide shapes regional pump procurement patterns. Fleet operators in major trading nations face divergent regulatory timelines for efficiency compliance.
China
Chinese bulk-carrier and container-ship newbuilds dominate global output, concentrating centrifugal pump demand in Shanghai and Jiangsu shipbuilding clusters. The Ministry of Ecology and Environment enforces domestic emission-control areas that elevate pump specification thresholds. Dalian and Guangzhou yards specify high-capacity ballast systems for Very Large Crude Carriers.
South Korea
South Korean shipbuilders integrate submersible cargo pumps into double-hull tank designs that eliminate deck machinery. The Korean Register classification rules constrain supplier qualification for hazardous-zone electrical equipment. Ulsan and Geoje shipbuilding complexes bundle pump performance data into digital twin deliverables for classification review.
Japan
Japanese shipowners operating Panamax fleets have unbundled pump procurement from yard contracts to secure direct OEM service relationships. METI energy-efficiency guidelines shape variable-speed drive penetration in domestic retrofit programs. Nagasaki and Kure shipyards standardize modular ballast-system skids to compress build schedules.
Germany
German tanker operators specify positive-displacement screw pumps for heavy-fuel-oil bunkering where metering accuracy prevents regulatory penalties. The EU Green Deal funds pump upgrades on existing fleets through national decarbonization programs. Hamburg and Bremen harbor facilities execute scheduled dry-dock replacements during compressed maintenance windows.
United States
US Coast Guard and EPA joint regulations on bilge-water treatment discharge limits push owners toward higher-specification oily-water separator pumps. The Jones Act fleet sustains replacement demand through domestic build requirements. Gulf Coast repair yards in Houston and New Orleans handle legacy piping integration challenges during retrofit installations.
Marine Pump Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated thermal-management providers, centrifugal portfolio generalists, and compact positive-displacement specialists. Consolidation pressure operates through shipyard labor outsourcing and modular skid standardization. Geographic expansion and technology licensing represent the dominant competitive vectors for accessing Asian newbuild programs.
Among European diversified industrials, Alfa Laval and KSB occupy positions exemplifying bundled system integration versus broad centrifugal coverage. DESMI anchors the specialist tier focused on naval and offshore patrol configurations. These three names represent distinct strategic postures without exhausting the competitive set.
| Leading Market Players |
|---|
| Grundfos |
| DESMI |
| KSB |
| Sulzer |
| Flowserve |
| WILO |
| Ebara |
| Pentair |
| Alfa Laval |
| Others |
Supply & Pricing Matrix
Fleet operator unbundling of pump procurement from shipyard turnkey contracts is forcing suppliers to absorb integration labor costs while defending aftermarket service margins. This shift compresses upfront equipment pricing while elevating lifecycle contract value.
Pricing Analysis
Margin tightening in standard centrifugal configurations reflects shipyard consolidation in China and South Korea. Three-tier pricing structure across classification-grade premium, fleet-standard, and economy aftermarket tiers separates Lloyd's Register-certified units from uncertified alternatives. Cost-down pressure on modular skid packages accelerates as Japanese yards outsource engine-room integration labor. Commercial vessel operators exhibit highest price sensitivity; naval procurement tolerates premium positioning for shock-resistant specifications.
Supply Chain Analysis
Direct-to-OEM channels handle Asian newbuild demand while European distributors manage retrofit aftermarket flows. Manufacturing concentrates in China, South Korea, and Germany where duplex stainless steel and nickel-aluminum bronze machining capabilities cluster. Component supply draws from Japanese electric motor specialists and Danish control system providers. Single-source vulnerability in nickel-aluminum bronze ingot supply exposes fabricators to mining output fluctuations. Distribution runs through shipyard procurement offices for newbuilds and port-region service depots for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized metallurgy welding skills concentrate in mature maritime labor markets, constraining production scaling and propping pricing for qualified suppliers.
For Market Incumbents: Anticipate margin compression in standard centrifugal segments as Chinese fabricators expand classification society approvals. Defend position by deepening backward integration into nickel-aluminum bronze casting and securing exclusive Lloyd's Register certification for high-speed variants. Channel control through direct fleet operator relationships insulates against shipyard procurement consolidation. For New Entrants and Emerging Players: EU Green Deal vessel retrofit incentives in Germany open a window for thermal-management system bundlers lacking established shipyard relationships. Target modular skid standardization for European tanker fleets where MARPOL Annex VI compliance deadlines compress replacement cycles. Go-to-market leverage rests on digital twin integration capabilities for classification society review acceleration. For Investors and Strategic Acquirers: The window for entry favors compact positive-displacement specialists with naval contract visibility. Long-term viability hinges on exposure to coast-guard procurement insulated from commercial-ship cyclicality. Watch Korean Register hazardous-zone electrical equipment qualification timelines as inflection signal for submersible pump supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Classification Society Certification Investment | Lloyd's Register approval gates market access for high-speed centrifugal variants in Chinese newbuild programs. |
| Backward Integration into Metallurgy | In-house nickel-aluminum bronze casting secures margin against raw material volatility from mining output fluctuations. |
| Modular Skid Standardization | Pre-integrated packages capture shipyard labor outsourcing value in South Korean and Japanese engine-room construction. |
| Digital Twin Capability Development | Performance data bundling for classification review accelerates Korean Register approval timelines for submersible configurations. |
| Direct Fleet Operator Relationship Building | Disintermediation from yard contracts secures lifecycle service revenue from German and Greek tanker owners. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with shipyard procurement managers, fleet engineering superintendents, classification society surveyors, and aftermarket service directors combined with Lloyd's Register type-approval databases, IMO MARPOL submissions, and Korean Register equipment lists. Bottom-up vessel newbuild tracking and top-down fleet retrofit cycle analysis provided triangulation across estimation approaches.
Granularity-level modeling operated at pump type, application, end-user category, and installation format dimensions across the analysis window. CAGRs derived from segmented demand build-ups incorporating IMO carbon-intensity indicator compliance deadlines and EU MRV reporting thresholds. Forecast inputs included shipbuilding orderbook data from Clarkson Research and ballast water management convention implementation timelines.
The model assumes a particular technology adoption path for variable-frequency drive integration; alternative pathways for permanent magnet motor adoption would alter the outlook. Forecasts reflect documented assumptions regarding classification society certification timelines and nickel-aluminum bronze price trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Pressure Pumping Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
United States Positive Displacement Pumps Market
Pumps and Control Devices
Global Hydraulic Gear Pump Market
Pumps and Control Devices
Condensate Pump Market
Pumps and Control Devices
Air Compressor Controller Market
Pumps and Control Devices
Asia Pacific Vacuum Pumps Market
Pumps and Control Devices
Cooling Pump Market
Pumps and Control Devices
Package Pumping Station Market
Pumps and Control Devices
Global High Pressure Pumps Market
Pumps and Control Devices
Multi-Stage Centrifugal Pumps Market
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Asia Pacific Industrial Pumps Market
Pumps and Control Devices
Droplet Separator Market
Pumps and Control Devices
Centrifugal Pump Market