
 Global Variable Displacement Pumps Market | 2026-2036
Global Variable Displacement Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Variable Displacement Pumps Market Intelligence
The shift toward equipment-as-a-service (EaaS) and long-term leasing models is tilting the competitive landscape toward manufacturers with robust service networks. This structure favors incumbents with established global footprints. Bosch Rexroth AG leverages its deep R&D in electro-hydraulic systems to capture high-specification contracts. Parker Hannifin Corp differentiates through its comprehensive portfolio of integrated hydraulic components, while Eaton Corporation sustains a strong position in the mobile equipment sector.
A variable displacement pump is a hydraulic component whose output flow rate can be changed dynamically during operation. This adjustment, often achieved by altering a swashplate angle in an axial piston pump, allows for precise power matching to the load. Its primary purpose is to improve overall energy efficiency in hydraulic circuits. Axial piston pumps lead the product segment due to superior pressure ratings and durability, while the construction equipment application constitutes the largest single source of demand.
Regulations such as the US EPA's Tier 4 emissions standards and the EU's Machinery Directive mandate higher efficiency in off-road vehicles. China's "dual carbon goals" further accelerate the transition to energy-saving industrial components. These frameworks compel original equipment manufacturers to integrate advanced hydraulic solutions. The critical decision for suppliers revolves around prioritizing investment in electro-hydraulics versus optimizing current mechanical designs for cost-sensitive segments.
Market Dynamics
The imperative for greater energy efficiency, codified in global environmental regulations, is the central force shaping the variable displacement pump market. This pressure compels equipment manufacturers across industrial and mobile sectors to adopt hydraulic systems that minimize wasted energy and reduce operational costs.
Growth Catalysts
- Regulatory Frameworks:The EU Green Deal and China's dual carbon goals are accelerating the replacement of less efficient fixed-displacement pumps in industrial machinery and off-road vehicles to meet stringent energy consumption targets.
- Agricultural Modernization:The adoption of precision agriculture relies on advanced machinery with sophisticated hydraulic controls for tasks like automated steering and variable-rate application, directly driving demand for responsive pump technology.
- Electro-Hydraulic Integration:The convergence of electronics and hydraulics allows for intelligent pump control, improving system responsiveness and enabling features like remote diagnostics and predictive maintenance, which attracts high-specification contracts.
Market Restraints
- High Initial Cost:The upfront investment for a variable displacement pump is significantly higher than for its fixed-displacement counterpart, creating a major adoption barrier for smaller OEMs and in cost-sensitive applications.
- System Complexity:Advanced variable pump systems require sophisticated electronic controls and specialized knowledge for maintenance and repair, posing challenges in regions with a limited skilled labor pool.
- Threat from Electrification:In low-power applications, the rise of all-electric actuators presents a direct substitution threat, as they offer simpler designs, eliminate hydraulic fluids, and provide easier integration with digital control networks.
Strategic Opportunities
- Predictive Maintenance Services:Integrating IoT sensors into pumps to monitor performance and predict failures opens new revenue streams through data-driven service contracts, shifting focus from hardware sales to system uptime.
- Marine and Offshore Applications:There is a significant opportunity in the marine sector for high-pressure, corrosion-resistant variable displacement pumps for equipment like deck cranes, winches, and steering systems.
- Expansion in Southeast Asia:Rapid industrialization and infrastructure projects in countries like Vietnam and Indonesia create fertile ground for introducing energy-efficient hydraulic solutions in construction and manufacturing equipment.
Industry Challenges
- Electro-Hydraulic Skill Gap:A persistent shortage of technicians who are proficient in both hydraulic mechanics and electronic control systems complicates field service and limits the deployment of the most advanced pump technologies.
- Software and Control Integration:Ensuring seamless compatibility between a pump's electronic controller and the diverse range of proprietary machine control units used by OEMs is a major software engineering and validation challenge.
- Component Sourcing Dependencies:The supply of critical high-precision components, such as pistons and swashplates, is concentrated among a few specialized manufacturers, creating vulnerability to supply chain disruptions and price volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Variable Displacement Pumps Market |
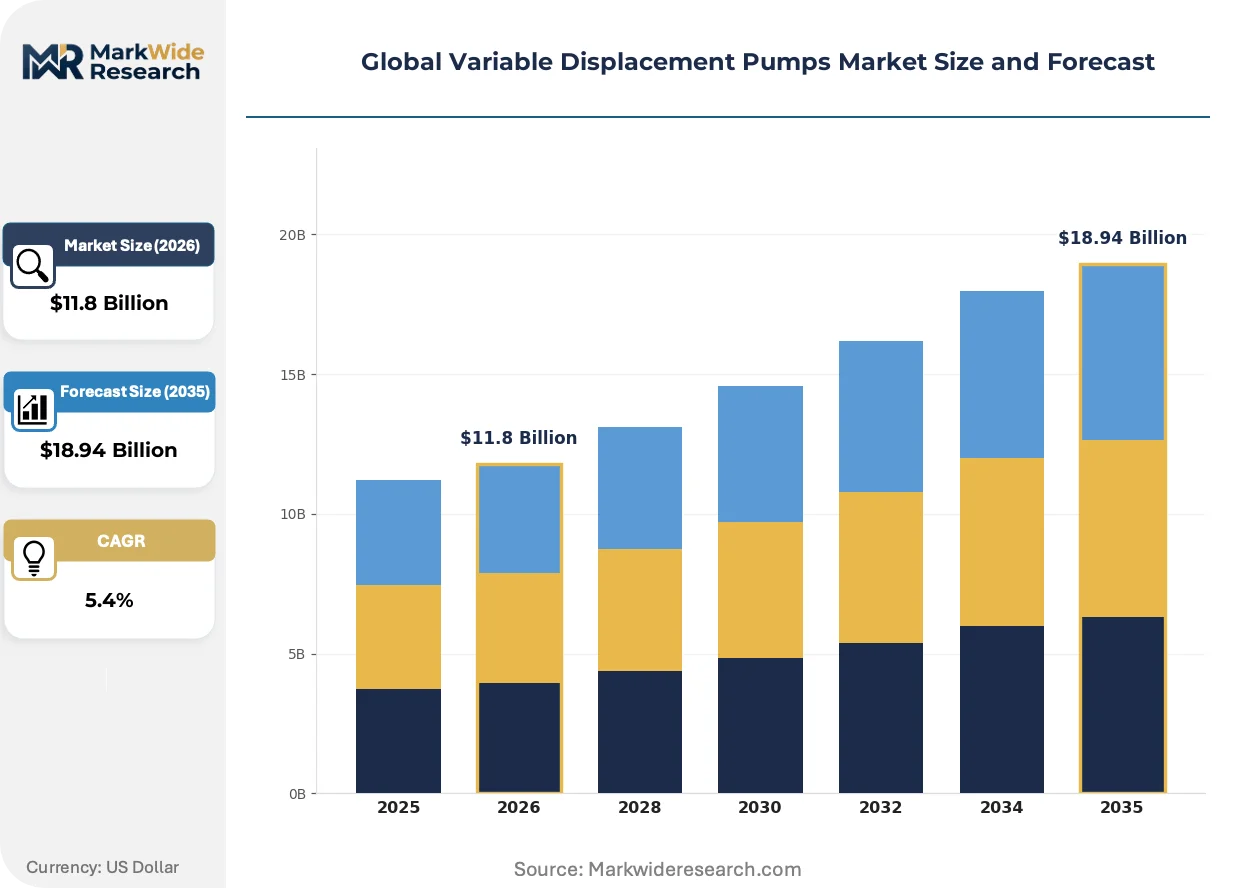
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Piston, Radial Piston, Vane, Gear Technology: Hydraulic, Electro-hydraulic, Electric, Mechanical Application: Construction Equipment, Agricultural Machinery, Marine Craft, Energy Generation End User Industry: Manufacturing Plants, Oilfield Services, Mining Operations, Utilities |
| Companies Covered | Bosch Rexroth AG, Parker Hannifin Corp, Kawasaki Heavy Industries, Ltd., Eaton Corporation, Danfoss A/S, The Oilgear Company, Yuken Kogyo Co., Ltd, HAWE Hydraulik SE, Casappa S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Variable Displacement Pumps Market Strategic Shifts & Innovations
The market's evolution is defined by the integration of digital controls and advanced sensor technology. This movement is transforming pumps from simple mechanical components into intelligent nodes within a larger, digitally managed ecosystem, prioritizing system-level performance and data generation.
Digital pump controllers with onboard microprocessors and integrated sensors allow for dynamic adjustment of flow and pressure. Original equipment manufacturers in demanding sectors like construction and forestry are adopting these smart systems to achieve superior fuel economy and meet emissions mandates. This shift toward intelligent, self-regulating hydraulics is rendering obsolete the purely hydro-mechanical control systems that cannot offer adaptive performance or diagnostic feedback.
The US EPA's Tier 4 Final standards for non-road diesel engines create a powerful incentive for hydraulic system optimization. These rules force equipment manufacturers to minimize parasitic energy losses from all subsystems to comply with strict emissions limits. The mobile equipment segment, particularly excavators and wheel loaders, is most affected, driving innovation in load-sensing and electronic pressure-limiting pump controls to reduce engine strain.
A clear shift away from one-time equipment sales toward long-term leasing and performance-based service contracts is altering buyer behavior. This model elevates the importance of total cost of ownership, reliability, and predictive maintenance over the initial acquisition price. The trend is most prominent in large-scale mining and logistics operations in North America and Europe, where maximizing fleet uptime and operational efficiency is critical.
Global Variable Displacement Pumps Market Segmentation
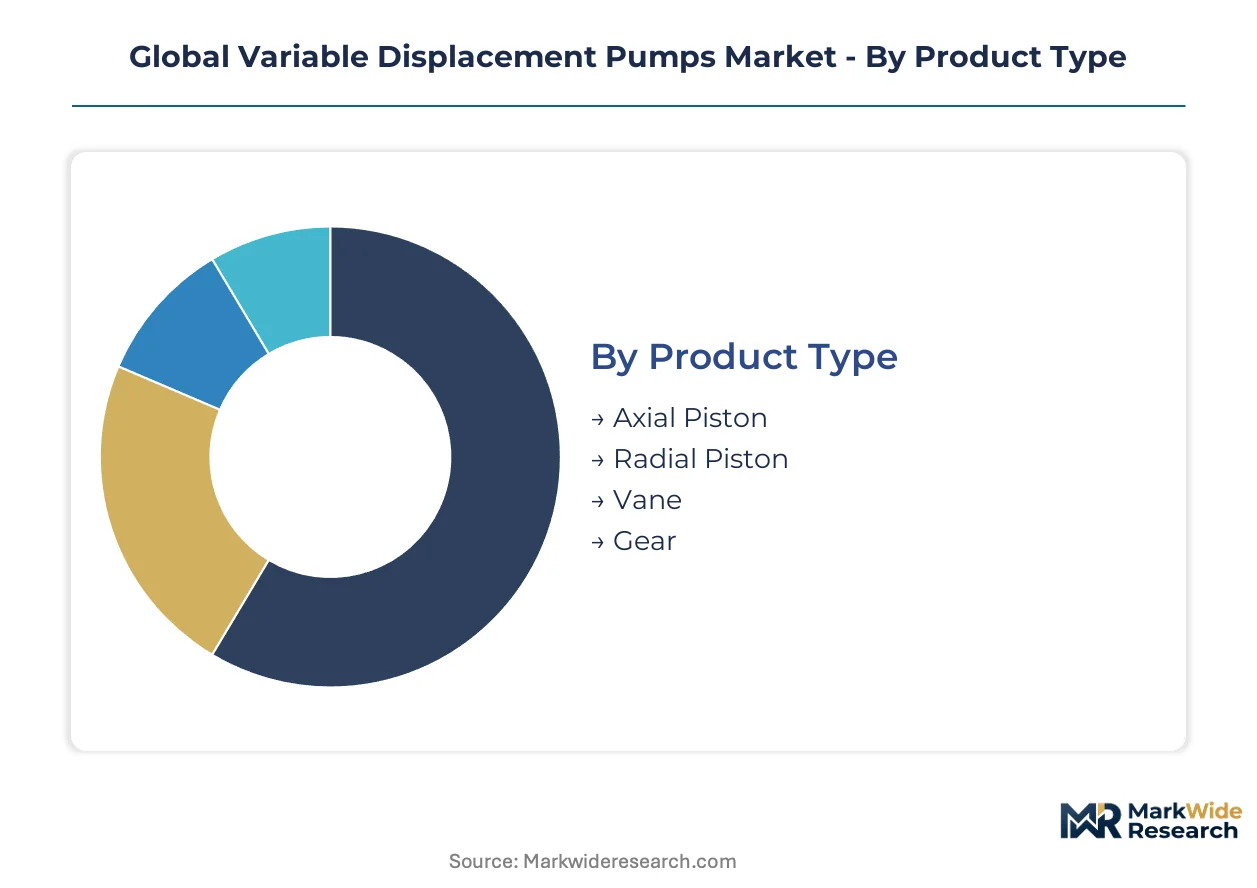
The segmentation of the global variable displacement pumps market delineates the diverse product configurations and application-specific demands that influence market dynamics. Understanding these distinctions is critical for manufacturers to align product development with evolving industry requirements and regulatory mandates.
Product Type:
The product type segmentation reveals how distinct pump designs influence both initial procurement and long-term after-sales service requirements for variable displacement pumps.
- Axial Piston:These pumps are characterized by pistons arranged parallel to the drive shaft, offering superior pressure ratings and high efficiency. Demand concentrates in heavy construction equipment in China due to their robust performance in demanding environments.
- Radial Piston:Featuring pistons arranged radially around a central shaft, these pumps provide high pressure, low noise, and minimal pulsation. Demand is strong in precision industrial machinery in Germany for applications requiring fine control.
- Vane:Vane pumps are known for their compact design and lower pressure capabilities, often used in less demanding applications.
- Gear:Gear pumps offer a simple and cost-effective solution, typically employed where high efficiency and precise control are not paramount.
Axial Piston pumps hold the largest share; momentum sits with Radial Piston designs.
Technology:
Technology differentiation directly impacts the cost structure and complexity of variable displacement pump systems.
- Electro-hydraulic:This technology integrates electronic controls and sensors with hydraulic components, enabling intelligent and dynamic flow adjustment. Demand is rising in off-road vehicles in the US for enhanced fuel efficiency and compliance with EPA Tier 4 standards.
- Hydraulic:Traditional hydraulic systems rely on mechanical or pilot-operated controls to vary pump output, offering proven reliability. Demand remains consistent in established industrial manufacturing plants in India for robust operation.
- Electric:Electric variable displacement pumps utilize direct electric motor control, often eliminating the need for hydraulic fluid in certain applications.
- Mechanical:Mechanical pumps employ cam-driven or other direct mechanical linkages to adjust displacement, representing a simpler control method.
Electro-hydraulic technology represents the fastest-growing trajectory, driven by intelligence demands.
Application:
Application segments dictate specific performance envelopes and environmental resilience requirements for variable displacement pumps.
- Construction Equipment:This segment requires high power density, robustness, and durability to handle heavy loads and harsh operating conditions. Demand is significant in infrastructure development projects in Vietnam for excavators and loaders.
- Agricultural Machinery:Precision control and adaptability to varied field conditions are critical for applications like automated steering and variable-rate spraying. Demand from automated farming systems in the US is strong for precise fluid management.
- Marine Craft:Marine applications demand corrosion-resistant and highly reliable pumps for steering, winches, and propulsion systems.
- Energy Generation:This segment utilizes variable displacement pumps for turbine control, cooling systems, and other auxiliary functions in power plants.
Construction Equipment drives the largest volume, while Agricultural Machinery shows significant expansion.
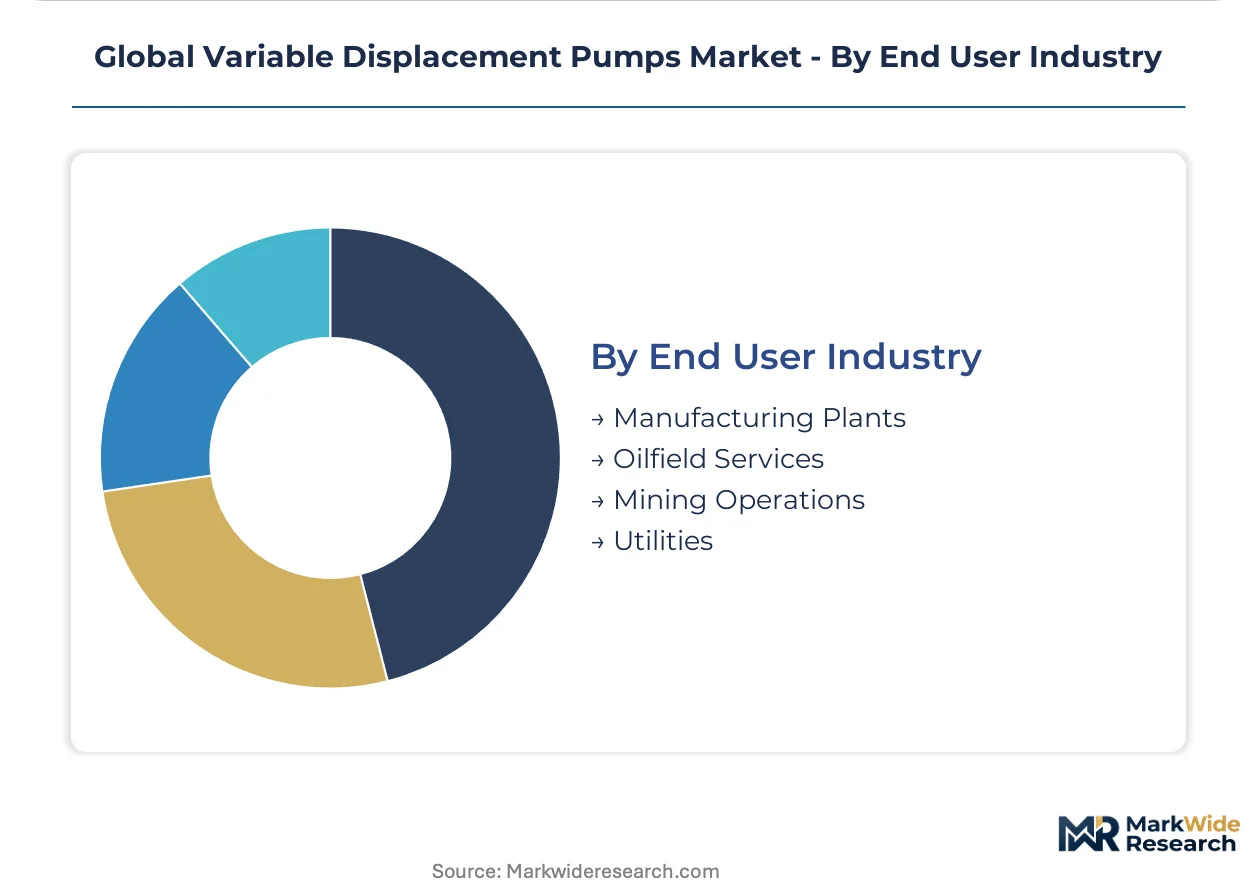
End User Industry:
End user industry segments define the operational environments and maintenance regimes for variable displacement pumps.
- Manufacturing Plants:These facilities utilize variable displacement pumps for precise process control, material handling, and energy-efficient machine operation. Demand is high in automotive production lines in Germany for automation and reduced energy consumption.
- Mining Operations:Variable displacement pumps in mining equipment must withstand extreme conditions, continuous duty cycles, and abrasive environments. Demand comes from large-scale extraction sites in Australia for heavy-duty hydraulics.
- Oilfield Services:This sector employs pumps for drilling, fracturing, and well intervention, requiring high pressure capabilities and resistance to corrosive fluids.
- Utilities:Utilities use these pumps in various infrastructure maintenance and operational tasks, prioritizing long lifespan and reliability.
Manufacturing Plants prioritize energy efficiency, whereas Mining Operations emphasize total cost of ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for variable displacement pumps exhibits regional asymmetry, with higher margins observed in Germany compared to more cost-sensitive markets like India. This disparity reflects differing levels of technological maturity and regulatory compliance across global industrial bases. Demand for advanced electro-hydraulic systems drives premium valuation in developed economies.
China
Demand for variable displacement pumps in China stems from heavy construction equipment and agricultural modernization. China's "dual carbon goals" compel manufacturers to integrate energy-efficient hydraulic solutions. Industrial manufacturing centers in the Yangtze River Delta are driving significant adoption of axial piston pumps.
Germany
Germany's market for variable displacement pumps is propelled by automotive production lines and precision industrial machinery. The EU Green Deal mandates higher energy efficiency standards across industrial sectors. Automotive clusters in Bavaria prioritize advanced electro-hydraulic systems for automation and reduced energy consumption.
United States
The United States market is driven by agricultural modernization and off-road vehicle manufacturing. US EPA's Tier 4 emissions standards incentivize the adoption of electro-hydraulic technology for fuel efficiency. Automated farming systems in the Midwest demand responsive pump technology for precise fluid management.
India
India's demand for variable displacement pumps arises from established industrial manufacturing plants and infrastructure development. The PLI scheme encourages domestic production of advanced machinery components. Industrial hubs in Maharashtra maintain consistent demand for robust hydraulic systems in various applications.
Vietnam
Vietnam's market for variable displacement pumps is expanding due to rapid industrialization and infrastructure projects. Government initiatives supporting manufacturing growth increase the need for efficient industrial components. Infrastructure development projects in Hanoi and Ho Chi Minh City require robust construction equipment, boosting pump demand.
Global Variable Displacement Pumps Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream providing core hydraulic technologies. The market exhibits a tiered structure, with established incumbents leveraging extensive R&D and global service networks. Specialist manufacturers focus on niche applications, often providing customized solutions for high-pressure or extreme environment demands. Strategic partnerships and targeted acquisitions are common competitive moves, alongside continuous portfolio diversification to meet evolving regulatory requirements.
On the premium and integrated solutions tier, Bosch Rexroth AG exemplifies deep R&D in electro-hydraulic systems, anchoring high-specification contracts globally. Parker Hannifin Corp. represents a comprehensive portfolio approach, offering integrated hydraulic components across diverse applications and geographies. Eaton Corporation sustains a strong position in the mobile equipment sector, demonstrating the importance of application-specific expertise and established footprints among market leaders. These entities often leverage their extensive service networks, which are crucial in the shift towards equipment-as-a-service models, to maintain their competitive edge.
| Leading Market Players |
|---|
| Bosch Rexroth AG |
| Parker Hannifin Corp |
| Kawasaki Heavy Industries, Ltd. |
| Eaton Corporation |
| Danfoss A/S |
| The Oilgear Company |
| Yuken Kogyo Co., Ltd |
| HAWE Hydraulik SE |
| Casappa S.p.A. |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta's concentrated production capacity for axial piston pumps significantly influences global pricing structures. This regional supply density dictates cost competitiveness for high-volume orders across the market.
Pricing Analysis
Configured-to-order electro-hydraulic systems command a significant premium over standard mechanical designs. Value-based pricing dominates the high-specification segment, driven by advanced R&D and integrated service offerings. Price differentiation stems from customization levels and the depth of after-sales service networks. Pricing pressure stems from the continuous investment required for electro-hydraulic innovation. Smaller OEMs and cost-sensitive applications exhibit the highest price sensitivity for basic variable pumps.
Supply Chain Analysis
Controls on high-precision manufacturing technologies can limit the global flow of critical variable pump components. Supply concentration for these components resides primarily in Germany, Japan, and China. The market draws from specialized manufacturers for pistons, swashplates, and integrated electronic control units. A structural risk involves vulnerability to supply chain disruptions due to limited component sourcing options. Distribution runs through direct sales channels to large OEMs and specialized regional distributors for smaller clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is experiencing a notable buyer-power shift, driven by the consolidation of procurement strategies among large equipment-as-a-service providers. These integrated buyers demand comprehensive solutions and long-term service commitments.
For Market Incumbents: Pre-empt the threat from electrification in low-power applications by accelerating electro-hydraulic R&D and expanding intelligent control offerings. Reinforce established global service networks to capitalize on equipment-as-a-service models and ensure system uptime. Invest in advanced sensor integration for predictive maintenance capabilities. Deepen vertical integration for critical components to mitigate supply chain vulnerabilities.
For New Entrants and Emerging Players: Establish a beachhead in rapidly industrializing regions like Southeast Asia, focusing on robust, cost-effective mechanical designs for construction equipment. Target the marine and offshore sector with corrosion-resistant, high-pressure variable displacement pumps. A go-to-market angle could involve offering modular, easily configurable hydraulic systems with localized service support.
For Investors and Strategic Acquirers: Long-term, this sits as a technology integration play because the convergence of electronics and hydraulics redefines performance benchmarks. Acquire mid-sized specialists in advanced electro-hydraulic controls or predictive maintenance software. Focus on companies with strong R&D pipelines addressing energy efficiency. A critical signal to watch is the acceleration of electro-hydraulic system adoption in off-road vehicles.
| Strategic Initiative | Industry Significance |
|---|---|
| Accelerate Electro-Hydraulic R&D | Drives energy efficiency in construction equipment, meeting EPA Tier 4 standards. |
| Develop Predictive Maintenance Platforms | Creates new revenue streams from data-driven service contracts for fleet operators. |
| Secure Critical Component Supply Agreements | Mitigates supply chain disruption risks for high-precision pistons and swashplates. |
| Invest in Electro-Hydraulic Skill Training | Addresses the persistent skill gap complicating advanced pump technology deployment. |
| Expand Operations in Southeast Asia | Captures demand from rapid industrialization and infrastructure projects in Vietnam. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and robust secondary data validation. The study combined insights from OEM procurement managers, hydraulic system engineers, and R&D directors. Secondary research leveraged industry association reports, patent databases, government energy efficiency mandates, and company financial filings. A comprehensive bottom-up and top-down triangulation approach ensured data consistency and accuracy.
The forecast inputs considered macroeconomic indicators, technological advancements, and regulatory shifts across the analysis window. The analytical framework modeled market dynamics across product type, technology, application, end-user industry, and regional regulatory stringency. Compound Annual Growth Rates were derived from historical trends and projected demand. Key industry-specific forecast inputs included global construction spending and agricultural machinery sales volumes.
Stress conditions across global economic volatility and raw material price fluctuations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these underlying assumptions. Material shifts in global trade policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Diaphragm Pump Market
Pumps and Control Devices
Subsea Pumps Market
Pumps and Control Devices
United States Subsea Pumps Market
Pumps and Control Devices
Reverse Osmosis Pump Market
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
Sanitary Pumps Market
Pumps and Control Devices
Suction Pump Market
Pumps and Control Devices
Electrostatic Coalescers Market
Pumps and Control Devices
Solar Pump Market
Pumps and Control Devices
Cooling Pump Market
Pumps and Control Devices
Sealless Magnetic Drive Pump Market
Pumps and Control Devices
Radial Split Pump Market
Pumps and Control Devices
Fuel Feed Pumps Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Latin America Positive Displacement Pumps Market
Pumps and Control Devices
Asia Pacific Submersible Pump Market