
 APAC Positive Displacement Pumps Market | 2026-2036
APAC Positive Displacement Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Positive Displacement Pumps Market Outlook
Chemical processing is repositioning as the dominant demand vertical across APAC, displacing traditional oil and gas procurement patterns in several national markets. Grundfos leverages its hydraulic technology leadership to anchor premium metering applications in water-scarce Australian mining districts. KSB competes through manufacturing scale across Indian and Chinese production hubs, sustaining cost advantages in standard gear pump categories. Flowserve differentiates via alloy specialization for corrosive chemical duty cycles, occupying niche high-margin segments that generic suppliers cannot serve.
Positive displacement pumps enclose a fixed fluid volume within a cavity and mechanically displace it through gear meshing, diaphragm flexing, screw rotation, or plunger reciprocation, with typical operating pressures ranging from 50 to 15,000 psi depending on pump architecture. These machines excel where precise volumetric delivery, high-viscosity handling, or self-priming capability outweighs the efficiency advantages of dynamic pump designs. Gear pumps lead the product type landscape in mature industrial economies like Japan and South Korea, while diaphragm pumps capture the fastest expansion in Southeast Asian water treatment and pharmaceutical metering applications where leak-free operation is mandatory. Electric drive technology dominates new installations across the region, though pneumatic systems retain share in explosive-atmosphere chemical plants governed by strict ignition-source controls.
China's SAMR enforces GB efficiency standards that filter low-tier pump suppliers from state-backed infrastructure tenders, while India's BIS certification requirements for industrial equipment create compliance barriers for unqualified imports. Japan's METI energy conservation guidelines shape premium product specifications, pushing manufacturers toward variable-speed electric drives and precision control architectures. Stakeholders must monitor how fragmented national certification regimes evolve toward mutual recognition or deeper divergence, as this trajectory determines whether regional scale or local specialization becomes the winning competitive formula.
Market Dynamics
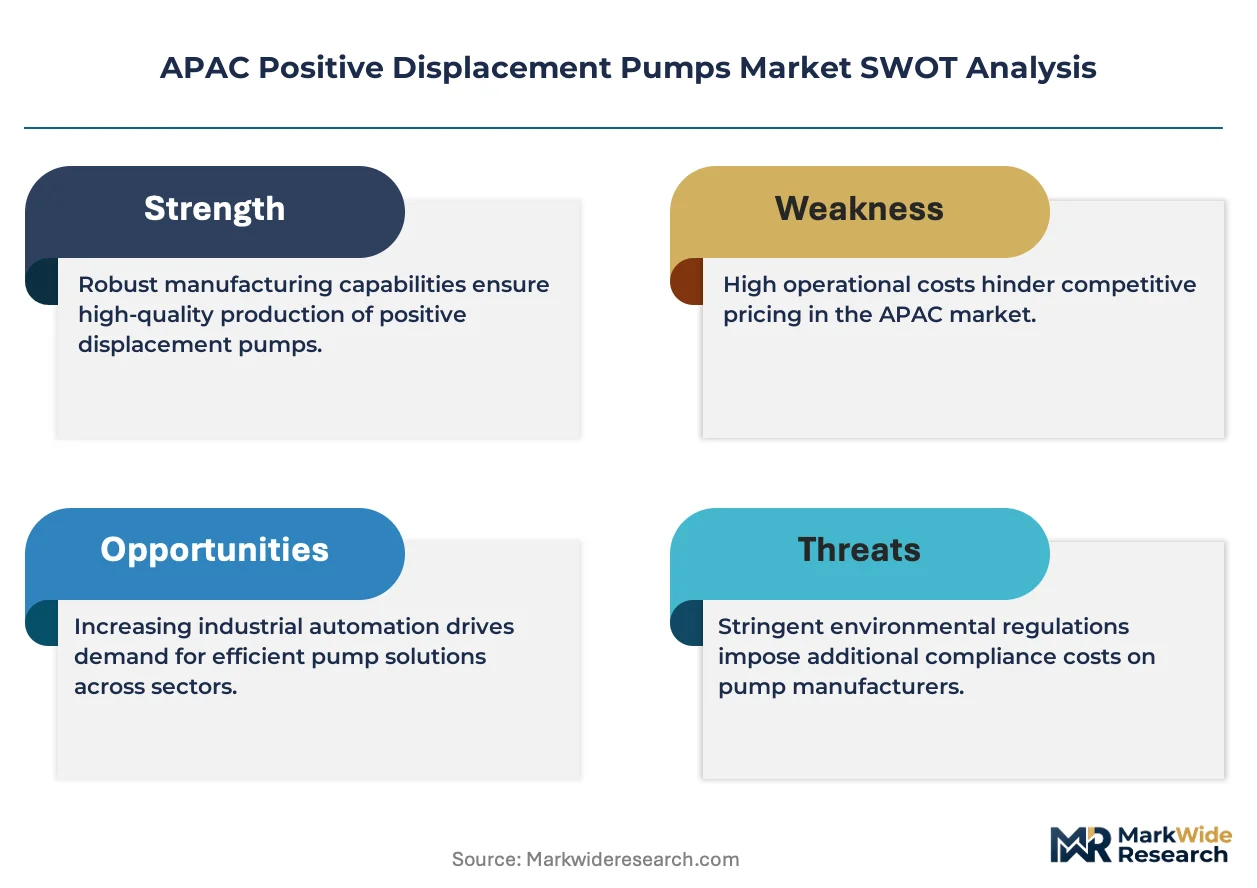
China's SAMR efficiency mandates and India's BIS certification barriers are filtering supplier bases and concentrating procurement authority among qualified fabricators across the region's chemical processing corridors.
Growth Catalysts
- GB Standards Compliance:China's tightened efficiency requirements for industrial fluid handling equipment are disqualifying low-tier suppliers from state infrastructure tenders, consolidating demand toward certified manufacturers.
- Water Treatment Infrastructure:Southeast Asian municipalities are accelerating diaphragm and screw pump procurement to expand sanitation networks and industrial wastewater capacity.
- Pharmaceutical Fluid Transfer:India's chemical processing clusters in Gujarat and Maharashtra are scaling domestic pump fabrication to serve specialty chemical and pharmaceutical metering applications.
Market Restraints
- Alloy Input Volatility:Specialized corrosion-resistant alloys for chemical-duty pumps face price instability, compressing margins on high-performance configurations.
- Supplier Concentration Risk:Premium metering technology for mining applications concentrates among a limited set of hydraulic specialists with proven Australian deployment records.
- Substitution Pressure:Centrifugal pump architectures continue capturing low-viscosity, high-flow applications where precision volumetric delivery is not mandatory.
Strategic Opportunities
- Vietnam Manufacturing Expansion:Underdeveloped domestic pump fabrication capacity creates openings for regional suppliers to establish localized assembly and service networks.
- Variable-Speed Electric Integration:Convergence of precision control architectures with diaphragm pump designs enables energy recovery in pharmaceutical batch processing.
- PLI Scheme Incentives:India's production-linked incentive framework for industrial equipment reduces capital barriers for domestic manufacturers scaling chemical-duty pump lines.
Industry Challenges
- Cross-Border Certification Complexity:Fragmented national regimes across China, India, Japan, and Southeast Asia force suppliers to maintain parallel compliance documentation, extending tender timelines.
- Precision Machining Talent Scarcity:Screw pump manufacturing requires specialized grinding and profile machining expertise that remains concentrated in mature industrial economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Positive Displacement Pumps Market |
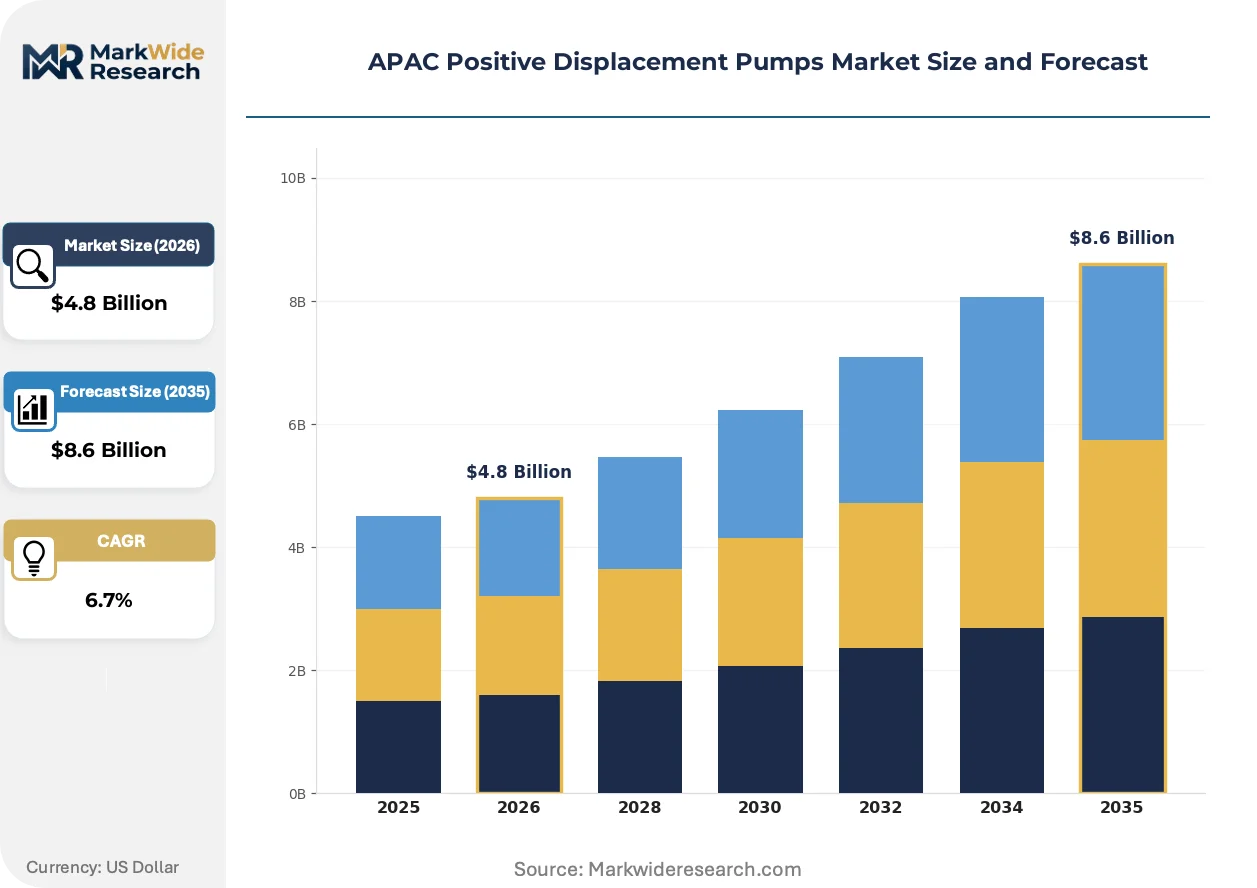
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gear Pumps, Diaphragm Pumps, Screw Pumps, Plunger Pumps End User: Oil & Gas, Chemical Processing, Water Treatment, Food & Beverage Technology: Hydraulic, Pneumatic, Electric, Manual Application: Transfer, Metering, Mixing, Lubrication |
| Companies Covered | Grundfos, KSB, Flowserve, Sulzer, Xylem, Atlas Copco, The Weir Group, NETZSCH, Ingersoll Rand, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Positive Displacement Pumps Market Strategic Shifts
Electrification and digital control architectures are displacing pneumatic systems across explosive-atmosphere applications, while regulatory efficiency mandates force redesigns of legacy hydraulic configurations.
Smart pump systems with embedded condition monitoring and predictive maintenance algorithms are modularizing field service architectures. Mining operators in Australia's water-scarce districts are adopting these configurations fastest, demanding remote diagnostic capability to reduce site visits. Equipment suppliers are compressing aftermarket revenue models as real-time performance data enables subscription-based maintenance.
METI energy conservation guidelines are mandating variable-speed drive integration across premium industrial equipment categories. Japanese process manufacturers must now specify precision-controlled electric architectures in new capital projects. This regulatory pressure is accelerating supplier R&D allocations toward integrated motor-pump designs with embedded power electronics.
After-sales service unbundling is fragmenting traditional bundled procurement contracts across Southeast Asian water treatment sectors. Municipal buyers are separating pump supply from installation and long-term maintenance, creating openings for specialized service contractors. This pattern is most visible in Thailand and Indonesia where public-private partnership frameworks separate capital and operational expenditure streams.
APAC Positive Displacement Pumps Market Segmentation
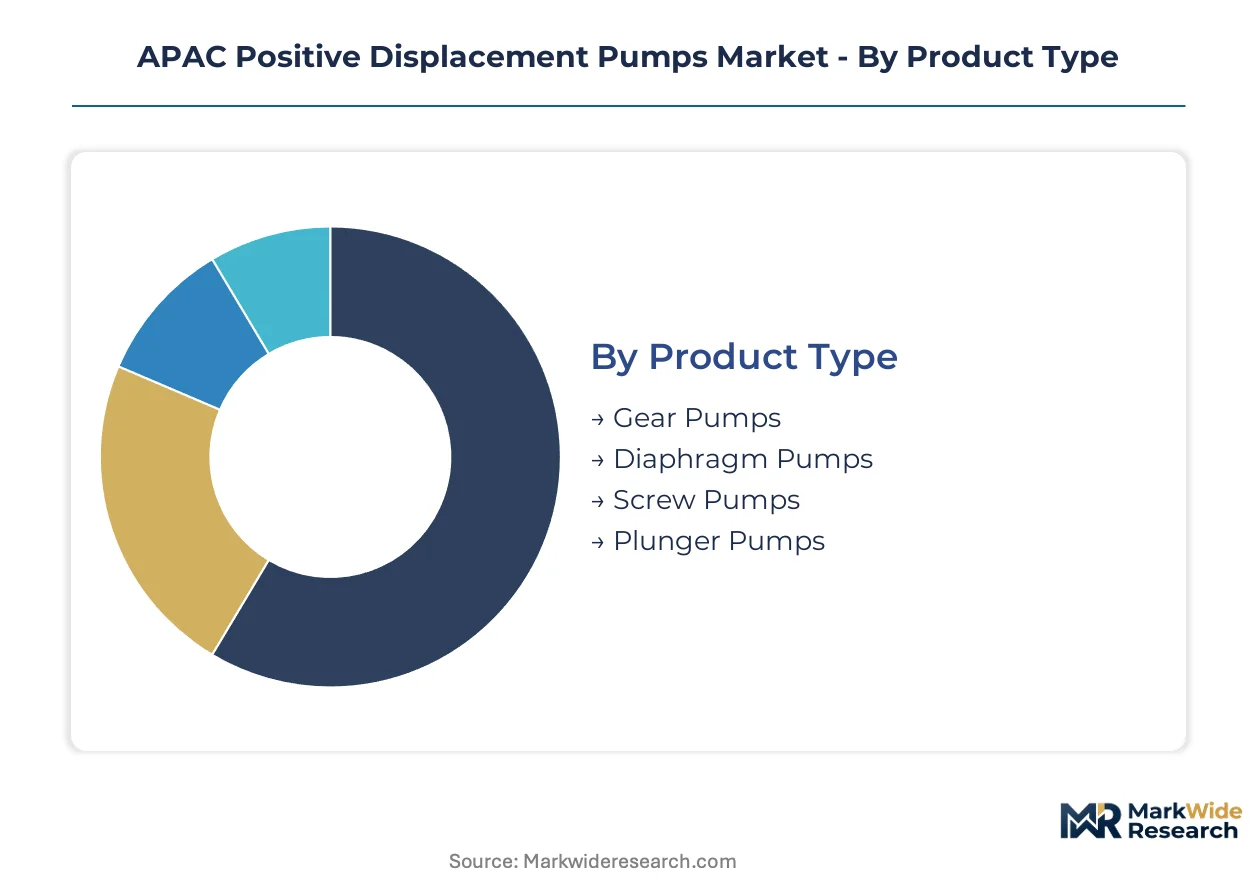
Positive displacement pump architectures vary dramatically in pressure capability, viscosity tolerance, and precision control. Specification choices determine whether deployments succeed in chemical metering, hydraulic power transmission, or sanitary food processing. Understanding how technology axes intersect with end-use requirements reveals where procurement authority concentrates across APAC's fragmented national markets.
Product Type:
Hydraulic architecture and mechanical displacement mechanism define performance envelopes across pressure ranges and fluid characteristics.
- Gear Pumps:Intermeshing gears trap and transport fluid through tight clearances with minimal pulsation. Japanese and South Korean automotive and machine tool manufacturers specify these for precision lubrication circuits where flow consistency outweighs shear sensitivity.
- Diaphragm Pumps:Flexible membranes isolate pumped fluid from mechanical actuation, eliminating seal leakage paths. Southeast Asian pharmaceutical corridors and Australian mining districts are scaling procurement of these configurations where zero-emission operation is mandatory for regulatory compliance or site safety.
- Screw Pumps:Meshing helical rotors generate continuous axial flow with minimal turbulence. These excel in high-viscosity crude oil transfer and polymer handling across Chinese petrochemical complexes.
- Plunger Pumps:Reciprocating pistons deliver extreme pressure capability for hydrostatic testing and high-pressure cleaning applications. Indian pressure-washing equipment fabricators source these for industrial maintenance tool integration.
Mature deployment sits with gear pumps. Newer deployment is concentrated in diaphragm configurations.
End User:
Process intensity and fluid hazard classification shape specification requirements and supplier qualification barriers.
- Chemical Processing:Corrosive duty cycles and toxic fluid containment demand alloy-specialized configurations with extended seal lifecycles. Gujarat and Maharashtra chemical clusters are driving domestic fabrication scaling for specialty fluid transfer.
- Water Treatment:Municipal sanitation expansion and industrial wastewater compliance are accelerating diaphragm and screw pump procurement across Thai and Indonesian public-private partnership frameworks.
- Oil & Gas:Upstream production and midstream logistics applications favor robust, field-serviceable architectures. Australian coal seam gas operators specify these for produced water handling in remote basins.
- Food & Beverage:Sanitary surface finishes and clean-in-place compatibility dominate specification sheets. Japanese dairy processors enforce strict material certification for product-contact surfaces.
Procurement authority concentrates in chemical processing. Fastest volume expansion is occurring in water treatment infrastructure.
Technology:
Actuation method determines energy efficiency, precision control, and ignition safety in hazardous atmospheres.
- Electric:Variable-speed drives with embedded power electronics enable precision flow control and energy recovery. METI conservation guidelines are mandating these configurations across Japanese capital projects.
- Pneumatic:Compressed air actuation eliminates electrical ignition sources in explosive atmosphere zones. Chinese petrochemical plants retain these for solvent transfer applications where intrinsic safety is non-negotiable.
- Hydraulic:Fluid power transmission delivers high force density for mobile equipment and heavy industrial machinery. Australian mining fleet maintenance operations specify these for field pump replacement compatibility.
- Manual:Hand-operated mechanisms serve backup and emergency applications where power infrastructure is unreliable. Remote Indonesian island municipalities deploy these for critical sanitation redundancy.
Electric architectures dominate new installations. Pneumatic systems retain defensive positions in hazardous classification zones.
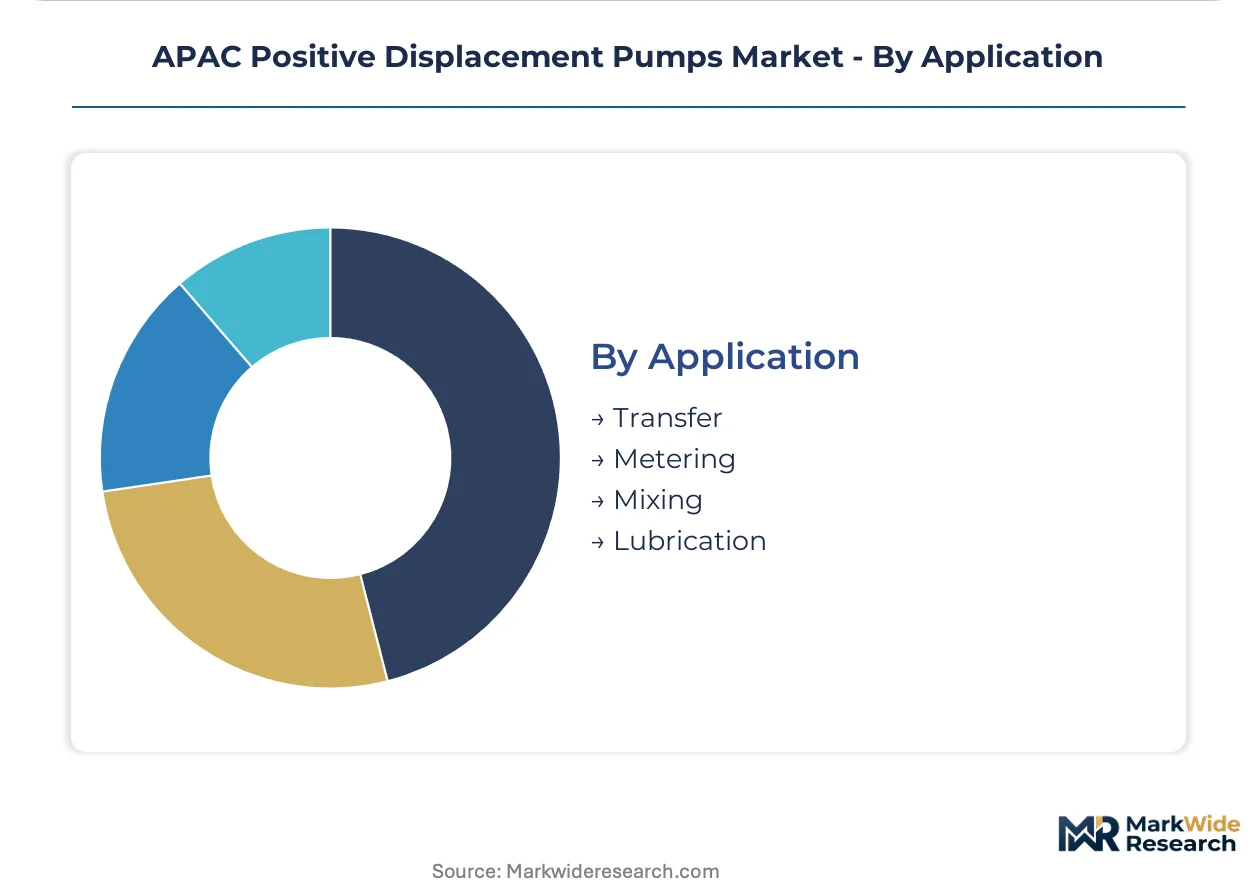
Application:
Functional purpose determines precision requirements, pressure specifications, and control system complexity.
- Metering:Accurate volumetric dosing with repeatability tolerances below one percent. Indian pharmaceutical batch processors specify these for active ingredient addition where concentration variance rejects entire production lots.
- Transfer:Bulk fluid movement prioritizing throughput over precision. Chinese refinery operators deploy these for intermediate product routing between process units.
- Mixing:Controlled circulation to achieve homogeneity in multi-component formulations. Japanese specialty chemical manufacturers integrate these into reactor feed systems.
- Lubrication:Continuous oil delivery to bearing surfaces and gearboxes. South Korean automotive press lines specify these for tool life extension and downtime reduction.
Transfer applications represent the largest installed base. Metering functions are climbing the fastest as pharmaceutical and specialty chemical precision requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates production capacity across the APAC positive displacement pumps landscape, while consumption concentrates in India's chemical corridors and Southeast Asia's municipal infrastructure buildouts. This production-consumption divide shapes regional trade flows and supplier qualification requirements.
China
SAMR's tightened GB efficiency standards for industrial fluid handling equipment are filtering low-tier suppliers from state-backed infrastructure tenders. Municipal water treatment expansion across the Yangtze River Delta and Pearl River Delta is accelerating diaphragm and screw pump procurement. Zhejiang and Jiangsu provinces host the densest clusters of certified pump fabricators serving both domestic and export demand.
India
BIS certification requirements for industrial equipment create compliance barriers that favor domestic manufacturers scaling chemical-duty pump lines. The PLI scheme for industrial equipment reduces capital barriers for fabricators expanding into specialty chemical and pharmaceutical fluid transfer. Gujarat and Maharashtra chemical processing corridors concentrate procurement authority for corrosion-resistant alloy pump configurations.
Japan
METI energy conservation guidelines mandate variable-speed electric drive integration across premium industrial equipment categories. Kanto and Kansai industrial zones specify precision-controlled architectures for automotive lubrication and machine tool coolant applications. Japanese process manufacturers enforce strict material certification for product-contact surfaces in food and dairy processing.
Australia
Water-scarce mining districts in Western Australia and Queensland are scaling procurement of smart pump systems with embedded condition monitoring and predictive maintenance algorithms. Premium metering technology concentrates among hydraulic specialists with proven deployment records in remote basins. Coal seam gas operators specify robust, field-serviceable architectures for produced water handling.
Vietnam
Underdeveloped domestic pump fabrication capacity creates openings for regional suppliers establishing localized assembly and service networks. Public-private partnership frameworks in Ho Chi Minh City and Hanoi are separating capital and operational expenditure streams for municipal water treatment. Industrial zones around Hai Phong and Da Nang are attracting foreign pump suppliers targeting ASEAN export markets.
APAC Positive Displacement Pumps Market Competitive Environment
Top-tier vendors anchor premium metering and alloy-specialized segments, while mid-scale fabricators compete on standard gear pump categories and regional service proximity. The supplier base stratifies across hydraulic technology leaders, manufacturing scale operators, and corrosion-resistant alloy specialists. Three archetypes dominate: premium technology anchors, cost-optimized volume players, and niche application specialists. Competitive moves concentrate on geographic expansion into underpenetrated Southeast Asian markets and portfolio diversification toward integrated smart pump systems.
Among European-origin multinationals, Grundfos and KSB exemplify contrasting scale-versus-technology positioning, while Flowserve occupies a position within the alloy-specialized tier serving corrosive chemical duty cycles. These three anchors represent how hydraulic expertise, manufacturing footprint breadth, and materials science capability respectively define competitive differentiation in a market where national certification regimes fragment procurement authority.
| Leading Market Players |
|---|
| Grundfos |
| KSB |
| Flowserve |
| Sulzer |
| Xylem |
| Atlas Copco |
| The Weir Group |
| NETZSCH |
| Ingersoll Rand |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between GB-compliant and uncertified pump tiers splits both pricing power and sourcing strategies across the APAC landscape. SAMR-mandated efficiency standards force procurement officers to pay premiums for qualified fabricators while relegating low-tier suppliers to spot-market inventory clearance.
Pricing Analysis
Lead-time compression commands measurable premiums across diaphragm and screw pump categories, with Australian mining operators paying top rates for sub-30-day delivery windows. Three-tier pricing structure across premium, standard, and economy levels tracks certification status, alloy grade, and after-sales bundling intensity. Price differentiation stems from BIS compliance overhead and corrosion-resistant alloy input costs. Margins are tightening in standard gear pump segments as Chinese fabricators expand capacity. Municipal water treatment buyers in Thailand and Indonesia exhibit highest price sensitivity, while Japanese automotive OEMs prioritize precision specifications over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized corrosion-resistant alloy suppliers serving chemical-duty pump manufacturers in Gujarat and Maharashtra. Component fabrication concentrates in China, India, and Japan, with precision grinding equipment for screw pump profiles anchored in Japanese and South Korean machine tool clusters. Raw material dependencies span nickel-based superalloys, high-grade stainless steel, and specialized elastomer compounds for diaphragm membranes. Supply chain risk centers on tariff exposure for alloy imports into Indian fabrication facilities. Distribution runs through authorized dealer networks for premium tiers and direct procurement for municipal bulk tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase as variable-speed electric drives displace pneumatic actuation across explosive-atmosphere chemical plants. METI conservation guidelines and SAMR efficiency mandates are accelerating the obsolescence of legacy hydraulic configurations.
For Market Incumbents: Deepen vertical integration into corrosion-resistant alloy supply through captive casting operations or long-term offtake agreements with Japanese specialty metal suppliers. Expand certified service networks across Vietnam's underdeveloped maintenance infrastructure to lock in aftermarket revenue streams. Defend against centrifugal pump substitution in low-viscosity applications by emphasizing precision volumetric guarantees in pharmaceutical metering contracts. For New Entrants and Emerging Players: Direct-to-municipal digital procurement platforms offer the fastest route to bypass entrenched distributor relationships in Southeast Asian water treatment sectors. Target Vietnam's Hai Phong and Da Nang industrial zones for localized assembly partnerships with regional fabricators lacking smart pump integration capabilities. Pursue white-label manufacturing arrangements with Indian PLI scheme beneficiaries seeking European brand cachet for chemical-duty export lines. For Investors and Strategic Acquirers: Re-rating potential sits with alloy-specialized mid-cap fabricators given tightening GB and BIS certification barriers that foreclose new entrant competition. Long-term viability favors suppliers with proven deployment records in Australian mining districts and Japanese precision manufacturing ecosystems. Monitor SAMR mutual recognition negotiations as the signal for whether regional scale or local specialization becomes the winning competitive formula.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive sourcing of corrosion-resistant materials insulates margins from nickel price volatility in chemical-duty segments. |
| Smart Pump System Development | Embedded condition monitoring enables subscription-based maintenance revenue from Australian mining operators. |
| Vietnam Manufacturing Expansion | Localized assembly reduces logistics costs for ASEAN municipal water treatment procurement tenders. |
| PLI Scheme Partnership Structure | Joint ventures with Indian certified fabricators accelerate market access to Gujarat pharmaceutical corridors. |
| Variable-Speed Drive Integration | METI-compliant architectures secure eligibility for Japanese automotive and machine tool capital projects. |
Study Parameters
Multi-period observation of pump procurement volumes, certification registration trends, and alloy price indices anchored the trend analysis, supplemented by interviews with plant engineers at chemical processing facilities, municipal water treatment procurement officers, aftermarket service heads at mining operations, and OEM sourcing managers at automotive manufacturers. Secondary validation drew from SAMR GB standard filings, BIS certification databases, METI energy conservation reports, Australian Bureau of Statistics mining equipment import data, and trade flow records from Chinese customs authorities. Bottom-up fabrication capacity estimates triangulated against top-down end-use demand projections.
Segment-weighting across product type, end user, technology, and application dimensions structured the analytical framework. Modeled categories included gear, diaphragm, screw, and plunger architectures; chemical processing, water treatment, oil and gas, and food and beverage verticals; electric, pneumatic, hydraulic, and manual actuation methods; and metering, transfer, mixing, and lubrication functions. CAGRs were derived from regression analysis of historical procurement patterns against regulatory implementation timelines and infrastructure investment announcements. Industry-specific forecast inputs incorporated PLI scheme disbursement schedules and ASEAN public-private partnership pipeline disclosures.
Inputs from regulatory filings and trade databases were available through the study window; gaps in real-time mining operator maintenance spend data introduce uncertainty bands around Australian aftermarket revenue projections. Forecasts reflect assumptions regarding certification regime stability and alloy supply continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Flow Back Equipment Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Magnetic Drive Pumps Market
Pumps and Control Devices
Food and Beverages Industry Pumps Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
Rotary Vane Vacuum Pump Market
Pumps and Control Devices
Rotary Pump Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Wind Powered Water Pumps Market
Pumps and Control Devices
Air-Operated Double Diaphragm (AODD) Pumps Market
Pumps and Control Devices
Solar Pump Market
Pumps and Control Devices
Plate Heat Exchanger Market
Pumps and Control Devices
Industrial ASME B73.1 Centrifugal Pumps Market
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Residential Pumps Market
Pumps and Control Devices
Subsea Pumping System Market