
 High Power Air Pump Market | 2026-2036
High Power Air Pump Market Size, Share, and Industry Trends Forecast 2026-2036
High Power Air Pump Market Insights
Skilled compressor technician availability is rotating toward electromechanical specializations as hydraulic and purely pneumatic systems lose share. Atlas Copco leverages its aftermarket service density to lock in replacement part revenue across European industrial clusters. Ingersoll Rand sustains competitive tension through vertical integration into precision casting for high-pressure piston assemblies. Parker-Hannifin dominates North American distribution channels for mobile hydraulic air pump variants used in construction and agriculture.
High power air pumps are positive displacement or dynamic machines engineered to deliver compressed air above standard industrial pressure thresholds, typically incorporating alloy-reinforced pistons, corrosion-resistant diaphragms, or multi-stage centrifugal impellers to achieve sustained volumetric flow rates in demanding process environments. These systems serve as critical motive force providers for pneumatic tools, aeration basins, material conveying lines, and pressurized process vessels across heavy industry. Piston pumps and centrifugal pumps anchor the current revenue base due to proven durability in oil and gas extraction and mining operations, though diaphragm pumps are gaining share in chemical processing where leak-free operation determines equipment selection. Electric motor technology leads installed capacity while solar powered configurations represent the fastest-growing sub-category, driven by remote site electrification and municipal sustainability mandates.
EPA emissions regulations and OSHA workplace noise exposure limits in the United States compress the viable product set toward quieter, more efficient electric and electromagnetic designs. China's MIIT efficiency grading system and the EU's Ecodesign requirements under the EU Green Deal framework impose parallel pressure on manufacturers to redesign motor-drive packages and thermal management systems. Stakeholders must monitor how dual carbon compliance deadlines in China and pending F-Gas Regulation amendments in Europe reshape the cost structure of sealed compressor architectures versus conventional open-frame designs.
Market Dynamics
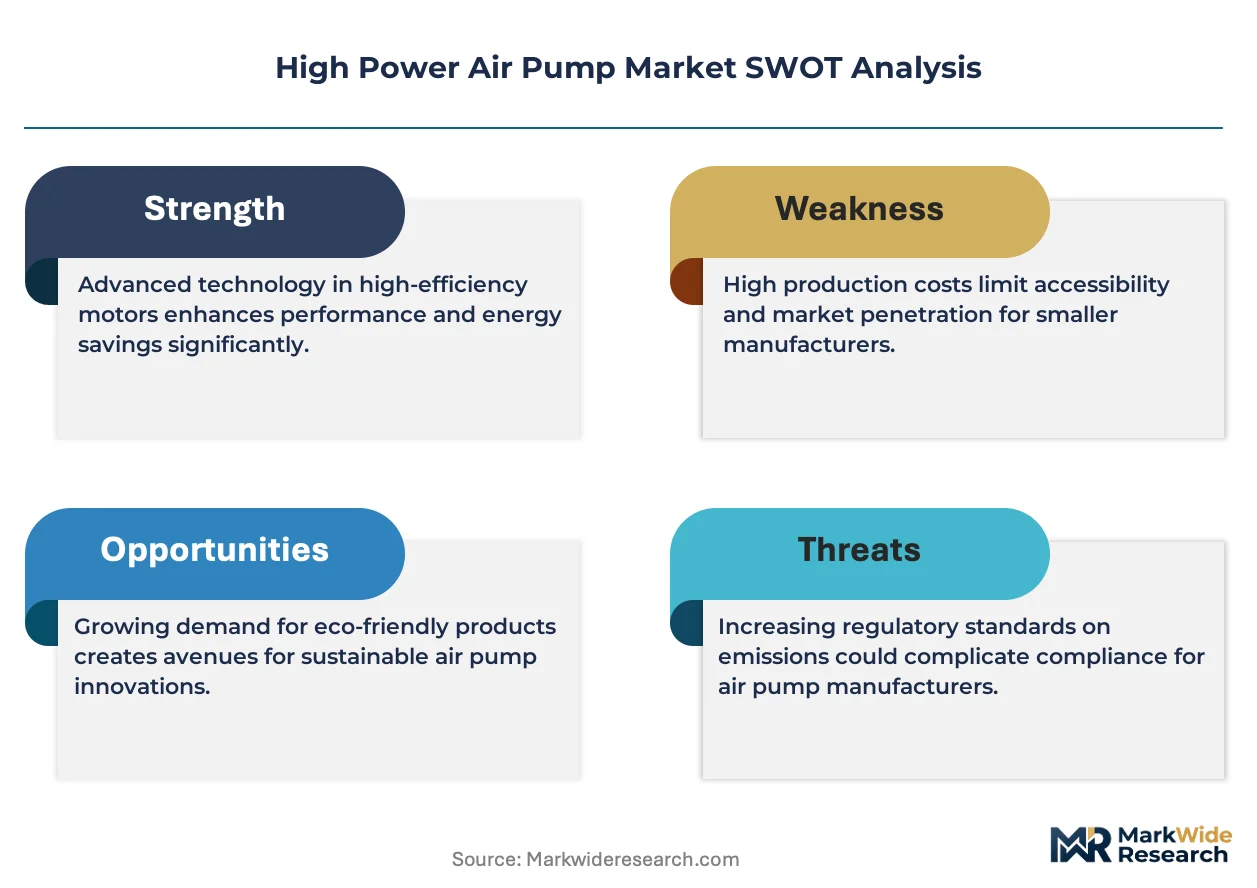
EPA emissions standards and OSHA noise exposure limits are compressing the viable product set toward quieter, more efficient electric and electromagnetic designs, forcing manufacturers to redesign motor-drive packages and thermal management systems across industrial clusters.
Growth Catalysts
- EPA emissions mandates:Tightening standards for industrial equipment in the United States are forcing upgrades to electric motor and solar powered variants, lifting replacement demand across manufacturing facilities.
- Wastewater treatment expansion:Rising deployment in aeration basins across Germany, Japan, and Brazil is driving order volumes for heavy-duty diaphragm and centrifugal systems.
- China's infrastructure buildouts:Municipal and industrial projects in China's manufacturing belt require sustained volumetric flow systems for chemical processing and mining operations.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings for permanent magnet motors compress margin structures for electric-drive manufacturers.
- Supply concentration in precision casting:Captive supply of high-pressure piston assemblies concentrates among integrated European and North American foundries, limiting second-source options.
- F-Gas Regulation friction:Pending amendments to Europe's sealed compressor requirements create compliance uncertainty for conventional open-frame architecture producers.
Strategic Opportunities
- Remote site electrification:Solar powered configurations represent white space in off-grid mining and agricultural operations across Australia and sub-Saharan Africa.
- EU Green Deal tailwinds:Ecodesign requirements and efficiency grading systems incentivize premium motor-drive retrofits in European industrial clusters.
- Digital distribution channels:Direct-to-plant procurement platforms are bypassing traditional distributor markups for standardized piston pump replacements.
Industry Challenges
- Electromechanical technician scarcity:Skilled compressor technician availability is rotating away from hydraulic and pneumatic specializations, creating hiring bottlenecks for service networks.
- Dual carbon compliance timelines:China's MIIT efficiency deadlines and parallel EU requirements force simultaneous product redesigns, straining R&D bandwidth.
- Legacy system integration:Retrofitting electromagnetic drives into existing pneumatic infrastructure requires custom manifold adaptations, extending commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Power Air Pump Market |
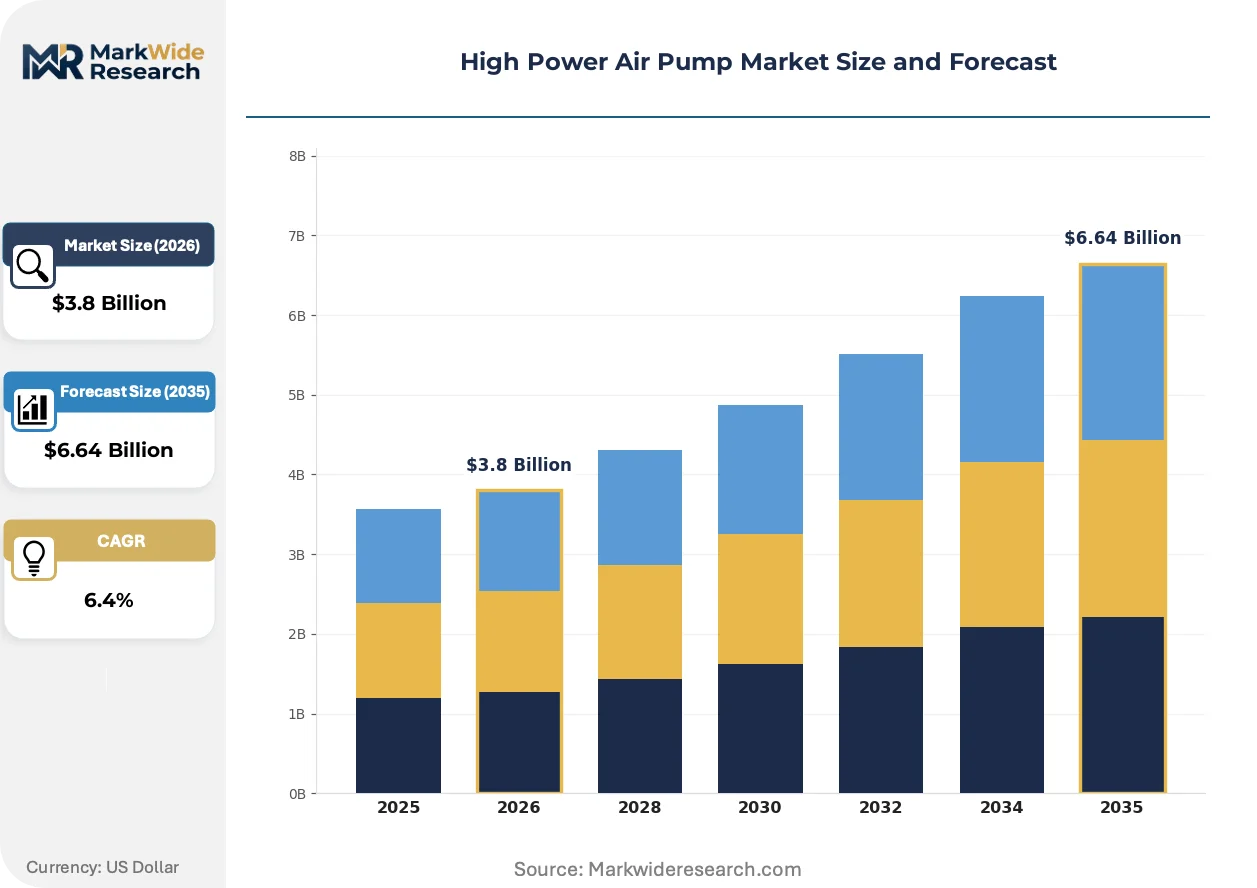
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm Pumps, Piston Pumps, Vane Pumps, Rotary Pumps, Centrifugal Pumps Technology: Electromagnetic, Pneumatic, Hydraulic, Electric Motor, Solar Powered Application: Wastewater Treatment, Chemical Processing, Food Packaging, Aquaculture, Mining Operations End User Industry: Oil & Gas, Manufacturing Plants, Municipal Facilities, Agriculture, Construction |
| Companies Covered | Atlas Copco AB, Ingersoll Rand, Parker-Hannifin Corporation, Eaton Corporation plc, SPX Flow, Grundfos Holding A/S, Flowserve Corporation, Enerpac Tool Group Corp., GEA Group Aktiengesellschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Power Air Pump Market Trends and Innovations
Active reshaping in this market centers on motor-drive electrification, regulatory compression toward sealed architectures, and procurement disintermediation that is fragmenting traditional distribution hierarchies.
Permanent magnet synchronous motor technology is fragmenting the established induction motor base in high-pressure applications. Oil and gas extraction operators in the Permian Basin and North Sea clusters are adopting these systems for their superior torque density and variable-speed precision. The technology is fragmenting vendor portfolios as manufacturers must now support dual motor platforms with incompatible thermal management and control electronics.
Europe's F-Gas Regulation amendments are accelerating the shift toward hermetically sealed compressor designs with lower global warming potential refrigerants. Industrial process cooling applications face the steepest compliance curves, particularly in German chemical processing corridors. Manufacturers are responding by redesigning thermal management systems and migrating toward oil-free scroll and diaphragm architectures that eliminate sealing complexity.
Buyer concentration among municipal wastewater authorities is compressing switching cycles and unbundling after-sales service contracts. German and Japanese utilities now separate pump procurement from maintenance agreements, pressuring OEM service revenue. This pattern is most visible in Brazil's state-level sanitation companies, where framework agreements favor lowest-life-cycle-cost bids over upfront capital expenditure minimization.
High Power Air Pump Market Segmentation
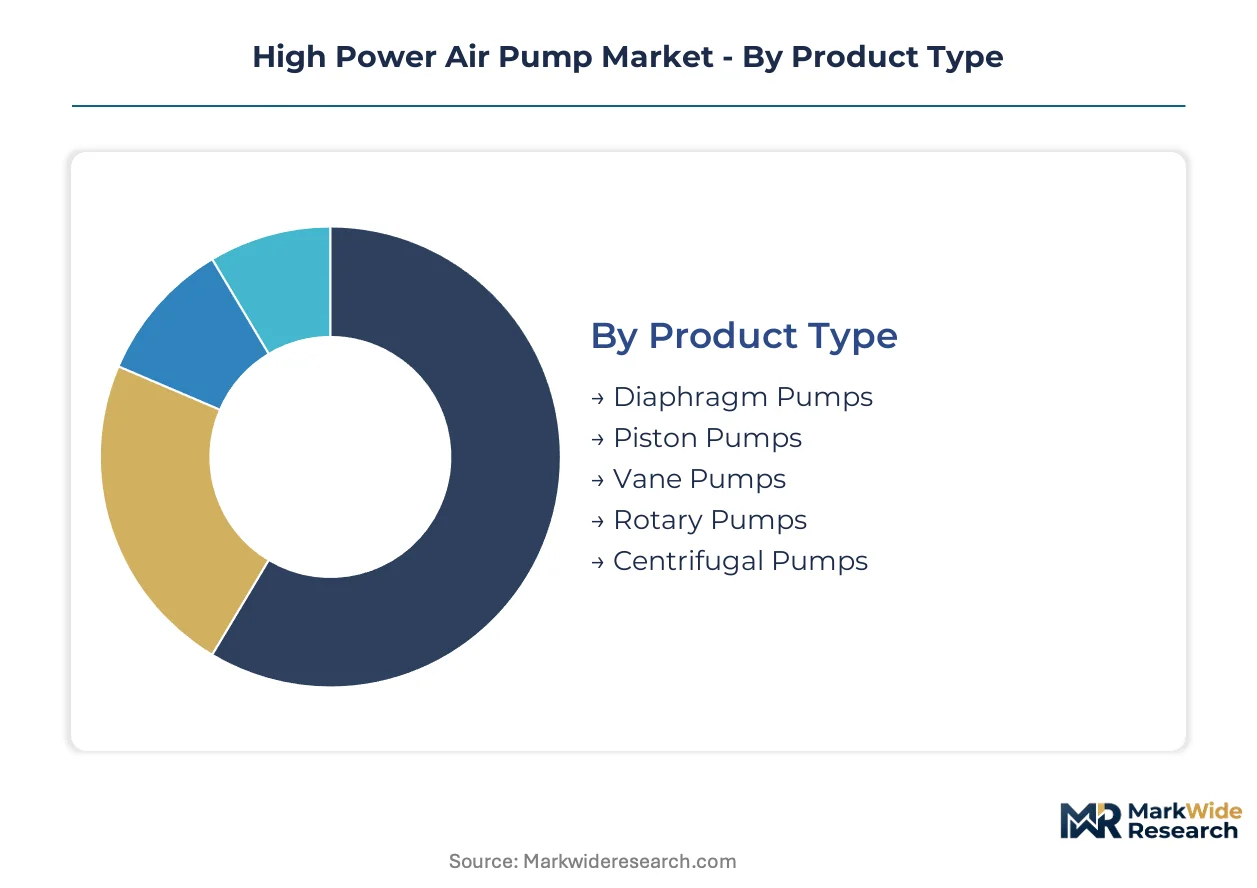
Segmentation in the high power air pump market reveals how substitution pressures and regulatory compliance reshape equipment selection across process environments. Understanding these divisions exposes where incumbent technologies face displacement and where new powertrain configurations capture order flow.
Product Type:
Piston pumps face the most acute substitution threat as permanent magnet motor systems displace traditional induction-drive configurations in oil and gas extraction clusters.
- Piston Pumps:Alloy-reinforced reciprocating assemblies deliver sustained pressure above 150 psi for hydraulic fracturing and deep-well applications. Demand concentrates in Permian Basin extraction sites where torque density requirements favor rugged positive-displacement architectures.
- Centrifugal Pumps:Multi-stage impeller systems achieve high volumetric flow rates through dynamic compression rather than mechanical displacement. Municipal wastewater authorities in Germany specify these for aeration basin duty cycles requiring 24/7 reliability under variable load conditions.
- Diaphragm Pumps:Corrosion-resistant elastomer membranes enable leak-free chemical transfer in processing environments.
- Vane Pumps:Sliding vane mechanisms provide consistent flow in lubricated industrial air systems.
- Rotary Pumps:Lobe and gear configurations handle viscous process fluids in food-grade applications.
Piston pumps anchor the volume base while centrifugal pumps gain share at the steepest rate in municipal infrastructure tenders.
Technology:
Cost tier stratification separates premium permanent magnet systems from standard induction motor platforms and economy-grade pneumatic alternatives.
- Electric Motor:Induction and synchronous architectures dominate installed capacity across manufacturing plants and mining operations. China's MIIT efficiency grading system forces redesigns of thermal management packages in motor-drive units serving chemical processing corridors.
- Solar Powered:Photovoltaic-driven compressors with battery buffering serve off-grid agricultural and mining sites in Australia and sub-Saharan Africa. Remote site electrification mandates from municipal sustainability programs accelerate procurement in regions lacking grid infrastructure.
- Electromagnetic:Linear motor configurations eliminate mechanical transmission losses in precision pressure control applications.
- Pneumatic:Compressed-air-driven pumps persist in explosive atmosphere zones where electrical ignition risks prohibit motor-driven alternatives.
- Hydraulic:Fluid-power systems retain niche positions in heavy construction equipment where integrated power take-offs exist.
Electric motor technology anchors the volume base while solar powered configurations expand most quickly in remote infrastructure projects.
Application:
Customer type concentration separates capital-intensive process industries from maintenance-driven municipal utilities with divergent procurement cycles.
- Wastewater Treatment:Aeration basin duty demands corrosion-resistant diaphragm and centrifugal systems with continuous-duty ratings. State-level sanitation companies in Brazil now unbundle pump procurement from service contracts, favoring lowest-life-cycle-cost bids.
- Chemical Processing:Hermetically sealed architectures prevent fugitive emissions in German processing corridors facing F-Gas Regulation compliance deadlines. Oil-free scroll and diaphragm configurations eliminate sealing complexity in high-purity process streams.
- Mining Operations:Underground and open-pit extraction requires portable high-pressure systems for pneumatic tools and material conveying.
- Food Packaging:Oil-free compression meets sanitary standards in processing and packaging lines.
- Aquaculture:Continuous aeration systems support intensive fish farming operations.
Wastewater treatment anchors the volume base while chemical processing climbs the fastest on emissions compliance investments.
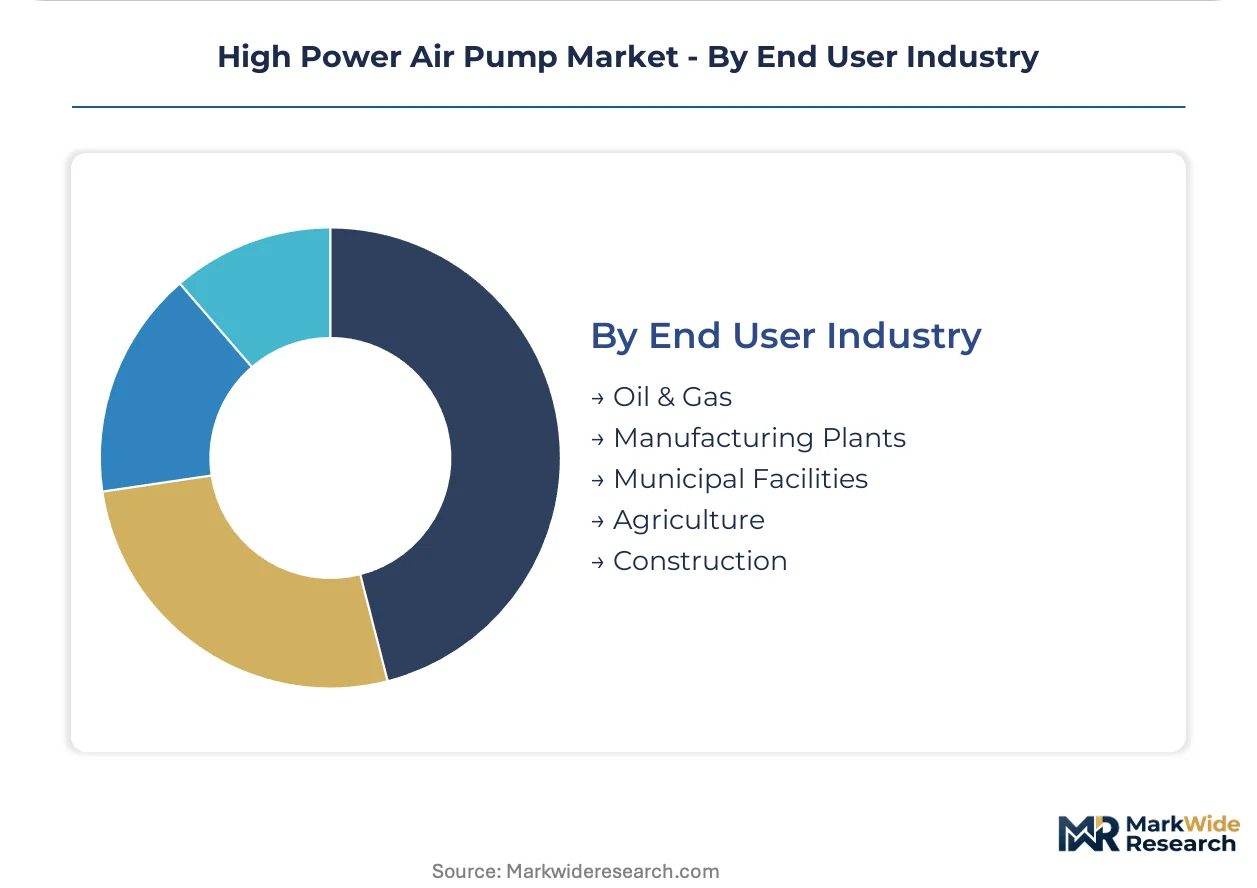
End User Industry:
Supply concentration in precision casting and permanent magnet materials shapes margin structures differently across integrated and fragmented customer bases.
- Oil & Gas:Exploration and production operators in the North Sea and Permian Basin specify high-pressure piston and centrifugal systems for wellhead compression and gas lift operations. Variable-speed permanent magnet drives displace fixed-speed induction motors in new installations.
- Municipal Facilities:Water and sanitation authorities in Japan and Germany separate equipment procurement from maintenance agreements, compressing OEM service revenue. Framework agreements prioritize operational expenditure minimization over upfront capital savings.
- Manufacturing Plants:Industrial compressed air networks power pneumatic automation and material handling systems.
- Construction:Mobile equipment fleets require portable compressor units for pneumatic tools.
- Agriculture:Irrigation and processing operations utilize mid-pressure systems for equipment actuation.
Oil and gas anchors the volume base while municipal facilities gain share fastest on infrastructure privatization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions mandates and OSHA workplace standards in the United States compress equipment specifications toward quieter electric configurations. Municipal buildouts in Germany, Japan, and Brazil concentrate aeration basin procurement. China's MIIT efficiency grading forces motor-drive redesigns across chemical processing corridors.
United States
Permian Basin extraction operators specify high-pressure piston systems for hydraulic fracturing and gas lift operations. EPA emissions standards and OSHA noise exposure limits force upgrades to electric motor and solar powered variants. Industrial clusters in Texas and Oklahoma anchor replacement demand as operators retire legacy pneumatic infrastructure.
Germany
Municipal wastewater authorities in the Rhine-Ruhr and Bavarian regions unbundle pump procurement from maintenance agreements. The EU Green Deal framework and F-Gas Regulation amendments accelerate hermetically sealed compressor adoption in chemical processing corridors around Ludwigshafen and Leverkusen. State-level utilities prioritize lowest-life-cycle-cost bids over upfront capital savings.
China
Municipal and industrial infrastructure buildouts in the Yangtze River Delta and Pearl River Delta require heavy-duty pumping systems for chemical processing and mining operations. MIIT efficiency grading forces redesigns of thermal management packages in motor-drive units. Manufacturing belt concentration drives sustained volumetric flow system orders.
Japan
State-level sanitation companies specify corrosion-resistant diaphragm and centrifugal systems for aeration basin duty cycles. METI efficiency standards and municipal sustainability mandates accelerate procurement of premium motor-drive retrofits. Industrial clusters around Osaka and Nagoya concentrate framework agreements favoring operational expenditure minimization.
Brazil
Rising deployment in wastewater treatment facilities across São Paulo and Rio de Janeiro states lifts order volumes for heavy-duty systems. ANVISA regulatory alignment with international equipment standards shapes import specifications. State-level sanitation companies separate equipment procurement from service contracts, compressing OEM aftermarket revenue.
High Power Air Pump Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the high power air pump market. Tier-one participants leverage captive supply chains and aftermarket service density to lock in replacement part revenue. Specialist fabricators compete on customization speed for niche pressure specifications. Dominant competitive moves include strategic partnerships for remote site electrification projects and portfolio diversification into solar powered configurations.
Among European integrated industrial groups, Atlas Copco AB and Ingersoll Rand exemplify the full-line archetype with extensive aftermarket networks. Parker-Hannifin Corporation represents the precision-component specialist tier with concentrated distribution channel control. These three anchors illustrate how geographic origin and corporate structure map to competitive positioning: Swedish and American full-line players versus American precision specialists.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Ingersoll Rand |
| Parker-Hannifin Corporation |
| Eaton Corporation plc |
| SPX Flow |
| Grundfos Holding A/S |
| Flowserve Corporation |
| Enerpac Tool Group Corp. |
| GEA Group Aktiengesellschaft |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for permanent magnet motor assemblies concentrate pricing power among foundries with captive neodymium sourcing, compressing margin structures for electric-drive manufacturers while elevating procurement leverage for integrated OEMs with backward component control.
Pricing Analysis
North American electric motor configurations command 15-25% premiums over comparable induction-drive units sourced from China's manufacturing belt. Three-tier pricing structure across premium permanent magnet, standard induction, and economy-grade pneumatic levels separates certified EPA-compliant systems from open-frame legacy architectures. Pricing pressure stems from rare earth magnet cost volatility as neodymium and dysprosium price swings transmit directly to motor-drive bill-of-materials. Municipal wastewater authorities exhibit highest price sensitivity due to unbundled procurement frameworks, while oil and gas extraction operators prioritize torque density over capital expenditure minimization.
Supply Chain Analysis
Strategic stockpiling of alloy-reinforced piston castings characterizes procurement behavior among Permian Basin operators confronting single-source vulnerability in European and North American foundries. Component sourcing draws from Germany for precision-machined pressure vessels, China for motor-drive electronics, and Japan for corrosion-resistant diaphragm elastomers. Supply chain risk concentrates in rare earth magnet processing concentration within China's refining corridor. Distribution runs through authorized distributor networks for mobile hydraulic variants and direct-to-plant platforms for standardized municipal replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as permanent magnet synchronous systems displace fixed-speed induction motors across oil and gas and wastewater treatment installations.
For Market Incumbents: Compound aftermarket service density through predictive maintenance platform deployment to lock in replacement part revenue streams. Deepen captive supply control over high-pressure piston casting capacity to defend against rare earth cost volatility. Prioritize dual motor platform support capabilities as permanent magnet and induction architectures fragment vendor portfolios.
For New Entrants and Emerging Players: Remote site electrification service gaps in Australian mining and sub-Saharan African agricultural corridors present white-space entry points. Solar powered configuration penetration remains underdeveloped relative to grid-tied electric systems. Pursue direct-to-plant procurement platform partnerships to bypass traditional distributor markups in municipal wastewater segments.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-optimized compressor divisions lacking aftermarket service scale. Long-term viability rests on electrification transition exposure rather than legacy pneumatic asset bases. Monitor F-Gas Regulation amendment timelines as inflection indicators for sealed compressor architecture valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive piston assembly production insulates margin structures from European foundry supply concentration. |
| Solar Powered Configuration Expansion | Photovoltaic-driven systems capture remote mining and agricultural demand across Australia's Pilbara region. |
| Digital Distribution Platform Launch | Direct-to-plant procurement bypasses traditional channel markups for standardized municipal replacements. |
| Permanent Magnet Motor Platform Development | Variable-speed synchronous architectures displace induction systems in Permian Basin extraction clusters. |
| Hermetically Sealed Compressor Redesign | Oil-free scroll architectures satisfy EU F-Gas Regulation compliance deadlines in German chemical corridors. |
Research Methodology
Desk research of customs trade databases, EPA enforcement records, and MIIT efficiency grading disclosures preceded structured interviews with maintenance directors at municipal wastewater facilities, OEM procurement teams at oil and gas operators, and aftermarket service heads at industrial distribution networks. Primary fieldwork across the United States, Germany, China, and Brazil validated secondary estimates through bottom-up order book analysis and top-down equipment installation tracking.
Variance decomposition across product type, technology platform, application environment, and end-user industry dimensions shaped volume and value outputs throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against macroeconomic infrastructure investment indicators. Forecast inputs incorporated MIIT efficiency deadline schedules, EPA emissions compliance trajectories, and municipal privatization trend velocities.
Forecasts assume regulatory continuity in EPA emissions enforcement, EU Ecodesign implementation, and China's dual carbon compliance timelines; material policy shifts would require re-modeling of electric motor adoption curves. Rare earth magnet price volatility, F-Gas Regulation amendment finalization, and technician availability constraints constitute primary revision triggers. Revision becomes warranted when permanent magnet motor cost parity thresholds cross against induction alternatives in municipal procurement frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Rental Industrial Pump Market
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Global Compressor Control Systems Market
Pumps and Control Devices
Chemical Pump Market
Pumps and Control Devices
Single-Use Pump Market
Pumps and Control Devices
Lubrication Pump Systems Market
Pumps and Control Devices
Package Pumping Station Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Steam Jet Ejector Market
Pumps and Control Devices
Mud Pumps Market
Pumps and Control Devices
Global Heavy Duty Pumps Market
Pumps and Control Devices
Circulators Market
Pumps and Control Devices
Pump Over Tanks Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
Global Smart Pumps Market