
 Latin America Centrifugal Pumps Market | 2026-2036
Latin America Centrifugal Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Centrifugal Pumps Market Foresight
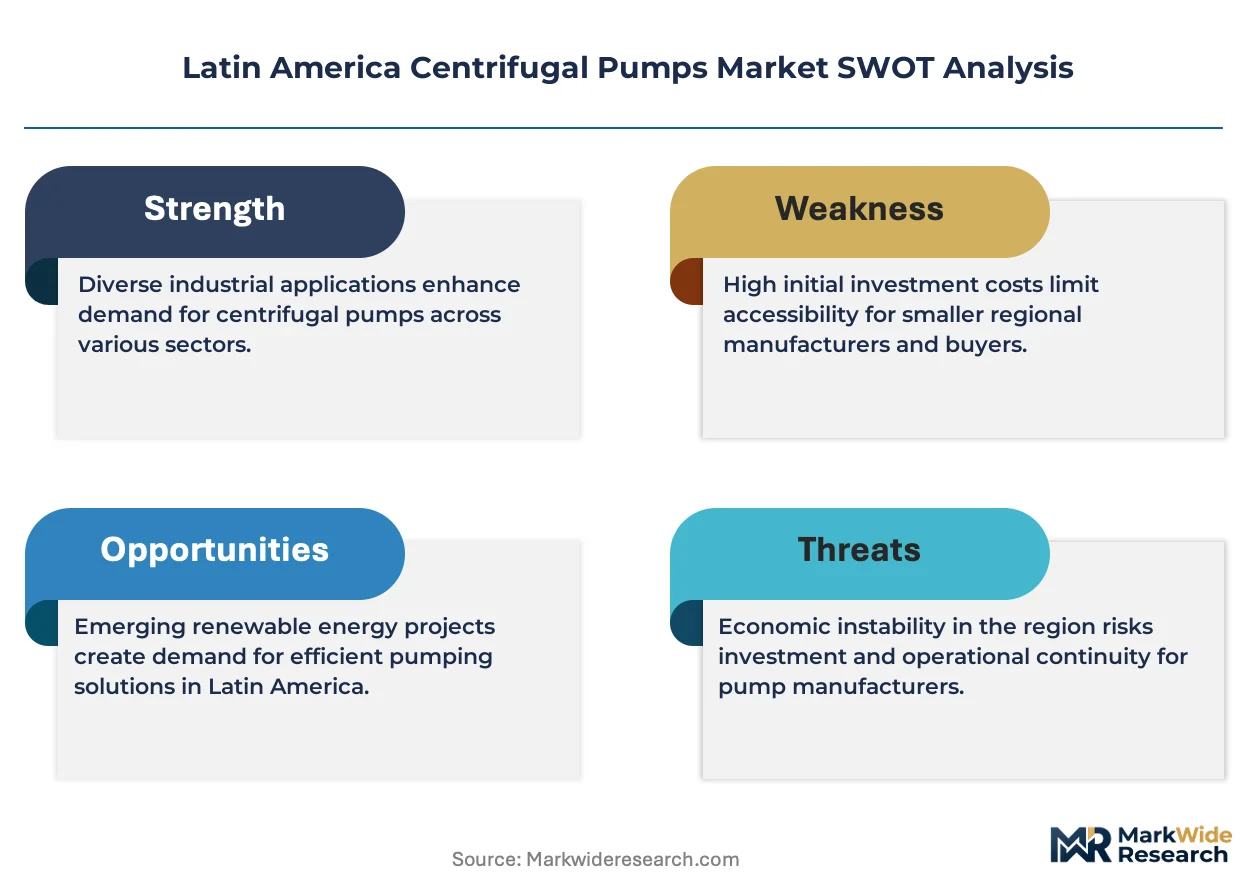
Project finance for municipal water infrastructure is tilting competitive dynamics toward vendors with balance-sheet capacity to underwrite long-term service contracts. KSB SE & Co. KGaA anchors its position through captive manufacturing of high-alloy wetted components. Sulzer Ltd differentiates via vertical integration into precision casting for corrosive duty pumps. Grundfos leverages its asset-light digital service platform to compete without heavy regional manufacturing footprint.
Centrifugal pumps convert rotational kinetic energy into hydrodynamic energy for fluid transport, typically achieving flow rates from cubic meters per hour to thousands of cubic meters per hour with impeller diameters spanning 50 mm to over 2,000 mm. Their primary commercial purpose centers on reliable fluid movement across water distribution networks, hydrocarbon processing trains, and thermal power cycles. The water supply product type dominates installed base value across Latin American utilities, while oil and gas end users command premium pricing for API-compliant heavy-duty configurations. Electric drive types occupy the volume majority, though solar drive types gain traction in off-grid agricultural zones.
Brazil's ANA water agency and Mexico's CONAGUA enforce efficiency mandates that filter procurement specifications toward higher-specific-speed pump designs. Argentina's IRAM standards and Chile's Superintendencia de Servicios Sanitarios add compliance layers for cross-border suppliers. Stakeholders must monitor how proposed updates to Mercosur technical regulations harmonize test standards across the customs union.
Market Dynamics
Energy efficiency mandates from Brazil's ANA and Mexico's CONAGUA are compressing procurement cycles toward higher-specific-speed pump designs, forcing vendors to reconfigure product portfolios or exit municipal tenders entirely.
Growth Catalysts
- Municipal Water Modernization:Brazil's federal water infrastructure programs are replacing legacy fixed-speed installations with variable frequency drive systems. State water utilities in São Paulo and Minas Gerais account for concentrated order volume.
- NOM-001-ENER Efficiency Standards:Mexico's mandatory pump efficiency labeling is disqualifying import-only suppliers without localized testing capabilities. Domestic assembly operations are expanding near Querétaro to maintain market access.
- Solar Drive Adoption:Photovoltaic-powered centrifugal pumps are displacing diesel units in off-grid agricultural zones across northeastern Brazil and northern Mexico. Irrigation cooperatives are financing deployments through development bank credit lines.
Market Restraints
- High-Alloy Input Volatility:Duplex stainless steel and super-duplex casting feedstock prices fluctuate with nickel and molybdenum exchange rates. Foundry capacity concentrates in southern Brazil and imported casting lead times extend to 16 weeks.
- Cross-Border Certification Friction:Argentina's IRAM testing protocols remain non-harmonized with Mercosur technical regulations. Manufacturers must duplicate certification efforts to serve Buenos Aires provincial utilities.
- Magnetic Drive Substitution:Sealless magnetic drive pumps are capturing corrosive chemical duty applications previously served by mechanically sealed centrifugal designs. Petrochemical end users in Bahía Blanca are piloting conversions.
Strategic Opportunities
- Chilean Mining Desalination:Copper and lithium extraction operations in Antofagasta are scaling seawater reverse osmosis feed pump capacity. High-pressure multistage configurations face supply gaps from established vendors.
- Digital Service Platforms:Remote monitoring and predictive maintenance subscriptions are creating recurring revenue streams independent of equipment sales. Brazilian sugar-ethanol processors are early adopters of uptime-guarantee contracts.
- Colombian Municipal PPP Structures:Bogotá's water utility is tendering 15-year concession contracts bundling pump supply with operation and maintenance. Balance-sheet capacity to underwrite performance guarantees separates qualified bidders.
Industry Challenges
- Hydraulic Design Talent Scarcity:Computational fluid dynamics specialists with pump-specific expertise are concentrated at federal universities in São Carlos and Campinas. Private-sector recruitment competes with academic and oil-sector compensation.
- Legacy Control System Integration:Municipal utilities in Mexico operate SCADA networks with proprietary protocols from 1990s-era installations. New pump variable frequency drives require custom gateway development for seamless commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Centrifugal Pumps Market |
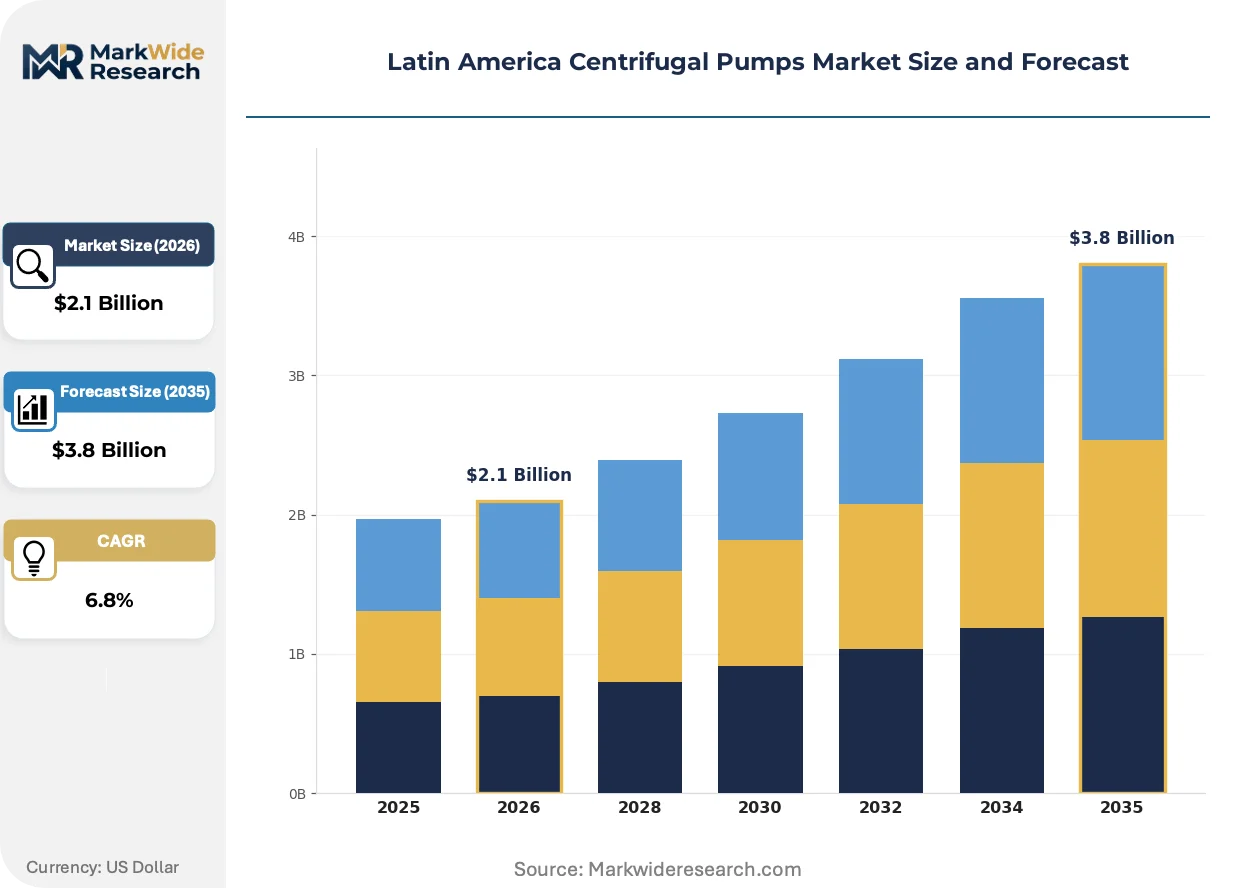
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Processing, Water Supply, HVAC, Fire Protection End User: Oil & Gas, Agriculture, Power Generation, Municipal Installation Type: Onshore, Offshore, Industrial, Commercial Drive Type: Electric, Diesel, Solar, Magnetic |
| Companies Covered | Baker Hughes Company, Wilo SE, Sulzer Ltd, KSB SE & Co. KGaA, Schlumberger Ltd, Ebara Corporation, ITT Inc, Weir Group PLC, Grundfos, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Centrifugal Pumps Market Shifts & Advancements
Fluid handling architectures are converging with edge computing and materials science advances, compressing the traditional separation between mechanical equipment and digital control layers.
Computational fluid dynamics simulation is hybridizing with generative design algorithms to optimize impeller geometries for specific duty points. Brazilian pump OEMs are adopting cloud-based topology optimization to reduce prototyping cycles from months to weeks. This capability is compressing R&D cost structures for mid-tier manufacturers competing against established European suppliers.
CONAGUA's proposed updates to NOM-001-ENER are tightening minimum efficiency index thresholds for clean water pumps above 10 kW. The regulatory revision will disqualify single-suction single-stage designs that dominated prior procurement cycles. Municipal water utilities in Jalisco and Nuevo León are pre-qualifying only mixed-flow and vertical turbine configurations for upcoming tenders.
After-sales service unbundling is fragmenting traditional full-service contracts into componentized offerings. Brazilian sugar mills are separately sourcing spare parts, field labor, and remote diagnostics from specialized providers rather than single-source OEM arrangements. This pattern is most pronounced in São Paulo state's ethanol processing corridor where maintenance budgets face pressure from commodity price cycles.
Latin America Centrifugal Pumps Market Segmentation
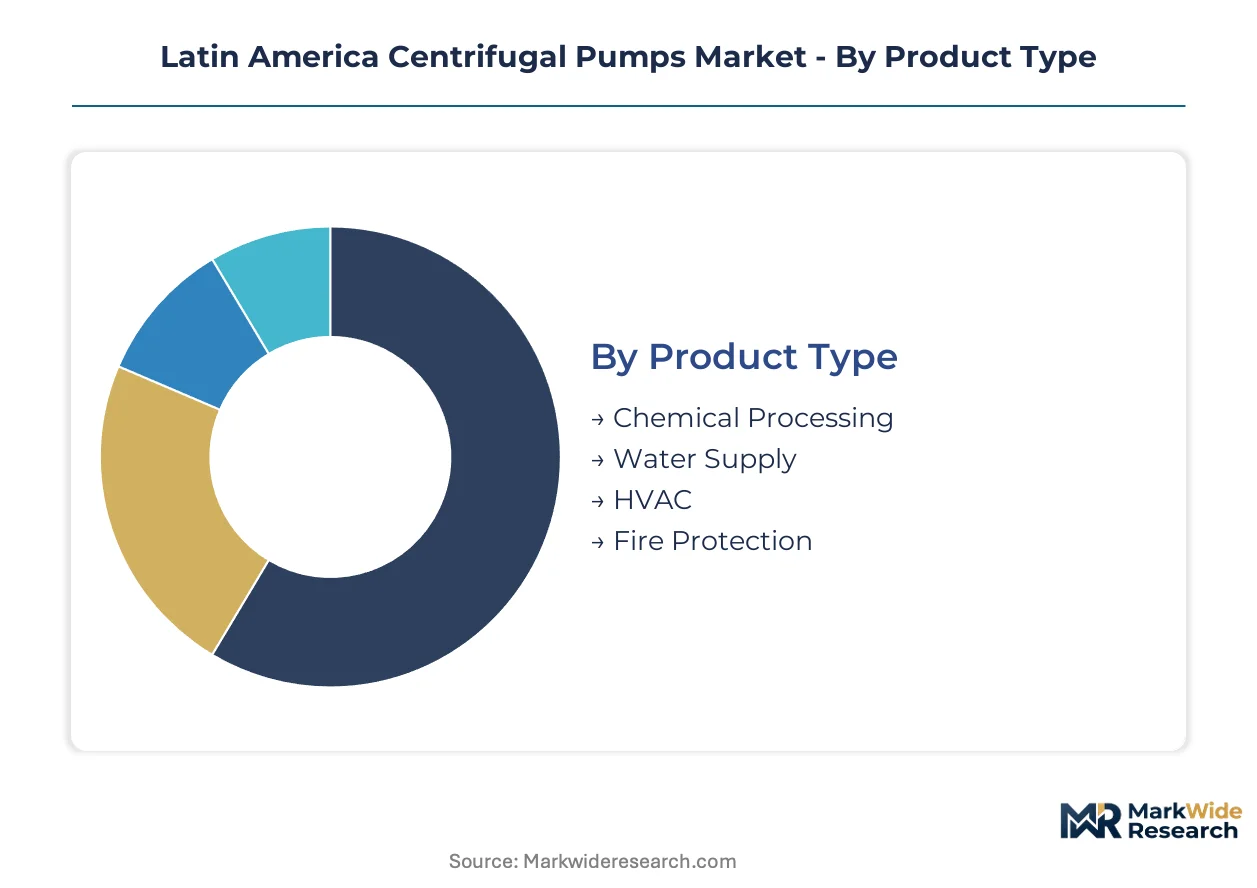
Segmentation in the Latin America centrifugal pumps market reveals distinct replacement cycles and procurement patterns across duty applications. Understanding which configurations turn over fastest versus which anchor long-term installed base value shapes portfolio strategy for regional suppliers.
Product Type:
Water supply installations rotate slowest with 15-20 year lifecycles, while chemical processing units face accelerated replacement from corrosion-induced failures.
- Water Supply:Single-suction and vertical turbine configurations handle potable water distribution and wastewater transport across Brazilian municipal networks. São Paulo's SABESP and Mexico City's SACMEX account for concentrated procurement volume under federal modernization mandates.
- Chemical Processing:ANSI and ISO-compliant designs with exotic alloy wetted parts resist aggressive process fluids in Brazilian petrochemical complexes. Duplex stainless steel specifications dominate Camacari and Coatzacoalcos industrial clusters where chloride exposure accelerates wear.
- HVAC:End-suction and inline circulators serve commercial building climate systems with standardized catalog offerings.
- Fire Protection:Horizontal split-case and vertical turbine pumps meet NFPA and local civil defense codes for industrial facility safety systems.
Water supply dominates installed base. Chemical processing is where expansion concentrates.
End User:
Municipal utilities operate on decade-scale capital cycles, while agricultural buyers make seasonal equipment decisions tied to crop financing windows.
- Municipal:State water companies across Brazil's ANA-regulated territories and Mexico's CONAGUA jurisdictions procure multistage and mixed-flow designs for distribution networks. Jalisco's SIAPA and Minas Gerais's COPASA drive tender volumes for efficiency-compliant equipment.
- Oil & Gas:API 610 and 682-compliant heavy-duty pumps handle crude transport and refinery processes. Pemex downstream operations and Petrobras pre-salt developments specify barrel-type and between-bearings configurations for high-pressure hydrocarbon duty.
- Agriculture:Surface and submersible pumps serve irrigation cooperatives in Brazil's São Francisco Valley and Mexico's Yaqui Valley.
- Power Generation:Boiler feed and cooling water pumps support thermal and combined-cycle plants across the region.
Municipal anchors replacement demand. Agriculture is climbing the fastest on solar-drive adoption.
Installation Type:
Onshore infrastructure commands volume scale, while offshore specifications extract premium pricing through certification complexity.
- Onshore:Fixed installations across pipeline stations, treatment facilities, and process plants constitute the volume majority. Brazilian midstream operators and Mexican water utilities standardize on horizontally mounted split-case and end-suction configurations for maintenance accessibility.
- Industrial:Heavy-duty process pumps in corrosive and abrasive duty applications require specialized metallurgy and sealing systems.
- Offshore:Platform and FPSO installations demand compact, high-reliability designs with marine-grade coatings and explosion-proof ratings.
- Commercial:Building services applications prioritize compact footprint and low noise signature over extreme performance specifications.
Onshore holds the deepest installed base. Offshore is gaining share fastest on pre-salt development.
Drive Type:
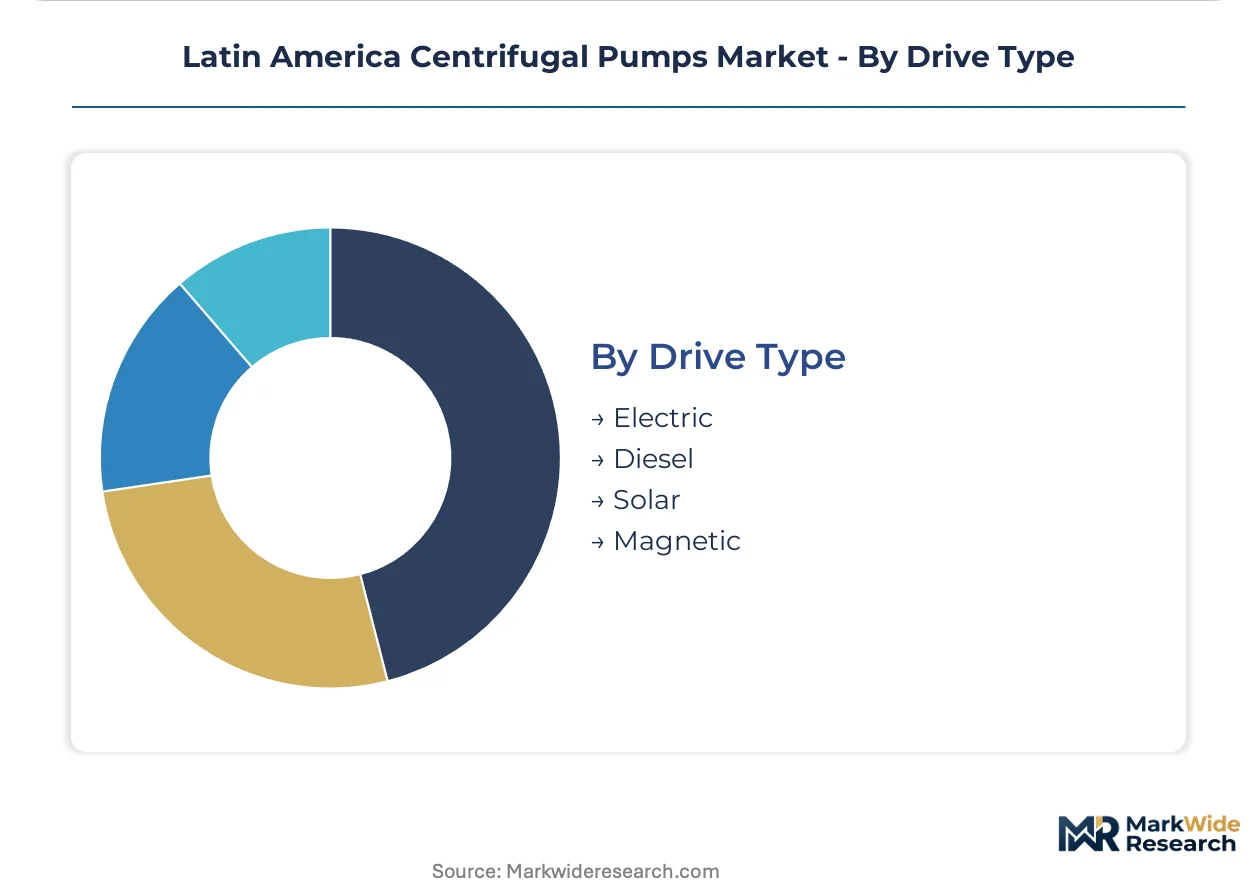
Electric drives anchor utility-scale procurement, while solar configurations disrupt agricultural segments through distributed generation economics.
- Electric:Grid-connected induction and synchronous motors paired with variable frequency drives dominate municipal and industrial specifications. Brazil's PROCEL and Mexico's CONUEE efficiency labeling programs filter procurement toward premium-efficiency motor-pump packages.
- Solar:Photovoltaic-powered DC and AC pump systems displace diesel units in off-grid agricultural zones. Northeastern Brazil's irrigation districts and northern Mexico's ejido cooperatives finance deployments through BNDES and FIRA development credit lines.
- Diesel:Portable and backup power configurations persist in remote construction and emergency applications.
- Magnetic:Sealless drive systems capture chemical duty applications requiring zero emissions containment.
Electric commands installed base value. Solar is where steepest expansion trajectory materializes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands pricing premiums through scale-driven procurement consolidation, while Argentina's certification friction forces suppliers to absorb margin compression through duplicated testing spend.
Brazil
São Paulo's SABESP and Minas Gerais's COPASA drive municipal pump replacement cycles under ANA efficiency mandates. PROCEL labeling filters procurement toward premium-efficiency motor-pump packages. The Camacari petrochemical cluster in Bahia specifies duplex stainless steel pumps for chloride-heavy process duty.
Mexico
CONAGUA's NOM-001-ENER standards disqualify import-only suppliers lacking localized testing infrastructure. Jalisco's SIAPA and Nuevo León utilities pre-qualify mixed-flow configurations for upcoming tenders. Assembly operations near Querétaro expand to maintain market access under tightening efficiency thresholds.
Argentina
IRAM testing protocols remain non-harmonized with Mercosur technical regulations, forcing duplicate certification efforts. Buenos Aires provincial utilities concentrate procurement volume for vertical turbine installations. Bahía Blanca petrochemical end users pilot magnetic drive conversions for corrosive chemical duty.
Chile
Antofagasta's copper and lithium extraction operations scale seawater reverse osmosis feed pump capacity. The Superintendencia de Servicios Sanitarios adds compliance layers for cross-border suppliers. High-pressure multistage configurations face supply gaps from established vendors in the mining desalination segment.
Colombia
Bogotá's water utility tenders 15-year concession contracts bundling pump supply with operation and maintenance. Balance-sheet capacity to underwrite performance guarantees separates qualified bidders in municipal PPP structures. Caribbean coastal irrigation districts finance solar-drive deployments through development bank credit lines.
Latin America Centrifugal Pumps Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain, supplying castings and precision-machined parts to final assemblers. The vendor base stratifies across three tiers: multinational OEMs with captive service networks, regional assemblers with localized testing capabilities, and specialized foundries feeding alloy components upstream. Consolidation pressures concentrate in the middle tier as efficiency mandates raise capital barriers to municipal tender participation. Dominant competitive moves include backward integration into precision casting capacity and geographic expansion through domestic assembly partnerships.
Among European-headquartered pump OEMs, KSB SE & Co. KGaA and Sulzer Ltd exemplify divergent strategic postures. KSB anchors its position through in-house production of high-alloy wetted components, while Sulzer occupies a position emphasizing upstream control over precision casting for corrosive duty applications. Grundfos represents the asset-light archetype, competing through digital service platforms without heavy regional manufacturing footprint.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Wilo SE |
| Sulzer Ltd |
| KSB SE & Co. KGaA |
| Schlumberger Ltd |
| Ebara Corporation |
| ITT Inc |
| Weir Group PLC |
| Grundfos |
| Others |
Supply & Pricing Matrix
Nickel and molybdenum exchange rate volatility determines both pricing tier spreads and supply chain shape across Latin American centrifugal pump markets. Duplex stainless steel feedstock fluctuations compress margins for foundry-dependent assemblers while rewarding vendors with captive alloy production.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. API 610-certified heavy-duty configurations command substantial premiums over municipal water specifications, with price differentiation driven by metallurgical grade and after-sales bundling. Cost compression in mid-tier municipal segments is intensifying because CONAGUA efficiency mandates force R&D recapture into narrower product lines. Agricultural cooperatives exhibit highest price sensitivity, while mining desalination operators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
High-alloy casting feedstock draws from Brazilian foundry clusters, Chinese nickel processors, and European specialty steel mills. Duplex stainless steel, super-duplex formulations, and precision-machined bearing housings constitute critical input dependencies. Single-source vulnerability concentrates in southern Brazilian foundry capacity where lead times extend unpredictably. Distribution runs through OEM-direct channels for large industrial projects and specialized pump distributors for municipal and agricultural segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's centrifugal pump market fragments across efficiency mandates, creating niches for specialists with localized testing infrastructure and balance-sheet capacity for long-term service contracts.
For Market Incumbents: Entrench municipal water positions by expanding captive foundry capacity near Querétaro to satisfy NOM-001-ENER localization requirements. Acquire precision casting specialists in southern Brazil to secure duplex stainless steel supply chains against nickel volatility. Magnetic drive substitution in Bahía Blanca petrochemical corridors demands defensive R&D investment in sealless configurations. For New Entrants and Emerging Players: Establish a beachhead in Chilean mining desalination where high-pressure multistage supply gaps persist among established vendors. Target Colombian municipal PPP structures in Bogotá where 15-year concession bundling favors new balance-sheet entrants over traditional equipment sellers. Pursue solar-drive agricultural deployments through BNDES and FIRA credit line partnerships. For Investors and Strategic Acquirers: Regional assemblers with CONAGUA-certified testing laboratories represent the most defensible acquisition archetype as efficiency mandates raise capital barriers. Long-term viability hinges on exposure to municipal modernization cycles rather than commodity-linked industrial replacement. Monitor CONAGUA's proposed NOM-001-ENER threshold revisions as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive duplex stainless supply insulates margins from nickel exchange volatility. |
| Domestic Assembly Partnership | Querétaro operations preserve NOM-001-ENER market access under tightening thresholds. |
| Digital Service Platform Launch | Predictive maintenance subscriptions generate recurring revenue beyond equipment sales cycles. |
| Magnetic Drive Product Line Expansion | Sealless configurations capture corrosive chemical duty from mechanically sealed designs. |
| Municipal PPP Concession Bid | Balance-sheet underwriting of 15-year performance guarantees secures installed base lock-in. |
Research Methodology
Initial hypotheses were tested against primary input from municipal utility procurement directors, petrochemical maintenance engineers, agricultural cooperative managers, and foundry operations heads and refined through secondary validation. Trade flow databases, ANA and CONAGUA regulatory filings, PROCEL efficiency labeling records, and customs import statistics provided triangulation anchors. Bottom-up tender tracking across Brazilian state water companies and top-down industrial production indices were reconciled to establish market sizing boundaries.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by duty application, end-user procurement cycle patterns, drive technology substitution trajectories, and regional regulatory cluster variations. CAGRs were derived from installed base turnover rates and efficiency mandate implementation schedules. Hydraulic design talent scarcity curves and alloy input price elasticity informed supply-side constraint parameters.
Sensitivities concentrate around CONAGUA NOM-001-ENER threshold revisions, ANA efficiency mandate enforcement intensity, and nickel-molybdenum exchange rate corridors. Forecasts embed assumptions regarding municipal modernization program continuity and solar-drive agricultural financing availability. Material shifts in Mercosur technical regulation harmonization or pre-salt development pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Electric Submersible Pump (ESP) in Oil and Gas Market
Pumps and Control Devices
Energy-Saving Canned Motor Pump Market
Pumps and Control Devices
Paint Pump Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
Fuel Transfer Pump Market
Pumps and Control Devices
Circulators Market
Pumps and Control Devices
Automatic Water Level Controller Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
Drum Pump Market
Pumps and Control Devices
Pumps and Trigger Spray Market
Pumps and Control Devices
Sea Water Injection Pumps Market
Pumps and Control Devices
Global Solar-Powered Pump Market
Pumps and Control Devices
Pool Heat Pumps Market