
 Fluid Power Equipment Market | 2026-2036
Fluid Power Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Power Equipment Market Analysis
Electrohydraulic integration is fragmenting traditional hydraulic architectures into modular, sensor-driven subsystems. Bosch Rexroth AG leverages its digital hydraulics portfolio to anchor high-precision motion control across European machine tool builders. Parker-Hannifin Corporation competes through extensive backward integration into seal technologies and filtration media. SMC Corporation specializes in compact pneumatic actuators that displace hydraulics in clean-room and food-processing environments.
Fluid power equipment comprises pumps, cylinders, valves, and actuators that transmit force through pressurized liquids or gases, typically operating at hydraulic pressures from 3,000 to 6,000 psi in heavy-duty industrial settings. These systems convert mechanical energy into fluid pressure to drive linear or rotary motion in machinery where electrical alternatives fail on torque density or environmental ruggedness. Hydraulic pumps and valves capture the dominant share of product-level revenue, reflecting their critical role in closed-loop circuit integrity and system efficiency. Pneumatic cylinders are displacing hydraulics in lighter-load factory automation where compressed air infrastructure already exists. Hybrid electrohydraulic technology is expanding fastest in mobile equipment applications where fuel efficiency regulations demand variable-displacement intelligence.
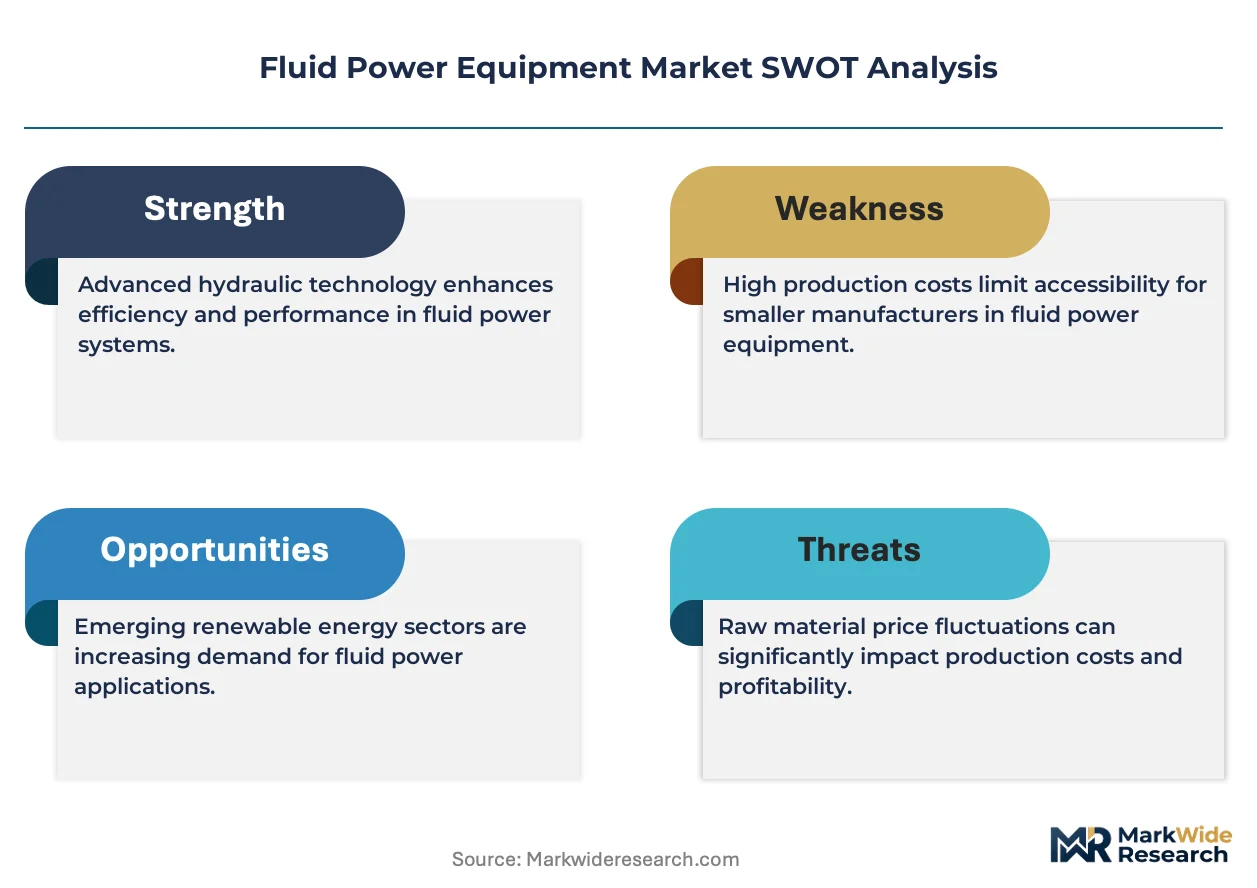
EPA emissions standards under the Clean Air Act constrain hydraulic fluid formulations and leak rates in US-built machinery, while REACH and the EU F-Gas Regulation govern chemical composition and greenhouse gas footprint across European supply chains. Japan's METI energy efficiency directives pressure OEMs to adopt variable-speed pump drives and regenerative hydraulic circuits. Stakeholders must weigh the capital intensity of smart fluid power retrofits against the operational savings from predictive maintenance architectures and energy recovery systems.
Market Dynamics
Electrohydraulic integration is fragmenting traditional hydraulic architectures into modular, sensor-driven subsystems that demand entirely new supplier capabilities and certification protocols across construction, agriculture, and industrial automation end-uses.
Growth Catalysts
- EU F-Gas Regulation:Tightening hydraulic fluid specifications are forcing OEMs to upgrade seal materials and filtration systems, creating replacement demand across European machine tool and mobile equipment fleets.
- China infrastructure programs:State-backed procurement of excavators, loaders, and cranes sustains order volumes for high-pressure hydraulic pumps and cylinders from domestic and foreign suppliers.
- Variable-displacement pump intelligence:Fuel efficiency mandates from Japan's METI accelerate adoption of regenerative hydraulic circuits in construction and agricultural machinery.
Market Restraints
- Specialized steel and alloy supply:Cylinder barrel and piston rod production depends on concentrated specialty steel mills in Germany and Japan, exposing fabricators to input volatility and extended lead times.
- EPA leak-rate enforcement:Clean Air Act compliance costs for fluid containment and disposal disproportionately burden smaller hydraulic system rebuilders and aftermarket service providers.
- Electromechanical substitution:Precision servo-electric actuators are capturing linear motion applications below 5,000 psi in packaging and electronics assembly, compressing addressable market for compact pneumatic cylinders.
Strategic Opportunities
- India manufacturing expansion:PLI scheme incentives for construction equipment and textile machinery create first-mover advantage for localized hydraulic component production and service networks.
- Predictive maintenance architectures:Integration of pressure sensors and edge computing into hydraulic circuits enables aftermarket service contracts and remote monitoring revenue streams.
- Clean-room pneumatic displacement:Semiconductor and pharmaceutical manufacturing growth in South Korea and Taiwan drives demand for oil-free compressed air systems that eliminate hydraulic contamination risk.
Industry Challenges
- Mechatronics skill convergence:Hydraulic technicians must now command PLC programming, sensor calibration, and data analytics competencies that traditional fluid power training programs do not deliver.
- Retrofit capex burden:Smart hydraulics upgrades require simultaneous investment in pumps, controllers, and communication protocols, stretching maintenance budgets for aging industrial press and injection molding fleets.
- ISO 4406 cleanliness certification:Achieving and maintaining prescribed particulate count levels demands continuous filtration monitoring that many distributor service centers lack infrastructure to support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Power Equipment Market |
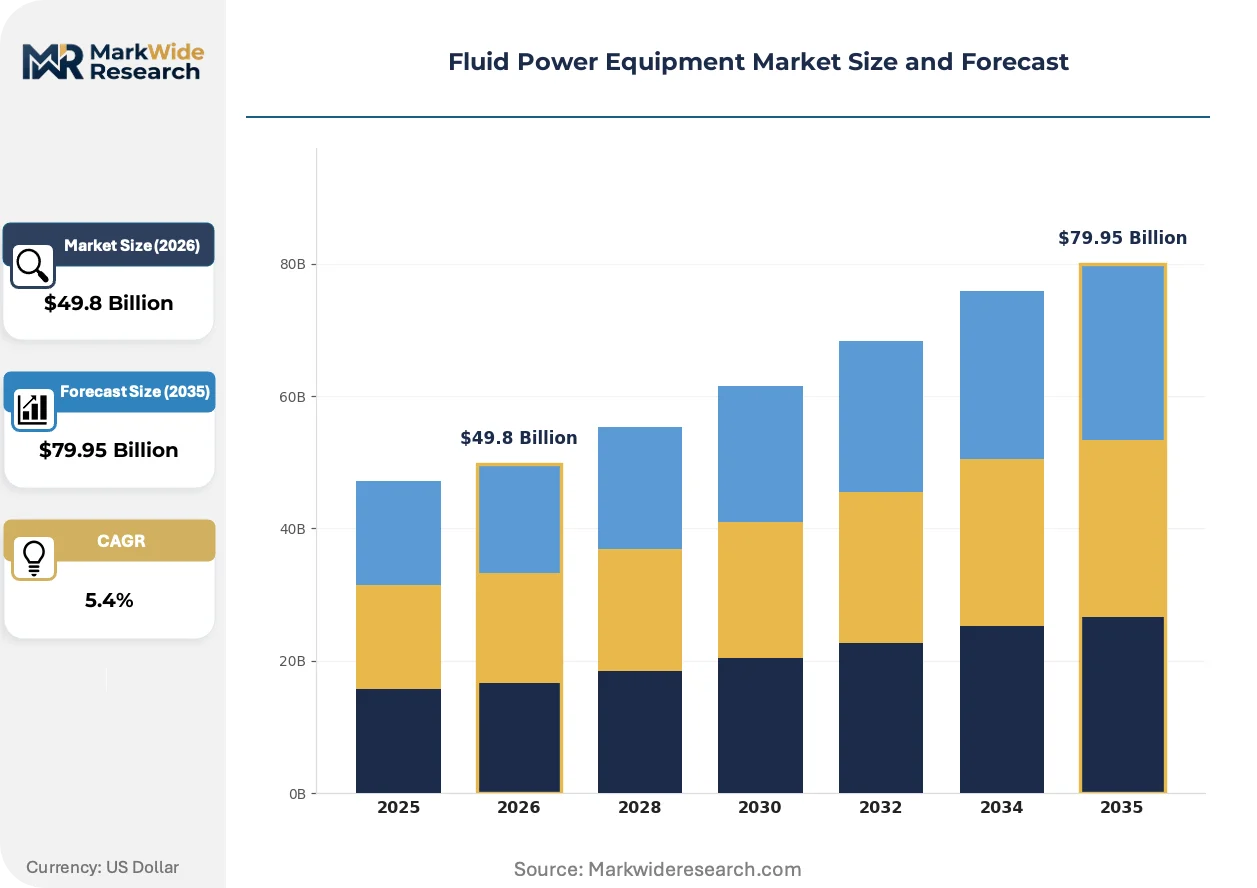
| Market Size in 2026 | $49.8 Billion |
| Market Size in 2035 | $79.95 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Pumps, Pneumatic Cylinders, Valves, Filters Technology: Electrohydraulic, Pneumatic, Hydraulic, Hybrid End User: Manufacturing, Construction, Automotive, Aerospace Application: Industrial Machinery, Mobile Equipment, Marine, Energy |
| Companies Covered | Eaton Corporation plc, Emerson Electric Co., Bosch Rexroth AG, Atos S.p.A., Festo SE & Co. KG, Parker-Hannifin Corporation, SMC Corporation, Bucher Hydraulics GmbH, Danfoss A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Power Equipment Market Emerging Trajectories
Digital twin technology is virtualizing fluid power system design and commissioning, compressing development cycles while enabling remote diagnostics that reshape aftermarket service economics across mobile and industrial equipment segments.
Digital hydraulics is virtualizing valve control architectures by replacing discrete directional valves with software-defined switching algorithms. German machine tool builders are piloting these systems for sub-millisecond motion precision. The technology is virtualizing hardware redundancy, reducing component count while improving fault tolerance in high-cycle press and forming applications.
REACH chemical restrictions and the EU F-Gas Regulation are prohibiting specific hydraulic fluid base stocks and greenhouse gas-intensive blowing agents for pneumatic seals. Formulators must requalify lubricant additive packages under shortened compliance deadlines. Mobile equipment OEMs serving European markets are accelerating qualification of bio-based and synthetic ester alternatives ahead of 2030 phase-down targets.
Buyer consolidation among rental fleet operators is compressing specification cycles and demanding standardized maintenance protocols across multi-brand equipment portfolios. Large construction rental companies in North America and Western Europe now mandate telematics-ready hydraulic systems as a procurement precondition. This behavioral shift forces component suppliers to prioritize controller compatibility and data interoperability over proprietary system architectures.
Fluid Power Equipment Market Segmentation
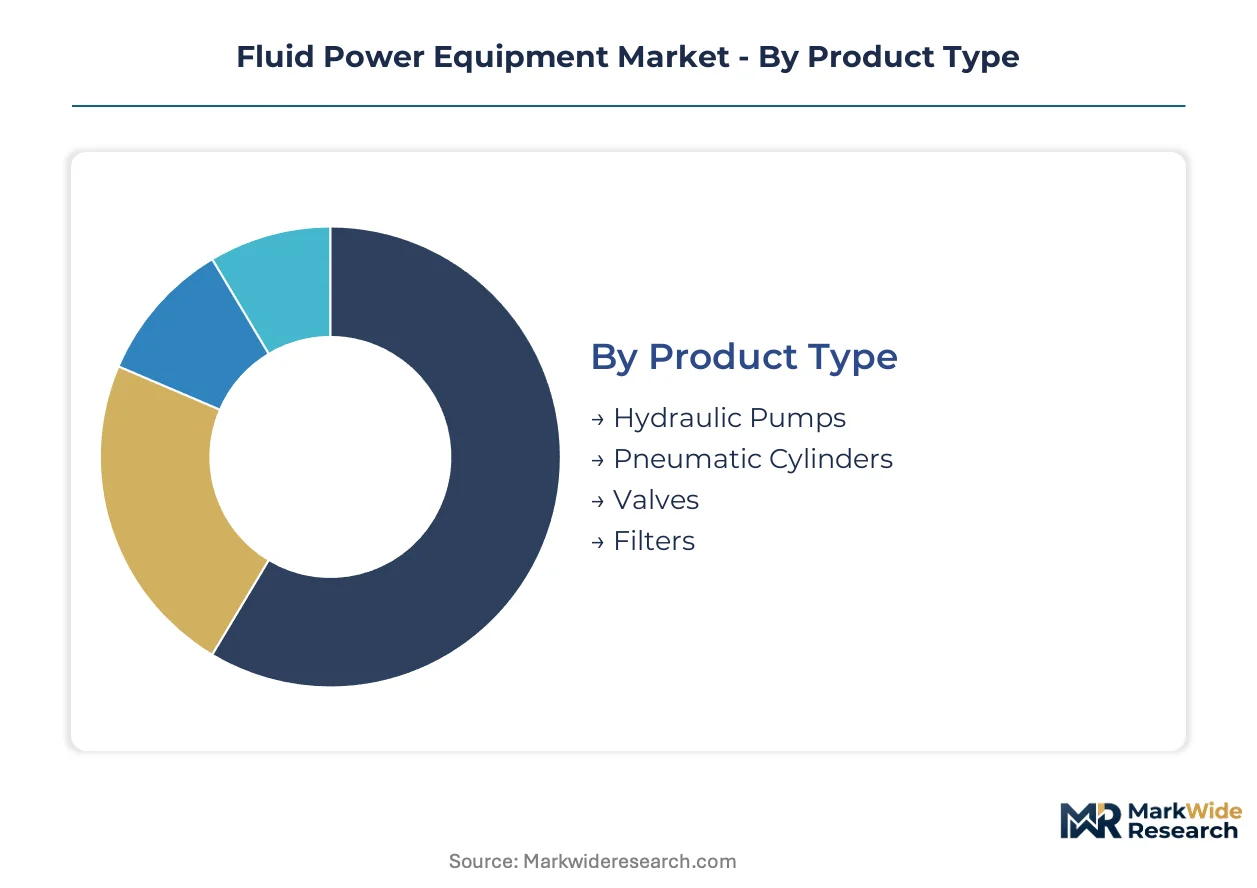
Fluid power equipment segmentation reveals divergent service intensity across product categories, with hydraulic systems demanding continuous filtration monitoring and pneumatic circuits requiring less intensive lifecycle support. Component modularity and sensor integration are reshaping how OEMs structure aftermarket contracts and spare parts forecasting.
Product Type:
After-sales service intensity varies dramatically across product categories, with high-pressure hydraulic components requiring predictive maintenance architectures while pneumatic elements sustain simpler replacement cycles.
- Hydraulic Pumps:These positive-displacement machines generate system pressure through gear, vane, or piston configurations, typically operating at 3,000 to 6,000 psi in heavy-duty settings. Demand concentrates in German and Japanese construction equipment OEMs expanding electrohydraulic system orders, driven by METI fuel efficiency directives and EU F-Gas fluid specification tightening.
- Pneumatic Cylinders:Compressed air actuators deliver linear motion in lighter-load factory automation where oil-free operation is mandatory. Clean-room and food-processing environments in Taiwan and South Korea are displacing hydraulics with these systems, eliminating contamination risk in semiconductor and pharmaceutical manufacturing.
- Valves:Directional, pressure, and flow control elements govern circuit integrity in closed-loop architectures.
- Filters:Particulate removal systems maintain ISO 4406 cleanliness standards across hydraulic and pneumatic circuits.
By volume, Hydraulic Pumps leads. By growth pace, Pneumatic Cylinders is expanding most quickly.
Technology:
Cost tier stratification separates premium electrohydraulic intelligence from conventional pneumatic infrastructure, with hybrid architectures capturing mid-tier mobile equipment applications.
- Electrohydraulic:Sensor-integrated pump and valve systems enable variable-displacement control through software-defined algorithms. German machine tool builders pilot these architectures for sub-millisecond motion precision, fragmenting traditional hydraulic systems into modular subsystems with entirely new certification demands.
- Pneumatic:Compressed air technology dominates light-load factory automation where infrastructure already exists. Food-processing and electronics assembly lines in South Korea rely on oil-free pneumatic circuits to satisfy clean-room contamination protocols.
- Hydraulic:Conventional fluid power systems transmit force through pressurized mineral oil in heavy machinery.
- Hybrid:Combined electro-mechanical and hydraulic architectures optimize energy recovery in mobile equipment.
By installed base, Hydraulic systems dominate. By expansion trajectory, Electrohydraulic is gaining share fastest.
End User:
Application maturity determines specification cycles, with aerospace demanding decade-long qualification timelines while manufacturing tolerates faster technology refresh.
- Manufacturing:Machine tools, presses, and automated assembly lines consume fluid power for precision motion control. European metal-forming operations are retrofitting aging fleets with digital hydraulics to compress development cycles and enable remote diagnostics.
- Construction:Excavators, loaders, and cranes depend on high-pressure hydraulic circuits for lifting and earthmoving torque. China's state-backed infrastructure programs sustain excavator and crane procurement volumes for domestic and foreign pump and cylinder suppliers.
- Automotive:Assembly line robotics and stamping presses require synchronized fluid power actuation.
- Aerospace:Flight control and landing gear systems demand certified hydraulic redundancy with extreme reliability margins.
By revenue concentration, Manufacturing leads. By capital intensity per installation, Aerospace is ahead.
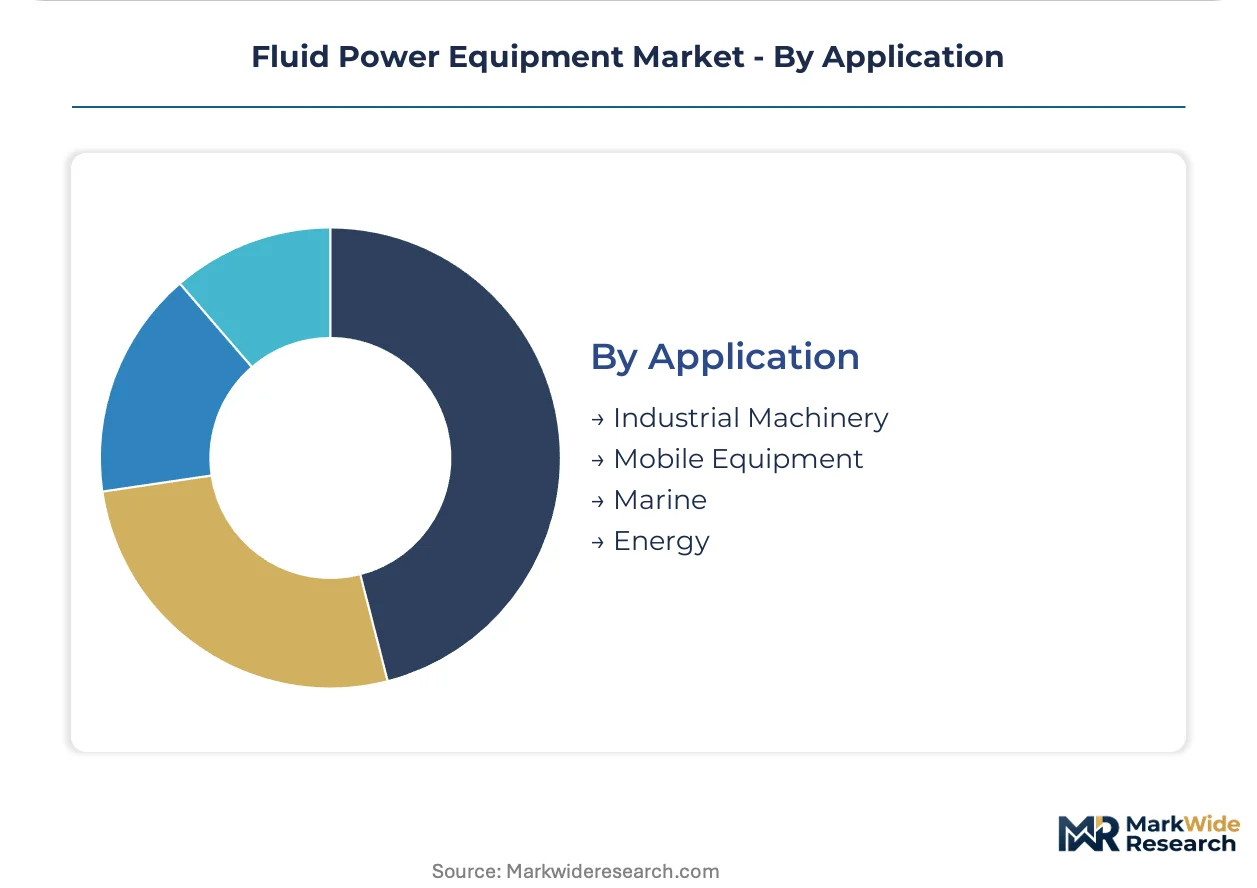
Application:
Geographic supply concentration shapes regional specification preferences, with European machine tool builders favoring digital hydraulics and Asian shipyards prioritizing corrosion-resistant marine systems.
- Industrial Machinery:Metal-forming presses, injection molding equipment, and machine tools require precise force control. German manufacturers anchor demand for high-precision motion control systems, with Bosch Rexroth supplying digital hydraulics portfolios across European builder networks.
- Mobile Equipment:Construction and agricultural machinery operate under variable load conditions in exposed environments. EPA emissions standards and Japan's METI energy efficiency directives pressure OEMs to adopt regenerative circuits and variable-speed pump drives.
- Marine:Offshore and vessel systems demand corrosion-resistant materials and sealed environmental protection.
- Energy:Oilfield and renewable power applications require high-reliability actuation in extreme temperature ranges.
By unit volume, Industrial Machinery leads. By specification complexity, Mobile Equipment is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision hydraulic systems to Chinese construction equipment OEMs, anchoring the dominant trade corridor in fluid power equipment.
United States
Domestic excavator and agricultural machinery production sustains demand for high-pressure pumps and cylinders. EPA emissions standards under the Clean Air Act constrain hydraulic fluid formulations and mandate leak-rate containment. Houston's energy sector cluster drives specialized actuation demand for oilfield and offshore applications.
Germany
Machine tool builders and automotive stamping press manufacturers anchor European demand for digital hydraulics and motion control systems. EU F-Gas Regulation and REACH chemical restrictions force reformulation of hydraulic fluids and seal materials. Stuttgart's industrial corridor hosts concentrated supplier development for electrohydraulic subsystems.
China
State-backed infrastructure programs sustain procurement volumes for excavators, loaders, and cranes from domestic and foreign suppliers. MIIT energy efficiency directives and dual carbon goals pressure OEMs to adopt variable-displacement pump intelligence. Shanghai's Yangtze River Delta manufacturing belt concentrates domestic hydraulic component fabrication and foreign joint venture operations.
Japan
Construction equipment OEMs expand electrohydraulic system orders to satisfy METI fuel efficiency directives. JIS standards and energy efficiency regulations accelerate adoption of regenerative hydraulic circuits and variable-speed pump drives. Nagoya's Chubu industrial region anchors precision hydraulic component manufacturing for domestic machinery builders.
India
PLI scheme incentives for construction equipment and textile machinery create demand for localized hydraulic component production. BIS standards and DGFT import regulations shape certification requirements for foreign suppliers entering domestic supply chains. Maharashtra's Pune-Nashik manufacturing corridor attracts first-mover investment in hydraulic cylinder and pump assembly operations.
Fluid Power Equipment Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with backward integration into seal technologies and filtration media; precision motion control specialists leveraging digital hydraulics portfolios; and compact pneumatic actuator manufacturers targeting clean-room displacement applications. Dominant competitive moves include M&A to capture sensor integration capabilities and capacity expansion to serve China infrastructure program procurement.
Within the diversified conglomerate tier, Eaton Corporation plc and Parker-Hannifin Corporation occupy positions anchored by extensive upstream control over complementary component technologies. Among German-based precision specialists, Bosch Rexroth AG exemplifies the digital hydraulics archetype serving machine tool builder networks. Japanese pneumatic specialists represented by SMC Corporation anchor the clean-room displacement segment serving semiconductor and pharmaceutical manufacturing clusters in Taiwan and South Korea.
| Leading Market Players |
|---|
| Eaton Corporation plc |
| Emerson Electric Co. |
| Bosch Rexroth AG |
| Atos S.p.A. |
| Festo SE & Co. KG |
| Parker-Hannifin Corporation |
| SMC Corporation |
| Bucher Hydraulics GmbH |
| Danfoss A/S |
| Others |
Supply Flow & Price Mechanics
Stuttgart's industrial corridor anchors European electrohydraulic subsystem production, where concentrated precision manufacturing capacity translates directly into pricing power for German component suppliers serving Chinese construction equipment OEMs. Capacity tightness at specialty steel mills in Germany and Japan feeds through to cylinder barrel and piston rod costs, compressing margins for hydraulic fabricators unable to secure long-term alloy offtake agreements.
Pricing Analysis
Electrohydraulic intelligence commands substantial premiums over conventional hydraulic architectures, while legacy pneumatic infrastructure trades at commodity-equivalent levels. Pricing stratifies across premium sensor-integrated systems, standard variable-displacement pumps, and economy fixed-displacement units. Cost compression in economy-tier pumps is intensifying because Chinese domestic manufacturers are scaling output for state-backed infrastructure procurement. Rental fleet operators demonstrate highest price sensitivity, demanding standardized maintenance protocols that erode supplier differentiation, whereas aerospace qualification timelines insulate premium-tier suppliers from procurement pressure.
Supply Chain Analysis
Specialty steel and alloy feedstock draws from concentrated mills in Germany, Japan, and select Austrian producers, creating input dependency for cylinder fabrication. High-grade chromium-molybdenum steel, precision-ground piston rods, and fluorocarbon seal compounds constitute critical component inputs. Single-source vulnerability concentrates around German specialty steel producers serving precision hydraulic applications. Distribution runs through OEM direct procurement for large construction equipment builders, with aftermarket service networks and industrial distributors handling replacement components for aging machine tool and injection molding fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluid power equipment constitutes a defensive-moat market anchored by regulatory entrenchment: EPA emissions standards, EU F-Gas Regulation, and Japan's METI directives create compliance barriers that lock in incumbent supplier relationships across decade-long equipment lifecycles.
For Market Incumbents: Insulate core positioning through captive supply of seal technologies and filtration media, while accelerating sensor integration capabilities to capture predictive maintenance revenue streams. Electromechanical substitution below 5,000 psi represents an existential threat to compact pneumatic cylinder portfolios. Certification investment in ISO 4406 cleanliness protocols defends aftermarket service contracts against distributor network competition. For New Entrants and Emerging Players: India's PLI scheme incentives for construction equipment and textile machinery represent the most penetrable entry point for localized hydraulic component production, bypassing entrenched European and Japanese supplier relationships. Clean-room pneumatic displacement in South Korean semiconductor manufacturing clusters offers white-space demand for oil-free compressed air systems. Direct technical partnership with domestic OEM procurement teams accelerates BIS certification pathways. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to monetize non-core fluid power divisions amid portfolio restructuring pressures. Long-term viability centers on electrohydraulic intelligence adoption curves across mobile equipment applications. The signal to watch is METI and EPA regulatory tightening velocity, which accelerates variable-displacement pump replacement cycles and expands addressable market for smart hydraulic retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Technologies | Parker-Hannifin Corporation's upstream control over fluorocarbon compounds reduces input volatility exposure. |
| Digital Hydraulics Portfolio Expansion | Bosch Rexroth AG's software-defined valve architectures capture sub-millisecond precision demand from German machine tool builders. |
| Localized Production in India | First-mover assembly operations in Maharashtra's Pune-Nashik corridor secure PLI scheme benefits for construction equipment supply. |
| Predictive Maintenance Architecture Deployment | Pressure sensor and edge computing integration enables aftermarket service contracts with remote monitoring revenue streams. |
| Clean-Room Pneumatic System Qualification | SMC Corporation's oil-free actuator portfolios displace hydraulics in South Korean semiconductor manufacturing environments. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs and trade data, and industry association reports from ACC and Cefic. Primary interviews engaged maintenance directors at manufacturing facilities, OEM procurement teams at construction equipment builders, aftermarket service heads at distributor networks, and plant engineers at metal-forming operations. Bottom-up component demand modeling triangulates against top-down equipment production forecasts across excavator, machine tool, and injection molding segments.
Forecast inputs incorporate hydraulic pump and cylinder shipment volumes, electrohydraulic system adoption rates, and pneumatic actuator displacement patterns across the projection horizon. Segmentation dimensions span product type, technology generation, end-use industry, and regional regulatory cluster. CAGRs derive from regression analysis of historical equipment production correlations with component intensity ratios, stress-tested against MIIT energy efficiency directive implementation timelines and EPA enforcement trajectory assumptions.
Stress conditions across specialty steel price volatility, F-Gas Regulation phase-down acceleration, and electromechanical substitution pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding infrastructure program continuity in China and METI directive compliance timelines in Japan. Cross-checking against IHS Markit equipment production databases and OEM order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Industrial Submersible Pumps Market
Pumps and Control Devices
Bubble Membrane Disc Diffuser Market
Pumps and Control Devices
Residential Pumps Market
Pumps and Control Devices
Europe Submersible Pump Market
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Global Vacuum Pump Market
Pumps and Control Devices
Global Diaphragm Pump Market
Pumps and Control Devices
Global Solar Water Pump Systems Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
India Solar Water Pump Systems Market
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Chopper Pumps Market
Pumps and Control Devices
Paint Pump Market
Pumps and Control Devices
Liquid Ring Vacuum Pump Market
Pumps and Control Devices
Progressing Cavity Pump Market