
 Subcool Metering Device Market | 2026-2036
Subcool Metering Device Market Size, Share, and Industry Trends Forecast 2026-2036
Subcool Metering Device Market Analytics
A shift from single-source procurement to multi-source qualification is realigning how OEMs and service contractors secure subcool metering instrumentation. Danfoss Group leverages its compressor technology heritage to anchor premium digital meter lines across European and North American distribution channels. Emerson Electric Co. competes through integrated HVAC controls portfolios that bundle subcool diagnostics with system automation platforms.
A subcool metering device measures the temperature depression of liquid refrigerant below its saturation point, typically employing thermocouple or thermistor sensors paired with pressure transducers to calculate actual versus target subcooling values in vapor-compression cycles. Digital meters incorporating IoT Integration and Smart Sensing technology are capturing the fastest expansion as remote diagnostics and predictive maintenance protocols displace manual gauge sets in commercial refrigeration service. Flow Meters oriented toward energy management applications sustain higher margin pools due to calibration-intensive specifications and utility-grade certification requirements.
EPA refrigerant regulations under Section 608 mandate leak repair and proper charging practices that directly elevate demand for accurate subcool measurement in the United States. CE marking under EU F-Gas Regulation and MEE dual carbon goals in China impose parallel equipment efficiency standards that shape product design and market access requirements across three continents. Stakeholders must monitor how refrigerant transition timelines toward lower-GWP alternatives alter sensor compatibility specifications and recalibration service models.
Market Dynamics
Precision charging mandates from EPA Section 608 compliance protocols are compressing service contractor tolerance for manual gauge-based subcool measurement, forcing capital redeployment toward calibrated digital instrumentation with embedded diagnostic logging.
Growth Catalysts
- EPA Refrigerant Management Rules:Leak repair thresholds and proper charging documentation requirements under Section 608 elevate accuracy demands for subcool measurement in commercial HVAC service workflows.
- Cold Chain Infrastructure Buildout:China's domestic logistics network expansion requires precision refrigeration monitoring across warehouse and transport refrigeration units, driving meter deployment at scale.
- IoT-Enabled Predictive Maintenance:Connected sensor platforms allow remote subcool diagnostics, reducing truck rolls and enabling condition-based service scheduling for multi-site operators.
Market Restraints
- Calibration Input Cost Volatility:Reference thermocouple precision and pressure transducer stability depend on specialty sensor supply concentrated in German and Japanese component manufacturers.
- Technical Limitation—Refrigerant Compatibility:Sensor materials face degradation risks with lower-GWP alternatives including R-32 and R-454B, requiring material science adaptation before full portfolio coverage.
- Regulatory Friction—EU F-Gas Phase-Down:Equipment certification timelines lag behind refrigerant transition schedules, creating approval bottlenecks for next-generation meter designs.
Strategic Opportunities
- Underpenetrated India Market:Cold chain infrastructure gaps in perishable logistics create whitespace for subcool monitoring as BIS efficiency standards tighten on commercial refrigeration equipment.
- Technology Convergence—Edge AI + Wireless Sensing:On-device inference capabilities combined with LoRaWAN or NB-IoT connectivity enable autonomous fault detection without cloud dependency for remote facilities.
- Utility Energy Management Mandates:Demand response programs in California and Texas incentivize real-time refrigerant cycle optimization, opening meter integration into building automation systems.
Industry Challenges
- Field Technician Skill Compression:Digital meter operation requires thermodynamics fluency beyond traditional gauge manifold training, widening the gap between equipment capability and workforce readiness.
- Multi-Refrigerant Certification Complexity:Separate calibration protocols for A2L mildly flammable blends extend product development cycles and service documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subcool Metering Device Market |
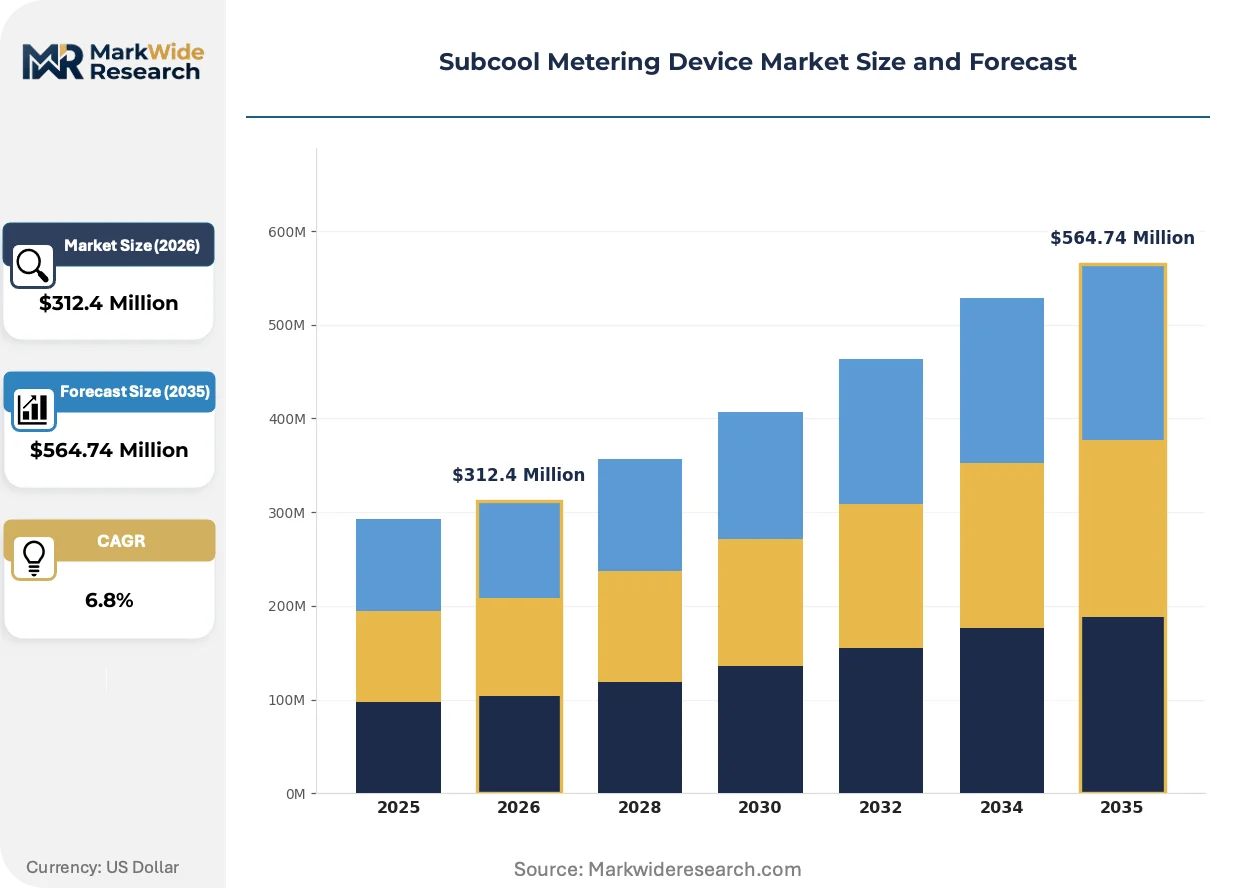
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Meters, Analog Meters, Flow Meters, Energy Meters Application: Industrial Processes, HVAC Systems, Refrigeration, Energy Management End User: Manufacturers, Contractors, Utilities, Retailers Technology: Wireless Technology, IoT Integration, Smart Sensing, Traditional Technology |
| Companies Covered | Fieldpiece Instruments Inc., Mastercool Inc., Ritchie Engineering Company Inc., Kane USA Inc., OURAN TECHNOLOGIES, Mitchell Instrument, CEM Instruments India, Danfoss Group, Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subcool Metering Device Market Evolving Landscape
Digital instrumentation architectures are displacing analog measurement conventions across commercial refrigeration service, with connectivity and embedded intelligence becoming baseline specifications rather than premium differentiators.
Smart subcool meters incorporating MEMS pressure transducers and multi-point temperature arrays are automating saturation point calculations that previously required manual psychrometric chart consultation. Large facility operators with distributed refrigeration assets are deploying these units fleet-wide to standardize charging protocols across contractor networks. The technology is automating diagnostic documentation for EPA compliance audits while compressing service call duration.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transition timelines that reshape sensor compatibility requirements. Equipment manufacturers must now validate subcool measurement accuracy across widening refrigerant portfolios including flammable A2L classifications. Commercial refrigeration OEMs in Germany and Italy are responding with modular sensor platforms permitting field-upgradable refrigerant profiles.
Service contractors are consolidating vendor relationships around instrumentation suppliers offering bundled calibration and firmware update subscriptions. Independent HVAC service firms in the United States are displacing transactional equipment purchases with multi-year meter-as-a-service agreements. This pattern concentrates procurement volume with fewer distribution channels while shifting margin capture toward recurring revenue streams.
Subcool Metering Device Market Segmentation
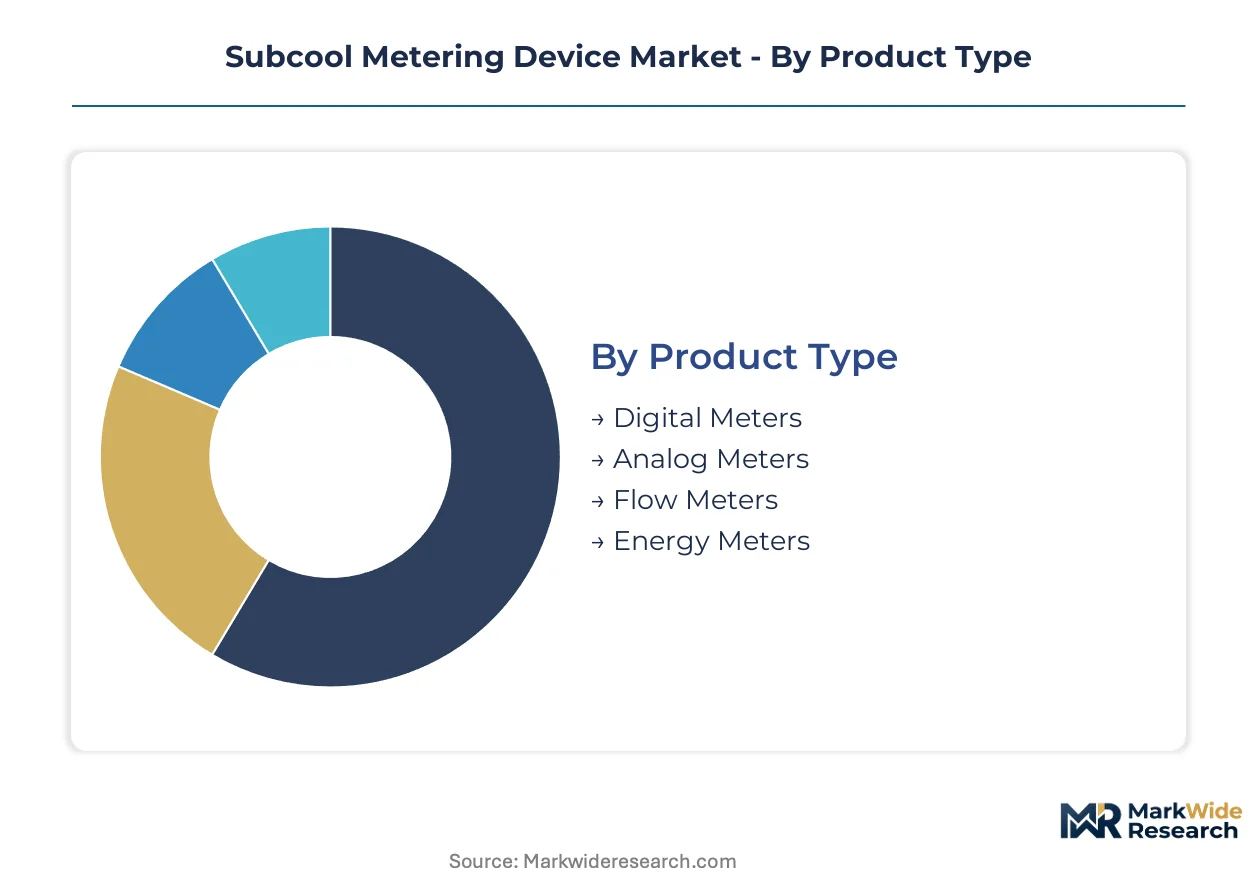
Subcool metering device procurement patterns diverge sharply across technical specifications and operational environments. Equipment replacement cycles and compliance-driven upgrades determine how manufacturers and service firms allocate capital across product tiers and connectivity levels.
Product Type:
Upgrade cycles favor precision instrumentation with embedded diagnostics over legacy gauge sets. Contractors face compressed tolerance windows under EPA Section 608 documentation mandates.
- Digital Meters:MEMS pressure transducers paired with multi-point thermocouple arrays automate saturation point calculations. Demand concentrates among US commercial HVAC service firms consolidating contractor networks around standardized charging protocols.
- Flow Meters:Calibration-intensive designs with utility-grade certification requirements serve energy management applications. German and Italian OEMs deploy these for refrigerant cycle optimization in industrial refrigeration clusters.
- Analog Meters:Conventional gauge manifold configurations persist in price-sensitive maintenance operations.
- Energy Meters:Integrated power consumption tracking supports demand response program compliance.
Volume placements concentrate in Digital Meters; the faster expansion belongs to Flow Meters.
Application:
Cost tier differentiation separates premium industrial installations from standardized commercial deployments. Capital intensity and regulatory exposure shape specification requirements.
- HVAC Systems:Connected subcool diagnostics with remote logging capabilities dominate commercial building automation retrofits. US service contractors deploy fleet-wide to compress truck rolls and standardize EPA audit documentation.
- Refrigeration:Cold chain infrastructure scaling in China drives precision monitoring across warehouse and transport units. Domestic logistics operators require calibrated instrumentation for perishable cargo compliance.
- Industrial Processes:Continuous process refrigeration demands redundant sensor arrays.
- Energy Management:Utility program participation incentivizes real-time cycle optimization.
Refrigeration commands the largest installed base; HVAC Systems are climbing the fastest.
End User:
Customer type determines procurement modality and service attachment rates. Recurring revenue models displace transactional equipment sales.
- Contractors:Independent HVAC service firms in the United States adopt meter-as-a-service subscriptions bundling calibration and firmware updates. Multi-year agreements concentrate procurement volume with fewer distribution channels.
- Utilities:Demand response administrators in California and Texas specify integrated building automation compatibility. Real-time refrigerant optimization supports grid stability programs.
- Manufacturers:OEM qualification requirements drive multi-source procurement strategies.
- Retailers:Distributed refrigeration asset operators prioritize fleet standardization.
Contractors generate the highest transaction frequency; Utilities show the steepest expansion trajectory.
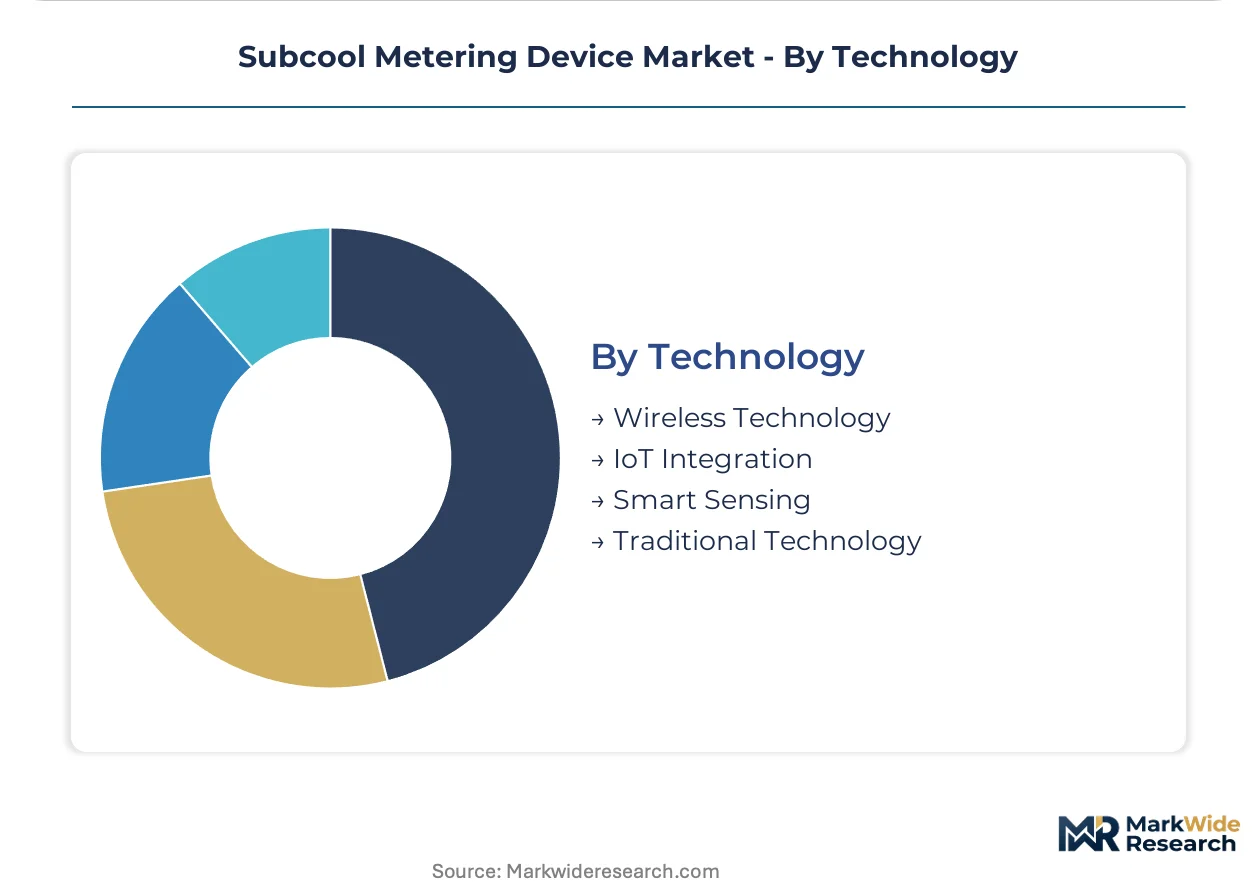
Technology:
Maturity curves separate established sensing architectures from emerging connectivity platforms. Edge intelligence and wireless protocols reshape field deployment economics.
- IoT Integration:Cloud-connected diagnostics with predictive maintenance algorithms displace manual gauge sets. Large facility operators with multi-site portfolios enable condition-based service scheduling.
- Smart Sensing:On-device inference capabilities combined with LoRaWAN or NB-IoT connectivity permit autonomous fault detection without cloud dependency for remote facilities.
- Wireless Technology:Eliminates wired sensor installation costs in retrofit applications.
- Traditional Technology:Hardwired thermocouple and transducer configurations persist in legacy infrastructure.
Traditional Technology retains volume dominance; IoT Integration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty sensor supply concentrates in German and Japanese component corridors, shaping regional deployment economics for subcool metering instrumentation across major refrigeration service markets.
United States
EPA Section 608 compliance protocols mandate leak repair documentation and proper charging practices that elevate accuracy demands for subcool measurement. Commercial HVAC contractors face compressed tolerance windows, forcing capital redeployment toward calibrated digital instrumentation with embedded diagnostic logging. Fleet standardization concentrates among multi-site operators in Texas and California utility territories.
China
Domestic cold chain infrastructure scaling drives precision refrigeration monitoring across warehouse and transport refrigeration units. MEE dual carbon goals impose equipment efficiency standards that shape product design requirements. Logistics operators in Yangtze River Delta and Pearl River Delta clusters deploy calibrated instrumentation at scale for perishable cargo compliance.
Germany
Industrial refrigeration clusters demand redundant sensor arrays for continuous process applications. EU F-Gas Regulation phase-down schedules accelerate refrigerant transition timelines that reshape sensor compatibility requirements. OEMs in Bavaria and Baden-Württemberg respond with modular sensor platforms permitting field-upgradable refrigerant profiles.
India
Cold chain infrastructure gaps in perishable logistics create whitespace for subcool monitoring deployment. BIS efficiency standards tighten on commercial refrigeration equipment, elevating specification requirements. Logistics operators in Maharashtra and Gujarat cold storage corridors represent early adoption pockets for precision charging instrumentation.
Subcool Metering Device Market Competitive Landscape
Global majors compete with regional champions across distribution channel depth and calibration service infrastructure. The vendor base stratifies between integrated HVAC controls portfolios and standalone instrumentation specialists. Three archetypes dominate: compressor technology heritage players bundling diagnostics with system automation, precision sensor specialists with utility-grade certification capabilities, and field-service-oriented brands with contractor-direct distribution. Competitive moves concentrate on multi-year meter-as-a-service subscription models and modular refrigerant-agnostic sensor platforms.
Within the integrated controls tier, Danfoss Group and Emerson Electric Co. anchor premium positioning through compressor technology heritage and HVAC automation bundling respectively. Fieldpiece Instruments Inc. and Mastercool Inc. exemplify the contractor-facing instrumentation specialist archetype with field-service-optimized distribution. These named entities represent the competitive spectrum from system-level integration to standalone precision measurement.
| Leading Market Players |
|---|
| Fieldpiece Instruments Inc. |
| Mastercool Inc. |
| Ritchie Engineering Company Inc. |
| Kane USA Inc. |
| OURAN TECHNOLOGIES |
| Mitchell Instrument |
| CEM Instruments India |
| Danfoss Group |
| Emerson Electric Co. |
| Others |
Value Network & Pricing Analysis
Multi-site commercial HVAC operators in Texas and California utility territories concentrate procurement volume, anchoring meter-as-a-service subscription models that bundle firmware updates and calibration services into multi-year agreements rather than transactional equipment purchases.
Pricing Analysis
Warranty and calibration service bundling separates premium digital meter tiers from unbundled economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and IoT connectivity depth. Cost compression in the economy tier intensifies because analog gauge sets face displacement by connected diagnostics. Independent contractors show highest price sensitivity; utilities and industrial OEMs absorb premium pricing for utility-grade certification and predictive maintenance integration.
Supply Chain Analysis
MEMS pressure transducer and precision thermocouple supply rests on German and Japanese specialty sensor manufacturers. Component sourcing draws from Bavarian semiconductor foundries and Nagoya-based precision electronics corridors. Single-source vulnerability concentrates in reference-grade temperature sensor supply. Distribution runs through HVAC wholesaler networks and direct contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
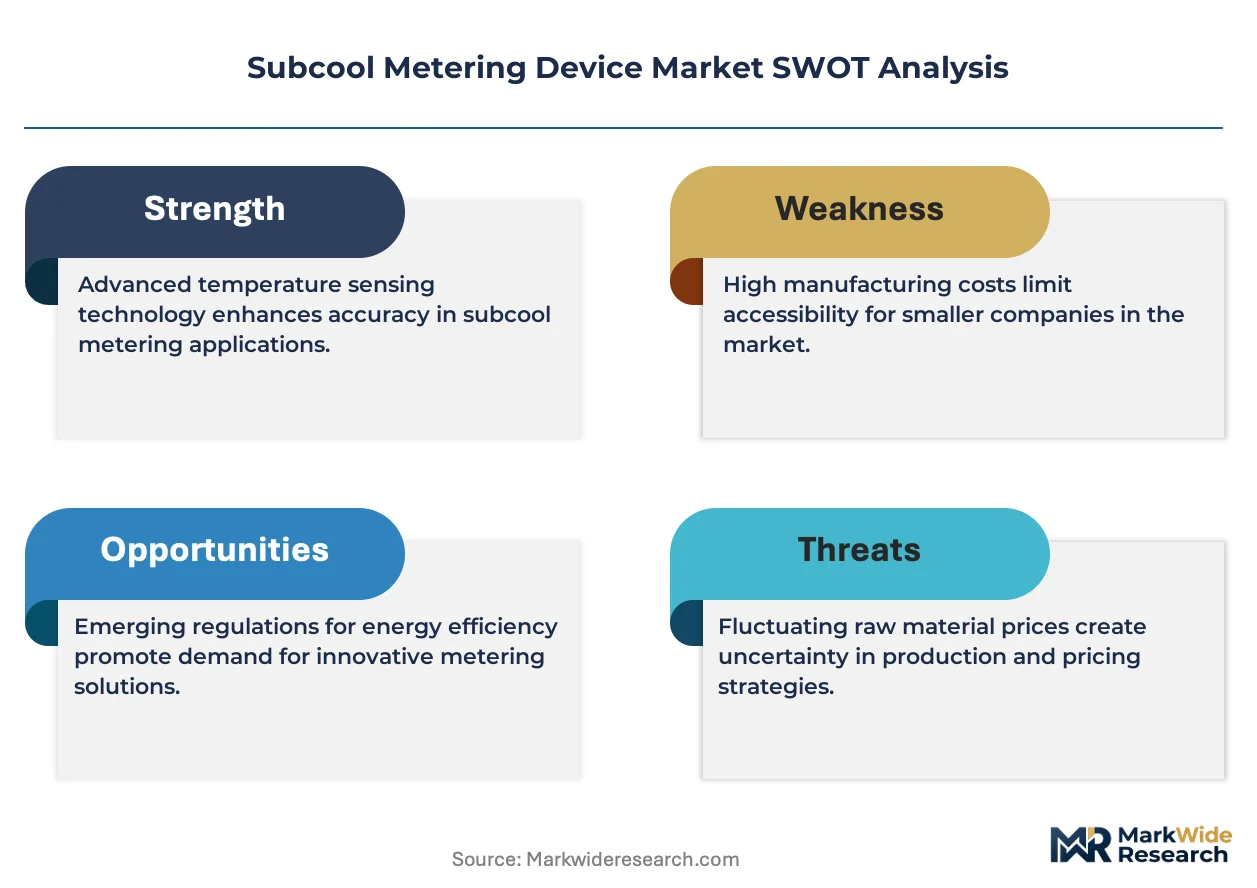
Vertical integration into captive sensor manufacturing and calibration service infrastructure is accelerating as players seek margin defense against specialty component price volatility and certification backlog risks.
For Market Incumbents: Anchor premium positioning through backward integration into MEMS transducer production and captive calibration laboratory networks. Compress contractor procurement concentration by acquiring regional instrumentation distributors. Defend against modular refrigerant-agnostic sensor platforms from German OEMs by locking exclusive sensor supply agreements with Japanese component houses. For New Entrants and Emerging Players: Enter via India's underpenetrated cold storage corridor where BIS efficiency standard enforcement creates first-mover specification advantages. Target Maharashtra and Gujarat logistics operators with localized calibration partnerships. Pursue white-label manufacturing relationships with established HVAC controls portfolios seeking subcool diagnostic line extensions. For Investors and Strategic Acquirers: The window for entry favors precision sensor specialists with utility-grade certification capabilities and established contractor-direct distribution. Long-term viability hinges on refrigerant transition readiness across A2L compatibility portfolios. Watch EPA Section 608 enforcement intensity as inflection indicator for US service contractor equipment refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Sensor Platform Development | Field-upgradable refrigerant profiles accelerate EU F-Gas compliance timelines for German OEMs. |
| Meter-as-a-Service Subscription Launch | Recurring revenue capture shifts US contractor procurement from transactional to multi-year agreements. |
| Calibration Infrastructure Expansion | Regional laboratory networks reduce turnaround dependency on German and Japanese component suppliers. |
| Edge AI Diagnostic Integration | On-device inference enables autonomous fault detection for remote Chinese cold chain facilities. |
| Refrigerant-Agnostic Certification Investment | A2L validation protocols open utility energy management program participation in California and Texas. |
Research Methodology
Independent corroboration across HVAC service contractor interviews, OEM product manager discussions, and regulatory affairs director consultations underwrites the qualitative findings. Secondary validation draws from EPA Section 608 enforcement databases, EU F-Gas Regulation implementation reports, and Chinese MEE equipment efficiency filings. Bottom-up equipment shipment tracking triangulates against top-down cold chain infrastructure investment assessments.
Comparable historical period analysis anchored the projection framework to post-refrigerant-transition equipment replacement cycles. Segmentation modeling spans product connectivity tier, application environment, end-user procurement modality, and regional regulatory cluster. CAGRs derive from equipment deployment run rates correlated with utility program participation and compliance audit intensity. Forecast inputs incorporate contractor workforce training pipeline data and refrigerant transition timeline acceleration scenarios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA enforcement escalation or A2L sensor material science breakthrough delays. Assumptions reflect documented refrigerant transition schedules and cold chain infrastructure buildout commitments. Refrigerant compatibility certification backlog duration and specialty sensor supply disruption represent primary revision triggers. A small set of regulatory enforcement intensity indicators warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
China Pressure Sensors Market
Sensors and Controls
Sensor Patch Market
Sensors and Controls
Asia-Pacific Current Transducer Market
Sensors and Controls
Global Intelligent Flow Meter Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
Global Pyrometer Market
Sensors and Controls
Chemical Sensors Market
Sensors and Controls
Exhaust Sensors for Automotive Market
Sensors and Controls
Torque Transducer Market
Sensors and Controls
Global Acceleration and Yaw Rate Sensors Market
Sensors and Controls
Tunnel Sensor Market
Sensors and Controls
US Wireless Sensors Market
Sensors and Controls
Smart Temporal Thermometer Market
Sensors and Controls
Nano Radiation Sensors Market