
 Analytical X-Ray Instrumentation Market | 2026-2036
Analytical X-Ray Instrumentation Market Size, Share, and Industry Trends Forecast 2026-2036
Analytical X-Ray Instrumentation Market Analysis
Contract research organizations are collapsing as the dominant procurement channel for X-ray instrumentation as semiconductor foundries build in-house metrology labs. Bruker Corporation leverages its dual-source technology portfolio to anchor European material science demand. Thermo Fisher Scientific Inc. sustains pharmaceutical compliance workflows through integrated software-validation packages. Shimadzu Corporation dominates Asian environmental testing channels with localized service infrastructure.
Analytical X-ray instrumentation encompasses systems that generate, direct, and detect X-ray radiation to determine elemental composition, crystallographic structure, or internal features of samples, typically operating at tube voltages from 20 kV to 300 kV with detection limits reaching parts-per-billion in fluorescence configurations. These systems serve quality assurance in manufacturing, regulatory compliance in drug development, and failure analysis in electronics. X-ray diffractometers capture the largest revenue pool due to entrenched demand from cement and mining laboratories, while X-ray fluorescence analyzers lead growth trajectories driven by RoHS and REACH restricted-substance enforcement. Semiconductor end users command premium pricing for high-resolution systems with sub-50 nm spot sizes, whereas environmental testing operates on tighter capital budgets favoring mobile technology configurations.
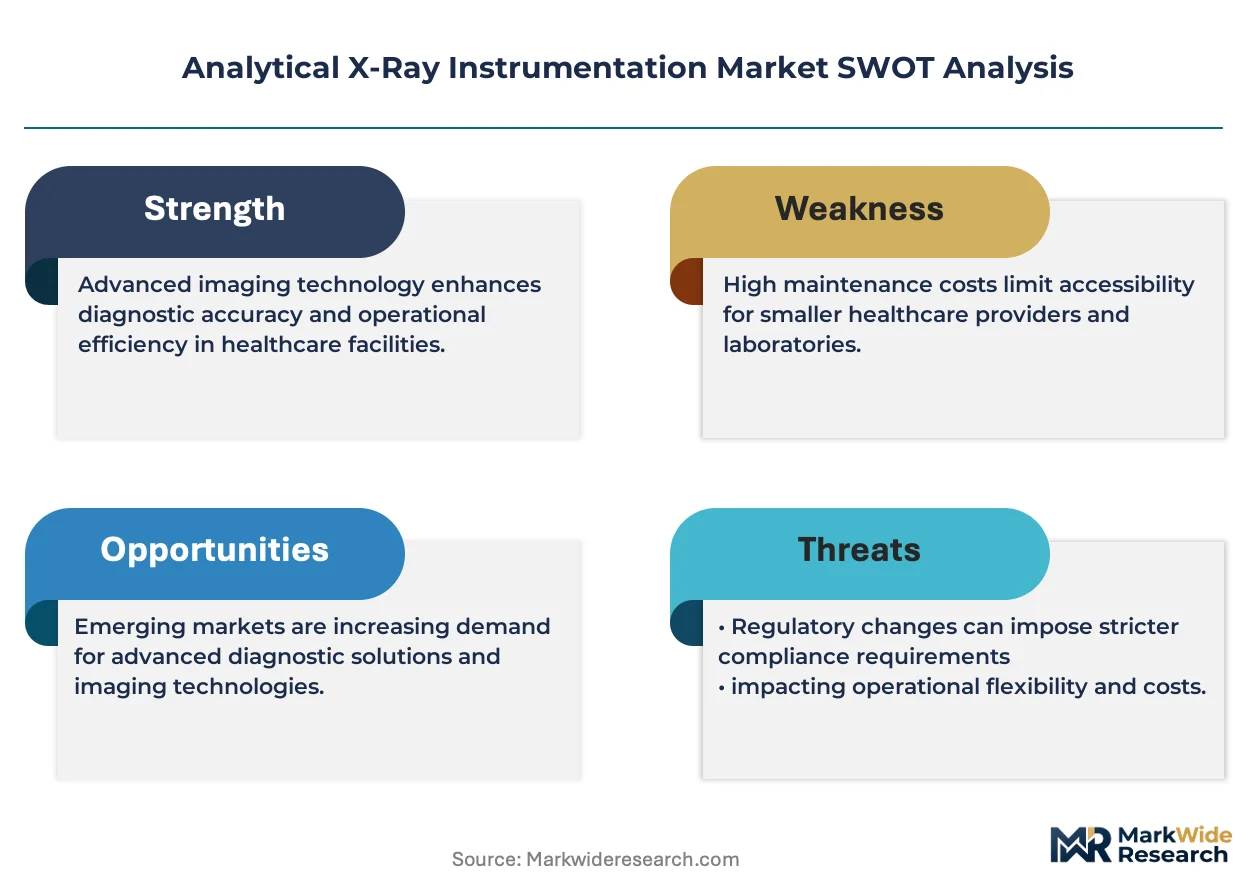
FDA 21 CFR Part 11, EU MDR, and ISO 17025 accreditation requirements shape instrument validation protocols, software audit trails, and calibration documentation that vendors must embed to maintain market access. EPA Method 6200 and REACH Annex XVII testing mandates direct environmental and industrial buyers toward specific fluorescence and diffraction capabilities. Stakeholders must monitor evolving semiconductor node transitions and corresponding metrology precision thresholds to align R&D roadmaps with buyer readiness windows.
Market Dynamics
Semiconductor foundries in Taiwan and South Korea are internalizing metrology capabilities, collapsing the traditional procurement channel dominance of contract research organizations and forcing vendors to restructure sales engagement models around direct technical validation partnerships.
Growth Catalysts
- EU MDR compliance deadlines:Pharmaceutical manufacturers must validate analytical platforms for drug characterization, creating replacement demand for legacy systems lacking 21 CFR Part 11 software audit trails.
- Sub-50 nm spot resolution requirements:Advanced packaging and compound semiconductor production in East Asian manufacturing clusters require high-resolution X-ray inspection for sub-micron defect detection.
- RoHS and REACH enforcement:Electronics manufacturers face restricted-substance testing mandates that drive fluorescence analyzer deployment across supply chain verification points.
Market Restraints
- Helium supply volatility:Cryogenic cooling systems for high-brightness X-ray sources depend on concentrated helium extraction, with price shocks rippling through detector maintenance contracts.
- Tube voltage standardization gaps:Incompatible power specifications between Japanese JIS and European EN standards force redundant engineering for multi-region deployments.
- Electron microscopy substitution:Scanning electron microscopes with elemental mapping capabilities capture budget allocation from mid-range X-ray fluorescence installations in materials science laboratories.
Strategic Opportunities
- India environmental monitoring expansion:Central Pollution Control Board mandates for industrial emissions testing create demand for portable X-ray fluorescence units in cement and mining corridors.
- AI-integrated defect classification:Machine learning algorithms trained on X-ray diffraction patterns enable real-time crystallographic analysis without specialist interpretation, opening pharmaceutical quality control workflows.
- Service unbundling models:Subscription-based calibration and validation packages replace capital-intensive ownership structures for environmental testing laboratories with cyclical project volumes.
Industry Challenges
- Crystallography expertise scarcity:Universities produce insufficient PhD-level diffraction specialists to support instrument utilization rates in industrial R&D facilities, constraining customer success metrics.
- Legacy LIMS integration friction:Pharmaceutical buyers require six-to-twelve-month validation timelines to connect new X-ray platforms with existing laboratory information management systems, elongating sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Analytical X-Ray Instrumentation Market |
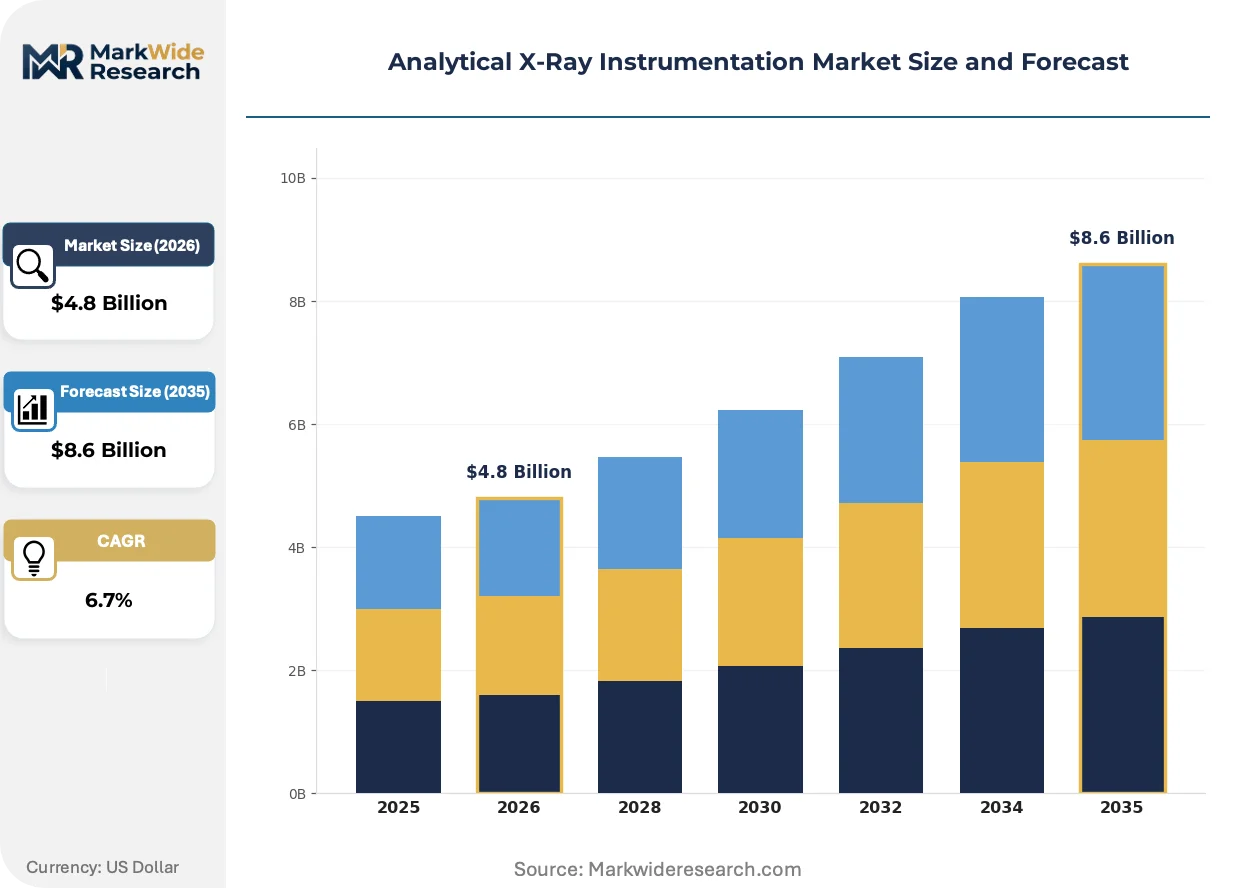
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Diffractometers, X-Ray Fluorescence Analyzers, X-Ray Spectrometers, X-Ray Microscopes Technology: Microfocus, High-Resolution, Dual-Source, Mobile End User: Pharmaceuticals, Environmental Testing, Material Science, Semiconductors Application: Quality Control, Research & Development, Forensic Analysis, Process Monitoring |
| Companies Covered | GE Healthcare, Thermo Fisher Scientific Inc., Fujifilm Medical Systems, Teledyne DALSA Inc., PerkinElmer Inc., Bruker Corporation, Rigaku Corporation, Shimadzu Corporation, Varex Imaging Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analytical X-Ray Instrumentation Market Emerging Trajectories
Polycapillary X-ray optics and direct-detection sensor arrays are compressing the performance gap between laboratory-grade and portable systems, redistributing competitive advantage toward software-integrated workflow vendors.
Polycapillary lens technology concentrates X-ray beams into sub-10 micron spots without complex focusing assemblies. Semiconductor failure analysis labs in Taiwan and South Korea are adopting these optics for 3D package inspection at throughput rates matching synchrotron beamlines. Benchtop systems with polycapillary configurations are supplanting floor-standing diffractometers in cement quality control laboratories where space constraints and operator skill limitations previously blocked adoption.
EPA Method 6200 field-portable X-ray fluorescence protocols are expanding from soil screening to construction material verification, compelling vendors to embed GPS tagging and chain-of-custody documentation in firmware. Industrial hygiene consultants in the United States now deploy these units for lead paint abatement project bidding, creating a secondary equipment market distinct from laboratory procurement channels. Environmental testing buyers prioritize EPA-compliant units over ISO-certified alternatives to eliminate regulatory interpretation risk.
Foundry customers now demand outcome-based service contracts where vendors guarantee measurement uncertainty thresholds rather than selling hardware with separate maintenance agreements. Thermo Fisher and Bruker are restructuring Asian sales organizations around application scientists embedded at customer sites, displacing distributor networks that previously handled installation and training. This model concentrates in South Korea's semiconductor cluster where in-house metrology teams lack bandwidth to validate new techniques internally.
Analytical X-Ray Instrumentation Market Segmentation
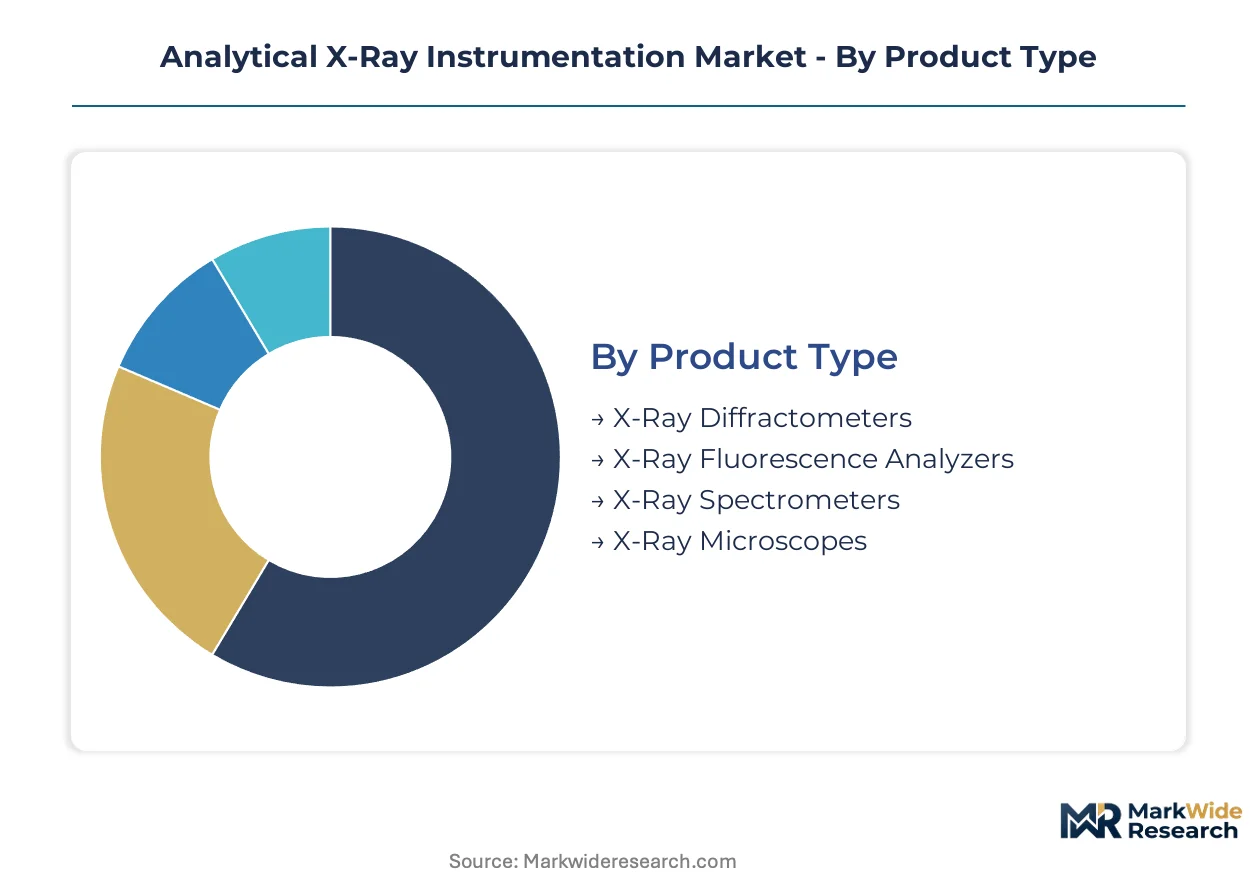
X-ray instrumentation vendors must align product architectures with distinct compliance regimes, resolution thresholds, and capital cycles across semiconductor fabs, pharmaceutical QC labs, and environmental field operations. Segmentation reveals where tube voltage specifications, software validation packages, and service bundling create pricing power versus commoditization pressure.
Product Type:
FDA 21 CFR Part 11 and EU MDR validation requirements fragment procurement specifications between pharmaceutical-grade audit trail systems and industrial configurations lacking compliance documentation.
- X-Ray Diffractometers:Systems measure crystallographic structure through Bragg diffraction patterns, employing goniometer assemblies with angular precision below 0.001 degrees. Cement and mining laboratories in India and China sustain entrenched demand for floor-standing configurations, though polycapillary optics are compressing footprint requirements for quality control deployment.
- X-Ray Fluorescence Analyzers:Non-destructive elemental composition instruments detect parts-per-billion concentrations through characteristic secondary X-ray emission. RoHS and REACH enforcement across European electronics supply chains and EPA Method 6200 soil screening mandates in the United States drive portable unit deployment for restricted-substance verification.
- X-Ray Spectrometers:Wavelength-dispersive and energy-dispersive variants serve metallurgical assay laboratories with heavy-element detection requirements.
- X-Ray Microscopes:Sub-50 nm spot resolution systems enable 3D package inspection for advanced semiconductor packaging nodes.
X-Ray Diffractometers handle the majority of throughput; X-Ray Fluorescence Analyzers are expanding most quickly on share.
Technology:
Capital intensity and operator skill requirements stratify adoption across foundry metrology labs, environmental field crews, and academic research facilities with divergent throughput demands.
- Microfocus:Sub-10 micron beam concentration through polycapillary lens assemblies eliminates complex focusing mechanics. Taiwan and South Korea semiconductor failure analysis labs adopt these configurations for 3D package inspection at throughput rates approaching synchrotron performance.
- High-Resolution:Sub-50 nm spot size systems command premium pricing from advanced packaging and compound semiconductor manufacturers in East Asian manufacturing clusters where defect detection thresholds tighten with each node transition.
- Dual-Source:Combined X-ray diffraction and fluorescence capabilities reduce capital footprint for material science laboratories with constrained floor space.
- Mobile:Battery-operated units with embedded GPS and chain-of-custody documentation serve EPA Method 6200 field protocols and industrial hygiene lead paint abatement workflows.
High-Resolution captures the steepest expansion trajectory; Mobile units face pricing compression from standardized field-portable specifications.
End User:
Procurement authority is concentrating in in-house metrology teams as semiconductor foundries internalize capabilities previously outsourced to contract research organizations.
- Semiconductors:Taiwan Semiconductor Manufacturing Company and Samsung Foundry operations command premium pricing for sub-50 nm resolution systems with guaranteed measurement uncertainty thresholds. Outcome-based service contracts replace traditional hardware-plus-maintenance sales structures.
- Pharmaceuticals:EU MDR compliance deadlines and FDA 21 CFR Part 11 requirements force replacement of legacy systems lacking software audit trails and calibration documentation. Validation timelines stretch six to twelve months for LIMS integration.
- Environmental Testing:Cyclical project volumes favor service unbundling models with subscription-based calibration packages over capital-intensive ownership.
- Material Science:University and industrial R&D facilities face crystallography expertise scarcity constraining instrument utilization rates.
Semiconductors dominate revenue concentration; Pharmaceuticals show the strongest replacement cycle momentum.
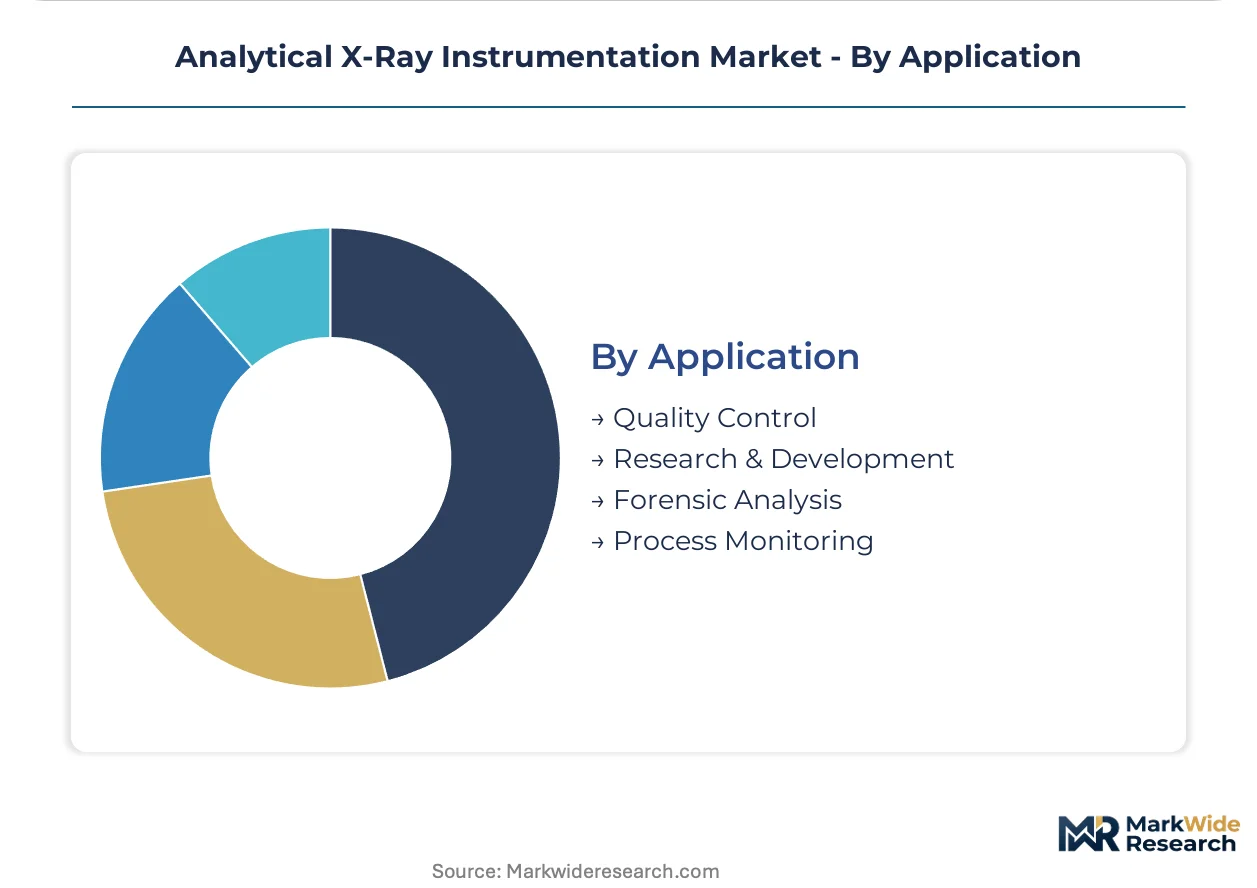
Application:
Workflow integration requirements separate validated production environments from exploratory research settings with tolerable downtime and recalibration frequency.
- Quality Control:Continuous production line integration demands 99.5% uptime guarantees and automated pass-fail classification with electronic signature capture for regulatory submission.
- Research & Development:Flexible configuration requirements accommodate method development and non-standard sample geometries with specialist interpretation.
- Forensic Analysis:Chain-of-custody documentation and court-admissible calibration records drive procurement toward vendor-validated systems.
- Process Monitoring:Real-time crystallographic feedback loops enable adaptive manufacturing parameter adjustment in pharmaceutical crystallization and metal alloy production.
Quality Control absorbs the largest installed base; Process Monitoring is climbing the fastest as AI-integrated defect classification matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese manufacturers export high-resolution X-ray systems to semiconductor foundries in Taiwan and South Korea, while US vendors supply EPA-compliant portable units to environmental testing contractors across North America and emerging Asian markets.
United States
Pharmaceutical manufacturers in Massachusetts and New Jersey drive demand for FDA 21 CFR Part 11 validated systems. EPA Method 6200 mandates for soil screening and lead paint abatement expand the installed base of portable fluorescence analyzers. Industrial hygiene consultants in Chicago and Houston deploy field-portable units for construction material verification.
Germany
REACH Annex XVII enforcement across European electronics supply chains sustains demand for restricted-substance testing capabilities. The EU MDR compliance deadline forces replacement of legacy pharmaceutical quality control systems lacking audit trail documentation. Material science laboratories in Bavaria and North Rhine-Westphalia anchor demand for dual-source diffraction-fluorescence configurations.
China
Cement quality control laboratories in the Yangtze River Delta and Pearl River Delta sustain entrenched demand for floor-standing diffractometers. The country's national environmental regulator mandates industrial emissions testing, creating procurement channels for portable X-ray fluorescence units. Mining corridors in Inner Mongolia and Shanxi Province deploy elemental analyzers for ore grade verification.
Japan
Semiconductor materials suppliers in the Kansai region require sub-50 nm resolution systems for advanced packaging inspection. JIS standards for tube voltage specifications shape domestic procurement requirements. Osaka-based industrial laboratories drive adoption of polycapillary optics for failure analysis workflows.
South Korea
Samsung Foundry and SK Hynix operations command premium pricing for high-resolution inspection systems with guaranteed measurement uncertainty thresholds. Outcome-based service contracts replace traditional hardware sales structures. The Seoul Capital Area semiconductor cluster internalizes metrology capabilities previously outsourced to contract research organizations.
Analytical X-Ray Instrumentation Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and compliance documentation capabilities. The vendor base stratifies between diversified life science conglomerates with integrated software-validation packages and focused analytical instrumentation specialists with localized service infrastructure. Three archetypes dominate: diversified conglomerates with cross-platform compliance workflows, precision optics specialists with polycapillary lens portfolios, and regional service-anchored providers with environmental testing channel dominance. Competitive moves concentrate on direct technical validation partnerships displacing distributor networks, and subscription-based calibration packages replacing capital-intensive ownership structures.
Among diversified analytical instrumentation conglomerates, Thermo Fisher Scientific Inc. and PerkinElmer Inc. represent the compliance-integrated archetype with pharmaceutical workflow embedding. Bruker Corporation anchors the precision optics specialist tier with European material science channel concentration. Shimadzu Corporation exemplifies the service-anchored regional model with Asian environmental testing infrastructure.
| Leading Market Players |
|---|
| GE Healthcare |
| Thermo Fisher Scientific Inc. |
| Fujifilm Medical Systems |
| Teledyne DALSA Inc. |
| PerkinElmer Inc. |
| Bruker Corporation |
| Rigaku Corporation |
| Shimadzu Corporation |
| Varex Imaging Corporation |
| Others |
Supply Flow & Price Mechanics
Fixed-cost absorption at high-brightness X-ray source foundries in Germany and Japan creates asymmetric pricing power, compressing margins for portable system assemblers while sustaining premium thresholds for sub-50 nm resolution platforms bound for Taiwan and South Korea semiconductor labs.
Pricing Analysis
Current-generation polycapillary optics systems command three-to-five-fold premiums over prior-generation goniometer-based diffractometers, while next-generation AI-integrated defect classification platforms are pre-quoting at value-based subscription tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from industrial configurations and mobile environmental units. Cost compression in the economy tier is intensifying because Chinese cement quality control labs are consolidating procurement around standardized floor-standing units. Environmental testing laboratories exhibit highest price sensitivity due to cyclical project volumes, whereas semiconductor foundries show lowest sensitivity given guaranteed measurement uncertainty requirements.
Supply Chain Analysis
Strategic stockpiling of helium-3 for cryogenic cooling systems dominates inventory strategy among high-resolution system manufacturers, contrasting with just-in-time component flows for portable fluorescence assemblers. German and Japanese precision optics workshops anchor supply for polycapillary lens assemblies, while Chinese machine shops feed metal fabrication for floor-standing diffractometer frames. Raw material dependencies center on high-purity germanium for detector crystals, specialized glass for X-ray tubes, and rare-earth phosphors for scintillation screens. Single-source vulnerability concentrates in helium extraction from Qatar and the United States. Distribution runs through direct technical validation partnerships displacing distributor networks in South Korea and Taiwan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The analytical X-ray instrumentation market is cycling through a semiconductor capital equipment upswing, with foundry metrology budget expansion in East Asia driving replacement demand that will persist through the current node transition wave.
For Market Incumbents: Shield service revenue streams by embedding application scientists at Samsung Foundry and TSMC sites, displacing distributor training dependencies. Consolidate polycapillary lens supply through backward integration into German precision optics workshops before Chinese competitors replicate beam concentration capabilities. Defend against electron microscopy substitution by guaranteeing measurement uncertainty thresholds that scanning electron microscopes cannot match for non-destructive packaging inspection. For New Entrants and Emerging Players: Anchor in India's Central Pollution Control Board emissions monitoring mandates, where portable X-ray fluorescence unit penetration remains below comparable Chinese environmental enforcement levels. Target cement quality control laboratories in the Yangtze River Delta with compact polycapillary diffractometers that compress footprint requirements. Pursue subscription-based calibration packages for environmental testing laboratories with cyclical project volumes, converting capital expenditure barriers into recurring revenue relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-anchored regional providers with localized environmental testing infrastructure. Long-term viability over the next decade hinges on software-integrated workflow capabilities that reduce specialist interpretation dependencies. Acquisition target archetype: precision optics specialists with polycapillary lens portfolios and established semiconductor failure analysis channel relationships. Watch for inflection when AI-integrated defect classification achieves regulatory acceptance for pharmaceutical quality control submissions without specialist sign-off.| Strategic Initiative | Industry Significance |
|---|---|
| Application Scientist Embedding | Thermo Fisher and Bruker restructuring displaces distributor networks in Seoul Capital Area semiconductor clusters. |
| Polycapillary Optics Integration | Benchtop systems supplant floor-standing diffractometers in cement quality control laboratories with space constraints. |
| Subscription Calibration Unbundling | Environmental testing laboratories with cyclical project volumes convert from capital ownership to service relationships. |
| AI Defect Classification Development | Machine learning algorithms enable real-time crystallographic analysis without PhD-level diffraction specialist interpretation. |
| Helium Supply Diversification | Cryogenic cooling system manufacturers reduce Qatar and United States single-source vulnerability through strategic stockpiling. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across semiconductor foundry metrology teams, pharmaceutical quality control managers, environmental testing laboratory directors, and analytical instrumentation product managers. Primary interviews combined with secondary validation from FDA 21 CFR Part 11 guidance documents, EPA Method 6200 field protocols, EU MDR compliance frameworks, and semiconductor industry capital expenditure disclosures. Bottom-up installed base modeling and top-down market sizing triangulated around tube voltage specifications, software validation package attach rates, and regional service infrastructure density.
Across the analysis window, forecasts incorporate product type segmentation by diffraction, fluorescence, spectrometer, and microscope configurations; technology tiering by resolution threshold and mobility; end-user concentration across semiconductor, pharmaceutical, environmental, and material science laboratories; and application workflow integration requirements. CAGRs derive from node transition pacing in East Asian foundries, EU MDR compliance deadline clustering, and RoHS enforcement intensity across European electronics supply chains. Industry-specific inputs include helium price shock propagation through detector maintenance contracts and polycapillary optics adoption curves in cement quality control.
Material uncertainties — semiconductor node transition delays, helium supply disruption, and crystallography expertise scarcity constraining instrument utilization — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory deadline adherence and foundry in-house metrology buildout pacing. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and EPA Method 6200 field protocol expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Surface Plasmon Resonance (SPR) System Market
Analytical Instruments
Microfluidic Devices Market
Analytical Instruments
Handheld Laser Measuring Instrument Market
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
Microfluidic Modulation Spectroscopy Market
Analytical Instruments
Laser-Based Gas Analyzers Market
Analytical Instruments
Asia-Pacific Handheld Spectrum Analyzer Market
Analytical Instruments
Headspace Gas Analyzers Market
Analytical Instruments
Logic Analyzer Market
Analytical Instruments
Surface Plasmon Resonance Instrument Market
Analytical Instruments
Elemental Analyzer Market
Analytical Instruments
Turbidimeter Market
Analytical Instruments
Electron Probe Microanalyzers (EPMA) Market
Analytical Instruments
Analytical Instrumentation for Food Applications Market
Analytical Instruments
Semiconductor X-Ray Diffractometers Market
Analytical Instruments
Analytical Instrumentation Market