
 Capacitive Touch Screen Market | 2026-2036
Capacitive Touch Screen Market Size, Share, and Industry Trends Forecast 2026-2036
Capacitive Touch Screen Market Analysis
East Asian panel makers is recalibrating capacity allocation toward automotive-grade substrates as vehicle electrification accelerates touch interface deployment. TPK Holding Co., Ltd. leverages its projected capacitive expertise to dominate industrial and medical display segments. Lens Technology Co., Ltd. anchors smartphone cover lens supply through backward integration into sapphire and ceramic processing. Shenzhen OFILM Intelligent Technology Co., Ltd. competes on optical bonding scale for tablet and laptop OEMs.
Capacitive touch screens detect finger proximity through electrostatic field distortion across indium tin oxide or metal mesh conductive layers bonded to glass or polymer substrates, enabling multi-point gesture recognition with response times below 10 milliseconds. Projected capacitive technology leads volume shipments due to its dominance in smartphones and tablets, while mutual capacitive architectures are displacing legacy alternatives in automotive center stacks where glove-touch reliability matters. Flexible form factors represent the fastest-growing segment as foldable handset designs from Korean and Chinese OEMs expand substrate bending radius requirements.
FCC electromagnetic interference standards in the United States, EU RoHS substance restrictions, and China's GB standards for electronic display safety collectively shape product certification costs and material substitution timelines. ECHA REACH compliance is forcing indium tin oxide alternatives as suppliers navigate restricted substance lists for transparent conductors. Stakeholders must monitor how automotive functional safety standards evolve to determine whether touch module suppliers require ISO 26262 process certification to retain tier-one supplier status.
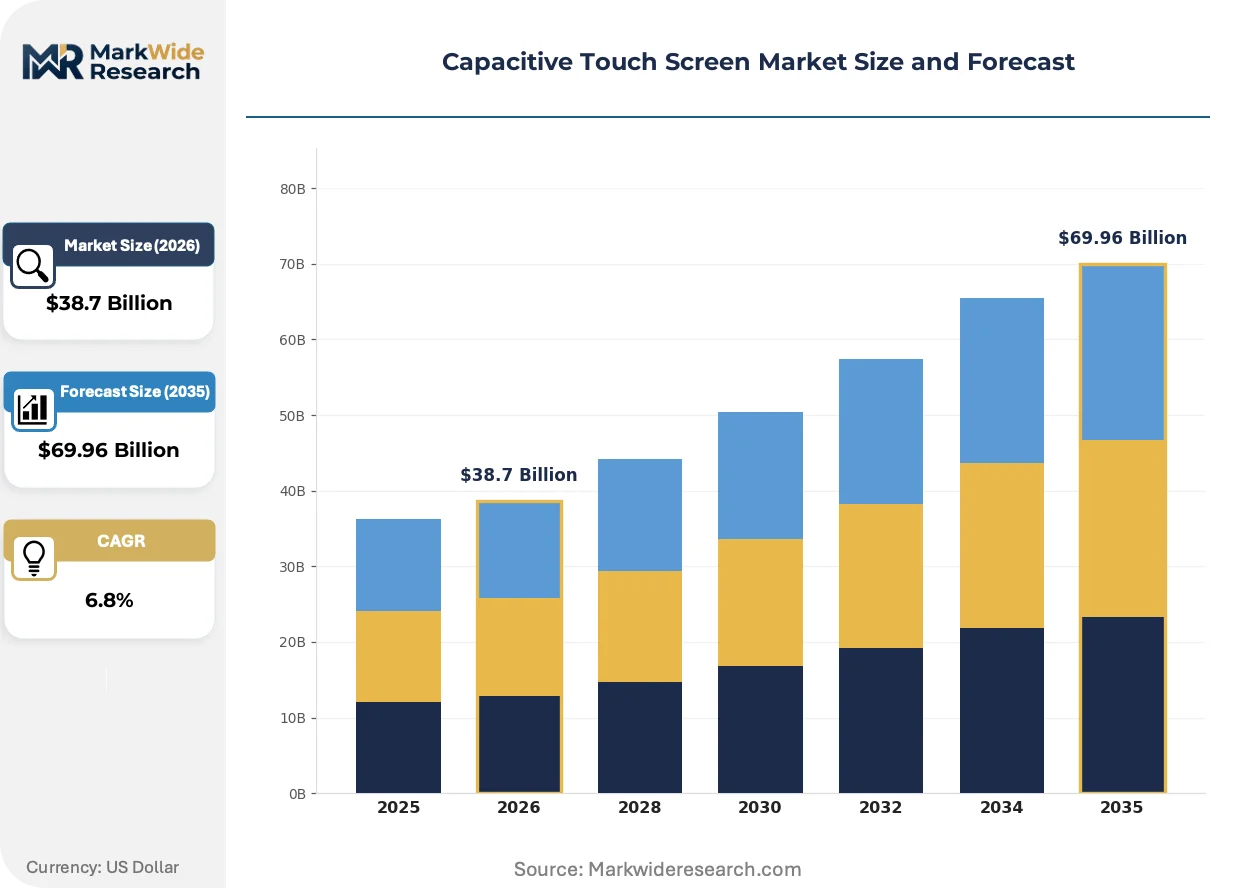
Market Dynamics
Automotive electrification is compressing touch module qualification timelines as OEMs demand glove-compatible interfaces for center-stack displays, forcing substrate suppliers to recalibrate yield rates for curved glass and polymer alternatives.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based etching gases is accelerating dry-process metal mesh adoption for transparent conductive layers in German and French automotive supply chains.
- Foldable handset industrialization:Korean and Chinese OEMs are expanding ultra-thin glass bending radius specifications, pulling flexible polymer substrate capacity from display module clusters in Shenzhen and Dongguan.
- Medical device digitization:Surgical navigation systems and patient monitoring interfaces are procuring antimicrobial-coated projected capacitive panels under FDA 510(k) clearance pathways.
Market Restraints
- Indium supply concentration:Over 80 percent of refined indium originates from Chinese zinc smelter byproduct recovery, creating price volatility for indium tin oxide sputtering targets.
- ECHA REACH substance restrictions:Candidate list expansion for nickel compounds is forcing reformulation of edge electrode plating chemistries, extending material qualification cycles by 8-14 months.
- Optical bonding yield limits:Vacuum lamination of polarizer-to-sensor stacks remains capped at 92-94 percent first-pass yield for automotive-grade specifications, constraining margin expansion.
Strategic Opportunities
- India PLI scheme for electronics:Component-level incentives for display module assembly are attracting touch sensor lamination investments in Uttar Pradesh and Tamil Nadu manufacturing corridors.
- Haptic feedback convergence:Integration of piezoelectric actuators with capacitive sensing layers is creating differentiated automotive interfaces for premium vehicle segments.
- Refurbishment channel emergence:Independent repair networks in Brazil and Mexico are sourcing aftermarket digitizer assemblies, bypassing OEM captive supply arrangements.
Industry Challenges
- ISO 26262 functional safety certification:Automotive tier-one suppliers must implement ASIL-B rated touch controller firmware development processes, requiring 18-24 month qualification investments.
- Legacy resistive touch retrofit complexity:Industrial equipment OEMs face controller firmware incompatibility when upgrading aging HMI platforms to multi-point capacitive architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capacitive Touch Screen Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Tablets, Laptops, Wearables Technology: Projected Capacitive, Surface Capacitive, Mutual Capacitive, Self-Capacitive End User: Consumer Electronics, Automotive, Industrial Automation, Healthcare Form Factor: Flat, Curved, Flexible, Transparent |
| Companies Covered | Shenzhen OFILM Intelligent Technology Co., Ltd., Lens Technology Co., Ltd., TPK Holding Co., Ltd., Nissha Printing, Elo Touch Solutions, LLC, General Interface Solution Holding Limited, Japan Display Inc., AU Optronics, Wintek Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capacitive Touch Screen Market Emerging Trajectories
Silver nanowire transparent conductors are disrupting established material hierarchies as sputtering equipment limitations and supply security concerns reshape conductive layer procurement strategies across display module supply chains.
Metal mesh patterning is decentralizing transparent electrode manufacturing from vacuum sputtering dominance toward roll-to-roll printing processes. Automotive display integrators in Germany and Japan are qualifying etched copper mesh alternatives for 12-inch-plus center-stack formats. This transition is compressing capital intensity requirements for mid-scale touch sensor producers.
ECHA REACH candidate list expansion is forcing systematic substitution of indium tin oxide in consumer electronics applications. Korean panel makers are accelerating silver nanowire ink formulation partnerships to preempt authorization timeline risks. Medical and industrial segments retain ITO preference where optical transmission specifications exceed 90 percent.
Automotive OEMs are consolidating touch module procurement under single-source display system contracts, displacing discrete sensor supplier relationships. Tier-one integrators in Stuttgart and Toyota City are absorbing optical bonding and controller firmware development in-house. This concentration is visible most acutely in premium electric vehicle programs where HMI differentiation determines brand positioning.
Capacitive Touch Screen Market Segmentation
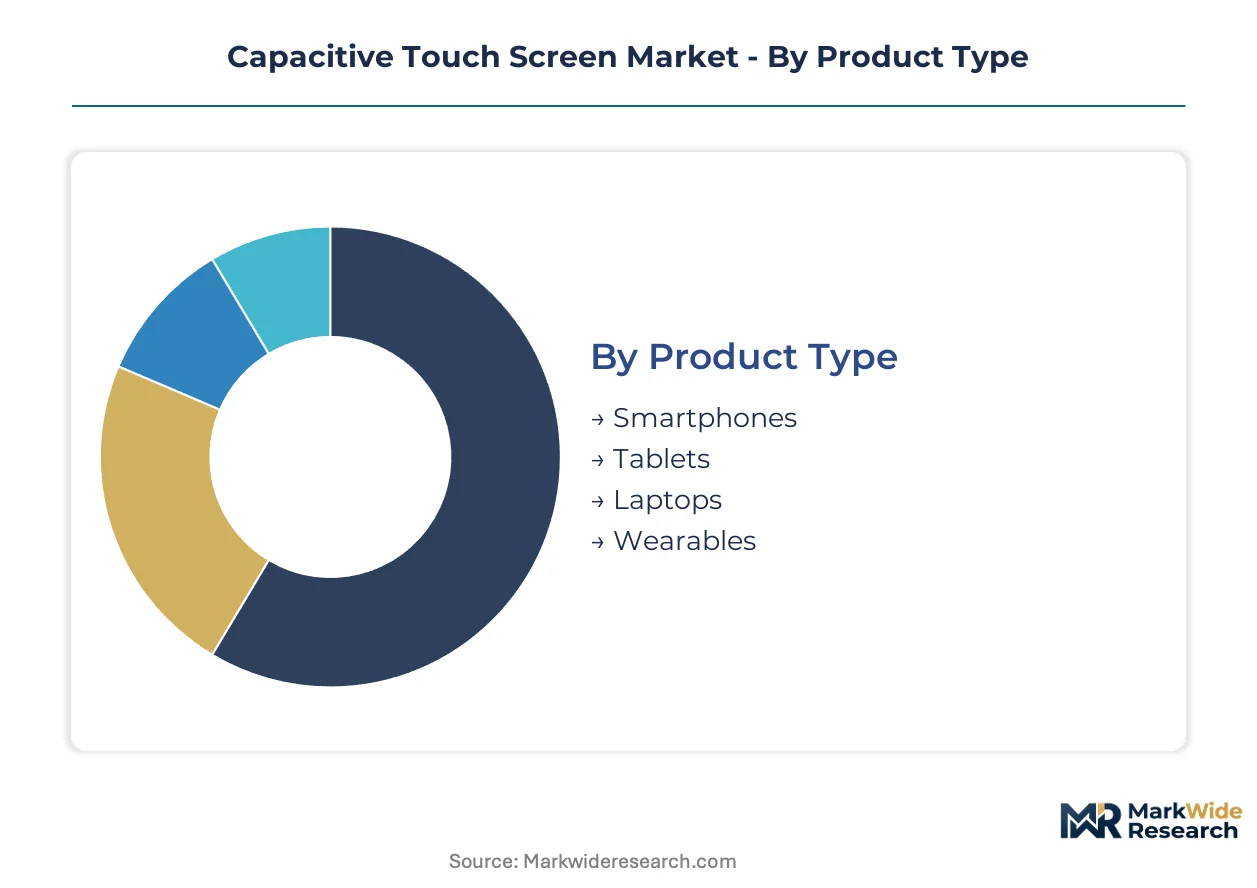
Capacitive touch screen procurement diverges sharply between high-volume consumer applications demanding sub-dollar sensor economics and specialized industrial deployments tolerating 10-20x unit premiums for glove-touch reliability and antimicrobial surface treatments. Segment boundaries are blurring as automotive OEMs consolidate display system contracts and foldable handset designs force substrate suppliers to qualify entirely new bending radius specifications.
Product Type:
Smartphones dominate unit economics through billion-scale annual procurement, while automotive and industrial applications extract premium pricing through extended qualification cycles and functional safety certification requirements.
- Smartphones:Projected capacitive sensors bonded to chemically strengthened glass substrates constitute the volume anchor for indium tin oxide sputtering target consumption and optical bonding capacity utilization. Chinese OEM procurement from Shenzhen and Dongguan module clusters compresses sensor ASPs through backward integration into cover lens processing.
- Tablets:Larger active area specifications strain metal mesh patterning yield rates while demanding enhanced palm rejection algorithms for stylus coexistence. Education sector procurement in India and Brazil sustains mid-tier demand independent of flagship handset refresh cycles.
- Laptops:In-cell touch integration within LCD module stacks is displacing discrete sensor lamination for mainstream clamshell designs, constraining standalone touch controller silicon opportunities.
- Wearables:Circular form factors and water ingress resistance specifications drive specialized one-glass solution architectures with reduced layer counts.
Today's leader: Smartphones. Tomorrow's challenger: Automotive-integrated laptops.
Technology:
Mutual capacitive architectures are displacing legacy alternatives in safety-critical applications where simultaneous multi-touch recognition and electromagnetic noise immunity determine qualification outcomes.
- Projected Capacitive:XY electrode matrix configurations etched from indium tin oxide or silver nanowire layers enable ten-point gesture recognition with sub-10 millisecond response latency. This technology commands consumer electronics volume through Korean and Chinese panel maker dominance.
- Surface Capacitive:Uniform conductive coating with voltage gradient sensing delivers superior optical clarity for industrial kiosk and casino gaming applications where durability outweighs multi-touch requirements. EMEA procurement concentrates in German automotive heritage supplier networks.
- Mutual Capacitive:Transmit-receive electrode pairing eliminates ghost touch artifacts under glove contact and moisture contamination, accelerating adoption in automotive center stacks and surgical navigation systems requiring FDA 510(k) clearance.
- Self-Capacitive:Single-electrode measurement simplifies controller architecture for cost-constrained single-touch applications in white goods and thermostat interfaces, though multi-touch expansion remains technically constrained.
Projected capacitive retains volume dominance. Mutual capacitive gains share fastest in premium automotive and medical tiers.
End User:
Automotive electrification is compressing touch module qualification timelines while forcing substrate suppliers to recalibrate yield rates for curved glass and polymer alternatives previously optimized for planar consumer electronics.
- Consumer Electronics:Handset OEM procurement cycles drive capacity allocation across Shenzhen module clusters, with foldable designs pulling flexible substrate investment from established rigid glass supply chains.
- Automotive:Center-stack display integration demands glove-compatible interfaces with ASIL-B functional safety certification, requiring 18-24 month firmware qualification investments that disqualify consumer-grade controller suppliers.
- Industrial Automation:HMI retrofit complexity from legacy resistive architectures constrains upgrade velocity, though antimicrobial coating specifications in food processing equipment are accelerating projected capacitive replacement timelines.
- Healthcare:Surgical navigation and patient monitoring interfaces procure under FDA 510(k) clearance pathways with stringent surface disinfection compatibility requirements.
Consumer electronics absorbs capacity. Automotive commands margin expansion.
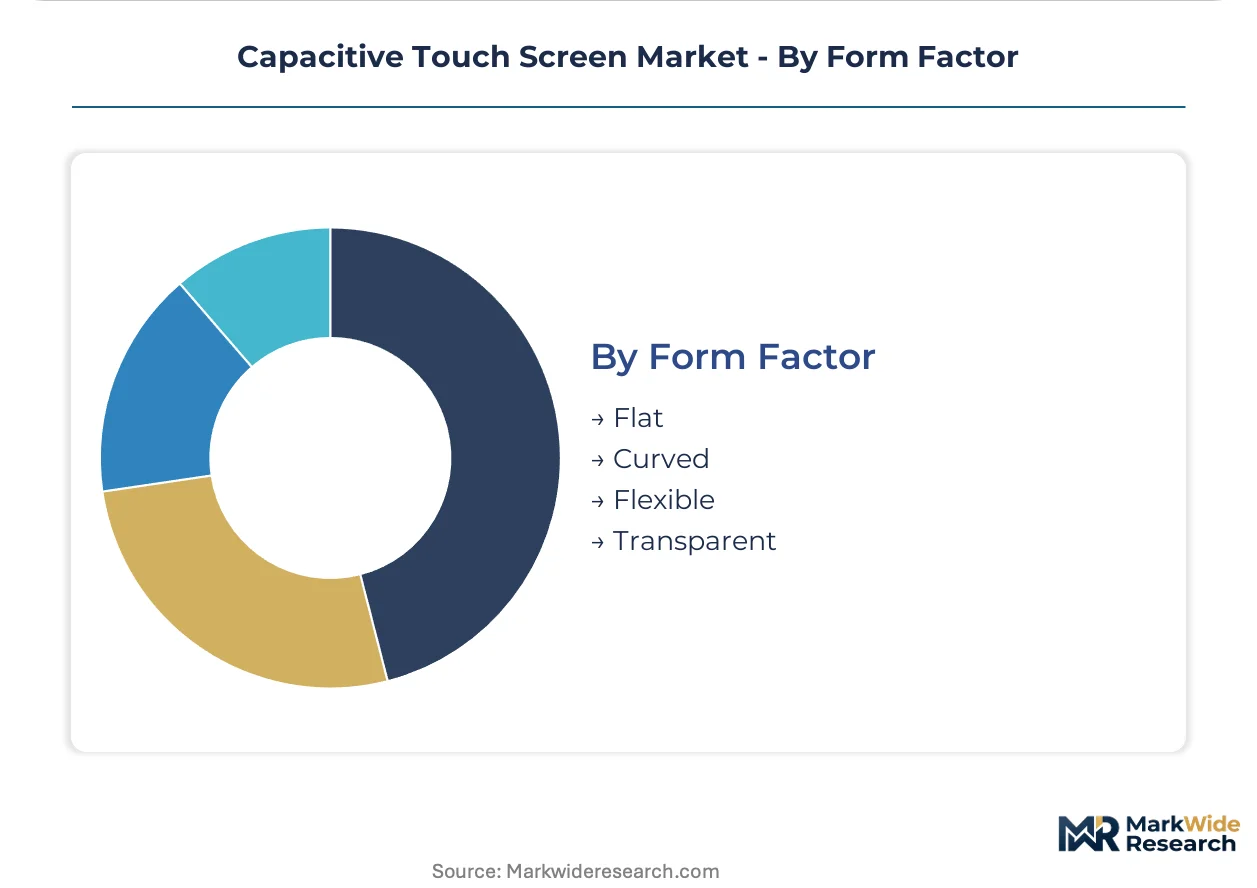
Form Factor:
Flexible substrates are climbing the fastest as Korean and Chinese OEMs industrialize foldable handset designs with ultra-thin glass bending radius specifications below 3 millimeters.
- Flat:Conventional chemically strengthened glass dominates laptop and industrial panel procurement where cost minimization outweighs differentiation requirements.
- Curved:Automotive center-stack integration demands 2.5D and 3D glass thermoforming capabilities concentrated in German and Japanese tier-one supplier networks.
- Flexible:Polyimide substrate alternatives to ultra-thin glass enable sub-3 millimeter bending radii for foldable smartphones, with silver nanowire conductors displacing brittle indium tin oxide layers under cyclic stress.
- Transparent:Head-up display integration and retail showcase applications sustain niche demand for high-transmission sensor stacks exceeding 90 percent optical clarity.
Flat form factors retain volume concentration. Flexible designs command steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting touch module assembly toward jurisdictions with streamlined chemical compliance pathways, as ECHA REACH substance restrictions and EU F-Gas phasedown protocols elevate European production costs relative to Asian manufacturing corridors.
China
Automotive electrification and foldable handset industrialization are pulling flexible substrate investment toward Shenzhen and Dongguan module clusters. MIIT GB standards for electronic display safety govern domestic certification timelines. Yangtze River Delta panel makers are recalibrating capacity allocation toward automotive-grade substrates as Korean and Chinese OEMs expand procurement.
Germany
Center-stack display integration for premium electric vehicle programs is compressing touch module qualification timelines across Stuttgart supplier networks. EU F-Gas Regulation phasedown of hydrofluorocarbon etching gases is accelerating dry-process metal mesh adoption for transparent conductive layers. Bavaria-based tier-one integrators are absorbing optical bonding and controller firmware development in-house.
United States
Medical device digitization is driving surgical navigation systems and patient monitoring interfaces toward antimicrobial-coated projected capacitive panels. FDA 510(k) clearance pathways structure procurement under electromagnetic compatibility requirements. FCC electromagnetic interference standards shape product certification costs for automotive and industrial display deployments.
Japan
Automotive display integrators in Toyota City and Nagoya corridors are qualifying etched copper mesh alternatives for 12-inch-plus center-stack formats. METI industrial policy supports roll-to-roll printing process transitions away from vacuum sputtering dominance. Kansai-based heritage suppliers retain surface capacitive expertise for industrial kiosk and casino gaming applications.
India
Component-level incentives for display module assembly under the PLI scheme are attracting touch sensor lamination investments in Uttar Pradesh and Tamil Nadu manufacturing corridors. BIS standards for electronic display safety govern domestic market entry requirements. Education sector tablet procurement sustains mid-tier demand independent of flagship handset refresh cycles.
Capacitive Touch Screen Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized automotive and medical certifications to bypass commoditized consumer electronics pricing. The vendor base stratifies across three archetypes: vertically integrated module assemblers with captive cover lens processing, independent sensor specialists focused on optical bonding scale, and diversified display panel makers absorbing touch functions into system-level contracts. Capacity expansion and strategic partnerships represent the dominant competitive moves, as tier-one automotive contracts consolidate procurement under single-source display system arrangements.
Among East Asian fabricators, TPK Holding Co., Ltd., Lens Technology Co., Ltd., and Shenzhen OFILM Intelligent Technology Co., Ltd. exemplify distinct strategic positions within the competitive structure. TPK Holding occupies a position within the projected capacitive specialist tier. Lens Technology anchors the backward-integrated cover lens segment through sapphire and ceramic processing capabilities. Shenzhen OFILM sits within the optical bonding scale tier serving tablet and laptop OEM procurement requirements.
| Leading Market Players |
|---|
| Shenzhen OFILM Intelligent Technology Co., Ltd. |
| Lens Technology Co., Ltd. |
| TPK Holding Co., Ltd. |
| Nissha Printing |
| Elo Touch Solutions, LLC |
| General Interface Solution Holding Limited |
| Japan Display Inc. |
| AU Optronics |
| Wintek Corporation |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists concentrated in China's Pearl River Delta maintain pricing discipline through captive cover lens processing and optical bonding scale, insulating margin structures from the spot-price volatility that plagues commodity sensor suppliers.
Pricing Analysis
Distributor markups compress as automotive OEMs consolidate procurement under single-source display system contracts, eliminating intermediary layers. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-B certified automotive modules from consumer-grade alternatives and aftermarket refurbishment channels. Cost compression in smartphone sensor tiers is intensifying because Chinese OEM backward integration into sapphire and ceramic processing erodes standalone supplier pricing power. Education sector tablet procurement in India and Brazil exhibits highest price sensitivity, while surgical navigation systems under FDA 510(k) pathways tolerate minimal negotiation.
Supply Chain Analysis
ISO 26262 functional safety certification gates tier-one automotive supplier status, forcing 18-24 month firmware qualification investments that disqualify consumer-grade controller vendors. Manufacturing concentrates in China, South Korea, and Japan, with Shenzhen and Dongguan module clusters feeding consumer electronics volume and Toyota City corridors serving premium automotive programs. Supply chains draw from indium tin oxide sputtering targets, silver nanowire ink formulations, and ultra-thin glass substrates. Single-source vulnerability concentrates in Chinese zinc smelter byproduct indium recovery. Distribution runs through vertically integrated module assemblers with captive cover lens processing, independent sensor specialists, and diversified display panel makers absorbing touch functions in-house.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
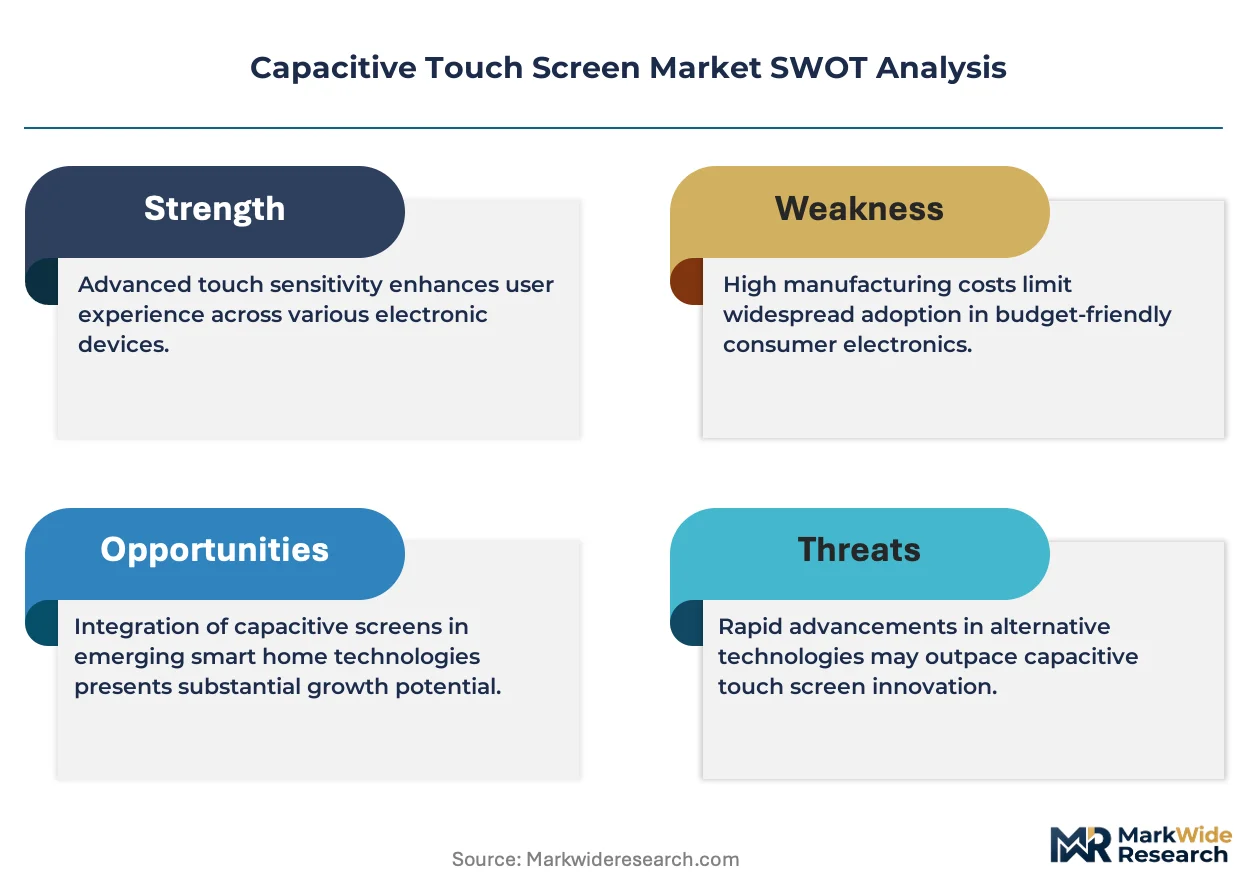
The capacitive touch screen market compounds steadily as vehicle electrification mandates glove-compatible interfaces across every OEM platform, embedding touch modules into non-discretionary automotive bill-of-materials.
For Market Incumbents: Extend certification moats by accelerating ASIL-B rated controller firmware development for automotive center-stack programs before tier-one integrators absorb optical bonding in-house. Deepen upstream control over silver nanowire ink formulation partnerships to preempt ECHA REACH authorization timeline risks for indium tin oxide substitution. Consolidate position in medical device digitization through antimicrobial coating specifications under FDA 510(k) clearance pathways.
For New Entrants and Emerging Players: Capture refurbishment channel economics in Brazil and Mexico where independent repair networks source aftermarket digitizer assemblies outside OEM captive supply arrangements. Target India's PLI scheme corridors in Uttar Pradesh and Tamil Nadu for touch sensor lamination investments before component-level incentives expire. Lead with optical bonding scale for education sector tablet procurement in price-sensitive emerging markets.
For Investors and Strategic Acquirers: Valuations sit cheapest among metal mesh patterning specialists with dry-process etching capabilities qualified for German automotive supply chains. Long-term viability hinges on differentiation from vacuum sputtering dominance through roll-to-roll printing transitions. Watch for consolidation signals when tier-one automotive contracts absorb discrete sensor suppliers under single-source display system arrangements.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-B Functional Safety Certification | Automotive tier-one supplier status requires ISO 26262 firmware development processes. |
| Silver Nanowire Ink Partnership | Korean panel makers accelerate formulation alliances to preempt ECHA REACH authorization risks. |
| India PLI Corridor Investment | Component-level incentives attract touch sensor lamination capacity to Uttar Pradesh manufacturing zones. |
| Optical Bonding Scale Expansion | Tablet and laptop OEM procurement demands vacuum lamination yield improvements above 92 percent. |
| Flexible Substrate Qualification | Foldable handset designs with sub-3 millimeter bending radii pull polyimide capacity from rigid glass supply chains. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with touch controller firmware engineers, automotive tier-one procurement directors, display module plant managers, and medical device regulatory affairs specialists with secondary validation from MIIT GB standards filings, ECHA REACH candidate list updates, FDA 510(k) clearance databases, and customs trade data for indium tin oxide sputtering target flows.
Input-output matrices map sensor unit economics across smartphone, automotive, and industrial end-uses, with segmentation dimensions spanning projected versus mutual capacitive architectures, rigid versus flexible form factors, and certification tiers from consumer-grade through ASIL-B automotive and FDA-cleared medical. CAGRs derive from elasticity-adjusted demand curves and capacity utilization trajectories across Shenzhen, Dongguan, and Yangtze River Delta manufacturing clusters throughout the forecast period.
Automotive electrification policy reversals, ECHA REACH substance list expansions, and indium supply disruptions from Chinese zinc smelter operations are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in OEM touch module procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Display Semiconductor Components Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Thin Display Technology Market
Display Technologies
Projector Screen Market
Display Technologies
DLP Projector Market
Display Technologies
Display Glass Substrate Market
Display Technologies
Large Industrial Displays Market
Display Technologies
Touch Screen Film Market
Display Technologies
Global 5K Display Resolution Market
Display Technologies
Multimedia Projectors Market
Display Technologies
Global OLED Market
Display Technologies
Middle East and Africa Industrial Display Market
Display Technologies
Advanced (3D/4D) Visualization Systems Market
Display Technologies
Microdisplay Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Interactive Display Market