
 Inertial Sensing Products Market | 2026-2036
Inertial Sensing Products Market Size, Share, and Industry Trends Forecast 2026-2036
Inertial Sensing Products Market Foresight
MEMS fabrication specialist availability is bifurcating the competitive landscape between captive foundries and fabless design houses. Honeywell International Inc. leverages decades of ring laser gyroscope heritage to dominate high-reliability aerospace contracts. Bosch Sensortec GmbH anchors the automotive and consumer tiers through wafer-scale MEMS integration at its Reutlingen facility.
Inertial sensing products encompass accelerometers, gyroscopes, inertial measurement units, and pressure sensors that detect linear acceleration, angular rate, and orientation relative to an inertial reference frame, typically fabricated via bulk or surface micromachining of silicon substrates with capacitive or piezoelectric transduction. These devices enable dead-reckoning navigation, platform stabilization, and motion control in GPS-denied environments across defense, transportation, and industrial domains. MEMS technology occupies the highest volume tier due to semiconductor cost curves, while optical gyroscopes sustain premium positioning in strategic missile and submarine applications where bias stability below 0.01 degrees per hour remains mandatory. IMU demand is accelerating fastest in autonomous robotics, where sensor fusion with lidar and vision systems requires compact, low-drift packages.
The US FAA and EU EASA impose stringent environmental qualification standards on inertial sensors for commercial aviation, while the US Department of Defense mandates ITAR controls on strategic-grade gyroscope exports. China's GB standards and NMPA medical device rules are expanding addressable demand for surgical navigation and robotic-assisted procedures. Stakeholders must monitor how export control harmonization between the US Bureau of Industry and Security and EU dual-use regulations reshapes supply chain geography for high-performance inertial components.
Market Dynamics
MEMS fabrication economics are compressing unit costs while aerospace-grade reliability requirements are simultaneously tightening, creating a bifurcation between high-volume consumer tiers and ITAR-controlled strategic-grade supply chains.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for hydrofluorocarbons are accelerating replacement cycles in industrial refrigeration systems, driving demand for precision pressure sensors and IMUs in compressor monitoring.
- Autonomous robotics OEMs:Warehouse automation and last-mile delivery platforms are absorbing compact IMUs for dead-reckoning navigation where GPS signals degrade indoors.
- Submarine navigation systems:Fiber-optic gyroscope procurement for underwater platforms sustains premium-tier demand with bias stability requirements below 0.01 degrees per hour.
Market Restraints
- Strategic-grade supply concentration:ITAR-controlled ring laser gyroscope production concentrates among a handful of US and European defense contractors, limiting procurement options for allied nations.
- Raw material volatility:High-purity silicon wafer and specialty glass substrate costs fluctuate with semiconductor cycle dynamics, squeezing margins for fabless MEMS designers.
- Optical gyroscope substitution ceiling:MEMS-based alternatives cannot yet match the bias stability of fiber-optic systems in strategic missile applications, preserving a technology moat.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing are drawing MEMS packaging and test capacity to Bangalore and Hyderabad corridors.
- Surgical navigation convergence:Sensor fusion between IMUs and optical tracking systems is opening robotic-assisted procedure platforms in spine and orthopedic applications.
- Direct-to-OEM distribution:Bypassing traditional component distributors, some MEMS suppliers are establishing technical sales offices adjacent to Stuttgart and Munich automotive clusters.
Industry Challenges
- Multi-physics simulation talent scarcity:MEMS design requires expertise spanning mechanical, electrical, and thermal domains, with limited university pipeline output.
- FAA certification timelines:Commercial aviation IMU qualification under DO-160G environmental standards extends development cycles by 18-36 months.
- Legacy platform integration:Newer MEMS IMUs must interface with existing ring laser gyroscope architectures in defense retrofit programs, comifying firmware requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inertial Sensing Products Market |
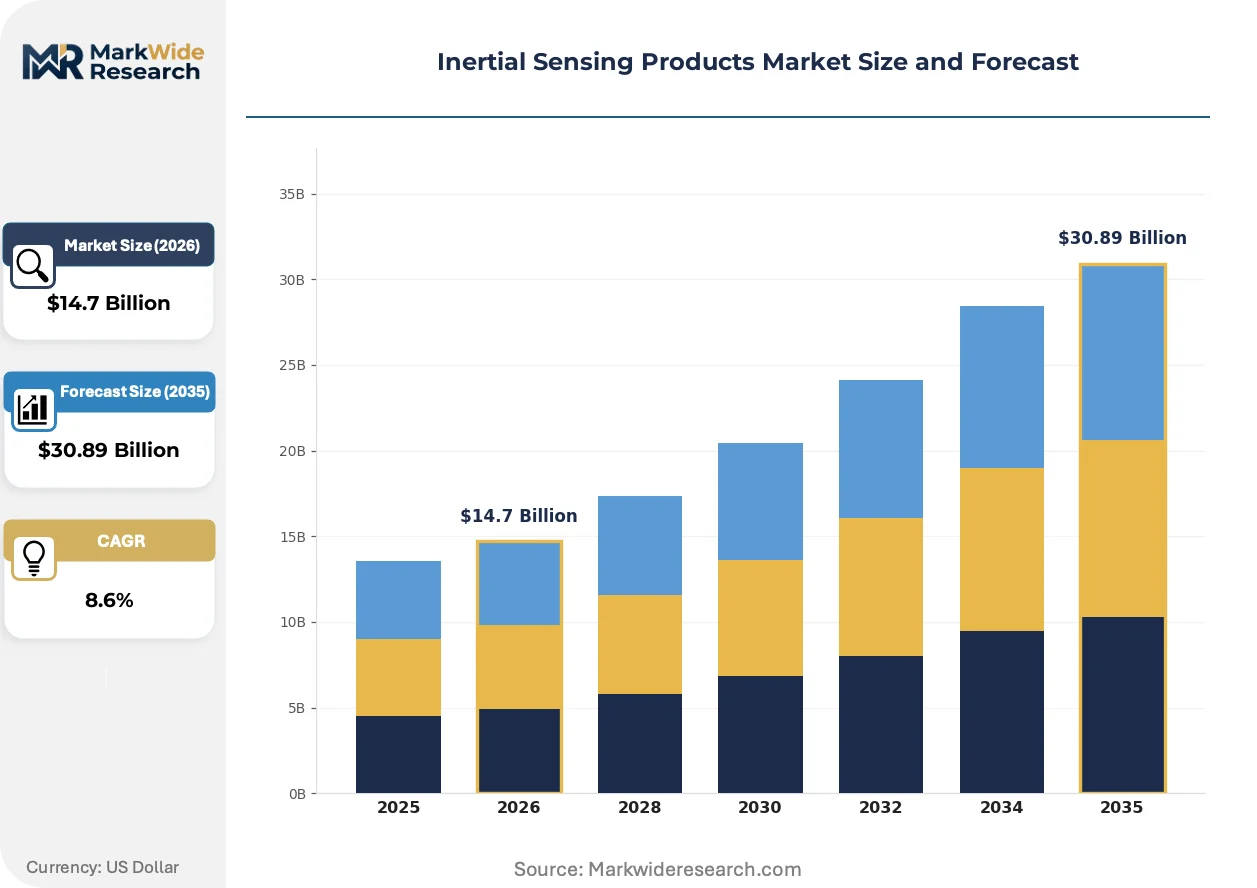
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
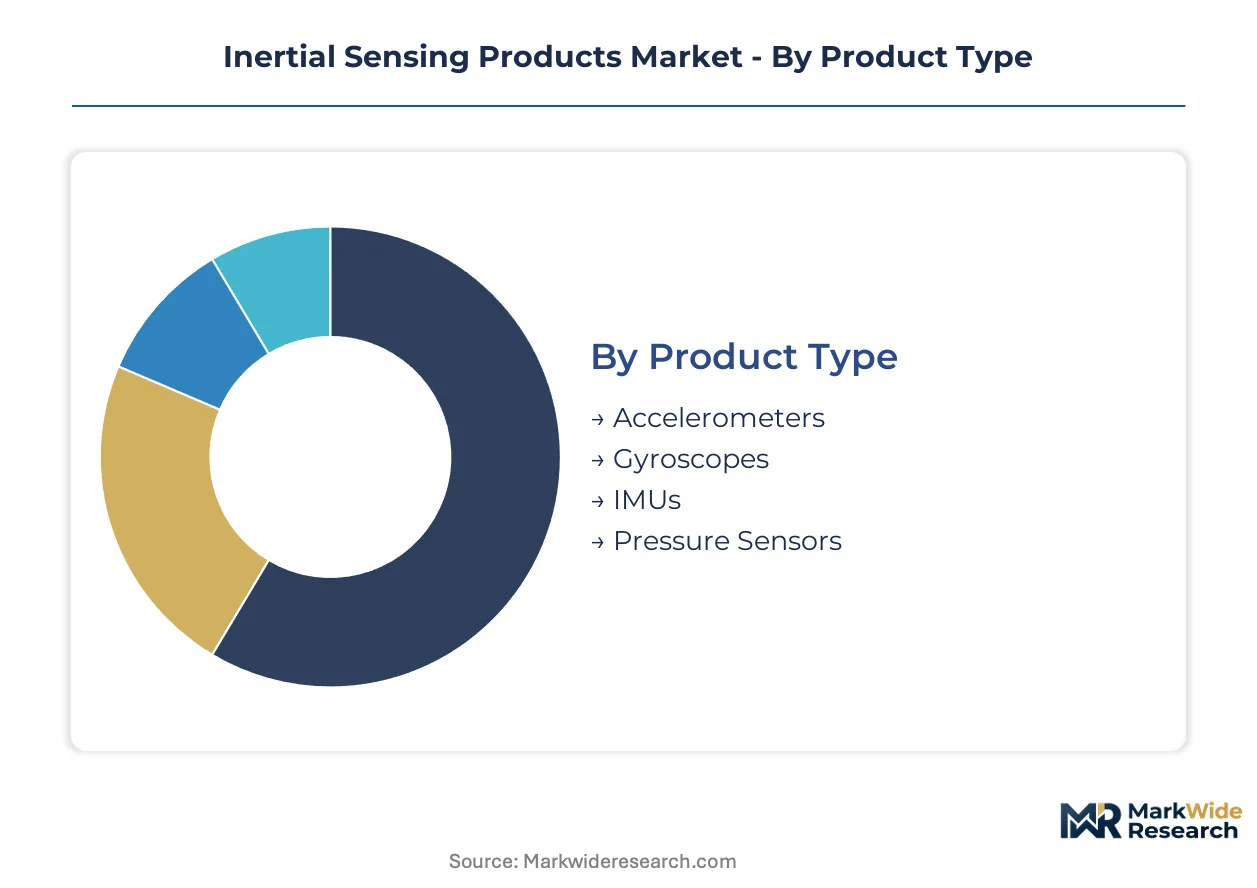
| Segmentation | Product Type: Accelerometers, Gyroscopes, IMUs, Pressure Sensors Technology: MEMS, Optical, Microelectronic, Servo End User: Aerospace, Automotive, Consumer Electronics, Industrial Automation Application: Navigation, Motion Tracking, Robotics, Vehicle Control |
| Companies Covered | Honeywell International Inc., Northrop Grumman Corporation, Safran Electronics & Defense, Thales Group, STMicroelectronics, Murata Manufacturing Co., TE Connectivity, Bosch Sensortec GmbH, VectorNav Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inertial Sensing Products Market Shifts & Advancements
Silicon photonics and advanced packaging are converging to reshape inertial sensing form factors, while regulatory pressure on fluorinated gases and unmanned aerial certification is rewriting procurement criteria.
Wafer-level vacuum packaging is miniaturizing high-performance MEMS gyroscopes below 3 cubic millimeters while preserving quality factor. Autonomous drone manufacturers are adopting these devices for attitude reference systems where weight budgets constrain payload capacity. The structural consequence is compressing the size gap between tactical-grade MEMS and traditional quartz gyroscopes.
The EU F-Gas Regulation is mandating leak detection systems in commercial refrigeration, expanding addressable demand for micro-machined pressure sensors with hermetic seals. Industrial cold chain operators must retrofit existing installations, accelerating replacement cycles for legacy electromechanical gauges. Germany's precision manufacturing corridor is absorbing disproportionate volume as equipment OEMs consolidate sensor procurement.
Buyer concentration among automotive Tier 1 suppliers is compressing negotiation cycles and demanding multi-year price roadmaps. Stuttgart-based chassis control specialists now specify IMU performance envelopes three model generations forward, locking suppliers into development partnerships. This pattern is most pronounced in Germany, where platform sharing across Volkswagen Group brands amplifies volume commitments.
Inertial Sensing Products Market Segmentation
Technology trajectories and end-use specifications fragment the inertial sensing landscape into distinct procurement tiers. Substitution pressures from adjacent sensor modalities reshape competitive boundaries within each category.
Product Type:
Optical sensing technologies exert the strongest substitution pressure on electromechanical alternatives in precision-critical applications.
- Accelerometers:Silicon bulk-micromachined devices with capacitive transduction dominate automotive safety systems and consumer drop-detection. Stuttgart-based chassis control specialists specify these for active suspension feedback loops where vibration isolation demands sub-milligram resolution.
- Gyroscopes: MEMS ring and tuning-fork architectures displace quartz rate sensors in tactical navigation, though fiber-optic systems retain submarine and strategic missile platforms. Bias stability below 0.01 degrees per hour remains beyond MEMS reach, preserving optical dominance in ITAR-controlled procurement.
- IMUs: Multi-axis packages fuse accelerometer and gyroscope outputs for dead-reckoning navigation in GPS-denied environments.
- Pressure Sensors: Piezoresistive and capacitive micro-machined variants monitor compressor performance in industrial refrigeration systems subject to EU F-Gas leak-detection mandates.
Accelerometers retain volume leadership; IMUs hold the steepest expansion curve.
Technology:
Cost tier stratification separates semiconductor-scalable approaches from precision-limited legacy architectures.
- MEMS:Wafer-scale silicon fabrication exploits semiconductor cost curves, enabling sub-dollar unit economics at consumer volumes. Bosch Sensortec's Reutlingen facility anchors European captive production for automotive and mobile device absorption.
- Optical: Fiber-optic and ring laser gyroscopes deliver bias stability unmatched by solid-state alternatives. US Department of Defense ITAR controls restrict strategic-grade production to a handful of domestic and allied contractors.
- Microelectronic: Integrated circuit approaches combine sensing elements with signal conditioning in compact surface-mount packages.
- Servo: Mechanical floated-gyro platforms persist in legacy aerospace retrofit programs where certification grandfathering outweighs replacement economics.
MEMS commands the broadest volume base; optical technology captures the highest value per unit.
End User:
Customer type concentration in Germany's precision manufacturing corridor concentrates procurement influence among automotive Tier 1 suppliers.
- Aerospace:Commercial aviation and defense platforms impose DO-160G environmental qualification standards that extend development cycles. FAA and EASA certification requirements favor established suppliers with ring laser gyroscope heritage.
- Automotive: Munich and Stuttgart clusters specify IMU performance envelopes three model generations forward, locking suppliers into multi-year development partnerships. Platform sharing across Volkswagen Group brands amplifies volume commitments.
- Consumer Electronics: Smartphone and wearable device manufacturers drive MEMS unit volumes through annual refresh cycles.
- Industrial Automation: Warehouse robotics and last-mile delivery platforms absorb compact IMUs for indoor dead-reckoning where GPS signals degrade.
Automotive absorbs the largest revenue share; industrial automation is climbing the fastest.
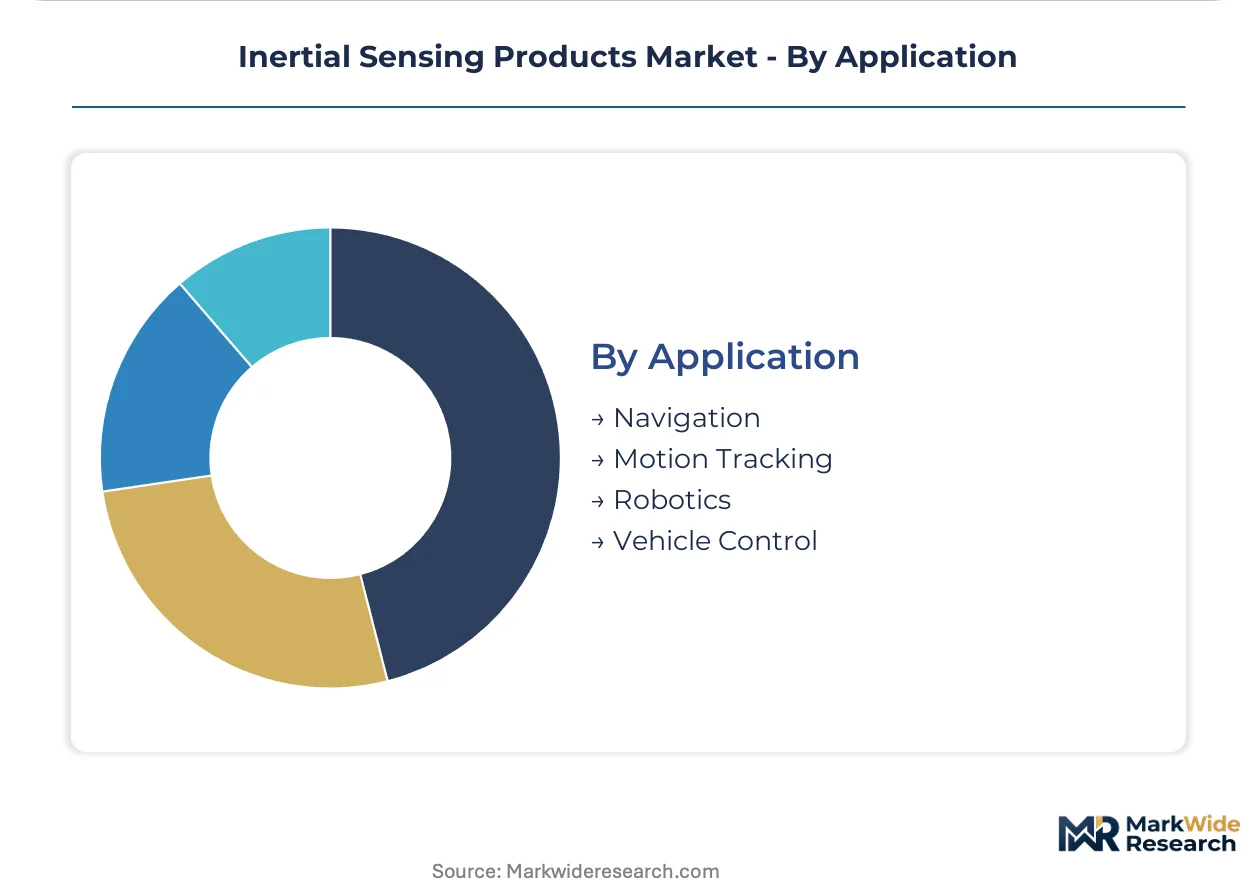
Application:
Application maturity varies sharply between established navigation infrastructure and emerging robotics deployment.
- Navigation:Platform stabilization and dead-reckoning systems in GPS-denied environments demand bias stability specifications that filter out MEMS alternatives in strategic-grade procurement.
- Motion Tracking: Sports science and biomechanics applications tolerate higher drift rates in exchange for form factor miniaturization.
- Robotics: Autonomous mobile robots fuse IMU outputs with lidar and vision systems for simultaneous localization and mapping in warehouse environments.
- Vehicle Control: Electronic stability control and autonomous driving subsystems integrate accelerometer and gyroscope data for real-time chassis dynamics adjustment.
Navigation retains the most stringent performance requirements; robotics is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA's evolving certification standards for unmanned aerial systems anchor the United States as the primary regulatory force shaping commercial aerospace demand. Germany's precision manufacturing corridor concentrates automotive and robotics procurement. China's GB standards and NMPA medical device rules expand surgical navigation applications.
United States
Defense contractors absorb strategic-grade ring laser gyroscopes for submarine and missile platforms. The Department of Commerce's Bureau of Industry and Security enforces ITAR controls that restrict high-performance component exports. Boston and Los Angeles aerospace clusters house established suppliers with decades of heritage in navigation-grade fabrication.
Germany
Automotive Tier 1 suppliers specify IMU performance envelopes three model generations forward for chassis control systems. The EU F-Gas Regulation mandates leak detection retrofits in industrial refrigeration, expanding pressure sensor demand. Stuttgart and Munich manufacturing corridors lock MEMS suppliers into multi-year development partnerships through platform-sharing across Volkswagen Group brands.
China
Domestic robotics OEMs source compact IMUs for warehouse automation and last-mile delivery platforms. NMPA medical device regulations enable surgical navigation systems combining inertial sensing with optical tracking. Shenzhen and Shanghai electronics manufacturing bases absorb wafer-scale MEMS production for consumer and industrial tiers.
Japan
Precise motion control applications in semiconductor equipment and factory automation drive gyroscope procurement. METI industrial standards shape performance benchmarks for automotive safety systems. Nagoya and Osaka precision manufacturing clusters integrate MEMS-based inertial units into robotic assembly platforms.
India
Electronics manufacturing incentives draw MEMS packaging and test capacity to emerging industrial corridors. The PLI scheme subsidizes component localization for automotive and mobile device supply chains. Bangalore and Hyderabad technology hubs attract fabless design houses establishing technical sales offices adjacent to domestic OEMs.
Inertial Sensing Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the inertial sensing market. Captive foundries with wafer-scale MEMS fabrication anchor high-volume automotive and consumer tiers, while defense contractors concentrate strategic-grade optical gyroscope production under export control restrictions. Three archetypes dominate: semiconductor-integrated MEMS suppliers, aerospace heritage specialists with ring laser gyroscope legacy, and fabless design houses outsourcing fabrication to merchant foundries. Competitive moves center on backward integration into MEMS fabrication capacity and geographic expansion of technical sales offices adjacent to automotive clusters.
Among defense heritage specialists, Honeywell International Inc. and Northrop Grumman Corporation exemplify the strategic-grade tier where ITAR-controlled production concentrates. Bosch Sensortec GmbH represents the captive-foundry archetype, anchoring European automotive MEMS supply through in-house wafer-scale integration. These three companies illustrate how vertical integration depth and regulatory compliance capabilities separate premium-tier positioning from commodity competition.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Northrop Grumman Corporation |
| Safran Electronics & Defense |
| Thales Group |
| STMicroelectronics |
| Murata Manufacturing Co. |
| TE Connectivity |
| Bosch Sensortec GmbH |
| VectorNav Technologies LLC |
| Others |
Supply & Pricing Matrix
Eighteen-to-thirty-six-month FAA certification timelines for commercial aviation IMUs compress supplier pricing power while concentrating procurement leverage among Stuttgart-based automotive Tier 1s who specify performance envelopes three model generations forward. This lead-time band locks MEMS suppliers into multi-year development partnerships that anchor contract-based pricing structures across the value chain.
Pricing Analysis
Germany-to-United States price spreads of 15-25 percent reflect EU F-Gas Regulation compliance costs embedded in pressure sensor procurement for industrial refrigeration retrofits. Three-tier pricing structure across ITAR-controlled strategic-grade, automotive-qualified tactical-grade, and consumer-tier MEMS separates bias stability certification levels from volume scale economics. Price differentiation hinges on DO-160G environmental qualification status and wafer-scale integration depth. Pricing pressure stems from raw material volatility in high-purity silicon wafers, squeezing fabless designer margins. Automotive chassis control specialists exhibit lowest price sensitivity due to platform-sharing volume commitments; consumer electronics OEMs drive hardest unit cost negotiations.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for specialty glass substrates and high-purity silicon wafers feeding MEMS fabrication. Supply concentrates in Germany's Reutlingen captive foundry cluster, United States defense contractor facilities under ITAR control, and China's Shenzhen packaging corridors. Raw material dependencies include silicon-on-insulator wafers, borosilicate glass for fiber-optic gyroscopes, and hermetic sealing alloys. Single-source vulnerability persists in ring laser gyroscope production restricted to a handful of US and European defense contractors. Distribution runs through direct technical sales offices adjacent to Stuttgart and Munich automotive clusters, bypassing traditional component distributors for high-volume programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among automotive Tier 1 suppliers and robotics OEMs who consolidate procurement through multi-year platform commitments, fragmenting supplier negotiation leverage across fragmented fabless design houses.
For Market Incumbents: Secure captive MEMS fabrication capacity in India's PLI-subsidized Bangalore and Hyderabad corridors to offset raw material cost volatility. Defend aerospace contracts by accelerating ring laser gyroscope bias stability roadmaps against fiber-optic substitution threats. Lock in Stuttgart-based chassis control specialists through three-model-generation performance specifications that raise switching costs for alternative suppliers. For New Entrants and Emerging Players: Differentiate on surgical navigation convergence by fusing IMU outputs with optical tracking systems for spine and orthopedic robotic platforms. Target India's emerging electronics manufacturing corridors where PLI incentives subsidize packaging and test capacity localization. Penetrate warehouse automation through direct-to-OEM technical sales offices bypassing legacy distribution markups. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because MEMS fabrication specialist scarcity and ITAR-controlled supply concentration favor scaled incumbents with captive foundry assets. Acquire fabless design houses with multi-physics simulation talent pipelines and existing automotive Tier 1 qualifications. Watch FAA unmanned aerial system certification standard evolution as the inflection signal for tactical-grade MEMS demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Captive wafer-scale production at Reutlingen-equivalent facilities secures automotive volume commitments against foundry capacity constraints. |
| Direct-to-OEM Technical Sales Expansion | Stuttgart and Munich office placements compress negotiation cycles with Volkswagen Group platform-sharing procurement teams. |
| Surgical Navigation Sensor Fusion Development | IMU-optical tracking integration opens NMPA-regulated robotic-assisted procedure platforms in spine applications. |
| India PLI Corridor Manufacturing Localization | Bangalore and Hyderabad packaging capacity draws MEMS test operations adjacent to domestic automotive and mobile OEMs. |
| ITAR-Compliant Strategic-Grade Capacity Preservation | Ring laser gyroscope heritage investments defend submarine and missile platform contracts against export control harmonization risks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FAA certification databases, EU F-Gas Regulation implementation reports, and semiconductor trade flow records through a bottom-up and top-down triangulation framework. Primary interviews engaged MEMS design engineering directors, automotive Tier 1 procurement leads, aerospace platform integration specialists, and industrial refrigeration OEM technical sales heads. Secondary validation incorporated Bureau of Industry and Security export control filings, EASA airworthiness directives, and India PLI scheme administrative records.
Segmentation dimensions modeled include technology tier, end-use application, performance specification band, and geographic regulatory cluster across the analysis window. CAGRs derive from unit shipment trajectories by product category calibrated against value-per-unit trends in strategic-grade versus consumer-tier procurement. Industry-specific forecast inputs encompass ITAR-controlled production capacity constraints and EU F-Gas leak-detection retrofit cycle timing.
Material uncertainties — ITAR control harmonization between US and EU dual-use regulations, raw material volatility in semiconductor substrate markets, and FAA unmanned aerial certification timeline shifts — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued MEMS cost curve compression and sustained automotive platform-sharing volume concentration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Distributed Fiber Optic Sensing Market
Sensors and Controls
Mass Flow Controller Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
Safety Sensors Market
Sensors and Controls
Automotive Image Sensors Market
Sensors and Controls
Current Sensor Market
Sensors and Controls
Asia-Pacific Digital Thermometer Market
Sensors and Controls
Wireless IoT Sensors Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
US Temperature Sensors Market
Sensors and Controls
Piece-Level Inventory Tracking and Vision Systems Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
Hydrogen Pressure Sensor Market
Sensors and Controls
Yaw Rate Sensors Market