
 Conductive Polymer Capacitor Market | 2026-2036
Conductive Polymer Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
Conductive Polymer Capacitor Market Analysis
Multi-source procurement for conductive polymer capacitors is recalibrating how tier-1 automotive suppliers manage supply risk. Panasonic leverages captive polymer chemistry R&D to sustain margin control across surface-mount lines. KEMET anchors North American supply through vertically integrated tantalum-polymer operations. Murata Manufacturing dominates high-frequency MLCC-polymer hybrids for 5G base stations.
Conductive polymer capacitors employ solid electrolytic layers of intrinsically conductive polymers such as PEDOT:PSS, replacing liquid electrolytes to achieve equivalent series resistance below 10 milliohms and operational lifetimes exceeding 10,000 hours at rated voltage. Their primary purpose is filtering and energy buffering in switched-mode power supplies where aluminum electrolytic reliability proves insufficient. Surface-mount formats lead volume shipments due to pick-and-place compatibility with high-density PCBs in consumer electronics and automotive ECUs. The automotive application segment represents the fastest-expanding demand pool as 48-volt mild-hybrid architectures multiply DC-link stabilization requirements. OEM end users capture the deepest margin pools through multi-year qualification cycles that lock out second-source competition.
REACH restrictions on hexavalent chromium and phthalate plasticizers constrain polymer dopant formulations across European supply chains, while EPA hazardous substance rules under TSCA govern U.S. import qualifications. Japan's METI enforces JIS standards for capacitor endurance that effectively filter non-compliant suppliers from precision industrial markets. Stakeholders must monitor evolving F-Gas Regulation scope expansions that could reclassify certain polymer curing chemistries and trigger reformulation costs ahead of compliance deadlines.
Market Dynamics
Automotive electrification is compressing qualification timelines while tightening performance specifications, forcing capacitor manufacturers to synchronize polymer chemistry R&D with tier-1 supplier validation gates.
Growth Catalysts
- 48-Volt Mild-Hybrid Architectures:DC-link stabilization requirements in powertrain electronics are pulling conductive polymer capacitors into engine control modules. This application segment commands premium qualification cycles that lock in multi-year supply agreements.
- REACH Phase-Out Mandates:Restrictions on hexavalent chromium in European supply chains are disqualifying traditional aluminum electrolytic formulations. Conductive polymer alternatives bypass these material bans while delivering sub-10 milliohm equivalent series resistance.
- PEDOT:PSS Formulation Advances:Intrinsically conductive polymer layers now achieve operational lifetimes exceeding 10,000 hours at rated voltage. Solid electrolytic construction eliminates dry-out failure modes that plague liquid electrolyte capacitors in high-temperature automotive underhood environments.
Market Restraints
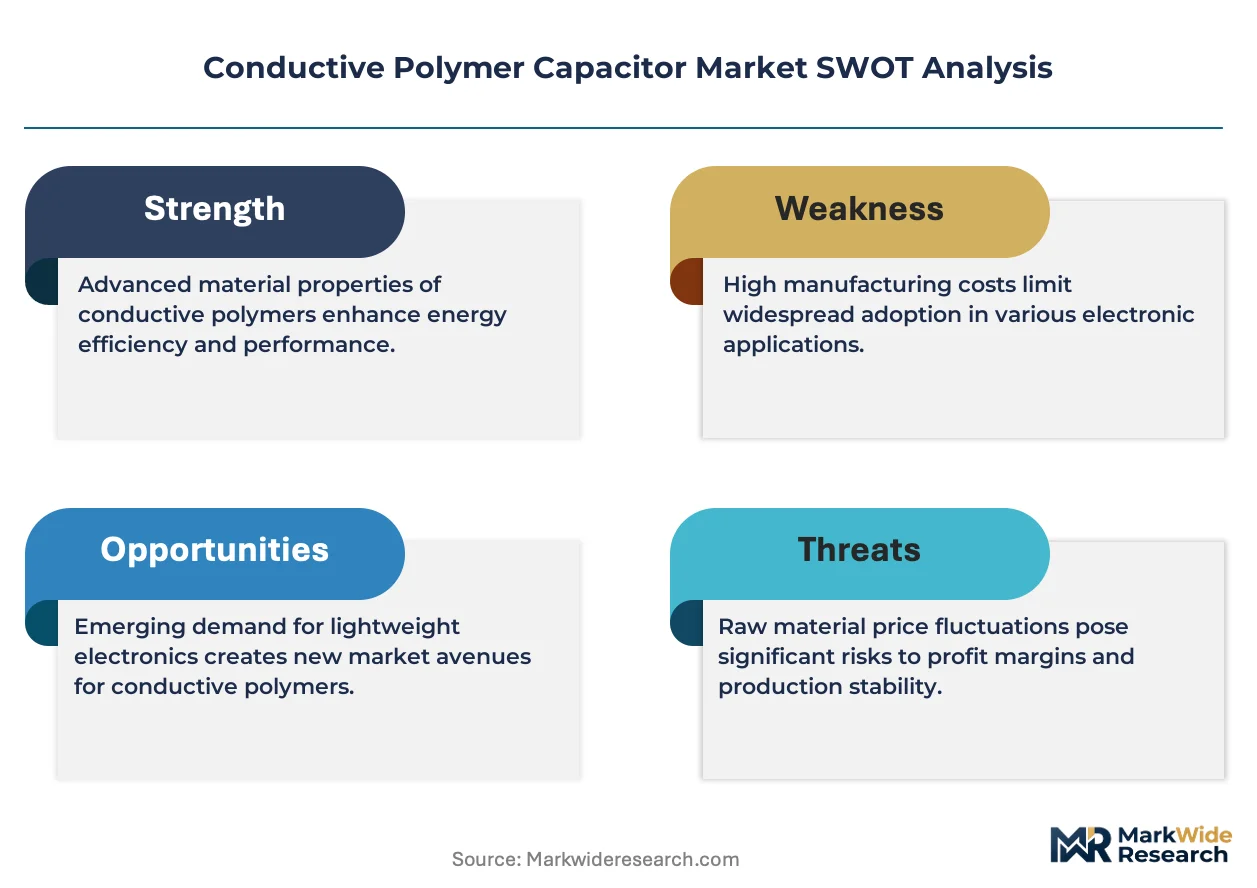
- Tantalum Ore Concentration:Vertical integration into tantalum-polymer operations depends on ore sourcing from conflict-affected regions. Supply concentration risk in Central Africa creates price volatility that propagates through capacitor bill-of-materials.
- Polymer Dopant Chemistry Constraints:Phthalate plasticizer restrictions under REACH constrain formulation flexibility for PEDOT:PSS derivatives. Reformulation costs cascade through European manufacturing footprints ahead of compliance deadlines.
- MLCC-Polymer Hybrid Substitution:Murata Manufacturing's high-frequency multilayer ceramic capacitor hybrids are displacing pure conductive polymer solutions in 5G base station power supplies. Frequency response advantages above 100 kilohertz erode the ESR performance edge of polymer alternatives.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and component production are drawing capacitor assembly investments. BIS certification requirements for industrial-grade components create first-mover advantages for qualified suppliers.
- Avionics Power Filtering:FAA DO-160G environmental qualification standards for airborne equipment are opening demand for high-reliability conductive polymer capacitors. Operational temperature ranges from minus 55 to 125 degrees Celsius match polymer thermal stability profiles.
- F-Gas Regulation Scope Expansion:Evolving EU classifications for polymer curing chemistries could trigger reformulation requirements. Suppliers with captive polymer synthesis capabilities capture compliance-driven switching demand from import-dependent competitors.
Industry Challenges
- Multi-Year Qualification Compression:Tier-1 automotive suppliers are compressing AEC-Q200 validation timelines from 24 months to 18 months. Concurrent engineering demands strain capacitor manufacturer application engineering resources.
- Surface-Mount Process Integration:Pick-and-place compatibility requirements for high-density PCBs in automotive ECUs demand precise moisture sensitivity level control. Reflow profile optimization for lead-free solder alloys adds process development overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conductive Polymer Capacitor Market |
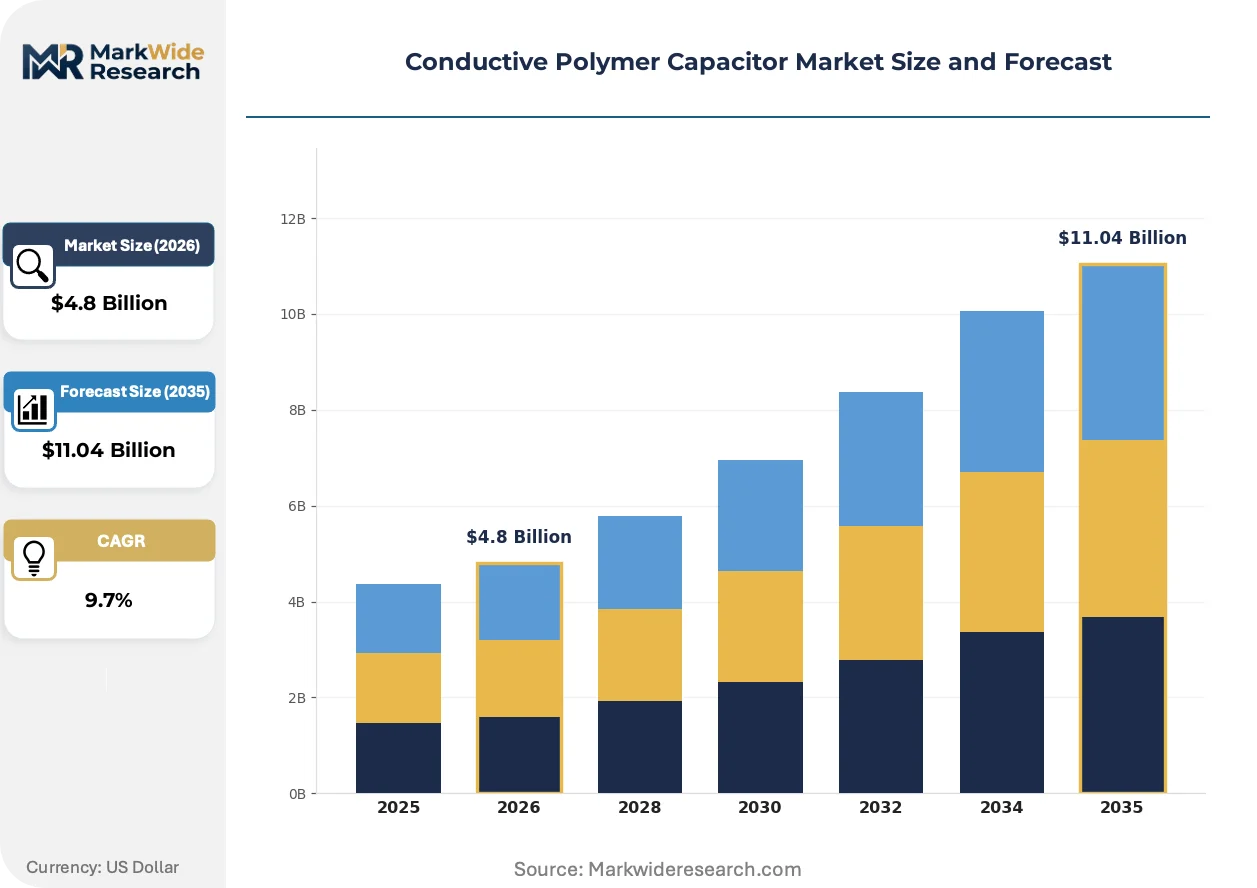
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
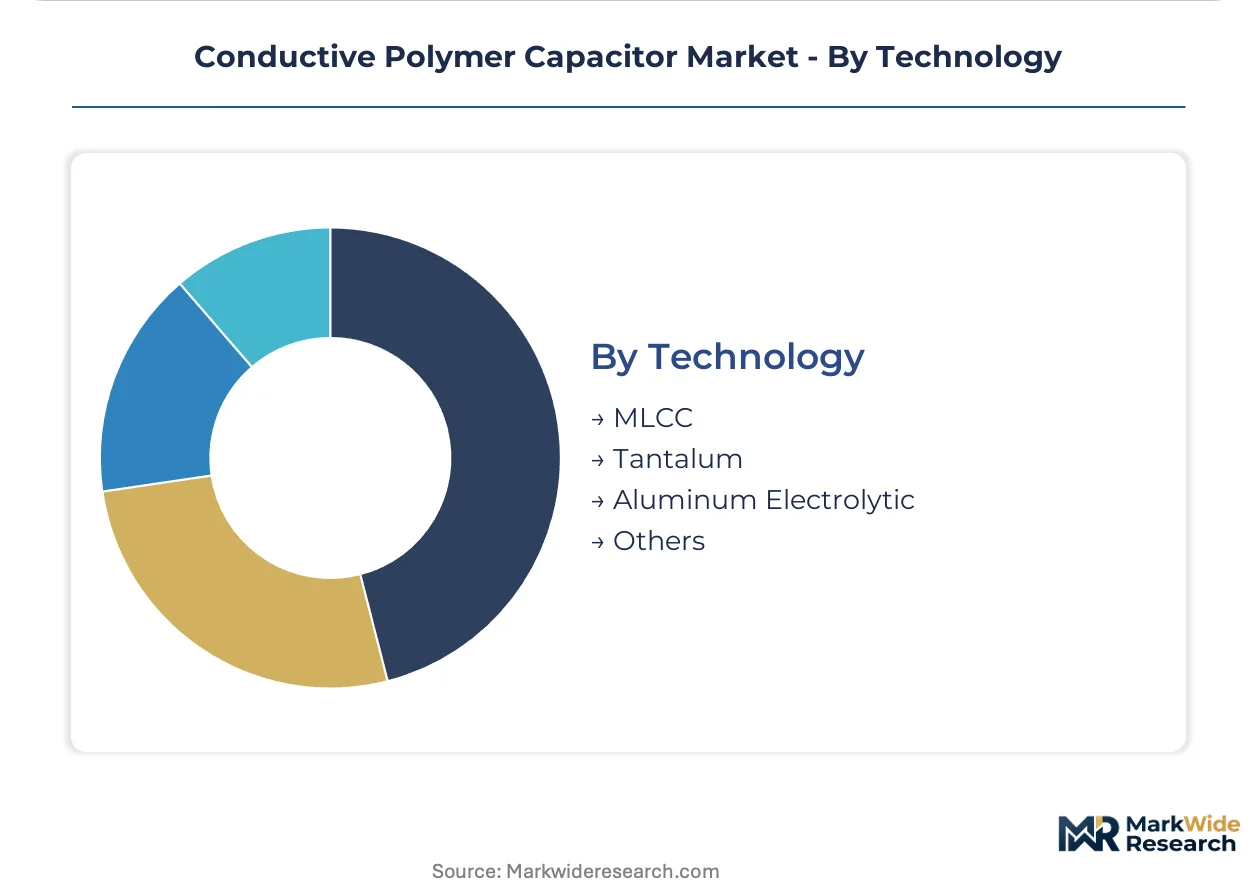
| Segmentation | Product Type: Surface Mount, Through Hole, Snap-In, Axial Application: Consumer Electronics, Automotive, Industrial Equipment, Telecommunications End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Device Manufacturers Technology: MLCC, Tantalum, Aluminum Electrolytic, Others |
| Companies Covered | Vishay Intertechnology, Inc., Cornell Dubilier Electronics, Inc., Panasonic Corporation, Lelon Electronics Corp., ROHM Co., Ltd., KEMET Corporation, Murata Manufacturing Co., Ltd., Tecate Group, Nippon Chemi-Con Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conductive Polymer Capacitor Market Emerging Trajectories
Conductive polymer capacitor technology is converging with advanced packaging formats and regulatory compliance frameworks, reshaping how manufacturers prioritize R&D investments and qualification sequencing.
PEDOT:PSS solid electrolyte formulations are integrating with aluminum foil etching processes to achieve volumetric efficiency gains in surface-mount packages. Automotive ECU designers are adopting these hybrid constructions for 48-volt mild-hybrid DC-link applications. The technology is integrating moisture barrier layers that extend operational life in underhood thermal cycling environments.
EPA hazardous substance rules under TSCA are tightening import qualification documentation for polymer precursor chemicals. Capacitor manufacturers must now submit pre-manufacture notices for modified dopant formulations. U.S.-based tier-1 suppliers are responding by dual-sourcing from domestic polymer synthesis operations to reduce customs clearance friction.
Multi-source procurement contracts are displacing sole-source agreements as tier-1 automotive buyers hedge against Japan-centric supply concentration. Panasonic and KEMET are competing for socket approvals through concurrent qualification programs. This pattern is most visible in Detroit-area powertrain engineering centers where procurement teams mandate qualified second sources before production release.
Conductive Polymer Capacitor Market Segmentation
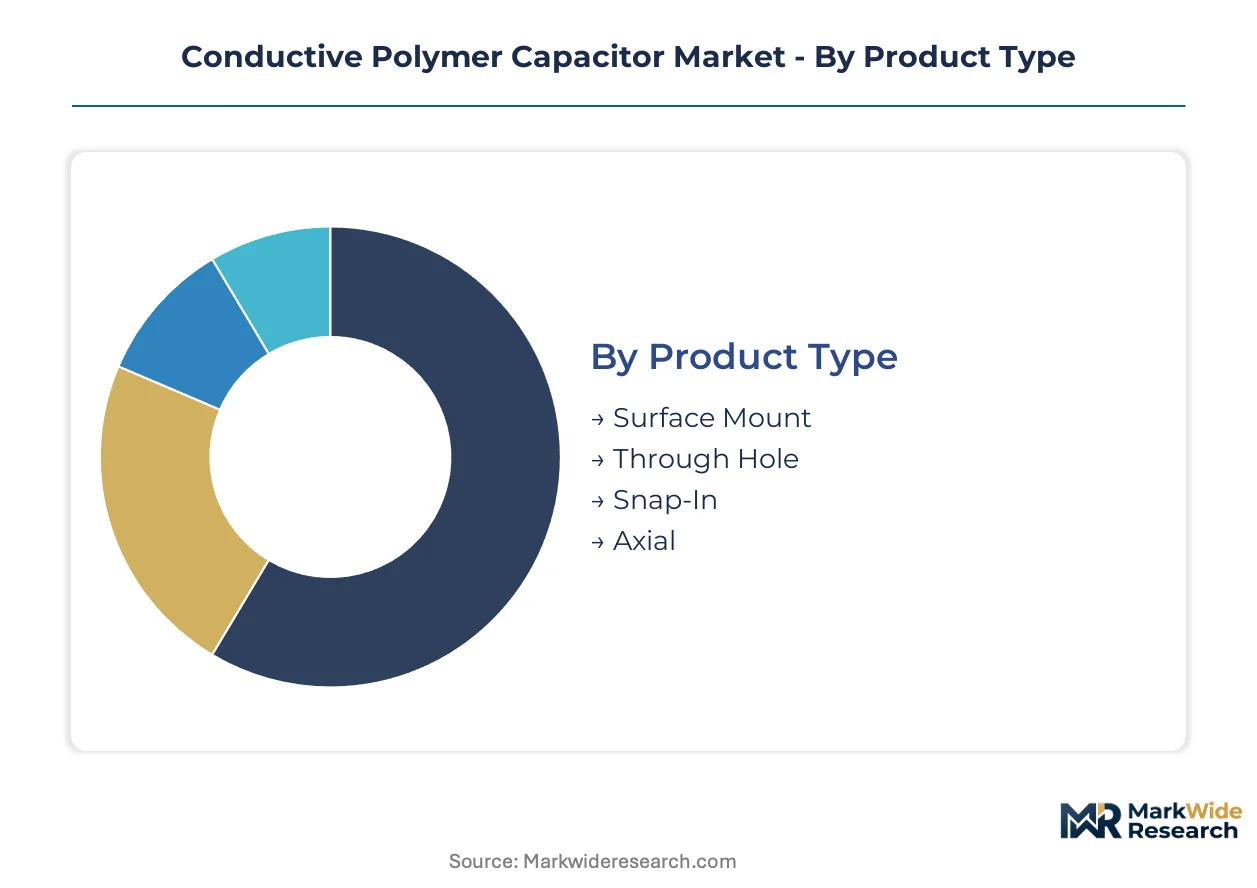
Conductive polymer capacitor procurement diverges sharply across mounting formats and end-use specifications. Automotive powertrain engineers prioritize thermal cycling endurance while consumer electronics buyers optimize for pick-and-place throughput.
Product Type:
Mounting geometry determines thermal management capabilities and assembly automation compatibility.
- Surface Mount:Compact rectangular packages with J-lead or L-tab terminations enable high-density PCB placement. Automotive ECU manufacturers in Detroit and Stuttgart specify these formats for 48-volt mild-hybrid DC-link filtering where space constraints dominate design trade-offs.
- Through Hole:Radial or axial lead configurations deliver superior mechanical stability under vibration. Industrial power supply designers in Japan's Kansai region specify through-hole polymer capacitors for factory automation equipment where solder joint fatigue resistance outweighs density requirements.
- Snap-In:Cylindrical aluminum canisters with dual-pin retention suit high-current inverter applications.
- Axial:Lead-out configurations at opposite ends accommodate legacy chassis-mount designs in telecommunications rectifiers.
Surface Mount leads on scale; Automotive specifications drive momentum for Through Hole.
Application:
End-use environments impose divergent qualification burdens and lifetime specifications.
- Automotive:Underhood thermal profiles from minus 40 to 150 degrees Celsius demand polymer electrolyte stability beyond liquid aluminum alternatives. AEC-Q200 validation gates in Germany's automotive engineering centers lock suppliers into multi-year qualification cycles.
- Consumer Electronics:High-volume smartphone and laptop production prioritizes moisture sensitivity level 3 ratings for reflow compatibility. Surface-mount polymer capacitors displace tantalum in USB-C power delivery circuits where low-profile packages enable slim industrial designs.
- Industrial Equipment:Motor drive inverters specify conductive polymer capacitors for DC bus filtering in variable frequency drives.
- Telecommunications:Base station power supplies balance ESR performance against MLCC hybrid substitution in 5G radio units.
Consumer Electronics dominates shipment volumes; Automotive commands the steepest expansion trajectory.
End User:
Procurement authority sits at different tiers of the electronics value chain.
- OEMs:Original equipment manufacturers capture margin pools through captive specification control. Japanese automotive OEMs in Toyota City and Hiroshima mandate polymer capacitor qualifications that exclude non-compliant suppliers from platform sourcing.
- Tier-1 Suppliers:Powertrain module integrators consolidate component procurement across multiple OEM programs. Bosch and Continental engineering centers specify conductive polymer capacitors for 48-volt starter-generator systems.
- Device Manufacturers:Contract electronics assemblers source to BOM cost targets with limited design influence.
- Aftermarket Providers:Repair and refurbishment channels prioritize price over qualification documentation.
OEMs lead on specification authority; Tier-1 Suppliers concentrate procurement scale.
Technology:
Electrode and dielectric materials define performance envelopes and supply chain risks.
- Aluminum Electrolytic:Etched aluminum foil anodes with PEDOT:PSS solid electrolyte layers achieve sub-10 milliohm ESR. Surface-mount formats from Japanese manufacturers dominate consumer electronics filtering applications.
- Tantalum:Sintered tantalum powder anodes with manganese dioxide or polymer cathode systems deliver volumetric efficiency. KEMET's vertically integrated operations in Simpsonville, South Carolina anchor North American supply.
- MLCC:Multilayer ceramic constructions displace polymer alternatives above 100 kilohertz in 5G base station power supplies.
- Others:Niobium oxide and hybrid polymer-ceramic constructions address niche reliability requirements.
Aluminum Electrolytic leads on unit shipments; Tantalum concentrates value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Kansai and Kanto manufacturing belts anchor conductive polymer capacitor production, with dense supplier ecosystems clustering around Osaka and Tokyo. Automotive electrification programs in Germany and the United States are redrawing procurement geography. India's electronics manufacturing incentives are attracting assembly investments away from traditional East Asian supply nodes.
Japan
48-volt mild-hybrid powertrain programs at Toyota and Honda are pulling conductive polymer capacitors into DC-link stabilization modules. METI enforces JIS C 5101 endurance standards that filter non-compliant suppliers from precision industrial markets. Kyoto and Osaka host Murata Manufacturing and Panasonic operations that dominate high-reliability surface-mount formats for automotive ECUs.
United States
EPA hazardous substance rules under TSCA govern import qualification documentation for PEDOT:PSS precursor chemicals. Tier-1 automotive suppliers in Detroit mandate qualified second sources before production release. KEMET's vertically integrated tantalum-polymer operations in South Carolina anchor North American supply for defense and aerospace filtering applications.
Germany
REACH restrictions on hexavalent chromium and phthalate plasticizers constrain polymer dopant formulations across European supply chains. Bosch and Continental engineering centers specify conductive polymer capacitors for 48-volt starter-generator systems. Stuttgart and Munich automotive clusters drive AEC-Q200 qualification cycles that lock suppliers into multi-year platform agreements.
China
MIIT industrial standards for capacitor reliability govern domestic procurement in telecommunications and consumer electronics. Yangtze River Delta manufacturing zones produce surface-mount polymer capacitors for smartphone USB-C power delivery circuits. Shenzhen and Dongguan electronics assemblers source to BOM cost targets with limited design influence over component selection.
India
PLI scheme incentives for semiconductor and component production are drawing capacitor assembly investments from Japanese and Taiwanese manufacturers. BIS certification requirements for industrial-grade components create first-mover advantages for qualified suppliers. Tamil Nadu and Karnataka electronics manufacturing clusters are emerging as alternative assembly locations to traditional East Asian supply nodes.
Conductive Polymer Capacitor Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue automotive qualification pathways as entry wedges. The vendor base clusters around three maturity tiers: integrated materials-chemistry specialists, discrete component assemblers, and regional distributors. Strategic archetypes include captive polymer synthesis operations, vertically integrated tantalum processors, and MLCC-polymer hybrid developers. Competitive moves concentrate on concurrent qualification programs and backward integration into polymer precursor supply.
Among Japanese manufacturers, Panasonic Corporation and Murata Manufacturing Co., Ltd. exemplify the materials-chemistry specialist archetype with captive R&D control. KEMET Corporation represents North American vertical integration into tantalum-polymer operations. These three anchors sit within distinct geographic supply nodes that shape procurement patterns for tier-1 automotive buyers.
| Leading Market Players |
|---|
| Vishay Intertechnology, Inc. |
| Cornell Dubilier Electronics, Inc. |
| Panasonic Corporation |
| Lelon Electronics Corp. |
| ROHM Co., Ltd. |
| KEMET Corporation |
| Murata Manufacturing Co., Ltd. |
| Tecate Group |
| Nippon Chemi-Con Corporation |
| Others |
Supply Flow & Price Mechanics
Captive polymer synthesis operations in Japan and the United States anchor both supply security and pricing power for conductive polymer capacitor manufacturers, insulating qualified suppliers from raw material volatility that propagates through import-dependent competitors.
Pricing Analysis
Input-cost pass-through from PEDOT:PSS precursor chemicals and etched aluminum foil determines contract pricing structures across automotive and consumer electronics tiers. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q200 qualified automotive grades from industrial and consumer specifications. Pricing pressure stems from MLCC-polymer hybrid substitution in 5G base stations where frequency response advantages above 100 kilohertz erode polymer value propositions. Tier-1 automotive buyers exhibit lowest price sensitivity due to multi-year qualification lock-in, while contract electronics assemblers in Shenzhen prioritize BOM cost minimization.
Supply Chain Analysis
Reverse-logistics flows for tantalum-polymer capacitors remain underdeveloped, with end-of-life recovery concentrated in precious metal reclamation rather than component remanufacturing. Manufacturing concentrates in Japan, the United States, and China, with KEMET's South Carolina operations and Murata's Osaka facilities anchoring regional supply. Raw material dependencies center on tantalum ore from Central Africa, PEDOT:PSS precursors from German and Japanese chemical suppliers, and high-purity aluminum foil from domestic Japanese etching operations. Single-source vulnerability in tantalum ore sourcing creates price volatility that propagates through capacitor bill-of-materials. Distribution runs through authorized distributors serving tier-1 automotive engineering centers and direct OEM contracts for high-reliability applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Conductive polymer capacitor procurement patterns favor geographic arbitrage between Japan's METI-enforced JIS standards and India's PLI scheme incentives, where regulatory compliance costs in the former contrast with subsidy-supported capacity buildout in the latter.
For Market Incumbents: Hedge against MLCC-polymer hybrid displacement by deepening backward integration into polymer precursor synthesis, capturing compliance-driven switching demand from REACH-constrained European competitors. Lock tier-1 automotive sockets through concurrent qualification programs before 18-month AEC-Q200 timelines compress further. Prioritize captive PEDOT:PSS R&D to sustain margin control as phthalate plasticizer restrictions constrain formulation flexibility.
For New Entrants and Emerging Players: REACH Phase-Out mandates in Europe open a window for conductive polymer alternatives to disqualified aluminum electrolytic formulations, particularly in industrial power supplies where sub-10 milliohm ESR specifications command premium positioning. Target India's PLI scheme beneficiary clusters in Tamil Nadu and Karnataka for assembly investments ahead of BIS certification requirements tightening. Pursue avionics power filtering as a go-to-market angle where FAA DO-160G qualification barriers filter incumbent competition.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap polymer chemistry specialists because tier-1 automotive procurement mandates qualified second sources before production release, creating acquisition currency for consolidated qualification portfolios. Five-to-ten year viability hinges on automotive electrification sustaining 48-volt mild-hybrid DC-link demand. Monitor F-Gas Regulation scope expansions for polymer curing chemistry reclassifications that trigger reformulation costs and compliance-driven switching waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Precursor Synthesis | KEMET's South Carolina captive operations insulate margins from PEDOT:PSS import documentation friction under EPA TSCA rules. |
| Concurrent Automotive Qualification Programs | Panasonic and Murata engineering centers compress AEC-Q200 timelines to secure multi-year platform agreements with Bosch and Continental. |
| India PLI Scheme Manufacturing Footprint | Japanese and Taiwanese assemblers establish Tamil Nadu operations to capture BIS certification first-mover advantages in industrial-grade segments. |
| Avionics DO-160G Certification Investment | High-reliability polymer formulations targeting minus 55 to 125 degrees Celsius operational ranges access defense and aerospace filtering demand. |
| REACH-Compliant Dopant Reformulation | Suppliers with captive chemistry R&D capture switching demand as hexavalent chromium and phthalate restrictions disqualify traditional formulations. |
Methodological Framework
Bottom-up automotive and consumer electronics modeling reconciled against top-down polymer precursor supply tracking forms the analytical core of this study. Primary interviews with tier-1 automotive procurement managers, capacitor manufacturer application engineers, polymer chemistry R&D directors, and industrial power supply designers combined with secondary validation from EPA TSCA filings, METI JIS standard documentation, ECHA REACH restriction updates, and customs trade data for PEDOT:PSS precursor chemicals. Triangulation across these sources ensures demand-side installation data aligns with supply-side capacity disclosures.
Historical trendline analysis of surface-mount and through-hole shipment patterns informs projection frameworks across the analysis window, with segmentation dimensions spanning mounting format, application environment, electrode technology, and end-user procurement authority. CAGRs derive from installed base growth in 48-volt mild-hybrid powertrains, MLCC substitution elasticity in telecommunications, and REACH compliance-driven formulation switching in European industrial markets. Forecast inputs incorporate AEC-Q200 qualification cycle compression effects and PLI scheme capacity absorption rates in India.
Revisions become necessary when F-Gas Regulation reclassifications, tantalum ore supply disruptions, or MLCC frequency performance breakthroughs materialize outside modeled parameters. Practitioners should monitor EPA TSCA pre-manufacture notice backlogs, METI JIS standard revision schedules, and Central African tantalum export licensing patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Acoustic Diaphragm Market
Electronic Components
Capacitive Stylus Pen Market
Electronic Components
Lowpass Filters Market
Electronic Components
Cordless Phone Battery Market
Electronic Components
Data Acquisition Card Market
Electronic Components
Audio DSP Market
Electronic Components
United States MLCC Market
Electronic Components
Power Inductors Market
Electronic Components
Loudspeaker Market
Electronic Components
Audio Power Amplifier Market
Electronic Components
Buffered Encoders and Decoders Market
Electronic Components
Global Capacitor Market
Electronic Components
Global Microfluidic Components Market
Electronic Components
North America MLCC Market
Electronic Components
Impulse Relays Market
Electronic Components
Coaxial Attenuators Market