
 Resonant Testing Machines Market | 2026-2036
Resonant Testing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Resonant Testing Machines Market Analysis
Aerospace component qualification is expanding as the dominant demand vertical for resonant testing machines, displacing traditional automotive fatigue testing in procurement priority. Zwick Roell leverages its electromechanical testing heritage to anchor European aerospace contracts. Russenberger Prüfmaschinen AG specializes in custom resonant frequency systems for Swiss precision manufacturing. Instron dominates North American material testing labs with servo-hydraulic resonant platforms.
Resonant testing machines apply cyclic loading at a specimen's natural frequency to evaluate fatigue life and fracture mechanics under controlled resonance conditions, typically operating between 20 Hz and 300 Hz with force capacities exceeding 1,000 kN. These systems serve critical functions in validating structural components for cyclic stress environments. Electromechanical systems lead installed base volumes due to lower maintenance profiles and energy efficiency, while hydraulic technology retains margin concentration in high-force aerospace applications. Vibration testing technology captures the fastest growth trajectory as electronics miniaturization intensifies board-level reliability demands.
EMA's Medical Device Regulation and CE marking requirements shape European equipment validation protocols, while FAA airworthiness directives mandate specific fatigue test methods for US aerospace suppliers. ISO 1099 and ASTM E466 standards define acceptable resonant test parameters across jurisdictions, creating compliance-driven replacement cycles. Stakeholders must monitor evolving battery-electric vehicle platform standards, as new chassis architectures redefine fatigue load spectra and test fixture requirements.
Market Dynamics
Electromechanical resonant testing architectures are displacing legacy hydraulic systems as aerospace OEMs prioritize energy efficiency and reduced maintenance downtime in validation workflows. This technology rotation is compressing equipment replacement cycles and redrawing competitive positioning across European and North American procurement centers.
Growth Catalysts
- FAA Airworthiness Directives:Mandated fatigue test protocols for US aerospace suppliers are accelerating resonant system deployments in wing and fuselage validation programs.
- EV Chassis Architectures:Battery-electric vehicle platforms require redesigned load spectra testing, pulling demand from Germany's automotive testing corridor into new fixture configurations.
- Electronics Miniaturization:Board-level reliability demands for 5G infrastructure and IoT devices are expanding vibration testing applications into semiconductor packaging validation.
Market Restraints
- Force Sensor Supply Concentration:Precision piezoelectric load cell manufacturing concentrates in Japanese and German specialty suppliers, creating input bottlenecks for high-capacity system builders.
- REACH Compliance Costs:European ECHA substance restrictions on test chamber coolants and hydraulic fluids are elevating material substitution expenses for equipment manufacturers serving EU markets.
- Frequency Bandwidth Limitations:Electromechanical actuators face technical ceilings above 200 Hz for high-force applications, preserving hydraulic dominance in large-component aerospace testing.
Strategic Opportunities
- Indian Aerospace Testing Infrastructure:Underdeveloped domestic fatigue validation capacity creates white space as Bangalore and Hyderabad expand MRO and manufacturing capabilities.
- Digital Twin Integration:Convergence of resonant testing data with physics-based simulation models enables predictive maintenance contracts and remote calibration services.
- EU Green Deal Incentives:Carbon footprint reduction mandates for industrial equipment are accelerating demand for energy-efficient electromechanical platforms over hydraulic alternatives.
Industry Challenges
- Calibration Technician Scarcity:Specialized expertise in resonant frequency tuning and modal analysis is concentrating in aging workforces across German and US testing centers.
- ISO 1099 Certification Timelines:Extended validation periods for new equipment designs are compressing product launch windows and elevating pre-market development costs.
- Legacy System Integration:Retrofitting digital control architectures into installed hydraulic resonant frames requires complex signal conditioning and safety system recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resonant Testing Machines Market |
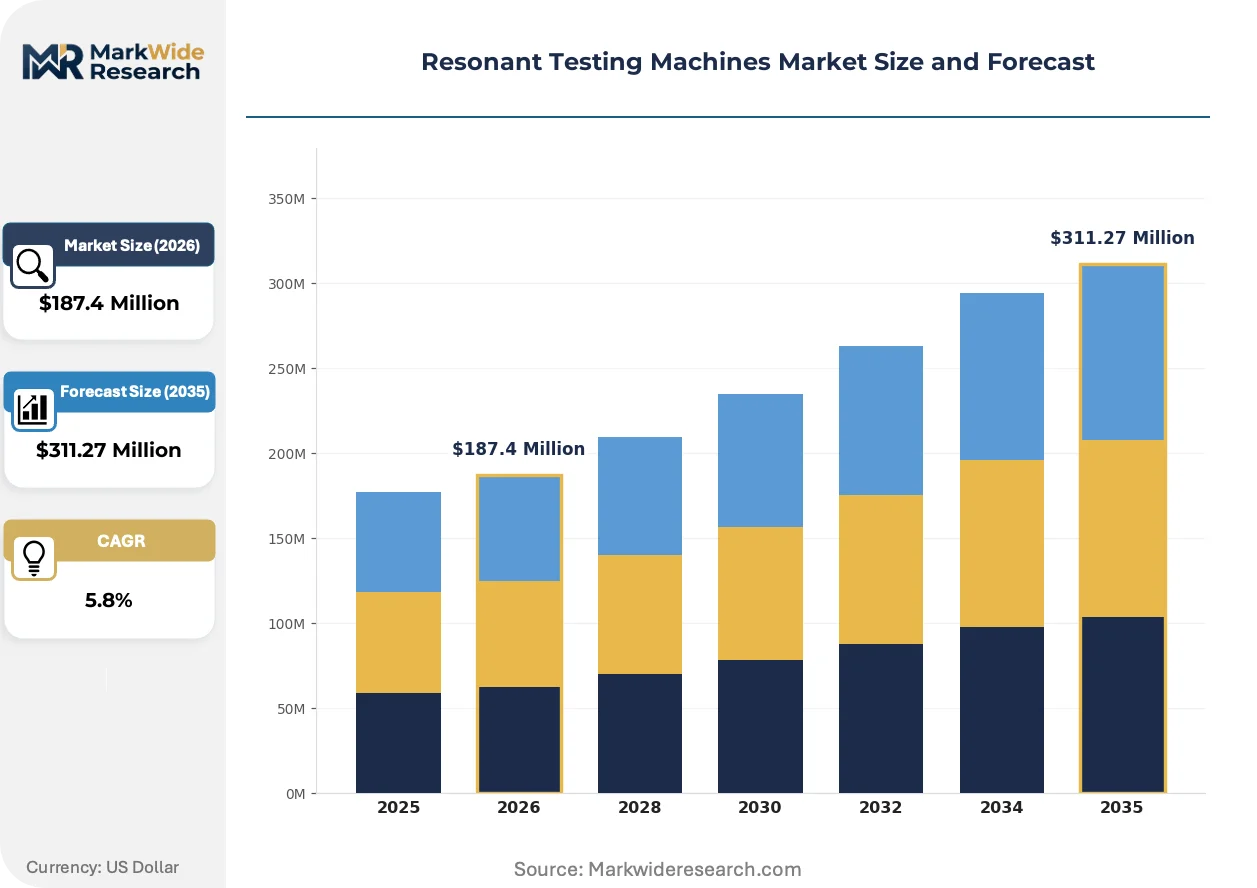
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Hydraulic, Pneumatic, Servo Application: Aerospace, Automotive Testing, Material Testing, Electronics End User: Manufacturers, Research Institutions, Aerospace Companies, Testing Labs Technology: Dynamic Testing, Static Testing, Vibration Testing, Shock Testing |
| Companies Covered | Zwick Roell, Russenberger Prüfmaschinen AG, APS Antriebs-, Prüf- und Steuertechnik GmbH, Blue Star Limited, Qualitest, Instron, PCB Piezotronics, TWI Ltd, Global Digital Systems Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resonant Testing Machines Market Emerging Trajectories
Digitalization of test workflows is compressing the gap between physical validation and virtual prototyping, reshaping how resonant systems generate value beyond raw fatigue data collection. Equipment vendors are repositioning around data services and predictive analytics capabilities.
Modular electromechanical actuator architectures are decentralizing force generation across multi-axis test configurations. Aerospace tier-one suppliers in France and Germany are adopting these platforms for simultaneous multi-component validation. This distributed approach is compressing test program durations while reducing fixture mass and setup complexity.
EU F-Gas Regulation phase-down schedules are mandating coolant transitions in environmental test chambers paired with resonant systems. Equipment manufacturers serving European markets are redesigning thermal management subsystems to accommodate lower-GWP refrigerants. Swiss and Austrian precision testing facilities are experiencing the most acute compliance-driven equipment refresh pressures.
Service contract unbundling is fragmenting traditional bundled maintenance agreements into discrete calibration, software update, and remote monitoring subscriptions. North American material testing laboratories are driving this shift, preferring usage-based payment structures over fixed annual contracts. This behavioral pivot is compressing vendor revenue recognition cycles while elevating customer lifetime value capture requirements.
Resonant Testing Machines Market Segmentation
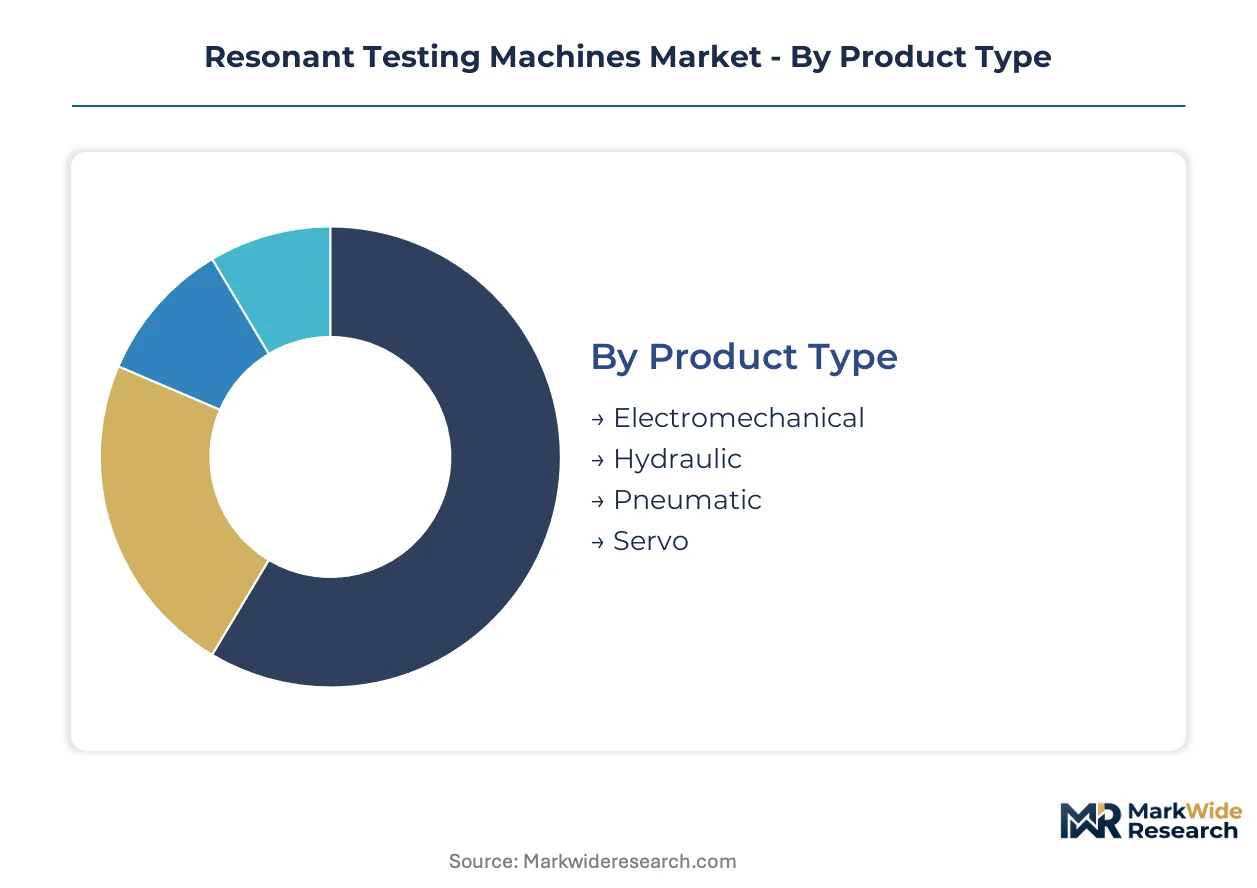
Resonant testing machine procurement hinges on matching actuator technology to specific fatigue load requirements, with aerospace validation protocols and automotive platform transitions reshaping segment priorities. Equipment specification decisions cascade across force capacity, frequency bandwidth, and environmental chamber integration requirements.
Product Type:
Capital intensity and energy efficiency tradeoffs dominate buyer evaluation, with total cost of ownership calculations extending 15-20 year equipment lifecycles.
- Electromechanical:Linear motor and ball-screw actuator architectures deliver 20-300 Hz frequency ranges with force capacities to 500 kN. German automotive OEM validation centers in Stuttgart and Wolfsburg prioritize these systems for reduced maintenance downtime and lower energy consumption versus hydraulic alternatives.
- Hydraulic:Servo-valve controlled fluid power systems achieve force outputs exceeding 1,000 kN for large aerospace structural components. US FAA-mandated wing and fuselage fatigue programs in Wichita and Seattle sustain demand despite higher operational costs.
- Pneumatic:Compressed air-driven actuators serve lower-force applications to 50 kN with rapid cycling capability. Swiss precision manufacturing facilities deploy these for small-component fatigue screening where force precision matters less than test velocity.
- Servo:Closed-loop feedback control systems integrate across electromechanical and hydraulic platforms to maintain resonance tracking accuracy. Japanese semiconductor packaging labs specify servo-enhanced configurations for board-level reliability validation.
Electromechanical systems lead on installed base scale; vibration testing applications lead on momentum.
Application:
End-use sector selection determines fixture complexity, environmental chamber requirements, and regulatory compliance protocols.
- Aerospace:Wing spar, fuselage panel, and landing gear validation under FAA airworthiness directives and EASA certification requirements. French tier-one suppliers around Toulouse deploy multi-axis resonant platforms for simultaneous component qualification.
- Automotive Testing:Chassis, suspension, and powertrain fatigue evaluation with evolving load spectra for battery-electric platforms. Germany's automotive testing corridor from Munich to Wolfsburg anchors regional procurement concentration.
- Material Testing:Metallurgical specimen characterization per ISO 1099 and ASTM E466 standards. North American university research labs and contract testing facilities drive replacement cycles for legacy hydraulic frames.
- Electronics:Printed circuit board and semiconductor package reliability under thermal-mechanical cycling. 5G infrastructure deployment and IoT device miniaturization are expanding demand in South Korean and Taiwanese electronics manufacturing centers.
Material testing leads on volume concentration; electronics leads on expansion trajectory.
End User:
Procurement authority and validation risk tolerance separate institutional buyers from commercial manufacturing operators.
- Manufacturers:In-house validation departments at automotive OEMs and aerospace primes seeking captive testing capacity. BMW's Munich validation center and Boeing's Everett test facility exemplify this segment's specification complexity.
- Research Institutions:University materials science departments and government laboratories pursuing fundamental fatigue mechanism studies. ETH Zurich and MIT maintain specialized resonant testing capabilities for academic and contracted research.
- Aerospace Companies:Dedicated airframe and engine manufacturers with proprietary test protocols exceeding commercial standards. Rolls-Royce Derby and Safran Paris operate customized resonant systems for engine component qualification.
- Testing Labs:Independent commercial facilities serving multiple industries with standardized certification services. SGS and Bureau Veritas operate resonant testing capacity across European and North American industrial corridors.
Manufacturers lead on capital deployment; testing labs lead on service model innovation.
Technology:
Test methodology selection governs data acquisition architecture, sensor integration, and simulation software compatibility.
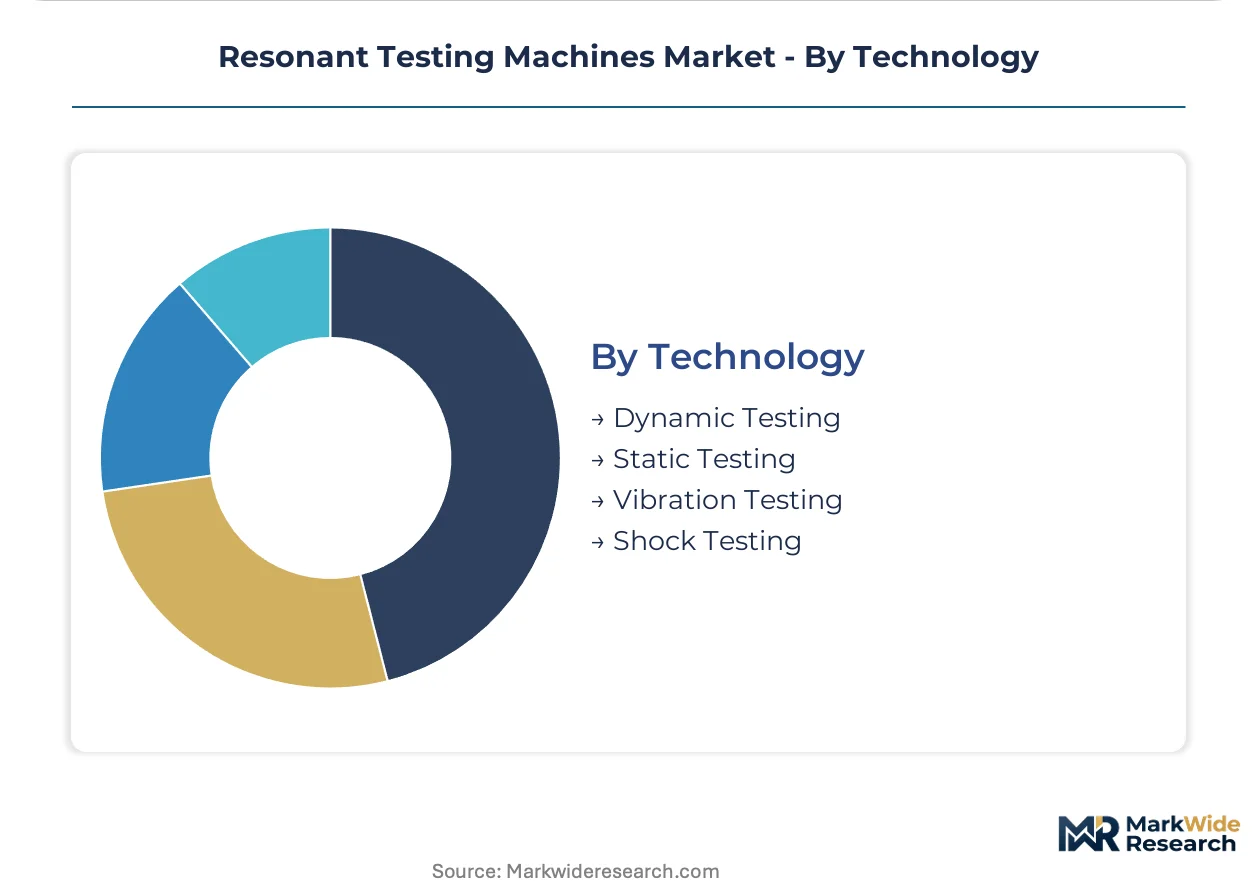
- Dynamic Testing:Cyclic loading at specimen natural frequencies to evaluate fatigue life under controlled resonance. Aerospace structural validation programs in Hamburg and Charleston specify dynamic resonant platforms for full-scale component testing.
- Static Testing:Monotonic load application for tensile and compressive strength determination. Material certification laboratories combine static frames with resonant fatigue capability for comprehensive mechanical characterization.
- Vibration Testing:Broadband frequency excitation for electronics and aerospace component environmental qualification. Environmental stress screening for 5G base station equipment is accelerating adoption in Finnish and Swedish telecommunications supply chains.
- Shock Testing:High-rate transient loading for impact resistance and crashworthiness evaluation. Automotive safety validation centers integrate shock capabilities with resonant fatigue systems for complete structural assessment.
Dynamic testing leads on revenue concentration; vibration testing leads on adoption velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping equipment procurement patterns as REACH compliance costs and F-Gas phase-down schedules in Europe elevate total cost of ownership for hydraulic systems. Manufacturers are redirecting capital toward jurisdictions with lighter environmental mandates while maintaining technical certification equivalence.
Germany
Automotive OEM validation centers in Stuttgart and Wolfsburg anchor European demand for electromechanical resonant platforms. KBA vehicle safety regulations and EU Green Deal carbon footprint mandates are accelerating displacement of legacy hydraulic frames in captive testing facilities. Bavaria's precision manufacturing corridor around Munich sustains specialized demand for high-frequency vibration testing systems serving semiconductor packaging applications.
United States
FAA airworthiness directives for wing spar and fuselage fatigue validation sustain demand for high-force hydraulic resonant systems in Wichita and Seattle aerospace clusters. EPA industrial emissions guidelines and OSHA workplace safety standards shape equipment specification protocols for domestic manufacturers. The Pacific Northwest electronics manufacturing base around Portland is expanding board-level reliability testing capacity for 5G infrastructure supply chains.
China
MIIT industrial equipment upgrade programs and GB standards compliance requirements are expanding domestic resonant testing capacity for automotive and electronics manufacturing. Yangtze River Delta manufacturing hubs around Shanghai and Suzhou are localizing supply chains for electromechanical test systems previously imported from European vendors. Dual carbon goals are elevating energy efficiency specifications in state-owned enterprise procurement tenders.
Japan
METI manufacturing technology roadmaps prioritize precision fatigue testing for automotive and electronics component validation. JIS standards certification requirements sustain demand for domestically manufactured resonant systems serving Toyota and Honda supplier networks. Nagoya's industrial corridor concentrates servo-hydraulic platform deployment for powertrain component qualification programs.
India
BIS industrial equipment standards and PLI scheme incentives for domestic manufacturing are expanding captive testing capacity in automotive and aerospace sectors. Bangalore and Hyderabad are developing MRO and manufacturing capabilities that currently rely on outsourced fatigue validation, creating white space for resonant system deployment. CDSCO medical device regulations are elevating testing protocol requirements for domestic orthopedic implant manufacturers.
Resonant Testing Machines Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with electromechanical platform vendors capturing procurement preference in automotive validation while hydraulic system builders retain aerospace structural testing relationships. The vendor base concentrates around German precision engineering heritage and North American servo-hydraulic expertise, with limited Asian participation in high-force applications. Three archetypes dominate: European electromechanical specialists, North American servo-hydraulic incumbents, and Asian volume fabricators serving cost-sensitive segments. Competitive dynamics center on technology licensing agreements for modular actuator architectures and strategic partnerships for digital twin software integration.
Among European-headquartered specialists, Zwick Roell and Russenberger Prüfmaschinen AG occupy positions within the precision electromechanical tier, with the former representing heritage testing equipment conglomerates and the latter exemplifying Swiss custom-system boutiques. Instron anchors the North American servo-hydraulic segment, sitting within the multinational materials testing platform category that spans resonant, static, and impact modalities. These three companies collectively illustrate how geographic engineering traditions translate into differentiated competitive positioning across force capacity and frequency bandwidth specifications.
| Leading Market Players |
|---|
| Zwick Roell |
| Russenberger Prüfmaschinen AG |
| APS Antriebs-, Prüf- und Steuertechnik GmbH |
| Blue Star Limited |
| Qualitest |
| Instron |
| PCB Piezotronics |
| TWI Ltd |
| Global Digital Systems Ltd |
| Others |
Supply Flow & Price Mechanics
Electromechanical actuator adoption is compressing both production costs and supplier geography as aerospace OEMs phase out hydraulic maintenance burdens. This technology rotation concentrates margin capture among linear motor specialists while fragmenting legacy pump and valve supply chains across German and Japanese industrial corridors.
Pricing Analysis
Distributor markups of 15-25% dominate European procurement channels serving mid-tier automotive validation centers, while direct-to-OEM contracts for Airbus and Boeing tier-one suppliers command volume discounts exceeding 30% off list. Pricing stratifies across aerospace-certified, automotive-standard, and economy-tier systems based on force capacity and CE marking compliance. Cost compression in electromechanical platforms stems from Chinese linear motor suppliers entering European distribution networks. Tier-one aerospace primes exhibit lowest price sensitivity due to FAA certification lock-in, whereas independent testing laboratories face acute margin pressure from unbundled service contract demands.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Airbus, Boeing, and BMW validation centers, while specialized distributors serve fragmented research laboratory procurement across North America and Europe. Precision piezoelectric load cell manufacturing concentrates in Japan and Germany, creating single-source vulnerability for force sensor inputs above 500 kN capacity. High-grade aluminum alloys for test frames and rare-earth magnets for linear motors represent critical raw material dependencies. Tariff exposure on Chinese-sourced permanent magnets is forcing European vendors toward Japanese and Korean magnet suppliers. Distribution runs through authorized service partners for calibration-intensive aftermarket revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical platform standardization is expanding margin pools as energy efficiency specifications displace hydraulic maintenance revenue into higher-margin digital service contracts. Premium-tier positioning around predictive analytics and remote calibration capabilities justifies pricing power expansion beyond hardware commoditization pressures.
For Market Incumbents: Extend digital twin integration capabilities to capture recurring software revenue from installed base telemetry, while consolidating force sensor supply relationships through equity stakes in Japanese piezoelectric specialists. Electromechanical actuator commoditization from Chinese entrants threatens mid-tier pricing; vertical integration into linear motor winding capacity in Germany or Austria defends margin structure. FAA and EASA certification timelines create defensive moats against fast-follower competition. For New Entrants and Emerging Players: Begin with modular vibration testing subsystems for 5G infrastructure and semiconductor packaging applications, where ISO 1099 compliance requirements remain less stringent than aerospace protocols. Indian aerospace MRO expansion around Bangalore and Hyderabad represents the most penetrable geographic white space, given underdeveloped domestic fatigue validation capacity. Partner with European electromechanical specialists for technology licensing rather than competing on force capacity. For Investors and Strategic Acquirers: Valuations sit cheapest among Swiss and Austrian custom-system boutiques with proprietary resonant frequency tuning software and aging founder ownership. Long-term viability favors vendors with installed base scale exceeding 500 units and service contract attach rates above 60%. Acquisition target archetype: electromechanical specialists with aerospace certification credentials and unpenetrated Indian or Southeast Asian distribution. Watch for inflection in battery-electric vehicle platform standardization announcements from German OEM consortiums.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Converges physical test data with simulation models for predictive maintenance contracts at Airbus validation centers. |
| Force Sensor Backward Integration | Secures piezoelectric load cell supply from Japanese specialists against input bottlenecks for high-capacity systems. |
| Indian Distribution Partnership | Establishes local service capacity for Bangalore aerospace MRO expansion before domestic competitors consolidate. |
| EU Green Deal Certification | Positions electromechanical platforms for carbon footprint procurement mandates in Stuttgart OEM validation centers. |
| Modular Actuator Architecture | Enables multi-axis configurations for French tier-one suppliers pursuing simultaneous component qualification. |
Methodological Framework
Multiple input streams — primary interviews with test lab directors and OEM validation engineers, secondary validation through SEC filings and EASA certification databases, and trade data reconciliation — were synthesized across bottom-up equipment shipment analysis and top-down aerospace procurement budget triangulation. Plant engineers at Stuttgart and Wolfsburg automotive centers, procurement leads at Wichita and Seattle aerospace clusters, and aftermarket service heads at European testing facilities provided operational validation. FAA airworthiness directive filings, ISO 1099 standard revision records, and EU F-Gas Regulation compliance disclosures furnished secondary anchors.
Data-stream reconciliation applied across the analysis window linked electromechanical and hydraulic technology adoption curves to segment-specific replacement cycles. Segmentation dimensions modeled include actuator technology, force capacity tier, end-use sector application, and geographic regulatory cluster. CAGRs were derived from equipment shipment trajectories cross-referenced with OEM capital expenditure disclosures. Battery-electric vehicle platform transition timelines and REACH substance restriction phase-down schedules served as industry-specific forecast modifiers.
Several conditions sit outside the modeled scope, including potential revisions to FAA fatigue test protocols, abrupt trade policy shifts affecting rare-earth magnet supply, and unanticipated breakthroughs in additive manufacturing for test fixture production. Forecasts reflect assumptions about electromechanical technology cost curves and European environmental regulation enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Sand Abrasion Tester Market
Test and Measurement
IoT Testing Equipment Market
Test and Measurement
Liquid Immersion Cooling Fluid Compatibility Test Equipment Market
Test and Measurement
Noise Vibration Harshness (NVH) Testing Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Drop Weight Testers Market
Test and Measurement
In-Circuit Test Market
Test and Measurement
Radio Frequency Test Equipment Market
Test and Measurement
Global 5G Test Equipment Market
Test and Measurement
Oscilloscope Market
Test and Measurement
Air Leak Testing Market
Test and Measurement
Force Gauge Market
Test and Measurement
Resistivity Meters Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Digital Depth Gauges Market
Test and Measurement
Wafer Testing Services Market