
 Europe Smart Air Purifier Market | 2026-2036
Europe Smart Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Air Purifier Market Foresight
A capital-intensity divergence between established HVAC conglomerates and agile appliance specialists is reorganizing competitive dynamics across Europe. Daikin Industries leverages its captive compressor manufacturing and building-systems integration to dominate commercial specification channels. Koninklijke Philips N.V. anchors its position through healthcare-adjacent brand credibility and dense retail distribution in Western European capitals. Blueair AB competes on Scandinavian design heritage and filter-subscription loyalty models that sustain recurring revenue per installed unit.
Europe Smart Air Purifiers are connected air-treatment appliances integrating particulate sensors, wireless communication modules, and automated filtration media to monitor and improve indoor air quality in real time. HEPA-class media remains the dominant technology architecture, though UV-C augmentation is displacing standalone ionizer configurations in premium residential and healthcare-adjacent commercial installations. Portable units occupy the largest volume position, while built-in systems command superior margin pools tied to new construction and deep retrofit cycles. The commercial end-user category represents the fastest structural expansion, driven by post-pandemic ventilation mandates in offices, hospitality, and education facilities.
The EU Ecodesign Directive and CE marking requirements shape product-level compliance costs and filter-efficiency disclosure standards, while national transpositions in France, Germany, and Italy add layered certification burdens. REACH restrictions on certain activated-carbon precursors and the F-Gas Regulation on refrigerant-based air-handling systems indirectly steer R&D budgets toward solid-state and electrostatic alternatives. Stakeholders must monitor whether the EU AI Act's risk-classification framework will impose algorithmic transparency obligations on adaptive purification systems that autonomously adjust to real-time air-quality telemetry.
Market Dynamics
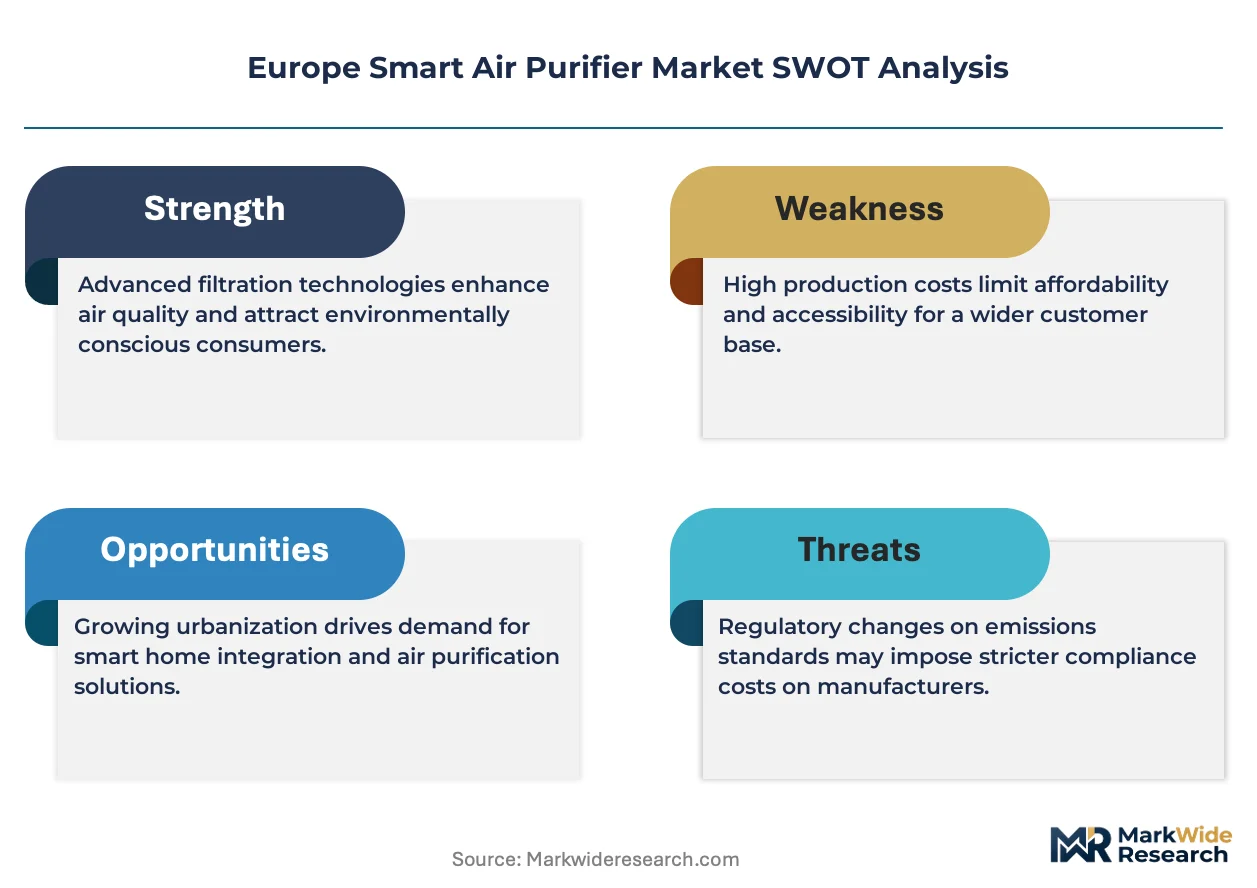
EU Ecodesign Directive amendments are compressing energy-consumption ceilings for connected appliances, forcing manufacturers to redesign compressor architectures and sensor arrays ahead of 2027 compliance deadlines. This regulatory compression is accelerating R&D migration toward solid-state filtration and low-power edge computing.
Growth Catalysts
- EU Green Deal building-renovation wave:Member-state recovery funds are channeling subsidies toward HVAC modernization in residential and commercial structures, expanding specification opportunities for integrated air-treatment systems.
- Post-pandemic ventilation mandates:France, Germany, and Italy have transposed workplace air-quality directives into national occupational health codes, mandating continuous particulate monitoring in offices, hospitality, and education facilities.
- Filter-subscription monetization:Hardware vendors are capturing recurring revenue through automated consumable replenishment tied to real-time sensor telemetry, improving customer lifetime value per installed unit.
Market Restraints
- REACH carbon-precursor restrictions:ECHA limitations on certain activated-carbon feedstocks are constraining supply flexibility for odor-removal configurations and elevating raw-material qualification costs.
- CE marking complexity:Multi-country transpositions of the Ecodesign Directive create layered certification burdens, extending product-launch timelines and fragmenting compliance budgets across national notified bodies.
- Ionizer substitution pressure:UV-C augmentation is displacing standalone ionizer architectures in premium segments, stranding inventory and compressing margins for suppliers locked into legacy electrostatic configurations.
Strategic Opportunities
- Underpenetrated Southern European housing stock:Spain and Portugal exhibit sub-15% smart-home penetration rates, creating whitespace for entry-tier connected purifiers bundled with utility-demand response programs.
- EU AI Act algorithmic transparency:Adaptive purification systems that autonomously adjust to real-time telemetry may face risk-classification obligations, creating first-mover advantage for vendors with pre-emptive documentation capabilities.
- Healthcare-adjacent commercial verticals:Clinics, dental practices, and eldercare facilities are specifying medical-grade filtration as patient-safety differentiators, opening margin pools above standard residential configurations.
Industry Challenges
- Cross-functional talent scarcity:Firmware engineering for low-power wireless modules and particulate-sensor calibration requires hybrid skill sets that command premium compensation in European labor markets.
- Retrofit integration friction:Built-in system deployments in existing structures face coordination complexity with legacy ductwork and building-management protocols, elongating sales cycles and elevating project-risk provisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Air Purifier Market |
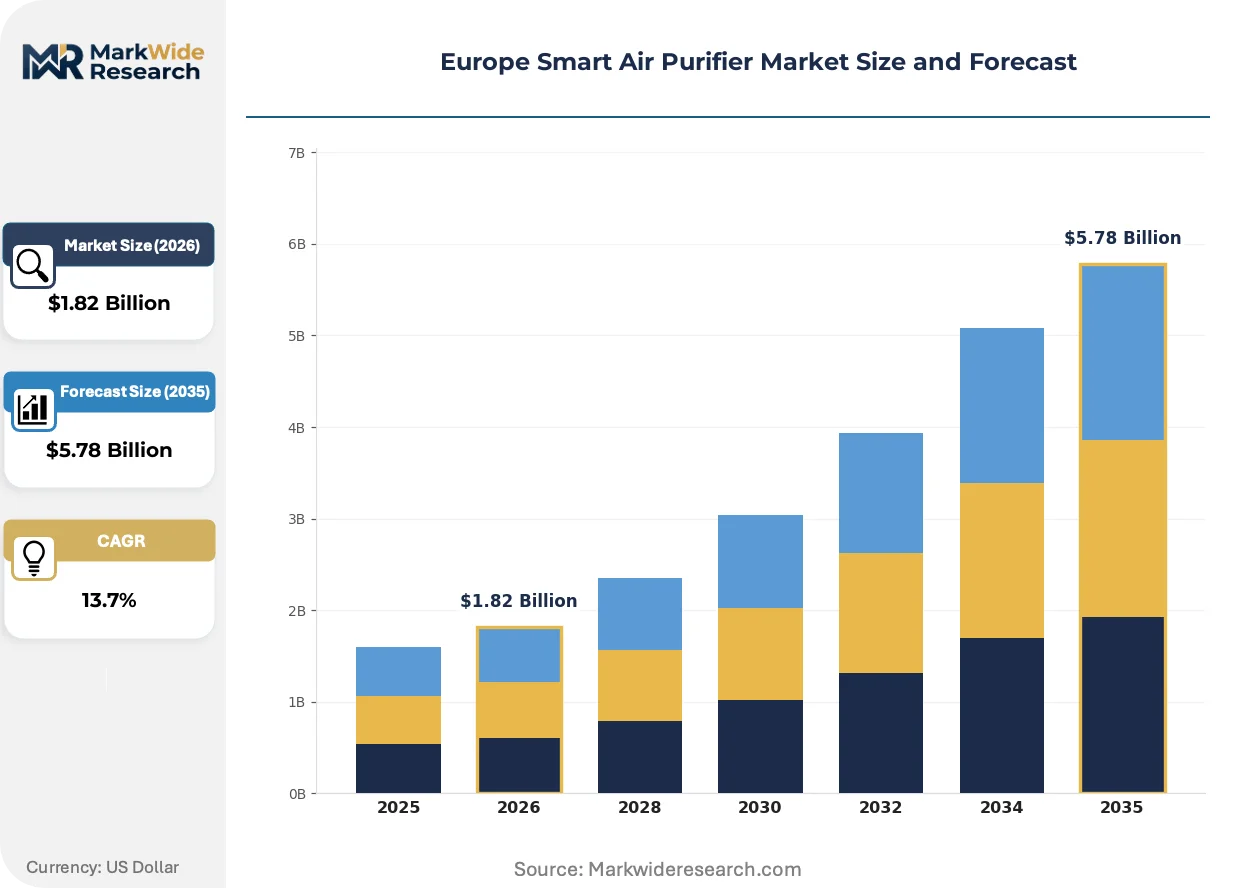
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Wall-Mounted, Built-In, Smart Plugs Technology: HEPA, UV-C, Activated Carbon, Ionizer End User: Residential, Commercial, Industrial, Automotive Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Daikin Industries, Ltd, Koninklijke Philips N.V., Honeywell International, Inc., Dyson Limited, Blueair AB, Hamilton Beach Brands, Inc., LG Electronics, Inc., Sharp Corporation, Panasonic Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Air Purifier Market Shifts & Advancements
Filtration architectures are bifurcating between HEPA-class mechanical media and emerging solid-state alternatives, while regulatory pressure on refrigerant-based systems redirects investment toward electrostatic and photocatalytic pathways. These shifts are compressing traditional technology lifecycles and redrawing supplier competitive positions.
Photocatalytic oxidation is fragmenting the premium residential segment as buyers seek chemical-vapor neutralization beyond particulate capture. High-end households in Germany and the Netherlands are specifying these configurations for VOC-sensitive environments including home offices and nurseries. The technology is fragmenting established price bands by introducing performance tiers that resist direct HEPA-equivalence comparison.
The EU AI Act's risk-classification framework is imposing algorithmic transparency obligations on adaptive purification systems that autonomously adjust to real-time air-quality telemetry. Vendors must document decision-logic for filtration-intensity modulation, elevating compliance costs for machine-learning-enabled product lines. Healthcare-adjacent commercial installations face the steepest documentation burdens as regulators scrutinize autonomous environmental-control systems in patient-facing settings.
Facility managers are consolidating vendor relationships through integrated indoor-air-quality service contracts that bundle hardware, consumables, and continuous monitoring. This procurement consolidation is displacing transactional equipment purchases in Nordic commercial markets, particularly among multi-site retail and hospitality operators. Denmark and Sweden exhibit the most advanced contract penetration, with specification teams prioritizing outcome guarantees over capital-expenditure minimization.
Europe Smart Air Purifier Market Segmentation
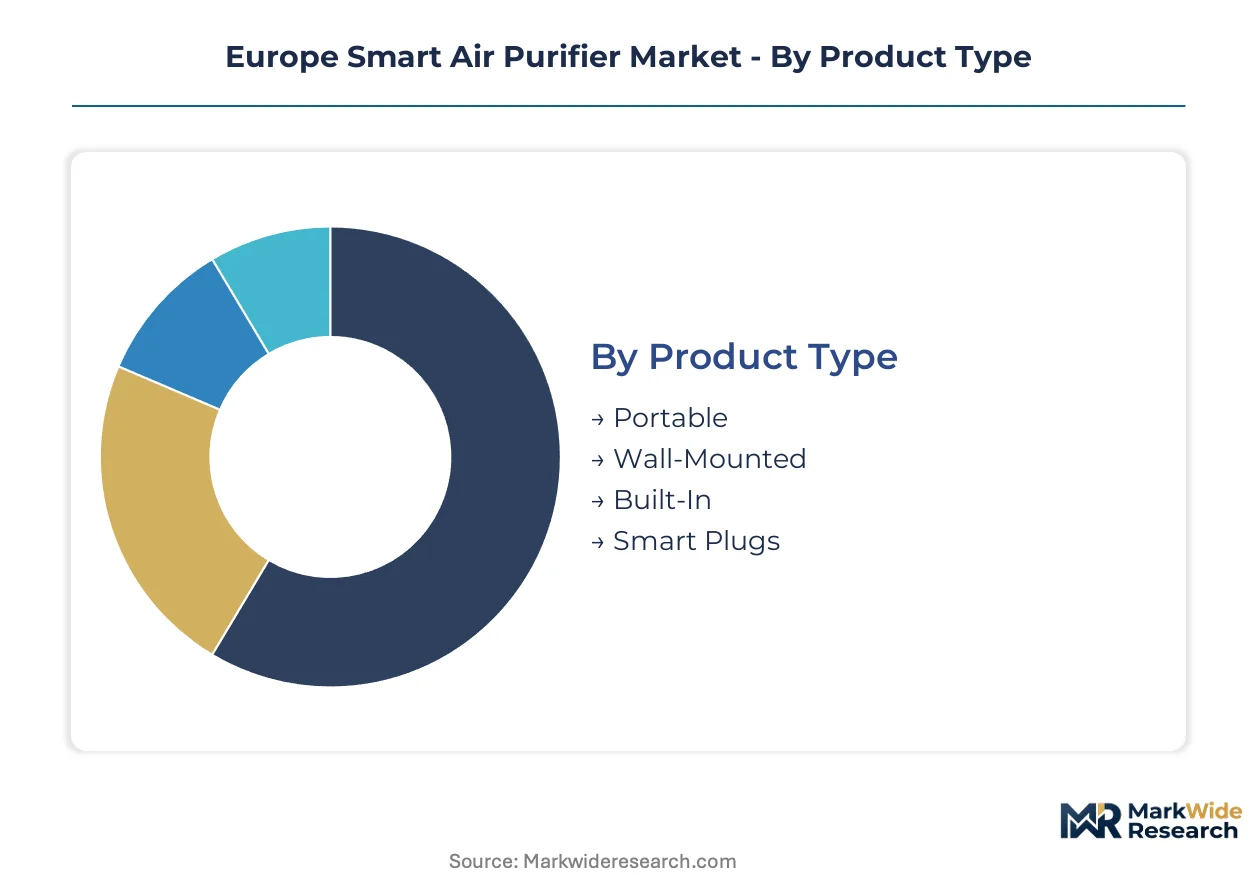
Channel strategy for Europe's smart air purifier market hinges on matching product form factors to buyer procurement patterns. Segment-specific requirements around installation complexity, filter replenishment, and regulatory documentation reshape how vendors allocate sales resources across member states.
Product Type:
Portable units dominate mass-market channels through electronics retailers and e-commerce platforms, while built-in systems flow through HVAC contractors and building-specification networks.
- Portable:Self-contained units with integrated sensors and wireless modules require no installation infrastructure. German and Dutch households drive volume through consumer electronics chains and marketplace platforms, with filter-subscription attach rates sustaining recurring revenue streams.
- Built-In:Duct-integrated systems with centralized filtration and building-management protocol compatibility. New construction and deep renovation cycles in France and Belgium concentrate demand, where EU Green Deal subsidies offset upfront capital costs.
- Wall-Mounted:Fixed-installation units bridging portability and built-in performance. Apartment renovations in urban Spain and Italy favor this configuration for space-constrained residential environments.
- Smart Plugs:Adapter-based connectivity modules converting standard purifiers to connected devices. Price-sensitive Southern European markets absorb this entry-tier option through utility bundling programs.
By volume, Portable leads. By growth pace, Built-In is ahead.
Technology:
Cost tiers stratify sharply between certified medical-grade configurations and consumer-oriented alternatives, with regulatory pressure accelerating R&D migration toward solid-state pathways.
- HEPA:Mechanical filtration media capturing 99.97% of 0.3-micron particles remains the baseline specification. German clinical environments and eldercare facilities mandate HEPA-class performance, with Ecodesign Directive amendments forcing energy-consumption reductions in motor and fan architectures.
- UV-C:Ultraviolet germicidal irradiation augmenting mechanical filtration for pathogen neutralization. Post-pandemic ventilation mandates in French offices and Italian hospitality venues specify UV-C augmentation, displacing legacy ionizer configurations in premium tenders.
- Activated Carbon:Adsorbent media targeting volatile organic compounds and odor molecules. REACH restrictions on certain carbon precursors constrain supply flexibility and elevate raw-material qualification costs for odor-removal configurations.
- Ionizer:Electrostatic precipitation systems charging particles for collection on oppositely charged plates. UV-C substitution pressure strands inventory and compresses margins for suppliers locked into legacy architectures.
HEPA commands installed base dominance. UV-C climbs the fastest as healthcare-adjacent specifications multiply.
End User:
Application requirements diverge across residential convenience priorities, commercial compliance mandates, and industrial contamination thresholds.
- Residential:Individual households prioritizing real-time air quality visibility and automated filter management. Scandinavian markets exhibit highest smart-home penetration, with dense urban centers in Germany and the Netherlands driving connected-unit adoption.
- Commercial:Offices, hospitality, and education facilities subject to occupational air-quality codes. France, Germany, and Italy have transposed workplace ventilation directives into national health regulations, mandating continuous particulate monitoring.
- Industrial:Manufacturing and processing environments with elevated particulate loads and chemical vapor exposure. Specialized configurations with reinforced housings and extended filter lifecycles serve automotive and pharmaceutical production facilities.
- Automotive:Cabin air treatment integrated with vehicle HVAC systems. Premium electric vehicle platforms in Germany and Sweden specify medical-grade filtration as passenger-safety differentiators.
Residential maintains volume leadership. Commercial posts the steepest expansion trajectory.
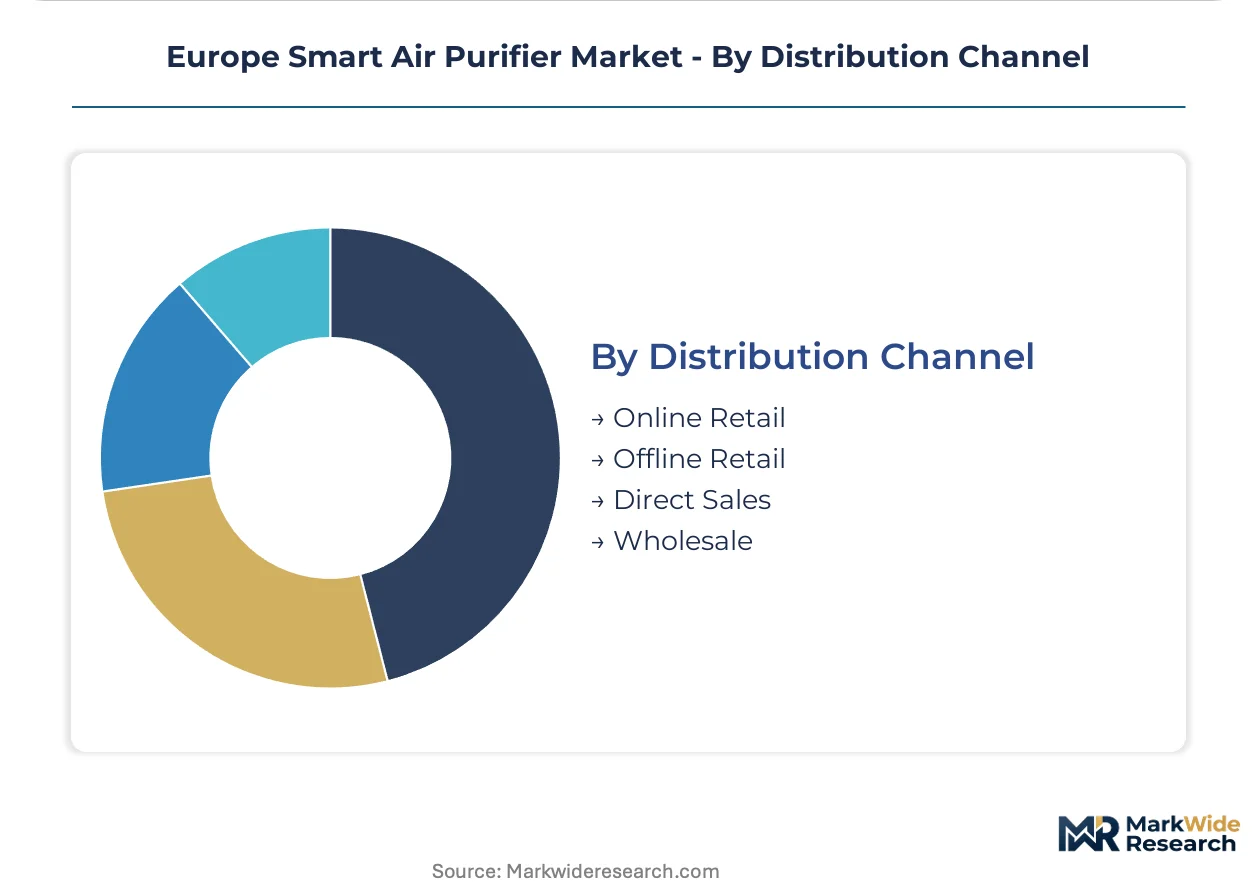
Distribution Channel:
Customer type and purchase frequency reshape channel economics, with high-velocity consumable replenishment favoring direct relationships over transactional retail.
- Online Retail:Marketplace platforms and brand-direct e-commerce capturing convenience-oriented residential buyers. Nordic markets exhibit highest digital purchase penetration for replacement filters and consumables.
- Offline Retail:Electronics chains, home improvement stores, and pharmacy networks providing tactile evaluation and immediate fulfillment. German and French capital cities retain strong specialty retail presence for premium product demonstration.
- Direct Sales:Manufacturer-to-end-user relationships for built-in systems and service contracts. Denmark and Sweden lead contract penetration, with facility managers prioritizing outcome guarantees over capital expenditure minimization.
- Wholesale:Distributor networks serving HVAC contractors and building-specification channels. Project-based procurement for new construction and deep retrofits flows through regional wholesaler relationships.
Online Retail captures transaction frequency leadership. Direct Sales expands most quickly as service-contract bundling displaces equipment-only purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's smart air purifier trade flows reveal a net importer position, with intra-EU sourcing dominating procurement channels and Nordic markets exporting specialized filtration components to Germany and France.
Germany
Building renovation subsidies under the EU Green Deal and elevated smart-home penetration drive residential demand for connected purification systems. The Federal Environment Agency enforces stringent Ecodesign compliance timelines for 2027. Munich and Stuttgart clusters concentrate HVAC integration specialists serving commercial specification channels.
France
Post-pandemic workplace ventilation mandates in offices and hospitality venues mandate continuous particulate monitoring. ANSM and labor inspectorates enforce occupational air-quality codes derived from EU directives. The Paris metropolitan area anchors specification activity for healthcare-adjacent commercial installations.
Netherlands
VOC-sensitive households in dense urban centers specify photocatalytic oxidation systems for home office and nursery environments. The Dutch Environmental Assessment Agency coordinates national implementation of REACH carbon-precursor restrictions. Eindhoven's technology corridor hosts sensor calibration and firmware engineering specialists.
Sweden
Outcome-based service contracts displace transactional equipment purchases among multi-site retail and hospitality operators. The Swedish Energy Agency administers subsidy programs tied to EU Green Deal building modernization targets. Stockholm concentrates integrated indoor-air-quality service providers pioneering contract bundling models.
Spain
Sub-15% smart-home penetration creates whitespace for entry-tier connected purifiers bundled with utility-demand response programs. The Ministry for Ecological Transition transposes Ecodesign Directive requirements into national technical regulations. Barcelona and Madrid apartment renovations favor wall-mounted configurations for space-constrained residential environments.
Europe Smart Air Purifier Market Competitive Landscape
Concentration sits with diversified HVAC conglomerates and healthcare-adjacent appliance specialists. The vendor base organizes into three strategic tiers: integrated building-systems providers leveraging captive component manufacturing, retail-anchored brands deploying dense distribution networks, and design-focused specialists monetizing recurring filter subscriptions. Dominant competitive moves include backward integration into sensor and filtration media production, plus strategic partnerships with building-management software platforms to secure specification in new construction and deep retrofit cycles.
Among diversified industrial conglomerates, Daikin Industries and Koninklijke Philips N.V. exemplify contrasting scale-driven positioning. Daikin leverages captive compressor manufacturing and building-systems integration capabilities to anchor commercial specification channels. Philips occupies a position defined by healthcare-adjacent brand credibility and dense retail distribution in Western European capitals. Blueair AB represents the specialist archetype, competing on Scandinavian design heritage and filter-subscription loyalty models that sustain recurring revenue per installed unit.
| Leading Market Players |
|---|
| Daikin Industries, Ltd |
| Koninklijke Philips N.V. |
| Honeywell International, Inc. |
| Dyson Limited |
| Blueair AB |
| Hamilton Beach Brands, Inc. |
| LG Electronics, Inc. |
| Sharp Corporation |
| Panasonic Corporation |
| Others |
Supply & Pricing Matrix
Captive compressor manufacturing in Germany and Japan anchors scale economies for integrated HVAC conglomerates, compressing unit economics for mid-tier portable specialists while elevating price floors for built-in system configurations. This concentration of component capacity concentrates margin capture among vertically integrated incumbents and fragments pricing power for assembly-only vendors across Southern European markets.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with medical-grade HEPA-UV-C configurations commanding substantial premiums over consumer portables. Price differentiation rests on CE marking tier and filter-subscription attach rates, with built-in systems bundling installation service into project-based quotations. Cost compression in the entry-tier portable segment is intensifying because utility-demand response programs in Spain and Portugal subsidize hardware acquisition. Residential households exhibit highest price sensitivity, while healthcare-adjacent commercial facilities prioritize performance guarantees over capital expenditure minimization.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for sensor modules and wireless chipsets sourced from Taiwan and South Korea. Manufacturing concentration centers on China for activated-carbon media, Germany for precision motors and compressor assemblies, and Sweden for filtration component R&D. REACH restrictions on carbon precursors constitute the primary supply chain risk, constraining odor-removal configuration flexibility. Distribution runs through HVAC contractor networks for built-in systems and electronics retail chains for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic transparency obligations are triggering a platform-economics inflection, rewarding vendors with pre-emptive documentation capabilities and interoperable building-management protocol integration.
For Market Incumbents: Consolidate specification channel control through backward integration into sensor calibration and filtration media production. Secure building-management software platform partnerships to embed air-treatment modules into new construction and deep retrofit cycles, defending against emerging solid-state filtration specialists threatening HEPA-dominated margin pools. For New Entrants and Emerging Players: CE marking fast-track services for adaptive purification systems create entry pathways into healthcare-adjacent commercial verticals. Target underpenetrated Southern European residential markets through utility bundling programs, deploying wall-mounted configurations for space-constrained apartment renovations in Barcelona and Madrid. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with hybrid mechanical-solid-state R&D pipelines and documented EU AI Act compliance frameworks. Long-term viability hinges on recurring revenue density from filter-subscription models. Watch for REACH carbon-precursor restriction expansions as inflection indicators for electrostatic alternative adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Filter-Subscription Platform Launch | Recurring revenue density improves customer lifetime value per installed German residential unit. |
| CE Marking Pre-Certification Investment | Accelerated compliance timelines capture healthcare-adjacent commercial specification opportunities. |
| Building-Management Software Partnership | Protocol integration secures embedded positioning in EU Green Deal renovation cycles. |
| Solid-State Filtration R&D Expansion | Photocatalytic and electrostatic alternatives hedge against REACH carbon-precursor constraints. |
| Southern European Utility Bundling Program | Demand-response integration unlocks whitespace in sub-15% smart-home penetration markets. |
Research Methodology
Operator-level perspectives from HVAC contractor specification teams, facility management procurement directors, sensor calibration engineers, and filter-subscription platform operators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against ECHA regulatory filings, EU Ecodesign Directive transposition documents, and customs trade data for filtration component flows. Bottom-up unit economics modeling and top-down market sizing triangulated volume estimates across the projection horizon.
Sensitivity analysis tested forecast robustness against regulatory timeline slippage and raw-material qualification cost escalations. The analytical framework segmented by product form factor, technology architecture, end-user vertical, and distribution channel, with CAGRs derived from installed base growth and replacement cycle dynamics. Modeled inputs included EU Green Deal subsidy disbursement trajectories and national occupational health code enforcement intensity.
The analysis sits within stated boundaries; outcomes outside sustained EU Ecodesign Directive compliance investment and stable REACH carbon-precursor supply would require recalibration. Forecasts reflect documented assumptions regarding algorithmic transparency obligation implementation timelines and smart-home penetration convergence rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Europe Vibration Sensors Market
Sensors and Controls
Smartphone Biometric Sensors Market
Sensors and Controls
Mexico Smart Ventilation Fans Market
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Asia-Pacific Water Detection Sensors Market
Sensors and Controls
Asia-Pacific Current Transducer Market
Sensors and Controls
Global Blind Spot Monitor Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
Asia-Pacific Digital Thermometer Market
Sensors and Controls
Sensor Fusion Market
Sensors and Controls
Magnetic Proximity Sensor Market
Sensors and Controls
Asia-Pacific Nano Radiation Sensors Market