
 Europe Machine Control System Market | 2026-2036
Europe Machine Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Machine Control System Market Foresight
Aftermarket service revenue for precision guidance retrofits is reconfiguring profit pools away from new equipment sales across European construction fleets. Trimble Inc leverages its dealer network density to capture recurring calibration and software update contracts. Hexagon AB anchors its position through deep integration of Leica Geosystems AG sensor hardware with its own software platforms. Topcon Corporation competes aggressively on total cost of ownership for mid-tier contractors in Southern Europe.
Europe machine control systems encompass hardware-software assemblies that integrate GNSS receivers, inertial measurement units, and hydraulic valve controllers to automate blade, bucket, and boom positioning within sub-centimeter tolerances, primarily serving earthmoving, paving, and agricultural tillage operations where manual grade control proves uneconomical at scale. CNC controllers currently occupy the largest product-type revenue pool due to entrenched metalworking automation across German and Italian manufacturing bases, while cloud-based installation architectures represent the fastest-expanding segment as fleet operators prioritize remote diagnostics and over-the-air parameter updates over capital-intensive on-premise server deployments. EtherCAT technology leads real-time communication protocols in new European installations given its deterministic cycle times and TÜV-certified functional safety profiles.
CE marking under the EU Machinery Directive and compliance with ECHA REACH substance restrictions shape hardware material selection and software safety validation requirements for all suppliers accessing European construction and agriculture channels. The EU AI Act's risk-classification framework for autonomous machine functions will impose additional conformity assessment burdens on manufacturers deploying self-learning grade-correction algorithms. Stakeholders must monitor how national transpositions of the F-Gas Regulation affect sensor cooling technologies and whether Germany's KBA type-approval expansions into automated earthmoving create precedent for cross-border equipment certification reciprocity.
Market Dynamics
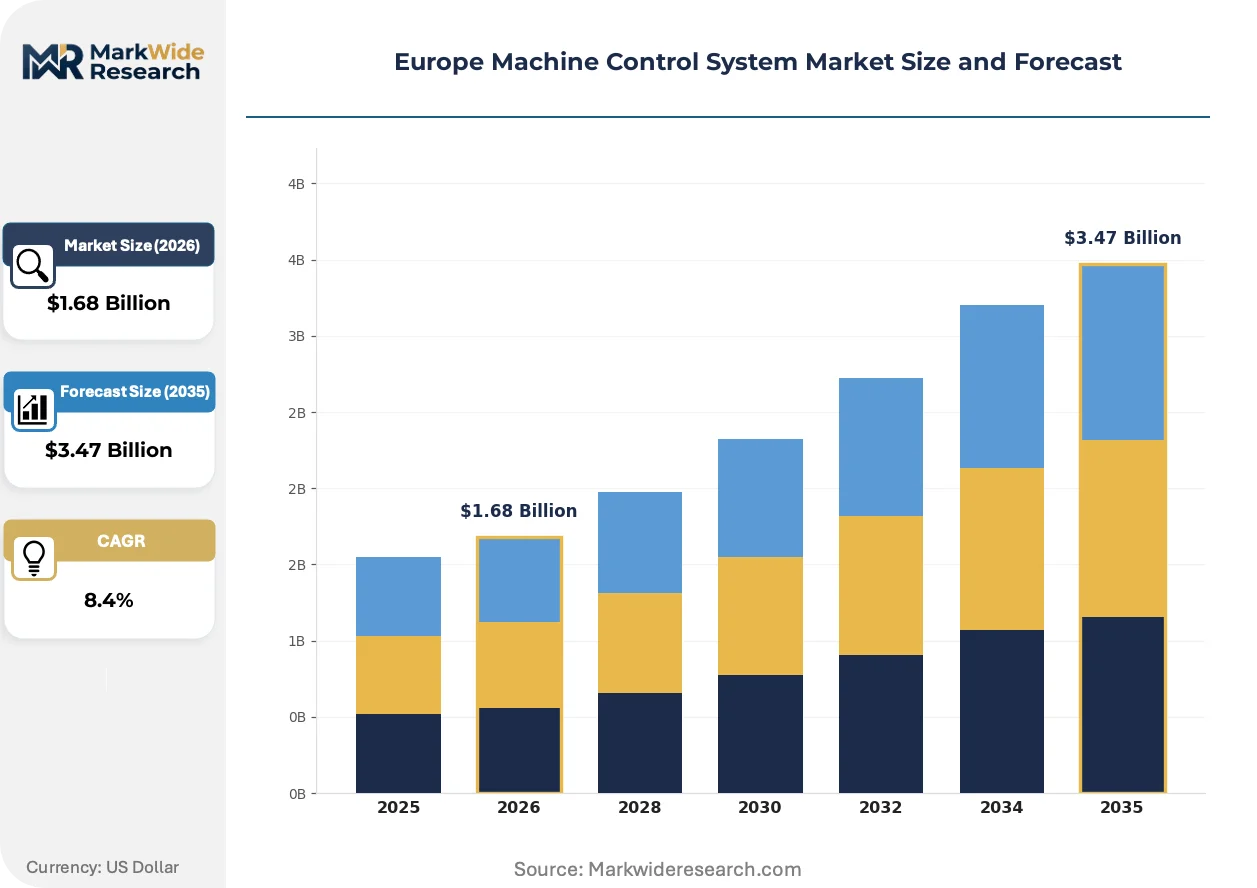
The EU Green Deal's emissions-reduction mandates for off-road machinery are restructuring capital allocation across European construction fleets, shifting procurement priority toward precision control retrofits that optimize fuel consumption and reduce rework.
Growth Catalysts
- EU Green Deal mandates:Binding emissions caps for off-road machinery under Stage V regulations are forcing fleet operators toward GPS-guided systems that minimize idle time and fuel burn during earthmoving operations.
- German civil engineering:Federal infrastructure rehabilitation programs are specifying machine control systems as technical requirements in public tender documents for highway and rail projects.
- Cloud-based architectures:Over-the-air software updates and remote diagnostics are eliminating downtime for calibration, accelerating replacement of on-premise legacy installations.
Market Restraints
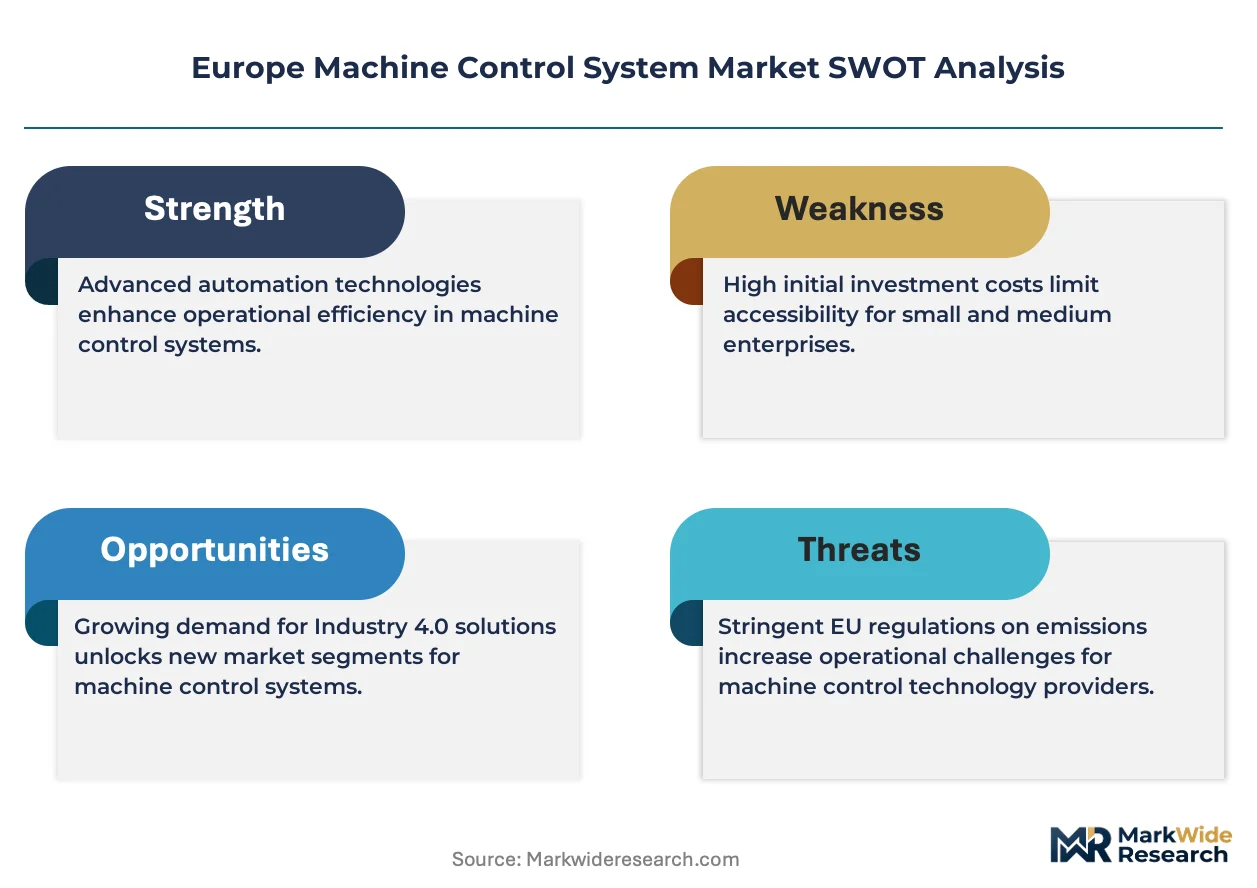
- Sensor hardware concentration:Dependence on specialized GNSS receiver and IMU suppliers creates vulnerability to semiconductor allocation constraints affecting lead times.
- REACH substance restrictions:ECHA limitations on specific cooling fluids and solder materials complicate thermal management design for precision sensors in extreme operating temperatures.
- Manual grade staking persistence:Small-scale earthmoving contractors in Southern Europe continue relying on traditional survey methods due to fragmented project sizes that dilute automation returns.
Strategic Opportunities
- French infrastructure rehabilitation:The national rail and waterway modernization program represents concentrated demand for 3D machine control on constrained urban worksites.
- EtherCAT-TÜV integration:Convergence of deterministic real-time communication with certified functional safety profiles opens automated earthmoving in tunneling and mining applications.
- EU AI Act compliance services:Risk-classification requirements for self-learning grade-correction algorithms create recurring revenue streams for conformity assessment and algorithm validation.
Industry Challenges
- GNSS-IMU calibration expertise:Scarce technician capacity for integrating inertial measurement units with satellite positioning systems delays deployment timelines for mid-tier contractors.
- CE marking complexity:Multi-country notified body assessments under the EU Machinery Directive extend time-to-revenue for new product introductions by six to twelve months.
- Hydraulic valve controller integration:Legacy equipment OEMs maintain proprietary communication protocols that fragment retrofit compatibility and inflate engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Machine Control System Market |
| Market Size in 2026 | $1.68 Billion |
| Market Size in 2035 | $3.47 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLC, CNC, DCS, SCADA Technology: EtherCAT, CANopen, Modbus, Profibus End User: Manufacturing, Construction, Agriculture, Mining Installation: On-premise, Embedded, Cloud-based, Hybrid |
| Companies Covered | Trimble Inc, Hexagon AB, Topcon Corporation, MOBA Mobile Automation AG, Hemisphere GNSS Inc, Leica Geosystems AG, Andritz AG, Komatsu Ltd, Schneider Electric SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Machine Control System Market Shifts & Advancements
Cloud-native architectures are displacing on-premise server deployments across European fleet operations, compressing the hardware-software boundary and redefining how precision guidance capabilities are delivered and monetized.
Digital twin platforms are virtualizing earthworks simulation and pre-construction validation, allowing contractors to model cut-fill sequences before mobilizing equipment. German and Scandinavian civil engineering firms are adopting these tools fastest, using them to compress project risk windows and reduce site-staffing levels. This virtualization is collapsing the traditional separation between design engineering and field execution.
The EU AI Act's risk-classification framework is imposing new conformity assessment burdens on manufacturers deploying autonomous grade-correction algorithms. Self-learning control systems must now demonstrate traceability and human oversight mechanisms to achieve CE marking under amended Machinery Directive interpretations. German KBA type-approval expansions into automated earthmoving are creating precedent that other national regulators are monitoring for cross-border reciprocity.
Fleet operators are unbundling after-sales service contracts from hardware procurement, purchasing calibration and software update subscriptions separately from initial system installation. This behavioral shift is visible most acutely in German construction markets where total cost of ownership modeling has matured. Equipment dealers are responding by restructuring compensation structures around recurring service attach rates rather than upfront margin on hardware sales.
Europe Machine Control System Market Segmentation
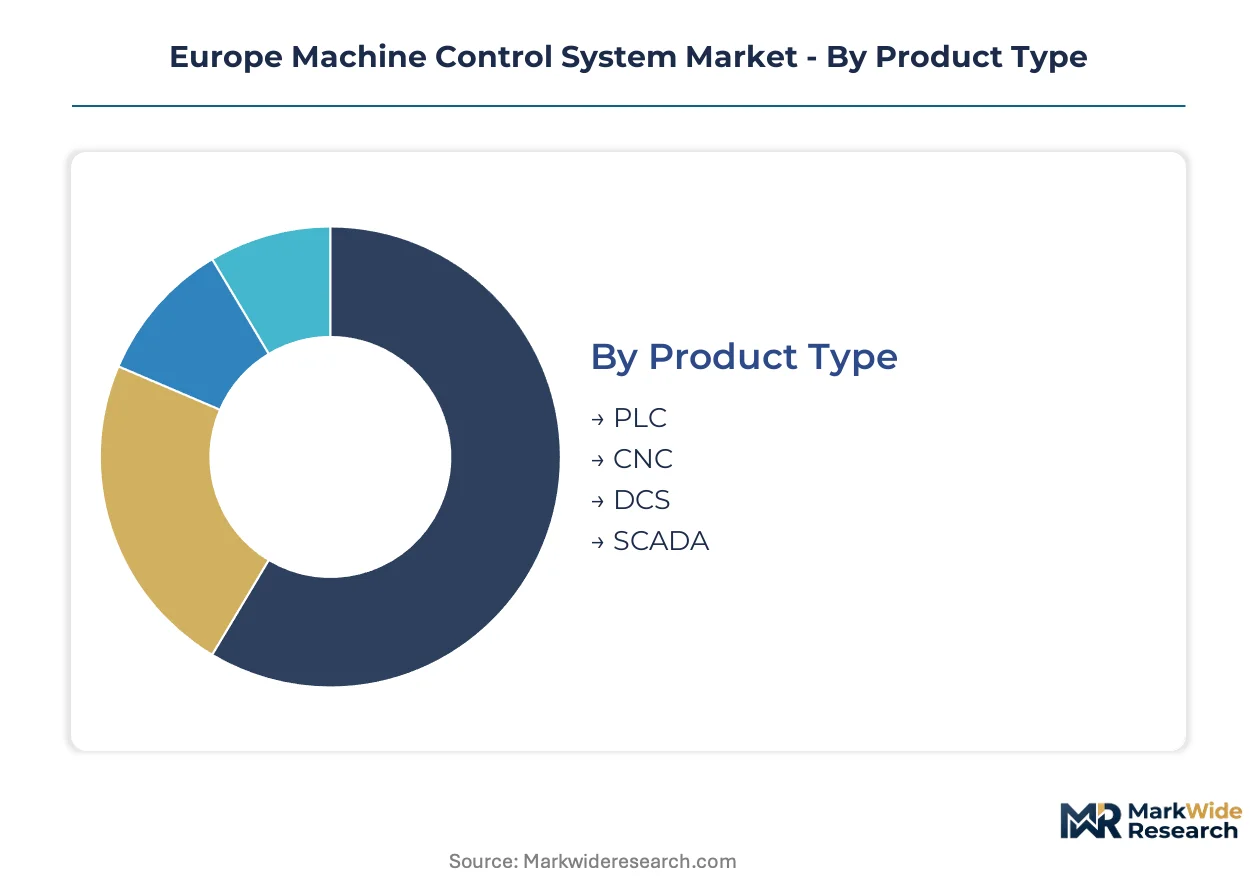
Machine control system segmentation in Europe reflects divergent automation maturity across industrial verticals. Procurement patterns split between precision earthmoving applications demanding sub-centimeter GNSS guidance and metalworking operations prioritizing deterministic motion control.
Product Type:
Industrial automation architectures span programmable logic arrays through distributed supervisory networks, each occupying distinct positions in the control hierarchy.
- CNC:Computer numerical control systems dominate metalworking automation across German and Italian manufacturing bases with multi-axis interpolation capabilities for precision machining centers. German automotive component suppliers and Italian tooling manufacturers anchor demand concentration, though capital intensity limits penetration among smaller fabrication shops.
- PLC:Programmable logic controllers provide modular I/O expansion for discrete manufacturing and material handling operations. French packaging machinery OEMs and Spanish food processing equipment builders specify these systems for flexible production line reconfiguration under EU Machinery Directive compliance requirements.
- DCS:Distributed control systems manage continuous process variables across chemical and pharmaceutical batch operations.
- SCADA:Supervisory control platforms aggregate field-level data for centralized monitoring of geographically dispersed assets.
Established volume favors CNC; emerging adoption favors PLC.
Technology:
Real-time communication protocols differentiate on determinism, safety certification, and integration complexity.
- EtherCAT:Ethernet-based fieldbus technology achieves sub-millisecond cycle times with TÜV-certified functional safety profiles. German tunneling contractors and Scandinavian mining operators specify EtherCAT for automated earthmoving where synchronized hydraulic valve control prevents collision hazards in confined underground environments.
- Profibus:Legacy fieldbus maintains installed base across Central European process industries with proven interoperability for brownfield retrofits.
- CANopen:Controller area network protocol serves mobile machinery with robust electromagnetic immunity for outdoor construction applications.
- Modbus:Simplified serial communication persists in cost-sensitive agricultural equipment where basic telemetry suffices.
Legacy dominance rests with Profibus; steepest expansion trajectory belongs to EtherCAT.
End User:
Vertical application requirements range from repetitive manufacturing precision to adaptive terrain following in unstructured environments.
- Construction:Earthmoving and paving operations deploy 3D machine control for automated grade and slope management. German federal highway rehabilitation programs and French rail modernization projects specify these systems as technical tender requirements, while emissions-reduction mandates under EU Green Deal accelerate GPS-guided retrofit adoption.
- Manufacturing:Discrete and process automation demands synchronized multi-axis motion control with traceable quality documentation.
- Agriculture:Precision tillage and planting operations utilize GNSS guidance for input optimization and field boundary mapping.
- Mining:Surface and underground extraction operations require ruggedized positioning systems with explosion protection certification.
Procurement maturity concentrates in Construction; technology refresh cycles favor Manufacturing.
Installation:
Deployment architectures reflect capital availability, connectivity infrastructure, and cybersecurity risk tolerance.
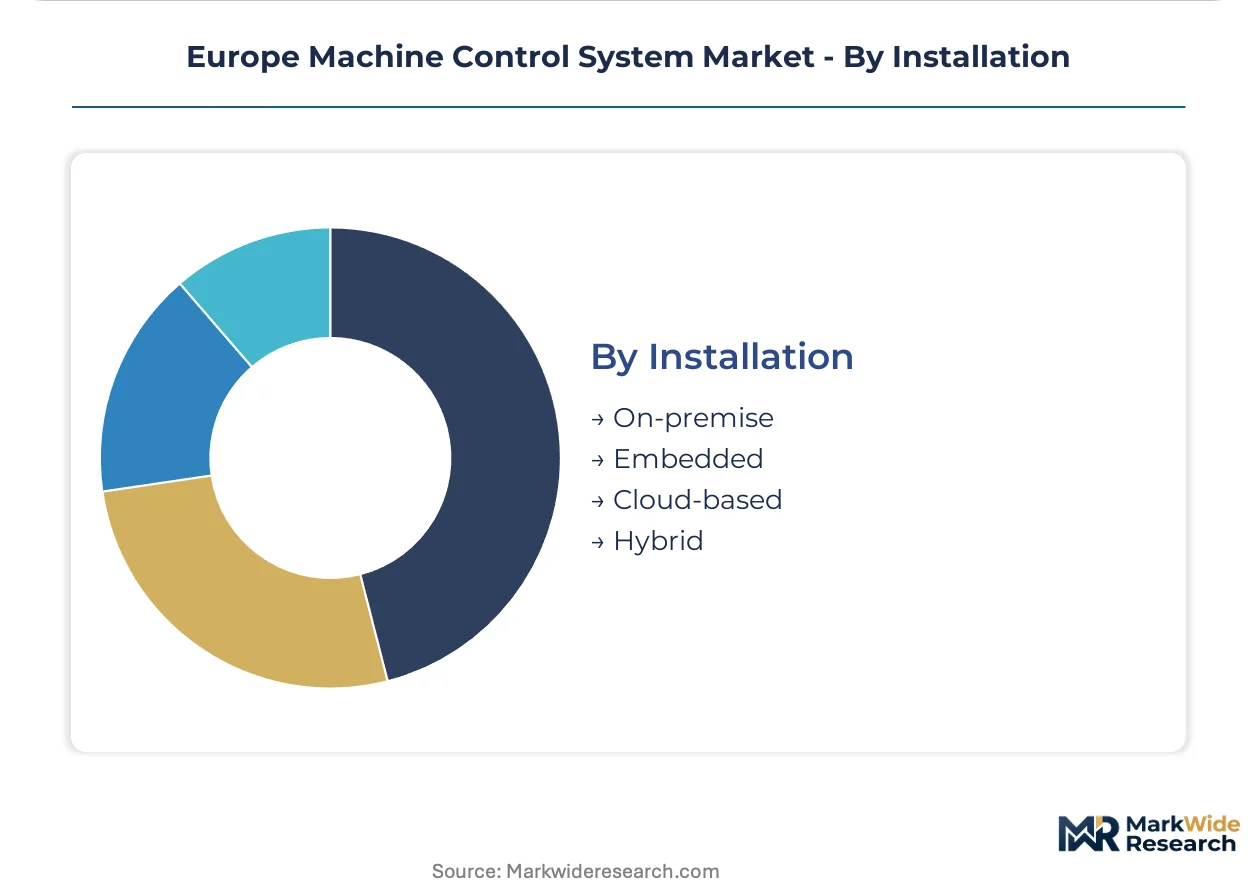
- Cloud-based:Over-the-air software distribution and remote diagnostics eliminate calibration downtime for distributed fleets. German construction fleet operators prioritize subscription-based update models that shift capital expenditure to operational budgets, with cellular connectivity expanding coverage across rural worksites previously dependent on manual service visits.
- On-premise:Local server installations persist where data sovereignty requirements or intermittent connectivity preclude external hosting.
- Embedded:Integrated controller-hardware combinations serve standalone machinery with minimal networking requirements.
- Hybrid:Edge-cloud partitioning balances real-time control latency with centralized analytics aggregation.
Current installed base favors On-premise; strategic investment flows toward Cloud-based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German contractors deploy machine control systems primarily for emissions compliance and fuel optimization, while French operators emphasize 3D grade management on constrained urban infrastructure sites. Scandinavian fleets lead cloud-based adoption for remote worksite management. Southern European contractors still favor manual staking on fragmented projects.
Germany
Federal highway and rail rehabilitation programs specify GPS-guided earthmoving equipment as mandatory tender requirements. The KBA type-approval expansion into automated earthmoving machinery creates precedent for cross-border certification reciprocity within the EU. Civil engineering clusters in Bavaria and North Rhine-Westphalia are retrofitting diesel fleets with precision control systems to meet Stage V emissions caps.
France
National rail and waterway modernization drives concentrated demand for 3D machine control in tunneling and urban worksites. The EU Machinery Directive's CE marking requirements shape procurement specifications for public infrastructure contracts. Construction firms in Île-de-France and Auvergne-Rhône-Alpes are deploying automated grade-correction systems to reduce rework on constrained Parisian rail corridors.
United Kingdom
HS2 rail construction and nuclear decommissioning programs require sub-centimeter positioning accuracy for earthmoving operations. The UK's post-Brexit regulatory alignment with EU machinery safety standards maintains CE marking continuity for continental suppliers. Contractors in the Midlands and Southeast England are unbundling after-sales service contracts from hardware procurement.
Italy
Metalworking automation in precision machining centers sustains CNC controller demand across automotive component suppliers. ECHA REACH substance restrictions complicate thermal management design for sensor hardware in extreme operating temperatures. Manufacturing clusters in Lombardy and Piedmont anchor the installed base of deterministic motion control systems.
Sweden
Mining operators specify EtherCAT-enabled machine control for automated extraction in confined underground environments. The EU Green Deal's emissions mandates accelerate GPS-guided retrofit adoption across surface mining fleets. Engineering contractors in Kiruna and the Bergslagen mining region are integrating TÜV-certified functional safety profiles into hydraulic valve control systems.
Europe Machine Control System Market Competitive Landscape
Capability concentration sits with sensor-hardware specialists; scale advantage sits with diversified industrial automation conglomerates. The vendor base stratifies across three tiers: precision positioning technology developers, construction equipment OEMs with captive control systems, and industrial automation platforms extending into earthmoving applications. Dominant competitive moves include strategic partnerships between GNSS receiver manufacturers and hydraulic valve controller suppliers, plus portfolio diversification into cloud-based software subscriptions.
Among precision positioning specialists, Trimble Inc exemplifies the integrated hardware-software archetype through its dealer network density for recurring service contracts. Hexagon AB anchors the sensor-platform tier through its Leica Geosystems AG heritage in measurement instrumentation. Topcon Corporation occupies a position competing on total cost of ownership metrics for mid-tier contractor segments.
| Leading Market Players |
|---|
| Trimble Inc |
| Hexagon AB |
| Topcon Corporation |
| MOBA Mobile Automation AG |
| Hemisphere GNSS Inc |
| Leica Geosystems AG |
| Andritz AG |
| Komatsu Ltd |
| Schneider Electric SE |
| Others |
Supply & Pricing Matrix
Bavarian precision engineering clusters anchor European machine control system manufacturing capacity, with their concentration of sensor hardware production conferring pricing leverage over downstream system integrators. This geographic supply dominance interacts with procurement patterns to create tiered pricing structures that separate premium-certified installations from economy retrofits.
Pricing Analysis
Long-term service contracts dominate the European machine control market, with German fleet operators favoring multi-year calibration and software update subscriptions over transactional hardware purchases. Price differentiation rests on CE marking tier and after-sales bundling intensity, with TÜV-certified functional safety profiles commanding substantial premiums. Cost compression in mid-tier segments is intensifying because Topcon Corporation and similar competitors are aggressively undercutting on total cost of ownership metrics. Small-scale earthmoving contractors in Southern Europe exhibit the highest price sensitivity, while German civil engineering consortiums prioritize compliance-grade specifications over unit economics.
Supply Chain Analysis
Export control regimes restricting dual-use GNSS receiver technology limit component flows from US and select Asian suppliers into European assembly operations. Manufacturing concentration centers on Germany, Sweden, and Japan for precision sensor hardware, with Taiwanese semiconductor foundries feeding critical GNSS chipset demand. Raw material dependencies span rare earth magnets for IMU stabilization, specialized cooling fluids constrained by REACH substance restrictions, and high-grade aluminum enclosures for electromagnetic shielding. Single-source vulnerability around Leica Geosystems AG and Trimble Inc receiver modules creates supply continuity exposure. Distribution runs through authorized dealer networks with captive calibration service capabilities rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European machine control market sits at a platform-economics inflection where cloud-native architectures are collapsing the traditional separation between hardware procurement and software service delivery. Interoperability convergence around EtherCAT-TÜV safety profiles is creating winner-take-most dynamics for ecosystem orchestrators.
For Market Incumbents: Pre-empt margin erosion in mid-tier segments by accelerating backward integration into GNSS receiver manufacturing and securing exclusive distribution agreements with German civil engineering procurement consortia. The threat of cloud-native entrants unbundling service revenue from hardware sales demands immediate investment in subscription platform infrastructure. Vertical integration into hydraulic valve controller production represents the critical defensive lever against proprietary OEM protocol fragmentation. For New Entrants and Emerging Players: Southern European earthmoving contractors present the most penetrable white-space opportunity, with their reliance on manual grade staking creating latent demand for affordable precision guidance retrofits. French rail infrastructure rehabilitation programs offer concentrated project-based entry points for 3D machine control specialists. A partnership-first go-to-market approach with established hydraulic system integrators circumvents the capital intensity of direct dealer network construction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor-hardware specialists with captive software platforms over pure-play automation conglomerates. The five-to-ten year viability window rewards acquisition targets combining Leica Geosystems AG-grade measurement heritage with cloud-native service architectures. Monitor Germany's KBA type-approval reciprocity negotiations as the critical inflection signal for cross-border certification harmonization and consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | EtherCAT-TÜV convergence enables automated earthmoving in confined German tunneling environments. |
| Backward Integration | In-house GNSS receiver production insulates margin from semiconductor allocation volatility. |
| Geographic Expansion | French rail modernization contracts concentrate demand for urban 3D grade management systems. |
| Strategic Partnership | Collaboration with hydraulic valve OEMs resolves proprietary protocol compatibility barriers. |
| Product Launch | Cloud-native architectures displace on-premise installations across Scandinavian remote worksites. |
Research Methodology
A standing panel of earthmoving fleet managers, precision agriculture operators, civil engineering procurement directors, and aftermarket service technicians provided ongoing calibration against operating reality. Primary interview data combined with secondary validation from EU Machinery Directive compliance databases, ECHA REACH substance restriction filings, and German federal infrastructure tender documentation. Bottom-up equipment shipment analysis and top-down construction sector capital expenditure modeling were triangulated to derive market sizing.
Scenario-bracketing around EU Green Deal implementation pace and Stage V emissions enforcement intensity bounded the projection horizon. Segmentation dimensions spanned product type, real-time communication protocol, end-use vertical, and installation architecture. CAGRs were derived from equipment replacement cycle analysis and retrofit penetration modeling. Industry-specific inputs included KBA type-approval timeline assumptions and ECHA substance restriction phase-out schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native software entrants or Chinese GNSS hardware specialists would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Sensors Market
Sensors and Controls
North America Wireless Sensors Market
Sensors and Controls
Europe Bulk Acoustic Wave Sensors Market
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Sound Sensor Market
Sensors and Controls
Global Sensors and Actuators Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
Fiber Optic Pressure Sensors Market
Sensors and Controls
Speed Sensor Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
Europe Pressure Sensors Market
Sensors and Controls
Global Mid-And-High-Level Precision GPS Receiver Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
Automotive MEMS Market