
 Oxygen Sensor Market | 2026-2036
Oxygen Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Sensor Market Analytics
Zirconia ceramics is repositioning product economics as manufacturers substitute platinum-rich electrode designs with stabilized yttria-zirconia architectures to cut precious metal loadings. Robert Bosch GmbH leverages captive ceramic production in Germany to sustain cost leadership across wideband sensor lines. Denso Corporation anchors its position through R&D intensity in miniaturized planar element geometries. NGK Spark Plug Co. Ltd dominates zirconia powder sourcing and competes aggressively on thermal shock resistance specifications.
An oxygen sensor measures partial pressure of oxygen in gases or liquids, typically employing a thimble-shaped or planar zirconia element coated with porous platinum electrodes and heated to temperatures exceeding 300°C to generate a voltage signal proportional to the oxygen concentration differential. Its primary industrial purpose spans closed-loop engine management, catalytic converter efficiency monitoring, and combustion optimization across powertrain and stationary source applications. Wideband sensors lead value generation given their continuous lambda measurement capability versus binary narrowband alternatives, while electrochemical technology occupies the mature cost-optimized tier and optical sensing represents the emerging high-precision segment for medical and aerospace deployments. Automotive OEMs channel the dominant demand flow, though industrial applications in steel and chemical processing are gaining share as stack monitoring requirements proliferate.
EPA tailpipe standards and the EU Green Deal's F-Gas Regulation shape product roadmaps by mandating faster light-off times and lower cold-start emissions, directly driving heater circuit power density improvements. China's MIIT enforces GB 18352.6 compliance timelines that force domestic automakers toward wideband architectures ahead of aftermarket refresh cycles. Health Canada and Japan's METI maintain aligned but distinct test protocols that fragment certification burdens for cross-border suppliers. Stakeholders must monitor divergence between California Air Resources Board waivers and federal EPA harmonization efforts to anticipate sensor specification fragmentation or consolidation.
Market Dynamics
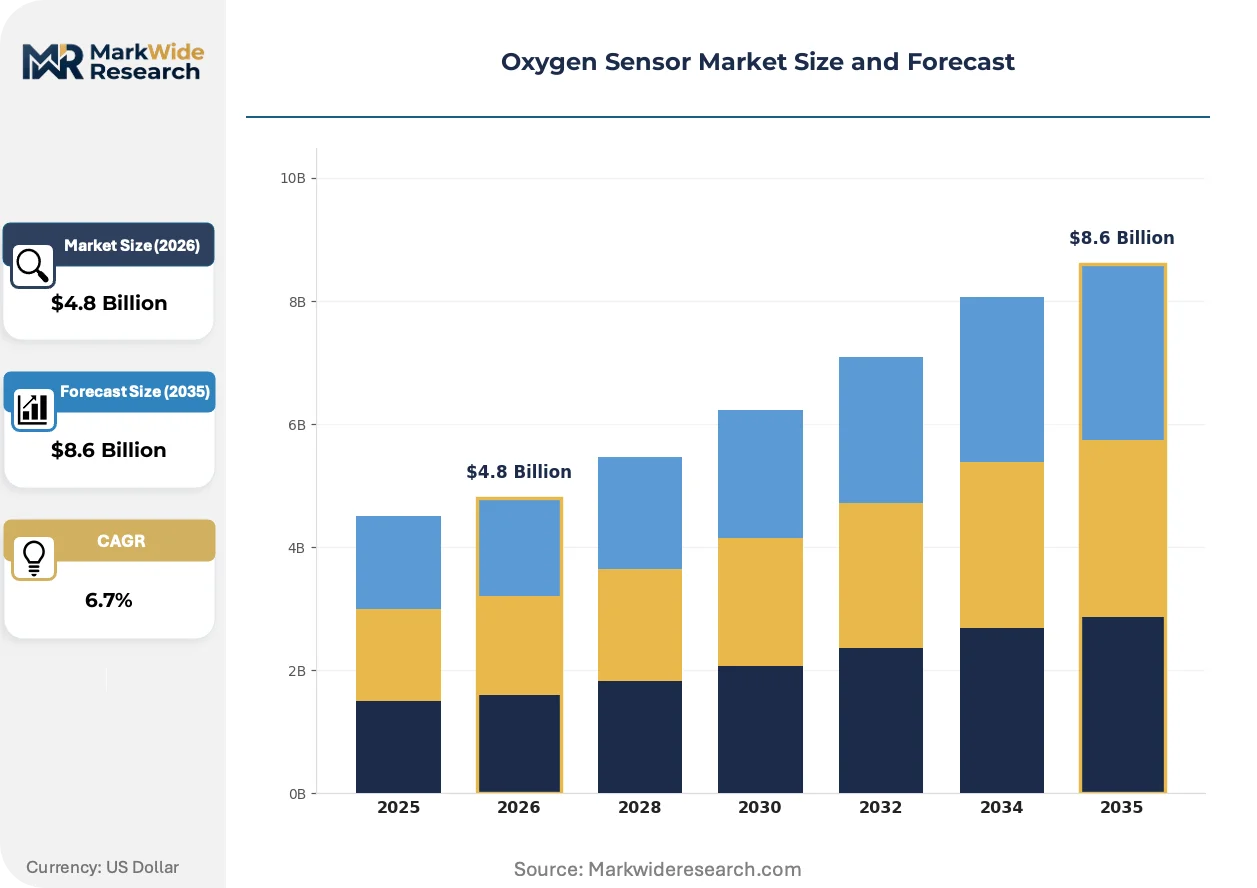
Zirconia ceramic architecture substitution is compressing precious metal loadings while EPA and Euro 7 NOx thresholds force faster light-off specifications, reshaping heater circuit power density requirements across automotive OEM supply contracts.
Growth Catalysts
- EPA Tier 3 and Euro 7 NOx mandates:Tightening tailpipe thresholds force closed-loop wideband sensor integration into gasoline and diesel powertrains, expanding unit volumes per vehicle platform.
- Steel and chemical stack monitoring:Industrial combustion optimization requirements proliferate across stationary source applications, creating secondary demand channels beyond automotive.
- Yttria-stabilized zirconia (YSZ) electrode architectures:Ceramic material substitution reduces platinum group metal dependency, lowering bill-of-material costs and enabling price elasticity in aftermarket replacement cycles.
Market Restraints
- Palladium and rhodium price volatility:Residual precious metal content in heater and electrode assemblies exposes manufacturers to London Metal Exchange commodity swings, compressing margin predictability.
- Zirconia powder supply concentration:High-purity YSZ precursor production clusters in East Asian ceramic processing corridors, creating single-source vulnerability for Western sensor fabricators.
- Optical sensing substitution threat:Tunable diode laser absorption spectroscopy advances in medical and aerospace oxygen measurement applications threaten electrochemical technology's precision-tier position.
Strategic Opportunities
- India BS-VI Phase II compliance timeline:Domestic automaker migration from narrowband to wideband architectures ahead of aftermarket saturation creates first-mover positioning for component suppliers.
- Marine and locomotive off-road applications:IMO Tier III and EPA Locomotive & Marine standards extend addressable demand beyond light-duty passenger vehicle segments.
- Integrated heater-sensor module convergence:Combining planar sensing elements with thick-film heater circuits reduces wiring harness complexity and assembly labor for OEMs.
Industry Challenges
- Calibration technician scarcity:Wideband lambda sensor diagnostic and recalibration requires specialized training that outpaces vocational program output in mature automotive service markets.
- GB 18352.6 certification timeline compression:China's MIIT enforcement windows force simultaneous engineering validation across multiple vehicle platforms, straining OEM sensor qualification bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Sensor Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wideband Sensors, Narrowband Sensors, Dual Sensors, Universal Sensors End User: Automotive OEMs, Aftermarket Providers, Industrial Applications, Marine Sector Technology: Electrochemical, Zirconia, Infrared, Optical Application: Emission Control, Engine Management, Exhaust Systems, Air-Fuel Ratio |
| Companies Covered | Robert Bosch GmbH, Honeywell International Inc, ABB, Denso Corporation, NGK Spark Plug Co. Ltd, Niterra Co., Ltd., Yokogawa Electric Corporation, Continental AG, Figaro Engineering Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Sensor Market Evolving Landscape
Planar wideband architectures are compressing thimble-form factor dominance as thermal management and signal precision requirements intensify across powertrain electrification transitions.
Planar zirconia sensing elements with integrated thick-film heater circuits enable sub-10-second light-off performance required by cold-start emission budgets. Tier 1 suppliers are adopting these geometries for gasoline direct-injection and mild-hybrid platforms where combustion variability demands continuous lambda feedback. This structural shift is overtaking legacy thimble designs in premium vehicle segments and propagating downward through mass-market nameplates.
The EU F-Gas Regulation and EPA Greenhouse Gas Emission Standards jointly mandate faster catalyst readiness windows, directly specifying heater power density thresholds in type-approval protocols. Sensor manufacturers must validate ceramic thermal shock resistance across expanded temperature cycling profiles. European OEMs have responded by consolidating supplier qualification lists to those with captive ceramic production and in-house heater patterning capabilities.
Fleet operators and independent repair channels are compressing replacement sensor procurement cycles through direct e-commerce sourcing, bypassing traditional warehouse distributor tiers. This channel disintermediation is most pronounced in North American and Western European aftermarket segments where standardized OBD-II diagnostic protocols enable self-directed part matching. Sensor suppliers are responding with SKU rationalization and packaging formats optimized for drop-ship fulfillment rather than bulk pallet distribution.
Oxygen Sensor Market Segmentation
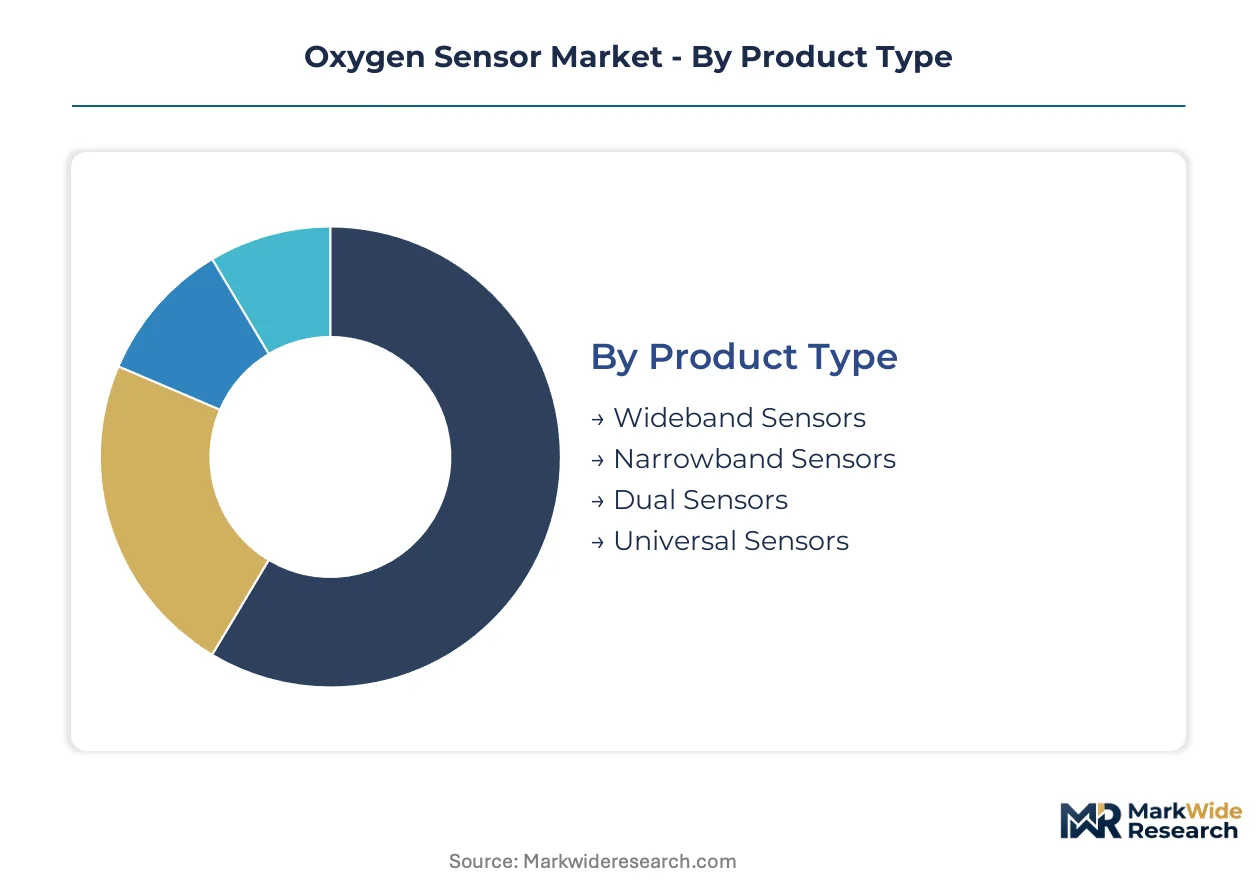
Oxygen sensor procurement patterns diverge sharply across product architectures and end-use channels. Replacement cycle timing, certification requirements, and technology migration paths create distinct commercial pockets within each segment category.
Product Type:
Upgrade cycles from narrowband to wideband architectures are compressing replacement intervals as EPA and Euro 7 standards force faster light-off performance across vehicle platforms.
- Wideband Sensors:These sensors employ planar zirconia elements with integrated thick-film heaters to deliver continuous lambda measurement across lean-to-rich combustion ranges. Automotive OEMs in Germany and the United States are mandating wideband integration for gasoline direct-injection platforms to meet cold-start emission budgets.
- Narrowband Sensors:Thimble-shaped zirconia designs generate binary rich/lean voltage signals at lower unit cost. Aftermarket demand concentrates in legacy vehicle parcs across India and Southeast Asia where emission enforcement remains less stringent than Euro 7-equivalent standards.
- Dual Sensors:Paired upstream/downstream configurations monitor catalytic converter efficiency through differential oxygen measurement. OEM fitment dominates as integrated modules reduce wiring harness complexity.
- Universal Sensors:Generic replacement units with configurable connector adapters serve price-sensitive aftermarket channels. E-commerce direct sourcing is compressing traditional distributor margins in North American repair markets.
Volume placements concentrate in narrowband sensors for aftermarket refresh; the faster expansion belongs to wideband architectures.
End User:
Cost tier differentiation separates specification-intensive OEM contracts from price-elastic aftermarket procurement.
- Automotive OEMs:Tier 1 suppliers qualify planar wideband modules through multi-year platform contracts with captive ceramic production requirements. EPA Tier 3 and Euro 7 type-approval protocols mandate sub-10-second light-off validation.
- Aftermarket Providers:Independent repair channels and e-commerce platforms source universal and narrowband replacements based on OBD-II diagnostic compatibility. SKU rationalization is accelerating as drop-ship fulfillment replaces bulk distribution.
- Industrial Applications:Steel mills and chemical processing plants deploy zirconia-based stack monitors for combustion optimization. China's MIIT enforcement of GB standards is expanding stationary source monitoring requirements.
- Marine Sector:IMO Tier III compliance for vessel engines is extending sensor demand beyond automotive into commercial shipping and recreational boat powertrains.
Revenue concentration sits with automotive OEMs; industrial applications are climbing the fastest as stack monitoring proliferates.
Technology:
Material substitution patterns are reshaping competitive positioning across electrochemical maturity and optical emergence.
- Electrochemical:Galvanic cell designs with liquid electrolyte chambers occupy cost-optimized medical and safety equipment segments. Long replacement cycles in portable gas detectors sustain residual demand.
- Zirconia:Yttria-stabilized ceramic elements with porous platinum electrodes dominate automotive emission control. YSZ precursor supply concentrates in East Asian ceramic corridors, creating sourcing vulnerability for Western fabricators.
- Infrared:NDIR absorption spectroscopy serves non-dispersive measurement in HVAC and indoor air quality applications. Calibration stability advantages suit long-deployment building automation systems.
- Optical:Tunable diode laser absorption spectroscopy enables ppb-precision measurement for aerospace life support and medical anesthesia monitoring. Technology transfer from telecom laser manufacturing is compressing unit costs.
Installed base dominance rests with zirconia; optical architectures show steepest expansion trajectory in precision-tier medical and aerospace deployments.
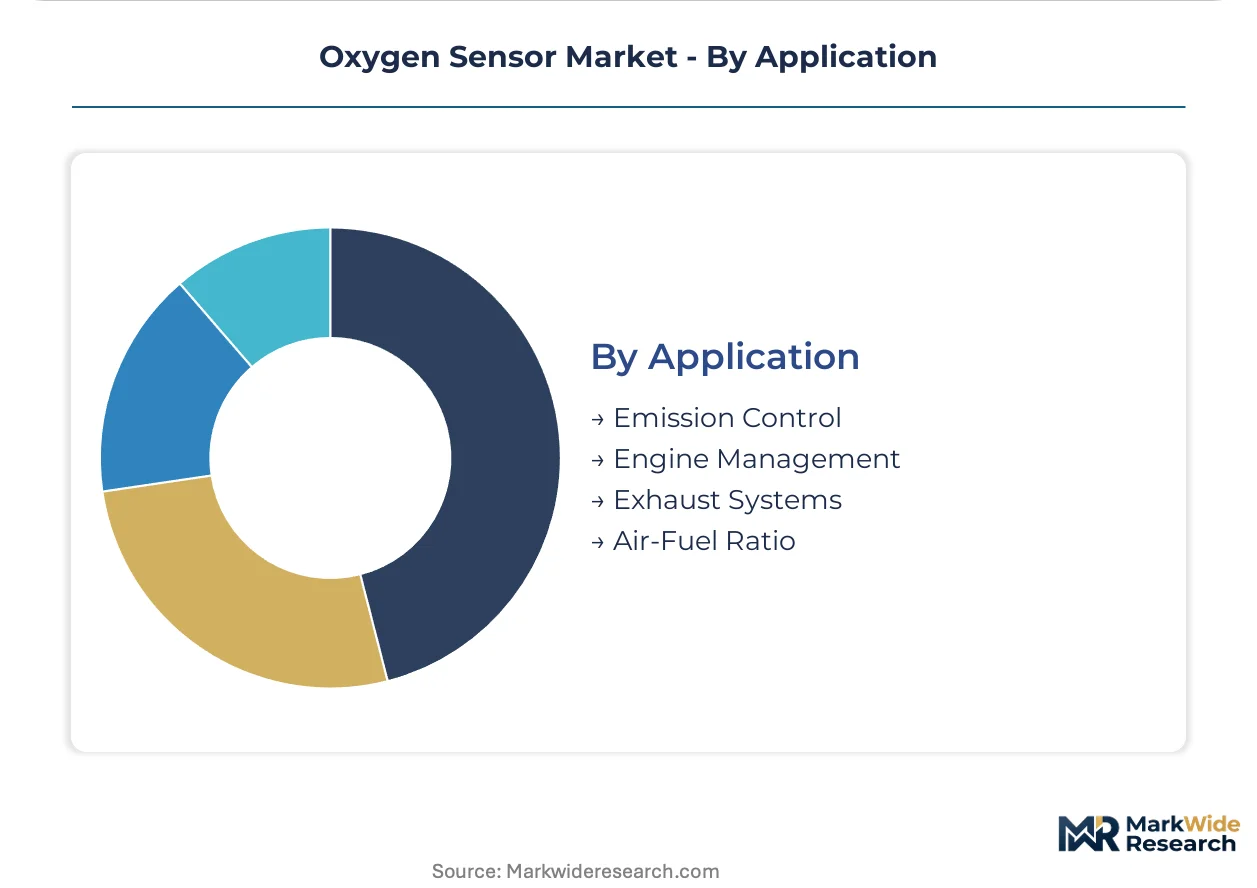
Application:
Customer type stratification separates regulatory-mandated emission systems from performance-optimized engine management.
- Emission Control:Upstream and downstream sensor placement monitors catalytic converter efficiency for EPA and Euro 7 compliance. OEMs consolidate supplier lists to those with in-house heater patterning capabilities.
- Engine Management:Closed-loop fuel injection feedback optimizes combustion efficiency across variable load conditions. Wideband lambda control enables lean-burn strategies in mild-hybrid powertrains.
- Exhaust Systems:Integrated sensor-heater modules reduce thermal mass for faster light-off. Thick-film ceramic processing advances are compressing wiring harness complexity.
- Air-Fuel Ratio:Stoichiometric feedback maintains 14.7:1 gasoline combustion for three-way catalyst efficiency. Racing and performance aftermarket segments demand wider measurement ranges than OEM specifications.
Deployment scale favors emission control integration; engine management applications are gaining share fastest through powertrain electrification transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supplier parks and China's MIIT-designated industrial zones concentrate zirconia ceramic processing capacity. EPA enforcement corridors in Michigan and California anchor North American sensor qualification activity. Japan's METI-funded technology clusters sustain precision heater circuit manufacturing.
United States
EPA Tier 3 tailpipe standards and CARB waiver programs drive wideband sensor integration across Detroit Three powertrain platforms. The agency's light-off time specifications compress supplier validation cycles. Michigan's automotive corridor hosts captive ceramic production facilities serving direct-injection gasoline programs.
Germany
Euro 7 NOx thresholds and the EU Green Deal's F-Gas Regulation mandate sub-10-second heater readiness for catalytic converter monitoring. Stuttgart and Munich supplier parks concentrate planar element manufacturing for premium OEM platforms. Bosch's Reutlingen ceramic operations anchor Western European zirconia supply security.
China
GB 18352.6 compliance timelines force domestic automakers toward wideband architectures ahead of aftermarket saturation. MIIT enforcement windows strain simultaneous engineering validation across multiple vehicle platforms. Yangtze River Delta ceramic processing corridors dominate high-purity YSZ precursor production.
Japan
METI-aligned test protocols and JIS standards maintain distinct certification requirements from EPA harmonization efforts. Denso's Aichi Prefecture R&D facilities anchor miniaturized planar element development. Kansai industrial clusters specialize in thermal shock resistance specifications for hybrid powertrain applications.
India
BS-VI Phase II compliance deadlines compress narrowband-to-wideband migration timelines for domestic automakers. The Ministry of Road Transport's enforcement creates first-mover positioning for component suppliers. Tamil Nadu and Maharashtra automotive belts concentrate sensor assembly operations for export-oriented OEM programs.
Oxygen Sensor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated OEM supply lists contrasting fragmented aftermarket channels. Tier 1 suppliers qualify through multi-year platform contracts requiring captive ceramic production, while universal sensor vendors compete on OBD-II diagnostic compatibility. Three archetypes dominate: integrated automotive suppliers with in-house heater patterning, zirconia powder specialists controlling upstream material flows, and precision electronics fabricators serving medical and aerospace tiers. Capacity expansion and SKU rationalization represent the dominant competitive moves as drop-ship fulfillment replaces bulk distribution.
Within the integrated automotive tier, Robert Bosch GmbH and Denso Corporation exemplify scale-driven positions anchored by captive ceramic production. NGK Spark Plug Co. Ltd occupies the materials-specialist archetype through zirconia powder sourcing dominance. Among precision electronics fabricators, Yokogawa Electric Corporation and Figaro Engineering Inc represent technology-intensive positioning for non-automotive measurement applications.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Honeywell International Inc |
| ABB |
| Denso Corporation |
| NGK Spark Plug Co. Ltd |
| Niterra Co., Ltd. |
| Yokogawa Electric Corporation |
| Continental AG |
| Figaro Engineering Inc |
| Others |
Value Network & Pricing Analysis
Planar wideband element manufacturing is compressing legacy thimble-form production economics while concentrating heater circuit fabrication among captive ceramic producers in Germany and Japan. This process transition simultaneously elevates qualification barriers for new entrants and shifts pricing power toward OEMs with multi-year platform contracts.
Pricing Analysis
Volume placements concentrate in narrowband aftermarket replacements while margin capture sits with wideband OEM modules. Pricing stratifies across premium wideband architectures with integrated thick-film heaters, standard planar elements for mass-market gasoline platforms, and economy narrowband thimble designs for legacy vehicle parcs. Cost compression in economy tiers is intensifying because e-commerce direct sourcing bypasses traditional distributor markups. Aftermarket repair channels exhibit highest price sensitivity; Tier 1 OEM contracts show lowest sensitivity given regulatory compliance mandates.
Supply Chain Analysis
Freight cost differentials between East Asian YSZ precursor corridors and Western sensor assembly plants are widening landed cost gaps for European and North American fabricators. High-purity yttria-stabilized zirconia powder production clusters in China's Yangtze River Delta and Japan's Kansai industrial belt, while planar element manufacturing anchors in Germany's Stuttgart supplier parks. The supply chain draws from platinum group metals for electrode coatings, ceramic substrates for thermal management, and thick-film heater pastes for light-off performance. Single-source vulnerability in YSZ precursor sourcing exposes Western manufacturers to export restriction risk. Distribution runs through Tier 1 automotive supplier contracts for OEM fitment and e-commerce drop-ship fulfillment for aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Planar wideband architectures are displacing thimble-form legacy designs across gasoline direct-injection and mild-hybrid platforms, compressing the window for narrowband technology refresh cycles.
For Market Incumbents: Lock in captive ceramic production capacity and in-house heater patterning capabilities to defend against optical sensing substitution in medical and aerospace precision tiers. Consolidate supplier qualification lists by acquiring YSZ precursor sourcing security in East Asian ceramic corridors. Prioritize R&D investment in thermal shock resistance specifications for hybrid powertrain thermal cycling profiles. For New Entrants and Emerging Players: Industrial stack monitoring operators in China's steel and chemical processing sectors represent underserved buyer archetypes with proliferating GB 18352.6 compliance requirements. Marine and locomotive off-road applications under IMO Tier III and EPA standards offer penetrable segments beyond saturated light-duty automotive. Pursue qualification partnerships with regional aftermarket distributors possessing OBD-II diagnostic platform relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated automotive suppliers seeking captive ceramic production and heater circuit capabilities. Long-term viability hinges on positioning within wideband architecture migration rather than narrowband aftermarket exposure. Watch for divergence between California Air Resources Board waiver programs and federal EPA harmonization efforts as inflection indicator for specification fragmentation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Production Capacity Expansion | Captive YSZ element manufacturing secures supply continuity against East Asian precursor concentration. |
| Heater-Sensor Module Integration | Combined planar elements with thick-film circuits reduce OEM wiring harness complexity and assembly labor. |
| Wideband Architecture Certification | EPA Tier 3 and Euro 7 sub-10-second light-off validation opens multi-year platform contract access. |
| Industrial Stack Monitoring Partnership | Steel mill and chemical plant combustion optimization extends addressable demand beyond automotive OEMs. |
| Aftermarket E-Commerce Channel Development | Drop-ship fulfillment optimization captures repair channel margin compression from distributor disintermediation. |
Research Methodology
Trade databases, automotive production registries, and regulatory filing repositories formed the secondary backbone of this study. Primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel managers, and ceramic processing technical directors informed demand-side validation. Bottom-up unit volume estimates across vehicle production platforms were cross-referenced with top-down market value assessments derived from supplier revenue disclosures and customs trade flows.
Bottom-up modeling of sensor content per vehicle by propulsion architecture and emission control configuration anchored volume projections. Top-down triangulation against automotive OEM procurement spend and aftermarket replacement cycle data validated value estimates. Segmentation dimensions included product architecture, end-user channel, sensing technology, and application function. CAGRs were derived from slope analysis of year-over-year platform penetration rates and regulatory compliance timeline impacts. Forecast inputs incorporated EPA and Euro 7 phase-in schedules, MIIT enforcement windows, and powertrain electrification transition curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to palladium and rhodium commodity volatility, optical sensing technology maturation, and divergence between regional emission standard harmonization efforts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Confocal Displacement Sensor Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
Phototransistor Market
Sensors and Controls
Europe Sensors Market
Sensors and Controls
Thermal Anemometer Market
Sensors and Controls
Asia-Pacific Bulk Acoustic Wave Sensors Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Wind Vane Sensor Market
Sensors and Controls
Global PH Sensor Market
Sensors and Controls
Wireless Sensor Tags Market
Sensors and Controls
Smart Temporal Thermometer Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Torque Transducer Market
Sensors and Controls
Latin America Wearable Sensors Market
Sensors and Controls
Infrared Sensors Market
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market