
 Force Sensor Market | 2026-2036
Force Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Force Sensor Market Intelligence
Precision-grade calibration tolerance is collapsing the gap between laboratory and factory-floor force measurement, forcing suppliers to unify metrology protocols. TE Connectivity leverages its electromechanical heritage to sustain dominance in aerospace load-cell supply. Honeywell International Inc anchors its position through backward integration into strain-gauge wafer fabrication. FUTEK Advanced Sensor Technology differentiates via ultra-miniature torque-and-force modules for robotic surgery.
A force sensor transduces mechanical load into quantifiable electrical output through resistive, piezoelectric, or capacitive mechanisms, typically resolving micro-newton to kilo-newton ranges with linearity errors below 0.1% full scale. Load cells command the largest installed base across industrial weighing and material-testing installations, while tactile sensors capture the fastest expansion as collaborative robots require skin-like distributed pressure mapping. Wireless technology segments attract premium pricing by eliminating cable-fatigue failures in cyclic-motion environments.
FDA 21 CFR Part 820 quality-system requirements govern force-sensor validation for US medical-device applications, while the EU Machinery Regulation mandates functional-safety certification for force-limited collaborative robot installations. REACH substance restrictions on lead-based solder alloys are reshaping piezoelectric element bonding processes. Stakeholders must monitor evolving IEC 62061 safety integrity levels as these standards increasingly dictate procurement specifications rather than merely compliance checklists.
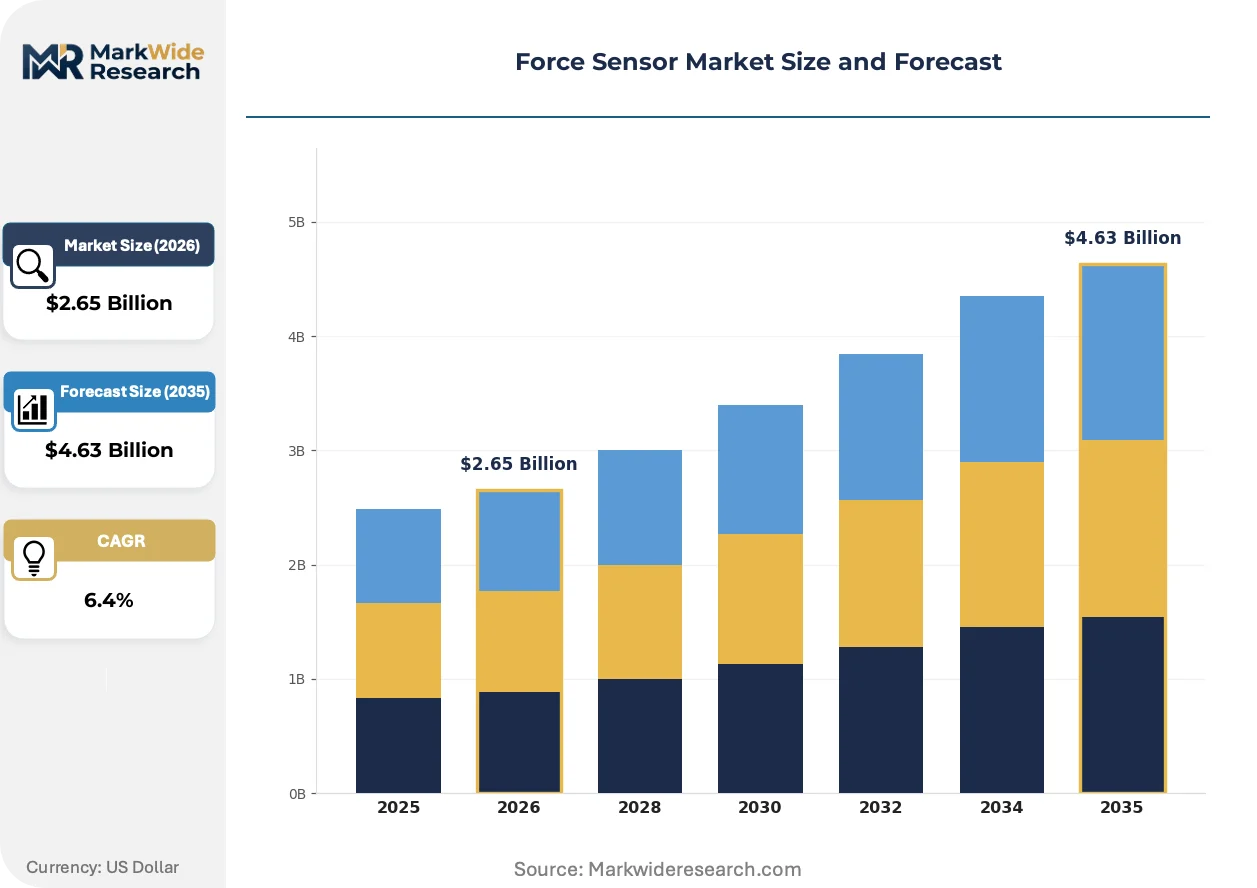
Market Dynamics
Precision calibration tolerance collapse is erasing the historical boundary between laboratory-grade metrology and factory-floor force measurement, compelling suppliers to consolidate previously separate quality protocols into unified manufacturing workflows.
Growth Catalysts
- EU Machinery Regulation functional-safety mandates:Force-limited collaborative robot installations require certified torque-and-force modules, accelerating replacement cycles in German automotive assembly plants.
- Tactile sensor arrays:Distributed pressure-mapping skin for human-robot collaboration is capturing procurement priority in surgical robotics and material-handling automation.
- Silicon strain-gauge wafer fabrication:Backward integration into MEMS processes is compressing lead times for aerospace load-cell suppliers serving FAA-certification pathways.
Market Restraints
- Piezoelectric element supply concentration:Lead-based solder alloy restrictions under REACH are forcing bond-process requalification at specialized European ceramic foundries.
- Calibration infrastructure capex:Deadweight force-standard machines and environmental chambers demand seven-figure facility investments that exclude mid-tier entrants.
- Optical force-sensing substitution:Fiber-Bragg-grating interrogators are displacing electrical strain-gauge architectures in explosive-atmosphere mining applications.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO quality-system enforcement for US FDA-export compliance is creating demand for precision tablet-compression load cells in Hyderabad and Ahmedabad clusters.
- Wireless cyclic-motion deployments:Cable-fatigue elimination commands premium pricing in Japanese automotive welding robots and German press-brake tooling.
- IEC 62061 safety-integrity specification:Procurement departments are embedding SIL ratings into vendor scorecards beyond checkbox compliance, favoring certified architecture suppliers.
Industry Challenges
- Metrology technician scarcity:Deadweight calibration and uncertainty-budget analysis skills are concentrating at national standards laboratories, constraining field-service expansion.
- Multi-protocol integration friction:EtherCAT, PROFINET, and IO-Link coexistence demands firmware architectures that delay time-to-revenue for sensor OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Force Sensor Market |
| Market Size in 2026 | $2.65 Billion |
| Market Size in 2035 | $4.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Load Cell, Strain Gauge, Piezoelectric Sensor, Tactile Sensor Technology: Mechanical, Electromechanical, Optical, Wireless End User: Automotive, Aerospace, Industrial, Consumer Electronics Application: Robotics, Industrial Automation, Medical Devices, Sports Equipment |
| Companies Covered | Honeywell International Inc, TE Connectivity, FUTEK Advanced Sensor Technology, Sensata Technologies, Tekscan, Vishay Precision Group, Flintec, Alps Alpine, Mettler Toledo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Force Sensor Market Strategic Shifts & Innovations
Capacitive microelectromechanical force sensing is compressing form factors below millimeter scales while preserving linearity, enabling anatomically conformable instrumentation that was previously mechanically impossible.
MEMS capacitive architectures are displacing bonded-foil strain gauges in sub-newton measurement regimes through wafer-level batch fabrication. Medical-device OEMs in Minneapolis and Tokyo are qualifying these die-level sensors for laparoscopic instrument tip-force feedback. The displacement is collapsing bill-of-material costs and enabling disposable instrument economics that resist sterilization-reuse models.
REACH substance restrictions on lead-bearing solders are mandating ultrasonic or laser welding for piezoelectric crystal attachment. European sensor houses in Stuttgart and Copenhagen are requalifying bond-joint fatigue life under thermal cycling. The regulation is compressing qualified supplier lists and concentrating procurement among vertically integrated ceramic-to-electronics assemblers.
Buyer consolidation among German automotive tier-ones is compressing vendor qualification cycles and unbundling aftermarket calibration services. Procurement departments at BMW and Volkswagen Group are mandating sensor-as-a-service contracts with guaranteed uptime clauses. The shift is visible most acutely in Bavaria and Lower Saxony, where powertrain test-stand operators now specify total-cost-of-ownership metrics rather than unit pricing.
Force Sensor Market Segmentation
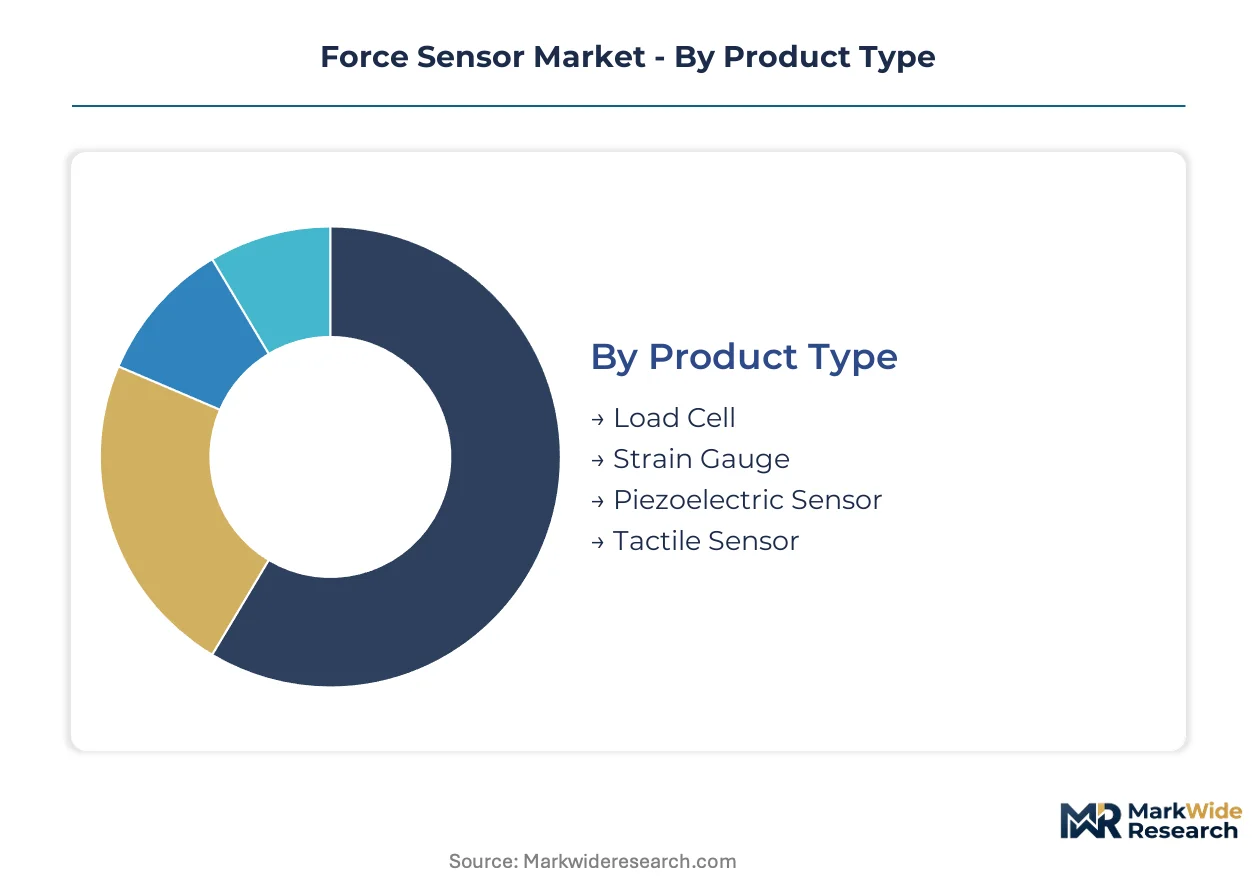
Force sensor procurement channels diverge sharply by performance tier: laboratory metrology flows through specialized distributors, while factory-floor volumes move via systems integrators. Understanding these pathway economics reveals where margin pools concentrate and which segments justify captive manufacturing investment.
Product Type:
Load cells and strain gauges dominate distributor stocking programs, while piezoelectric and tactile variants require direct OEM engagement due to application-specific calibration protocols.
- Load Cell:Bonded-foil strain elements in metal enclosures resolve forces from newtons to meganewtons with hermetic sealing for washdown environments. German automotive test-stand operators specify these for powertrain durability validation under EU Machinery Regulation functional-safety mandates.
- Strain Gauge:Foil or semiconductor resistive grids bonded to structural members translate mechanical deformation into resistance change. Aerospace airframe manufacturers in Toulouse and Hamburg procure these through FAA-certification pathways demanding traceable calibration chains.
- Piezoelectric Sensor:Quartz or ceramic crystals generate charge proportional to dynamic force, excelling at high-frequency vibration measurement.
- Tactile Sensor:Distributed pressure-mapping arrays emulate human skin for robotic manipulation feedback.
Load cells dominate installed base. Tactile sensors are where expansion concentrates.
Technology:
Cost structures stratify sharply: mechanical architectures compete on unit economics, while wireless implementations command premium positioning through cable-elimination value.
- Mechanical:Spring-and-dial or proving-ring mechanisms provide force indication without electrical power, serving explosive-atmosphere mining operations where ignition protection overrides precision requirements.
- Electromechanical:Strain-gauge or piezoelectric transducers with signal conditioning dominate industrial automation, offering 0.1% linearity and digital output protocols. Japanese automotive welding robot OEMs specify these for cyclic-motion endurance.
- Optical:Fiber-Bragg-grating interrogators measure strain through wavelength shift, intrinsically safe for hydrocarbon processing environments.
- Wireless:Battery-powered or energy-harvesting transmitters eliminate cable fatigue in multi-axis robotic cells.
Electromechanical systems capture the majority of revenue. Wireless configurations are climbing the fastest as cable-replacement economics improve.
End User:
Volume concentration versus specification intensity creates divergent procurement patterns: automotive and industrial buyers prioritize total cost of ownership, while aerospace and medical segments emphasize qualification documentation.
- Automotive:Powertrain test stands, assembly-line torque monitoring, and crash-test dummy instrumentation drive high-volume demand. BMW and Volkswagen Group procurement in Bavaria and Lower Saxony mandate sensor-as-a-service contracts with guaranteed uptime clauses.
- Aerospace:Flight-control load monitoring, landing-gear weight-on-wheels detection, and structural health monitoring require FAA or EASA certification traceability. TE Connectivity sustains dominance here through electromechanical heritage and backward integration into strain-gauge wafer fabrication.
- Industrial:Material testing, packaging machinery, and press-brake force limiting span price-performance tiers.
- Consumer Electronics:Touch-force detection in smartphones and stylus pressure sensing prioritize millimeter-scale form factors.
Industrial end users dominate installed base. Aerospace represents the steepest expansion trajectory as next-generation airframes embed more load-path monitoring.
Application:
Regulatory intensity varies dramatically: medical devices face FDA 21 CFR Part 820 quality-system requirements, while sports equipment operates with minimal compliance burden.
- Robotics:Collaborative robot force-torque modules and surgical manipulator haptic feedback demand SIL-rated safety architectures. FUTEK Advanced Sensor Technology differentiates via ultra-miniature torque-and-force modules for robotic surgery applications in Minneapolis and Tokyo.
- Industrial Automation:Assembly-line press fitting, material-handling weight verification, and CNC machine-tool force monitoring prioritize reliability metrics over precision. German precision-engineering clusters in Stuttgart drive high-specification procurement for these installations.
- Medical Devices:Laparoscopic instrument tip-force feedback and prosthetic limb load monitoring require biocompatible materials and sterilization compatibility. MEMS capacitive architectures are displacing bonded-foil strain gauges in sub-newton regimes through wafer-level batch fabrication.
- Sports Equipment:Smart golf club swing analysis and bicycle power meters emphasize low-cost, disposable electronics.
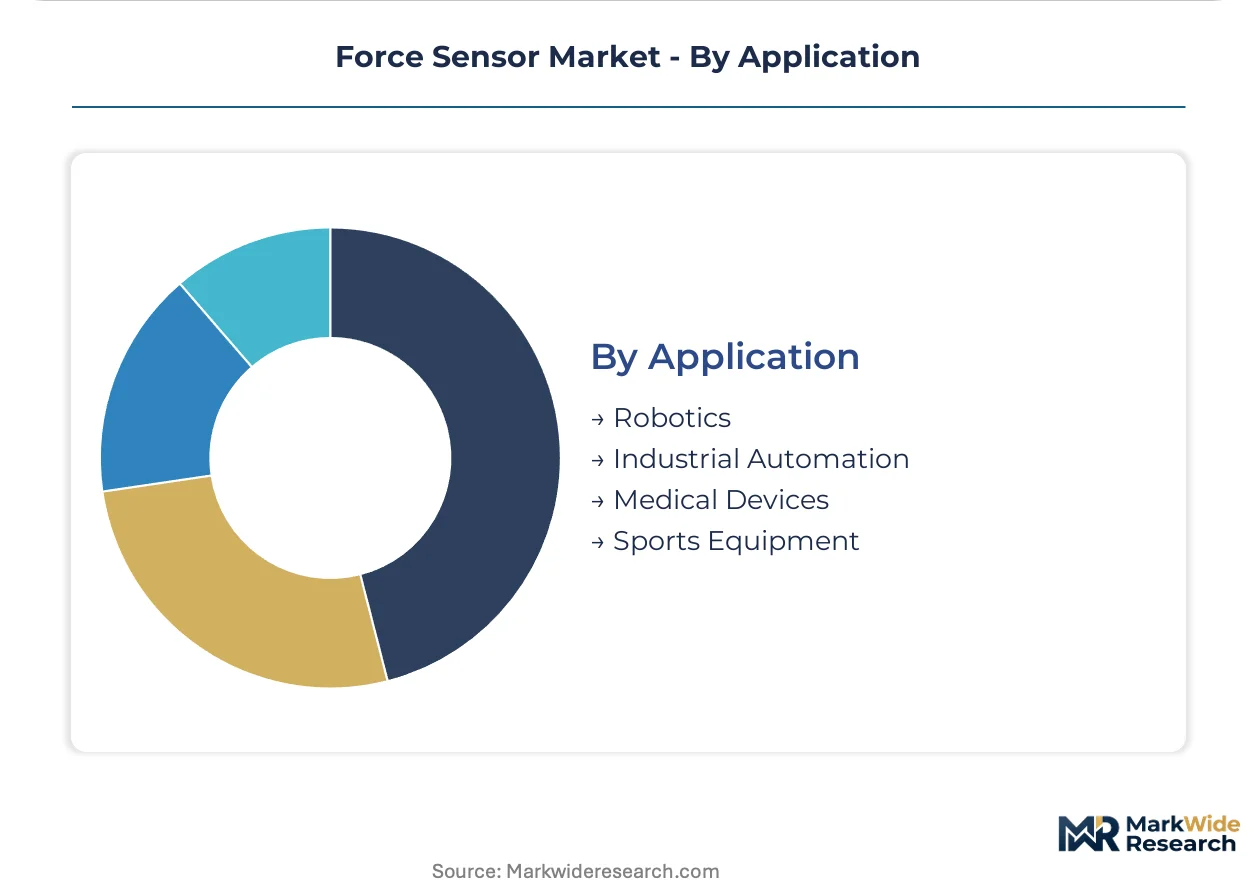
Industrial automation dominates installed base. Medical devices are gaining share fastest as minimally invasive surgery instrumentation expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Force sensor fabrication clusters in Germany, Japan, and the United States, with precision-engineering ecosystems in Stuttgart, Nagoya, and Minneapolis anchoring high-specification supply. Demand dispersion follows automotive, aerospace, and medical-device manufacturing footprints across these territories.
Germany
BMW and Volkswagen Group procurement mandates for sensor-as-a-service contracts with uptime guarantees are reshaping vendor relationships. EU Machinery Regulation functional-safety certification requirements accelerate replacement cycles in Bavarian and Lower Saxon automotive plants. Stuttgart precision-engineering clusters drive high-specification procurement for powertrain test-stand installations.
United States
FAA-certification pathways for aerospace load cells sustain demand traceability requirements from NIST-calibrated sources. FDA 21 CFR Part 820 quality-system requirements govern force-sensor validation for medical-device applications in Minneapolis surgical robotics clusters. TE Connectivity leverages electromechanical heritage to sustain dominance across these regulated procurement channels.
Japan
Automotive welding robot OEMs specify electromechanical force sensors for cyclic-motion endurance in multi-axis cells. METI industrial automation incentives support tactile sensor array development for human-robot collaboration. Nagoya manufacturing belt procurement prioritizes cable-fatigue elimination through wireless configurations in press-brake tooling.
China
MIIT smart manufacturing directives accelerate force-sensor deployment in automotive assembly lines serving domestic EV producers. GB standards alignment with IEC 62061 safety integrity levels is embedding SIL ratings into procurement specifications. Yangtze River Delta industrial automation clusters concentrate demand for load cells in material-handling and packaging machinery.
India
CDSCO quality-system enforcement for US FDA-export compliance creates demand for precision tablet-compression load cells. Hyderabad and Ahmedabad pharmaceutical manufacturing clusters require calibrated force measurement for international regulatory submission. BIS standards adoption is gradually aligning domestic procurement with IEC metrology protocols.
Force Sensor Market Key Industry Players
Concentration sits with diversified electromechanical conglomerates possessing backward integration into strain-gauge wafer fabrication and FAA-certification pathway access. Mid-tier specialists compete on application-specific calibration protocols and regional regulatory intimacy. Three archetypes dominate: vertically integrated sensor-to-systems suppliers, MEMS-focused miniaturization specialists, and precision-metrology houses with national standards laboratory relationships. Competitive moves center on sensor-as-a-service contract structures with guaranteed uptime clauses, and ultrasonic welding process requalification to satisfy REACH lead-free bonding mandates.
Among US-based diversified technology conglomerates, Honeywell International Inc and TE Connectivity occupy positions spanning aerospace, industrial automation, and medical-device verticals through electromechanical heritage and calibration traceability infrastructure. FUTEK Advanced Sensor Technology exemplifies the miniaturization specialist archetype, anchoring ultra-compact torque-and-force module supply for robotic surgery applications in Minneapolis and Tokyo medical-device clusters.
| Leading Market Players |
|---|
| Honeywell International Inc |
| TE Connectivity |
| FUTEK Advanced Sensor Technology |
| Sensata Technologies |
| Tekscan |
| Vishay Precision Group |
| Flintec |
| Alps Alpine |
| Mettler Toledo |
| Others |
Cost & Logistics Intelligence
Fourteen-week lead times for FAA-certified strain-gauge wafers concentrate pricing power with German and US suppliers possessing in-house MEMS fabrication, while inventory buffers at automotive tier-ones compress spot-market premiums for standard load cells.
Pricing Analysis
EU Machinery Regulation functional-safety certification dictates the pricing tier structure across the force sensor market. Three-tier pricing separates SIL-rated aerospace modules from industrial automation standard cells and economy-grade consumer electronics variants. Cost compression in the industrial tier is intensifying because German automotive procurement departments unbundle aftermarket calibration services and mandate sensor-as-a-service contracts. Medical-device OEMs in Minneapolis and Tokyo exhibit the lowest price sensitivity due to FDA 21 CFR Part 820 validation requirements and disposable instrument economics.
Supply Chain Analysis
Quartz crystal supply from specialized European ceramic foundries in Stuttgart and Copenhagen underwrites piezoelectric sensor availability, creating vulnerability to REACH lead-free bonding requalification delays. Manufacturing concentration rests on Germany for precision load cells, Japan for electromechanical welding robot modules, and the United States for aerospace certification pathways. Raw material dependencies include silicon wafers for MEMS capacitive architectures, lead-free solder alloys for piezoelectric attachment, and hermetic metal enclosures for washdown environments. Single-source vulnerability concentrates at national standards laboratories for deadweight calibration equipment. Distribution runs through specialized metrology distributors for laboratory-grade instruments and systems integrators for factory-floor volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer consolidation among German automotive tier-ones and Japanese welding robot OEMs has shifted procurement leverage toward volume purchasers demanding uptime guarantees and unbundled service economics.
For Market Incumbents: Secure backward integration into strain-gauge wafer fabrication to defend against MEMS capacitive substitution in sub-newton medical applications. Deepen captive supply of piezoelectric ceramic elements to mitigate REACH requalification risk at European foundries. Anchor relationships with national standards laboratories to constrain field-service expansion by mid-tier competitors lacking calibration infrastructure. For New Entrants and Emerging Players: IEC 62061 SIL certification fast-tracks offer the most penetrable entry path into German automotive powertrain test-stand procurement. Target Indian pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad where CDSCO enforcement for US FDA-export compliance creates demand for precision tablet-compression load cells lacking established supplier relationships. Pursue wireless cyclic-motion configurations for Japanese press-brake tooling as a cable-fatigue-elimination value proposition. For Investors and Strategic Acquirers: Long-term, this sits as a precision-metrology consolidation play because buyer mandates for sensor-as-a-service contracts favor vendors with calibration traceability infrastructure and national standards laboratory relationships. Acquisition targets should display vertical integration into MEMS fabrication or FAA-certification pathway access. Monitor procurement department embedding of SIL ratings into vendor scorecards as the inflection signal for certified architecture supplier concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Wafer Fabrication | Compresses lead times for FAA-certification pathways serving TE Connectivity and Honeywell aerospace contracts. |
| Ultrasonic Welding Process Requalification | Satisfies REACH lead-free bonding mandates at Stuttgart and Copenhagen ceramic foundries. |
| Sensor-as-a-Service Contract Launch | Matches BMW and Volkswagen Group procurement mandates for guaranteed uptime clauses in Bavaria. |
| IEC 62061 SIL Certification Investment | Embeds safety-integrity ratings into vendor scorecards beyond checkbox compliance. |
| Wireless Configuration Development | Eliminates cable fatigue in Japanese automotive welding robots and German press-brake tooling. |
Research Approach
Desk research of SEC 10-K filings, FAA certification databases, and EU Machinery Regulation implementation guidance preceded structured interviews with metrology technicians, automotive procurement managers, biomedical engineers at surgical robotics OEMs, and calibration service heads at national standards laboratories. Primary fieldwork with German precision-engineering clusters and Minneapolis medical-device manufacturers combined with secondary validation from IEC standards documentation and REACH substance restriction filings. Bottom-up demand modeling across robotics, industrial automation, and medical device applications triangulated against top-down macroeconomic indicators.
Variance decomposition across product type, technology, end user, and application dimensions shaped the analytical framework throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included EU Machinery Regulation replacement cycle acceleration, MEMS capacitive architecture displacement rates in sub-newton regimes, and wireless configuration adoption in cyclic-motion environments.
Underlying assumptions cover continued REACH enforcement on lead-bearing solders, with deviation risk concentrated in piezoelectric bond-process requalification timelines and metrology technician scarcity at field-service expansion points. Practitioners should keep alternative scenarios live as FDA 21 CFR Part 820 validation requirements and IEC 62061 safety integrity procurement embedding evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Touch Sensor Market
Sensors and Controls
Environmental Noise Cancellation Microphones Market
Sensors and Controls
Temperature Controller Market
Sensors and Controls
Solid Flow Rate Valve Control Market
Sensors and Controls
Proximity Sensors Market
Sensors and Controls
Magnetoresistance Sensor Market
Sensors and Controls
Aspiration Control Systems Market
Sensors and Controls
Asia Pacific Touch Screen Controllers Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Smart Level Probe Market
Sensors and Controls
Global Biosensors Market
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market
Sensors and Controls
Current Sensor Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Taiwan Sensors Market