
 China PV Monitoring Systems Market | 2026-2036
China PV Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
China PV Monitoring Systems Market Insights
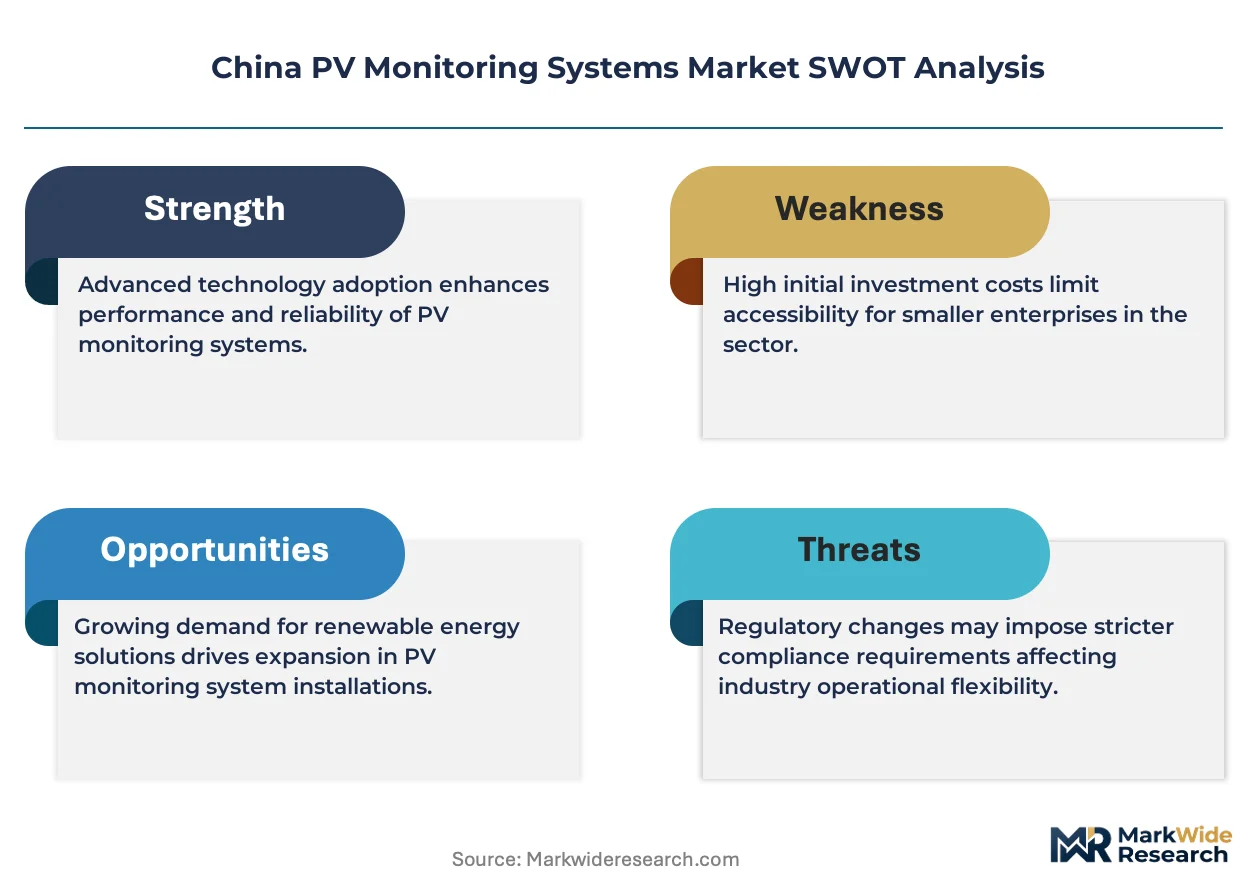
Asset-light leasing models for monitoring hardware are reshaping competitive entry barriers for smaller fleet operators in China. Huawei Digital Power leverages its silicon-to-system integration to dominate high-voltage string inverter monitoring architectures. Sungrow sustains cost leadership through captive manufacturing of power electronics and sensor arrays. JinkoSolar anchors downstream service revenue by bundling monitoring subscriptions with module supply contracts.
PV monitoring systems encompass hardware sensors, data acquisition units, and software platforms that measure irradiance, temperature, current-voltage curves, and energy yield across photovoltaic installations. These systems enable fault isolation, performance ratio tracking, and predictive maintenance to maximize plant availability and investor returns. Cloud-based deployment leads in new installations due to lower capital outlay and centralized fleet visibility for multi-site owners. Edge computing segments are gaining traction where latency-sensitive fault detection protects utility-scale revenue streams. Hardware components retain the largest revenue share but face margin compression as software analytics and subscription services capture expanding value pools.
China's National Energy Administration and Ministry of Ecology and Environment enforce grid-code compliance and carbon accounting rules that mandate real-time data transparency from solar assets. GB standards and MIIT cybersecurity protocols shape product certification requirements for connected monitoring equipment. Stakeholders must weigh the trade-off between cloud scalability and edge autonomy as provincial grid operators tighten data localization requirements.
Market Dynamics
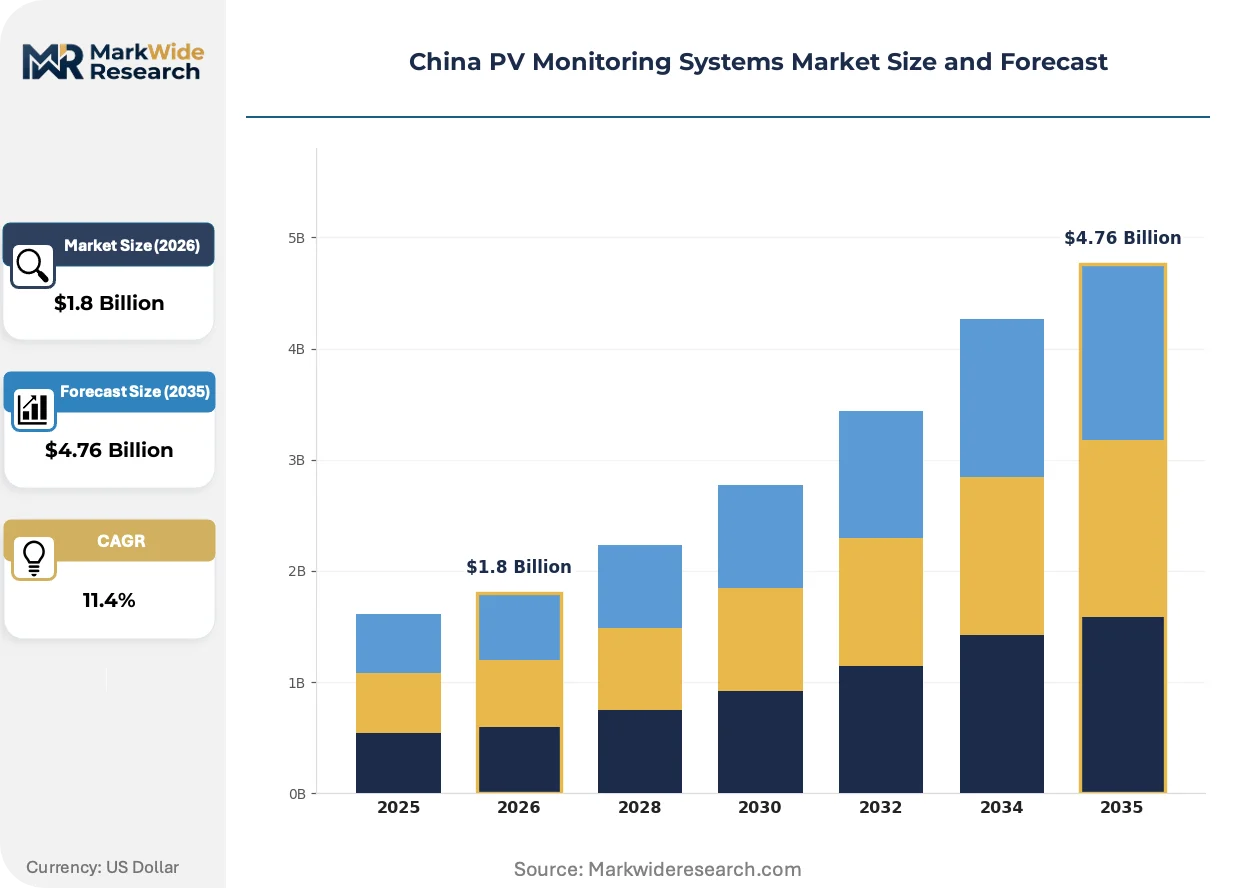
China's dual carbon mandates and NEEA grid integration standards are compressing deployment timelines for real-time data infrastructure across solar fleets. Provincial grid operators now enforce granular telemetry requirements that force asset owners to upgrade legacy monitoring architectures.
Growth Catalysts
- NEEA grid-code mandates:Real-time data transparency requirements are accelerating hardware refresh cycles across utility-scale installations. Fleet operators must deploy compliant monitoring suites to maintain grid connection eligibility.
- Distributed solar clusters:Coastal provinces Jiangsu and Zhejiang are aggregating rooftop portfolios that demand centralized visibility tools. Asset managers require fleet-wide dashboards to optimize performance across fragmented site footprints.
- Silicon-to-system integration:Inverter manufacturers are embedding monitoring intelligence directly into power electronics. This convergence reduces installation complexity and accelerates commissioning timelines for new capacity.
Market Restraints
- Sensor hardware cost volatility:Fluctuations in semiconductor and optical component pricing compress margins for data acquisition unit suppliers. Manufacturers face working capital pressure from inventory holding costs.
- MIIT cybersecurity protocols:Certification timelines for connected equipment extend product launch schedules. Compliance testing creates bottlenecks for software platform updates.
- Cloud dependency risks:Latency-sensitive fault detection in utility-scale revenue protection applications limits pure cloud architectures. Edge computing requirements inflate hardware bills of materials.
Strategic Opportunities
- Western province expansion:Inner Mongolia and Xinjiang utility-scale developments lack mature monitoring service infrastructure. First-mover platforms can anchor long-term O&M contracts in these high-insolation zones.
- Carbon accounting convergence:MEE enforcement of asset-level emissions tracking creates demand for monitoring data integration with enterprise sustainability systems. Software vendors can capture subscription value from compliance reporting workflows.
- Predictive maintenance analytics:Machine learning applied to inverter degradation signatures enables failure anticipation. This capability differentiates service providers in competitive O&M tender processes.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for edge computing nodes requires specialized talent pools concentrated in Shenzhen and Beijing. Recruitment competition from consumer electronics sectors inflates compensation costs.
- Legacy SCADA integration:Existing plant control systems in older solar farms use proprietary protocols that resist standardized data extraction. Retrofit projects demand custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China PV Monitoring Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Hybrid, Cloud-Based End User: Utilities, Commercial Enterprises, Residential Users, Energy Management Companies Deployment: On-Premises, Cloud, Edge Computing, Remote Application: Performance Monitoring, Fault Detection, Energy Management, Data Logging |
| Companies Covered | Huawei Digital Power, Sungrow, LONGi Solar, JinkoSolar, Trina Solar, GoodWe, Ginlong Technologies, BYD, CATL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China PV Monitoring Systems Market Trends and Innovations
Digital thread architectures are threading measurement data from module-level sensors through cloud analytics to grid operator dashboards. This integration is collapsing information latency between field assets and dispatch centers.
Module-level power electronics with integrated monitoring intelligence is digitizing performance visibility down to individual panel strings. Utility-scale developers in Ningxia and Qinghai are deploying these architectures to isolate shading and soiling losses. The granularity is digitizing insurance underwriting and financing due diligence processes for project finance.
MIIT cybersecurity certification pathways for connected industrial equipment are tightening firmware update procedures. Manufacturers must pre-validate software patches through approved testing laboratories before remote deployment. The protocol friction is compressing platform development cycles and forcing architectural choices toward modular hardware designs.
Hardware-as-a-service contracting is displacing capital purchase models among distributed solar fleet operators. Leasing arrangements for sensor networks and data acquisition units lower entry barriers for smaller commercial and industrial installers. The shift is most visible in Zhejiang's textile and electronics manufacturing zones where rooftop aggregation specialists compete on O&M service bundling.
China PV Monitoring Systems Market Segmentation
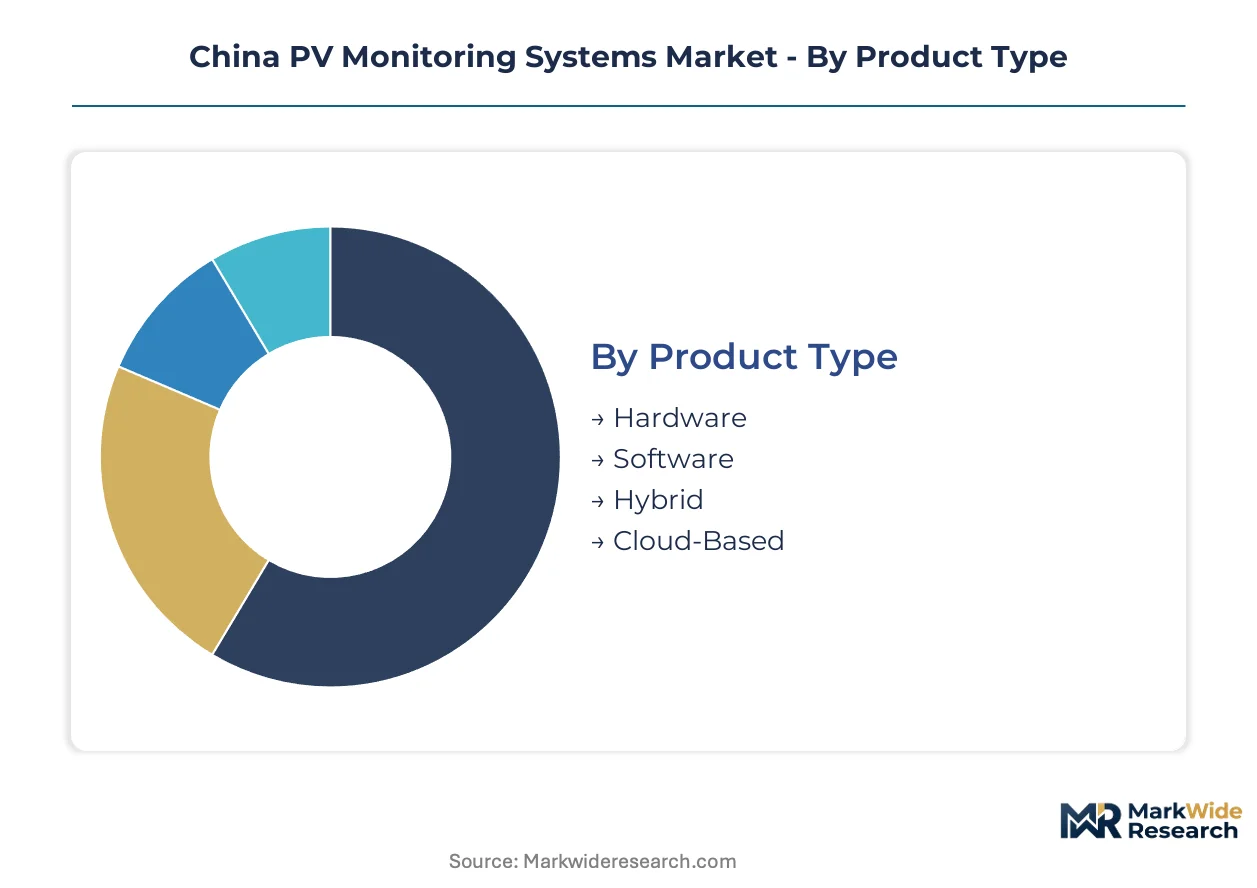
PV monitoring architectures fragment across product layers, user sophistication, and deployment topology. Each dimension carries distinct margin profiles and regulatory compliance burdens under China's dual carbon mandates and MIIT cybersecurity protocols.
Product Type:
Cost tier determines procurement patterns across hardware-heavy versus software-centric configurations.
- Hardware:Physical sensors, data acquisition units, and communication gateways capture irradiance, temperature, and current-voltage signatures. Utility-scale installations in Ningxia and Qinghai drive procurement volume where module-level granularity protects revenue streams. Sensor hardware faces margin compression from semiconductor cost volatility and power electronics integration trends.
- Software:Cloud analytics platforms, fleet dashboards, and predictive maintenance algorithms extract value from raw telemetry. Demand concentrates among multi-site asset managers in Jiangsu and Zhejiang requiring centralized visibility across distributed rooftop portfolios. Subscription revenue models are displacing perpetual licenses as fleet operators prioritize operational expenditure flexibility.
- Hybrid:Bundled hardware-software offerings combine edge data collection with cloud analytics. Coastal province installers favor these packages to accelerate commissioning timelines.
- Cloud-Based:Pure software-as-a-service deployments eliminate on-site server infrastructure. Lower capital barriers attract smaller commercial and industrial fleet operators.
Hardware holds installed capacity. Software is rotating up the share rankings.
End User:
Application maturity varies sharply between centralized procurement and fragmented commercial demand.
- Utilities:State-owned grid operators and independent power producers mandate enterprise-grade monitoring with NEEA grid-code compliance. Real-time telemetry requirements from provincial dispatch centers drive hardware refresh cycles. Fault detection latency directly impacts grid connection eligibility and curtailment penalties.
- Commercial Enterprises:Manufacturing facilities, logistics parks, and retail chains operate rooftop solar assets requiring performance optimization. Zhejiang textile and electronics manufacturing zones aggregate significant distributed capacity where fleet management tools reduce operational complexity. Energy cost hedging motivations dominate procurement criteria.
- Residential Users:Individual homeowners and small building operators deploy basic monitoring through inverter-integrated solutions. Simple mobile dashboards suffice for yield visibility.
- Energy Management Companies:Third-party O&M providers and asset aggregators purchase white-label monitoring platforms to service downstream clients.
Utilities anchor procurement volume. Commercial Enterprises are expanding most quickly.
Deployment:
Latency requirements and data sovereignty rules shape architectural selection.
- On-Premises:Local server infrastructure processes and stores all telemetry within facility boundaries. Military installations and critical infrastructure operators mandate this topology for air-gapped security compliance.
- Cloud:Centralized data processing enables fleet-wide analytics and remote access. Lower upfront capital attracts distributed solar aggregators.
- Edge Computing:Local processing nodes execute fault detection algorithms with millisecond response times. Utility-scale revenue protection applications in high-insolation western provinces require this architecture to isolate string failures before yield degradation accumulates.
- Remote:Satellite or cellular backhaul connects off-grid installations to central platforms. Inner Mongolia and Xinjiang frontier projects rely on this topology.
Cloud dominates new installations. Edge Computing is gaining share fastest.
Application:
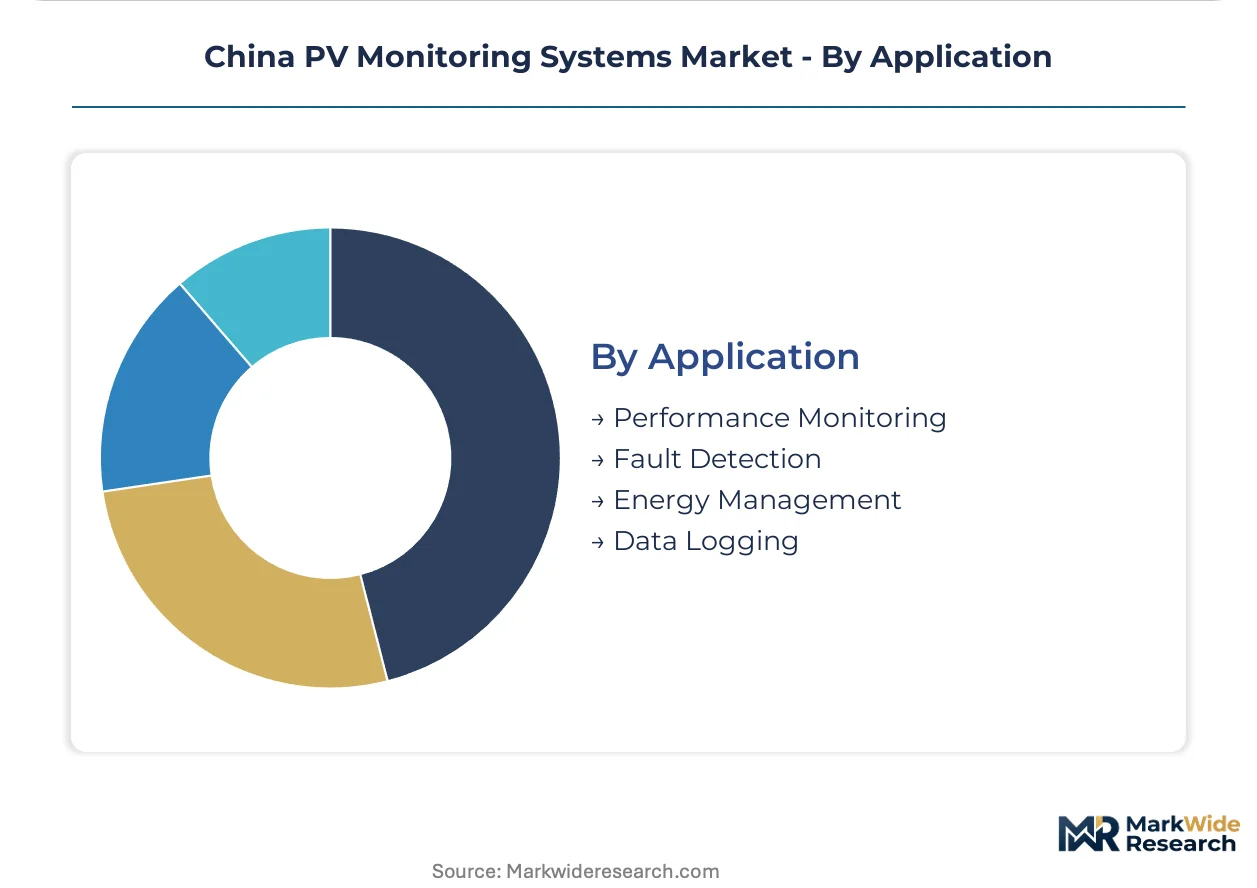
Functional use case determines sensor density and analytics sophistication requirements.
- Performance Monitoring:Continuous tracking of energy yield, performance ratio, and availability metrics against modeled expectations. Asset managers in Jiangsu benchmark actual output against satellite-derived irradiance data to isolate underperformance. Insurance underwriting and project finance due diligence increasingly require this baseline visibility.
- Fault Detection:Automated identification of inverter failures, string disconnects, and module degradation patterns. Machine learning classifiers trained on historical failure signatures enable predictive intervention. This capability differentiates competitive O&M tender outcomes.
- Energy Management:Integration with building automation systems and grid dispatch signals for demand response participation.
- Data Logging:Regulatory-compliant archival of telemetry for NEEA reporting and carbon accounting verification.
Performance Monitoring holds installed capacity. Fault Detection is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale developers and distributed solar aggregators concentrate procurement decisions in coastal provinces where grid-code compliance deadlines are tightest. Provincial energy bureaus enforce NEEA telemetry standards that vary in implementation rigor across China's economic zones.
Jiangsu
Textile and electronics manufacturing zones drive distributed solar cluster formation. NEEA grid integration standards mandate real-time data reporting from assets above 6MW capacity. Suzhou and Wuxi host fleet management platform deployments serving multi-site commercial portfolios.
Zhejiang
Rooftop aggregation specialists compete on O&M service bundling in manufacturing corridors. MIIT cybersecurity protocols shape certification requirements for connected monitoring equipment. Hangzhou-based software vendors supply cloud analytics platforms to fragmented commercial installers.
Inner Mongolia
Utility-scale developments in high-insolation zones lack mature monitoring service infrastructure. Dual carbon goals accelerate procurement timelines for real-time data systems. Hohhot and Ordos anchor frontier projects where first-mover platforms secure long-term O&M contracts.
Xinjiang
Frontier solar farms require satellite or cellular backhaul for remote telemetry transmission. GB standards govern data acquisition unit specifications for grid-connected assets. Ürümqi and Hami concentrate procurement activity where edge computing architectures protect revenue streams.
Ningxia
Module-level power electronics deployments digitize performance visibility down to individual panel strings. Provincial grid operators enforce granular telemetry requirements from dispatch centers. Yinchuan hosts utility-scale developers isolating shading and soiling losses through advanced monitoring architectures.
China PV Monitoring Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware, software, and bundled service configurations. The vendor base organizes around inverter manufacturers embedding monitoring intelligence, standalone platform developers, and module suppliers bundling subscriptions. Three archetypes dominate: silicon-to-system integrators leveraging power electronics convergence; captive manufacturers controlling sensor and data acquisition unit production; and downstream service providers anchoring recurring revenue through O&M contracts. Competitive moves center on strategic partnerships for firmware development and portfolio diversification into predictive maintenance analytics.
Among inverter-integrated monitoring specialists, Huawei Digital Power and Sungrow occupy positions where power electronics convergence reduces installation complexity. JinkoSolar exemplifies the downstream service archetype by bundling monitoring subscriptions with module supply relationships. These three companies represent distinct strategic paths: silicon-to-system integration, captive manufacturing control, and downstream revenue anchoring.
| Leading Market Players |
|---|
| Huawei Digital Power |
| Sungrow |
| LONGi Solar |
| JinkoSolar |
| Trina Solar |
| GoodWe |
| Ginlong Technologies |
| BYD |
| CATL |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Shenzhen sensor foundries is compressing component lead times and forcing data acquisition unit suppliers to absorb inventory carrying costs. This utilization dynamic weakens bargaining power against downstream inverter integrators while accelerating migration toward subscription-based software pricing.
Pricing Analysis
Certification level under MIIT cybersecurity protocols creates the primary spread between premium and standard tiers. Three-tier pricing structure across NEEA-compliant, enterprise-grade, and basic monitoring configurations dominates procurement. Cost compression in hardware tiers is intensifying because power electronics convergence eliminates standalone sensor demand. Commercial rooftop aggregators in Zhejiang exhibit highest price sensitivity while state-owned utilities prioritize compliance over unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for data acquisition unit procurement as suppliers compete for inverter OEM shelf space. Semiconductor fabrication concentrates in Taiwan, South Korea, and mainland China. Optical sensor substrates draw from Japanese and German specialty glass suppliers. Single-source vulnerability in edge computing chipsets poses structural risk. Distribution runs through inverter OEM bundling and direct EPC contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive boundaries as NEEA telemetry standards force interoperability between proprietary inverter ecosystems and third-party fleet management tools.
For Market Incumbents: Entrench silicon-to-system integration advantages by embedding firmware directly into power electronics before competitors achieve comparable convergence. Captive manufacturing of sensor arrays in Jiangsu protects margin structure against semiconductor cost volatility. Priority investment in predictive maintenance algorithms differentiates service contracts as hardware margins compress. For New Entrants and Emerging Players: Establish a beachhead in western province utility-scale developments where incumbent monitoring infrastructure remains underdeveloped. Inner Mongolia and Xinjiang frontier projects lack mature O&M service providers. White-label platform licensing to regional EPC contractors accelerates customer acquisition without direct sales force investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software vendors with NEEA compliance integration and carbon accounting workflow automation. Long-term viability over a multi-year horizon favors platforms anchoring enterprise sustainability system integrations. Acquisition targets should demonstrate firmware development capabilities in edge computing architectures. The signal to watch is provincial grid operator data localization mandates accelerating edge deployment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-to-System Firmware Integration | Huawei Digital Power and Sungrow leverage embedded intelligence to collapse installation timelines and lock out standalone monitoring vendors. |
| Hardware-as-a-Service Leasing Models | Asset-light contracting in Zhejiang textile zones lowers entry barriers for smaller commercial rooftop aggregators competing on O&M bundling. |
| MIIT Cybersecurity Certification Investment | Pre-validation through approved testing laboratories accelerates product launch schedules and creates regulatory moats against uncertified competitors. |
| Predictive Maintenance Analytics Development | Machine learning classifiers trained on inverter degradation signatures differentiate competitive O&M tender outcomes in Jiangsu utility auctions. |
| Western Province Service Infrastructure Buildout | First-mover platforms in Inner Mongolia and Xinjiang anchor long-term contracts in high-insolation zones where monitoring maturity lags coastal provinces. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NEEA regulatory filings, MIIT certification databases, and provincial energy bureau procurement records. Interviews with inverter OEM product managers, EPC contractor procurement leads, utility planning officers, and third-party O&M platform executives informed demand-side validation. Secondary sources include customs trade data on sensor component imports, GB standards documentation, and grid-code compliance disclosure filings. Bottom-up capacity installation tracking triangulates against top-down revenue estimates across hardware, software, and hybrid deployment configurations.
Forecast inputs incorporate module-level power electronics adoption curves, NEEA telemetry mandate implementation timelines, and edge computing architecture penetration rates across utility-scale versus distributed segments. Segmentation dimensions span product type, end user sophistication, deployment topology, and application function. CAGRs derive from regression analysis of historical procurement patterns against regulatory enforcement intensity. Carbon accounting convergence with enterprise sustainability systems and predictive maintenance algorithm commercialization pace constitute industry-specific forecast variables across the analysis window.
Sensitivities concentrate around MIIT cybersecurity protocol revisions, provincial grid operator data localization enforcement, and semiconductor supply chain disruption. Forecasts reflect documented assumptions regarding NEEA mandate compliance timelines and inverter-integrated monitoring displacement rates. Macroeconomic credit tightening affecting utility-scale project finance, regulatory acceleration of carbon accounting requirements, or breakthrough advances in module-level power electronics economics would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Portable Air Purifier Market
Sensors and Controls
Mass Flow Controller Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
Air Quality Monitoring System Market
Sensors and Controls
In-Display Fingerprint Sensors Market
Sensors and Controls
Environmental Sensing and Monitoring Technologies Market
Sensors and Controls
Antenna Transducer and Radome Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
US Vibration Sensors Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Instrumented Load Shackle Market
Sensors and Controls
Surface Vision and Inspection Market
Sensors and Controls
Sensor Data Analytics Market
Sensors and Controls
PID Controller Market