
 Automated Number Plate Recognition (ANPR) and Detection Sensors Market | 2026-2036
Automated Number Plate Recognition (ANPR) and Detection Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Number Plate Recognition (ANPR) and Detection Sensors Market Outlook
The United Kingdom is tilting toward expanded ANPR deployment across motorway networks and urban congestion zones. Hikvision leverages integrated video analytics platforms that combine plate capture with vehicle classification. Axis Communications AB sustains Nordic design heritage in ruggedized camera hardware for harsh-climate installations. Kapsch TrafficCom AG anchors European tolling expertise through multi-lane free-flow systems.
Automated Number Plate Recognition and Detection Sensors encompass camera modules, infrared illuminators, optical character recognition engines, and neural network processors that capture, interpret, and log vehicle registration data under variable lighting and speed conditions. These systems serve traffic enforcement, access control, and revenue collection functions across public roadway and private facility environments. Deep Learning segments command premium positioning as municipalities replace rule-based optical character recognition with convolutional neural networks that improve accuracy in adverse weather. Fixed Systems installations dominate volume in highway and border applications, while Mobile Systems segments in law enforcement fleets exhibit faster expansion due to flexible deployment economics.
FCC equipment authorization governs radio-frequency components in U.S. ANPR hardware, while the EU AI Act imposes risk-classification requirements on automated biometric identification in public spaces. The U.K. Home Office oversees national ANPR data retention standards through the National ANPR Service. Stakeholders must monitor evolving algorithmic accountability rules that could mandate explainability audits for deep learning-based plate recognition systems.
Market Dynamics
The migration from rule-based optical character recognition to convolutional neural networks is compressing hardware refresh cycles as transportation authorities demand accuracy gains in adverse weather and high-speed capture scenarios.
Growth Catalysts
- EU AI Act risk-classification mandates:Biometric identification thresholds in public spaces are accelerating vendor investment in explainable algorithm architectures ahead of enforcement deadlines.
- United States federal highway funding:Municipal smart-city budget allocations are sustaining deployment momentum for fixed-system installations across interstate corridors.
- Edge computing architectures:On-device neural processing is reducing latency for real-time enforcement decisions and lowering backhaul bandwidth requirements.
Market Restraints
- Specialized semiconductor supply concentration:Neural network processors and infrared sensor substrates face fabrication bottlenecks concentrated in East Asian foundry capacity.
- GDPR-derived data retention friction:Cross-border vehicle data flows encounter compliance complexity when national ANPR databases lack mutual recognition frameworks.
- Legacy optical system substitution:Rule-based OCR hardware in installed base represents sunk capital resisting premature replacement despite accuracy gaps.
Strategic Opportunities
- India national highway digitization:Toll plaza automation mandates under the Bharatmala program create greenfield demand for multi-lane free-flow systems.
- Law enforcement mobile fleet expansion:Patrol vehicle retrofit programs favor flexible deployment economics over fixed infrastructure commitments.
- 5G-V2X convergence:Vehicle-to-everything communication standards enable cooperative perception architectures that fuse camera capture with onboard telemetry.
Industry Challenges
- Convolutional neural network optimization expertise:Scarce embedded systems engineers capable of tuning inference engines for resource-constrained edge devices command premium compensation.
- FCC equipment authorization timelines:Radio-frequency component certifications for infrared illuminators and wireless backhaul modules extend product launch schedules.
- Interoperability with legacy traffic management backends:Proprietary data formats in existing central systems necessitate costly middleware development for neural-network-enabled cameras.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Number Plate Recognition (ANPR) and Detection Sensors Market |
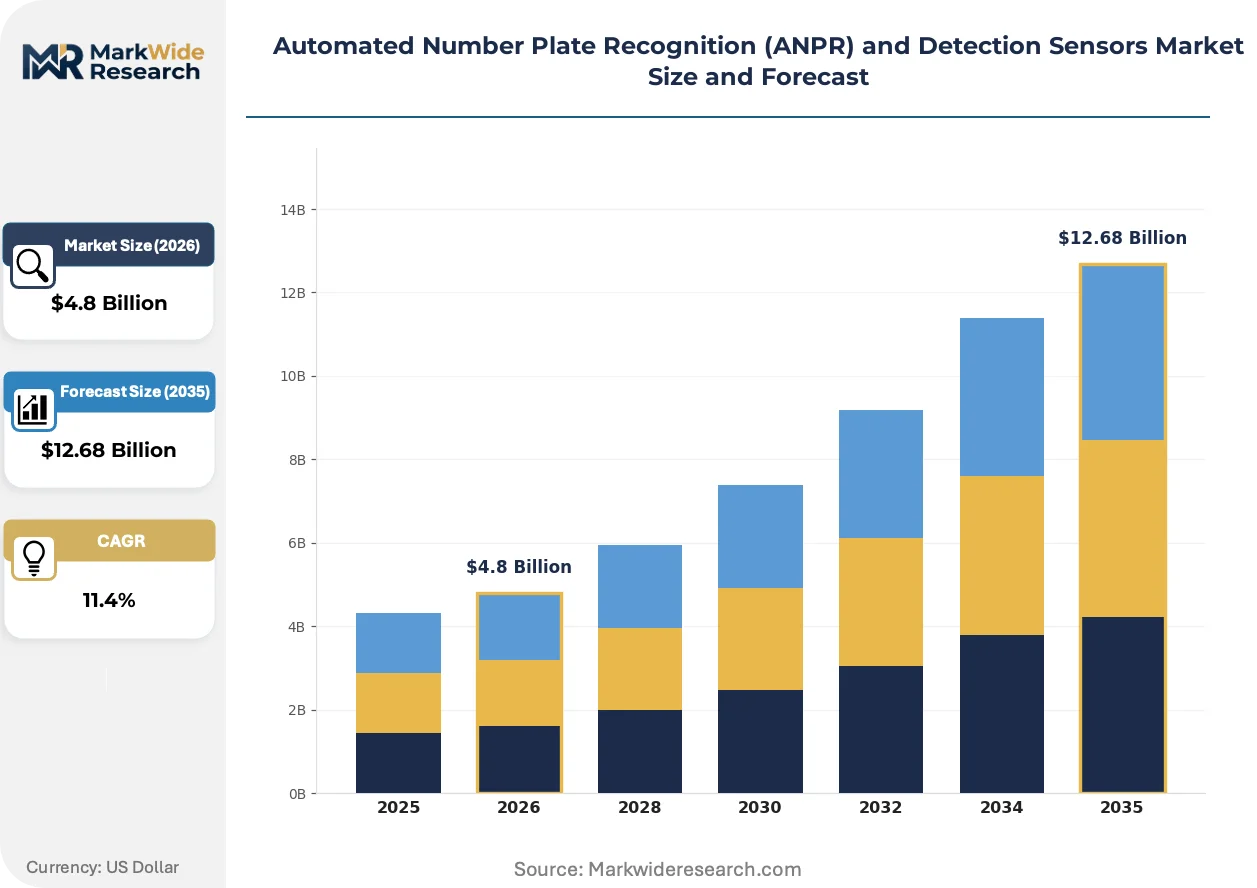
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Optical Character Recognition, Image Processing, Deep Learning, LPR Software Application: Traffic Management, Law Enforcement, Parking Management, Toll Collection End User: Government Agencies, Private Security Firms, Parking Operators, Transportation Authorities Installation: Fixed Systems, Mobile Systems, Integrated Solutions, Standalone Units |
| Companies Covered | Hikvision, Axis Communications AB, Siemens AG, Kapsch TrafficCom AG, Genetec Inc., Motorola Solutions, Robert Bosch GmbH, Jenoptik AG, Adaptive Recognition Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Number Plate Recognition (ANPR) and Detection Sensors Market Strategic Shifts
Computational photography and on-device inference are redrawing competitive boundaries between camera hardware specialists and semiconductor suppliers.
Neural processing units with dedicated tensor cores are rendering obsolete the separation between image capture and server-side OCR interpretation. State transportation departments in the United States are specifying NPU-integrated cameras for new procurements. This compression of the processing stack is collapsing vendor margins on standalone illumination and lens modules.
REACH restrictions on heavy metals in electronic components are forcing redesigns of infrared LED arrays and power supply assemblies. European tolling operators now require substance-of-concern documentation across their supplier tiers. The fixed-system segment is absorbing compliance costs through extended qualification cycles for new hardware platforms.
Performance-based maintenance contracts are displacing capital purchase models for large-scale highway deployments. Australian state road authorities and Canadian provincial operators are piloting availability-guarantee structures where vendors retain ownership. This shift transfers operational risk to integrators while locking in long-term revenue streams.
Automated Number Plate Recognition (ANPR) and Detection Sensors Market Segmentation
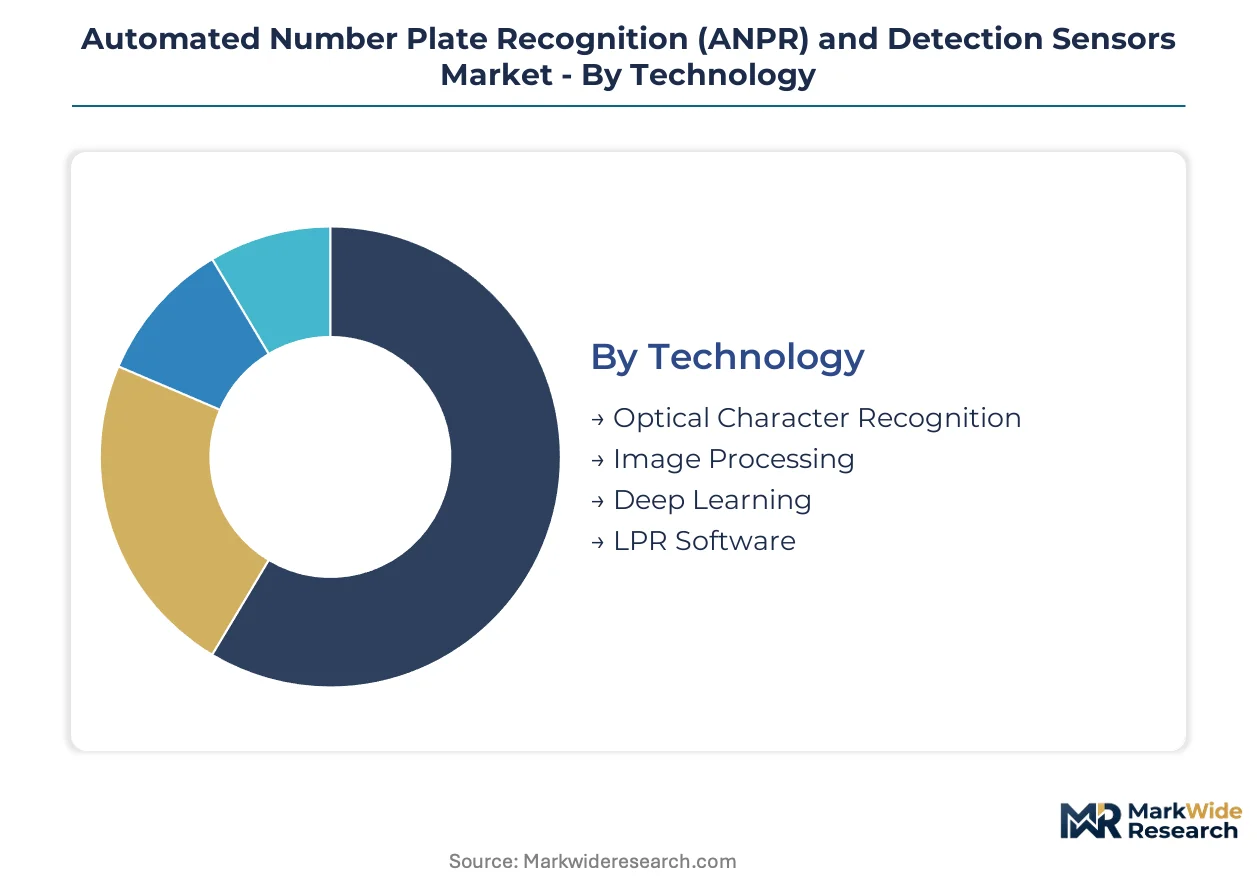
ANPR market segmentation reveals divergent replacement cycles across technology layers. Hardware installations refresh every 7-10 years while software algorithms compress to 18-36 month upgrade windows. Understanding these cadences shapes procurement timing and vendor relationship structures.
Technology:
Deep Learning segments turn over fastest as neural architectures iterate quarterly, while Optical Character Recognition platforms linger in installed bases for decades. Image Processing and LPR Software occupy intermediate refresh positions.
- Deep Learning:Convolutional neural networks with dedicated tensor cores process plate capture through on-device inference. United States state transportation departments specify NPU-integrated cameras for new procurements as accuracy demands intensify in adverse weather scenarios.
- Optical Character Recognition:Rule-based pattern matching engines persist in legacy highway installations where capital replacement cycles resist premature disruption despite accuracy gaps against neural alternatives.
- Image Processing:Computational photography pipelines enhance raw sensor data through noise reduction and contrast optimization before character extraction.
- LPR Software:License plate recognition middleware manages database integration, alert generation, and audit logging across heterogeneous camera fleets.
Optical Character Recognition anchors the volume base while Deep Learning gains share at the steepest rate.
Application:
Cost tier differentiation separates capital-intensive infrastructure from operational expenditure models. Toll Collection commands premium system pricing while Parking Management competes on per-space economics.
- Toll Collection:Multi-lane free-flow systems demand sub-100 millisecond processing latency for revenue integrity at highway speeds. European operators under the EU AI Act risk-classification framework invest in explainable algorithm architectures ahead of enforcement deadlines.
- Traffic Management:Real-time congestion monitoring and signal optimization networks span metropolitan corridors with 24/7 operational requirements.
- Law Enforcement:Mobile patrol deployments prioritize flexible retrofit economics over fixed infrastructure commitments in fleet modernization programs.
- Parking Management:Entry-exit automation and enforcement citation systems serve commercial garages and municipal curb zones.
Toll Collection commands the highest unit values while Law Enforcement expands most quickly through mobile fleet programs.
End User:
Customer type segmentation separates sovereign procurement with extended compliance timelines from commercial operators with compressed decision cycles. Government Agencies navigate multi-year appropriation processes while Parking Operators execute quarterly capital plans.
- Government Agencies:National security and border control applications specify hardened systems with classified data handling protocols. The U.K. Home Office oversees national ANPR data retention standards through the National ANPR Service.
- Transportation Authorities:State and provincial road operators manage highway camera networks under performance-based maintenance contracts displacing capital purchase models.
- Private Security Firms:Corporate campus and critical facility access control drives demand for integrated video analytics platforms.
- Parking Operators:Commercial garage chains and municipal operators optimize for per-transaction processing costs across high-volume entry points.
Transportation Authorities anchor the volume base while Private Security Firms gain share at the steepest rate.
Installation:
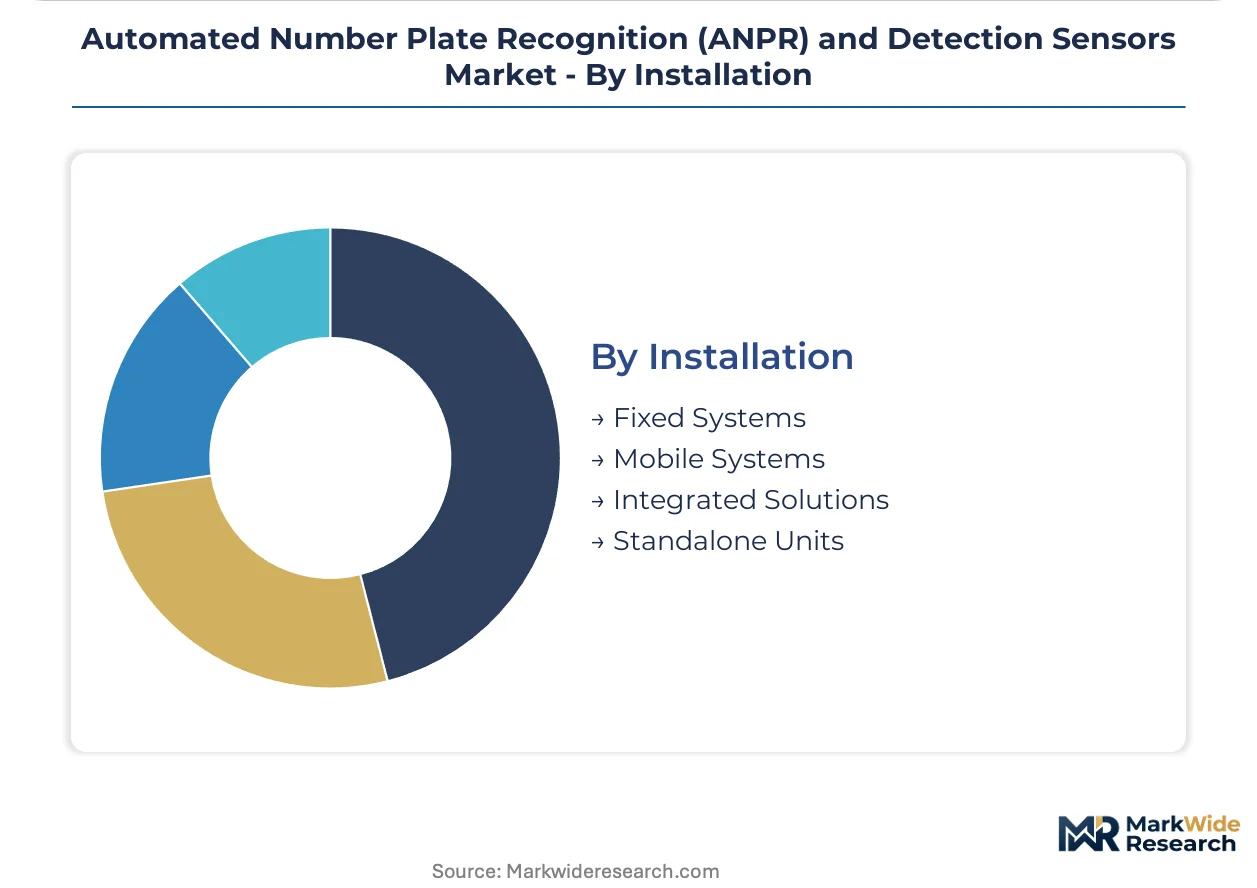
Supply concentration varies sharply between fixed infrastructure requiring civil works and mobile units leveraging existing vehicle platforms. Integrated Solutions demand systems engineering capabilities distinct from Standalone Unit distribution.
- Fixed Systems:Pole-mounted and gantry installations dominate highway and border applications with decade-long depreciation schedules. Australian state road authorities pilot availability-guarantee structures where vendors retain ownership and operational risk.
- Mobile Systems:Patrol vehicle retrofit programs favor flexible deployment economics and rapid relocation across enforcement jurisdictions.
- Integrated Solutions:Multi-sensor fusion architectures combine ANPR with vehicle classification, speed detection, and V2X communication modules.
- Standalone Units:Self-contained camera-illuminator-processor packages serve temporary deployments and private facility access points.
Fixed Systems anchor the volume base while Mobile Systems gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC equipment authorization governs radio-frequency components in United States ANPR hardware, while the EU AI Act imposes risk-classification requirements on automated biometric identification across European public spaces. Transportation authorities in multiple jurisdictions are expanding camera infrastructure for toll collection and traffic enforcement.
United States
Federal highway funding and municipal smart-city budgets sustain deployment momentum for fixed-system installations across interstate corridors. State transportation departments specify NPU-integrated cameras for new procurements under FCC equipment authorization timelines. The Southwest and Southeast corridors host the densest gantry installations for multi-lane free-flow tolling.
Germany
Kapsch TrafficCom AG anchors European tolling expertise through multi-lane free-flow systems on autobahn networks. The KBA oversees vehicle registration data standards that intersect with ANPR system interoperability requirements. Bavaria and Baden-Württemberg concentrate manufacturing clusters for ruggedized camera hardware serving harsh-climate installations.
United Kingdom
The Home Office oversees national ANPR data retention standards through the National ANPR Service. Expanded deployment across motorway networks and urban congestion zones is accelerating vendor investment in explainable algorithm architectures. Greater London and the Midlands corridor host the most extensive camera density for traffic enforcement applications.
India
Toll plaza automation mandates under the Bharatmala program create greenfield demand for multi-lane free-flow systems. The Ministry of Road Transport and Highways specifies FASTag integration requirements that drive ANPR procurement specifications. Maharashtra and Gujarat lead deployment velocity along the Delhi-Mumbai Industrial Corridor.
Australia
State road authorities pilot availability-guarantee structures where vendors retain ownership and operational risk under performance-based maintenance contracts. The TGA framework influences data handling protocols for cross-border vehicle recognition systems. New South Wales and Victoria concentrate the heaviest camera infrastructure for metropolitan congestion management.
Automated Number Plate Recognition (ANPR) and Detection Sensors Market Competitive Environment
Integrated video analytics specialists and ruggedized hardware fabricators split the market between software-defined accuracy and environmental durability. The vendor base concentrates around three strategic archetypes: semiconductor-integrated camera OEMs, tolling systems integrators with civil works capabilities, and edge-AI software platforms licensing inference engines. Dominant competitive moves include strategic partnerships between sensor manufacturers and neural processing unit suppliers, plus geographic expansion through performance-based maintenance contracts displacing capital purchase models.
Within the integrated platform tier, Hikvision and Axis Communications AB exemplify divergent approaches to video analytics convergence. Hikvision represents the vertically integrated Chinese model combining sensor fabrication with proprietary algorithm stacks. Axis Communications AB occupies a position within the Nordic design heritage for ruggedized hardware. Kapsch TrafficCom AG anchors the European tolling systems integrator archetype with multi-decade free-flow infrastructure expertise.
| Leading Market Players |
|---|
| Hikvision |
| Axis Communications AB |
| Siemens AG |
| Kapsch TrafficCom AG |
| Genetec Inc. |
| Motorola Solutions |
| Robert Bosch GmbH |
| Jenoptik AG |
| Adaptive Recognition Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in neural processing unit fabrication across Taiwan and South Korea is compressing supplier margins while amplifying pricing power for integrated camera OEMs that secured foundry allocation early. Transportation authorities with multi-year procurement horizons face cost escalation in edge-AI hardware tiers as capacity constraints propagate through semiconductor supply chains.
Pricing Analysis
Unit pricing spreads widest between North American municipal smart-city budgets and Indian greenfield highway deployments under the Bharatmala program. Three-tier pricing structure across premium deep-learning systems, standard OCR-based hardware, and economy retrofit packages separates procurement tiers. Cost compression in standard-tier fixed systems is intensifying because legacy optical substitution cycles resist acceleration despite neural-network accuracy advantages. Parking operators exhibit the sharpest price sensitivity per transaction, while national security agencies prioritize certification compliance over unit economics.
Supply Chain Analysis
Specialized infrared LED substrates and neural network processors draw from concentrated fabrication capacity in Taiwan, South Korea, and mainland China. Critical inputs span gallium arsenide wafers for illuminator arrays, high-sensitivity CMOS sensors, and tensor-core NPU silicon. Single-source vulnerability in East Asian foundry capacity exposes vendors to tariff exposure under evolving trade policy frameworks. Distribution runs through systems integrators with civil works capabilities for fixed highway installations, while mobile fleet retrofits channel through aftermarket automotive electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANPR and detection sensors sit in early-cycle expansion as edge-AI architectures displace rule-based optical systems across transportation authority procurement specifications. Deep learning penetration in adverse-weather accuracy requirements sustains replacement momentum despite legacy installed base inertia.
For Market Incumbents: Pre-empt margin erosion in standalone illumination modules by accelerating NPU-integrated camera platform development before semiconductor supply constraints ease. Secure multi-year foundry allocation agreements to defend against fabless entrant disruption in edge-AI tiers. Vertical integration into infrared LED substrate sourcing mitigates REACH compliance cost absorption in European tolling markets. For New Entrants and Emerging Players: Establish a beachhead in mobile law enforcement fleet retrofits where flexible deployment economics bypass fixed infrastructure incumbency. Target Australian and Canadian state road authorities piloting performance-based maintenance contracts with availability-guarantee structures. Lead with rapid-deployment standalone units that minimize civil engineering dependencies in emerging market greenfield installations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across deep-learning camera tiers as NPU integration requirements expand working capital needs for inventory-heavy semiconductor procurement. Acquisition candidates with embedded systems engineering capabilities for convolutional neural network optimization on resource-constrained devices represent the most defensible long-term positioning. Monitor FCC equipment authorization timeline extensions as a signal for product launch delays that could compress valuation multiples in hardware-heavy segments.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Platform Integration | NPU-integrated cameras collapse standalone illumination margins for Hikvision and Axis Communications. |
| Performance-Based Maintenance Contracts | Availability-guarantee structures transfer operational risk to Kapsch TrafficCom in Australian deployments. |
| Regulatory Compliance Investment | EU AI Act explainability requirements accelerate vendor R&D spend ahead of enforcement deadlines. |
| Geographic Expansion Through Civil Partnerships | Systems integrators with Bharatmala program relationships capture Indian greenfield toll automation demand. |
| Backward Integration into Sensor Fabrication | In-house CMOS and infrared LED production reduces REACH compliance vulnerability for European operators. |
Study Parameters
Operator-level perspectives from state transportation procurement officers, tolling systems integrators, edge-AI platform engineers, and municipal smart-city budget directors anchored the qualitative base. Primary interview findings triangulated against secondary sources including FCC equipment authorization filings, EU AI Act regulatory impact assessments, National ANPR Service data retention standards, and Bharatmala program procurement disclosures. Bottom-up segment sizing across technology, application, and installation dimensions converged with top-down macroeconomic elasticity checks.
Scenario-bracketing around semiconductor supply constraints and regulatory enforcement timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deep learning versus optical character recognition technology tiers, fixed versus mobile installation types, and sovereign versus commercial end-user categories. CAGRs derived from logistic diffusion curves for edge-AI substitution and infrastructure replacement cycle analysis. Forecast inputs incorporated neural network processor cost trajectories and transportation authority appropriation patterns.
Sensitivities concentrate around East Asian foundry capacity utilization, EU AI Act algorithmic accountability rule finalization, and federal highway funding appropriation volatility. Cross-checking against state DOT procurement database trends and tolling operator capex disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Pin and Sleeve Devices Market
Detection and Regulation Devices
Water Leak Detector Market
Detection and Regulation Devices
Compliance Monitoring Devices Market
Detection and Regulation Devices
Betavoltaic Device Market
Detection and Regulation Devices
Positive Temperature Coefficient (PTC) Thermistor Market
Detection and Regulation Devices
Leak Detection Equipment Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
Europe Trace Detection Market
Detection and Regulation Devices
Superconducting Detector Market
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
Gas Detectors Market
Detection and Regulation Devices
Signaling Devices Market
Detection and Regulation Devices
Radiometric Detectors Market
Detection and Regulation Devices
Global Surge Protection Devices Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market
Detection and Regulation Devices
Vapour Particle Barrier Market