
 Fixed and Mobile C-Arms Market | 2026-2036
Fixed and Mobile C-Arms Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed and Mobile C-Arms Market Intelligence
The FDA's 510(k) clearance pathway is hardening the cost-of-entry calculus for C-arm manufacturers seeking US market access. Siemens Healthineers leverages its installed base of angiography suites to cross-sell mobile C-arm configurations. GE Healthcare anchors its competitive stance through backward integration into X-ray tube manufacturing, reducing supplier dependency.
Fixed and mobile C-arms are articulated imaging systems with C-shaped gantries that rotate around the patient, typically housing flat-panel detectors capable of producing real-time fluoroscopic images at 30 frames per second for surgical guidance. Mobile C-arms lead volume demand due to their flexibility across operating rooms and lower capital commitment, while fixed systems command premium positioning in dedicated cardiac catheterization labs where 3D imaging integration creates higher margin pools. Digital imaging technology is displacing legacy analog fluoroscopy across both product categories, driven by dose reduction protocols and image storage requirements.
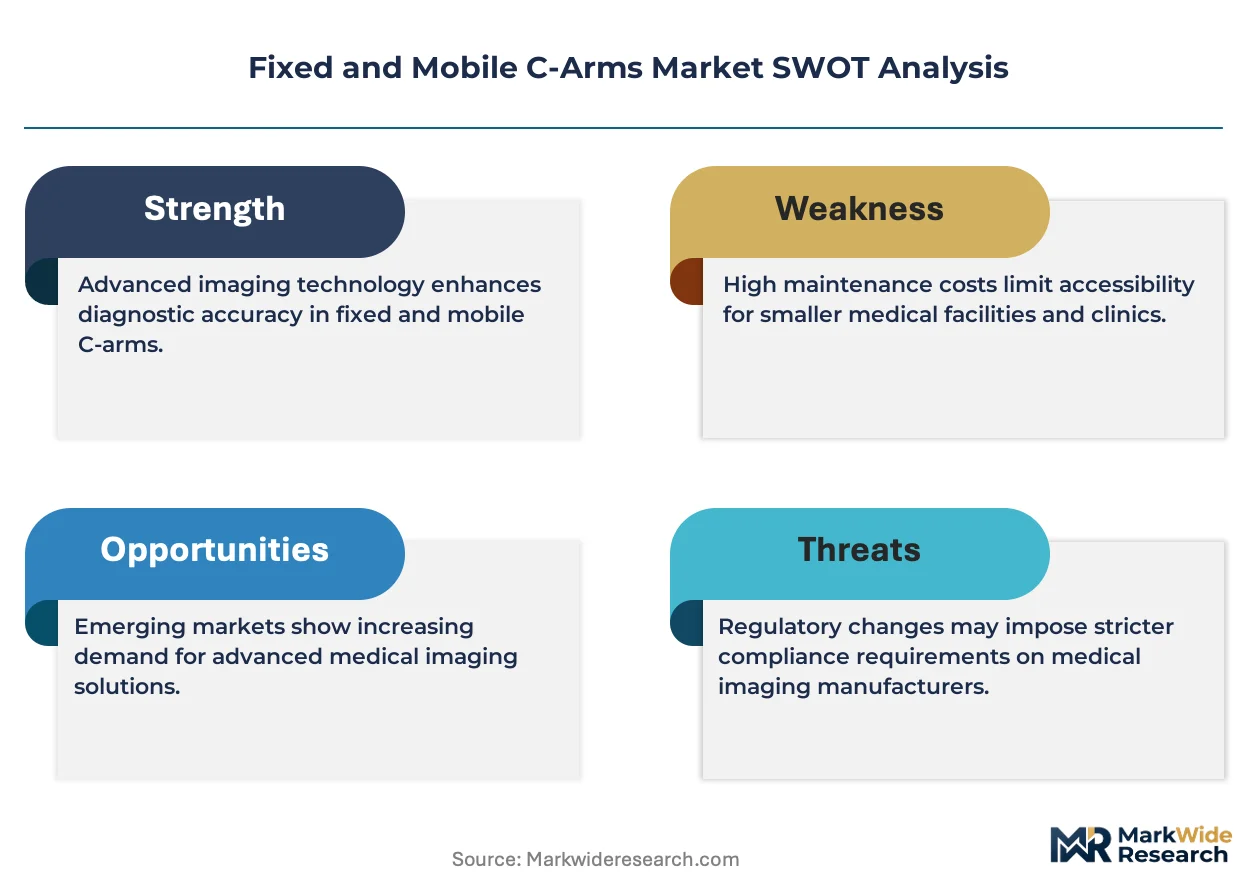
The FDA's Quality System Regulation shapes device manufacturing standards, while IEC 60601-1-3 governs radiation emission limits for international market access, and the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa imaging equipment. Stakeholders must monitor how evolving radiation dose tracking mandates reshape procurement criteria across hospital systems and ambulatory networks.
Market Dynamics
Digital flat-panel detector technology is compressing replacement cycles across installed C-arm bases while ambulatory surgical centers in the United States accelerate capital deployment for intraoperative imaging flexibility.
Growth Catalysts
- Orthopedic surgery expansion:Hospital systems are retrofitting operating rooms with mobile C-arms to support minimally invasive spine and joint procedures requiring real-time fluoroscopic guidance.
- FDA 510(k) pathway efficiency:The streamlined clearance mechanism for digital radiography devices is shortening time-to-market intervals for manufacturers introducing iterative detector upgrades.
- Flat-panel detector maturation:Solid-state digital sensors are displacing image intensifier tubes across mid-tier system configurations, enabling dose reduction protocols that satisfy hospital radiation safety committees.
Market Restraints
- X-ray tube supply concentration:Specialized vacuum tube manufacturing concentrates among a limited supplier base, creating vulnerability for original equipment manufacturers lacking backward integration into this component category.
- IEC 60601-1-3 compliance burden:International radiation emission testing requirements impose substantial certification costs and timeline uncertainty for market entry outside the United States.
- Fixed system capital intensity:Dedicated cardiac catheterization lab installations require infrastructure commitments that ambulatory surgical centers cannot absorb, constraining addressable market expansion.
Strategic Opportunities
- United States ASC penetration:Ambulatory surgical centers in Texas, Florida, and Arizona are upgrading fluoroscopy equipment at accelerated rates as case volume migrates from inpatient settings.
- 3D imaging integration:Cone-beam CT capability convergence with conventional C-arm fluoroscopy is creating premium positioning opportunities in neurosurgical and orthopedic navigation applications.
- EU MDR clinical evidence pathways:Stricter documentation requirements for Class IIa imaging equipment favor established manufacturers with robust post-market surveillance infrastructure.
Industry Challenges
- Medical physicist shortage:Radiation safety officer certification requirements outpace qualified personnel supply, delaying facility commissioning and operational startup timelines.
- Legacy system integration friction:Digital detector retrofits onto analog C-arm gantries frequently encounter mechanical incompatibility with aging positioner mechanics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed and Mobile C-Arms Market |
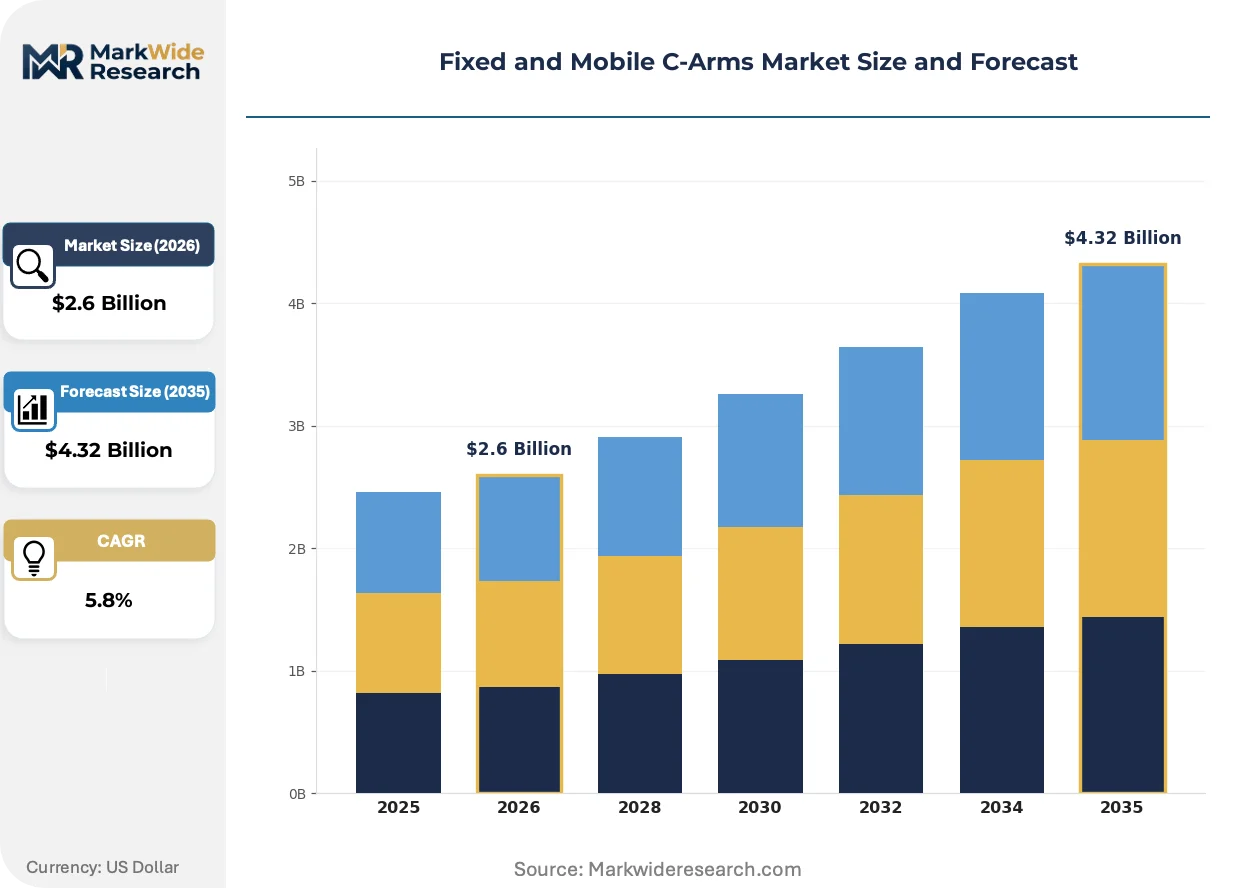
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.32 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed C-Arms, Mobile C-Arms, Mini C-Arms, Surgical C-Arms Technology: Fluoroscopy, 3D Imaging, Digital Imaging, Computed Radiography End User: Hospitals, Clinics, Ambulatory Surgical Centers, Diagnostic Imaging Centers Application: Orthopedic Surgery, Urology, Cardiology, Neurosurgery |
| Companies Covered | Ziehm Imaging GmbH, FUJIFILM Holdings Corporation, GE Healthcare, Hologic, Shimadzu Corporation, Siemens Healthineers, Canon Medical Systems, Medtronic, Koninklijke Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed and Mobile C-Arms Market Strategic Shifts & Innovations
Software-defined imaging workflows are displacing hardware-centric system architectures across the C-arm category. This shift enables remote serviceability and feature activation through license management rather than physical component swaps.
Flat-panel detector technology is modularizing C-arm system architecture. Solid-state digital sensors separate image acquisition from mechanical positioning subsystems. Hospital biomedical engineering departments are adopting field-replaceable detector modules to compress service turnaround intervals. This modularity is enabling third-party refurbishment channels to challenge original manufacturer service revenue streams.
The EU Medical Device Regulation is tightening clinical evidence requirements for Class IIa imaging equipment. Manufacturers must now submit post-market performance data for substantial equivalence determinations. Cardiac catheterization lab configurations face heightened scrutiny due to their role in high-risk interventional procedures. European notified bodies are extending review timelines, compressing product launch windows for iterative hardware releases.
Hospital capital committees are unbundling after-sales service contracts from equipment procurement. Purchasing departments now evaluate extended warranty and preventive maintenance agreements through competitive tender processes. Independent service organizations are capturing portions of the installed base support market. This unbundling is most pronounced in the United States, where health system consolidation creates centralized procurement leverage across multi-facility networks.
Fixed and Mobile C-Arms Market Segmentation
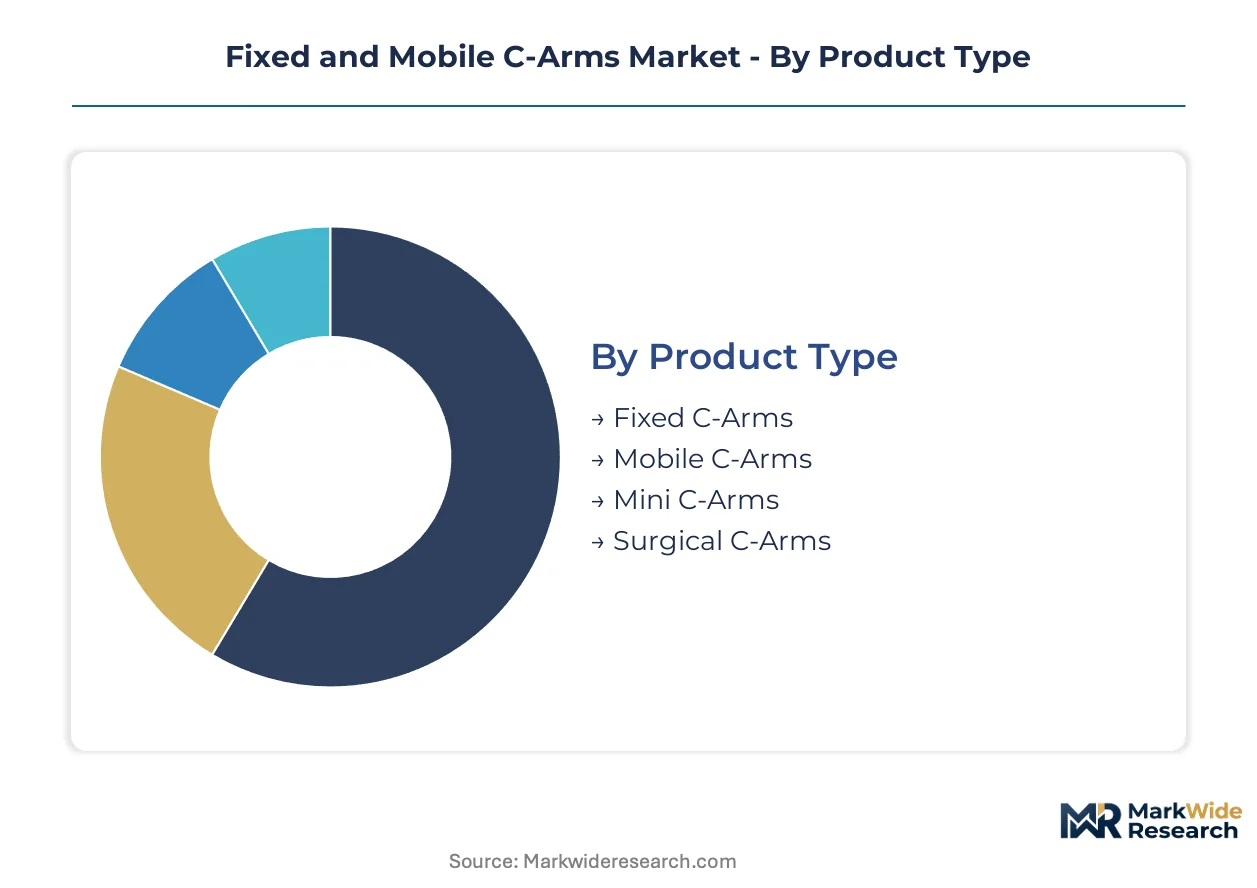
Hospital capital committees evaluate C-arm acquisitions through multiple lenses simultaneously. Product mobility, detector technology, procedural application, and facility type each reshape procurement criteria and margin structures for manufacturers.
Product Type:
Capital commitment thresholds and infrastructure requirements separate buyer segments across the installed base.
- Mobile C-Arms:Articulated C-shaped gantries on motorized bases enable intraoperative repositioning across multiple operating rooms. Ambulatory surgical centers in Texas, Florida, and Arizona prioritize these configurations for spine and joint procedure flexibility without dedicated lab infrastructure.
- Fixed C-Arms:Permanent ceiling-mounted or floor-fixed installations integrate with hemodynamic monitoring and contrast injection systems. Cardiac catheterization labs absorb these systems despite substantial construction commitments, driven by 3D rotational angiography requirements for complex interventional procedures.
- Mini C-Arms:Compact footprint systems target extremity imaging with reduced radiation output profiles. Orthopedic clinics deploy these for fracture reduction and hardware placement in outpatient settings.
- Surgical C-Arms:Hybrid configurations optimized for sterile field integration with extended lateral positioning range. Neurosurgical navigation suites specify these for cranial and spinal fusion guidance.
Volume sits with Mobile C-Arms; growth tilts toward Surgical C-Arms.
Technology:
Image acquisition architecture determines dose efficiency, storage compatibility, and service lifecycle economics.
- Digital Imaging:Solid-state flat-panel detectors capture direct radiographic signals without analog conversion stages. Hospital radiation safety committees mandate these systems for ALARA compliance and PACS integration.
- 3D Imaging:Cone-beam CT reconstruction from rotational fluoroscopic acquisitions generates volumetric datasets for surgical navigation. Neurosurgical and orthopedic applications drive premium positioning where intraoperative CT eliminates patient transfer.
- Fluoroscopy:Continuous X-ray beam pulsing at 15-30 frames per second enables real-time instrument tracking. Legacy image intensifier tubes persist in cost-constrained replacement cycles.
- Computed Radiography:Photostimulable phosphor plates bridge analog-to-digital workflows in transitional installations. Budget-limited clinics retain these for non-urgent extremity studies.
Deployment concentrates in Digital Imaging; capability expansion favors 3D Imaging.
End User:
Reimbursement environment and case volume density shape procurement authority and timing.
- Hospitals:Integrated delivery networks consolidate purchasing across cardiac catheterization labs, hybrid operating rooms, and emergency departments. Capital committees bundle C-arm acquisitions with enterprise PACS upgrades.
- Ambulatory Surgical Centers:Freestanding surgical facilities in the United States accelerate fluoroscopy equipment deployment as orthopedic and spine cases migrate from inpatient settings. Medicare reimbursement parity enables this infrastructure investment.
- Clinics:Physician-owned practices prioritize mini C-arm configurations for fracture care and sports medicine. Leasing structures predominate given limited capital reserves.
- Diagnostic Imaging Centers:Independent facilities concentrate on extremity and musculoskeletal studies with scheduled appointment workflows. Lower utilization rates extend replacement cycles versus acute care settings.
Revenue pools anchor in Hospitals; facility expansion concentrates in Ambulatory Surgical Centers.
Application:
Procedural complexity and imaging specificity requirements segment demand by clinical discipline.
- Orthopedic Surgery:Spine fusion, arthroplasty, and fracture fixation demand continuous fluoroscopic feedback for hardware placement accuracy. Minimally invasive approaches intensify real-time imaging dependence.
- Cardiology:Percutaneous coronary intervention and electrophysiology procedures require biplane or single-plane fixed systems with 3D roadmap integration. High-risk interventions elevate regulatory scrutiny for device performance documentation.
- Urology:Endourological stone extraction and stent placement utilize mobile C-arms with extended C-arm rotation for oblique renal access. Procedure volume concentrates in hospital-based suites.
- Neurosurgery:Spinal instrumentation and cranial navigation merge C-arm fluoroscopy with optical tracking systems. Cone-beam CT capability eliminates intraoperative patient transport to fixed CT suites.
Procedure volume concentrates in Orthopedic Surgery; technology premium commands in Neurosurgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in the United States and Germany concentrate C-arm manufacturing capacity and accelerate regulatory approvals for digital imaging systems.
United States
Ambulatory surgical centers in Texas, Florida, and Arizona drive mobile C-arm procurement as orthopedic cases migrate from inpatient settings. The FDA's 510(k) clearance pathway compresses time-to-market for manufacturers introducing iterative detector upgrades. Minneapolis-St. Paul anchors a cluster of imaging equipment engineering talent serving both domestic and export markets.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia prioritize 3D-capable fixed systems for cardiac catheterization lab modernization. The EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa imaging equipment, extending review timelines for notified bodies. Erlangen and Forchheim host concentrated medical imaging R&D operations with direct supply chain integration into European hospital networks.
Japan
Aging demographics and surgical volume expansion sustain replacement demand for mini C-arm configurations in orthopedic clinics. PMDA regulatory harmonization with IEC 60601-1-3 standards streamlines international certification for domestic manufacturers. Tokyo and Osaka metropolitan areas concentrate both production facilities and high-volume hospital procurement authority.
China
Domestic hospital construction programs in the Yangtze River Delta and Pearl River Delta absorb mid-tier mobile C-arm volumes. NMPA registration requirements for Class II medical devices mandate local clinical trials, creating barriers for non-domestic manufacturers. Shenzhen and Suzhou industrial parks host contract manufacturing operations serving both branded OEMs and emerging domestic competitors.
India
Private hospital chains in Maharashtra and Karnataka expand fluoroscopy capacity for spinal and trauma surgery. CDSCO medical device rules align with ISO 13485 quality management standards, though import licensing delays persist for finished systems. Mumbai and Bengaluru clusters concentrate both distribution logistics and biomedical engineering service capabilities.
Fixed and Mobile C-Arms Market Key Industry Players
German and Japanese producers anchor one tier; United States-based specialists hold differentiated positions in software-integrated configurations. The vendor base concentrates among diversified medical imaging conglomerates with captive X-ray tube supply chains and dedicated cardiovascular system portfolios. Three archetypes dominate: full-stack imaging conglomerates with angiography heritage, precision surgical navigation specialists, and regional equipment fabricators serving cost-constrained replacement cycles. M&A activity targets digital detector technology assets, while strategic partnerships with independent service organizations expand post-market revenue capture.
Among diversified imaging conglomerates, Siemens Healthineers and GE Healthcare exemplify full-stack positioning through backward integration into X-ray tube manufacturing and cross-selling leverage from installed angiography bases. Shimadzu Corporation occupies a specialist tier focused on precision fluoroscopy configurations for surgical navigation. Ziehm Imaging GmbH represents mid-market mobile system architecture optimized for orthopedic intraoperative flexibility.
| Leading Market Players |
|---|
| Ziehm Imaging GmbH |
| FUJIFILM Holdings Corporation |
| GE Healthcare |
| Hologic |
| Shimadzu Corporation |
| Siemens Healthineers |
| Canon Medical Systems |
| Medtronic |
| Koninklijke Philips |
| Others |
Cost & Logistics Intelligence
Radiation dose tracking mandates from the FDA and IEC 60601-1-3 compliance requirements gate qualified supply access for C-arm manufacturers, with premium-tier pricing reserved for systems demonstrating documented ALARA performance and seamless PACS integration.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent procurement from planned replacement cycles, with hospitals paying premiums for sub-90-day delivery while spot inventory from distributors trades at modest discounts. Three-tier pricing structure across premium, standard, and economy levels reflects detector technology generation, FDA 510(k) clearance status, and bundled service contract duration. Pricing pressure stems from health system consolidation creating centralized procurement leverage across multi-facility networks. Ambulatory surgical centers exhibit highest price sensitivity due to constrained capital reserves, while integrated delivery networks prioritize total cost-of-ownership over acquisition price.
Supply Chain Analysis
Workforce availability constraints in Germany, Japan, and the United States limit specialized vacuum tube manufacturing capacity, compressing output from X-ray tube foundries serving tier-one imaging conglomerates. Component sourcing draws from concentrated flat-panel detector fabrication in South Korea and Japan, precision motion control systems from German industrial automation suppliers, and high-voltage power electronics from domestic US producers. Single-source vulnerability around specialized image intensifier tube remnants creates disruption risk for mid-tier system configurations. Distribution runs through direct manufacturer sales forces for hospital capital committees, with independent service organizations capturing aftermarket parts and refurbishment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over X-ray tube manufacturing and digital detector supply determines margin sustainability and procurement committee access.
For Market Incumbents: Anticipate independent service organization encroachment by expanding field-replaceable detector module programs and software-defined feature activation licensing. Siemens Healthineers and GE Healthcare should deepen backward integration into solid-state sensor fabrication to neutralize third-party refurbishment threats and capture recurring revenue streams from installed base upgrades. For New Entrants and Emerging Players: Enter via ambulatory surgical center networks in Texas, Florida, and Arizona where Medicare reimbursement parity enables infrastructure investment without integrated delivery network procurement dominance. Target mini C-arm configurations for orthopedic clinics with leasing structures that overcome capital reserve limitations, leveraging cone-beam CT capability gaps in cost-constrained replacement cycles. For Investors and Strategic Acquirers: FDA 510(k) clearance timeline compression for digital radiography devices is the leading indicator that regulatory pathway efficiency will favor established manufacturers with robust quality management infrastructure. Long-term viability centers on acquisition targets possessing captive X-ray tube supply or software-integrated surgical navigation platforms, with post-market surveillance data assets becoming the decisive valuation differentiator under EU MDR requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into X-ray Tube Manufacturing | Siemens Healthineers and GE Healthcare reduce supplier dependency while securing margin pools in replacement cycles. |
| FDA 510(k) Digital Radiography Pathway Optimization | Streamlined clearance mechanisms compress time-to-market for iterative detector upgrades and software releases. |
| Ambulatory Surgical Center Direct Sales Expansion | Texas, Florida, and Arizona facility networks offer procurement access outside consolidated health system structures. |
| Software-Defined Imaging Workflow Development | Remote serviceability and license-based feature activation displace hardware-centric revenue models. |
| EU MDR Post-Market Surveillance Infrastructure Buildout | Clinical evidence requirements for Class IIa imaging equipment favor manufacturers with robust documentation systems. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hospital purchasing committee chairs, biomedical engineering directors, ambulatory surgical center administrators, GPO contracts managers, and medical physicists responsible for radiation safety officer certification. FDA 510(k) clearance databases, IEC 60601-1-3 test house reports, EU notified body documentation, and hospital procurement platform records provided quantitative validation. Bottom-up demand modeling from installed base replacement cycles and top-down market sizing from manufacturer revenue disclosures were reconciled through iterative triangulation.
Data-stream reconciliation across shipment records, capital expenditure disclosures, and health system procurement announcements informed the analytical framework. Segmentation dimensions included product mobility tier, detector technology generation, procedural application specialty, and facility type reimbursement environment. CAGRs were derived from logistic diffusion curves fitted to replacement cycle acceleration patterns and ambulatory surgical center penetration trajectories. Flat-panel detector cost curves and X-ray tube foundry capacity utilization served as industry-specific forecast inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged medical physicist shortages or abrupt EU MDR review timeline extensions. Forecasts reflect documented assumptions regarding Medicare reimbursement parity sustainability and orthopedic case migration velocity from inpatient to ambulatory settings. Supply chain disruption from specialized vacuum tube manufacturing concentration and radiation dose tracking mandate implementation delays warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Diagnostic Catheter Market
Medical Devices
Cervical Retractors Market
Medical Devices
Global Photomedicine Market
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
Bare Metal Stents Market
Medical Devices
Global Microcatheter Market
Medical Devices
Tubal Obstruction Devices Market
Medical Devices
China Electrocardiograph (ECG) Market
Medical Devices
GCC Implantable Medical Devices Market
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
Intravascular Warming Systems Market
Medical Devices
Global Foley Catheters Market
Medical Devices
Anti-Fatigue Lenses Market
Medical Devices
Bariatric Beds Market
Medical Devices
Pleural Catheters Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market