
 Global Photomedicine Market | 2026-2036
Global Photomedicine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Photomedicine Market Intelligence
The historical division between dermatology and aesthetic medicine training is unwinding, creating a new cohort of practitioners skilled in photomedicine. This convergence supports broader device adoption in both medical and cosmetic centers. Candela Medical specializes in aesthetic laser systems for this combined market, while Koninklijke Philips leverages its broad healthcare technology portfolio. Lumenis differentiates through its focus on minimally invasive clinical solutions across ophthalmology, surgery, and aesthetics.
Photomedicine involves the application of light, typically within specific non-ionizing wavelengths from ultraviolet to infrared, for therapeutic or diagnostic purposes. The practice relies on precisely controlling energy delivery to target cells or tissues, which triggers specific photochemical or photothermal responses. Within applications, dermatology remains the largest segment, addressing conditions from acne to skin cancer. However, pain management applications utilizing low-level laser therapy represent the fastest-growing technology segment.
Regulatory frameworks from the US FDA and China's NMPA dictate stringent pre-market approval pathways for new photomedicine devices. The EU's Medical Device Regulation (MDR) imposes rigorous post-market surveillance and clinical evidence requirements. Navigating these varied international standards for device classification and efficacy validation remains a key challenge for manufacturers. Success depends on developing technology platforms adaptable to diverse regional regulatory demands.
Market Dynamics
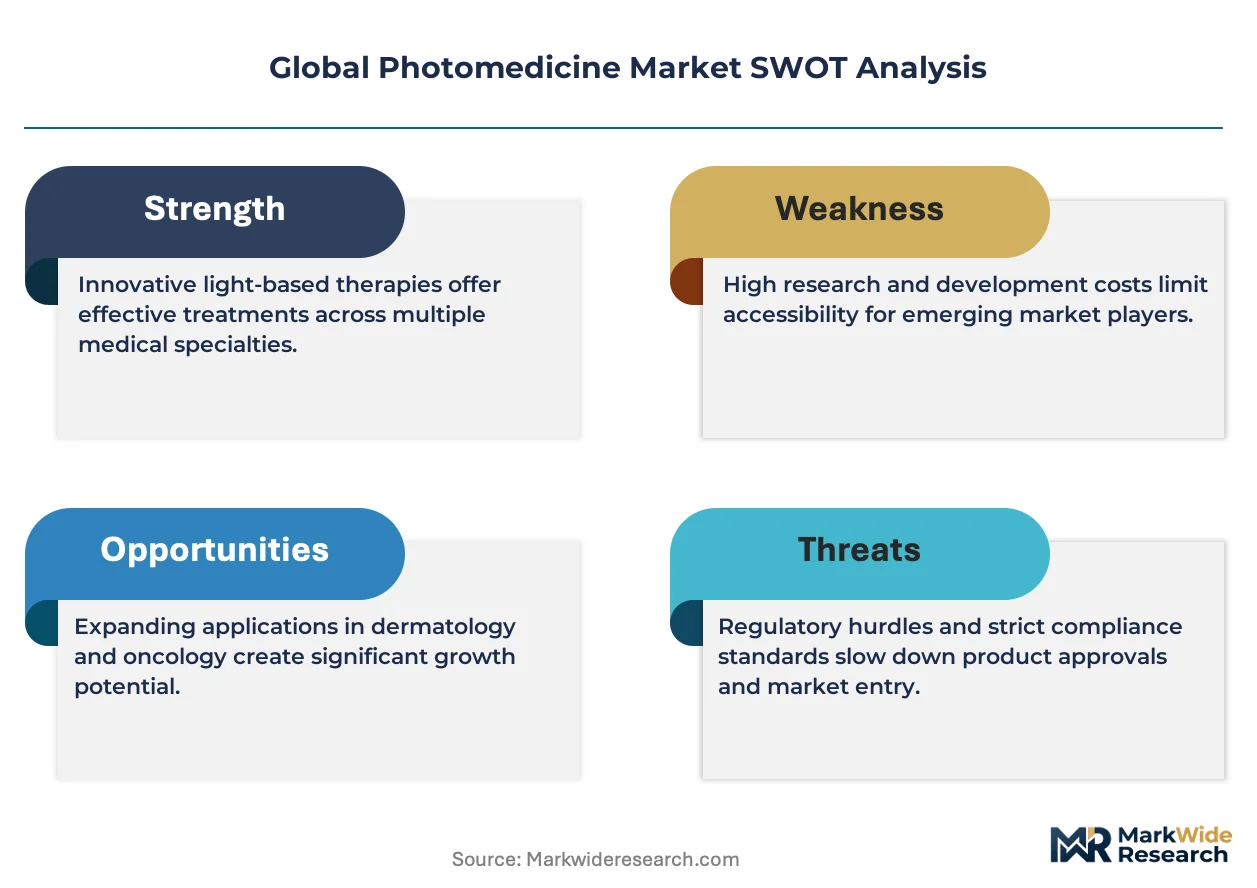
The convergence of stringent regulatory oversight and expanding clinical applications defines the photomedicine market's core dynamic. Heightened requirements from the EU's Medical Device Regulation (MDR) and the US FDA are forcing greater investment in clinical validation for all device classes.
Growth Catalysts
- Expanding Clinical Applications:The use of low-level laser therapy (LLLT) is expanding beyond dermatology into new therapeutic areas like musculoskeletal pain management and wound healing, creating new demand streams within hospital and physical therapy settings.
- Practitioner Skill Convergence:A merging of dermatology and aesthetic medicine training programs is producing a new generation of clinicians skilled in photomedicine, accelerating device adoption across both specialized medical clinics and cosmetic centers.
- Chronic Disease Management:An increasing prevalence of chronic skin conditions such as psoriasis and vitiligo, particularly in developed regions like North America and Europe, sustains consistent demand for effective, non-pharmacological treatment options.
Market Restraints
- High Device Costs:The significant capital investment required for advanced laser and intense pulsed light (IPL) systems acts as a barrier to entry for smaller private practices and clinics in emerging economies, limiting market penetration.
- Complex Regulatory Pathways:Navigating the divergent pre-market approval and post-market surveillance standards of regulators like the US FDA, China's NMPA, and European authorities under MDR creates significant compliance costs and lengthens time-to-market.
- Risk of Side Effects:The potential for adverse effects, including burns, scarring, or pigmentation changes from improper device use or patient selection, creates clinical risk and can lead to patient apprehension, constraining adoption rates.
Strategic Opportunities
- Home-Use Devices:The development of safe, effective, and FDA-cleared or CE-marked phototherapy devices for at-home use represents a significant opportunity to address the consumer market for conditions like acne, hair loss, and anti-aging.
- Oncology and Photodynamic Therapy:Advancements in photosensitizing agents are opening new avenues for photodynamic therapy (PDT) in treating certain types of cancer, offering a targeted treatment modality with fewer systemic side effects.
- Emerging Market Penetration:Untapped demand in regions such as Latin America and Southeast Asia, where healthcare spending and awareness of aesthetic procedures are rising, offers long-term growth potential for manufacturers able to navigate local distribution.
Industry Challenges
- Practitioner Training Gap:A persistent shortage of technicians and clinicians with specialized training on the safe and effective operation of sophisticated photomedicine equipment presents an operational hurdle to widespread adoption and consistent outcomes.
- Clinical Evidence Generation:Meeting the rigorous clinical data requirements mandated by frameworks like the EU's MDR for demonstrating device efficacy and safety demands substantial, long-term investment in clinical trials for manufacturers.
- Lack of Treatment Standardization:The absence of universally accepted treatment protocols for many conditions leads to variability in clinical outcomes, complicating efforts to establish clear efficacy benchmarks and secure reimbursement from payors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Photomedicine Market |
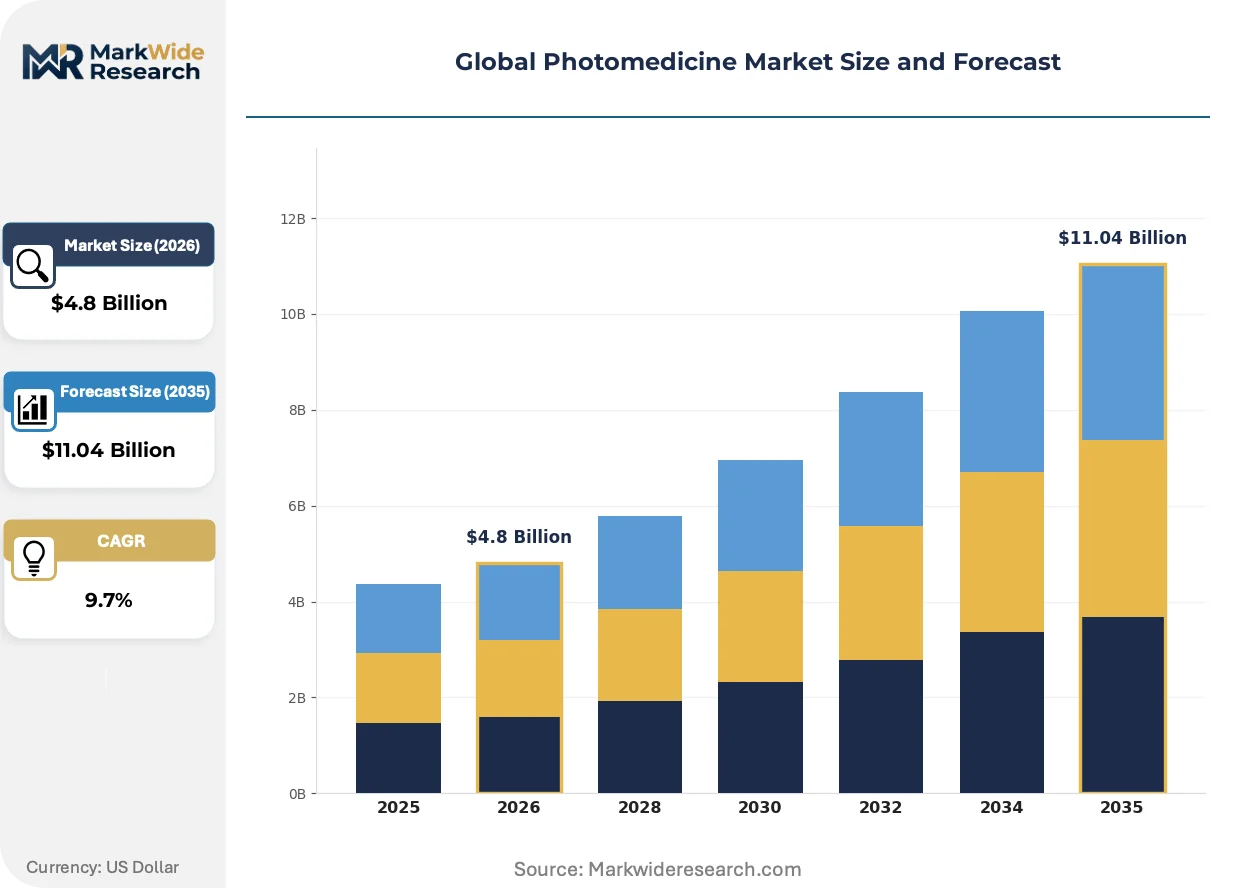
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photodynamic Therapy Devices, Light Emitting Diodes, Laser Systems, Ultraviolet Lamps, Infrared Emitters Application: Dermatology, Wound Healing, Pain Management, Oncology, Dentistry End User: Hospitals, Specialized Clinics, Research Institutes, Cosmetic Centers Technology: Low-Level Laser Therapy, Intense Pulsed Light, Ultraviolet Phototherapy, Near-Infrared Photobiomodulation |
| Companies Covered | Candela Medical, THOR Photomedicine, Koninklijke Philips, Lumibird Group, PhotoMedex, Lumenis, Alma Lasers, IRIDEX Corporation, Sisram Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Photomedicine Market Strategic Shifts & Innovations
Precision and accessibility are the primary forces shaping product innovation. Technology is evolving to deliver highly targeted energy with minimal collateral tissue effects, while new form factors are making phototherapy accessible beyond specialized hospital departments into smaller clinics and homes.
Solid-state light sources like light-emitting diodes (LEDs) and diode lasers provide highly specific wavelengths for targeted photobiomodulation. Aesthetic clinics and dermatology practices are the primary adopters of these systems for their reliability and compact size. This technology is miniaturizing the form factor of therapeutic systems, enabling the creation of wearable and handheld devices for managing chronic conditions like acne or pain.
The European Union's Medical Device Regulation (MDR) is setting a new global benchmark for device safety and performance. This regulation imposes stricter requirements for clinical evidence and post-market surveillance, impacting all devices sold in the EU. Manufacturers of both aesthetic and medical photomedicine systems are most affected, now needing to fund more extensive clinical studies to maintain their CE marking.
Patient demand is shifting toward non-invasive treatments that offer clinical efficacy with minimal recovery time. This behavioral change is displacing more aggressive procedures in aesthetics and dermatology in favor of light-based therapies. The trend is most visible in North American and European markets, where patient procurement decisions for cosmetic procedures are heavily influenced by the desire to avoid surgical intervention and associated downtime.
Global Photomedicine Market Segmentation
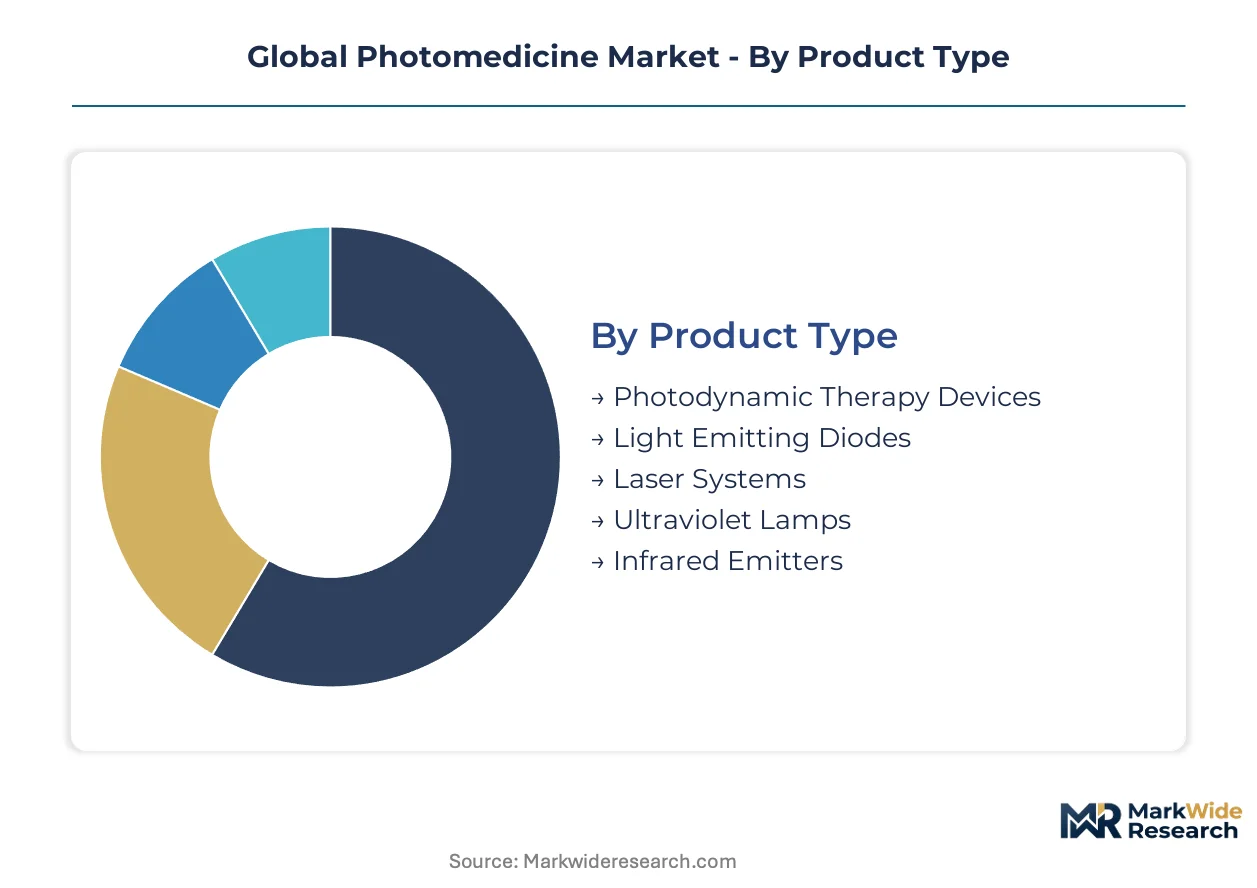
The photomedicine market's segmentation reveals distinct demand patterns and technological preferences across various end-use environments. Understanding these divisions helps manufacturers tailor product development and regulatory strategies for diverse clinical applications. Each segment reflects unique requirements for device efficacy, safety, and operational integration.
Product Type:
The geographic spread of product types often depends on regional healthcare infrastructure and regulatory maturity. Advanced laser systems see higher adoption in developed markets like the United States and Germany, while more accessible ultraviolet lamps maintain presence in broader global contexts.
- Laser Systems:These devices generate highly coherent, monochromatic light, allowing for precise energy delivery to target tissues. Demand concentrates in specialized clinics and cosmetic centers across North America and Western Europe due to their versatility in aesthetic and dermatological procedures.
- Photodynamic Therapy Devices:These systems utilize specific light wavelengths to activate photosensitizing agents within diseased cells, primarily for oncology applications. Their adoption expands in advanced healthcare systems in Japan and France, driven by the search for targeted cancer treatments with reduced systemic side effects.
- Light Emitting Diodes:LEDs provide specific non-coherent light wavelengths for applications like photobiomodulation and skin rejuvenation. These find widespread use in home-use devices and smaller aesthetic practices.
- Ultraviolet Lamps:These devices emit UV radiation for treating chronic skin conditions such as psoriasis and vitiligo. They remain a standard treatment modality in dermatology clinics globally.
- Infrared Emitters:Infrared light sources are used for therapeutic heating and pain management applications. Their utility extends to physical therapy clinics and sports medicine centers.
Ultraviolet Lamps commands the established base. The steepest expansion runs through Photodynamic Therapy Devices.
Application:
The market's application segments vary significantly in their maturity and established clinical protocols. Dermatology represents a long-standing application with well-defined treatment pathways, while oncology applications are still emerging with new photosensitizing agents.
- Dermatology:This segment includes treatments for chronic skin conditions, acne, and aesthetic procedures using light-based therapies. Demand remains consistently high in North America and Europe, supported by a strong clinical evidence base and patient preference for non-invasive options.
- Pain Management:Applications here involve low-level laser therapy (LLLT) to reduce inflammation and accelerate tissue repair for musculoskeletal conditions. This segment is expanding rapidly in physical therapy clinics in countries like Canada and Australia, driven by non-pharmacological treatment trends.
- Wound Healing:Photomedicine aids in tissue regeneration and infection control for various types of wounds. Hospitals and specialized wound care centers increasingly integrate these therapies.
- Oncology:Photodynamic therapy offers a targeted approach for certain cancers, particularly superficial tumors. Research institutes and specialized cancer centers are driving advancements in this area.
- Dentistry:Light-based technologies are used for teeth whitening, curing dental resins, and treating oral lesions. Dental clinics worldwide integrate these efficient tools into daily practice.
Dermatology applications maintain the largest established volume. Pain Management applications are climbing the fastest.
End User:
End-user segments reflect different procurement scales and operational complexities for photomedicine devices. Hospitals require robust, multi-application systems, while specialized clinics prioritize specific, high-throughput devices.
- Hospitals:These large institutions integrate photomedicine devices across multiple departments, including dermatology, surgery, and physical therapy. Their procurement decisions emphasize device versatility and long-term service contracts.
- Specialized Clinics:This category includes dermatology clinics, pain management centers, and aesthetic practices that focus on specific photomedicine treatments. High adoption rates exist in the United States and Germany, driven by patient demand for targeted therapies.
- Research Institutes:These entities focus on developing new photomedicine applications and improving existing technologies. Their demand centers on advanced and experimental light sources for clinical trials.
- Cosmetic Centers:These facilities primarily use photomedicine for aesthetic procedures like hair removal, skin rejuvenation, and tattoo removal. They often prioritize devices with high patient satisfaction and minimal downtime.
Hospitals represent the foundational end-user segment. Specialized Clinics are expanding their device portfolios most quickly.
Technology:
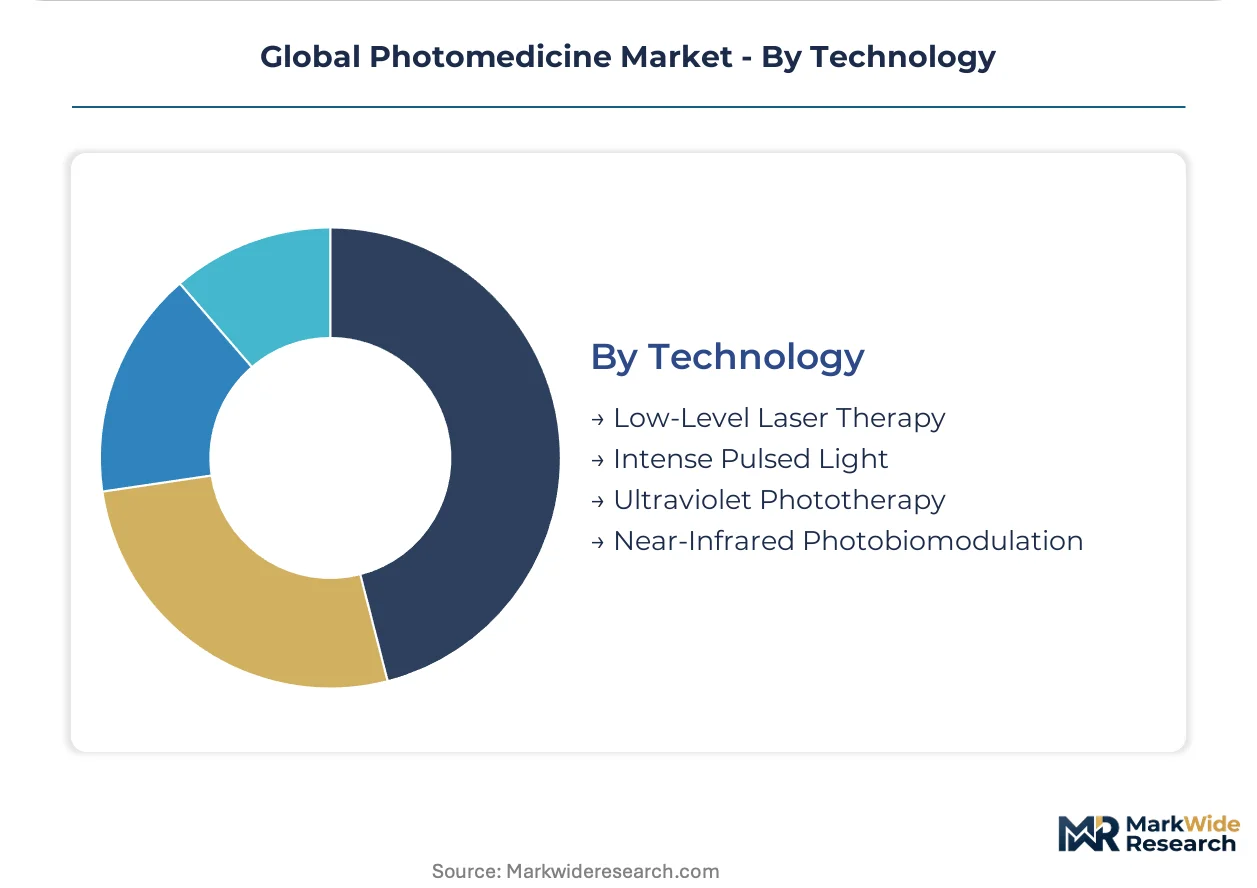
The technology segment showcases the diverse mechanisms by which light interacts with biological tissues. Low-Level Laser Therapy (LLLT) focuses on stimulating cellular function, while Intense Pulsed Light (IPL) targets chromophores for aesthetic effects.
- Low-Level Laser Therapy:LLLT utilizes non-thermal light to stimulate cellular function, reduce inflammation, and alleviate pain. Its expanding clinical applications in musculoskeletal pain management and wound healing drive demand in physical therapy centers globally.
- Intense Pulsed Light:IPL systems emit broad-spectrum light, targeting specific chromophores in the skin for hair removal, vascular lesions, and pigmentation issues. Aesthetic clinics in the United Kingdom and Canada extensively use these versatile devices.
- Ultraviolet Phototherapy:This technology employs specific UV wavelengths for treating chronic dermatological conditions. Dermatology practices widely adopt these systems for their proven efficacy.
- Near-Infrared Photobiomodulation:NIR light penetrates deeper into tissues, supporting applications in pain relief and muscle recovery. Sports medicine and rehabilitation clinics increasingly utilize this technology.
Ultraviolet Phototherapy holds a significant established base. Low-Level Laser Therapy exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US FDA's stringent regulatory oversight significantly influences photomedicine market development, particularly in North America. This regulatory environment drives innovation in device safety and efficacy, establishing a benchmark for global manufacturers. Demand concentration in the United States reflects high adoption rates within specialized clinics and major hospital networks.
United States
Photomedicine demand in the United States stems from a high prevalence of chronic skin conditions and a strong aesthetic market. The US FDA mandates rigorous pre-market approval for all medical devices, ensuring high safety and efficacy standards. Major medical technology clusters in California and Massachusetts actively develop advanced photomedicine systems.
Germany
Germany's photomedicine market benefits from a well-established healthcare infrastructure and a strong emphasis on non-invasive therapies. The EU's Medical Device Regulation (MDR) imposes strict post-market surveillance requirements, influencing device design and clinical validation. Munich and Berlin serve as key centers for medical device innovation and specialized dermatology clinics.
Japan
Japan exhibits a growing demand for photodynamic therapy devices, driven by advancements in oncology treatments and an aging population. The PMDA regulates medical devices, focusing on clinical evidence and patient safety for market entry. Major research institutions in Tokyo and Osaka are at the forefront of photomedicine research and development.
China
China's photomedicine market expands due to rising healthcare spending and a growing consumer interest in aesthetic procedures. The NMPA implements a comprehensive regulatory framework for medical devices, including pre-market approval and post-market oversight. Shanghai and Shenzhen host significant manufacturing bases and research hubs for medical technology.
Canada
Canada's market for photomedicine, particularly low-level laser therapy, is expanding within physical therapy and pain management clinics. Health Canada oversees medical device licensing, emphasizing safety and clinical effectiveness. Toronto and Vancouver are emerging as centers for specialized aesthetic practices and rehabilitation facilities utilizing light-based therapies.
Global Photomedicine Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the photomedicine market. This structure combines established healthcare technology giants with focused innovators. Strategic archetypes include diversified healthcare conglomerates, specialized aesthetic device manufacturers, and niche therapeutic solution providers. Dominant competitive moves involve technology licensing and portfolio diversification to capture new application areas.
Specialists in aesthetic and therapeutic light systems, Candela Medical and Lumenis, exemplify focused market penetration. Candela Medical concentrates on advanced laser systems for dermatology and aesthetics, while Lumenis differentiates through minimally invasive clinical solutions across ophthalmology, surgery, and aesthetics. Koninklijke Philips, a broader healthcare technology provider, leverages its extensive portfolio to integrate photomedicine into comprehensive health solutions, anchoring the market's diversified segment.
| Leading Market Players |
|---|
| Candela Medical |
| THOR Photomedicine |
| Koninklijke Philips |
| Lumibird Group |
| PhotoMedex |
| Lumenis |
| Alma Lasers |
| IRIDEX Corporation |
| Sisram Medical |
| Others |
Cost & Logistics Intelligence
Economies of scale in advanced manufacturing of photomedicine devices concentrate production capability, which directly influences pricing power and establishes price floors across key product categories. This concentration creates a dependency on specialized component suppliers and regulatory pathways for market access.
Pricing Analysis
Geographic price spreads for photomedicine devices reflect varying market maturity and regulatory burdens. Value-based pricing dominates for advanced laser systems, while per-unit transactional models apply to consumables and simpler LED devices. Price differentiation stems from device certification level, such as FDA or CE marking, and the breadth of after-sales service bundles. Pricing pressure intensifies for entry-level devices due to rising competition and manufacturing efficiencies. Smaller private practices in emerging economies exhibit the highest price sensitivity for photomedicine equipment.
Supply Chain Analysis
Long lead times for specialized optical components and high-power laser diodes necessitate careful inventory management within the photomedicine supply chain. Geographic supply concentration for these critical components centers on countries like Germany, the United States, and China. Raw material dependencies include rare earth elements for certain light sources and photosensitizing agents for photodynamic therapy. A key supply chain risk is regulatory restriction on component exports, impacting global device availability. Distribution runs through a combination of direct sales forces for hospitals and specialized clinics, alongside regional distributors for smaller practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The photomedicine market presents a capability scarcity, particularly in specialized practitioner training for advanced devices. Bridging this gap is crucial for wider adoption and consistent treatment outcomes.
For Market Incumbents:
Compound investment in clinical validation, especially for new applications under the EU MDR, to reinforce market leadership and differentiate from emerging competitors. Acquire specialized component manufacturers to secure critical supply chains and mitigate single-source vulnerabilities. Focus R&D on next-generation solid-state light sources for improved efficacy and reduced form factor. Pursue strategic partnerships with large hospital networks to ensure long-term service contracts and device integration.
For New Entrants and Emerging Players:
FDA 510(k) clearance pathways offer a certification fast-track for certain low-risk photomedicine devices, enabling quicker market entry. Target the home-use device segment for conditions like acne or hair loss, leveraging direct-to-consumer marketing strategies. Penetrate emerging markets such as Latin America and Southeast Asia with cost-effective, clinically validated solutions. Focus on specific pain management applications using LLLT, partnering with established physical therapy chains for distribution.
For Investors and Strategic Acquirers:
Recurring-revenue conversion is highest among manufacturers offering consumables and service contracts for their devices. The market offers long-term viability, driven by persistent demand for non-invasive therapies for chronic conditions and aesthetic procedures. Target niche therapeutic solution providers with strong intellectual property and established regulatory approvals in specific application areas like photodynamic therapy. Watch for expanding reimbursement coverage for low-level laser therapy as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Optimization | Streamlines market access in Europe, reducing time-to-market for medical photomedicine devices. |
| Clinical Trial Advancement for PDT | Expands treatment indications for photodynamic therapy, addressing unmet oncology needs. |
| Channel Expansion into Physical Therapy | Increases adoption of low-level laser therapy devices in musculoskeletal pain management. |
| Home-Use Device Product Launch | Captures consumer demand for accessible phototherapy solutions for dermatological conditions. |
| Technology Licensing for Advanced Optics | Secures access to proprietary light source components, enhancing device performance. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research. Primary research involved in-depth conversations with clinicians, R&D directors, regulatory affairs specialists, and hospital procurement managers. Secondary data sources included FDA filings, NMPA reports, EU MDR guidance documents, and medical device company financial statements. This approach ensured a robust bottom-up and top-down triangulation of market size and growth projections.
The forecasting framework projects market dynamics across the analysis window through a combination of demand-side and supply-side modeling. Segmentation dimensions modeled include product type, application, end user, technology, and regional regulatory environment. Compound annual growth rates were derived from historical trends, identified market drivers, and expert consensus. Key industry-specific forecast inputs included chronic skin disease prevalence rates and medical device approval rates by region.
Decision-makers should treat outputs as directional under base assumptions regarding regulatory stability and technological advancement; material deviation would warrant model refresh. Unforeseen changes in reimbursement policies or the emergence of disruptive competitive therapies represent specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Internal Neuromodulation Devices Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Europe Minimally Invasive Surgery Devices Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Lactation Massager Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Artificial Pancreas Market
Medical Devices
Global Abdominal Surgical Robot Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
Auto Keratometer Market
Medical Devices
Global Medical Device Connectors Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Global Nebulizers Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
Global Electronic Drug Delivery Systems Market