
 Tubal Obstruction Devices Market | 2026-2036
Tubal Obstruction Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Tubal Obstruction Devices Market Analytics
Hospital procurement consortiums in North America and Western Europe is reconfiguring how tubal obstruction devices reach surgical suites, with centralized purchasing now governing a rising share of gynecology spend. Boston Scientific Corporation leverages its broad interventional portfolio to sustain direct contracts with integrated delivery networks across multiple states. Medtronic anchors its position through dedicated sales infrastructure serving academic medical centers with high-volume fertility programs. Cook Group specializes in custom catheter configurations that differentiate its offerings within teaching hospital channels.
Tubal obstruction devices are implantable or insertable medical instruments designed to block, bypass, or restore patency within the fallopian tubes, typically constructed from biocompatible polymers, nickel-titanium alloys, or silicone composites with diameters ranging from 1.2 to 3.0 millimeters for hysteroscopic delivery. These devices serve primary clinical purposes spanning permanent contraception, infertility treatment via tubal cannulation, and management of ectopic pregnancy complications. Hysteroscopic adhesiolysis systems currently occupy the largest revenue pool within device type segmentation due to their established reimbursement in hospital outpatient departments. Minimally invasive surgery technology leads procedural volume growth as ambulatory surgical centers expand their gynecology service lines, while robotic surgery platforms concentrate in premium-tier fertility centers where capital equipment investments justify higher per-procedure economics. Endometrial ablation devices represent a mature segment with slower expansion but stable replacement demand across community hospital settings.
The FDA maintains stringent premarket submission requirements for permanent tubal implants under its obstetrics and gynecology device classification, while the EU Medical Device Regulation imposes enhanced clinical evidence standards for Class III implantable products entering European markets. ISO 10993 biocompatibility testing protocols govern material safety assessments across all major regulatory jurisdictions, directly influencing manufacturer R&D timelines and commercialization costs. Stakeholders must monitor evolving FDA guidance on post-market surveillance for permanent contraceptive devices, as emerging safety signals could trigger labeling changes or restricted use determinations that reshape competitive positioning among established suppliers.
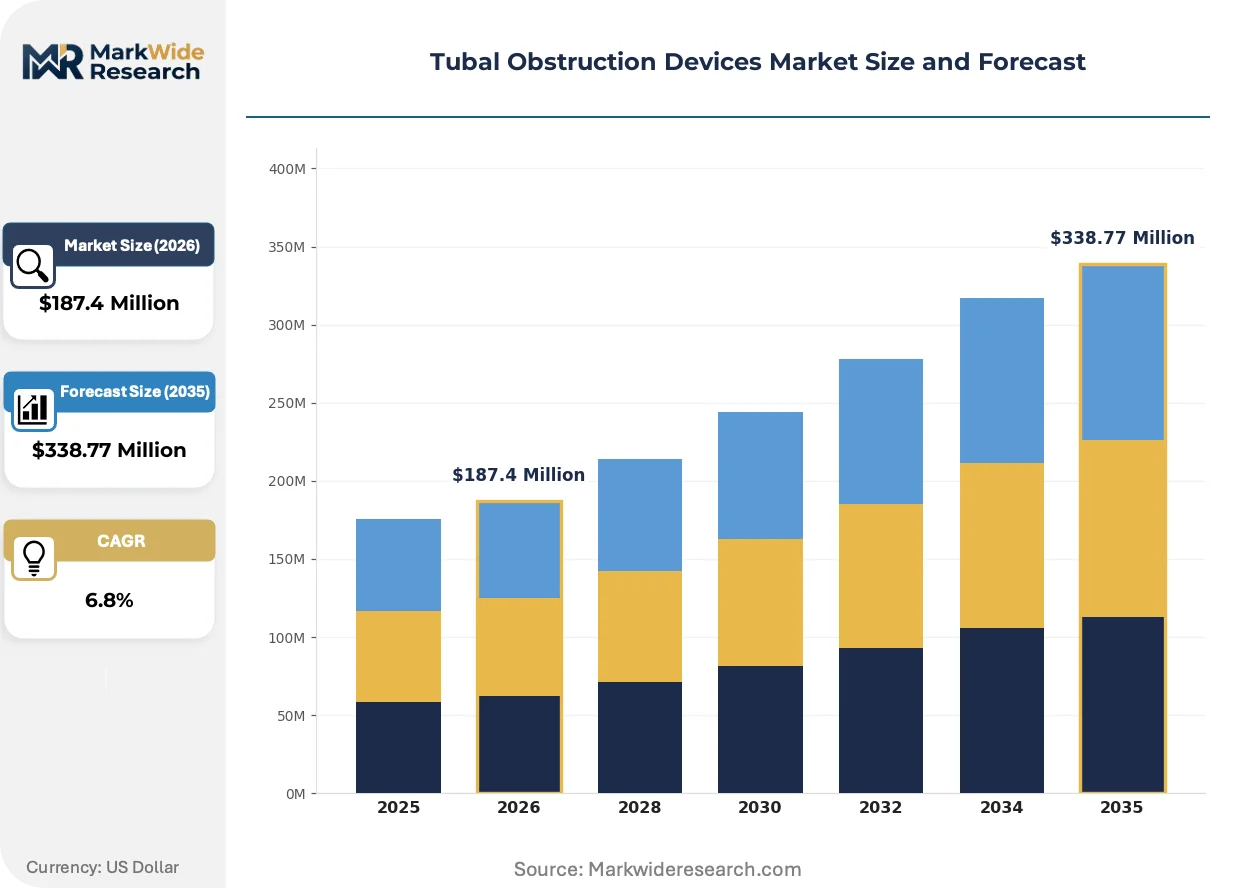
Market Dynamics
Outpatient migration of hysteroscopic tubal procedures is compressing hospital revenue cycles while forcing manufacturers to reconfigure device specifications for ambulatory surgical center workflows and same-day discharge protocols.
Growth Catalysts
- EU MDR Class III Pathways:Enhanced clinical evidence requirements for permanent implantables are accelerating investment in prospective registry studies across German and French fertility networks, creating competitive moats for compliant suppliers.
- Ambulatory Surgical Centers:United States outpatient facilities are expanding dedicated gynecology service lines, driving demand for compact, single-use hysteroscopic delivery systems optimized for lower-acuity settings.
- Nickel-Titanium Alloys:Advanced shape-memory configurations enable self-expanding tubal implants that reduce procedural time and operator skill requirements, broadening addressable physician populations.
Market Restraints
- Platinum-Iridium Markers:Volatility in precious metal input costs for radiopaque device components creates margin pressure that manufacturers struggle to pass through contracted hospital pricing agreements.
- Silicone Polymer Supply:Medical-grade silicone concentrate production clusters in northeastern China, exposing device makers to single-source geographic risk and customs processing delays.
- Permanent Contraceptive Device Classification:FDA premarket approval requirements impose 18-36 month regulatory timelines that deter mid-cap entrants and consolidate incumbent advantages.
Strategic Opportunities
- India Fertility Clinic Expansion:Private reproductive health chains in Mumbai and Bangalore are deploying capital for hysteroscopy suites, creating first-mover positioning for device suppliers establishing direct distribution.
- Reversible Tubal Occlusion:Biodegradable polymer research converging with controlled-release steroid coatings opens procedural categories between permanent sterilization and assisted reproduction.
- Japan PMDA Sakigake Pathway:Expedited review designation for novel gynecological implants reduces time-to-reimbursement for breakthrough devices targeting aging-related infertility.
Industry Challenges
- Hysteroscopy Fellowship Training:Subspecialty programs produce insufficient operators to match ambulatory center expansion, creating procedure backlogs and device utilization gaps.
- ISO 10993-23 Update:Revised irritation testing protocols require protocol amendments for existing biocompatibility dossiers, delaying line extensions and geographic registrations.
- Health System EHR Integration:Device-specific implant registries demand interoperability investments that strain mid-tier manufacturer IT resources and implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tubal Obstruction Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Hysteroscopic Adhesiolysis, Laparoscopic Tubal Occlusion, Fallopian Tube Plugs, Endometrial Ablation Devices Indication: Infertility Treatment, Congenital Anomalies, Ectopic Pregnancy, Menstrual Disorders End User: Gynecology Clinics, Hospitals, Surgical Centers, Fertility Centers Technology: Minimally Invasive Surgery, Robotic Surgery, Traditional Surgery, Ultrasound-Guided Procedures |
| Companies Covered | Boston Scientific Corporation, Medtronic, Abbott, Terumo Corporation, Stryker Corporation, Johnson & Johnson, Edwards Lifesciences Corporation, Cook Group, Penumbra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tubal Obstruction Devices Market Evolving Landscape
Device architecture is converging with digital surgical platforms while regulatory frameworks harden evidence requirements and procurement centralization reshapes commercial access pathways.
Bioresorbable tubal scaffolds is hybridizing permanent occlusion with fertility preservation by enabling timed dissolution that restores patency without secondary intervention. Academic medical centers in the United States are piloting these constructs within institutional review board protocols. The technology is compressing the historical binary between sterilization and reproductive intervention, forcing portfolio reallocation among suppliers anchored to irreversible implants.
EU Medical Device Regulation post-market surveillance mandates now require systematic literature review updates every two years for Class III implantables, imposing documentation burdens that favor organizations with dedicated regulatory affairs infrastructure. Manufacturers serving European fertility networks are consolidating adverse event reporting across national competent authorities. Hysteroscopic adhesion prevention devices face particular scrutiny given their prophylactic indication and diffuse outcome measurement.
Integrated delivery networks in the United States are consolidating gynecology device purchasing through regional procurement collaboratives, displacing individual hospital contracting autonomy. Boston Scientific and Medtronic have established dedicated key account management for these entities, while smaller suppliers face exclusion without scale economics. Texas and Florida health systems exhibit the most advanced centralization, with single-source agreements now governing hysteroscopic instrument standardization across multiple facilities.
Tubal Obstruction Devices Market Segmentation
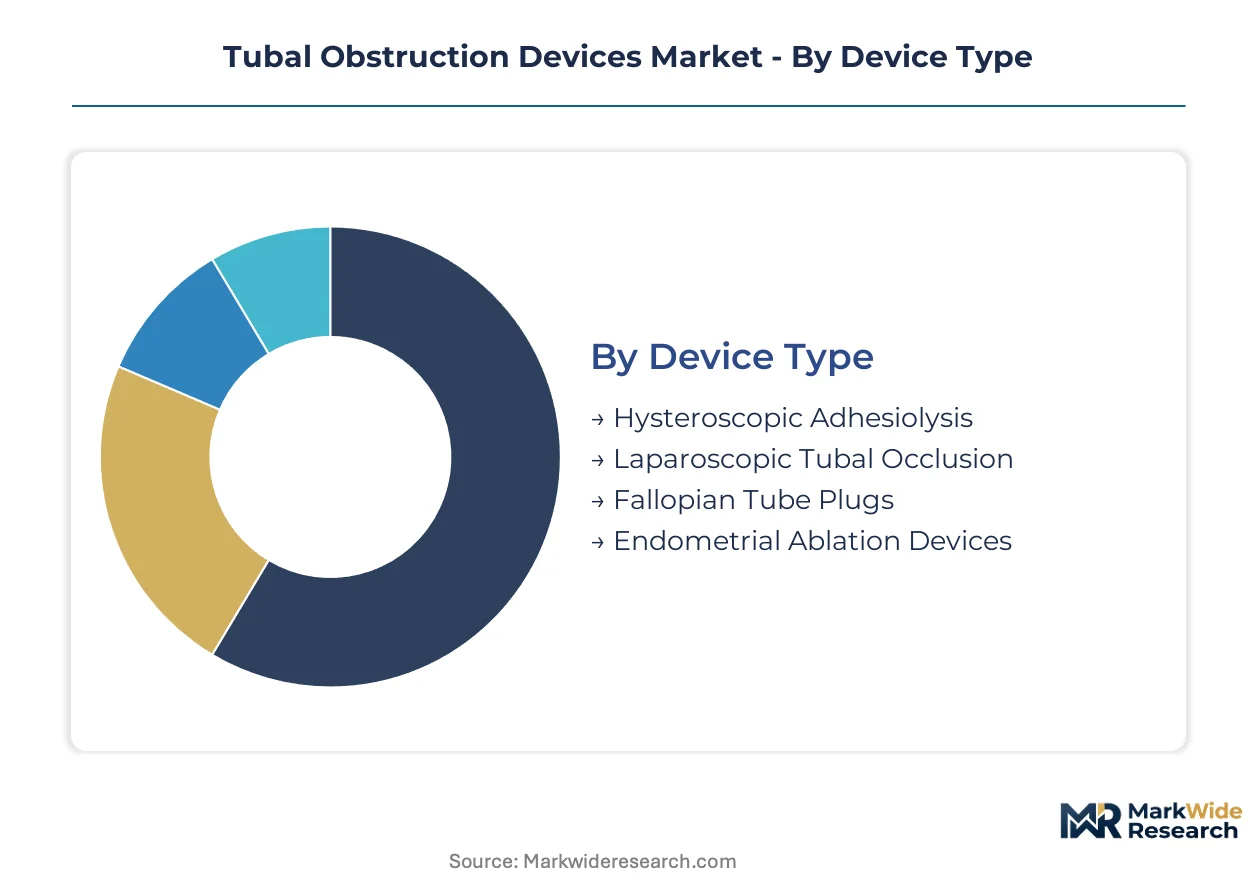
Tubal obstruction devices fragment across four intersecting dimensions that determine reimbursement pathways, regulatory classification, and procurement economics. Device architecture, clinical indication, delivery setting, and surgical modality each reshape competitive positioning and margin structure for suppliers.
Device Type:
Mature hysteroscopic platforms anchor hospital revenue while emerging plug configurations target ambulatory migration.
- Hysteroscopic Adhesiolysis:Polymer-based mechanical systems with integrated irrigation channels enable intrauterine visualization during tubal cannulation. Demand concentrates in United States hospital outpatient departments where established CPT codes sustain reimbursement stability.
- Laparoscopic Tubal Occlusion:Nickel-titanium clip applicators and bipolar coagulation devices deliver permanent sterilization through abdominal port access. German fertility networks drive specification requirements under national framework agreements that prioritize reusable instrument compatibility.
- Fallopian Tube Plugs:Silicone composite inserts with radiopaque markers enable hysteroscopic delivery without abdominal incision.
- Endometrial Ablation Devices:Radiofrequency and cryothermal systems address menstrual disorders through endometrial destruction rather than tubal intervention.
Hysteroscopic adhesiolysis retains volume leadership; fallopian tube plugs hold the steepest expansion curve.
Indication:
Reproductive versus non-reproductive applications split regulatory pathways and clinical training requirements.
- Infertility Treatment:Tubal cannulation and proximal occlusion reversal procedures leverage microcatheter technology with hydrophilic coatings to restore patency. Mumbai and Bangalore fertility chains are deploying dedicated hysteroscopy suites that standardize device specifications across multi-site networks.
- Congenital Anomalies:Uterine septum correction and tubal malformation interventions require specialized instrument curvature and working channel configurations. Academic medical centers in the United States pilot bioresorbable scaffolds within institutional review board protocols for fertility preservation.
- Ectopic Pregnancy:Methotrexate delivery catheters and linear salpingotomy devices manage fallopian implantation complications.
- Menstrual Disorders:Endometrial ablation and tubal occlusion for heavy bleeding management operate under distinct reimbursement categories.
Infertility treatment retains volume leadership; congenital anomaly interventions hold the steepest expansion curve.
End User:
Capital intensity and procedure volume determine purchasing autonomy versus centralized procurement inclusion.
- Gynecology Clinics:Office-based hysteroscopy suites demand compact, single-use delivery systems optimized for limited sterilization infrastructure. Texas and Florida health systems are consolidating gynecology device purchasing through regional procurement collaboratives that displace individual clinic contracting.
- Hospitals:Inpatient surgical departments maintain hybrid portfolios supporting both open and minimally invasive tubal procedures. Integrated delivery networks in the United States now govern hysteroscopic instrument standardization across multiple facilities through single-source agreements.
- Surgical Centers:Ambulatory facilities prioritize same-day discharge protocols and reduced operator skill requirements.
- Fertility Centers:High-volume reproductive medicine programs justify capital equipment investments in robotic platforms.
Hospitals retain volume leadership; surgical centers hold the steepest expansion curve.
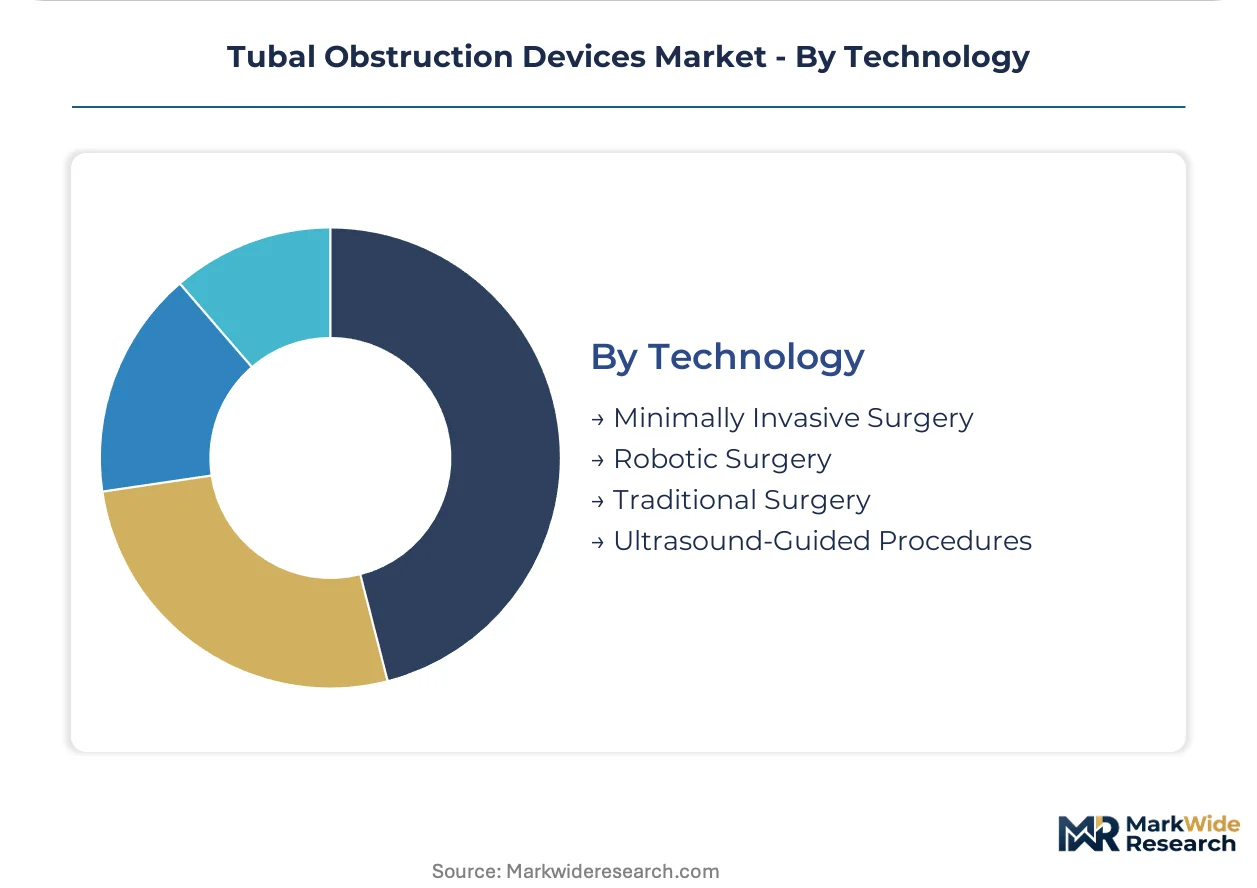
Technology:
Procedural invasiveness and capital requirements stratify addressable physician populations and reimbursement tiers.
- Minimally Invasive Surgery:Hysteroscopic and laparoscopic approaches utilizing 1.2 to 3.0 millimeter diameter instruments enable tubal intervention without laparotomy. Ambulatory surgical centers across the United States are expanding dedicated gynecology service lines that drive specification demand for compact, single-use systems.
- Robotic Surgery:Da Vinci and competing platforms concentrate in premium-tier fertility centers where capital investments justify higher per-procedure economics. Japanese academic medical centers leverage PMDA Sakigake pathway designations to expedite novel robotic instrument reimbursement for aging-related infertility interventions.
- Traditional Surgery:Open laparotomy approaches persist for complex tubal reconstruction and emergency ectopic management.
- Ultrasound-Guided Procedures:Transcervical fallopian tube catheterization under sonographic visualization reduces fluoroscopy exposure.
Minimally invasive surgery retains volume leadership; robotic surgery holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's medical device logistics hub underwrites Germany's central role in European distribution, while direct rail links from Shenzhen to Duisburg compress lead times for Asian-manufactured components entering continental markets.
United States
Gynecology clinics in Texas and Florida are expanding hysteroscopy suites as outpatient migration accelerates. FDA premarket approval requirements for permanent contraceptive devices impose 18-36 month regulatory timelines that deter mid-cap entrants. Integrated delivery networks in the Southeast now govern instrument standardization across multiple facilities through single-source agreements.
Germany
Fertility centers in Munich and Heidelberg drive specification requirements for reusable instrument compatibility under national health framework agreements. EU Medical Device Regulation Class III pathways mandate systematic literature review updates every two years for implantables. The Rhine-Main cluster concentrates adverse event reporting infrastructure across national competent authorities.
India
Private reproductive health chains in Mumbai and Bangalore are deploying capital for dedicated hysteroscopy suites that standardize device specifications across multi-site networks. CDSCO import licensing requirements for Class D implantables create registration backlogs for first-time entrants. The Maharashtra-Gujarat pharmaceutical corridor anchors domestic manufacturing ambitions for polymer-based delivery systems.
Japan
Academic medical centers in Tokyo and Osaka leverage PMDA Sakigake pathway designations to expedite novel robotic instrument reimbursement for aging-related infertility interventions. METI's medical device industry revitalization program subsidizes domestic clinical trial infrastructure. The Kansai region concentrates premium-tier fertility centers where capital equipment investments justify higher per-procedure economics.
China
NMPA innovative device approval channels are compressing registration timelines for nickel-titanium alloy implants with domestic clinical evidence. The Yangtze River Delta medical device cluster in Jiangsu and Shanghai anchors silicone polymer processing capacity. Shenzhen's precision manufacturing ecosystem supplies radiopaque marker components to multinational assembly operations.
Tubal Obstruction Devices Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: diversified interventional giants with direct integrated delivery network contracts, dedicated gynecology specialists with teaching hospital relationships, and regional fabricators serving procurement collaboratives. Strategic moves concentrate on M&A to absorb regulatory affairs infrastructure and geographic expansion into Indian fertility clinic chains.
Within the diversified interventional tier, Boston Scientific Corporation and Medtronic exemplify scale-driven positioning through dedicated sales infrastructure serving high-volume fertility programs. Cook Group occupies a specialist position among catheter configuration providers with teaching hospital channel focus. These three entities represent distinct archetypes: the broad portfolio consolidator, the academic medical center anchor, and the custom instrument specialist.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Abbott |
| Terumo Corporation |
| Stryker Corporation |
| Johnson & Johnson |
| Edwards Lifesciences Corporation |
| Cook Group |
| Penumbra |
| Others |
Value Network & Pricing Analysis
Northeastern China's medical-grade silicone concentrate production clusters tether device economics to single-source geographic exposure, compressing margin pools for manufacturers locked into long-term hospital pricing agreements. Contracted procurement rates across United States integrated delivery networks resist pass-through of precious metal volatility, forcing suppliers to absorb radiopaque marker cost swings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA premarket approval tier and hysteroscopic delivery system complexity. Price differentiation rests on ISO 10993 biocompatibility certification completeness and nickel-titanium alloy grade specification. Cost compression in standard-tier single-use devices is intensifying because ambulatory surgical centers demand simplified instrument configurations. Fertility centers exhibit lowest price sensitivity due to capital equipment amortization requirements, while community gynecology clinics face acute budget constraints.
Supply Chain Analysis
Export-control restrictions on nickel-titanium shape-memory alloys limit cross-border flows of advanced hysteroscopic implant materials from United States and Japanese suppliers. Component manufacturing draws from China's Yangtze River Delta for silicone polymer processing, Germany's Rhine-Main cluster for precision instrument fabrication, and Shenzhen's precision manufacturing ecosystem for radiopaque marker components. Single-source vulnerability concentrates in northeastern China medical-grade silicone feedstock. Distribution runs through hospital procurement consortiums and regional GPO collaboratives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical contraception and reversible fertility interventions threaten permanent tubal implant demand, forcing incumbents to justify hysteroscopic procedure economics against less invasive alternatives.
For Market Incumbents: Entrench position through backward integration into nickel-titanium alloy processing to offset platinum-iridium marker volatility, while securing FDA premarket approval pathway exclusivity against mid-cap challengers. Prioritize teaching hospital channel lock-in via dedicated sales infrastructure serving high-volume fertility programs. For New Entrants and Emerging Players: Establish a beachhead in India's Mumbai and Bangalore fertility clinic chains before CDSCO registration backlogs clear for multinational competitors. Target ambulatory surgical center workflows with compact, single-use hysteroscopic delivery systems optimized for same-day discharge protocols. For Investors and Strategic Acquirers: Capital is best deployed toward regulatory affairs infrastructure specialists with EU MDR Class III compliance capabilities and dedicated European fertility network relationships. Long-term viability hinges on bioresorbable scaffold technology maturation. Watch PMDA Sakigake pathway designation velocity as inflection signal for robotic instrument reimbursement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | 18-36 month regulatory timelines deter mid-cap entrants and consolidate incumbent positioning. |
| EU MDR Class III Compliance Investment | Systematic literature review mandates every two years favor organizations with dedicated regulatory infrastructure. |
| Hospital System Partnership | Integrated delivery network single-source agreements now govern hysteroscopic instrument standardization. |
| Backward Integration into Alloy Processing | In-house nickel-titanium production offsets platinum-iridium input cost volatility. |
| Reimbursement Strategy | CPT code stability in United States hospital outpatient departments anchors hysteroscopic adhesiolysis revenue. |
Research Methodology
A standing panel of hysteroscopic fellowship program directors, GPO contracts managers, biomedical engineers, and fertility center medical directors provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) and PMA filings, EU MDR technical documentation databases, hospital procurement consortium contract disclosures, and ISO 10993 biocompatibility testing protocols. Bottom-up device shipment modeling triangulated against top-down fertility procedure volume estimates.
Scenario-bracketing around ambulatory surgical center expansion velocity and EU MDR implementation pace bounded projections across the analysis window. Segmentation dimensions spanned device architecture, clinical indication, delivery setting, and surgical modality, with nickel-titanium alloy adoption curves and bioresorbable scaffold clinical trial progression as industry-specific forecast inputs. CAGRs derived from logistic diffusion modeling of minimally invasive procedure migration.
Sensitivities concentrate around FDA post-market surveillance guidance revisions for permanent contraceptive devices and ISO 10993-23 irritation testing protocol amendments. Forecasts reflect assumptions regarding reimbursement stability under national health framework agreements. Material shifts in regulatory classification or biocompatibility testing requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
Sinus Dilation Devices Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
Arthroscopic Shaver Market
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
India Respiratory Devices Market
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
China Diabetes Devices Market
Medical Devices
Global Defibrillators Market
Medical Devices
Steerable Needles Market
Medical Devices
Implantable Drug Eluting Devices Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Sweden Respiratory Devices Market
Medical Devices
Capnography Devices Market
Medical Devices
Atrial Fibrillation Devices Market
Medical Devices
Interatrial Shunt Market