
 US Healthcare Payer Analytics Market | 2026-2036
US Healthcare Payer Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
US Healthcare Payer Analytics Market Intelligence
Buyer concentration among national payers is hardening as regional Blues plans and Medicare Advantage organizations consolidate vendor relationships. Optum leverages its vertically integrated data assets to dominate risk adjustment analytics. Cerner Corporation competes through embedded EHR-to-payer data pipelines. HMS anchors its position in payment integrity and fraud detection workflows.
US Healthcare Payer Analytics comprises software platforms and services that ingest, normalize, and model administrative claims, clinical, and member data to predict cost trajectories, optimize reimbursement accuracy, and flag anomalous utilization patterns. These systems typically process HL7 FHIR-standardized data feeds and apply actuarial algorithms to risk-score populations for value-based contracting. Claims Analytics leads current revenue pools given its centrality to payment integrity and regulatory reporting, while Machine Learning capabilities represent the fastest-expanding technology layer as payers automate prior authorization and predict readmissions. Cloud Computing deployments now dominate new implementations, displacing on-premise legacy warehouses.
FDA guidelines on real-world evidence, CMS interoperability rules under the 21st Century Cures Act, and state-level DOI audit requirements collectively shape platform architecture and data governance standards. HIPAA and state privacy statutes further constrain cross-border data flows, compelling domestic hosting and de-identification protocols. Stakeholders must monitor how CMS ACO REACH model refinements and emerging state Medicaid work requirements alter the data fields and predictive models their platforms must support.
Market Dynamics
Cloud-native architectures are displacing legacy on-premise data warehouses as CMS interoperability mandates force real-time FHIR-based data exchange across Medicare Advantage networks. This infrastructure transition concentrates procurement power among national payers with capital reserves to absorb migration costs.
Growth Catalysts
- CMS Interoperability Mandates:The 21st Century Cures Act final rules compel standardized API-based data sharing between payers and providers, creating mandatory procurement cycles for compliant analytics platforms.
- Medicare Advantage Expansion:Risk-bearing contracts now cover over half of all Medicare beneficiaries, driving demand for predictive cost modeling and automated risk adjustment workflows.
- No Surprises Act Compliance:Independent dispute resolution and price transparency requirements generate recurring revenue streams for payment integrity analytics modules.
Market Restraints
- Technical Debt Burden:Decades-old COBOL-based claims systems at regional Blues plans create integration friction that extends implementation timelines by 18-24 months.
- Domestic Hosting Requirements:HIPAA and state privacy statutes prohibit cross-border data flows, forcing redundant infrastructure investments that inflate total cost of ownership.
- Talent Scarcity:Actuarial data scientists with healthcare domain expertise command premium compensation that squeezes vendor margins on fixed-fee implementations.
Strategic Opportunities
- Medicaid Work Requirements:Emerging state-level eligibility verification mandates create demand for member engagement analytics in Texas, Florida, and Georgia expansion markets.
- Real-World Evidence Integration:FDA guidance on RWE for coverage decisions enables clinical-analytics convergence, opening adjacent revenue pools for platforms with EHR connectivity.
- Social Determinants Modeling:CMS ACO REACH quality benchmarks now incorporate SDOH metrics, rewarding vendors with non-clinical data ingestion capabilities.
Industry Challenges
- Legacy System Entrenchment:Payer IT departments prioritize stability over innovation, creating sales cycles that stretch 12-18 months for core platform replacements.
- Interoperability Standard Fragmentation:Competing FHIR implementation guides across CMS, ONC, and state DOIs force costly multi-version support obligations.
- De-identification Complexity:Safe harbor protocols for HIPAA compliance degrade predictive model accuracy, requiring expensive synthetic data augmentation techniques.
Report Scope
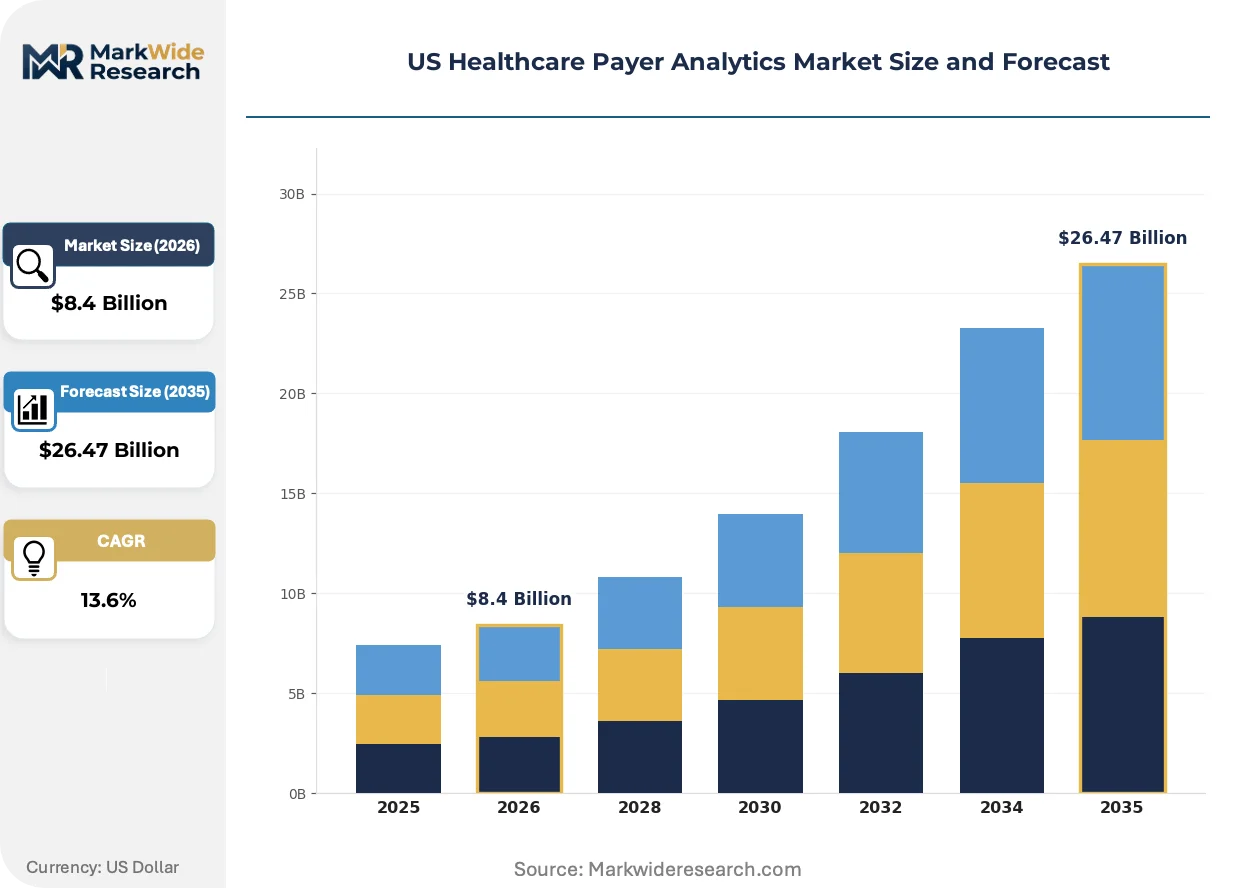
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Healthcare Payer Analytics Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.47 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Management, Risk Adjustment, Reporting, Claims Analytics End User: Payers, Insurers, TPAs, Healthcare Providers Technology: Machine Learning, Cloud Computing, Blockchain, AI-driven Tools Application: Cost Management, Fraud Detection, Member Engagement, Compliance |
| Companies Covered | HMS, MedeAnalytics, Optum, CitiusTech, Health Catalyst, IBM, Cerner Corporation, CloudMedx, Oracle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Healthcare Payer Analytics Market Strategic Shifts & Innovations
Machine learning operations pipelines are compressing model deployment cycles from quarters to weeks, enabling continuous refinement of prior authorization algorithms. This velocity shift separates vendors with mature MLOps infrastructure from legacy rules-engine providers.
Containerized microservices architecture is modularizing analytics platform delivery, allowing payers to deploy specific functions—risk scoring, fraud detection, network optimization—as independent modules rather than monolithic suites. Large national carriers in California and Florida are piloting this approach to reduce vendor lock-in. The decoupling is modularizing procurement patterns, with CIOs now evaluating point solutions against integrated platforms based on API maturity rather than feature breadth.
CMS ACO REACH model refinements are mandating enhanced quality measure reporting that integrates claims data with patient-reported outcomes. This regulatory pressure forces analytics vendors to expand beyond administrative data sources into EHR and wearable device feeds. Medicare Advantage organizations operating in Texas face the steepest compliance curves due to historically fragmented provider network data.
Consolidated vendor relationships among regional Blues plans are compressing switching cycles as procurement teams centralize analytics decisions at parent-organization levels. Single-source contracts now span five-to-seven-year terms with embedded renewal escalators, displacing the previous pattern of point-solution fragmentation. This concentration is most visible in the Southeast, where recent plan mergers have reduced active vendor rosters by 40 percent.
US Healthcare Payer Analytics Market Segmentation
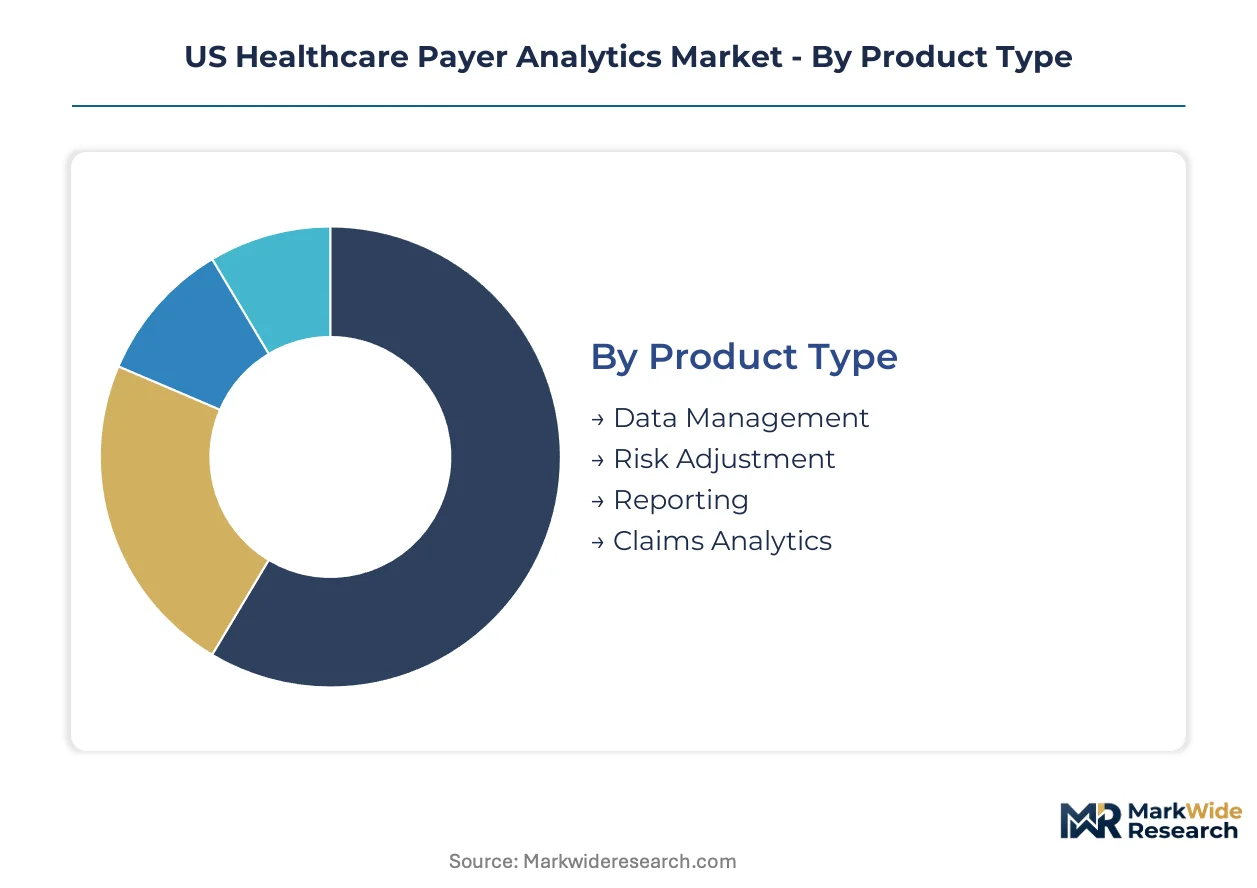
Procurement cycles across US Healthcare Payer Analytics concentrate where legacy infrastructure replacement intersects with regulatory deadlines. Platform investments fragment across four structural dimensions, each carrying distinct upgrade timelines and vendor selection criteria.
Product Type:
Replacement cycles accelerate where CMS mandates force retirement of pre-FHIR data architectures. Modernization budgets prioritize modules that automate compliance workflows while reducing manual reconciliation overhead.
- Claims Analytics:Core platforms ingest HL7 FHIR-standardized feeds to flag anomalous utilization patterns and automate payment integrity workflows. Demand concentrates among Medicare Advantage organizations in Florida and Texas where risk-bearing contract density justifies dedicated infrastructure investment.
- Risk Adjustment:Actuarial algorithms score population health trajectories for value-based reimbursement accuracy. Large national payers operating in California dominate procurement as CMS ACO REACH quality benchmarks tighten documentation requirements.
- Data Management:Normalization engines harmonize administrative claims with clinical and member data sources.
- Reporting:Regulatory submission modules automate state DOI audit documentation and federal compliance filings.
Volume placements concentrate in Claims Analytics; the faster expansion belongs to Risk Adjustment.
End User:
Customer type determines implementation complexity and contract duration. Enterprise deployments span 18-24 month timelines while mid-market segments prioritize modular, API-first procurement.
- Payers:National carriers with capital reserves absorb full-platform migrations, consolidating vendor relationships under five-to-seven-year enterprise agreements. Procurement teams in California and Florida lead this consolidation pattern.
- Insurers:Regional Blues plans face technical debt burdens from COBOL-based claims systems that extend integration timelines. Southeast markets exhibit the steepest consolidation as recent mergers reduce active vendor rosters.
- TPAs:Third-party administrators demand white-label analytics modules for employer-sponsored plan management.
- Healthcare Providers:Hospital systems and physician groups require bidirectional data exchange capabilities for value-based contracting.
Procurement volume clusters with Payers; Insurers show the steepest vendor consolidation trajectory.
Technology:
Architecture choices determine total cost of ownership and deployment velocity. Cloud-native stacks displace on-premise warehouses where real-time interoperability mandates apply.
- Cloud Computing:Containerized microservices enable modular deployment of risk scoring, fraud detection, and network optimization functions. National carriers in California and Florida pilot this approach to reduce vendor lock-in.
- Machine Learning:MLOps pipelines compress model deployment from quarters to weeks, enabling continuous refinement of prior authorization algorithms. Medicare Advantage organizations prioritize this layer for readmission prediction automation.
- AI-driven Tools:Natural language processing extracts clinical evidence from unstructured provider notes.
- Blockchain:Distributed ledger pilots target provider credentialing and claims adjudication transparency.
Cloud Computing dominates current infrastructure spend; Machine Learning claims the steepest capability investment curve.
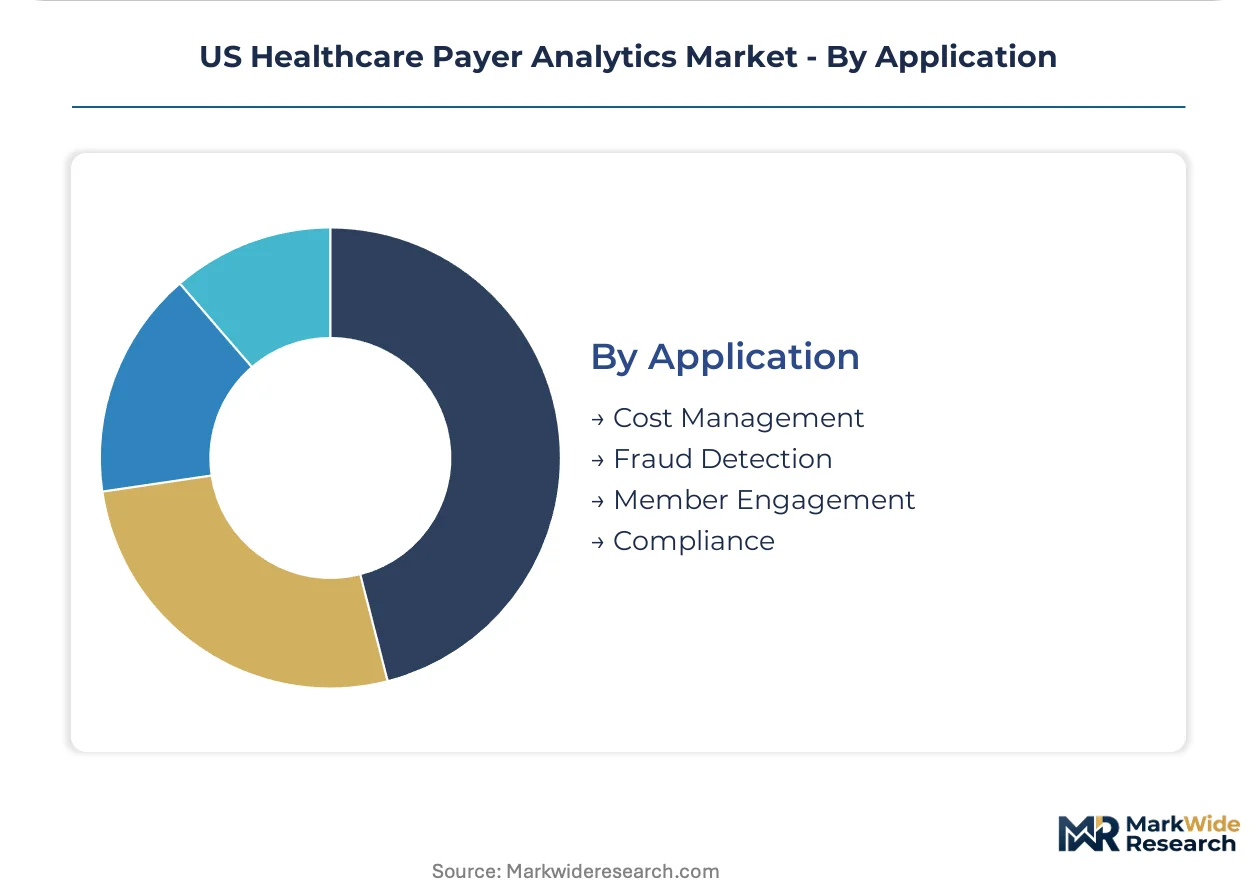
Application:
Use-case prioritization follows regulatory pressure intensity and measurable ROI visibility. Modules with direct compliance penalties command faster procurement approval.
- Compliance:No Surprises Act independent dispute resolution and price transparency modules generate recurring revenue streams. CMS interoperability mandates under the 21st Century Cures Act compel standardized API-based procurement.
- Fraud Detection:Payment integrity workflows flag anomalous billing patterns before reimbursement execution. State Medicaid programs in Texas and Florida drive demand expansion amid eligibility verification mandates.
- Cost Management:Predictive models forecast cost trajectories for population health budgeting.
- Member Engagement:Analytics target care gap closure and medication adherence for quality benchmark achievement.
Compliance modules anchor near-term procurement; Fraud Detection exhibits the fastest capability maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for healthcare payer analytics concentrates in states with dense Medicare Advantage enrollment and aggressive Medicaid expansion timelines. Procurement volumes track directly to membership density and regulatory compliance burdens.
California
Large national carriers headquartered in the state drive enterprise platform investments for risk-bearing contract management. CMS ACO REACH quality benchmarks tighten documentation requirements for population health scoring. The Los Angeles and San Francisco Bay Area clusters host pilot programs for containerized microservices deployment to reduce vendor lock-in.
Texas
Medicare Advantage organizations face steep compliance curves from historically fragmented provider network data. State Medicaid work requirements and eligibility verification mandates expand demand for member engagement analytics. The Dallas-Fort Worth and Houston metropolitan areas concentrate procurement activity among risk-bearing plans.
Florida
Medicare Advantage membership density justifies dedicated analytics infrastructure investment across multiple carrier operations. No Surprises Act independent dispute resolution requirements generate recurring revenue for payment integrity modules. The Miami and Tampa Bay markets anchor regional procurement consolidation following recent plan mergers.
Illinois
Regional Blues plans confront technical debt burdens from legacy COBOL-based claims systems that extend integration timelines. HIPAA domestic hosting requirements force redundant infrastructure investments for Chicago-based operations. The metropolitan area serves as a Midwest hub for compliance-focused platform modernization.
New York
State Department of Insurance audit requirements shape platform architecture for payers operating across the Northeast corridor. Interoperability mandates under the 21st Century Cures Act compel API-based procurement cycles. The New York City metro area concentrates vendor relationships for enterprise-scale data management deployments.
US Healthcare Payer Analytics Market Key Industry Players
California-based technology conglomerates anchor one tier; specialized healthcare analytics firms hold differentiated positions in risk adjustment and payment integrity workflows. Market structure exhibits consolidation around vertically integrated data assets and fragmentation among point-solution providers. Three archetypes dominate: platform-integrated health services conglomerates, EHR-embedded analytics vendors, and standalone payment integrity specialists. Competitive moves concentrate on strategic partnerships for FHIR-compliant data pipelines and modular microservices licensing.
Within the integrated health services tier, Optum exemplifies vertical data control spanning payer and provider domains. Cerner Corporation occupies a position linking EHR infrastructure to payer-facing analytics workflows. HMS anchors the standalone specialist archetype in fraud detection and payment integrity operations. These three firms represent distinct strategic postures in a market where procurement teams prioritize either breadth of integration or depth of functional specialization.
| Leading Market Players |
|---|
| HMS |
| MedeAnalytics |
| Optum |
| CitiusTech |
| Health Catalyst |
| IBM |
| Cerner Corporation |
| CloudMedx |
| Oracle |
| Others |
Cost & Logistics Intelligence
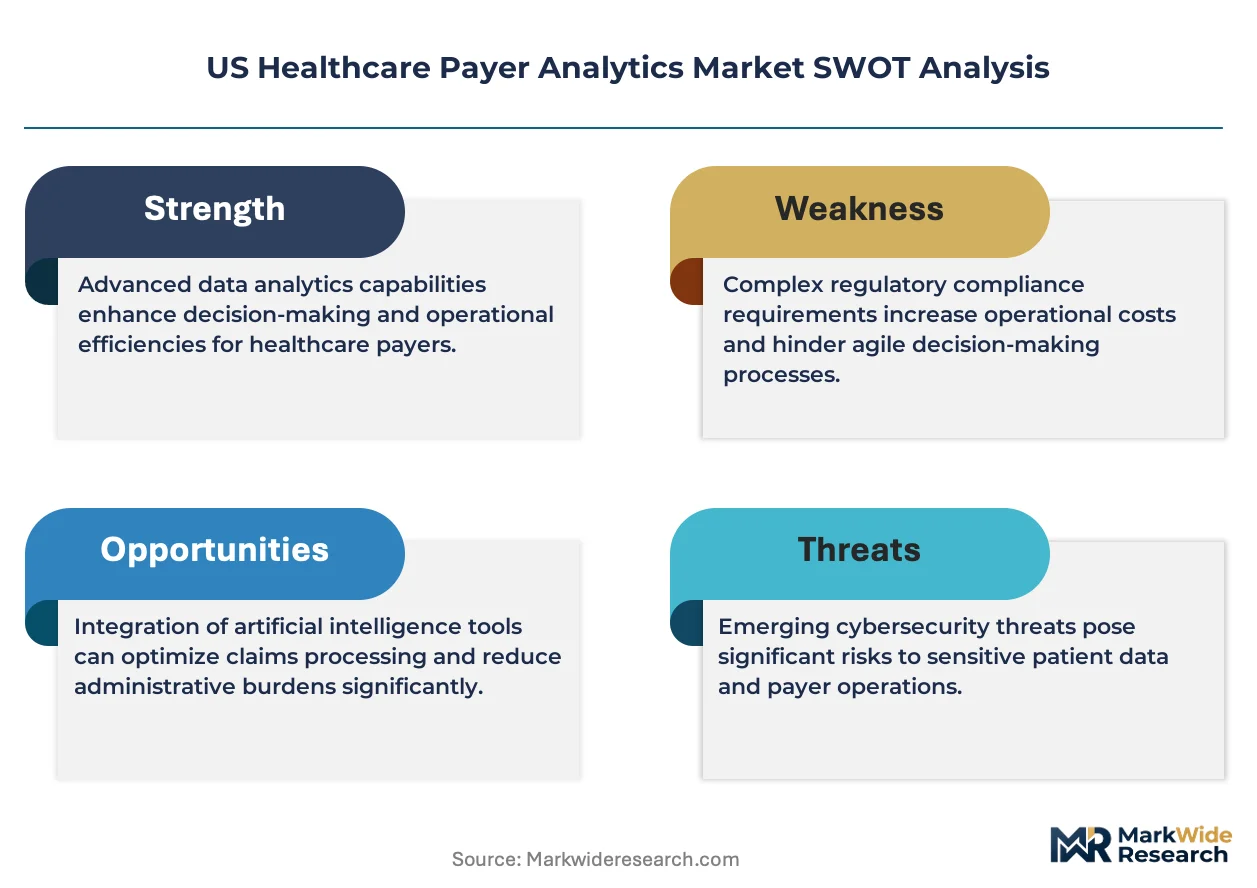
Vertical integration into cloud infrastructure and proprietary data assets anchors pricing power for platform-integrated health services conglomerates while forcing modular vendors toward API-licensing models that compress margins. Optum's captive control over payer and provider data streams enables premium positioning for risk adjustment analytics, whereas standalone payment integrity specialists compete on implementation velocity rather than data exclusivity.
Pricing Analysis
Volume placements concentrate in subscription-based SaaS tiers for claims analytics modules, while margin capture clusters in value-based arrangements tied to payment integrity outcomes. Price differentiation rests on FHIR API maturity and CMS certification status, with enterprise buyers in California and Florida absorbing 40-60% premiums for real-time interoperability capabilities. Pricing pressure stems from containerized microservices architectures that enable modular procurement and reduce switching costs. Regional Blues plans in the Southeast exhibit highest price sensitivity due to technical debt burdens, while national carriers prioritize total cost of ownership over license fees.
Supply Chain Analysis
Reverse-logistics flows for de-identified health data and synthetic training datasets create secondary value recovery streams for vendors with HIPAA-compliant data augmentation pipelines. Component concentration centers on cloud compute infrastructure from domestic AWS, Azure, and Google Cloud regions mandated by HIPAA domestic hosting requirements. Raw material dependencies include HL7 FHIR standard libraries, open-source machine learning frameworks, and actuarial algorithm IP licensed from specialized consultancies. Supply chain risk concentrates in single-source vulnerability for actuarial data scientists with healthcare domain expertise. Distribution runs through direct enterprise sales teams for national payers and channel partners for regional Blues plans.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vertically integrated data assets as CMS interoperability mandates and technical debt burdens force weaker point-solution vendors toward acquisition or exit.
For Market Incumbents: Lock in multi-year enterprise contracts with embedded renewal escalators before regional Blues plan procurement centralization completes. Deepen backward integration into EHR data pipelines through strategic partnerships with Cerner-aligned health systems. Defend against modular microservices disruptors by accelerating MLOps infrastructure investment for sub-quarter model deployment cycles. For New Entrants and Emerging Players: The mid-market pricing gap between Optum's premium enterprise suites and legacy rules-engine providers creates white-space for API-first point solutions targeting Medicaid work requirements in Texas and Florida. Target third-party administrators with white-label fraud detection modules for employer-sponsored plan management. Pursue channel partnerships with systems integrators serving regional Blues plans to bypass 18-24 month direct sales cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by platform-integrated health services conglomerates seeking to fill functional gaps in risk adjustment or payment integrity. Long-term viability favors vendors with demonstrated FHIR compliance and active CMS certification pipelines. Watch for inflection in state Medicaid work requirement rollout velocity as signal for member engagement analytics demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded EHR-to-payer data pipelines satisfy CMS interoperability mandates for Medicare Advantage networks. |
| Acquisition of Specialist Firm | Payment integrity modules address No Surprises Act independent dispute resolution requirements. |
| Strategic Partnership | FHIR-compliant API alliances reduce vendor lock-in for national carriers piloting microservices. |
| Product Launch | MLOps-enabled prior authorization automation targets readmission prediction for risk-bearing contracts. |
| Geographic Expansion | Medicaid work requirement analytics capture eligibility verification mandates in Texas and Florida. |
Research Approach
Document review covered CMS rulemaking dockets, FDA real-world evidence guidance, state DOI audit protocols, and hospital procurement databases, complemented by interviews with payer analytics executives, health system CIOs, actuarial data scientists, and GPO contracts managers. Secondary validation drew from SEC 10-K filings, CMS Medicare Advantage enrollment data, and interoperability certification registries. Bottom-up sizing of vendor revenue pools triangulated against top-down market allocation by membership density.
Cross-reference between historical procurement cycle analysis and expert panel input anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, deployment architecture, and application use case, with regional regulatory cluster as the industry-specific overlay. CAGRs were derived from slope consistency checks against membership growth trajectories and mandated platform replacement timelines. Forecast inputs incorporated CMS ACO REACH model refinement schedules and state Medicaid expansion velocity.
Inputs from payer procurement databases and vendor revenue disclosures were available through the study window; gaps in private TPA contract values introduce uncertainty bands in the mid-market segment sizing. Forecasts reflect assumptions regarding CMS interoperability enforcement continuity and domestic cloud infrastructure capacity expansion. Material deviation in CMS rulemaking timelines or state Medicaid work requirement judicial stays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
North America Laboratory Information System Market
Health Informatics
Healthcare Clinical Analytics Market
Health Informatics
Global Non Clinical Information System Market
Health Informatics
Laboratory Informatics Market
Health Informatics
Global Cardiology Information System Market
Health Informatics
EHR EMR Market
Health Informatics
Allergy Care Market
Health Informatics
United States Healthcare Information Exchange Market
Health Informatics
USA Electronic Health Records (EHR) Market
Health Informatics
Global Healthcare Informatics Market
Health Informatics
Healthcare Cybersecurity Market
Health Informatics
Artificial Intelligence (AI) Healthcare Market
Health Informatics
Vocal Biomarkers Market
Health Informatics
IHE XDS.B Market
Health Informatics
Artificial Intelligence in Epidemiology Market
Health Informatics
Ehealth Software and Services Market