
 Global Mini C-Arm Market | 2026-2036
Global Mini C-Arm Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mini C-Arm Market Foresight
The EU Medical Device Regulation is consolidating procurement criteria across European hospital systems, favoring manufacturers with established CE marking and post-market surveillance infrastructure. Siemens Healthcare leverages its integrated imaging portfolio to sustain service contracts that lock in multi-year replacement cycles. GE Healthcare anchors its position through backward integration into tube and detector manufacturing, reducing lead times for critical components. Philips Healthcare competes on digital workflow integration, connecting mini C-arm output to enterprise PACS networks.
A mini C-arm is a compact fluoroscopic imaging system with a C-shaped gantry typically housing an X-ray tube and flat-panel detector or image intensifier, designed for real-time intraoperative visualization during orthopedic, podiatric, and pain management procedures. The device generates live video feed at 25-30 frames per second with dose rates significantly below full-size C-arm systems, enabling safe operation in smaller procedure rooms without specialized shielding requirements. Mobile and portable configurations lead unit shipments due to flexibility across multi-suite ASC layouts, while CMOS sensor technology is displacing legacy image intensifier architectures as the dominant detector platform. Orthopedics and sports medicine applications command the largest share of installed base, though veterinary care represents an emerging margin pool with less price-sensitive buyers and lighter regulatory burden.
The FDA governs 510(k) premarket notification for mini C-arm systems in the United States, while the EU MDR and CE marking framework enforce clinical evidence and quality management requirements across European markets. Japan's PMDA maintains distinct pharmaceutical and medical device regulations that foreign manufacturers must navigate through in-country designated marketing authorization holders. Stakeholders should monitor how evolving radiation dose reporting mandates and sustainability-linked procurement criteria reshape competitive access across major national markets.
Market Dynamics
CMOS flat-panel detectors are compressing replacement cycles across the mini C-arm installed base as image intensifier architectures face accelerated obsolescence from dose optimization mandates and ASC space constraints.
Growth Catalysts
- EU MDR consolidation:European hospital procurement teams now favor vendors with mature post-market surveillance infrastructure, rewarding early CE marking investments with multi-year contract locks.
- Orthopedic procedure migration:Ambulatory surgical centers in the United States absorb rising volumes of outpatient joint and fracture repairs, each suite requiring dedicated fluoroscopic capability.
- CMOS sensor maturation:Detector manufacturing scale effects have reduced unit costs for flat-panel architectures, enabling price parity with legacy image intensifier systems at superior image quality.
Market Restraints
- X-ray tube supply concentration:Specialized tube manufacturing remains captive to a limited supplier base in Germany and Japan, exposing lead time volatility for system integrators.
- Shielding exemption thresholds:FDA radiation dose reporting requirements for fluoroscopic equipment impose documentation burdens that extend sales cycles for smaller ASC buyers.
- Full-size C-arm substitution:Hospital buyers with existing fixed-room installations resist downsizing to mini systems despite space advantages, preserving installed base inertia.
Strategic Opportunities
- Veterinary care expansion:Companion animal orthopedic surgery in the United States and United Kingdom presents margin pools with reduced regulatory friction and lower price sensitivity.
- Japan PMDA pathway refinement:Streamlined foreign manufacturer registration through designated marketing authorization holders accelerates market entry timelines for compliant applicants.
- Wireless detector convergence:Battery-powered flat-panel architectures paired with tablet-based control interfaces enable true point-of-care deployment outside traditional radiology infrastructure.
Industry Challenges
- Clinical engineering talent scarcity:ASC facilities lack in-house biomedical technicians capable of troubleshooting fluoroscopic hardware, forcing reliance on OEM service contracts at premium rates.
- Legacy PACS integration friction:Mini C-arm digital output formats frequently require middleware conversion to achieve seamless enterprise imaging archive connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mini C-Arm Market |
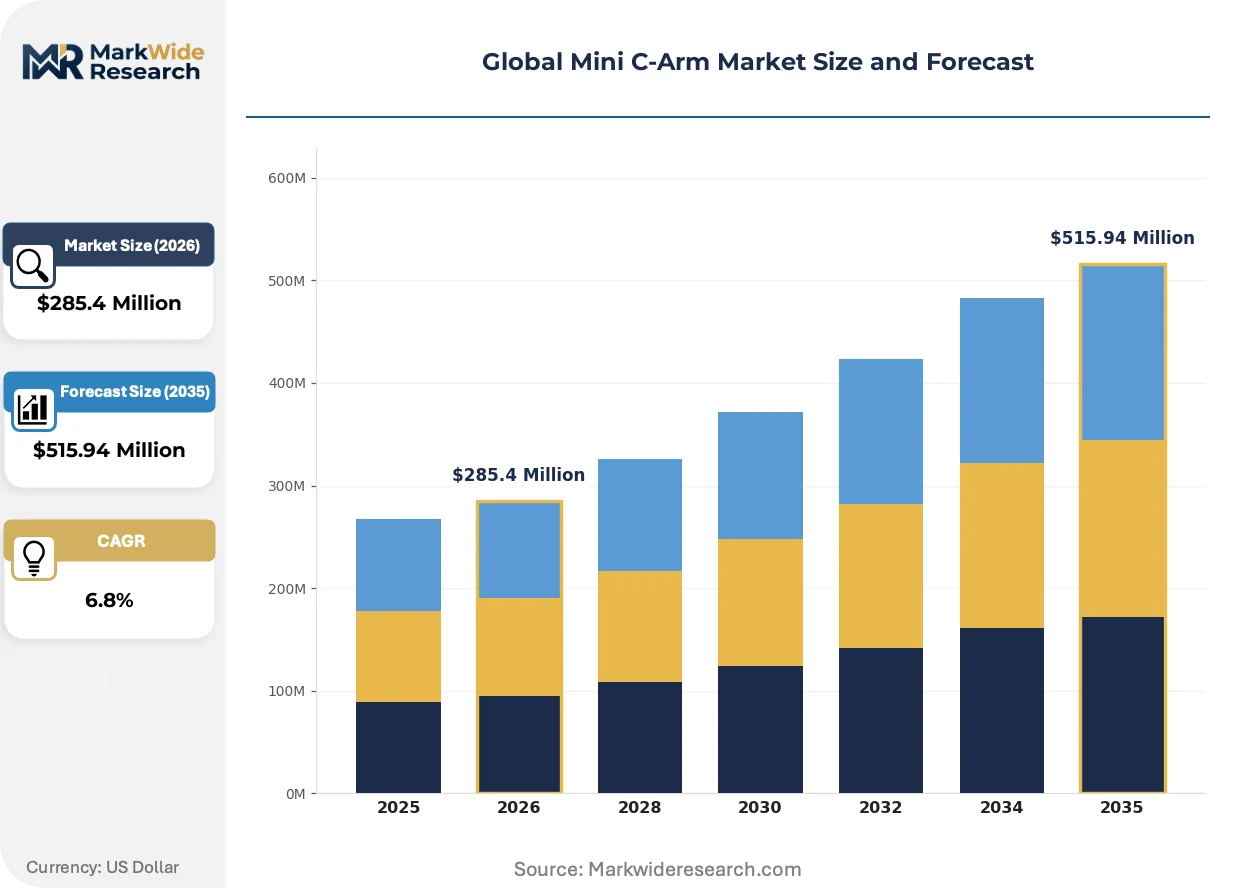
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile, Fixed, Compact, Portable Technology: Digital, Analog, Fluoroscopic, CMOS Sensor Application: Orthopedics, Sports Medicine, Dental Surgery, Pain Management, Veterinary Care End User: Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Centers, Rehabilitation Facilities |
| Companies Covered | Siemens Healthcare, GE Healthcare, Philips Healthcare, Hologic, OrthoScan, Canon Medical Systems, Ziehm Imaging GmbH, Perlong Medical, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mini C-Arm Market Shifts & Advancements
Real-time surgical imaging is converging with enterprise data infrastructure, compressing the boundary between intraoperative visualization and longitudinal patient records while forcing vendors to compete on software integration depth.
CMOS-based flat-panel detector technology is unifying image capture and digital processing within single-chip architectures, eliminating analog signal chains that previously dominated image intensifier systems. ASC operators in the United States and Germany adopt these configurations for multi-suite flexibility without dedicated shielding rooms. This unification is compressing the total cost of ownership gap between premium and mid-tier system tiers, forcing price repositioning across the product stack.
EU Medical Device Regulation post-market surveillance requirements are mandating systematic clinical follow-up data collection for fluoroscopic equipment placed on the European market. Manufacturers must maintain vigilance systems capable of detecting rare adverse events across distributed installed bases. High-volume system vendors with existing European service infrastructure capture compliance economies that smaller competitors cannot replicate.
After-sales service contracts are unbundling from hardware purchase agreements as ASC buyers seek operational expense predictability separate from capital depreciation schedules. Third-party clinical engineering firms in the United States now compete for preventive maintenance volumes previously captive to OEM service organizations. This unbundling is most advanced in Texas and Florida metropolitan markets where ASC chain consolidation has concentrated purchasing leverage.
Global Mini C-Arm Market Segmentation
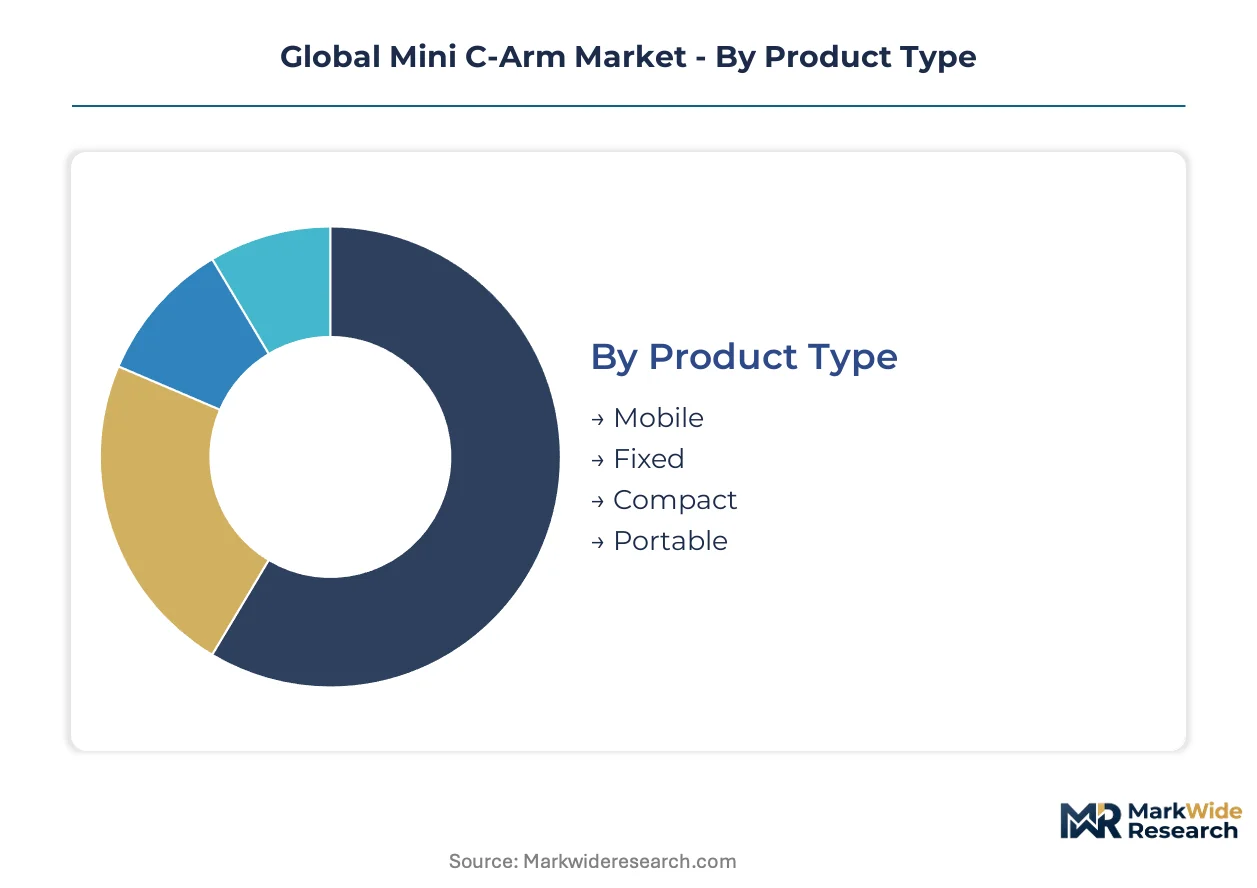
Mini C-arm purchasing decisions fragment across mobility requirements, detector architectures, procedure types, and facility infrastructure. Each segmentation axis carries distinct margin profiles and replacement cycle dynamics that reshape competitive positioning.
Product Type:
Integration depth varies sharply: mobile and portable configurations operate as standalone assets deployable across suites, while fixed installations embed into dedicated procedure rooms with permanent shielding.
- Mobile:Wheeled chassis with onboard generator enables relocation between operating theaters without facility modification. Demand concentrates in United States ASC chains where multi-suite layouts prioritize asset utilization rates over dedicated room builds.
- Portable:Battery-powered architectures with wireless detector links support true point-of-care deployment outside radiology infrastructure. German outpatient orthopedic clinics adopt these for same-day discharge protocols that require imaging at the procedure site rather than centralized departments.
- Fixed:Ceiling-mounted or floor-fixed gantries integrate with permanent shielding and dedicated HVAC. Compact form factors suit Japanese clinics with constrained floor plates where every square meter carries premium lease costs.
- Compact:Reduced footprint systems trade detector field-of-view for maneuverability in crowded suites. United Kingdom veterinary practices favor these for companion animal fracture repair where procedure volume does not justify full-size C-arm capital.
Volume placements concentrate in Mobile; the faster expansion belongs to Portable.
Technology:
Cost tiers separate legacy analog architectures from digital detector platforms, with CMOS-based flat-panel systems commanding premium positioning against image intensifier remnants.
- CMOS Sensor:Single-chip integration of photodiode array and readout electronics eliminates analog signal chains, reducing electronic noise and enabling lower dose protocols. United States ASC procurement criteria now specify CMOS as baseline for new purchases, accelerating obsolescence of competing architectures.
- Digital:Broad category encompassing flat-panel detector systems with direct digital output to PACS networks. French hospital systems under EU MDR procurement consolidation favor digital-native vendors with established post-market surveillance infrastructure.
- Fluoroscopic:Continuous X-ray emission with real-time image processing remains the functional core across all mini C-arm systems regardless of detector type. Italian orthopedic clinics maintain installed base of fluoroscopic units approaching replacement age.
- Analog:Image intensifier tubes with analog video output persist in price-sensitive segments and developing markets. Brazilian outpatient surgery centers continue analog purchases where capital constraints outweigh dose optimization priorities.
Replacement demand clusters in CMOS Sensor; steepest expansion trajectory characterizes Digital.
Application:
Procedure volume and reimbursement rates determine application attractiveness, with orthopedic and sports medicine procedures anchoring installed base concentration.
- Orthopedics:Fracture reduction, joint arthroplasty, and hardware placement procedures require real-time bony visualization with sub-millimeter resolution. United States outpatient joint repair migration drives dedicated mini C-arm deployment per operating suite.
- Sports Medicine:Arthroscopic procedures and soft-tissue reconstruction demand rapid positioning flexibility across knee, shoulder, and ankle anatomy. Australian private sports medicine clinics invest in mobile configurations for athlete same-day return protocols.
- Veterinary Care:Companion animal orthopedic surgery carries reduced regulatory burden and lighter price sensitivity relative to human medical markets. United Kingdom veterinary chains expand fluoroscopic capability for cruciate ligament repair in canines.
- Pain Management:Fluoroscopic guidance for epidural injections and nerve blocks requires precise needle visualization with minimal patient movement. Canadian pain clinics adopt compact systems for office-based procedure rooms.
- Dental Surgery:Implant placement and maxillofacial procedures utilize mini C-arm configurations with specialized orbital positioning. South Korean dental hospital networks integrate these into implantology suites.
Revenue concentration sits with Orthopedics; Veterinary Care gains share fastest.
End User:
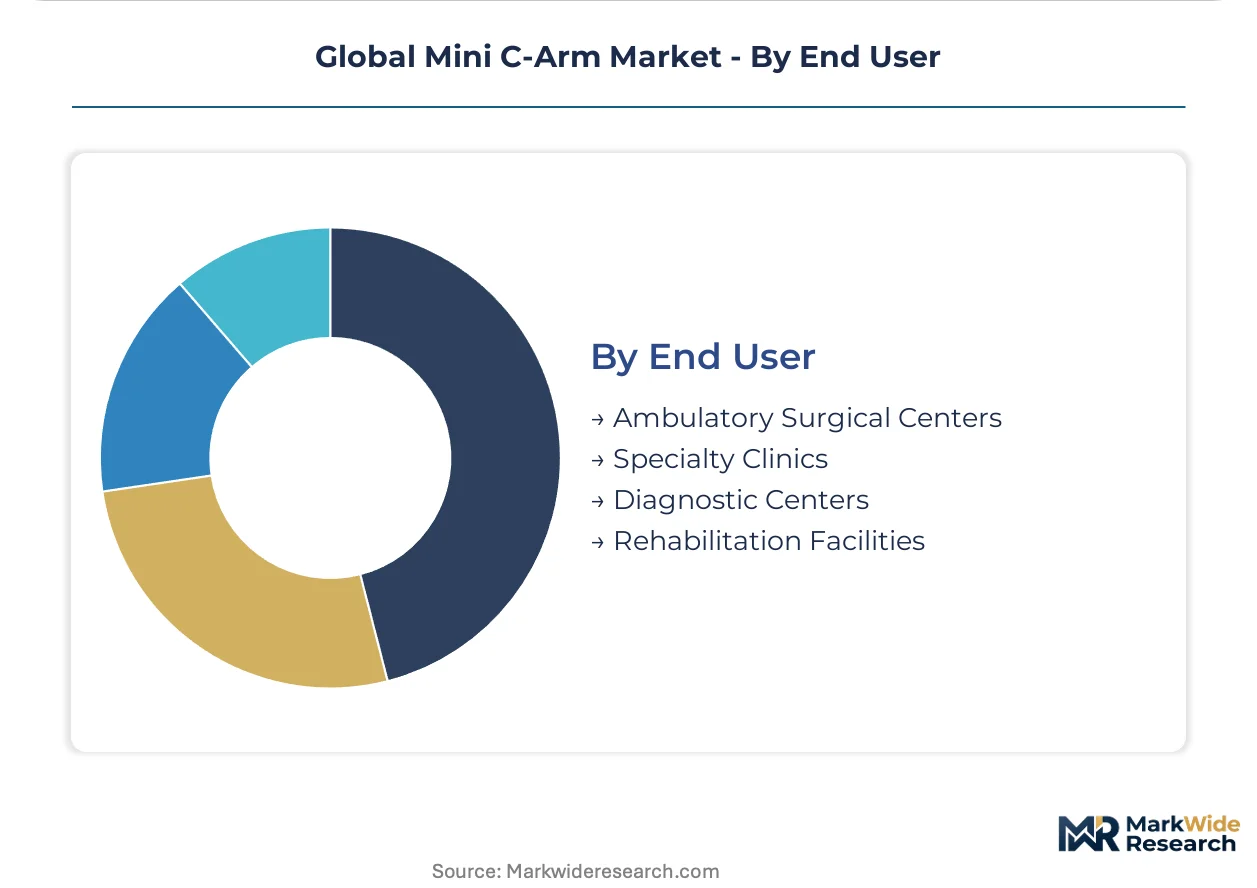
Customer type dictates purchasing process complexity, with ASC chains leveraging volume leverage against fragmented specialty clinic procurement.
- Ambulatory Surgical Centers:Multi-suite facilities with centralized purchasing negotiate service-inclusive contracts spanning hardware and preventive maintenance. Texas and Florida ASC consolidation creates procurement leverage for standardized fleet configurations.
- Specialty Clinics:Orthopedic, podiatric, and pain management practices with single or limited procedure rooms prioritize equipment financing over capital purchase. German outpatient surgery centers favor operating lease structures.
- Diagnostic Centers:Imaging-focused facilities require enterprise PACS integration and DICOM compliance for referral network connectivity. Japanese diagnostic chains specify seamless radiology information system compatibility.
- Rehabilitation Facilities:Post-acute settings with procedure capability for pain intervention or minor orthopedic correction represent emerging demand. United States skilled nursing facility expansion into outpatient procedures drives initial fluoroscopic investment.
Unit shipments dominate Ambulatory Surgical Centers; Rehabilitation Facilities climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors North American mini C-arm procurement as ASC chains consolidate purchasing across Texas surgical markets.
United States
Outpatient orthopedic migration drives fluoroscopic investment across Texas and Florida ASC networks. FDA 510(k) clearance pathways compress product launch timelines for digital radiography equipment. The Dallas-Fort Worth corridor concentrates multi-suite surgical centers negotiating standardized fleet configurations.
Germany
Outpatient surgery centers adopt portable configurations for same-day discharge protocols in orthopedic care. EU MDR post-market surveillance requirements favor vendors with established CE marking infrastructure. The Rhine-Ruhr industrial basin hosts imaging equipment service providers supporting distributed clinic networks.
Japan
Constrained clinic floor plates drive demand for ceiling-mounted compact gantries in urban centers. PMDA maintains distinct pharmaceutical and medical device regulations requiring foreign manufacturers to register through designated marketing authorization holders. The Osaka-Kobe corridor concentrates diagnostic imaging distribution channels.
United Kingdom
Veterinary chains expand fluoroscopic capability for companion animal orthopedic surgery with reduced regulatory burden. MHRA convergence with EU MDR standards streamlines conformity assessment for CE-marked devices. The Greater London area concentrates private veterinary specialist referral centers.
China
Domestic manufacturing scale effects reduce detector costs for flat-panel architectures. NMPA medical device registration requirements enforce quality management system compliance for imported fluoroscopic equipment. The Yangtze River Delta cluster concentrates CMOS sensor fabrication capacity serving regional system integrators.
Global Mini C-Arm Market Competitive Landscape
The competitive structure tilts toward diversified imaging conglomerates with captive detector manufacturing and established service infrastructure. Three archetypes dominate: integrated healthcare technology conglomerates with multi-modality portfolios; mid-scale specialists concentrating on orthopedic fluoroscopy; and regional fabricators serving price-sensitive developing markets. Dominant competitive moves include backward integration into tube and detector supply chains, plus unbundling of service contracts from hardware purchase agreements.
Among diversified imaging conglomerates, Siemens Healthcare, GE Healthcare, and Philips Healthcare occupy positions defined by integrated portfolio breadth and multi-year service contract penetration. These players anchor the premium tier through enterprise PACS connectivity and post-market surveillance infrastructure that satisfies EU MDR procurement consolidation. Ziehm Imaging GmbH represents the specialist archetype with focused orthopedic fluoroscopy positioning.
| Leading Market Players |
|---|
| Siemens Healthcare |
| GE Healthcare |
| Philips Healthcare |
| Hologic |
| OrthoScan |
| Canon Medical Systems |
| Ziehm Imaging GmbH |
| Perlong Medical |
| Shimadzu Corporation |
| Others |
Supply & Pricing Matrix
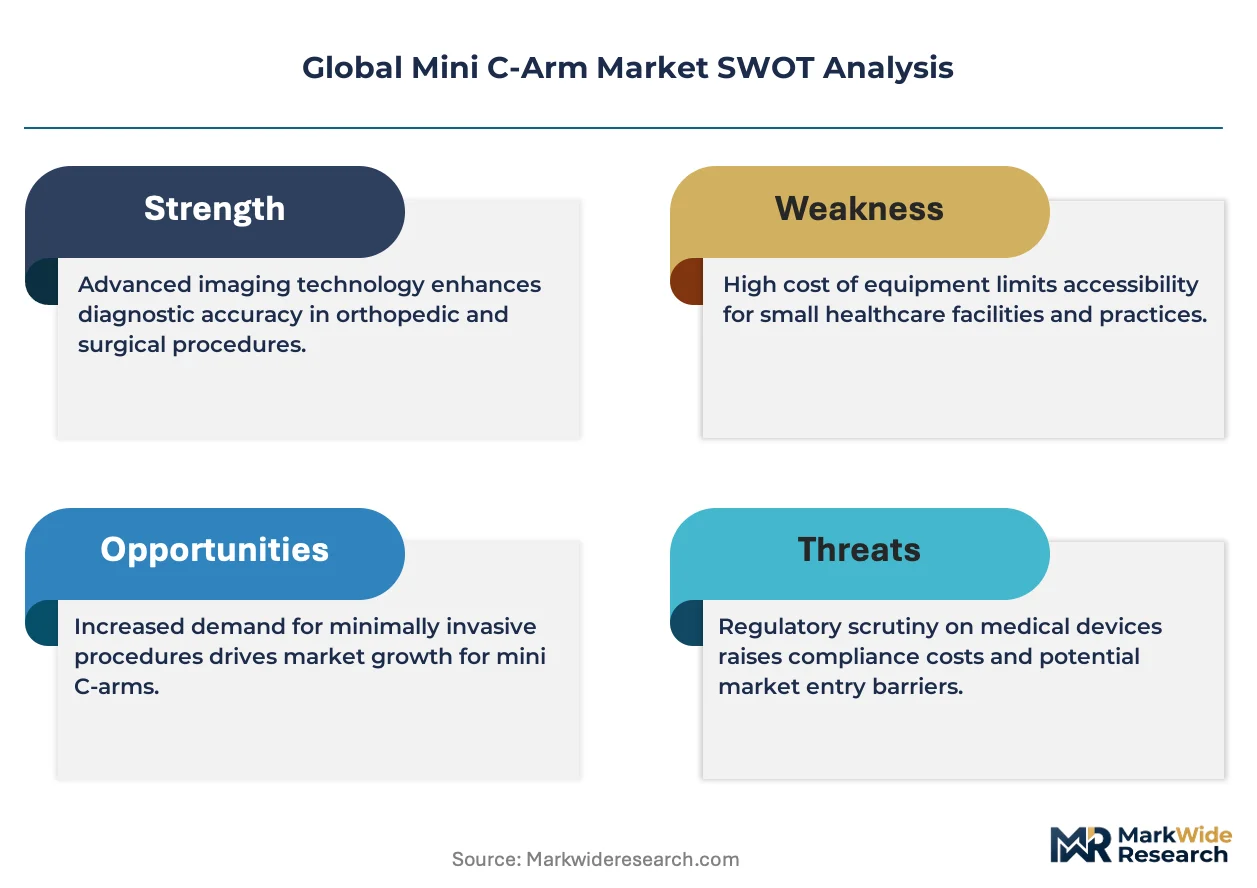
ASC procurement consolidation in Texas and Florida is forcing detector manufacturers to absorb CMOS sensor cost compression while maintaining FDA 510(k) compliance documentation, compressing margins across mid-tier system integrators unable to match conglomerate scale economics.
Pricing Analysis
Value-based pricing anchored to procedure throughput and system uptime dominates ASC contract negotiations, with three-tier pricing structure across premium, standard, and economy levels separating Siemens Healthcare's enterprise PACS-integrated bundles from Ziehm Imaging's orthopedic-specialist configurations and Perlong Medical's price-sensitive developing-market units. Price differentiation rests on CE marking tier and after-sales service bundling, with EU MDR post-market surveillance infrastructure commanding premium positioning. Cost compression in standard-tier systems is intensifying because CMOS manufacturing scale effects have collapsed detector cost curves. Brazilian outpatient surgery centers exhibit highest price sensitivity, while United States ASC chains with centralized GPO contracts demonstrate lowest sensitivity due to operational expense predictability requirements.
Supply Chain Analysis
CE marking and FDA 510(k) qualification gating restricts X-ray tube sourcing to German and Japanese specialty manufacturers, with CMOS sensor fabrication concentrated in China, South Korea, and Taiwan. Critical component dependencies include high-voltage X-ray tubes, flat-panel detector substrates, and precision motion control systems. Single-source vulnerability in specialized tube manufacturing exposes lead time volatility for system integrators lacking captive supply arrangements. Distribution runs through hospital GPO contracts in the United States, direct manufacturer-to-clinic relationships in Germany, and designated marketing authorization holders in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with captive detector manufacturing and established EU MDR post-market surveillance infrastructure, with smaller specialists facing displacement from CMOS sensor cost compression and ASC procurement centralization.
For Market Incumbents: Extend service contract penetration through predictive maintenance software integration, locking in multi-year replacement cycles before third-party clinical engineering firms capture preventive maintenance volumes. Deepen backward integration into CMOS sensor fabrication to defend against Chinese domestic manufacturers leveraging Yangtze River Delta scale effects. Prioritize CE marking pathway investments to capture EU MDR procurement consolidation rewards.
For New Entrants and Emerging Players: Launch via veterinary clinic direct sales models in the United Kingdom and United States, where reduced regulatory burden and lighter price sensitivity create white-space opportunity outside human medical procurement complexity. Target companion animal orthopedic surgery applications with compact wireless detector configurations. Exploit Japan PMDA pathway refinement through designated marketing authorization holder partnerships to accelerate foreign manufacturer registration timelines.
For Investors and Strategic Acquirers: The window for entry favors mid-scale specialists with established orthopedic fluoroscopy positioning and intact CE marking infrastructure, viable over the extended projection horizon as conglomerates pursue portfolio rationalization. Acquisition signals include EU MDR vigilance system deployment capability and existing United States ASC service contract density. Watch for CMOS sensor cost curve inflection as the indicator for mid-tier pricing collapse and accelerated consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR post-market surveillance infrastructure captures multi-year hospital procurement locks across French and German systems. |
| Backward Integration into Detector Manufacturing | Captive CMOS sensor supply reduces lead time volatility and defends margin position against Chinese scale competitors. |
| Hospital System Partnership | Texas and Florida ASC chain consolidation creates standardized fleet configuration opportunities with centralized purchasing leverage. |
| Software Companion Development | Predictive maintenance platforms lock in service contract renewals before third-party clinical engineering firms capture volumes. |
| Reimbursement Strategy | Outpatient orthopedic procedure migration in United States Medicare and commercial payer networks secures demand visibility for capital planning. |
Research Methodology
Document review covered FDA 510(k) premarket notification filings, EU MDR technical documentation, and hospital procurement database records, complemented by interviews with ASC operations directors, biomedical engineering managers, orthopedic surgeons, and GPO contracts specialists. Secondary validation drew from CMS Medicare reimbursement data, Japanese PMDA foreign manufacturer registration filings, and CMOS sensor trade flow records. Bottom-up unit shipment estimates by product configuration and top-down revenue triangulation against imaging equipment manufacturer disclosures were cross-referenced for convergence.
Historical shipment trajectories were cross-referenced against panel input from equipment procurement committees and clinical engineering service providers across the analysis window. Segmentation dimensions modeled include mobility configuration, detector architecture, application specialty, and end-user facility type, with CAGRs derived from procedure volume elasticity and replacement cycle compression dynamics. Forecast inputs incorporated outpatient orthopedic migration rates and EU MDR compliance cost pass-through assumptions.
Regulatory pathway delays, ASC capital expenditure freezes, and CMOS sensor supply disruption are the dominant revision risks that would warrant forecast adjustment. A model refresh is warranted upon material change in FDA radiation dose reporting mandate implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Asia-Pacific Digital Radiology Market
Medical Imaging
China Medical Imaging Market
Medical Imaging
Europe Mobile Tomography Market
Medical Imaging
South Korea Computed Tomography Market
Medical Imaging
Preclinical Ultrasound Systems Market
Medical Imaging
Asia Pacific Open System MRI Market
Medical Imaging
China Mammography Market
Medical Imaging
Global Veterinary CT Scanner Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
PACS and RIS Market
Medical Imaging
Contrast Media Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
North America Digital X-Ray Market
Medical Imaging
Global Picture Archiving Communications System Market