
 Global Microcatheter Market | 2026-2036
Global Microcatheter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microcatheter Market Foresight
Aftermarket service revenue for microcatheter navigation systems is fragmenting as OEMs and third-party refurbishers compete for maintenance contracts. Medtronic leverages its integrated surgical ecosystem to capture recurring service income across installed base. Boston Scientific Corporation anchors its position through dedicated interventional cardiology training programs that lock in hospital purchasing preferences.
A microcatheter is a small-diameter, flexible catheter typically constructed from braided nitinol or polymer composites with an outer diameter below 3 French, designed to access distal vasculature for diagnostic or therapeutic delivery. The device enables superselective cannulation of cerebral, coronary, or peripheral vessels during minimally invasive procedures. Over-the-wire microcatheters retain dominant share in complex neurovascular navigation where torque response and pushability determine procedural success. Flow-directed microcatheters are gaining fastest in aneurysm embolization cases where distal vessel conformability reduces vessel trauma. Neurovascular interventions command premium pricing relative to peripheral vascular procedures due to higher regulatory barriers and specialized physician training requirements.
FDA premarket notification pathways and EU MDR technical documentation requirements shape product development timelines and market entry costs for microcatheter manufacturers. ISO 13485 quality management standards and Japan PMDA foreign manufacturer registration create additional compliance layers for cross-border commercialization. Stakeholders must monitor evolving reimbursement codes for thrombectomy and embolization procedures across Medicare, NHS England, and German statutory health insurance frameworks.
Market Dynamics
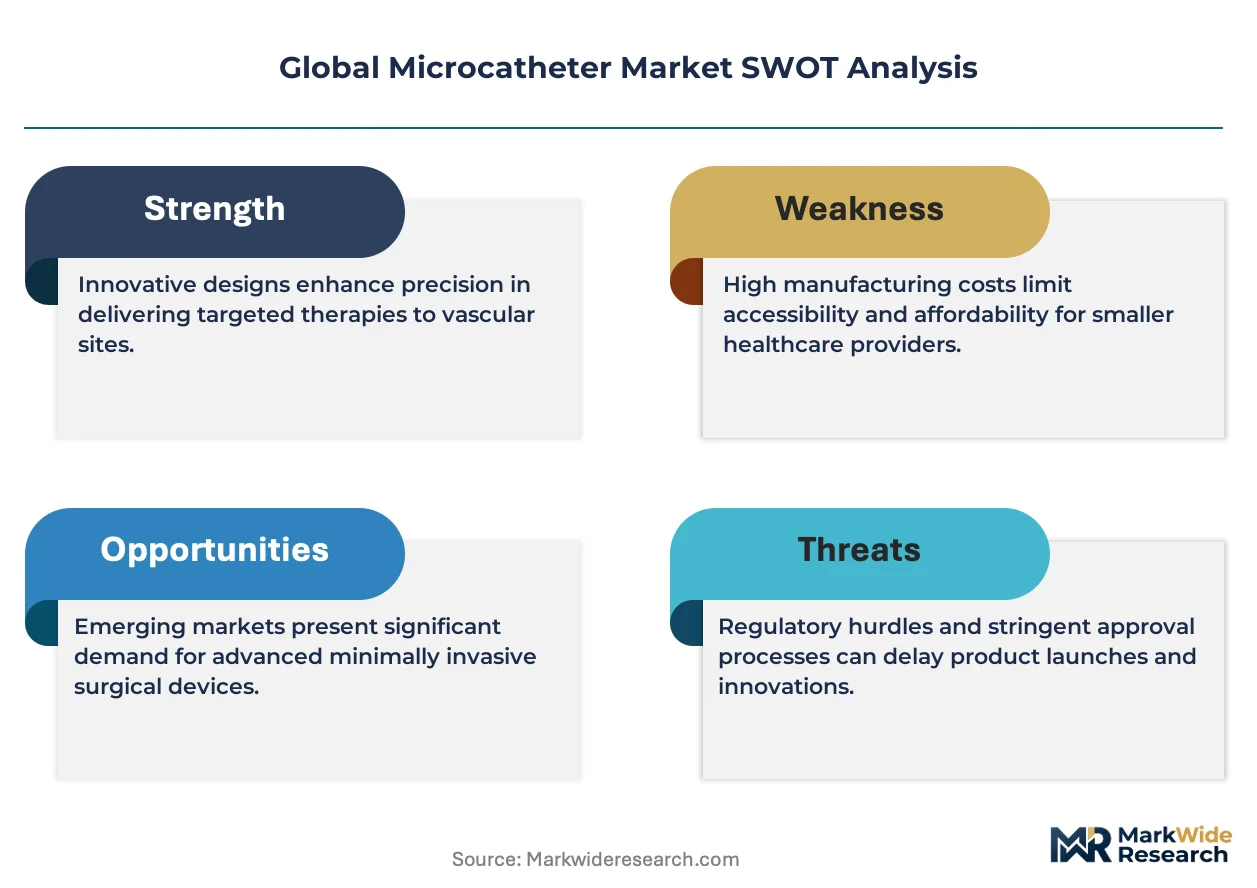
EU MDR technical documentation requirements are compressing product development timelines and elevating market entry costs, forcing manufacturers to restructure clinical evidence portfolios and quality management systems ahead of notified body capacity constraints.
Growth Catalysts
- Neurovascular intervention volumes:Specialized stroke centers in Germany, Japan, and the United States are scaling thrombectomy procedural throughput, creating pull-through demand for superselective navigation platforms.
- ISO 13485 harmonization:Converging quality management standards across Japan PMDA, FDA, and EU MDR pathways are reducing redundant audit burdens for multi-regional manufacturers.
- Braided nitinol torque transmission:Advanced composite constructions enabling distal vessel access in tortuous cerebral anatomy are expanding treatable patient populations previously excluded from endovascular therapy.
Market Restraints
- Notified body bottlenecks:EU MDR designation delays are extending time-to-market for new microcatheter submissions beyond historical CE-marking windows.
- Polymer resin concentration:Specialized Pebax and polyimide supply chains cluster among limited European and Asian chemical processors, exposing manufacturers to input volatility.
- Physician training thresholds:Complex neurovascular procedures require fellowship-level credentialing that constrains addressable operator pools in secondary and tertiary markets.
Strategic Opportunities
- Peripheral vascular expansion:Below-the-knee chronic limb ischemia interventions in India and Brazil remain underpenetrated relative to coronary and neurovascular adoption curves.
- Flow-directed platform extension:Conformable distal tip technologies proven in aneurysm embolization are migrating into arteriovenous malformation and tumor embolization applications.
- Japan PMDA foreign manufacturer registration streamlining:Revised importer-of-record frameworks are reducing administrative friction for Western OEMs seeking direct market access without domestic subsidiary requirements.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and hemocompatibility validation protocols for novel polymer formulations extend development cycles by 12-18 months.
- Legacy system integration:Next-generation navigation platforms must maintain backward compatibility with installed angiography suites from multiple imaging equipment vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microcatheter Market |
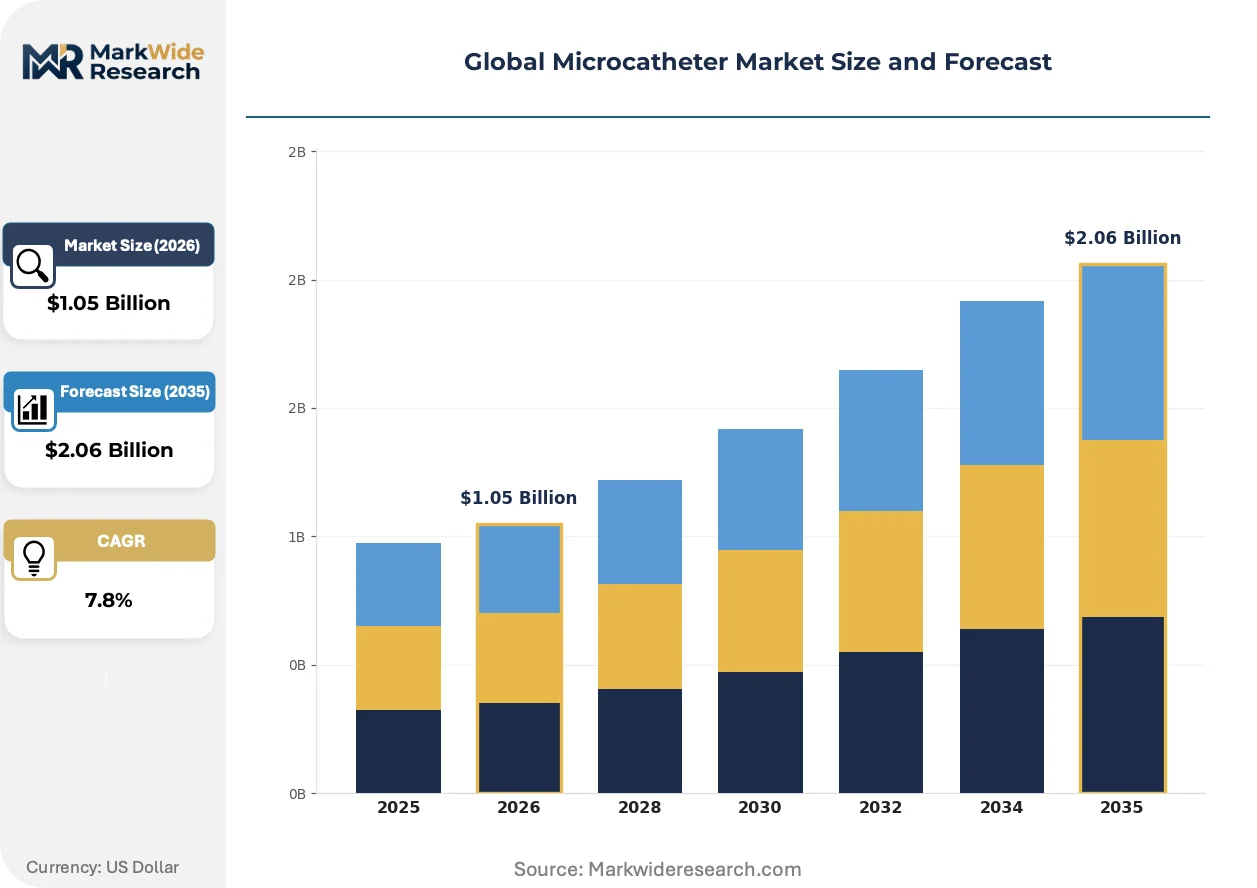
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Microcatheters, Flow-Directed Microcatheters, Over-the-Wire Microcatheters, Rapid Exchange Microcatheters, Steerable Microcatheters Application: Neurovascular Interventions, Peripheral Vascular Procedures, Coronary Artery Treatment, Urology Procedures, Gastroenterology Procedures End User: Specialty Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Cardiac Clinics, Interventional Radiology Centers Deployment: Elective Procedures, Emergency Surgeries, Outpatient Settings, Inpatient Settings, Minimally Invasive Procedures |
| Companies Covered | Medtronic, Boston Scientific Corporation, Terumo Corporation, Stryker, Penumbra Inc., Merit Medical Systems, Teleflex Incorporated, Asahi Intecc, Surmodics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microcatheter Market Shifts & Advancements
Active material science programs and procedural workflow digitization are redefining performance benchmarks for distal access platforms, compressing the gap between diagnostic capability and therapeutic delivery precision.
Dual-layer braided construction with variable pitch density is migrating from coronary applications into neurovascular portfolios, enabling torque response previously achievable only with larger French-size platforms. Academic stroke centers in the United States and Germany are piloting these architectures for middle cerebral artery M2 segment access. The shift is compressing the addressable market for traditional single-layer polymer microcatheters in complex anatomy cases.
EU MDR Annex XIV clinical evaluation requirements are mandating systematic post-market clinical follow-up for Class III devices, compelling manufacturers to build prospective registries rather than rely on equivalence arguments. This regulatory architecture favors organizations with established infrastructure for real-world evidence capture across multiple jurisdictions. Neurovascular indications face the steepest compliance gradient due to higher-risk classification and limited predicate device availability.
Hospital procurement committees are consolidating vendor relationships around integrated stroke program contracts that bundle microcatheter supply with thrombectomy device, aspiration pump, and training commitments. This behavioral shift displaces spot purchasing of individual navigation platforms and concentrates volume among suppliers offering comprehensive interventional suites. The pattern is most pronounced in United States integrated delivery networks and German hospital federations seeking to standardize device inventories across multiple cath lab sites.
Global Microcatheter Market Segmentation
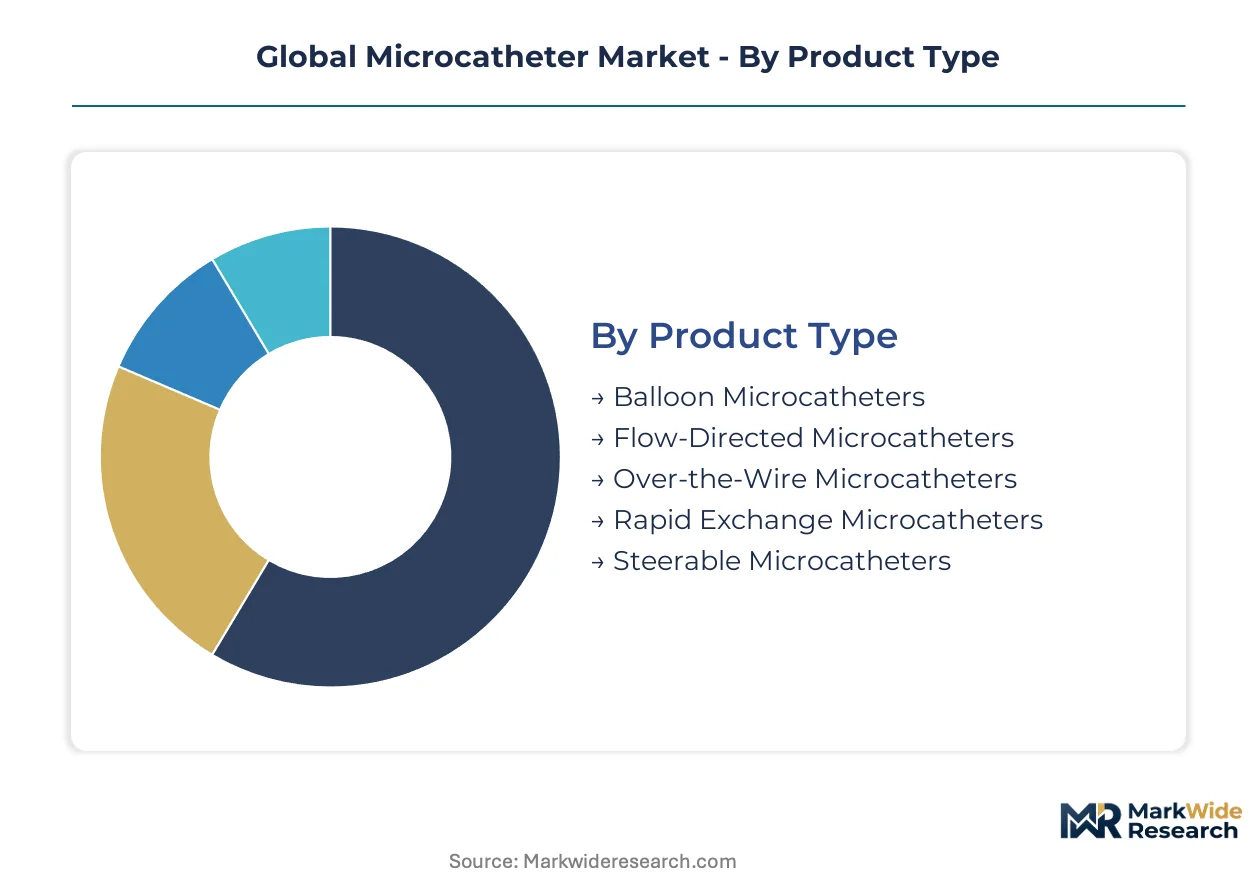
Microcatheter segmentation reflects divergent technical requirements across anatomical territories and procedural settings. Product architecture, application site, care venue, and urgency level each impose distinct performance specifications that manufacturers must address through specialized platform development.
Product Type:
Mature braided architectures dominate high-volume coronary workhorses, while emerging tip-conformability technologies capture share in neurovascular navigation where vessel tortuosity demands specialized engineering.
- Over-the-Wire Microcatheters:Braided nitinol or polymer composite construction delivers torque response and pushability essential for navigating tortuous cerebral vasculature. Demand concentrates in United States and German stroke centers scaling thrombectomy volumes, constrained by physician training thresholds that limit addressable operator pools.
- Flow-Directed Microcatheters:Distal tip conformability reduces vessel trauma during aneurysm embolization by allowing passive navigation with blood flow rather than mechanical force. Japanese neurovascular specialists are adopting these platforms fastest for arteriovenous malformation cases where traditional wire-guided approaches risk perforation.
- Balloon Microcatheters:Integrated inflation lumens enable simultaneous navigation and vessel remodeling in coronary and peripheral applications.
- Rapid Exchange Microcatheters:Short wire-exit ports reduce procedural time and radiation exposure in cardiac catheterization labs.
- Steerable Microcatheters:Active tip deflection mechanisms target complex anatomies in biliary and urological interventions.
Over-the-Wire Microcatheters handle the majority of throughput; Flow-Directed Microcatheters are expanding most quickly on share.
Application:
Revenue concentration follows regulatory barrier height, with higher-risk anatomical sites commanding premium positioning and specialized commercial infrastructure.
- Neurovascular Interventions:Superselective cannulation of cerebral vessels for thrombectomy, aneurysm embolization, and arteriovenous malformation treatment. German and Japanese stroke centers are scaling procedural throughput fastest, though EU MDR Class III device requirements compress development timelines and elevate market entry costs.
- Coronary Artery Treatment:Distal lesion access and side-branch wiring in complex percutaneous coronary intervention. United States interventional cardiology programs generate the largest installed base volumes, with procurement committees consolidating vendor relationships around integrated device suites.
- Peripheral Vascular Procedures:Below-the-knee chronic limb ischemia interventions remain underpenetrated in India and Brazil relative to coronary adoption curves.
- Urology Procedures:Ureteral stricture navigation and stone extraction access in ambulatory settings.
- Gastroenterology Procedures:Biliary drainage and pancreatic duct cannulation in specialized endoscopy units.
Coronary Artery Treatment generates the highest absolute procedure volumes; Neurovascular Interventions show the steepest expansion trajectory.
End User:
Capital intensity and reimbursement frameworks segment demand across facility types, with comprehensive stroke centers capturing the most complex cases.
- Specialty Hospitals:Comprehensive stroke centers and cardiac institutes with 24/7 interventional capabilities. United States integrated delivery networks and German hospital federations are standardizing device inventories across multiple cath lab sites, concentrating purchasing power among suppliers offering bundled program contracts.
- Interventional Radiology Centers:Freestanding facilities performing tumor embolization and peripheral vascular work. Japan's revised importer-of-record frameworks are reducing administrative friction for Western OEMs seeking direct access to these specialized venues.
- Diagnostic Centers:Limited interventional capabilities focused on diagnostic angiography and pre-procedural planning.
- Ambulatory Surgical Centers:Lower-acuity peripheral and urological procedures with same-day discharge protocols.
- Cardiac Clinics:Office-based practices with selective catheterization capabilities for stable coronary disease.
Specialty Hospitals command the largest revenue share; Interventional Radiology Centers are gaining share fastest as outpatient migration accelerates.
Deployment:
Urgency stratification determines inventory location, sterilization protocols, and device readiness requirements across care settings.
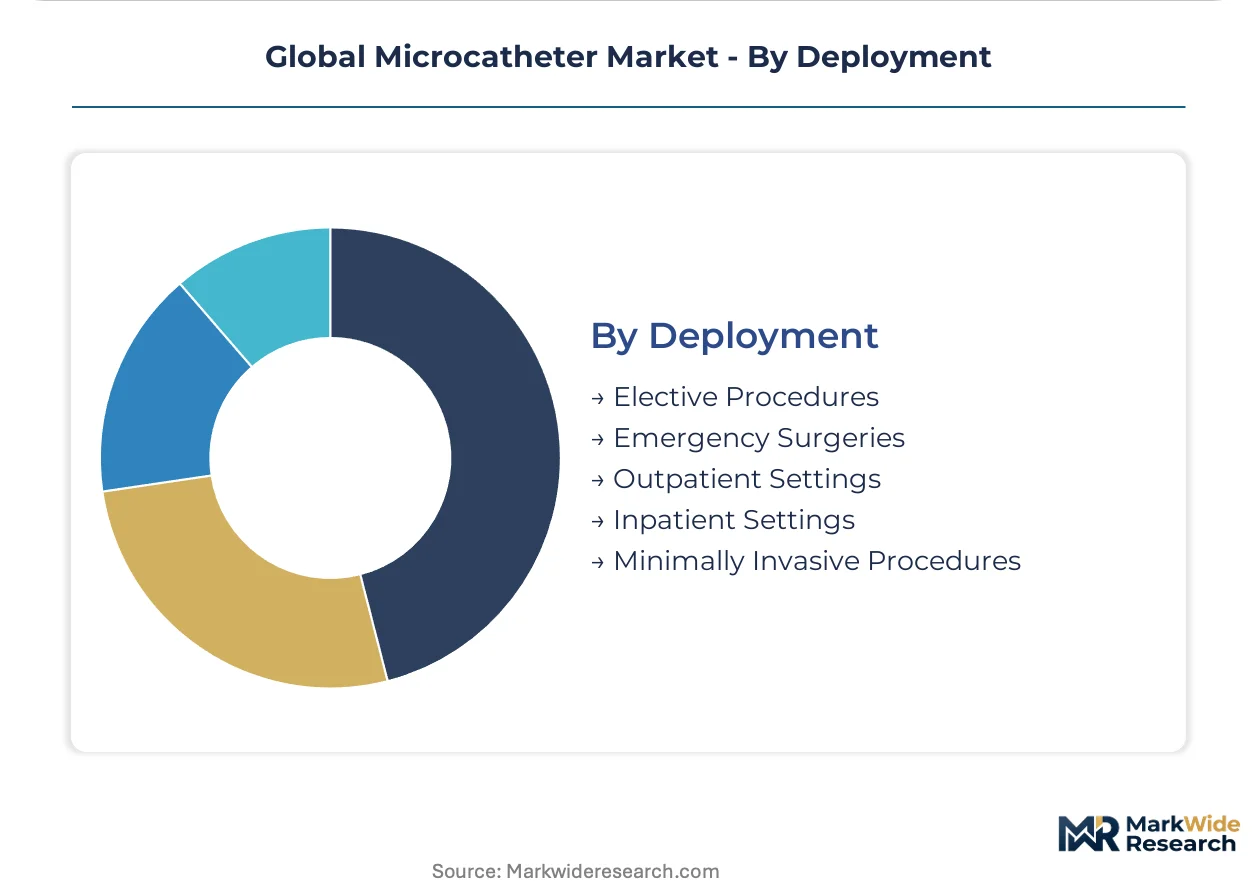
- Emergency Surgeries:Acute ischemic stroke thrombectomy and ruptured aneurysm embolization requiring immediate device availability. United States comprehensive stroke centers maintain dedicated neurovascular inventory with 24/7 on-call teams, with reimbursement codes under Medicare shaping procurement priorities.
- Minimally Invasive Procedures:Elective endovascular interventions across all anatomical territories. German statutory health insurance frameworks and NHS England reimbursement schedules influence adoption velocity for novel navigation platforms in these scheduled cases.
- Elective Procedures:Scheduled coronary and peripheral interventions with advance device planning.
- Outpatient Settings:Same-day discharge protocols for stable peripheral vascular and urological cases.
- Inpatient Settings:Post-procedural observation requirements for higher-risk anatomical interventions.
Emergency Surgeries drive premium pricing; Minimally Invasive Procedures are climbing the fastest on procedural volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer processors and nitinol braiding facilities cluster in Germany, Japan, and the United States, creating geographic lock-in for microcatheter manufacturing. These three countries host the majority of notified body capacity and regulatory expertise that shapes market access timelines.
United States
Comprehensive stroke centers in Texas, Florida, and California are scaling thrombectomy procedural volumes fastest. FDA 510(k) premarket notification pathways and Medicare reimbursement codes for mechanical thrombectomy create predictable market entry economics. The Minneapolis and Boston metropolitan areas concentrate device development operations for major OEMs.
Germany
Specialized interventional cardiology and neurovascular centers in Bavaria and North Rhine-Westphalia generate premium demand for superselective navigation platforms. EU MDR notified body bottlenecks in Berlin and Munich are extending certification timelines beyond historical CE-marking windows. The Stuttgart industrial corridor hosts precision braiding operations supplying nitinol torque-transmission components.
Japan
Tokyo and Osaka metropolitan stroke centers are adopting flow-directed microcatheter platforms fastest for arteriovenous malformation cases. PMDA foreign manufacturer registration streamlining and revised importer-of-record frameworks are reducing administrative friction for Western OEMs. The Kansai region maintains concentrated expertise in distal tip conformability engineering.
India
Below-the-knee chronic limb ischemia interventions remain underpenetrated in Maharashtra and Karnataka relative to coronary adoption curves. CDSCO medical device rules and state-level procurement frameworks for government hospitals shape commercial access patterns. Hyderabad and Bengaluru are emerging as interventional radiology training hubs for peripheral vascular specialists.
Brazil
Minimally invasive endovascular procedures are expanding in São Paulo and Rio de Janeiro through private hospital networks. ANVISA medical device registration requirements and import tariff structures influence pricing and local partnership strategies. The southeastern industrial corridor is developing limited domestic assembly capacity for disposable catheter components.
Global Microcatheter Market Competitive Landscape
Integrated surgical ecosystems and specialized interventional platforms split the market between comprehensive program suppliers and focused navigation specialists. The vendor base concentrates around three strategic archetypes: diversified medtech conglomerates with bundled stroke program offerings, mid-scale interventional specialists with dedicated training infrastructure, and component-focused technology licensors. M&A activity targets real-world evidence capture capabilities and notified body relationship assets. Geographic expansion through distributor acquisition dominates competitive moves in underpenetrated peripheral vascular markets.
Within the diversified medtech tier, Medtronic and Boston Scientific Corporation occupy positions anchoring integrated hospital contracting. Terumo Corporation exemplifies the specialized interventional archetype with concentrated expertise in distal access engineering. These three entities represent the dominant competitive anchors shaping procurement committee vendor consolidation patterns across United States integrated delivery networks and German hospital federations.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Terumo Corporation |
| Stryker |
| Penumbra Inc. |
| Merit Medical Systems |
| Teleflex Incorporated |
| Asahi Intecc |
| Surmodics Inc. |
| Others |
Supply & Pricing Matrix
Frankfurt-Rotterdam rail corridors carry Pebax and polyimide resin shipments from specialized European chemical processors to nitinol braiding facilities in Stuttgart and Munich, with freight cost volatility feeding directly into both supply concentration premiums and the three-tier pricing structure that separates premium braided platforms from standard polymer constructions from economy-grade alternatives.
Pricing Analysis
Aftermarket service contracts and refurbishment revenue streams now drive lifetime value capture for navigation system OEMs. Pricing stratifies across premium, standard, and economy tiers based on torque-response certification levels and bundled training program depth. Cost compression in the standard tier is intensifying because third-party refurbishers are undercutting OEM maintenance rates. Interventional radiology centers in India and Brazil exhibit highest price sensitivity; comprehensive stroke centers in Germany and the United States show lowest sensitivity due to bundled program contracting.
Supply Chain Analysis
Extended payment terms from German and Japanese braiding facilities now stretch to 90-120 days, straining working capital for mid-scale manufacturers. Nitinol wire supply concentrates in Germany, Japan, and the United States; Pebax polymer resin sources from France, Germany, and limited Asian chemical processors. Single-source vulnerability in EU MDR-notified body capacity creates certification bottlenecks that delay production ramp timing. Distribution runs through regional medical device distributors with GPO contract access in the United States and hospital federation procurement in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microcatheter adoption sits in early-cycle expansion across peripheral vascular territories, with below-the-knee chronic limb ischemia procedural volumes in India and Brazil running multiple years behind coronary and neurovascular penetration curves.
For Market Incumbents: Entrench position through backward integration into nitinol braiding capacity and captive supply of specialized polymer resins. Lock in comprehensive stroke program contracts that bundle device supply with thrombectomy platforms and training commitments. Defend against third-party refurbisher encroachment by embedding proprietary navigation software that requires OEM service access. For New Entrants and Emerging Players: Build out interventional radiology center relationships in Maharashtra and Karnataka where government hospital procurement frameworks create accessible entry points. Target arteriovenous malformation applications with flow-directed platform extensions proven in Japanese neurovascular centers. Pursue direct importer-of-record registration under streamlined PMDA frameworks to bypass domestic subsidiary requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medtech conglomerates seeking to divest non-core navigation assets amid EU MDR compliance cost pressures. Five-to-ten-year viability hinges on real-world evidence capture infrastructure and notified body relationship depth. Watch for inflection when EU MDR Annex XIV post-market clinical follow-up requirements trigger consolidation among sub-scale manufacturers unable to fund prospective registry builds.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Buildout | Notified body capacity constraints in Berlin and Munich extend certification timelines beyond historical windows. |
| Flow-Directed Platform Extension | Japanese stroke centers in Tokyo and Osaka drive fastest adoption for arteriovenous malformation applications. |
| Peripheral Vascular Geographic Expansion | Below-the-knee interventions in Maharashtra and Karnataka remain underpenetrated relative to coronary curves. |
| Real-World Evidence Infrastructure Investment | EU MDR Annex XIV mandates systematic post-market clinical follow-up for Class III neurovascular devices. |
| Integrated Stroke Program Contracting | United States IDNs and German hospital federations consolidate vendor relationships around bundled device suites. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with interventional neuroradiologists, cath lab directors, biomedical engineers, GPO contracts managers, and OEM product development executives. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, German statutory health insurance procedure codes, and Japan PMDA foreign manufacturer registration records. Bottom-up procedural volume estimates and top-down device revenue triangulation were cross-referenced against hospital procurement database extracts.
Calibration against historical neurovascular and coronary procedural growth trajectories anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, anatomical application site, care venue capital intensity, and urgency stratification. CAGRs were derived from slope analysis of procedural adoption curves and device pricing trend lines. Forecast inputs incorporated EU MDR notified body capacity constraints, PMDA importer-of-record framework revisions, and Medicare thrombectomy reimbursement code stability.
Stress conditions across notified body certification delays, polymer resin supply disruptions, and physician training pipeline constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway stability and procedural reimbursement continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
Global Non-Surgical Aesthetic Devices Market
Medical Devices
Japan Hemostats Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
India Diabetes Devices Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
Neonatal Hearing Screening Devices Market
Medical Devices
Electroencephalography (EEG) Systems Market
Medical Devices
Sweden Respiratory Devices Market
Medical Devices
Global Auto-Injectors Market
Medical Devices
Europe Surgical Visualization Products Market
Medical Devices
Urodynamic Devices Market
Medical Devices
Minimally Invasive Spine Technologies Market
Medical Devices
Global on-Body Injectors Market
Medical Devices
Epistaxis Devices Market