
 Europe Fire-Resistant Glass Market | 2026-2036
Europe Fire-Resistant Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fire-Resistant Glass Market Foresight
European specialty glass producers is repositioning capacity toward higher-performance fire-rated product lines. Saint Gobain S A leverages its integrated float-glass network to sustain cost advantages across laminated and tempered fire-rated outputs. Schott specializes in ceramic-based fire-resistant panels, dominating niche applications where thermal shock tolerance exceeds standard intumescent specifications. AGC Glass Europe anchors its competitive stance through geographic coverage of commercial facade projects across Western and Central Europe.
Europe fire-resistant glass comprises engineered glazing systems designed to maintain structural integrity and limit heat transfer during standardized fire exposure periods, typically rated from 30 minutes to 180 minutes depending on intumescent interlayer composition, ceramic frit density, or wired reinforcement configuration. Laminated glass with intumescent interlayers leads volume shipments for fire-door and partition applications where optical clarity must combine with code-compliant fire ratings. Tempered glass competes aggressively on cost for window applications with lower duration requirements, while ceramic-based technology captures premium positioning in facade segments demanding extended fire resistance without dimensional distortion.
The EU Construction Products Regulation and national implementations through Germany's KBA-notified bodies and France's CSTB certification framework mandate CE-marked fire resistance testing under EN 1363 and EN 1364 standards, effectively filtering non-compliant imports from Eastern European and Asian suppliers. ECHA REACH compliance adds material transparency requirements for sodium silicate interlayers and borosilicate ceramic components, raising formulation documentation costs for smaller compounders. Stakeholders must monitor divergence between harmonized EU test protocols and emerging national amendments in Poland and Italy that could fragment product certification requirements across the continent.
Market Dynamics
The EU Green Deal is forcing a wholesale reconfiguration of glazing specifications across commercial renovation pipelines, as energy-efficiency retrofits now bundle mandatory fire-safety upgrades into single procurement packages.
Growth Catalysts
- EU Construction Products Regulation:Harmonized CE marking requirements under EN 1363 and EN 1364 standards are filtering out non-compliant imports, creating protected demand channels for certified European producers.
- Commercial building renovation:Germany's commercial retrofit pipeline is bundling fire-rated glazing with thermal performance upgrades, concentrating demand in multi-tenant office and hospitality verticals.
- Intumescent interlayer advances:Sodium silicate formulations with improved optical clarity are expanding addressable applications beyond traditional fire-door segments into full-height architectural glazing.
Market Restraints
- Soda ash and boron supply concentration:Input cost volatility from Turkish and South American boron suppliers compresses margin stability for ceramic-based product lines.
- REACH compliance documentation:ECHA material transparency mandates for interlayer chemistry raise fixed formulation costs, disadvantaging smaller compounders against integrated glass producers.
- Tempered glass substitution:Lower-duration fire ratings in window applications face aggressive price competition from standard tempered alternatives that meet minimum code requirements.
Strategic Opportunities
- Polish and Italian regulatory divergence:Emerging national amendments to harmonized EU test protocols create first-mover advantage for producers establishing localized certification capabilities ahead of fragmentation.
- Facade-integrated photovoltaic fire glazing:Convergence of Building-Integrated Photovoltaics with extended fire-resistance ratings opens premium positioning in net-zero commercial developments.
- Direct contractor procurement platforms:Digital specification tools are disintermediating traditional distributor channels, enabling producers to capture specification influence earlier in project timelines.
Industry Challenges
- Fire-test engineer scarcity:Specialized expertise in EN 1363 furnace testing and CSTB certification procedures commands wage premiums that extend R&D timelines for new product launches.
- Multi-standard certification complexity:Simultaneous compliance with Germany's KBA-notified bodies, France's CSTB framework, and diverging Polish amendments fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fire-Resistant Glass Market |
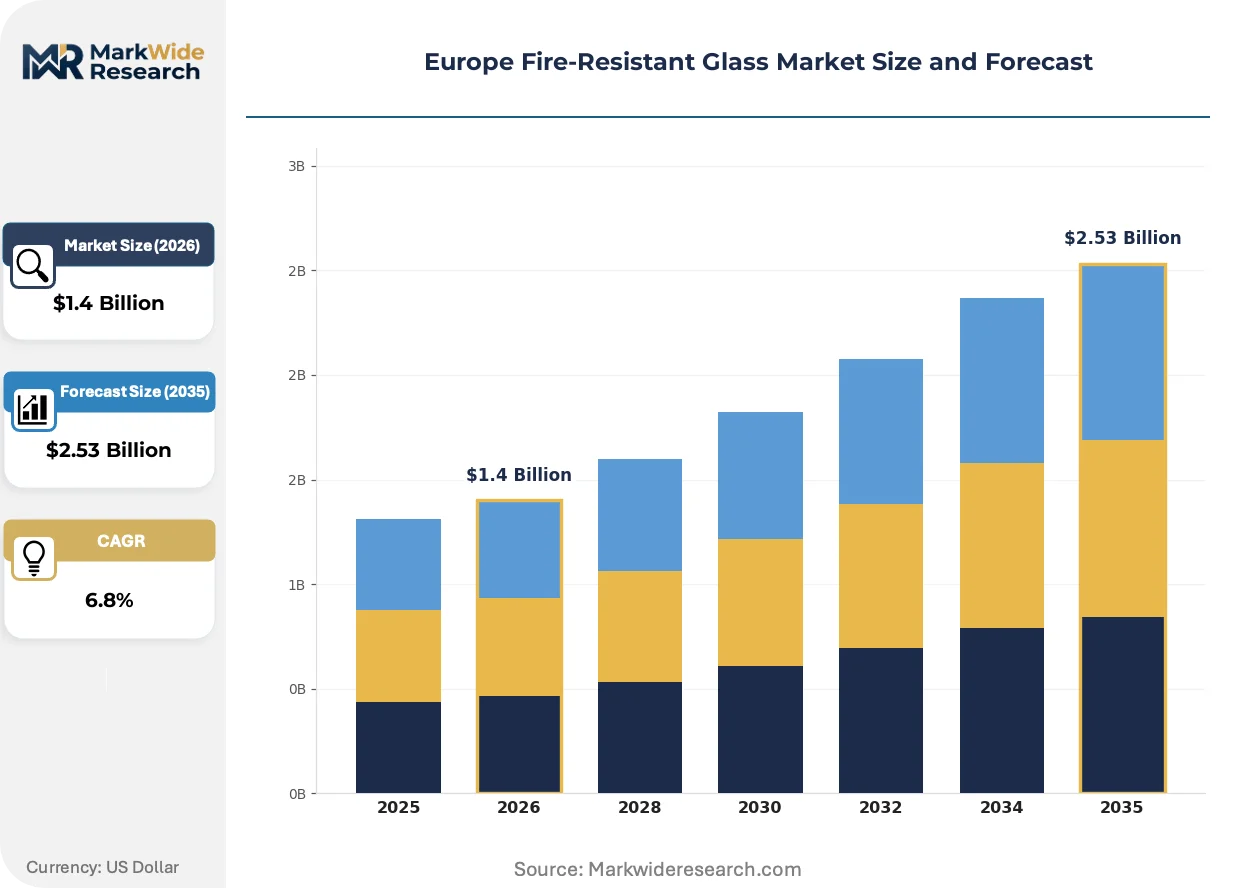
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Glass, Laminated Glass, Tempered Glass, Wired Glass End User: Commercial Buildings, Residential Properties, Industrial Facilities, Hospitality Sector Application: Fire Doors, Windows, Partitions, Facades Technology: Intumescent, Non-intumescent, Ceramic-based, Composite |
| Companies Covered | Nippon Sheet Glass Co Ltd, GLAS TROSCH AG, AGC Glass Europe, PRESS GLASS Holding SA, POLFLAM Sp z o o, Saint Gobain S A, Pyroguard Ltd, Promat, Schott, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fire-Resistant Glass Market Shifts & Advancements
Fire-resistant glazing is undergoing specification evolution as thermal performance, solar control, and fire ratings converge into single-product procurement decisions. Three forces are actively restructuring competitive positioning.
Electrochromic ceramic fire glazing is electrifying facade specification norms by combining dynamic solar control with 120-minute fire resistance in monolithic panels. High-rise commercial developers in London and Frankfurt are specifying these systems for atrium enclosures where thermal comfort and code compliance must coexist. The technology is electrifying premium segment growth by collapsing what previously required separate glazing layers into unified structural elements.
REACH substance restriction amendments are tightening documentation requirements for borosilicate ceramic components and sodium silicate interlayers used in laminated assemblies. Compounders must now maintain granular supply chain transparency from raw material sources through finished product distribution. Germany's KBA-notified certification bodies are enforcing these requirements most stringently, creating compliance differentiation between established European suppliers and import-dependent distributors.
Specification authority is migrating from general contractors to fire-safety consultants who control submittal approval workflows on large commercial projects. These specialist intermediaries demand extended warranty terms and documented test history that smaller producers struggle to match. France's CSTB-certified projects exhibit this pattern most acutely, where consultant-driven procurement now dominates facade specifications above 50 million euro construction value.
Europe Fire-Resistant Glass Market Segmentation
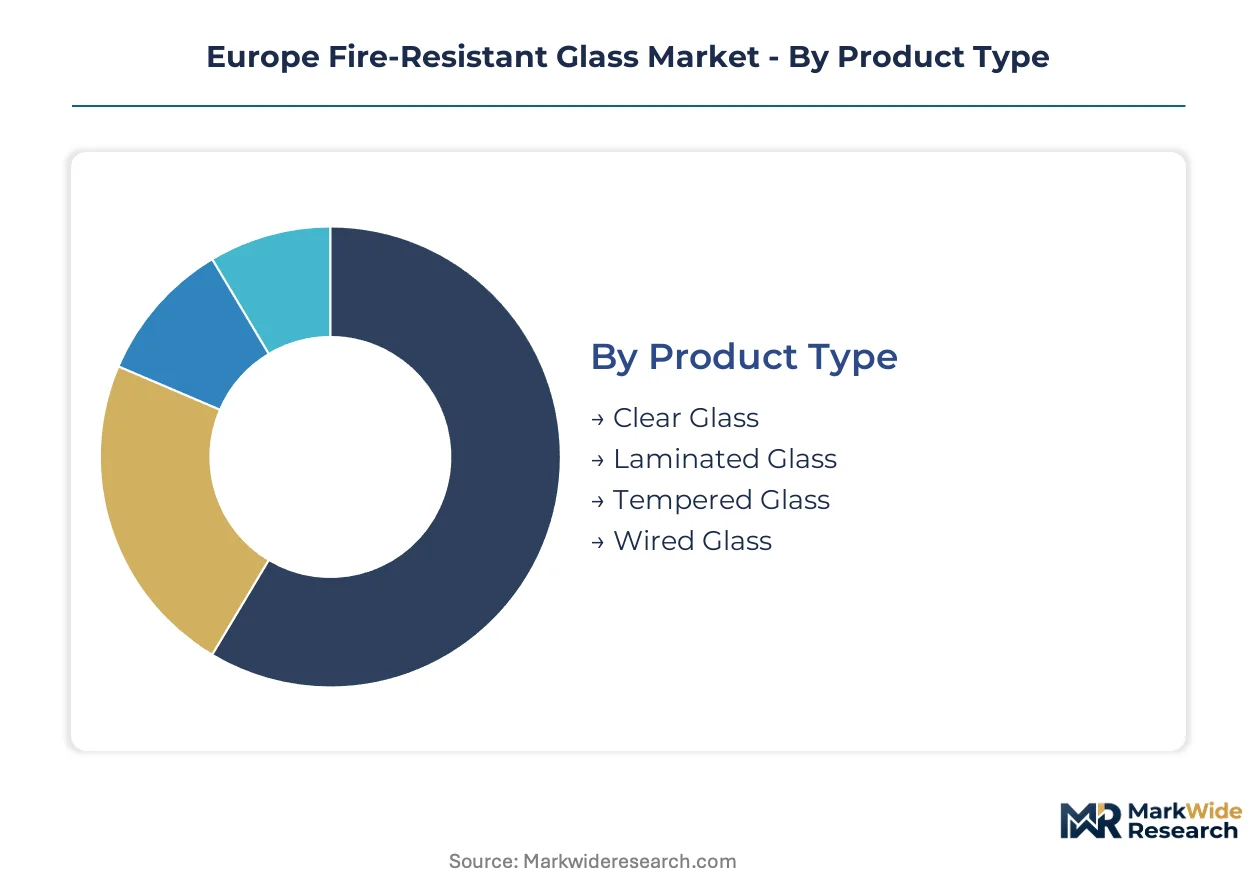
Fire-resistant glass procurement in Europe increasingly bundles performance specifications across multiple dimensions simultaneously. Buyers now specify products by fire rating duration, optical clarity, thermal insulation, and solar control in single purchase orders, collapsing what were historically separate supplier relationships.
Product Type:
Standalone fire-rated panels dominate retrofit applications, while embedded laminated assemblies capture new construction where multi-function glazing is specified from design phase.
- Laminated Glass:Sodium silicate interlayers expand when heated, forming an opaque char barrier that maintains structural integrity for 30 to 120 minutes. Germany's commercial renovation pipeline concentrates demand here, where fire-door upgrades must preserve sightlines while meeting EN 1363 certification.
- Tempered Glass:Thermal shock resistance comes from surface compression layers created during rapid cooling, delivering 20-30 minute ratings at substantially lower cost than laminated alternatives. French and UK window replacement programs specify this grade aggressively where code minimums permit shorter fire resistance durations.
- Clear Glass:Standard soda-lime formulations with surface-applied fire-retardant coatings serve budget-conscious residential applications where optical perfection matters less than price accessibility.
- Wired Glass:Embedded steel mesh provides mechanical retention during fire exposure, persisting in legacy industrial facilities across Poland and Eastern Europe where replacement cycles lag Western markets.
Laminated glass leads volumes today; tempered glass is gaining share fastest in cost-sensitive window segments.
End User:
Procurement authority concentrates with fire-safety consultants on large projects, while direct contractor purchasing dominates smaller-scale residential and light commercial installations.
- Commercial Buildings:Multi-tenant offices and retail complexes across Frankfurt, London, and Paris drive specification of 90-120 minute rated facades and atrium enclosures. The EU Green Deal's energy retrofit mandates bundle thermal performance upgrades with fire-safety replacements, expanding project scopes.
- Hospitality Sector:Hotels and conference facilities prioritize optical clarity in fire-rated partitions to maintain open sightlines in lobbies and circulation spaces. Extended warranty demands from international brand operators filter supplier eligibility toward established European manufacturers with documented EN 1364 test histories.
- Industrial Facilities:Manufacturing plants and warehouses specify wired and tempered grades where fire ratings below 60 minutes suffice and impact resistance matters more than aesthetics.
- Residential Properties:Single-family and multi-family housing in Germany and Austria deploy clear and tempered options primarily for escape-route windows and door vision panels.
Commercial buildings anchor current demand; hospitality applications are expanding most quickly as renovation cycles accelerate.
Application:
Installation location determines fire rating requirements more than building type, with egress path components facing the strictest certification thresholds.
- Fire Doors:Laminated assemblies with intumescent interlayers dominate this segment, delivering 30-90 minute ratings while maintaining door-lite transparency for wayfinding. Germany's KBA-notified bodies enforce the continent's most stringent certification protocols here.
- Facades:Ceramic-based and composite technologies capture high-rise specifications where 120-180 minute ratings must coexist with wind load and thermal performance requirements. London's tall building guidance drives adoption of these premium systems.
- Partitions:Full-height fire-rated glazing in office interiors demands optical clarity combined with acoustic dampening, favoring laminated products with added PVB layers for sound control.
- Windows:Tempered and clear glass grades compete aggressively on price for escape-route and compartmentation applications where shorter ratings are code-compliant.
Fire doors represent the largest application volume; facades follow the steepest expansion trajectory as high-rise construction revives.
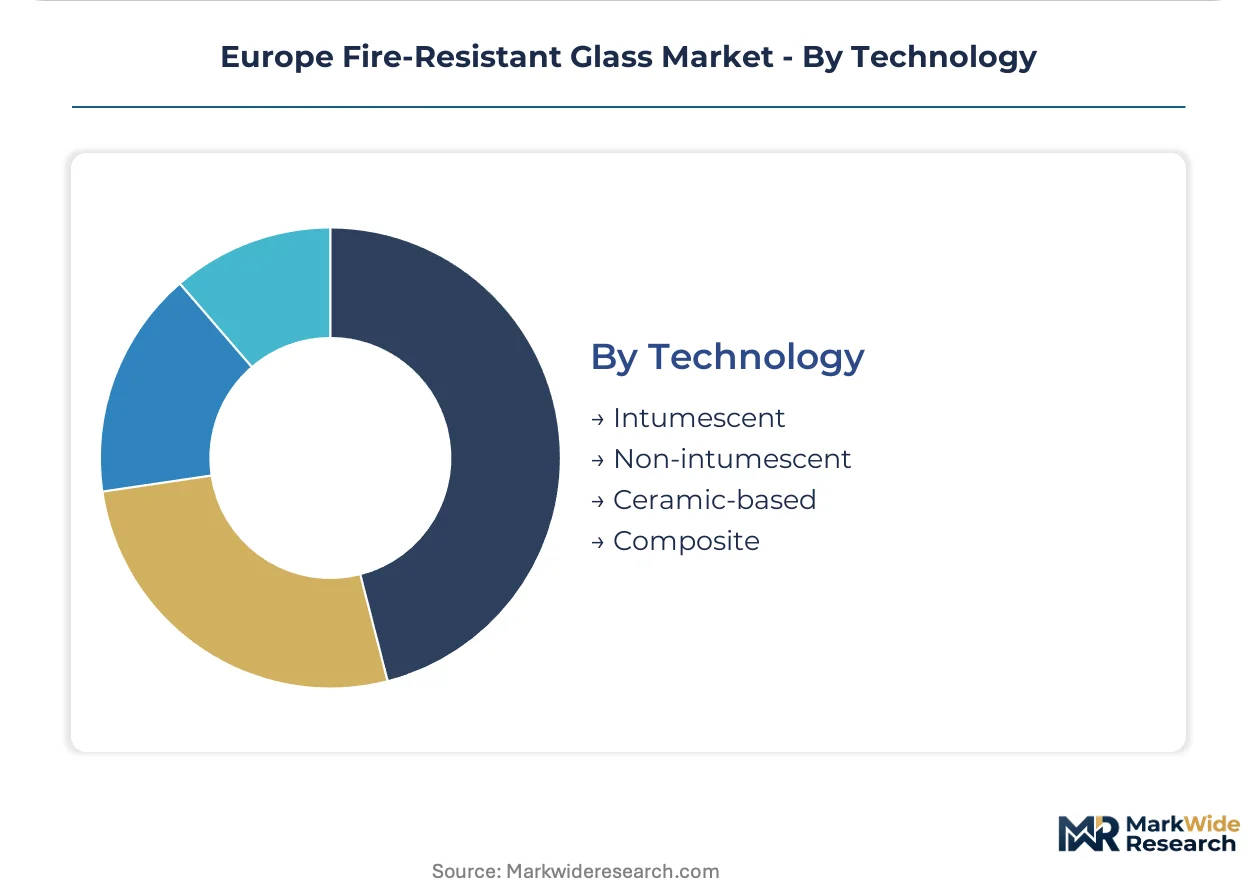
Technology:
Formulation chemistry determines thermal performance limits and directly influences manufacturing asset requirements and supply chain positioning.
- Intumescent:Sodium silicate and graphite-based interlayers expand 10-40x when heated, creating insulating barriers that protect the glass substrate. Continuous lamination lines in Germany and France concentrate production capacity for this technology.
- Ceramic-based:Borosilicate and glass-ceramic monoliths withstand thermal shock beyond 1000°C without dimensional distortion, commanding premium pricing for facade and atrium applications where extended ratings are non-negotiable.
- Non-intumescent:Surface-applied coatings and inherent material properties provide fire resistance without chemical expansion, serving niche applications where coating durability concerns limit intumescent adoption.
- Composite:Hybrid assemblies combining multiple technologies—typically ceramic facing layers with intumescent interlayers—optimize performance for the most demanding specifications in airport terminals and critical infrastructure.
Intumescent technology dominates shipment volumes; ceramic-based systems are climbing fastest in premium facade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as compliance-cost gaps between Western and Central Europe drive capacity relocation toward Poland and Czechia. Manufacturers seek ECHA REACH documentation efficiencies while maintaining CE marking proximity to core demand centers.
Germany
Commercial renovation pipelines in Frankfurt and Berlin concentrate fire-rated glazing procurement, with KBA-notified bodies enforcing the continent's most stringent EN 1363 certification protocols. The EU Green Deal bundles thermal retrofits with mandatory fire-safety upgrades across multi-tenant office stock. Bavaria's industrial fabricators are expanding laminated glass capacity to serve this bundled demand.
France
CSTB-certified projects above 50 million euro construction value now dominate facade specifications, with fire-safety consultants controlling submittal workflows. Paris and Lyon high-rise developments specify 120-minute rated ceramic systems for atrium enclosures. The country's national building code amendments are tightening escape-route glazing requirements in hospitality verticals.
United Kingdom
London's tall building guidance drives adoption of extended-fire-resistance facade systems in commercial towers. Post-Grenfell regulatory revisions have accelerated replacement cycles in residential high-rises. Manchester and Birmingham retrofit clusters are specifying intumescent-laminated assemblies for fire-door upgrades in aging commercial stock.
Poland
Emerging national amendments to harmonized EU test protocols are creating first-mover opportunities for producers establishing localized certification ahead of fragmentation. Warsaw and Krakow construction markets are absorbing capacity from Western European producers seeking REACH compliance cost advantages. Industrial facilities in Silesia continue specifying wired glass where replacement cycles lag Western markets.
Italy
Diverging national certification requirements from harmonized EU protocols are fragmenting quality assurance resources for suppliers. Milan and Rome commercial developments are specifying composite fire glazing for airport-adjacent hospitality projects. The country's building product regulator is enforcing stricter documentation for borosilicate ceramic imports.
Europe Fire-Resistant Glass Market Competitive Landscape
Western European producers anchor the premium tier; Central European specialists hold cost-competitive positions on standardized grades. The vendor base splits between integrated glass manufacturers with captive float capacity and independent fabricators purchasing substrate externally. Two strategic archetypes dominate: full-range suppliers bundling fire ratings with thermal performance, and technology specialists commanding niche ceramic segments. Competitive moves concentrate on M&A for certification portfolio expansion and geographic licensing agreements to bypass furnace-test engineer scarcity.
Among integrated manufacturers, Saint Gobain S A and AGC Glass Europe exemplify full-range positioning across laminated, tempered, and ceramic product lines. Schott occupies a specialist tier in ceramic-based fire-resistant panels. GLAS TROSCH AG and POLFLAM Sp z o o represent Central European fabricators leveraging geographic proximity to serve fragmented national certification requirements. Pyroguard Ltd and Promat sit within the independent fabricator archetype, sourcing substrate externally while differentiating on specification support and warranty documentation.
| Leading Market Players |
|---|
| Nippon Sheet Glass Co Ltd |
| GLAS TROSCH AG |
| AGC Glass Europe |
| PRESS GLASS Holding SA |
| POLFLAM Sp z o o |
| Saint Gobain S A |
| Pyroguard Ltd |
| Promat |
| Schott |
| Others |
Supply & Pricing Matrix
EU Green Deal mandates for energy-efficient retrofits gate both qualified supply and premium-tier pricing access, as contractors bundling fire-safety upgrades with thermal performance improvements must source CE-marked products from certified European fabricators. This sustainability-driven procurement filter concentrates pricing power with integrated manufacturers possessing captive float-glass capacity and documented EN 1363 test histories.
Pricing Analysis
Distributor margins compress pricing transparency across laminated fire-rated assemblies, with specification consultants capturing value through warranty-backed submittal approvals on large commercial projects. Three-tier pricing structure across premium, standard, and economy levels separates ceramic-based facade systems from intumescent-laminated doors and tempered window grades. Cost compression in economy-tier tempered products is intensifying because Turkish and South Asian suppliers compete on minimum code compliance. Industrial facility buyers exhibit highest price sensitivity, while hospitality brand operators accept premium positioning for documented EN 1364 test histories.
Supply Chain Analysis
Borosilicate ceramic feedstock rests on Turkish and South American mining operations, with sodium silicate interlayer chemistry anchored in German and French specialty chemical production. Soda ash supply draws from domestic European sources, while graphite intumescent formulations hinge on Chinese processed materials. Single-source vulnerability concentrates in boron-derived inputs for high-performance ceramic panels. Distribution runs through specification-influencer channels where fire-safety consultants control submittal workflows on projects above threshold construction values.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe fire-resistant glass market functions as a stable compounder, with regulatory retrofit mandates across Germany, France, and the United Kingdom driving replacement-cycle visibility through the projection horizon.
For Market Incumbents: Cement certification portfolio breadth across diverging national amendments in Poland and Italy before fragmentation accelerates compliance costs. Deepen backward integration into sodium silicate interlayer production to defend margin stability against REACH documentation cost inflation. Prioritize furnace-test engineer retention through specialized training partnerships with CSTB and KBA-notified bodies. For New Entrants and Emerging Players: The price-point gap between premium ceramic facade systems and economy tempered grades offers white-space targeting for mid-market laminated specialists. Polish commercial construction markets present the most penetrable geography, with localized certification capabilities creating first-mover positioning ahead of regulatory divergence. Pursue direct contractor procurement platform partnerships to disintermediate traditional distributor channels and capture specification influence earlier in project timelines. For Investors and Strategic Acquirers: Roll-up economics work for independent fabricators with localized certification capabilities because national test protocol fragmentation is raising fixed compliance costs beyond standalone scale. Target mid-cap specialists possessing CSTB or KBA-notified body relationships across Central European geographies. Watch for divergence between harmonized EU protocols and emerging Polish amendments as inflection indicator for consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Interlayer Chemistry | Captive sodium silicate production insulates margin stability from ECHA REACH documentation cost inflation. |
| Localized Certification Investment | Polish and Italian test protocol amendments reward early establishment of in-country furnace-test capabilities. |
| Direct Contractor Platform Partnership | Digital specification tools disintermediate distributor channels and accelerate submittal approval workflows. |
| Fire-Safety Consultant Relationship Development | Specification authority migration toward CSTB-certified consultants demands documented EN 1364 test histories. |
| Facade-Integrated Photovoltaic Fire Glazing Development | Building-Integrated Photovoltaics convergence with extended fire ratings opens premium positioning in net-zero commercial developments. |
Research Methodology
Multiple input streams — primary interviews with fire-safety consultants and facade specification engineers, trade data from European glass fabricator associations, and regulatory filing analysis through ECHA and national notified bodies — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from EN 1363 and EN 1364 test certification databases, Construction Products Regulation implementation guidance, and commercial renovation pipeline tracking across Frankfurt, London, and Paris metropolitan clusters.
Historical shipment patterns were cross-referenced against panel-input from plant managers at laminated glass production facilities and procurement leads at multi-tenant office developers. Segmentation modeling across product type, end-user vertical, application location, and technology chemistry was applied throughout the forecast period. CAGRs were derived from installed base replacement cycles, regulatory mandate implementation timelines, and bundled retrofit procurement trends.
Caveats apply where boron supply disruption, REACH substance restriction amendments, or furnace-test engineer scarcity could materially shift the outlook. A small set of named triggers — Polish regulatory divergence acceleration, Turkish mining export policy revision, and electrochromic ceramic technology cost curves — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Department Software Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
Earthing Lightning Protection System Market
Fire Safety & Protection
Africa Fire Suppression Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Global Flame Detector Market
Fire Safety & Protection
Fire Pump Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
North America Fire Protection Water Storage Tanks Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
GCC Firefighting Foam Market
Fire Safety & Protection
Global Portable Foam Fire Extinguisher Market
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Fireproof Insulation Market