
 Firefighting Hose Market | 2026-2036
Firefighting Hose Market Size, Share, and Industry Trends Forecast 2026-2036
Firefighting Hose Market Analytics
Leasing arrangements for municipal fleet equipment is tilting procurement patterns toward operational-expense models rather than capital-intensive hose purchases. Angus Fire leverages its integrated manufacturing footprint across European and North American plants to sustain pricing flexibility on attack hose contracts. Key Hose anchors its position through specialized polyurethane formulations that dominate wildland firefighting specifications in the western United States. Niedner Inc. competes by controlling captive textile weaving operations that reduce lead times for custom layflat hose orders.
A firefighting hose constitutes a reinforced, pressure-rated flexible conduit engineered from synthetic textiles and elastomeric compounds, designed to transport water or suppressant agents at operating pressures typically ranging from 150 to 400 psi. Its primary industrial purpose centers on delivering calibrated flow volumes to structural, wildland, or marine fire incidents while withstanding abrasion, thermal exposure, and kink deformation under emergency deployment. Attack hose commands the largest share of product-type revenue due to universal deployment across municipal engine companies, while layflat hose registers the fastest expansion as industrial safety teams adopt large-diameter supply configurations for remote facility protection. Polyurethane material formulations concentrate margin pools through extended service-life claims that reduce total cost-of-ownership calculations for fire departments.
The National Fire Protection Association shapes baseline construction standards through NFPA 1961 and NFPA 1962, while the Occupational Safety and Health Administration enforces workplace equipment integrity rules that influence industrial safety team procurement. The Federal Emergency Management Agency coordinates grant funding structures that determine replacement cycles for municipal hose inventories. Stakeholders must monitor evolving NFPA pressure-rating amendments and FEMA preparedness grant reauthorization timelines to align production planning with funded replacement windows.
Market Dynamics
Municipal fleet modernization cycles are compressing replacement timelines for high-pressure attack hose systems as NFPA 1961 pressure-rating amendments force premature retirement of legacy inventory. Leasing structures now dominate capital planning, converting durable goods procurement into operational expenditure frameworks.
Growth Catalysts
- Wildland-urban interface expansion:California, Texas, and Florida municipalities are accelerating specialized forestry hose procurement to address escalating wildfire exposure in suburban perimeter zones.
- NFPA 1962 inspection mandates:Annual pressure-testing requirements for in-service attack hoses are shortening replacement cycles and sustaining aftermarket demand volumes.
- Polyurethane formulation advances:Extended service-life claims from thermoplastic elastomer compounds are displacing rubber-based constructions in municipal specification sheets.
Market Restraints
- Aramid fiber cost volatility:Reinforcement textile input prices fluctuate with aerospace and defense sector demand, compressing margin predictability for hose manufacturers.
- Single-source coupling dependency:Proprietary threaded connection standards from dominant fittings suppliers create supply concentration risk in custom attack hose assemblies.
- Legacy fleet compatibility requirements:Existing pumper truck manifold configurations limit adoption of next-generation large-diameter supply configurations.
Strategic Opportunities
- Industrial safety team penetration:Remote facility protection contracts in petrochemical and mining sectors represent underdeveloped demand for layflat supply configurations.
- FEMA preparedness grant reauthorization:Federal funding windows for rural volunteer fire departments create cyclical procurement surges for basic attack hose inventory.
- Smart pressure-monitoring integration:Embedded fiber-optic sensing layers enabling real-time burst-risk alerts are converging with municipal fleet telematics platforms.
Industry Challenges
- Certified hose technician scarcity:NFPA-certified testing and repair personnel shortages extend depot maintenance turnaround times for municipal fleets.
- Multi-standard compliance complexity:Simultaneous adherence to NFPA 1961, OSHA workplace equipment rules, and state-level procurement specifications fragments quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Firefighting Hose Market |
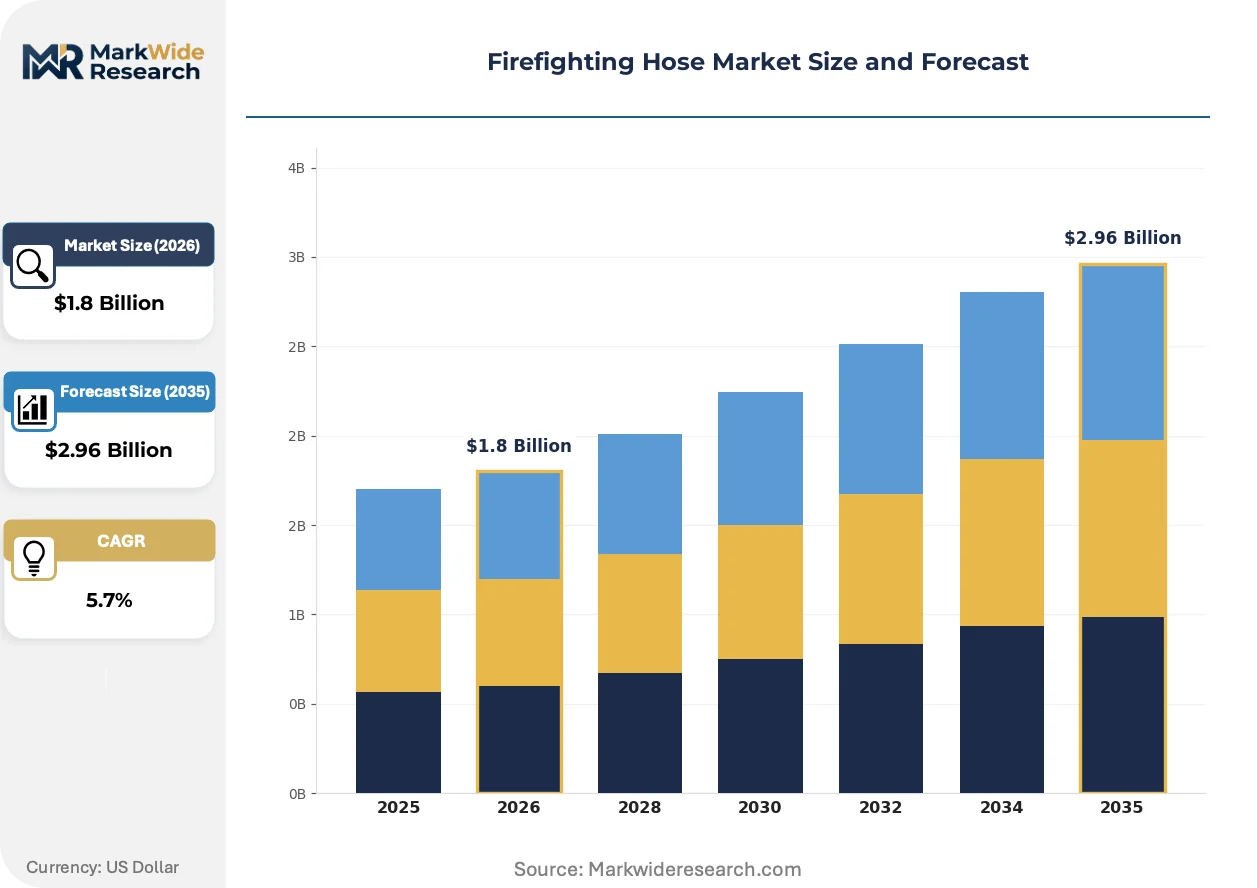
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Attack Hose, Supply Hose, Forestry Hose, Booster Hose, Layflat Hose Material: Rubber, Polyurethane, PVC, Nylon, Polypropylene Application: Structural Fire Protection, Wildland Firefighting, Industrial Fire Safety, Marine Firefighting End User: Fire Departments, Municipal Services, Industrial Safety Teams, Emergency Responders |
| Companies Covered | Angus Fire, Key Hose, Niedner Inc., Mercedes Textiles Limited, North America Fire Hose Corporation, Superior Fire Hose Corp., All-American Holdings LLC, Delta Fire Ltd, Kuriyama of America Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Firefighting Hose Market Evolving Landscape
Material science advances and procurement model restructuring are redrawing competitive boundaries between integrated manufacturers and specialized compound suppliers. Regulatory pressure-rating escalations and embedded sensor adoption are accelerating product obsolescence cycles.
Thermoplastic polyurethane jacket constructions with helical wire reinforcement are rendering obsolete traditional rubber-lined, polyester-jacketed attack hoses in municipal specifications. Western United States fire departments are specifying these constructions for wildland-urban interface deployments. The shift is compressing service-life depreciation schedules from fifteen-year to ten-year replacement horizons.
OSHA workplace equipment integrity enforcement is tightening inspection documentation requirements for industrial safety team hose inventories. Manufacturing facilities must now maintain traceable pressure-test records for all suppressant delivery conduits. Petrochemical and mining sector safety managers are responding by consolidating vendor relationships to reduce compliance administration burden.
Operational lease arrangements for municipal fleet equipment are displacing capital-intensive purchase models in engine company procurement. Municipal finance departments prefer predictable monthly expenditures over lump-sum appropriations. California and Texas municipal fire authorities are piloting managed service contracts bundling hose replacement, testing, and disposal within single vendor agreements.
Firefighting Hose Market Segmentation
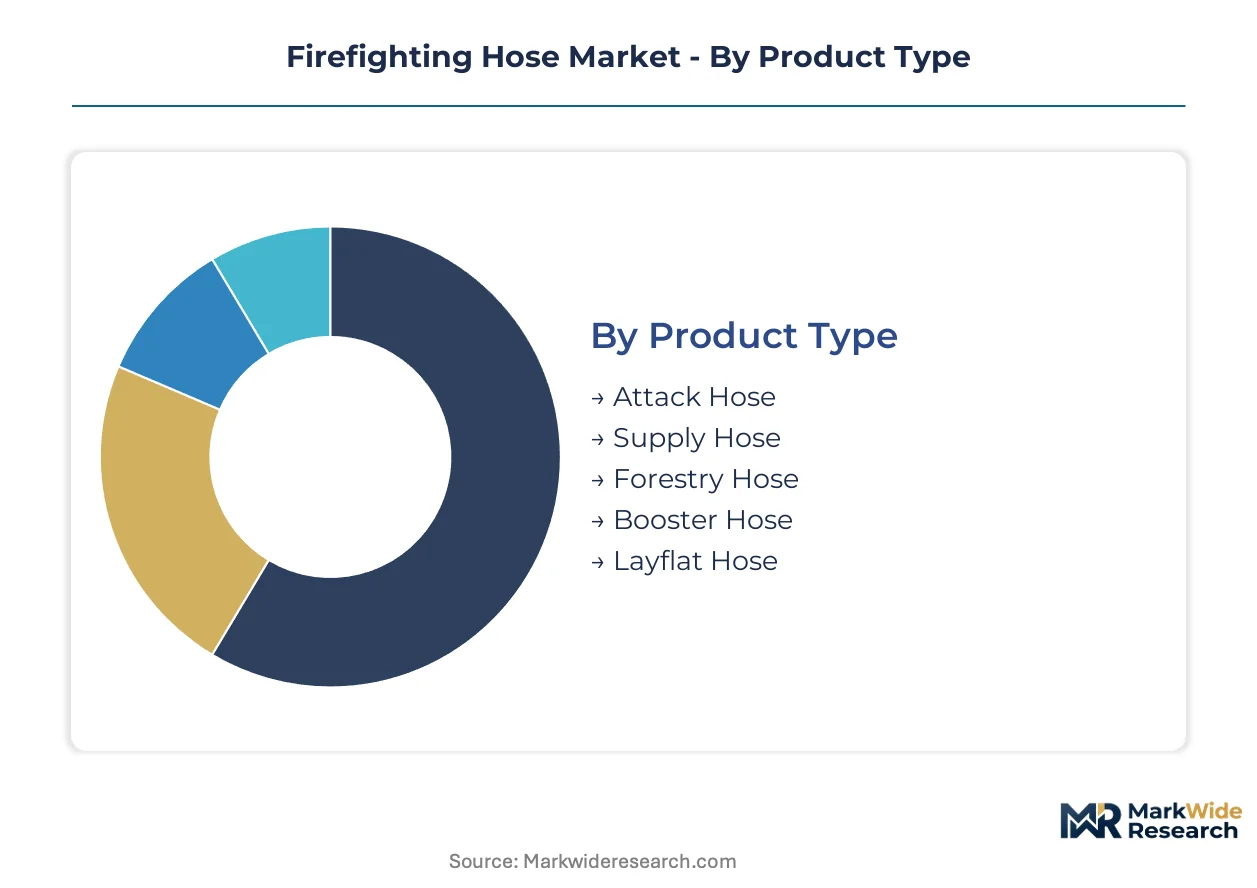
Segmentation in the firefighting hose market reveals how pressure-rating specifications and deployment environments fragment procurement requirements. Each dimension carries distinct after-sales-service intensity, from annual NFPA 1962 pressure-testing mandates for attack hose inventories to extended service-life monitoring for thermoplastic polyurethane formulations in wildland applications.
Product Type:
After-sales-service intensity varies sharply across product types, with attack hose requiring annual certification testing and layflat hose demanding field-repair capability for remote industrial deployments.
- Attack Hose:High-pressure flexible conduit engineered with synthetic textile reinforcement and elastomeric inner linings, rated for 150-400 psi operating pressures. Municipal engine companies in California, Texas, and Florida concentrate procurement as NFPA 1961 pressure-rating amendments compress replacement cycles from fifteen-year to ten-year horizons.
- Layflat Hose:Large-diameter collapsible conduit designed for rapid deployment and high-volume water transfer in remote supply operations. Industrial safety teams at petrochemical and mining facilities in wildland-urban interface zones drive adoption for facility protection contracts requiring minimal storage footprint.
- Supply Hose:Medium-pressure configuration optimized for pumper-to-pumper water relay operations.
- Forestry Hose:Lightweight construction specified for wildland firefighting mobility requirements.
- Booster Hose:Small-diameter reel-mounted assembly for initial attack and vehicle protection.
Attack hose holds the largest share; momentum sits with layflat hose.
Material:
Material selection dictates margin architecture, with thermoplastic elastomer compounds commanding premium positioning through total cost-of-ownership calculations while rubber constructions defend share in budget-constrained municipal segments.
- Polyurethane:Thermoplastic elastomer formulation delivering extended service-life claims through superior abrasion resistance and thermal stability. Western United States fire departments specify polyurethane jacket constructions with helical wire reinforcement for wildland-urban interface deployments, displacing traditional rubber-lined alternatives.
- Rubber:Conventional synthetic elastomer lining paired with polyester textile jackets, historically dominant in municipal specifications. Legacy fleet compatibility requirements and lower unit costs sustain demand among rural volunteer fire departments accessing FEMA preparedness grant funding.
- PVC:Cost-optimized thermoplastic construction for light-duty industrial applications.
- Nylon:High-tensile textile reinforcement for specialized high-pressure assemblies.
- Polypropylene:Lightweight compound specified for forestry and wildland mobility requirements.
Polyurethane captures the steepest expansion trajectory; rubber maintains volume leadership in municipal replacement cycles.
Application:
Application segmentation tracks regulatory enforcement intensity, with OSHA workplace equipment rules tightening inspection documentation for industrial safety teams while structural protection follows NFPA 1962 mandates.
- Structural Fire Protection:Interior suppression systems for built environments requiring calibrated flow volumes and kink-resistance under emergency deployment. Municipal fire departments across California, Texas, and Florida anchor demand as fleet modernization budgets expand for higher-pressure attack hose systems.
- Wildland Firefighting:Exterior perimeter defense and mobile suppression for vegetation-fueled incidents. Specialized forestry hose procurement accelerates in suburban perimeter zones where wildland-urban interface expansion intensifies exposure.
- Industrial Fire Safety:Facility protection and hazardous material response for petrochemical and mining operations.
- Marine Firefighting:Shipboard and dockside suppression systems requiring saltwater corrosion resistance.
Structural fire protection dominates revenue; wildland firefighting climbs fastest on interface zone expansion.
End User:
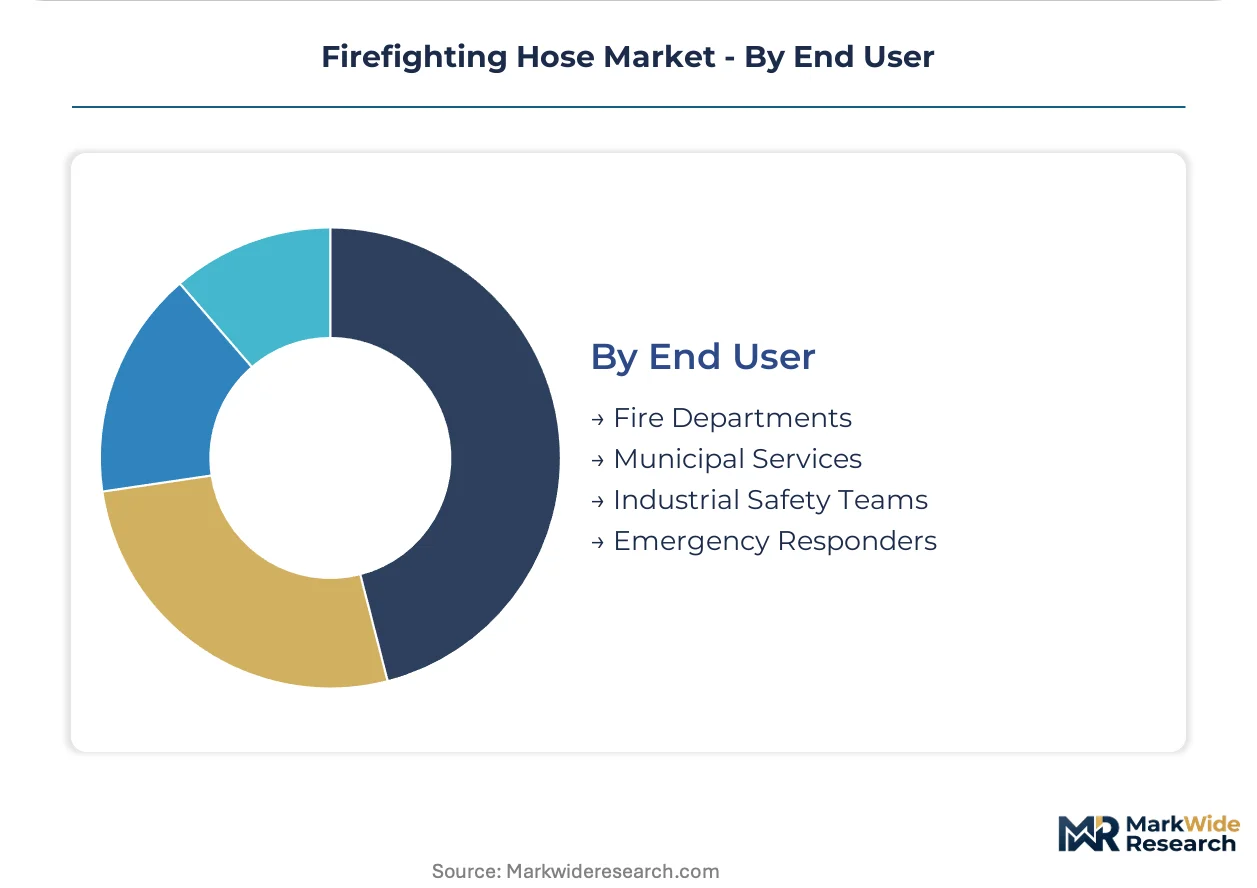
End-user segmentation reflects procurement model divergence, with municipal finance departments favoring operational lease structures while industrial safety teams consolidate vendor relationships to reduce compliance administration burden.
- Fire Departments:Municipal engine companies and volunteer organizations responsible for structural and wildland incident response. California and Texas municipal fire authorities pilot managed service contracts bundling hose replacement, testing, and disposal within single vendor agreements.
- Industrial Safety Teams:Petrochemical, mining, and manufacturing facility protection units governed by OSHA workplace equipment integrity enforcement. Safety managers respond to traceable pressure-test record requirements by consolidating vendor relationships.
- Municipal Services:Non-fire emergency response and public works departments with secondary suppression responsibilities.
- Emergency Responders:Multi-agency incident command and mutual aid networks requiring interoperable equipment standards.
Fire departments command the largest share; industrial safety teams offer the most rapid penetration opportunity for layflat supply configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FEMA preparedness grant reauthorization cycles and NFPA pressure-rating amendments are compressing replacement timelines for municipal hose inventories across key national markets. Federal funding windows and tightening construction standards are synchronizing procurement surges in wildland-urban interface zones.
United States
California, Texas, and Florida municipalities dominate specialized forestry hose procurement as suburban perimeter wildfire exposure intensifies. NFPA 1961 pressure-rating amendments force premature retirement of legacy attack hose inventory, accelerating fleet modernization budgets. Los Angeles County Fire Department and Houston Fire Department anchor demand for higher-pressure polyurethane formulations with helical wire reinforcement.
Germany
Industrial safety teams at petrochemical complexes along the Rhine-Ruhr corridor are consolidating vendor relationships under OSHA-equivalent workplace equipment integrity enforcement. REACH chemical compliance requirements are tightening material traceability specifications for elastomeric hose constructions. Bavarian manufacturing facilities are piloting managed service contracts bundling testing, replacement, and disposal for layflat supply configurations.
China
GB standards for firefighting equipment are converging with international pressure-rating benchmarks as domestic municipal fleets modernize. MIIT industrial safety directives are mandating documented pressure-test records for facility protection hose inventories. Yangtze River Delta petrochemical clusters are adopting large-diameter supply configurations for remote site protection under dual carbon goals facility hardening programs.
Japan
METI energy infrastructure resilience programs are funding hose replacement cycles for thermal power plant and LNG terminal fire protection systems. JIS standards alignment with NFPA construction specifications is accelerating specification sheet revisions for attack hose procurement. Osaka-Kobe industrial corridor safety managers are specifying thermoplastic polyurethane constructions for extended service-life claims in coastal marine environments.
Australia
CFA and RFS volunteer fire authorities in Victoria and New South Wales are accessing federal disaster resilience funding for wildland-urban interface hose procurement. TGA-equivalent equipment integrity frameworks are tightening inspection documentation for industrial mining site suppressant delivery systems. Queensland Bowen Basin mining safety teams are driving demand for lightweight forestry hose configurations in remote facility protection contracts.
Firefighting Hose Market Competitive Landscape
On the supply side, the industry is moderately consolidated around integrated manufacturers with captive textile weaving operations and specialized compound formulators with proprietary polyurethane recipes. Tiered competitive positioning separates scale-driven municipal contract winners from niche wildland specification specialists. Strategic archetypes include integrated European-North American manufacturers, western United States polyurethane specialists, and captive textile weavers with custom layflat capabilities. Dominant competitive moves encompass operational lease arrangement bundling and embedded sensor technology licensing for fleet telematics integration.
Among integrated transatlantic manufacturers, Angus Fire exemplifies the multi-plant footprint archetype sustaining pricing flexibility on municipal attack hose contracts. Key Hose occupies a position within the specialized formulation tier, anchoring wildland firefighting specifications through thermoplastic elastomer expertise. Niedner Inc. represents the captive supply archetype, with in-house textile weaving operations compressing lead times for custom layflat orders. These three company profiles illustrate how supply-side differentiation converges on either manufacturing scale, material science specialization, or vertical production control.
| Leading Market Players |
|---|
| Angus Fire |
| Key Hose |
| Niedner Inc. |
| Mercedes Textiles Limited |
| North America Fire Hose Corporation |
| Superior Fire Hose Corp. |
| All-American Holdings LLC |
| Delta Fire Ltd |
| Kuriyama of America Inc. |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta synthetic textile clusters anchor global firefighting hose manufacturing capacity, with captive weaving operations in Jiangsu and Zhejiang provinces feeding downstream elastomeric compounding facilities. This geographic concentration grants integrated manufacturers pricing leverage over specialized compounders dependent on spot-market aramid fiber purchases.
Pricing Analysis
NFPA 1961 certification tier creates the primary spread between municipal-grade attack hose and uncertified industrial configurations. Three-tier pricing structure across premium polyurethane, standard rubber-lined, and economy PVC constructions tracks material service-life claims and pressure-rating thresholds. Cost compression in standard rubber tiers is intensifying because aramid fiber input volatility transfers directly to bill-of-materials uncertainty. Rural volunteer fire departments accessing FEMA preparedness grants exhibit highest price sensitivity, while petrochemical industrial safety teams prioritize total cost-of-ownership over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for North American attack hose assemblers. Manufacturing gravity centers on China, Germany, and the United States, with Chinese facilities drawing from domestic aramid fiber production and German plants sourcing specialized polyurethane resins from Rhine-Ruhr chemical clusters. Single-source dependency on proprietary threaded coupling standards from dominant fittings suppliers creates supply concentration risk in custom municipal assemblies. Distribution runs through municipal procurement consortiums and industrial safety vendor consolidation frameworks rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity because NFPA 1962 annual pressure-testing mandates generate recurring revenue streams that compound faster than initial hardware procurement cycles.
For Market Incumbents: Entrench position through backward integration into captive textile weaving operations that compress lead times for custom layflat orders. Invest in embedded fiber-optic sensing layer R&D to capture municipal fleet telematics integration contracts. Counter emerging polyurethane formulation specialists by locking multi-year municipal managed service agreements before FEMA grant reauthorization windows.
For New Entrants and Emerging Players: Establish a beachhead in industrial safety team layflat supply configurations for petrochemical and mining remote facility protection contracts. Target Queensland mining corridors and Rhine-Ruhr petrochemical clusters where vendor consolidation appetite runs highest. Lead with bundled compliance administration services that reduce OSHA workplace equipment documentation burden for safety managers.
For Investors and Strategic Acquirers: Long-term, this sits as a replacement-cycle compounding play because NFPA pressure-rating amendments structurally compress hose retirement timelines from fifteen-year to ten-year horizons. Prioritize acquisition targets with established municipal managed service contract portfolios and certified hose technician training infrastructure. Monitor FEMA preparedness grant reauthorization timelines as cyclical procurement surge indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Managed Service Contract Bundling | Converts capital-intensive municipal procurement into predictable operational expenditure frameworks with testing and disposal attachments. |
| Polyurethane Formulation Scale-Up | Captures wildland-urban interface specifications in California, Texas, and Florida through extended service-life claims. |
| Embedded Sensor Technology Licensing | Enables real-time burst-risk alerts converging with municipal engine company telematics platforms. |
| Backward Integration into Textile Weaving | Reduces lead times for custom layflat orders and insulates margin from aramid fiber spot-market volatility. |
| Certified Technician Training Infrastructure | Addresses NFPA-certified testing personnel scarcity that extends municipal fleet depot maintenance turnaround times. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with municipal fire chiefs, industrial safety managers, hose manufacturing plant directors, and elastomeric compound R&D leads; and secondary validation through NFPA standard revision records, FEMA preparedness grant disbursement databases, OSHA workplace equipment enforcement actions, and customs trade data on synthetic textile imports. Bottom-up triangulation across product-type shipment volumes and top-down reconciliation against municipal fleet modernization budget appropriations anchored value estimates.
Forecast inputs span attack hose, layflat hose, supply hose, forestry hose, and booster hose product categories across structural fire protection, wildland firefighting, industrial fire safety, and marine firefighting applications. Modeled dimensions include pressure-rating tier, material formulation, end-user procurement model, and regional regulatory cluster. CAGRs were derived from replacement-cycle compression dynamics and FEMA funding authorization patterns across the projection horizon. Wildland-urban interface expansion rates and polyurethane displacement curves for rubber-lined constructions served as industry-specific demand drivers.
Sensitivities concentrate around NFPA 1961 pressure-rating amendment timing, aramid fiber aerospace sector demand spillover, and FEMA preparedness grant reauthorization political cycles. Forecasts embed assumptions regarding municipal lease-arrangement adoption velocity and industrial safety team vendor consolidation trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Hose Market
Fire Safety & Protection
Fire Pump Market
Fire Safety & Protection
Fire Safety Equipment Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market
Fire Safety & Protection
Africa Fire Suppression Market
Fire Safety & Protection
Deflagration Flame Arresters Market
Fire Safety & Protection
China Thermal Protector Market
Fire Safety & Protection
Laser Smoke Detector Market
Fire Safety & Protection
Automatic Fire Suppression System (AFSS) Market
Fire Safety & Protection
Global Fire Extinguisher Cylinders Market
Fire Safety & Protection
Global Fire Barrier Sealant Market
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
North America Fire Extinguisher Market