
 Europe Passive Fire Protection Market | 2026-2036
Europe Passive Fire Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Passive Fire Protection Market Intelligence
The EU Green Deal is expanding the addressable market for low-carbon passive fire materials as member states transpose stricter embodied-carbon rules into national building codes. Hempel A/S leverages its marine-coating R&D infrastructure to transfer intumescent chemistry expertise into European commercial construction specifications. Etex Group anchors its position through captive mineral wool production and direct distribution to continental retrofit contractors. Saint-Gobain S.A. competes across the full envelope-fire-protection stack, combining glass, insulation, and gypsum board within unified specification packages.
Europe Passive Fire Protection encompasses engineered materials and systems that contain fire spread, limit temperature rise, and preserve structural integrity without active suppression mechanisms, typically rated by fire resistance duration in minutes under standardized furnace testing. Intumescent coatings expand under heat to form insulating char layers up to fifty times original thickness, while fire-stop systems seal penetrations in compartment walls and floors to restore barrier continuity. Fire-Resistant Coatings dominate current value generation due to specification density in steel-framed commercial buildings, whereas Fire-Stop Systems represent the fastest-expanding segment as regulatory enforcement of compartmentation tightens across existing building stock. Fire Dampers command premium pricing in healthcare and transportation infrastructure where mechanical ventilation continuity must survive duct-melting temperatures.
CE marking under the Construction Products Regulation, BS EN fire resistance classification standards, and national building control regimes in Germany, France, and the United Kingdom collectively mandate third-party certification for market access, compressing informal supplier participation. ECHA scrutiny of halogenated flame retardants under REACH restriction procedures is redirecting formulation investment toward phosphorus-based and mineral alternatives. FM Approved and UL Listed certifications function as de facto procurement filters in insurance-linked construction finance, elevating compliance cost barriers for smaller competitors. Stakeholders must monitor the intersection of embodied-carbon accounting and fire performance testing as the EU Taxonomy for sustainable finance reweights technical specifications in public and institutional tendering.
Market Dynamics
The EU Green Deal's embodied-carbon mandates are compressing specification windows for passive fire materials as national building codes transpose stricter environmental performance thresholds into procurement requirements.
Growth Catalysts
- Energy Performance of Buildings Directive:Retrofit obligations across Nordic markets are sustaining procurement volume for certified fire-stop and damper systems in existing building stock.
- Steel-framed commercial construction:High-rise development in Germany, France, and the United Kingdom is expanding specification density for intumescent coatings.
- Mineral wool barriers:Material substitution toward low-emission alternatives is accelerating as ECHA scrutiny redirects formulation investment under REACH procedures.
Market Restraints
- Third-party certification costs:CE marking under the Construction Products Regulation and BS EN fire resistance classification standards compress informal supplier participation.
- Halogenated flame retardant phase-out:REACH restriction procedures on legacy chemistries force expensive reformulation cycles before patent-protected alternatives achieve scale.
- Insurance-linked procurement filters:FM Approved and UL Listed certifications function as de facto barriers in construction finance, elevating compliance costs for smaller competitors.
Strategic Opportunities
- Healthcare infrastructure:Fire dampers command premium pricing in medical facilities where mechanical ventilation continuity must survive duct-melting temperatures.
- EU Taxonomy alignment:Sustainable finance reweighting of technical specifications creates first-mover advantage in public and institutional tendering.
- Phosphorus-based intumescents:Convergence of marine-coating chemistry expertise with commercial construction specifications opens specification pathways.
Industry Challenges
- Fire resistance testing capacity:Standardized furnace testing bottlenecks compress product launch timelines as demand for certified systems outpaces laboratory availability.
- Compartmentation enforcement gaps:Inconsistent regulatory inspection regimes across member states create specification uncertainty for retrofit contractors.
- Legacy building integration:Fire-stop system installation in aging concrete and masonry structures demands specialized labor skills in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Passive Fire Protection Market |
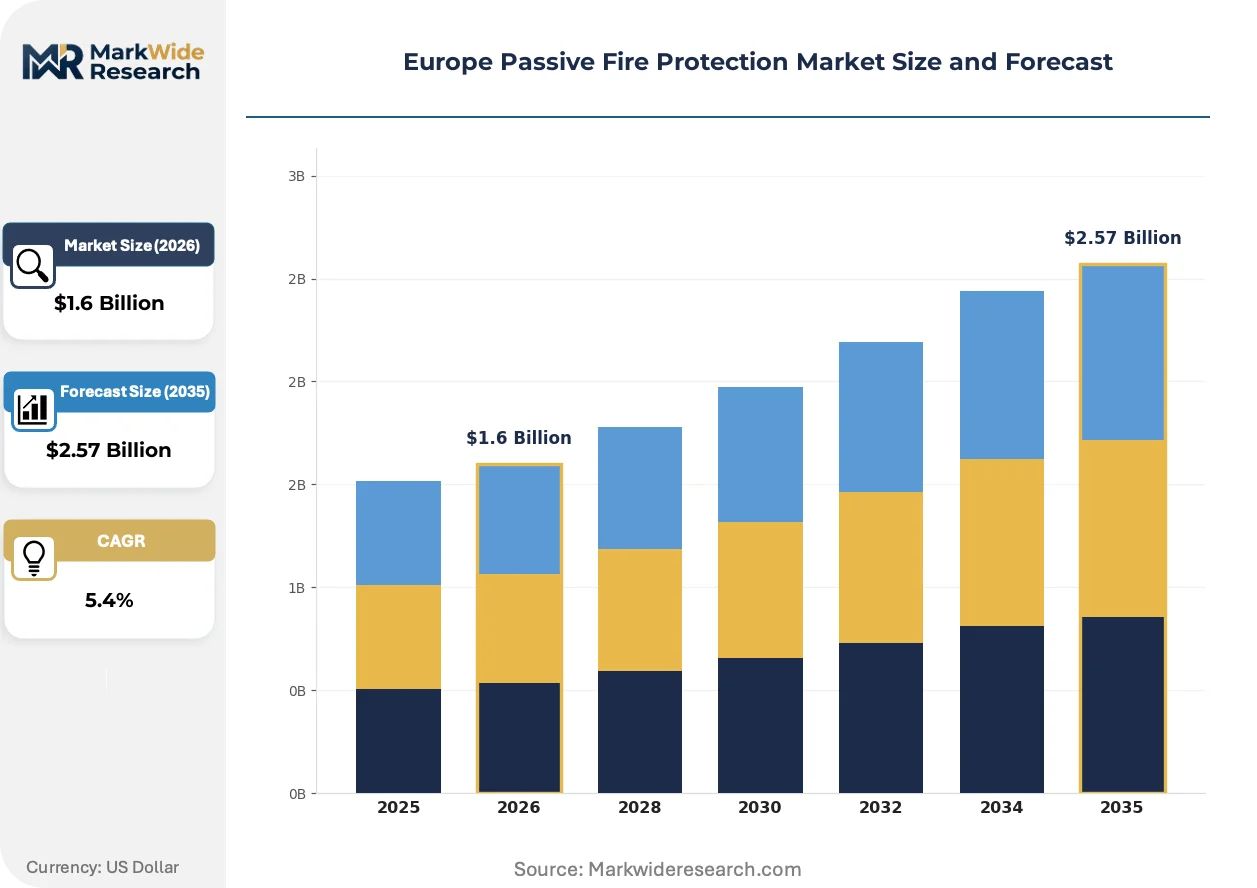
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Resistant Coatings, Fire-Stop Systems, Fire Dampers, Fire-Resistant Glass End User: Construction, Oil & Gas, Manufacturing, Transportation Installation Type: New Construction, Renovation, Retrofit, Maintenance Certification: UL Listed, BS EN, FM Approved, ISO 9001 |
| Companies Covered | Hempel A/S, Etex Group, 3M, PPG Industries Inc., Saint-Gobain S.A., Hilti Corporation, RPM International Inc., Sika AG, Sherwin-Williams Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Passive Fire Protection Market Strategic Shifts & Innovations
Specification packaging is consolidating around unified envelope-fire-protection stacks as buyers seek single-source accountability for multi-material barrier systems.
Pre-engineered fire-stop kits is modularizing penetration sealing for mechanical, electrical, and plumbing contractors. Tier-one retrofit specialists across Germany's industrial corridor are specifying these systems to compress installation timelines on renovation sites. The shift is compressing demand for site-fabricated solutions and elevating certified-system providers.
REACH restriction procedures on halogenated flame retardants are redirecting formulation investment toward phosphorus-based and mineral alternatives. ECHA's scrutiny is forcing multi-year reformulation cycles as manufacturers validate new chemistries against BS EN fire resistance classification standards. Steel-framed commercial construction specifications are the first application segment responding with accelerated substitution timelines.
Buyer preference is consolidating around unified specification packages spanning glass, insulation, and gypsum board. General contractors in France and the United Kingdom are awarding envelope-fire-protection contracts to single-source suppliers capable of warranting multi-material barrier performance. This consolidation is most visible in high-rise commercial developments where insurance-linked construction finance demands traceable certification chains.
Europe Passive Fire Protection Market Segmentation
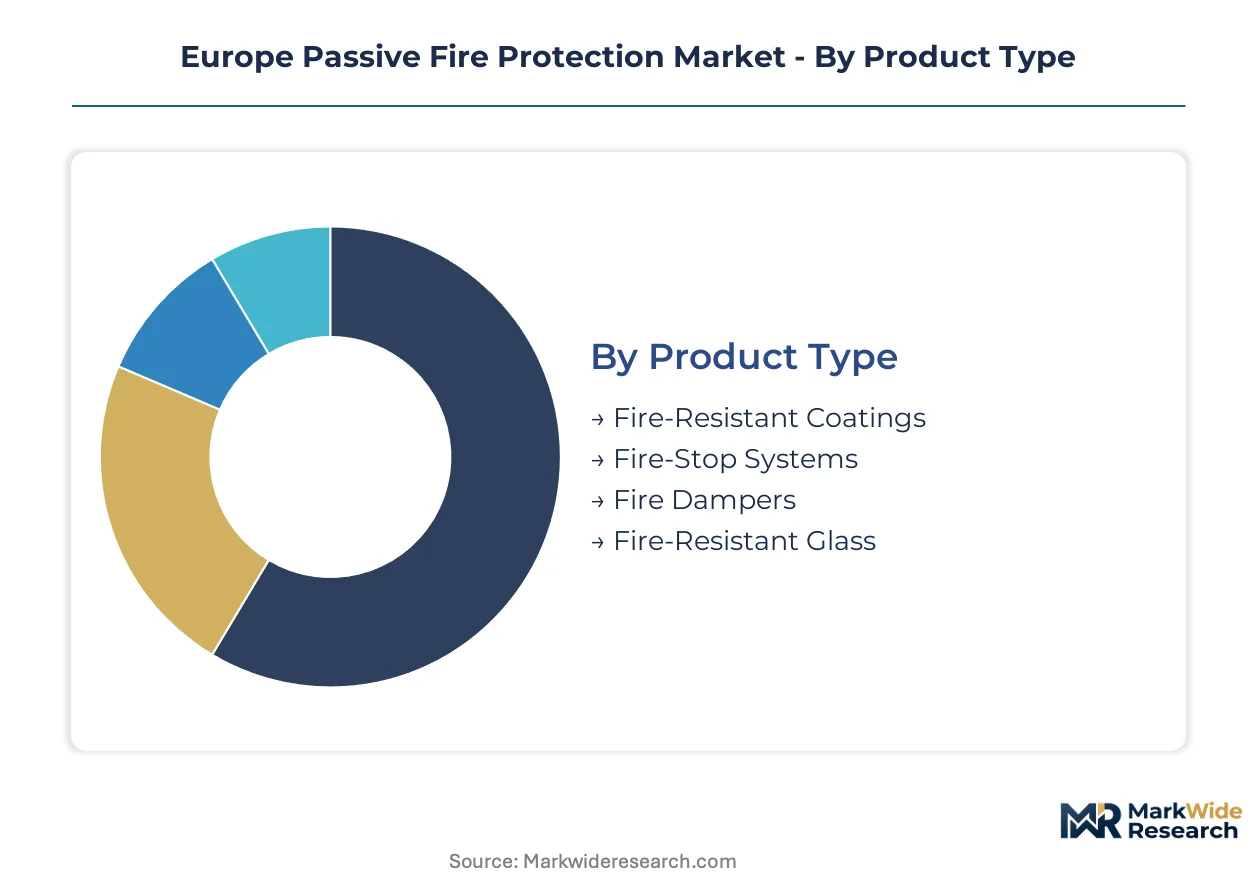
Segmentation in Europe's passive fire protection market reflects divergent specification intensities across product lifecycles and regulatory enforcement stages. Upgrade cycles in aging building stock create asymmetric growth profiles that reward suppliers with certified-system portfolios spanning multiple installation scenarios.
Product Type:
Material upgrade cycles vary sharply across chemistry platforms, with embodied-carbon mandates forcing substitution timelines that compress revenue recognition for legacy formulations.
- Fire-Resistant Coatings:Intumescent and cementitious formulations expand under heat to insulate structural steel. Germany's commercial high-rise pipeline concentrates specification volume for thin-film intumescents rated to 120-minute resistance.
- Fire-Stop Systems:Pre-engineered penetration seals restore compartment barrier continuity around mechanical and electrical services. Nordic retrofit contractors under Energy Performance of Buildings Directive obligations are procuring certified fire-stop kits at accelerating rates.
- Fire Dampers:HVAC-integrated devices maintain duct integrity during fire events. Healthcare infrastructure in France and the United Kingdom commands premium pricing for spring-loaded and fusible-link variants.
- Fire-Resistant Glass:Multi-laminate barriers combine transparency with integrity insulation ratings. Airport and rail terminal expansions across the Netherlands and Spain are specifying wired and gel-filled configurations.
Fire-Resistant Coatings sits at the top of the volume ranking, with Fire-Stop Systems climbing the fastest.
End User:
Customer-type concentration follows capital expenditure cycles, with public infrastructure and regulated industrial facilities showing least sensitivity to construction downturns.
- Construction:Commercial, residential, and infrastructure building envelopes account for dominant specification flow. Steel-framed office towers in Frankfurt, Paris, and London are driving coating and barrier system procurement.
- Oil & Gas:Offshore platforms and downstream processing facilities demand hydrocarbon-resistant intumescents. North Sea decommissioning timelines and Norwegian greenfield investments are sustaining Nordic demand.
- Manufacturing:Automotive and electronics factories require compartmentation for high-value inventory protection. Central European industrial corridors are retrofitting aging production facilities with mineral wool barriers.
- Transportation:Tunnels, airports, and rail systems need fire-resistant glazing and structural protection. Channel Tunnel safety upgrades and Spanish AVE network extensions are current procurement anchors.
Construction commands the largest absolute spend, while Transportation is expanding most quickly on infrastructure renewal mandates.
Installation Type:
Volume distribution across installation modes reveals market maturity, with maintenance and retrofit segments offering superior margin stability compared to new-build cyclicality.
- New Construction:Greenfield projects allow integrated fire protection design from structural planning stages. German commercial development permits are specifying unified envelope-fire-protection stacks in rising numbers.
- Renovation:Partial upgrades in occupied buildings demand modular systems with minimal disruption. French office-to-residential conversions are creating specification pathways for certified fire-stop kits.
- Retrofit:Mandatory compliance upgrades in existing stock concentrate in Nordic markets. Danish and Swedish building registries are enforcing compartmentation inspections that drive damper and barrier replacements.
- Maintenance:Scheduled inspection and component replacement ensures continued certification validity. United Kingdom healthcare estates are contracting multi-year maintenance frameworks for fire damper testing and recertification.
New Construction leads by installed value, though Retrofit is gaining share fastest on regulatory enforcement tightening.
Certification:
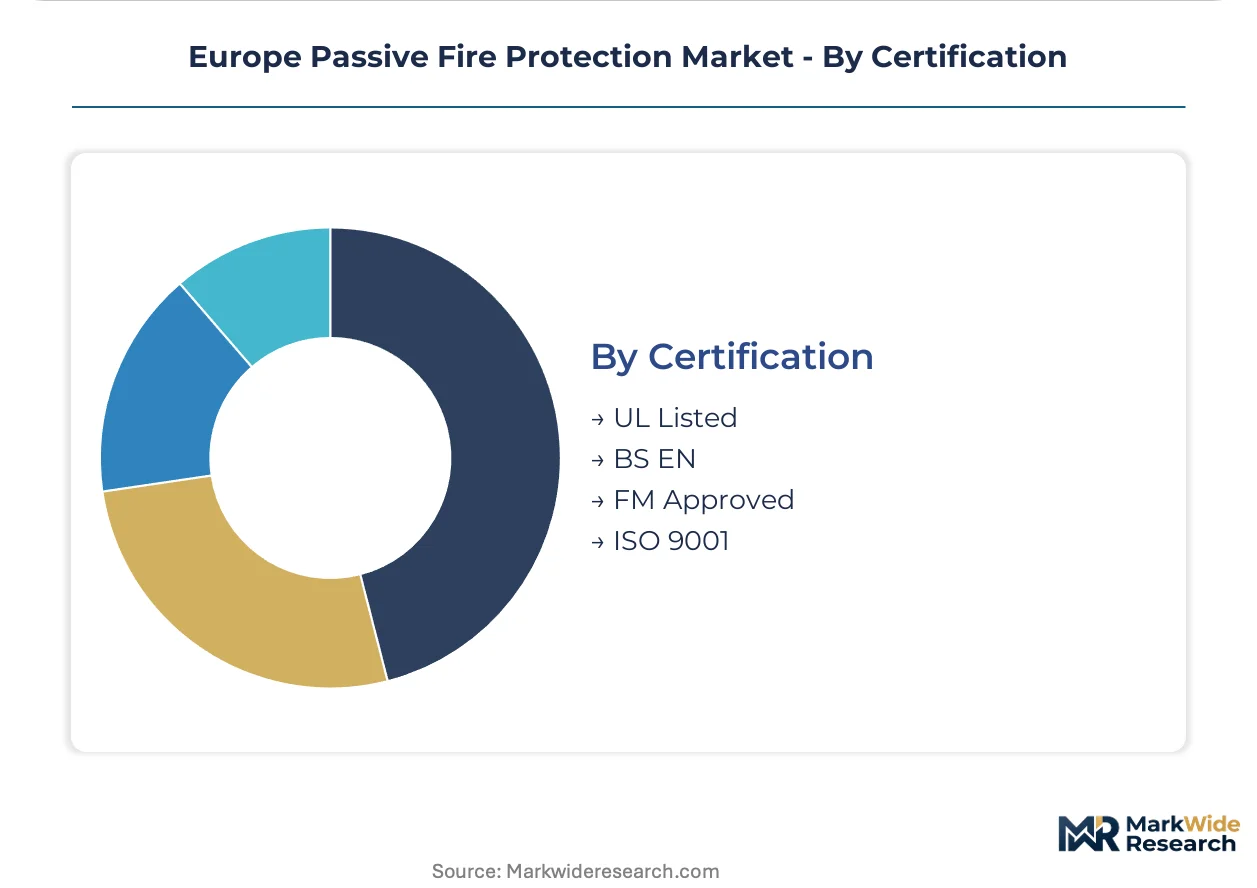
Certification tier functions as a procurement filter that stratifies supplier access, with insurance-linked construction finance elevating third-party validation requirements.
- UL Listed:North American-origin testing protocol with European recognition in cross-border projects. International contractors operating in Ireland and the Netherlands specify UL Listed dampers for global portfolio consistency.
- BS EN:Harmonized European fire resistance classification standards under Construction Products Regulation. German and French public tenders mandate BS EN 1366 and EN 13501 compliance for market access.
- FM Approved:Factory Mutual certification signals insurance-grade risk reduction. Logistics and data center developers in the United Kingdom and Benelux specify FM Approved coatings for premium financing terms.
- ISO 9001:Quality management certification underpins traceability for multi-material barrier systems. Tier-one retrofit specialists across Europe require ISO 9001 from subcontractor supply chains.
BS EN dominates procurement specifications by volume, with FM Approved showing the steepest expansion trajectory in insurance-sensitive asset classes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fire protection engineers and certified installation contractors concentrate in Germany's industrial corridor, France's commercial construction hubs, and the Nordic renovation markets. These talent clusters anchor specification development and enforcement capacity across the continent.
Germany
Frankfurt and Munich high-rise pipelines drive coating procurement for steel-framed commercial towers. The Energy Performance of Buildings Directive transposition mandates compartmentation upgrades in existing stock. Bavaria's industrial zones are retrofitting automotive and electronics factories with mineral wool barriers under stricter enforcement.
United Kingdom
London's commercial development permits specify unified envelope-fire-protection stacks for insurance-linked construction finance. The Building Safety Regulator enforces stricter fire resistance testing documentation for high-risk residential buildings. Healthcare estates across England are contracting multi-year maintenance frameworks for damper testing and recertification.
France
Paris office-to-residential conversions create specification pathways for certified fire-stop kits in occupied building upgrades. RE2020 environmental regulations accelerate material substitution toward low-emission intumescent formulations. Lyon and Marseille infrastructure projects are specifying fire-resistant glazing for airport and rail terminal expansions.
Nordic Region
Danish and Swedish building registries enforce mandatory compartmentation inspections that drive damper and barrier replacements in existing stock. The EU Green Deal's embodied-carbon mandates compress specification windows for passive fire materials across renovation markets. Copenhagen and Stockholm retrofit contractors are procuring pre-engineered fire-stop systems at accelerating rates.
Netherlands
Amsterdam and Rotterdam logistics and data center developers specify FM Approved coatings for premium financing terms. The Construction Products Regulation mandates CE marking for market access in cross-border projects. Eindhoven's technology corridor is driving demand for cleanroom-rated fire dampers in semiconductor fabrication facilities.
Europe Passive Fire Protection Market Key Industry Players
Capital-heavy mineral wool producers compete with asset-light specialty coating formulators for specification influence in commercial construction. The supplier base consolidates around integrated material portfolios capable of warranting multi-barrier system performance. Three archetypes dominate: diversified building materials conglomerates with captive mineral wool production, marine-coating specialists transferring intumescent chemistry expertise, and fire-stop system providers with modular installation platforms. Competitive positioning hardens through strategic partnerships with certified installation networks and geographic expansion into Nordic retrofit markets.
Within the diversified materials tier, Saint-Gobain S.A. and Etex Group exemplify full-stack envelope-fire-protection positioning. Hempel A/S anchors the coating-specialist vector with marine-derived intumescent expertise. These three occupy distinct specification pathways while competing for contractor loyalty through unified warranty offerings and direct distribution relationships.
| Leading Market Players |
|---|
| Hempel A/S |
| Etex Group |
| 3M |
| PPG Industries Inc. |
| Saint-Gobain S.A. |
| Hilti Corporation |
| RPM International Inc. |
| Sika AG |
| Sherwin-Williams Company |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's embodied-carbon mandates gate both qualified supply and premium-tier pricing access, compressing specification windows for low-emission intumescent coatings and mineral wool barriers while elevating certification costs for uncertified competitors. Buyers in Germany's industrial corridor and Nordic retrofit markets now face bifurcated procurement landscapes where BS EN-compliant systems command financing advantages.
Pricing Analysis
Bundled specification packages spanning glass, insulation, and gypsum board command 15-25% premiums over unbundled component sourcing, with unified warranty offerings driving contractor preference in high-rise commercial developments. Price differentiation rests on certification tier—FM Approved and UL Listed products access insurance-linked construction finance—while volume scale and after-sales service bundling separate mid-market from economy positioning. Cost compression in standard-grade cementitious coatings is intensifying due to mineral wool substitution, though premium thin-film intumescents show pricing resilience. Public infrastructure buyers exhibit least price sensitivity; residential retrofit contractors face tightest margin constraints.
Supply Chain Analysis
Warehouse-distribution layers concentrate in Germany, Belgium, and the Netherlands, with regional distribution centers serving Frankfurt, Paris, and London construction corridors through hub-and-spoke patterns. Raw material flows draw from captive mineral wool production in France and Belgium, phosphorus-based intumescent precursors from marine-coating supply chains, and specialized steel substrates from German and Italian mills. Single-source vulnerability in halogenated flame-retardant feedstocks—accelerating under ECHA REACH restrictions—elevates reformulation risk. Distribution runs through direct relationships with tier-one retrofit specialists and certified installation networks rather than commodity wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Europe's passive fire protection market stems from specification consolidation around unified envelope systems, where bundled offerings capture financing premiums and compress competitor access.
For Market Incumbents: Anticipate REACH-driven chemistry transitions by securing phosphorus-based formulation partnerships before patent-protected alternatives achieve scale. Deepen backward integration into mineral wool production to defend input cost positions against Etex Group and Saint-Gobain S.A. captive supply advantages. Prioritize FM Approved certification investment for data center and logistics asset classes where insurance-linked procurement filters are tightening fastest. For New Entrants and Emerging Players: Enter via Nordic retrofit markets under Energy Performance of Buildings Directive enforcement, where compartmentation inspection mandates create sustained demand for certified fire-stop kits and damper systems with limited incumbent saturation. Target Danish and Swedish building registry compliance cycles as the most penetrable geography-application intersection. Pursue direct distribution relationships with certified installation contractors rather than competing through commodity channels. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fire-stop system providers with modular installation platforms but limited certification breadth, offering consolidation leverage into BS EN and FM Approved portfolios. Long-term viability hinges on EU Taxonomy alignment capabilities as sustainable finance reweights technical specifications in public tendering. Watch phosphorus-based intumescent patent filings as inflection indicator for chemistry transition timing and competitive repositioning windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Wool Production | Etex Group and Saint-Gobain S.A. demonstrate how captive supply secures specification control in German commercial construction. |
| FM Approved Certification Investment | Insurance-grade validation unlocks premium financing terms for United Kingdom logistics and data center developers. |
| Phosphorus-Based Intumescent Formulation Partnership | Hempel A/S leverages marine-coating R&D infrastructure to transfer chemistry expertise into commercial construction specifications. |
| Direct Distribution to Nordic Retrofit Contractors | Pre-engineered fire-stop kit procurement accelerates under Danish and Swedish mandatory compartmentation inspections. |
| Unified Envelope-Fire-Protection Stack Packaging | Single-source accountability for multi-material barrier systems captures contractor loyalty in French and United Kingdom high-rise developments. |
Research Approach
Multiple input streams—structured interviews with passive fire protection specification engineers, fire resistance testing laboratory directors, and procurement leads at major European construction firms; regulatory filing analysis from ECHA REACH restriction procedures and EU Green Deal implementation documents; and trade data on mineral wool and intumescent coating flows—were reconciled through bottom-up and top-down triangulation. Secondary validation drew from Construction Products Regulation certification databases, BS EN fire resistance classification standards documentation, and national building control regime enforcement records across Germany, France, and the United Kingdom.
Historical project pipeline data from Frankfurt, Paris, and London commercial development permits were cross-referenced against panel input from Nordic Energy Performance of Buildings Directive compliance officers to anchor volume assumptions across the projection horizon. Segmentation modeling incorporated product type chemistry platforms, end-use capital expenditure cycles, installation mode regulatory enforcement stages, and certification tier procurement filters. CAGRs were derived from regression analysis of specification intensity trends and material substitution timelines under embodied-carbon mandates.
Inputs from ECHA regulatory proceedings and national building registry enforcement records were available through the study window; gaps in real-time compartmentation inspection compliance rates introduce uncertainty bands around retrofit segment forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Marine Fire Extinguishing System Market
Fire Safety & Protection
Automatic Fire Suppression System (AFSS) Market
Fire Safety & Protection
Europe Fire-Resistant Glass Market
Fire Safety & Protection
Fire and Rescue Helmets Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
Fire Suppression Market
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
Earthing Lightning Protection System Market
Fire Safety & Protection
United States Fire Sprinklers Market
Fire Safety & Protection
US Fire Safety Equipment Market
Fire Safety & Protection
Flame Detector System Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Global Portable Foam Fire Extinguisher Market
Fire Safety & Protection
Global Flame Arrestors Market