
 Isolation Gloves Market | 2026-2036
Isolation Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Isolation Gloves Market Insights
EU MDR compliance is consolidating the cost-of-entry calculus for isolation glove manufacturers serving European healthcare systems. Ansell leverages its vertically integrated nitrile supply chain to sustain pricing power across German and French hospital networks. PIERCAN anchors its position through specialized butyl and neoprene formulations for pharmaceutical isolator applications, while Honeywell competes via broad industrial distribution and chemical-protection certifications in North American manufacturing.
Isolation gloves are engineered barrier devices manufactured from elastomeric compounds—nitrile, latex, neoprene, or vinyl—typically 4-8 mil in thickness, designed to prevent biological or chemical transmission between user and environment. Nitrile segments now lead value generation as healthcare systems phase out latex due to Type I hypersensitivity protocols, with premium examination-grade variants commanding margin pools in surgical and laboratory end uses. Chemical-protection applications across industrial and pharmaceutical settings represent the fastest-growing demand vector, driven by ECHA REACH substance restrictions and OSHA permissible exposure limit enforcement.
FDA 510(k) requirements for medical-grade gloves, combined with EU MDR technical documentation mandates and ECHA REACH substance-of-very-high-concern listings, collectively elevate testing burdens and reshape competitive access. The FDA's ongoing quality surveillance of imported gloves, particularly from Southeast Asian manufacturing zones, redirects procurement toward validated supply chains. Stakeholders must monitor evolving polymer sustainability regulations and biodegradability standards, as these frameworks will determine material substitution timelines and capital allocation across nitrile, neoprene, and emerging bio-based alternatives.
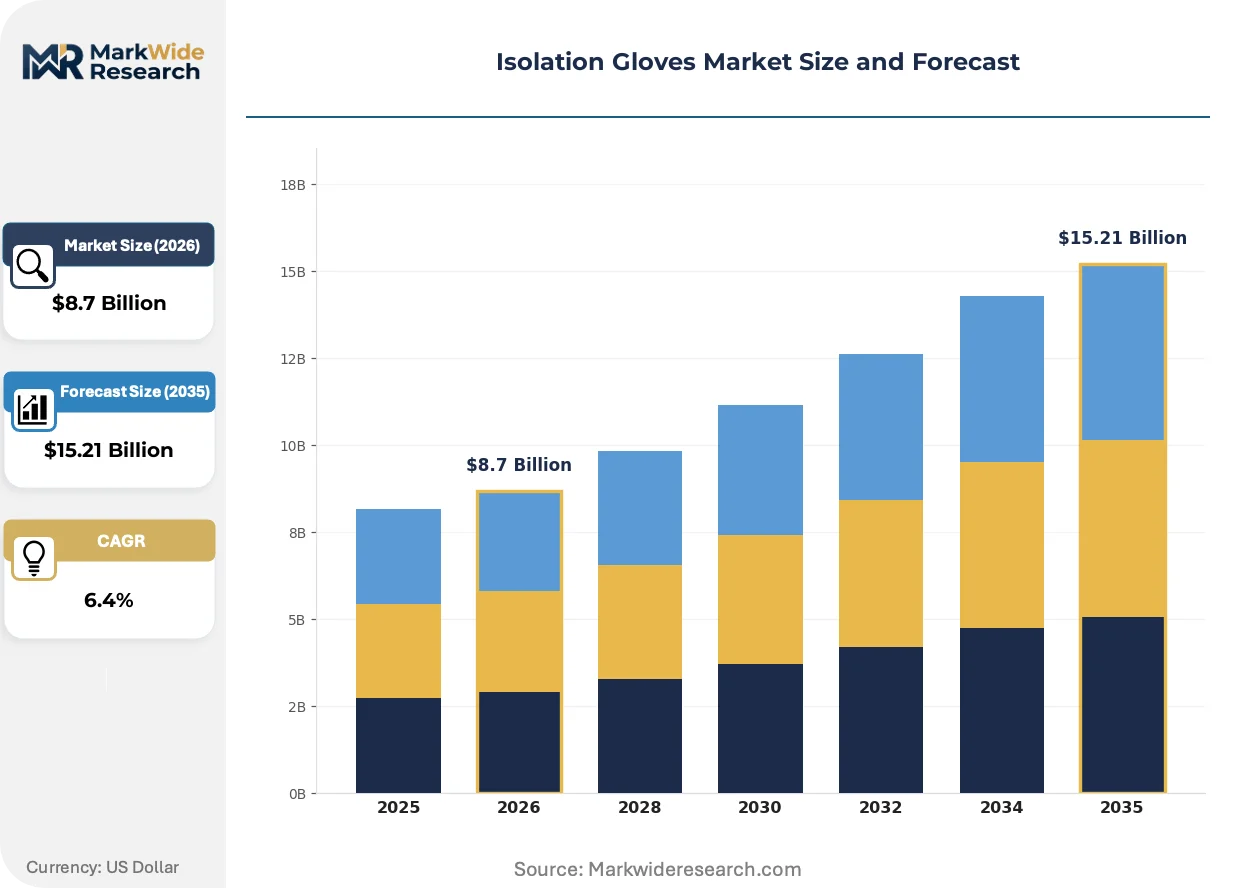
Market Dynamics
Hospital procurement offices now consolidate glove purchasing through single-source contracts that bundle nitrile examination and surgical grades, compressing vendor margins while elevating compliance documentation burdens under FDA 510(k) and EU MDR frameworks.
Growth Catalysts
- EU MDR Technical Documentation Mandates:European healthcare systems now require extensive polymer traceability records, accelerating replacement cycles for legacy latex inventories and redirecting volume toward nitrile alternatives with validated supply chains.
- Pharmaceutical Isolator Operations:Germany's Rhine-Main manufacturing corridor drives specialized demand for butyl and neoprene formulations as ECHA REACH substance restrictions tighten handling protocols for high-potency active pharmaceutical ingredients.
- Nitrile Polymer Substitution:Type I hypersensitivity protocols across United States hospital networks phase out natural rubber latex, creating structural volume migration toward synthetic elastomer platforms with comparable tactile sensitivity profiles.
Market Restraints
- Acrylonitrile Feedstock Volatility:Nitrile glove production faces margin compression from petrochemical input cost swings, with acrylonitrile-butadiene rubber pricing tied to crude oil derivatives and regional refinery capacity constraints.
- Southeast Asian Supply Concentration:FDA import surveillance has flagged quality inconsistencies from Malaysian and Thai manufacturing zones, creating procurement risk for buyers dependent on non-validated supply chains without redundant sourcing.
- Biodegradability Performance Gap:Current nitrile formulations lack viable industrial composting pathways, exposing manufacturers to prospective polymer sustainability regulations that could mandate material substitution before next-generation bio-based alternatives achieve scale.
Strategic Opportunities
- Bio-Based Elastomer Development:Polymer science advances in microbial fermentation-derived rubber compounds offer pathway to reduce petrochemical dependency while maintaining barrier performance specifications for surgical applications.
- Indian Pharmaceutical Manufacturing Expansion:CDSCO regulatory harmonization with ICH standards positions domestic isolator glove demand for acceleration as contract manufacturing organizations build sterile handling capacity for export markets.
- Direct Hospital System Contracting:Bypassing traditional medical distribution channels through group purchasing organization alliances enables manufacturers to capture margin pools previously allocated to intermediaries while securing multi-year volume commitments.
Industry Challenges
- ISO 13485 Quality Management System Certification:Medical-grade glove production requires documented risk management protocols and post-market surveillance infrastructure that extends certification timelines and elevates fixed cost thresholds for market entry.
- Legacy Latex Production Line Conversion:Retooling chlorination and polymer dipping equipment for nitrile formulations demands capital deployment at scale, stranding assets for manufacturers with delayed transition timelines.
- Cross-Contamination Prevention Protocols:Multi-material manufacturing facilities must segregate latex and synthetic production environments to prevent allergen carryover, complicating plant layout optimization and capacity utilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isolation Gloves Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrile, Vinyl, Latex, Neoprene End User: Healthcare, Laboratories, Food Service, Industrial Application: Medical Examination, Surgical Use, Food Handling, Chemical Protection Size: Small, Medium, Large, X-Large |
| Companies Covered | Ansell, PIERCAN, Renco, Safetyware Group, GB Industries Sdn Bhd, JUNG GUMMITECHNIK, Terra Universal, Honeywell, Nichwell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isolation Gloves Market Trends and Innovations
Material science advances and regulatory documentation requirements are converging to reshape glove manufacturing economics, with polymer traceability and end-of-life accountability emerging as competitive differentiators alongside traditional barrier performance metrics.
Multi-layer co-extrusion technology is modularizing glove construction by enabling discrete functional zones—textured fingertips for instrument grip, reduced-thickness palm sections for tactile feedback, and reinforced cuffs for tear resistance—within single continuous production runs. United States surgical centers now specify these hybrid constructions for microsurgical suites where dexterity and durability tradeoffs previously required separate product lines. The technology is modularizing inventory management for hospital supply chains by collapsing multiple SKUs into unified product codes that adapt to procedure-specific requirements.
ECHA REACH substance-of-very-high-concern listings for phthalate plasticizers and certain accelerator compounds used in glove manufacturing are forcing reformulation of neoprene and nitrile compounds across European pharmaceutical and industrial applications. Chemical-handling operations in Germany and France now demand certificates of analysis documenting absence of restricted substances, extending supplier qualification timelines. Medical device manufacturers with integrated glove production are responding by bringing polymer compounding in-house to control additive portfolios and accelerate regulatory response cycles.
Hospital system sustainability officers now embed carbon footprint and waste stream metrics into glove tender evaluations, displacing pure unit-cost procurement models that dominated pre-pandemic purchasing. United States academic medical centers and integrated delivery networks have established environmental purchasing criteria that weight biodegradability roadmaps and renewable energy utilization in manufacturing facilities. This behavioral shift concentrates volume toward suppliers with validated Scope 3 emissions disclosures and circular economy partnerships for post-use glove collection and thermal processing.
Isolation Gloves Market Segmentation
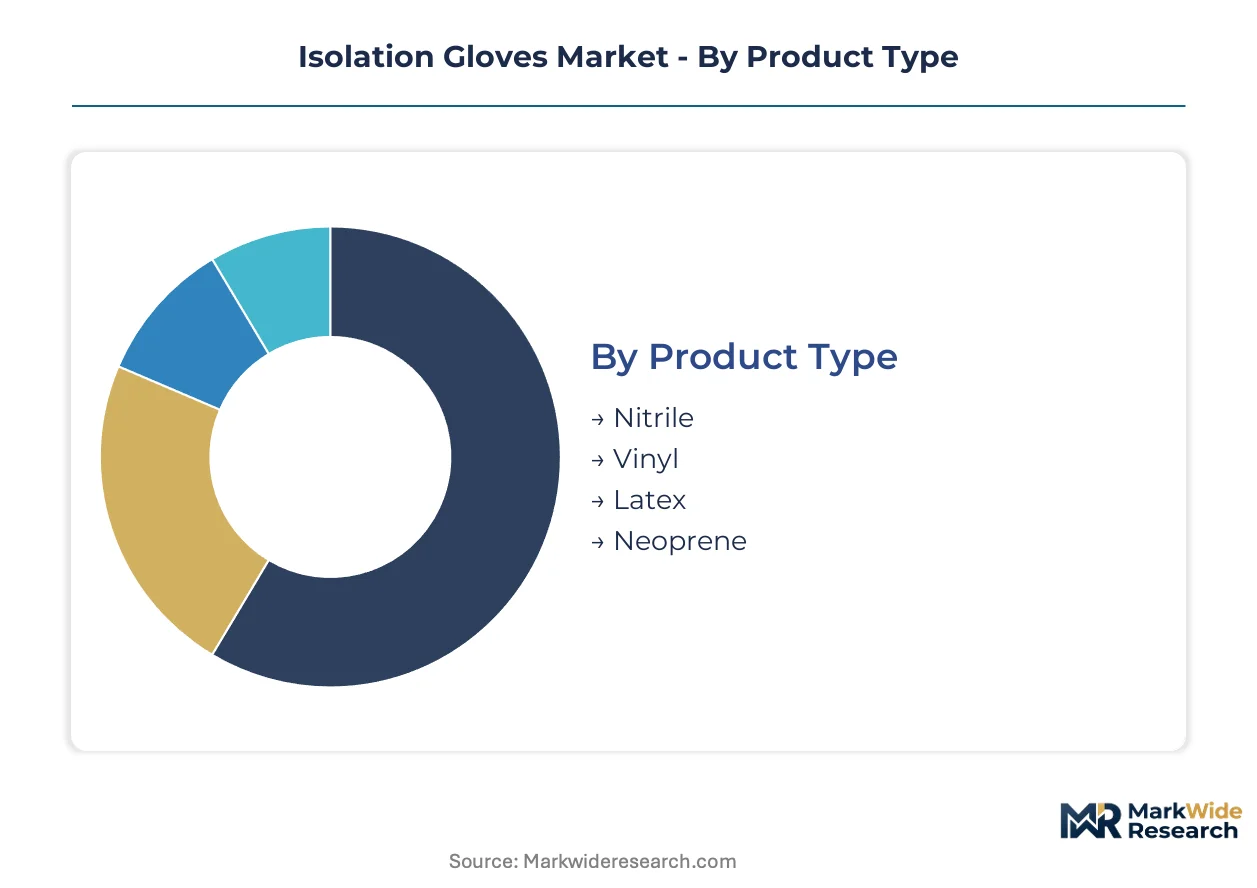
Material substitution cycles and procedure-specific performance requirements fragment demand across multiple technical specifications. Procurement offices negotiate distinct contract terms for each segment combination, creating pricing dispersion that rewards manufacturers with flexible production footprints.
Product Type:
Replacement cycles accelerate where legacy formulations fail emerging regulatory standards or allergy protocols, compressing transition timelines for hospital systems.
- Nitrile:Acrylonitrile-butadiene copolymer delivers puncture resistance 3-5x superior to latex with zero protein allergen content. United States hospital networks now mandate nitrile for all examination-grade procurement under Joint Commission hypersensitivity protocols, displacing natural rubber inventories.
- Latex:Hevea brasiliensis-derived natural rubber retains dominance in microsurgical suites requiring maximum tactile sensitivity. Germany's university hospitals maintain latex sterilization capacity for specialized cardiac and neurosurgical procedures despite workforce allergy screening burdens.
- Vinyl:Polyvinyl chloride formulations serve cost-constrained food service and janitorial applications where barrier duration is limited. Phthalate plasticizer restrictions under ECHA REACH SVHC listings constrain European deployment.
- Neoprene:Polychloroprene resists degradation from oils, solvents, and oxidizing agents in industrial chemical-handling environments. Pharmaceutical isolator operations specify neoprene for extended-duration containment of cytotoxic compounds.
Nitrile sits at the top of the volume ranking, with neoprene climbing the fastest on pharmaceutical manufacturing expansion.
End User:
Customer procurement sophistication varies sharply, with integrated delivery networks extracting volume discounts that independent operators cannot match.
- Healthcare:Hospital systems, outpatient clinics, and long-term care facilities drive bulk purchasing through group purchasing organization contracts. FDA 510(k) medical device classification mandates quality management systems that elevate supplier qualification thresholds.
- Laboratories:Research institutions and diagnostic testing facilities prioritize chemical resistance and dexterity for pipetting and microscopy tasks. Academic medical centers embed sustainability scoring into tender evaluations alongside unit cost.
- Food Service:Restaurants, catering operations, and food processing plants require compliance with FDA Food Code and HACCP protocols. Vinyl dominates this price-sensitive segment despite inferior durability.
- Industrial:Manufacturing, automotive, and chemical processing operations specify gloves by hazard type under OSHA permissible exposure limit frameworks. Chemical-protection applications command premium pricing over general-purpose variants.
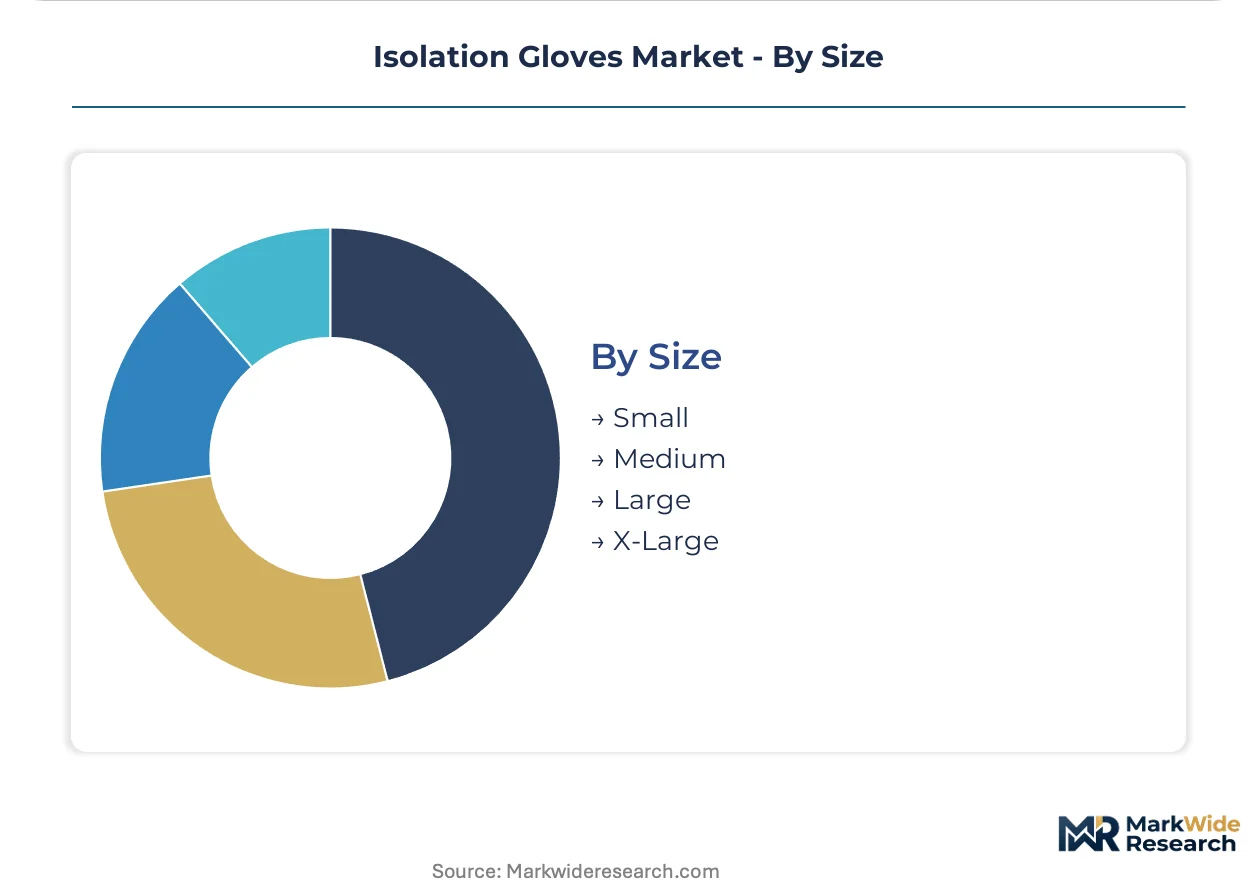
Healthcare dominates absolute volume, though industrial applications are expanding most quickly on regulatory enforcement tightening.
Application:
Procedure risk stratification determines specification intensity, with sterile surgical applications demanding documentation that examination-grade products escape.
- Medical Examination:Non-sterile barrier protection for patient contact, specimen handling, and surface disinfection. Nitrile has displaced latex across United States physician practices and urgent care networks.
- Surgical Use:Sterile, powder-free formulations with anatomical curvature and textured surfaces for instrument control. FDA quality surveillance of Southeast Asian imports redirects procurement toward validated supply chains.
- Food Handling:Compliance with FDA Food Code glove requirements for ready-to-eat food contact. Vinyl and low-cost nitrile compete on price in high-turnover quick-service restaurant environments.
- Chemical Protection:Extended-duration barrier performance against solvents, acids, and cytotoxic agents. ECHA REACH substance restrictions drive replacement cycles for legacy neoprene formulations in German pharmaceutical corridors.
Medical examination generates the highest shipment volumes, while chemical protection gains share fastest on industrial safety enforcement.
Size:
Fit standardization reduces inventory complexity, though ergonomic litigation risks pressure distributors toward inclusive sizing portfolios.
- Small:Sized for hand breadth under 76mm, serving pediatric care, dental hygienists, and segments of the Asian manufacturing workforce. Lower production volumes elevate per-unit costs.
- Medium:Hand breadth 76-89mm covers the population median across North American and European user bases. Hospital contracts specify medium as the default stocking unit, with adjacent sizes available on request.
- Large:Hand breadth 89-102mm serves male-dominant industrial and surgical technician populations. Food processing and automotive assembly lines standardize on large to accommodate workforce demographics.
- X-Large:Hand breadth exceeding 102mm for specialized industrial, emergency response, and bariatric care applications. Limited production runs constrain availability and extend lead times.
Medium sits at the top of the volume ranking, with X-Large climbing the fastest on industrial workforce demographic shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical chemists and Malaysian rubber technicians anchor the industry's geographic footprint, with regulatory enforcement and feedstock access determining regional competitive intensity.
United States
FDA import surveillance redirects hospital procurement toward validated nitrile supply chains after quality inconsistencies flagged Malaysian and Thai manufacturing zones. OSHA permissible exposure limit enforcement tightens across chemical-processing facilities in Texas and Louisiana, elevating demand for extended-duration barrier gloves. The Houston Ship Channel petrochemical corridor drives industrial glove consumption as refineries upgrade personal protective equipment protocols.
Germany
ECHA REACH substance-of-very-high-concern listings force reformulation of neoprene and butyl compounds used in pharmaceutical isolator operations. The Rhine-Main manufacturing corridor concentrates demand for specialized containment gloves handling high-potency active pharmaceutical ingredients. Bavarian university hospitals maintain latex sterilization capacity for cardiac microsurgery despite workforce allergy screening burdens.
China
NMPA medical device classification harmonization with international standards accelerates domestic certification for export-oriented glove manufacturers. The Yangtze River Delta chemical processing belt expands procurement of solvent-resistant formulations under stricter MEE environmental enforcement. Zhejiang and Jiangsu provinces concentrate nitrile production capacity serving both domestic healthcare systems and Southeast Asian re-export markets.
India
CDSCO regulatory alignment with ICH standards positions contract manufacturing organizations to build sterile isolator capacity for export markets. Maharashtra's pharmaceutical cluster in Mumbai-Pune drives specialized glove demand as sterile API handling requirements tighten. Karnataka's biotech corridor in Bangalore accelerates laboratory-grade procurement for research and diagnostic applications.
Japan
METI industrial safety standards elevate chemical-protection specifications across automotive and electronics manufacturing supply chains. The Kansai region's Osaka-based pharmaceutical manufacturers specify butyl gloves for cytotoxic compound containment. PMDA quality management system requirements extend supplier qualification timelines for medical-grade imports.
Isolation Gloves Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions, with procurement consolidation compressing margins while regulatory documentation burdens elevate fixed cost thresholds. The vendor base stratifies between scale-driven nitrile manufacturers, specialized pharmaceutical isolator suppliers, and industrial chemical-protection providers. Three archetypes dominate: vertically integrated polymer producers with captive feedstock access, regional fabricators serving price-sensitive institutional buyers, and technology licensors monetizing proprietary dipping processes. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure multi-year hospital system contracts.
Among the named participants, Ansell and Honeywell exemplify diversified industrial conglomerates with broad personal protective equipment portfolios spanning multiple barrier categories. PIERCAN occupies a specialized position representing pharmaceutical isolator specialists focused on butyl and neoprene containment formulations. These three anchors illustrate how competitive positioning fragments between scale-driven generalists and application-specific experts.
| Leading Market Players |
|---|
| Ansell |
| PIERCAN |
| Renco |
| Safetyware Group |
| GB Industries Sdn Bhd |
| JUNG GUMMITECHNIK |
| Terra Universal |
| Honeywell |
| Nichwell |
| Others |
Pricing and Supply Chain Analysis
Acrylonitrile-butadiene rubber spot pricing on the Singapore Exchange cascades through nitrile glove manufacturing into three distinct procurement tiers. Hospital systems with multi-year group purchasing organization contracts lock in examination-grade volumes at standard rates, while pharmaceutical isolator operations absorb premium pricing for validated butyl and neoprene formulations under ECHA compliance mandates.
Pricing Analysis
Bundled contracting for examination and surgical grades dominates hospital procurement, compressing vendor margins through single-source agreements. Price differentiation separates FDA 510(k) certified medical-grade products from industrial chemical-protection variants, with certification tier and volume scale as primary drivers. Pricing pressure stems from acrylonitrile feedstock volatility tied to regional refinery capacity constraints. Food service buyers exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize barrier performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian and Thai nitrile manufacturing zones after FDA import surveillance flagged quality inconsistencies. Production concentrates in Malaysia, Thailand, and China, with the Yangtze River Delta feeding both domestic healthcare systems and re-export markets. Raw material dependencies include acrylonitrile monomer, butadiene feedstock, and accelerator compounds. Tariff exposure on Southeast Asian imports creates procurement risk for North American buyers. Distribution runs through medical supply distributors and group purchasing organization alliances to hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Isolation Gloves Market represents a late-cycle quality story as procurement officers embed sustainability scoring and polymer traceability into tender evaluations, displacing pure unit-cost models.
For Market Incumbents: Deploy backward integration into acrylonitrile feedstock to buffer margin compression from petrochemical volatility. Consolidate position through multi-year hospital system contracts with embedded compliance documentation services. Ansell's vertically integrated nitrile supply chain offers a template for sustaining pricing power against emerging bio-based elastomer substitutes.
For New Entrants and Emerging Players: EU MDR technical documentation mandates in Germany and France open a window for specialized pharmaceutical isolator glove suppliers. Target India's CDSCO-aligned contract manufacturing organizations building sterile API handling capacity. Capture volume through direct hospital system contracting that bypasses traditional medical distribution channels.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists holding ISO 13485 certification and validated polymer supply chains. Long-term viability hinges on biodegradability roadmaps and circular economy partnerships for post-use glove processing. Watch for inflection signals in microbial fermentation-derived rubber compound scale-up announcements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive acrylonitrile supply insulates margins from Singapore Exchange price volatility. |
| Hospital System Direct Contracting | Bypassing GPO intermediaries captures margin pools previously allocated to distribution channels. |
| Bio-Based Elastomer R&D Partnership | Microbial fermentation-derived rubber reduces petrochemical dependency ahead of sustainability mandates. |
| Pharmaceutical Isolator Specialization | Butyl and neoprene formulations for ECHA REACH compliance command premium pricing in Rhine-Main corridor. |
| Circular Economy Collection Infrastructure | Post-use glove thermal processing partnerships satisfy hospital sustainability officer tender criteria. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary research engaged hospital procurement managers, pharmaceutical manufacturing engineers, GPO contracts specialists, and polymer compounding technical directors. Secondary validation drew from FDA 510(k) device listings, ECHA REACH substance registrations, customs trade data for nitrile glove imports, and hospital procurement database disclosures. Bottom-up volume modeling and top-down market sizing triangulated to consensus estimates.
Historical reference periods anchored the projection horizon through verified shipment data and contract award tracking. The analytical framework modeled segmentation across material type, end-user industry, application risk tier, and geographic regulatory cluster. CAGRs derived from regression analysis against acrylonitrile price indices and hospital capital expenditure cycles. Industry-specific inputs included FDA import surveillance alert frequencies and ECHA SVHC listing update timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt polymer sustainability regulation or Southeast Asian supply disruption scenarios. Forecasts reflect documented assumptions regarding nitrile substitution rates and pharmaceutical manufacturing expansion trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium Motorcycle Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Guards Market
Safety Equipment and Personal Protective Equipment (PPE)
Wearable Airbag Belt Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Lancet Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Remote Breathalyzer Market
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Explosion Proof Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Hazard and Safety Indicator Control Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Security Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment Packaging Market