
 North America Fire Extinguisher Market | 2026-2036
North America Fire Extinguisher Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fire Extinguisher Market Intelligence
Dry chemical powder formulations are recalibrating cost structures across the North America Fire Extinguisher Market as manufacturers reduce reliance on imported monoammonium phosphate. Amerex Corporation leverages its Alabama manufacturing base to control domestic supply chains for ABC extinguisher assemblies. Kidde anchors retail distribution through big-box home improvement channels, while Buckeye Fire Equipment specializes in industrial-grade wheeled units for petrochemical facilities.
A fire extinguisher is a pressurized active fire protection device containing an agent that can be discharged to suppress or extinguish small fires by cooling burning material, depriving flames of oxygen, or interrupting chemical chain reactions; units typically operate at pressures between 100 and 250 psi and must withstand hydrostatic testing at five-year intervals under NFPA 10 protocols. ABC dry chemical products dominate volume shipments across residential and commercial end users due to versatility against Class A, B, and C fires, while CO2 systems command premium positioning in data center and electrical room applications where residue-free discharge protects sensitive equipment. Fixed installation types are gaining share in new commercial construction as building codes mandate pre-plumbed suppression infrastructure.
NFPA 10 standards enforced by local Authorities Having Jurisdiction shape product specifications and inspection frequencies across the United States, while UL Listed certification governs market access for portable units sold through retail and commercial channels. Health Canada and the EPA coordinate on clean agent regulations that restrict certain halon alternatives, pushing manufacturers toward fluorinated ketone and inert gas formulations. Stakeholders must monitor state-level amendments to the International Fire Code, as California and New York adopt accelerated inspection and recharge mandates that tighten aftermarket service requirements.
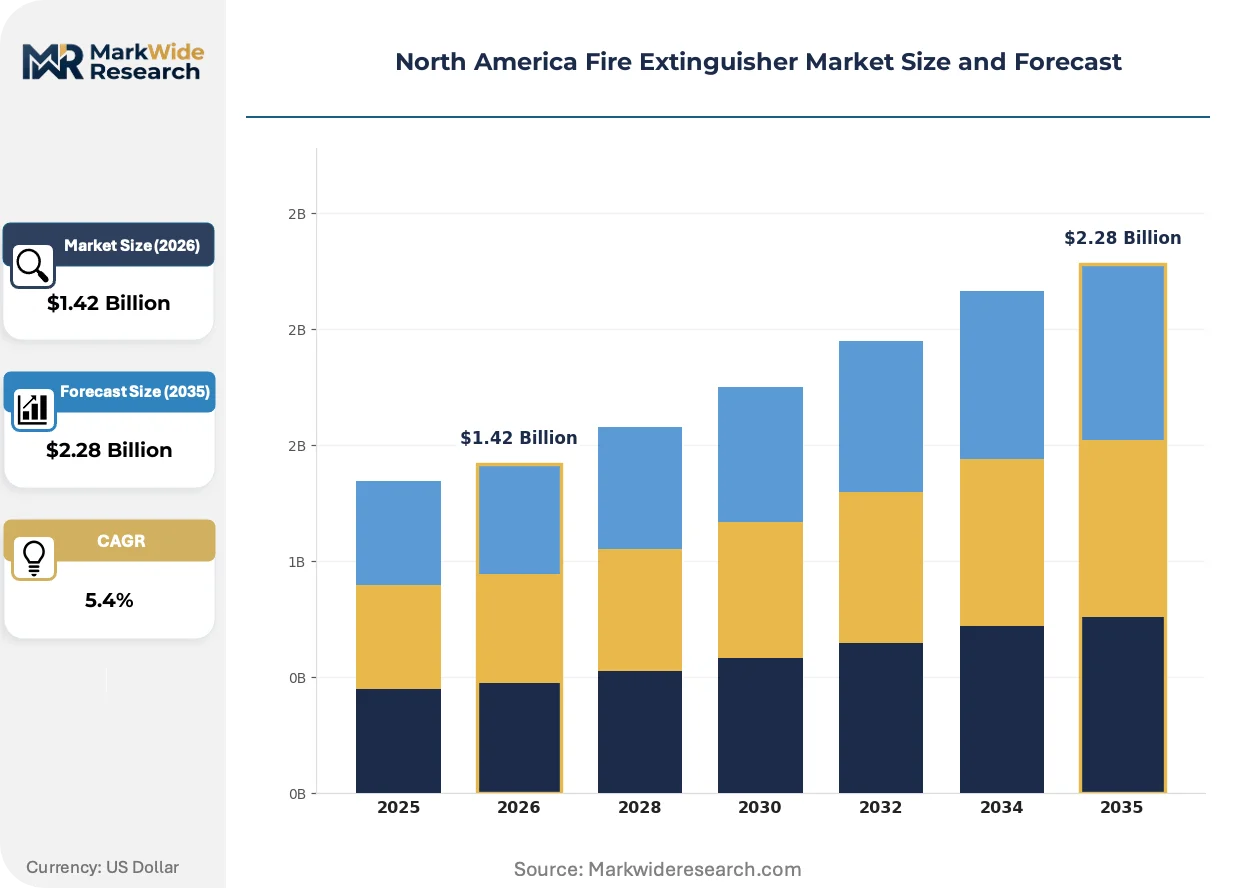
Market Dynamics
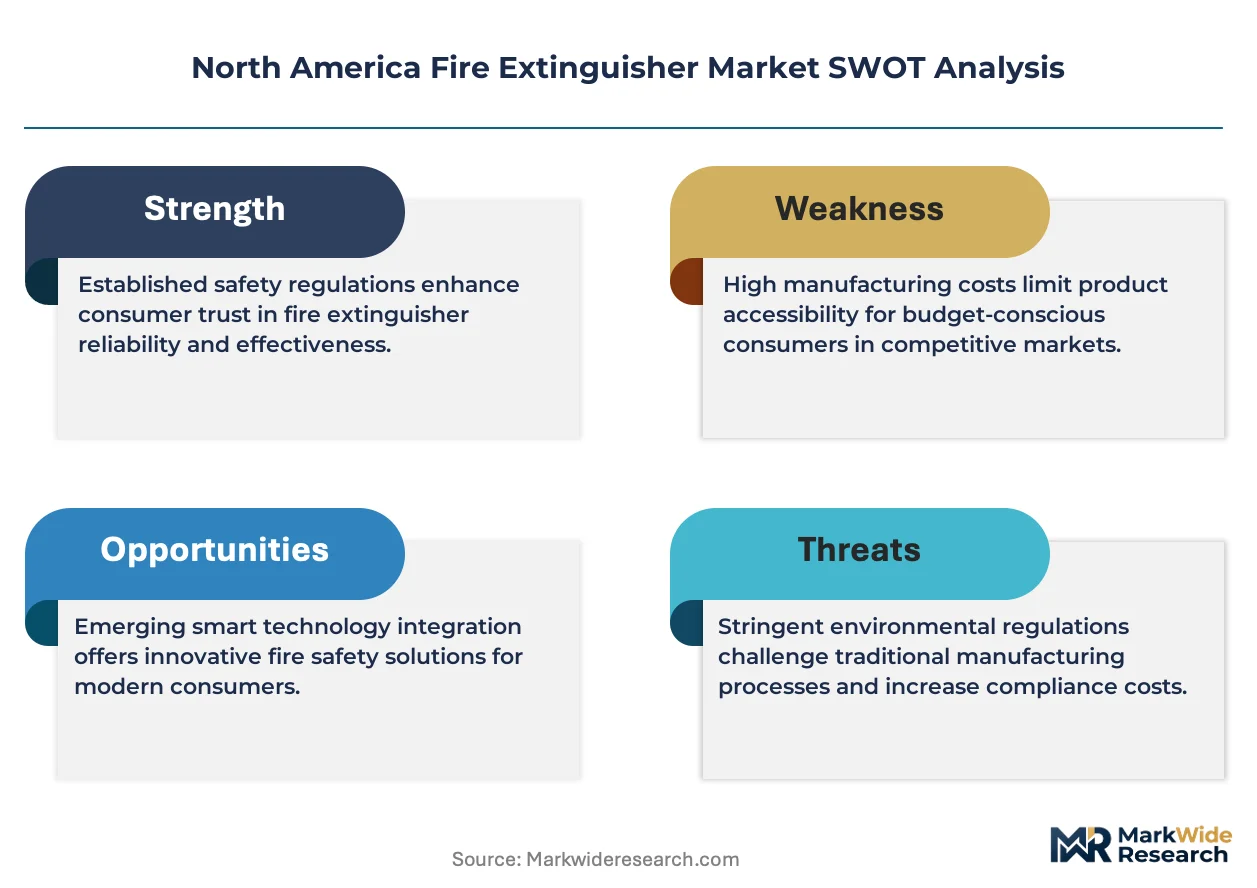
The EPA's phasedown of hydrofluorocarbons under the AIM Act is forcing manufacturers to reformulate clean agent extinguishers, compressing margins while creating first-mover advantages for domestic compound synthesis capabilities.
Growth Catalysts
- AIM Act HFC Restrictions:The EPA's hydrofluorocarbon phasedown mandates are accelerating demand for fluorinated ketone and inert gas alternatives, expanding the addressable market for next-generation clean agent systems.
- Texas Warehouse Construction:Industrial real estate development in Dallas-Fort Worth and Houston is driving procurement of wheeled ABC units and pre-engineered fixed installations for fulfillment center fire protection.
- California Wildfire Mitigation:State-funded vegetation management and rural structure hardening programs are subsidizing residential and commercial extinguisher deployment in high-risk wildland-urban interface zones.
Market Restraints
- Monoammonium Phosphate Import Dependence:Dry chemical powder formulations rely heavily on Chinese and Moroccan phosphate rock processing, exposing manufacturers to freight cost volatility and tariff uncertainty.
- NFPA 10 Inspection Mandates:Local Authorities Having Jurisdiction enforce five-year hydrostatic testing and annual maintenance requirements that inflate total cost of ownership and suppress replacement demand cycles.
- CO2 System Limitations:Carbon dioxide extinguishers face substitution pressure from fluorinated ketones in enclosed spaces due to asphyxiation risk and OSHA confined space restrictions.
Strategic Opportunities
- Mexico Manufacturing Integration:Nearshoring of cylinder fabrication and valve assembly to Baja California and Nuevo León offers tariff-advantaged supply chain restructuring for US distributors.
- Data Center Clean Agent Retrofit:Hyperscale facility operators in Ashburn, Virginia and Phoenix are replacing halon 1301 systems with FK-5-1-12 installations ahead of EPA phaseout deadlines.
- Smart Extinguisher IoT Convergence:Pressure transducer and RFID-enabled monitoring systems are creating recurring revenue streams through predictive maintenance subscriptions for multi-site commercial portfolios.
Industry Challenges
- UL Listing Timeline Compression:Third-party certification for new fluorinated ketone formulations requires 18-24 month validation cycles that delay product launches behind regulatory deadlines.
- Service Technician Shortage:NFPA 10-certified inspection and recharge technicians are concentrated in legacy manufacturing hubs, creating coverage gaps in rapidly growing Sun Belt metropolitan areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fire Extinguisher Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ABC, CO2, Water, Foam End User: Residential, Commercial, Industrial, Automotive Installation Type: Portable, Wall-mounted, Vehicle-mounted, Fixed Certification: UL Listed, NFPA 10, ISO 9001, CE Mark |
| Companies Covered | Buckeye Fire Equipment, Fire-End & Croker Corporation, Amerex Corporation, Badger Fire Protection, General Fire Extinguisher Corp., Kidde, Strike First Corporation, First Alert, Ansul, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fire Extinguisher Market Strategic Shifts & Innovations
Reformulation pressure from the AIM Act is catalyzing material science investment across the clean agent segment, while connectivity integration and procurement centralization are restructuring how extinguisher assets are managed and monetized.
Fluorinated ketone compounds are decentralizing the clean agent supply chain by enabling domestic synthesis without dependence on HFC-227ea and HFC-236fa imports subject to EPA production quotas. Data center operators and semiconductor fabrication facilities are adopting these formulations at accelerated pace to maintain insurance compliance. This technology is decentralizing market power away from incumbent HFC producers toward specialized chemical manufacturers with in-house ketone production.
The EPA's Significant New Alternatives Policy program is narrowing the approved clean agent roster, compelling manufacturers to submit toxicity and environmental fate data for emerging compounds. Industrial consequence includes extended pre-commercialization investment cycles and partnership requirements with toxicology laboratories. Semiconductor cleanroom and aviation hangar segments are most affected, responding by consolidating procurement around UL-listed FK-5-1-12 systems with established safety documentation.
Multi-site commercial portfolios are consolidating extinguisher service contracts under integrated facility management providers, displacing fragmented local vendor relationships. This channel compression is most visible in California and Texas, where property management platforms for industrial and logistics real estate are bundling fire protection with HVAC and electrical maintenance under single-source agreements.
North America Fire Extinguisher Market Segmentation
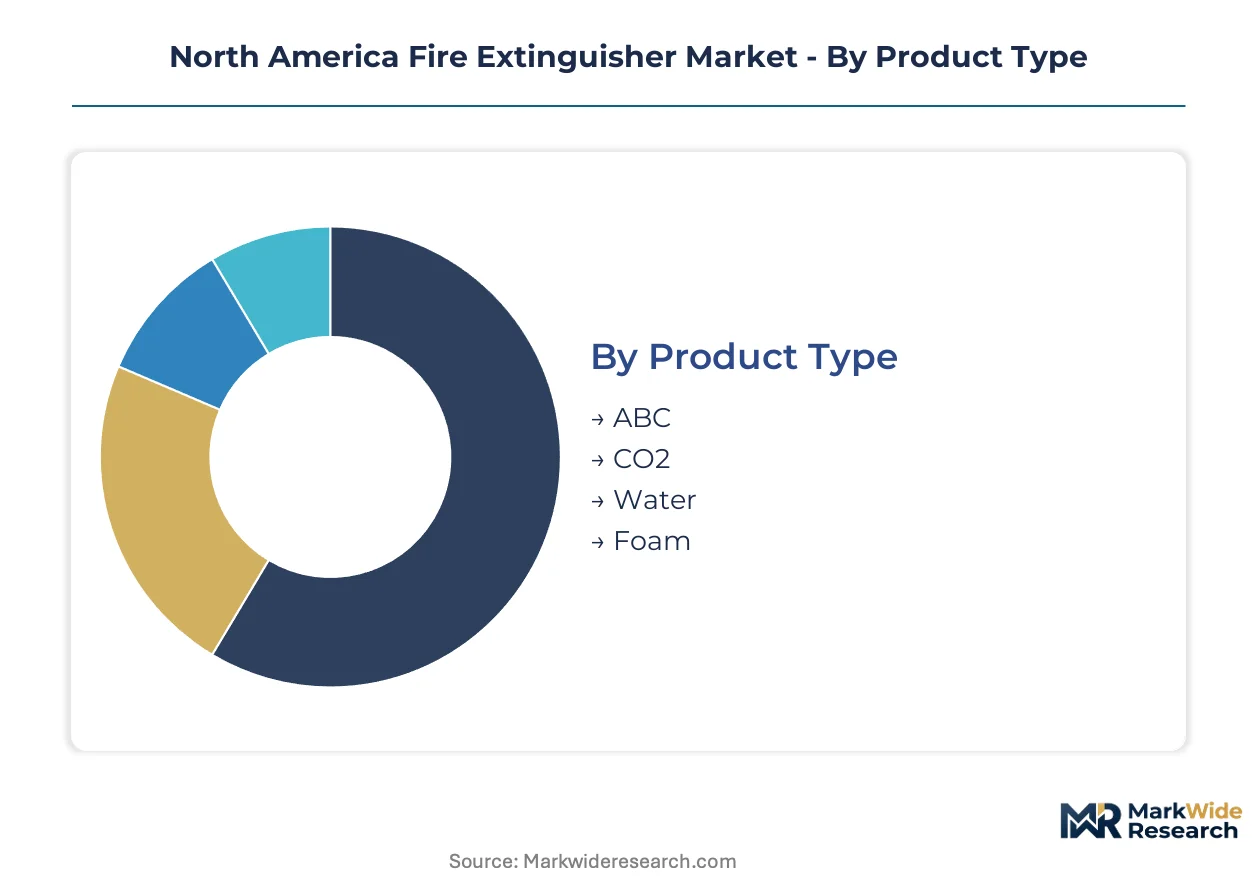
Fire extinguisher procurement patterns diverge sharply across technical specifications and deployment contexts. Manufacturers align production capacity with certification requirements that vary by end-use environment and regulatory jurisdiction.
Product Type:
Supply concentration favors dry chemical production in Alabama and Texas, where domestic phosphate processing and cylinder fabrication clusters reduce import exposure.
- ABC:Monoammonium phosphate-based dry chemical formulations dominate unit shipments through versatility against Class A, B, and C fires. Demand concentrates in Texas warehouse construction and California commercial real estate, where building codes mandate multi-class coverage and NFPA 10 inspection protocols drive replacement cycles.
- CO2:Pressurized carbon dioxide systems discharge residue-free suppression for electrical and flammable liquid fires. Data centers in Ashburn, Virginia and Phoenix are expanding procurement despite OSHA confined space restrictions, as insurance underwriters demand clean agent alternatives to water-based systems.
- Water:Pressurized water and antifreeze units serve Class A fire risks in residential and light commercial settings where freezing temperatures permit.
- Foam:Aqueous film-forming foam formulations target flammable liquid fires in aviation hangars and petrochemical facilities, though EPA PFAS scrutiny is constraining military and airport procurement.
Today's leader: ABC. Tomorrow's challenger: CO2.
End User:
Cost tier differentiation separates commodity residential units from engineered industrial systems with customized mounting and monitoring.
- Residential:Retail-channel portable units with 5-10 pound capacity dominate homeowner purchases. California wildfire mitigation subsidies are accelerating deployment in wildland-urban interface zones ahead of peak fire season.
- Commercial:Multi-site property portfolios in Dallas-Fort Worth and Houston are consolidating service contracts under integrated facility management providers, bundling extinguisher maintenance with HVAC and electrical systems.
- Industrial:Wheeled high-capacity units and pre-engineered fixed installations protect petrochemical facilities and semiconductor cleanrooms. Texas Gulf Coast refinery expansion is driving demand for corrosion-resistant assemblies.
- Automotive:Compact vehicle-mounted units serve fleet operators and consumer aftermarket channels with bracket-integrated designs for truck cabins and passenger compartments.
Commercial procurement is climbing the fastest as logistics real estate expansion outpaces residential replacement cycles.
Installation Type:
Volume concentration in portable units masks margin expansion in fixed infrastructure tied to new construction permitting.
- Portable:Hand-carried units with carrying handles or vehicle brackets constitute the baseline specification for NFPA 10 compliance across all end-use segments.
- Wall-mounted:Bracket-secured cabinets in commercial corridors and industrial walkways enable rapid access while protecting units from environmental exposure.
- Vehicle-mounted:Compact bracket-integrated designs for fleet vehicles and heavy equipment meet DOT and OSHA mobile equipment requirements.
- Fixed:Pre-plumbed suppression infrastructure with centralized agent storage and distributed discharge nozzles is gaining share in new commercial construction as building codes mandate integrated fire protection systems.
Fixed installations are gaining share fastest as code adoption accelerates in Texas and California commercial development.
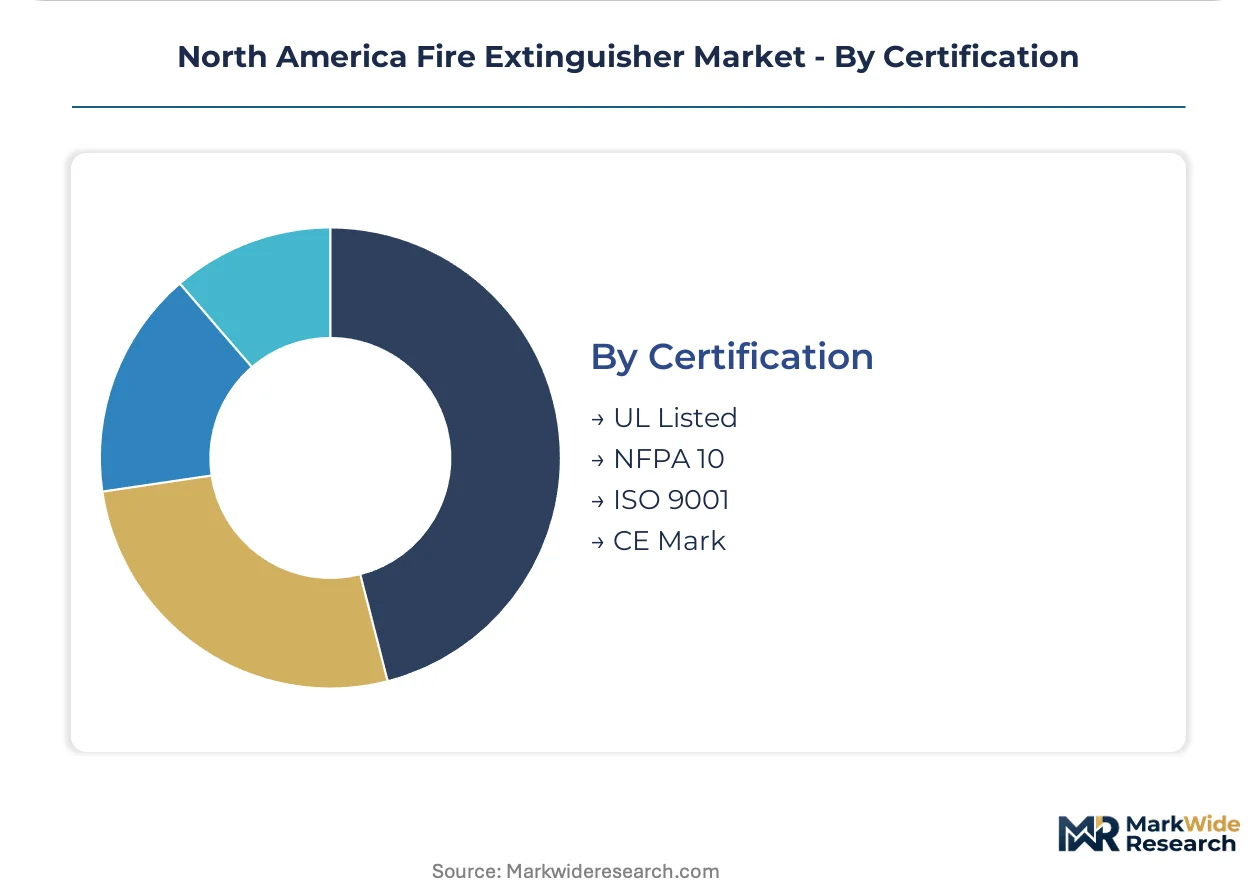
Certification:
Margin structure stratifies around testing rigor, with laboratory validation timelines creating bottlenecks for novel clean agent formulations.
- UL Listed:Underwriters Laboratories certification governs market access for portable units sold through retail and commercial channels in the United States, with 18-24 month validation cycles for new fluorinated ketone formulations.
- NFPA 10:National Fire Protection Association standards enforced by local Authorities Having Jurisdiction shape inspection frequencies and hydrostatic testing requirements across US jurisdictions.
- ISO 9001:Quality management system certification supports cross-border procurement for multinational facility operators standardizing supplier qualification.
- CE Mark:European conformity marking enables Canadian and Mexican manufacturers to access EU export markets, though US domestic procurement rarely requires this designation.
UL Listed dominates US procurement. NFPA 10 compliance is becoming the baseline expectation for commercial service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas Gulf Coast petrochemical corridor generates concentrated demand for industrial-grade wheeled units and corrosion-resistant extinguisher assemblies serving refinery expansion projects.
United States
Texas warehouse construction in Dallas-Fort Worth and Houston accelerates procurement of wheeled ABC units and pre-engineered fixed installations. EPA's AIM Act HFC phasedown forces reformulation of clean agent systems ahead of production quota reductions. Virginia's Ashburn data center cluster replaces halon 1301 with FK-5-1-12 installations to maintain insurance compliance.
California
Wildfire mitigation subsidies in wildland-urban interface zones subsidize residential and commercial extinguisher deployment ahead of peak fire season. State amendments to the International Fire Code adopt accelerated inspection mandates that tighten aftermarket service requirements. Los Angeles and San Francisco commercial real estate portfolios consolidate fire protection contracts under integrated facility management providers.
Canada
Health Canada coordinates with EPA on clean agent regulations restricting halon alternatives, pushing distribution toward fluorinated ketone formulations. Ontario and Quebec industrial facilities upgrade fixed suppression infrastructure to meet provincial fire code harmonization with NFPA standards. Alberta's oil sands operations demand specialized high-capacity units for remote extraction site protection.
Mexico
Baja California and Nuevo León cylinder fabrication clusters attract nearshoring investment from US distributors seeking tariff-advantaged supply chain restructuring. Mexico City commercial construction adopts NFPA 10-equivalent standards as building codes modernize. Guadalajara's automotive manufacturing belt drives vehicle-mounted extinguisher procurement for fleet operators.
North America Fire Extinguisher Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers retrofit production lines for fluorinated ketone formulations ahead of EPA deadlines. The vendor base stratifies between integrated domestic producers with captive phosphate processing and specialized clean agent compounders. Three archetypes define competitive positioning: legacy manufacturers with UL-listed product breadth, regional fabricators serving industrial end users, and technology licensors supplying next-generation agent formulations. M&A activity concentrates on acquiring NFPA 10-certified service networks, while strategic partnerships between chemical compounders and cylinder fabricators accelerate clean agent commercialization timelines.
Among established US-based manufacturers, Amerex Corporation occupies a position exemplifying integrated domestic production, while Kidde anchors retail distribution archetypes through big-box channel penetration. Buckeye Fire Equipment represents the industrial-specialist tier with wheeled unit expertise. These named entities illustrate how competitive positioning fragments across certification depth, channel access, and end-use specialization rather than consolidating around scale alone.
| Leading Market Players |
|---|
| Buckeye Fire Equipment |
| Fire-End & Croker Corporation |
| Amerex Corporation |
| Badger Fire Protection |
| General Fire Extinguisher Corp. |
| Kidde |
| Strike First Corporation |
| First Alert |
| Ansul |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up service networks dominate aftermarket fire protection, consolidating fragmented local vendors into platformed operations that extract procurement scale and standardize pricing discipline across multi-site commercial portfolios in Texas and California.
Pricing Analysis
Input-cost pass-through from monoammonium phosphate and fluorinated ketone compound prices shapes tiered pricing across certification levels. Three-tier pricing structure across premium, standard, and economy levels separates UL-listed clean agent systems from NFPA 10-compliant dry chemical units and uncertified residential imports. Cost compression in standard-grade ABC extinguishers is intensifying because Chinese phosphate rock processing faces freight volatility and tariff exposure. Residential buyers exhibit highest price sensitivity, while data center operators accept premium positioning for residue-free FK-5-1-12 installations.
Supply Chain Analysis
Reverse-logistics flows for hydrostatic testing and recharge services create recurring touchpoints that anchor cylinder retention within domestic service networks. Manufacturing concentrates in Alabama, Texas, and Mexico's Baja California corridor, where cylinder fabrication and valve assembly clusters reduce import exposure. Raw material sourcing draws from Moroccan phosphate processing, Chinese chemical intermediates, and domestic steel for pressure vessels. Single-source vulnerability in fluorinated ketone compound synthesis poses structural risk as EPA production quotas tighten. Distribution runs through integrated facility management providers consolidating multi-site contracts in Dallas-Fort Worth and Houston logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on fluorinated ketone domestic synthesis capabilities that capture premium pricing ahead of HFC phaseout deadlines, while service-network consolidation extracts recurring revenue from inspection mandates.
For Market Incumbents: Deepen captive supply of fluorinated ketone compounds through backward integration into chemical synthesis, insulating margins from EPA quota restrictions. Expand NFPA 10-certified technician training programs in Sun Belt metropolitan areas to close coverage gaps threatening service contract renewals. Prioritize acquisition of regional service networks in California and Texas to consolidate procurement relationships with logistics real estate operators. For New Entrants and Emerging Players: Begin with smart extinguisher IoT convergence targeting multi-site commercial portfolios in Phoenix and Ashburn, where pressure-monitoring subscriptions create recurring revenue attachment. Exploit technician shortage gaps in rapidly growing Sun Belt markets by deploying mobile recharge units with RFID-enabled asset tracking. Pursue white-label manufacturing partnerships with Mexican cylinder fabricators to bypass tariff exposure on imported assemblies. For Investors and Strategic Acquirers: Integrated facility management providers are the most active acquirer in this space, consolidating fire protection service contracts under bundled HVAC and electrical maintenance agreements. Long-term viability favors platforms with dense technician networks and recurring inspection revenue streams over pure manufacturing plays. Monitor EPA enforcement acceleration on HFC production quotas as inflection indicator for clean agent substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorinated Ketone Synthesis | Captures premium pricing from EPA HFC phasedown mandates tightening supply. |
| NFPA 10-Certified Technician Network Expansion | Closes coverage gaps in Dallas-Fort Worth and Houston logistics corridors. |
| Smart Extinguisher IoT Platform Launch | Enables predictive maintenance subscriptions for multi-site commercial portfolios. |
| Mexico Manufacturing Footprint Establishment | Secures tariff-advantaged cylinder fabrication in Baja California clusters. |
| Integrated Facility Management Partnership | Bundles fire protection with HVAC maintenance for California commercial real estate. |
Research Approach
Multiple input streams — regulatory filings from EPA and Health Canada, trade data on phosphate rock and fluorinated compound imports, and NFPA 10 adoption tracking across state jurisdictions — were reconciled through bottom-up and top-down triangulation. Primary interviews with fire protection equipment procurement managers, UL certification engineers, integrated facility management executives, and aftermarket service technicians informed demand-side validation. Secondary sources encompassed EPA AIM Act implementation documents, customs records on monoammonium phosphate shipments, and commercial building permit databases in Texas and California metropolitan areas.
Data-stream reconciliation across product type, end-user segment, installation configuration, and certification tier enabled granular volume and value modeling across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro drivers including warehouse construction permitting, wildfire mitigation program funding, and HFC phasedown enforcement velocity. Industry-specific forecast inputs incorporated data center clean agent retrofit pipelines and petrochemical facility expansion timelines along the Texas Gulf Coast.
Several conditions sit outside the modeled scope, including potential acceleration of California inspection mandates beyond current International Fire Code amendments and unanticipated EPA toxicity reclassification of emerging clean agent compounds. Forecasts reflect assumptions regarding continued phosphate rock import availability and stable NFPA 10 enforcement intensity across local Authorities Having Jurisdiction. Practitioners should monitor EPA production quota allocation announcements and Texas commercial permitting velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Africa Fire Suppression Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
Portable Fire Extinguisher Market
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Fire Fighting Foam Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
Fire Safety Equipment Market
Fire Safety & Protection
Fire Door Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Fire and Explosion Proof Lights Market
Fire Safety & Protection
Commercial Smoke Alarm Market
Fire Safety & Protection
Global Fire Extinguisher Cylinders Market
Fire Safety & Protection
North America Fire Protection Water Storage Tanks Market
Fire Safety & Protection
Europe Passive Fire Protection Market