
 Fire Extinguisher Inspection Services Market | 2026-2036
Fire Extinguisher Inspection Services Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Extinguisher Inspection Services Market Intelligence
The technology investment gap between national-scale providers and local independent service companies is collapsing the competitive middle ground. Large entities like Johnson Controls leverage integrated building management systems to offer bundled services. Cintas Corporation specializes in recurring compliance services for a broad commercial client base. In contrast, regional players such as Pye-Barker Fire & Safety compete through localized customer relationships and rapid response times.
Fire extinguisher inspection services encompass the systematic examination, testing, and certification of portable and wheeled fire suppression units. These services verify compliance through procedures like visual checks of pressure gauges and mandated hydrostatic testing at specified intervals. Within service types, annual inspections and maintenance services constitute the bulk of recurring revenue. The manufacturing and healthcare industry verticals command a premium due to complex site requirements and stringent regulatory oversight.
Compliance frameworks, principally the National Fire Protection Association (NFPA) standards in the United States and national equivalents in the European Union, mandate specific inspection frequencies. Regulations from bodies like the Occupational Safety and Health Administration (OSHA) enforce these requirements, creating non-discretionary demand. Service providers must now decide whether to invest in digital platforms for compliance tracking or specialize in high-margin hydrostatic testing capabilities.
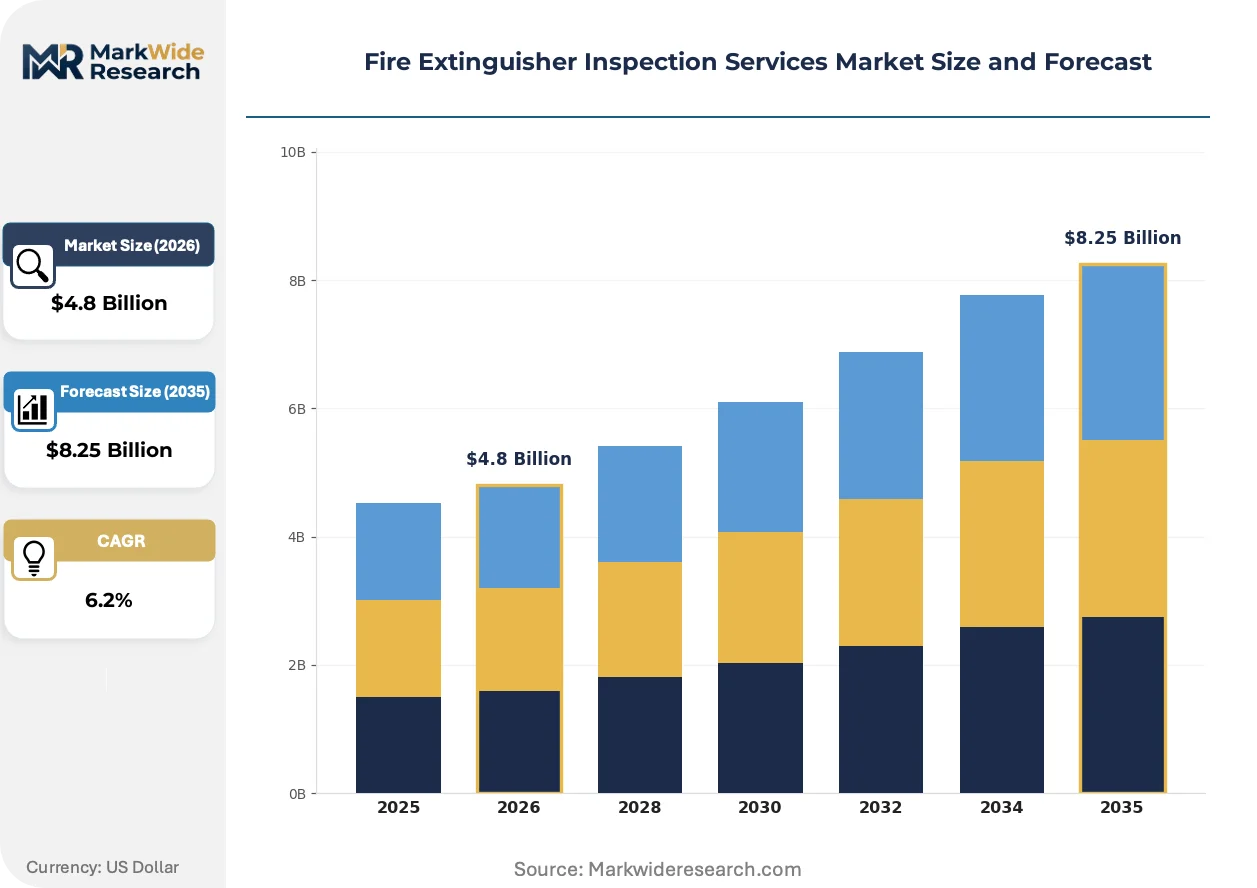
Market Dynamics
The fire extinguisher inspection services market is being reshaped by a fundamental bifurcation between technology-enabled national providers and relationship-driven local firms. This divergence is driven by the adoption of digital reporting platforms, which creates a competitive gap that mid-sized companies find difficult to bridge.
Growth Catalysts
- Regulatory Mandates:Stringent codes, such as the NFPA 10 standard in the United States, create non-discretionary, recurring demand for certified inspection and maintenance services across all commercial and industrial facilities.
- Healthcare Sector Expansion:Growth in hospitals and long-term care facilities, which operate under strict life safety protocols, is a significant catalyst, as these clients require meticulous and frequent compliance verification.
- Industrialization in India:The rapid development of manufacturing and industrial zones in India necessitates consistent, large-scale deployment of fire safety compliance services to meet both national standards and corporate risk management policies.
Market Restraints
- High Capital Costs:The significant investment required for specialized equipment, particularly for high-pressure hydrostatic testing, creates a high barrier to entry for smaller firms and restrains service portfolio expansion.
- Service Bundling Competition:Large building management firms offer fire inspection as part of a bundled service package, which can commoditize the service and exert downward price pressure on specialist providers.
- Labor Intensity:Despite digital aids, the core task of physical inspection remains labor-intensive and geographically bound, limiting the scalability and operational leverage of service providers.
Strategic Opportunities
- Predictive Maintenance Services:Integrating IoT sensors on extinguishers to monitor pressure and status in real-time opens an opportunity for new, high-margin predictive and data-driven maintenance contracts beyond scheduled inspections.
- Specialized Testing Verticals:Developing dedicated service lines for high-margin hydrostatic testing and certification targeting regulated industries like aerospace or chemical manufacturing allows for service differentiation.
- Southeast Asian Expansion:Underpenetrated markets within Southeast Asia's growing manufacturing and logistics hubs present a clear opportunity for establishing new service operations to meet rising safety compliance standards.
Industry Challenges
- Technician Skill Gaps:A shortage of technicians skilled in both traditional fire safety certification and the operation of modern digital inspection software presents a significant operational bottleneck for service delivery.
- Legacy System Integration:Integrating new digital reporting platforms with clients' disparate and often outdated facility management or enterprise resource planning systems is a major technical and implementation challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Extinguisher Inspection Services Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Annual Inspections, Monthly Inspections, Hydrostatic Testing, Maintenance Services Industry Vertical: Healthcare, Manufacturing, Hospitality, Education End User: Facility Managers, Property Owners, Safety Officers, Fire Departments Compliance Standard: NFPA, OSHA, Local Codes, ISO |
| Companies Covered | Cintas Corporation, High Rise Security Systems, Koorsen Fire & Security, Johnson Controls, Pye-Barker Fire & Safety, Impact Fire Services, Reliable Fire & Security, Summit Fire & Security, Chubb Fire & Security, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Extinguisher Inspection Services Market Strategic Shifts & Innovations
Digitalization is transforming the operational fabric of the fire extinguisher inspection market. The shift moves the core service from a manual, checklist-driven activity toward a more efficient, data-centric compliance and asset management function.
Digital Inspection Platforms
Mobile-first software using cloud-based data storage is replacing traditional paper-based tags and logbooks for documenting inspections. Large-scale commercial and industrial clients with multi-site portfolios are the primary adopters, seeking centralized compliance oversight. This technology is decomposing the monolithic service model into distinct data management and physical verification components, enabling new service tiers.
Enhanced Data and Reporting Mandates
European Union sustainability directives like CSRD are indirectly influencing inspection data requirements by demanding more granular asset tracking. This forces a shift beyond simple pass-fail safety checks to detailed documentation of equipment lifecycle and maintenance history. Service providers in the EU targeting large corporate clients must now enhance their reporting capabilities to satisfy these expanded compliance needs.
Service Unbundling by Facility Owners
A notable procurement shift involves large facility operators unbundling fire inspection from general building management contracts. This trend away from a single-source model allows clients to select specialist fire safety firms for critical compliance tasks. This behavior is most prominent in the North American healthcare and commercial real estate verticals, where regulatory expertise is a key selection criterion.
Fire Extinguisher Inspection Services Market Segmentation
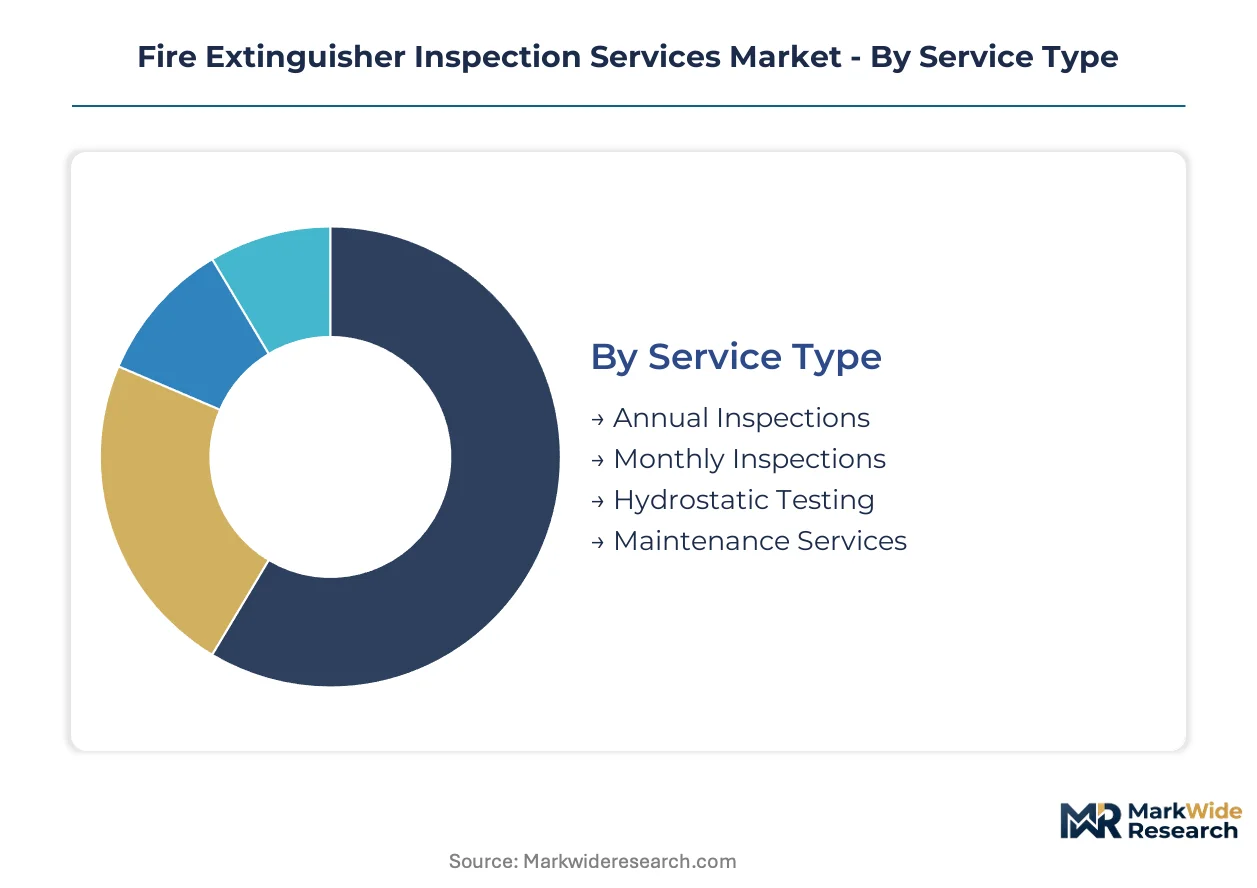
The fire extinguisher inspection services market segments based on the specific service rendered, the industry requiring compliance, the decision-makers involved, and the regulatory frameworks governing safety. Understanding these segments reveals where demand concentrates and how service providers must tailor their offerings for maximum impact.
Service Type:
The geographic distribution of service types highlights where specialized capabilities are concentrated versus universally available offerings.
- Annual Inspections:These involve a thorough visual and functional check of fire extinguishers, ensuring proper pressure, condition, and accessibility. Demand for annual inspections is widespread across all commercial and industrial facilities, driven by mandatory regulatory cycles in the US and EU.
- Hydrostatic Testing:This service involves pressure testing the extinguisher cylinder to verify structural integrity, typically mandated every 5 or 12 years depending on the agent. Specialized hydrostatic testing facilities cater to industrial zones and large commercial real estate portfolios, particularly those with high-pressure units.
- Monthly Inspections:These are quick visual checks performed by facility staff or service providers to ensure extinguishers are in their designated locations and are not obviously damaged.
- Maintenance Services:This category includes refilling, recharging, and replacing parts for fire extinguishers that fail inspection or have been discharged.
Annual Inspections commands the established base. The steepest expansion runs through Hydrostatic Testing.
Industry Vertical:
The profitability profile across industry verticals reflects the complexity of compliance and the stringency of safety requirements for each sector.
- Healthcare:Hospitals and long-term care facilities require meticulous inspection and certification due to strict life safety protocols and patient vulnerability. This sector commands premium service rates for its complex site requirements and frequent compliance verification.
- Manufacturing:Industrial facilities, especially those handling hazardous materials or operating heavy machinery, necessitate robust fire safety systems and frequent inspections. Demand is concentrating in rapidly industrializing zones like India, driven by both national standards and corporate risk management.
- Hospitality:Hotels, restaurants, and event venues require regular fire extinguisher checks to ensure guest safety and meet local fire codes.
- Education:Schools and universities mandate inspections to protect students and staff, complying with specific institutional safety policies.
The Healthcare segment drives the largest revenue share. Manufacturing demonstrates significant expansion due to industrial growth.
End User:
End-user types dictate procurement channels and service customization levels, influencing how inspection services are packaged and delivered.
- Facility Managers:These professionals directly oversee building operations and maintenance, making them primary decision-makers for fire safety services. Their demand focuses on efficiency, digital reporting, and seamless integration with existing building management systems.
- Property Owners:As ultimate responsible parties, property owners ensure compliance across their real estate portfolios, often seeking bundled services for cost efficiency and liability management. This user group prioritizes comprehensive compliance records and risk mitigation.
- Safety Officers:These individuals within organizations focus on workplace safety, ensuring all fire protection equipment meets internal and external regulatory standards.
- Fire Departments:While primarily regulatory and emergency response bodies, fire departments often recommend or enforce specific inspection schedules and standards for businesses.
Facility Managers represent the largest procurement influence. Property Owners are increasingly seeking comprehensive, single-source compliance solutions.
Compliance Standard:
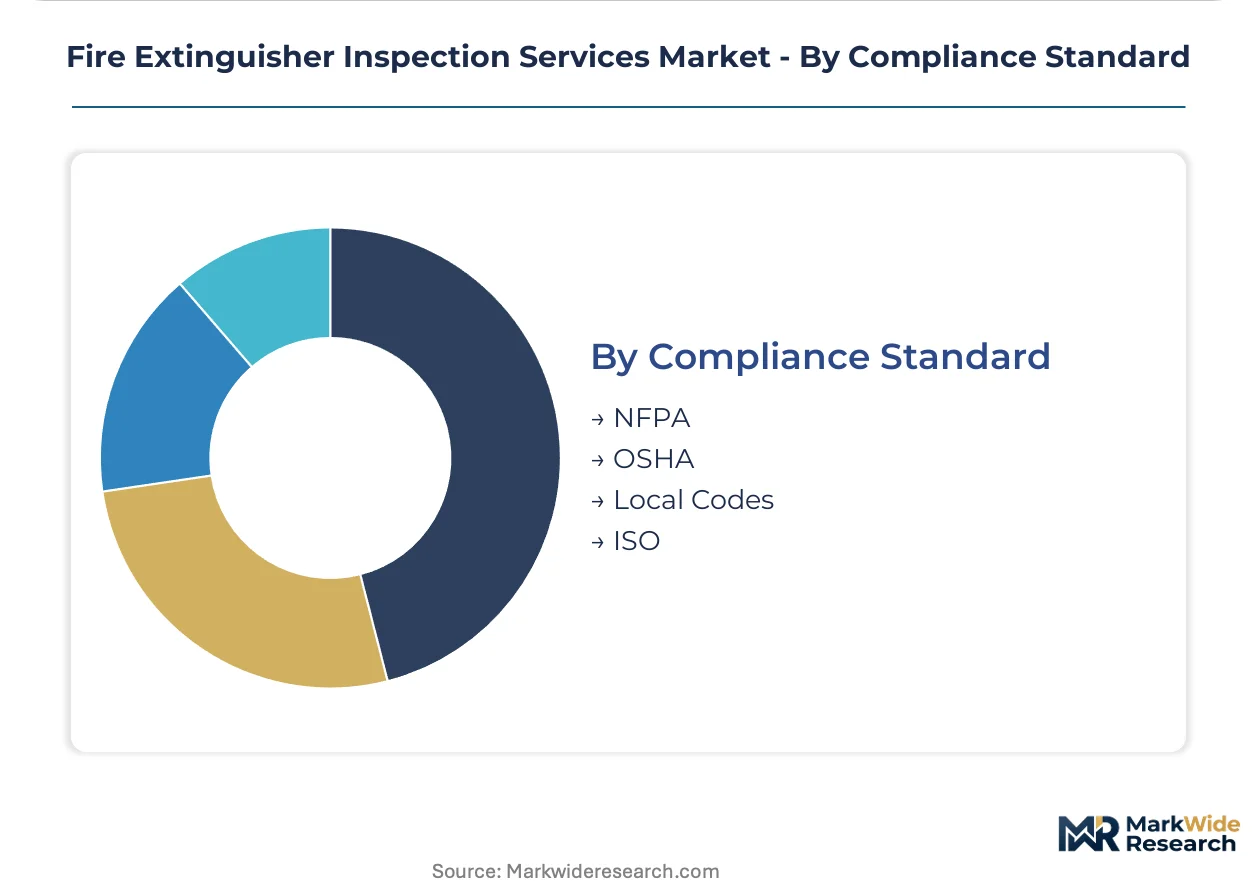
The regulatory landscape defines the non-discretionary demand for fire extinguisher inspection services, with specific standards governing frequency and methodology.
- NFPA:The National Fire Protection Association (NFPA) standards, particularly NFPA 10, establish the foundational requirements for portable fire extinguisher selection, installation, inspection, maintenance, and testing in the United States. Compliance with NFPA is non-negotiable for most commercial entities.
- OSHA:The Occupational Safety and Health Administration (OSHA) enforces fire safety regulations in US workplaces, often referencing NFPA standards. OSHA mandates regular inspections and maintenance to ensure employee safety and avoid penalties.
- Local Codes:Municipal and state-level fire codes often supplement national standards, adding specific requirements or frequencies based on local building types and risks.
- ISO:International Organization for Standardization (ISO) standards, while not directly mandating fire extinguisher inspections, influence quality management systems that encompass safety protocols.
NFPA compliance underpins the majority of service demand. OSHA enforcement provides a critical regulatory impetus for workplace safety.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for fire extinguisher inspection services varies across global regions, reflecting diverse regulatory enforcement and industrial development. North American and European markets prioritize digital reporting and advanced compliance tracking. Rapidly industrializing Asian economies focus on foundational safety protocols for new facilities.
United States
United States demand for fire extinguisher inspection services stems from stringent life safety protocols in commercial and healthcare sectors. NFPA 10 standards and OSHA regulations mandate recurring inspections. Major metropolitan areas like New York City and Los Angeles drive significant service volumes due to dense commercial developments.
Germany
Germany's industrial base requires robust fire safety compliance, particularly within its advanced manufacturing and automotive sectors. National fire safety directives, aligned with broader EU standards, enforce rigorous inspection frequencies. Industrial clusters in Bavaria and North Rhine-Westphalia necessitate specialized hydrostatic testing and maintenance services.
India
India's accelerating industrialization fuels substantial demand for fire extinguisher inspection services in its burgeoning manufacturing and logistics hubs. The country's national fire safety codes, coupled with corporate risk management, drive consistent compliance service requirements. Industrial corridors in Gujarat and Maharashtra are seeing large-scale deployment of fire safety infrastructure.
Singapore
Singapore, as a key logistics and financial hub, emphasizes high safety standards across its commercial and industrial properties. The Singapore Civil Defence Force (SCDF) mandates comprehensive fire safety audits and regular extinguisher inspections. The Jurong Island industrial complex and Marina Bay financial district exhibit concentrated demand for advanced compliance verification.
Fire Extinguisher Inspection Services Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the fire extinguisher inspection services market. This tiered structure reflects the bifurcation between technology-enabled national providers and relationship-driven local firms. Strategic archetypes include large-scale facility management integrators, specialized recurring compliance providers, and localized rapid-response experts. Dominant competitive moves involve both strategic acquisitions to expand geographic reach and significant investment in digital reporting platforms for efficiency gains.
Within the integrated facility management tier, Johnson Controls represents a provider leveraging bundled services through extensive building management systems. Cintas Corporation exemplifies a specialist in recurring compliance services, serving a broad commercial client base with standardized inspection protocols. Pye-Barker Fire & Safety occupies a position as a regional player, anchoring localized customer relationships and rapid response capabilities across various markets. These entities collectively shape the competitive dynamics through their distinct operational models and market penetration strategies.
| Leading Market Players |
|---|
| Cintas Corporation |
| High Rise Security Systems |
| Koorsen Fire & Security |
| Johnson Controls |
| Pye-Barker Fire & Safety |
| Impact Fire Services |
| Reliable Fire & Security |
| Summit Fire & Security |
| Chubb Fire & Security |
| Others |
Cost & Logistics Intelligence
Contract-based long-term service agreements define access and price visibility for fire extinguisher inspection services, particularly for large commercial and industrial clients. These agreements stabilize revenue streams for providers while ensuring consistent compliance for facility operators.
Pricing Analysis
After-sales maintenance services, including refills and parts replacement, drive significant lifetime value for service providers. Pricing stratifies across premium, standard, and economy tiers, reflecting the complexity of compliance requirements and the service level offered. Certification level, such as NFPA adherence, and geographic delivery costs are key differentiation drivers. Pricing pressure stems from large facility management firms bundling services, which can commoditize basic inspections. Healthcare facilities are generally the least price-sensitive due to stringent regulatory oversight, while small commercial clients exhibit higher price sensitivity.
Supply Chain Analysis
Just-in-time inventory strategies, supplemented by strategic stockpiles for critical components, characterize the supply chain for fire extinguisher inspection services. Geographic supply concentration for extinguisher manufacturing centers in countries like China and India, while specialized hydrostatic testing equipment often sources from Germany. Raw material dependencies include steel and aluminum for cylinders, along with various chemical suppression agents. Single-source vulnerability for highly specialized testing equipment presents a structural risk. Distribution runs through localized service networks for routine inspections, complemented by national logistics for large-scale equipment procurement and specialized testing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
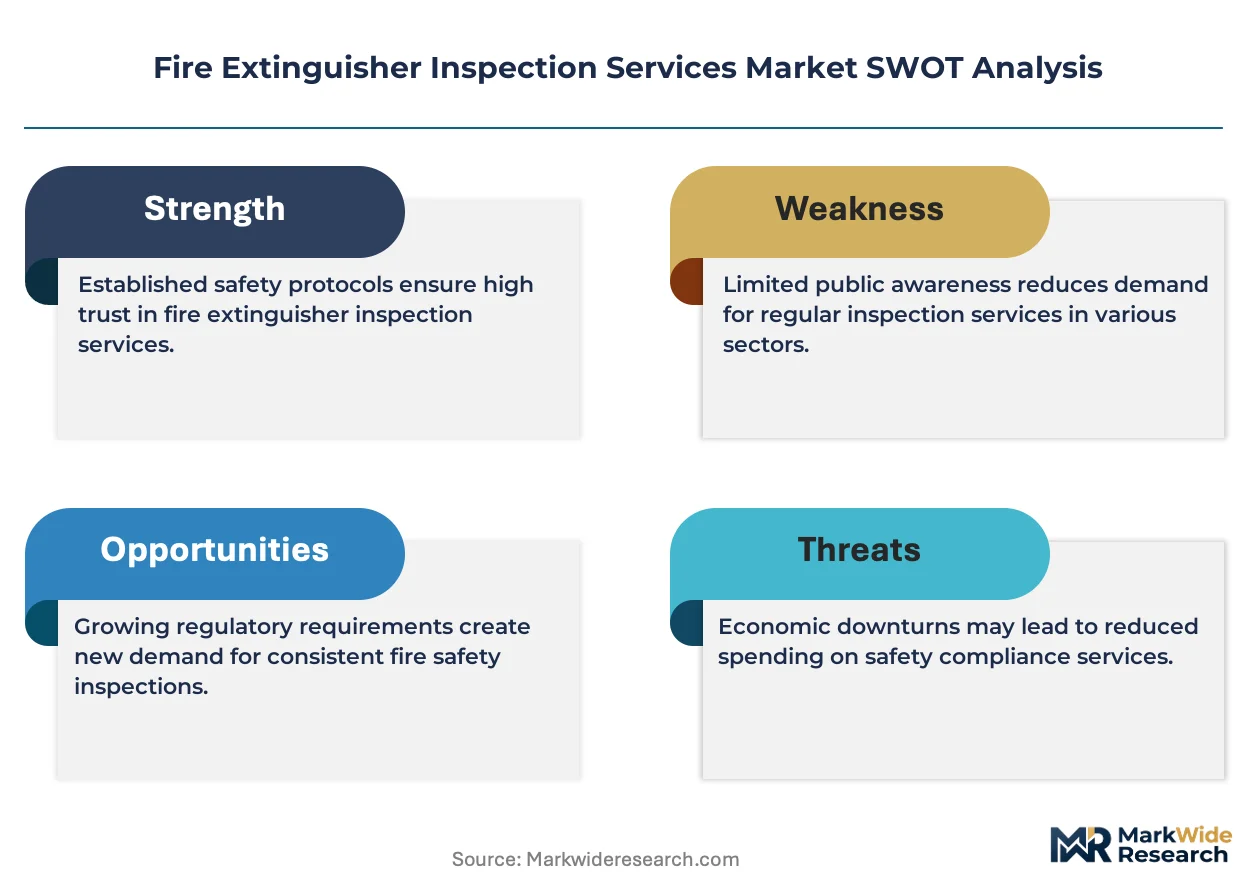
This market functions as a defensive-moat story, primarily due to regulatory entrenchment which creates non-discretionary, recurring demand for certified services.
For Market Incumbents: Consolidate fragmented regional markets through strategic acquisitions of smaller, localized service providers. Invest heavily in digital inspection platforms to enhance efficiency and provide integrated compliance reporting, countering commoditization from bundled services. Focus on expanding high-margin hydrostatic testing capabilities, particularly in regulated industrial zones, leveraging existing certification investments to differentiate service offerings.
For New Entrants and Emerging Players: Anchor in specialized testing verticals like aerospace or chemical manufacturing, which command premium rates due to unique regulatory demands. Target underpenetrated markets within Southeast Asia's growing manufacturing hubs, offering localized, rapid-response services. A viable go-to-market angle involves developing mobile-first reporting solutions tailored for small-to-medium enterprises, emphasizing transparent compliance and ease of use.
For Investors and Strategic Acquirers: Capital is best deployed toward technology-enabled regional specialists possessing strong local customer relationships and advanced digital reporting capabilities. The long-term viability remains strong, driven by consistent regulatory enforcement across all commercial and industrial sectors. A key signal to watch is the adoption rate of predictive maintenance services, indicating a shift towards higher-value, data-driven contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | Enhances operational efficiency and centralized compliance oversight for multi-site clients. |
| Hydrostatic Testing Capability Expansion | Addresses growing demand for high-margin, specialized certification in regulated industries. |
| Southeast Asia Market Entry | Captures new compliance service demand from rapidly industrializing manufacturing and logistics hubs. |
| Technician Training Programs | Mitigates skill gaps in both traditional fire safety and modern digital inspection software operation. |
| Regional Service Provider Acquisition | Expands geographic reach and localized customer relationships, consolidating market share. |
Research Approach
The analysis maps fire safety inspection services, specialized testing, and maintenance, each validated through primary interviews with Facility Managers, Safety Officers, and Fire Marshals. Secondary validation draws from NFPA standards, OSHA enforcement records, national statistical agency reports, and industry association publications. The methodology employs both bottom-up and top-down triangulation to ensure data accuracy.
Outputs were validated against external benchmarks from leading industry bodies and regulatory agencies over the projection horizon. The analytical framework modeled segmentation dimensions including service type, industry vertical, end-user, compliance standard, and regional market. Compound annual growth rates were derived from historical trends, projected regulatory shifts, and anticipated commercial construction activity, with new commercial construction permits serving as a key forecast input.
Material uncertainties — unforeseen regulatory amendments or significant economic downturns impacting commercial construction — sit outside the modeled envelope. Forecasts reflect assumptions documented through extensive primary and secondary research. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
Fire Extinguisher Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Firefighting Hose Market
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
Global Portable Foam Fire Extinguisher Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
Earthing Lightning Protection System Market
Fire Safety & Protection
Fire Suppression Market
Fire Safety & Protection
Smoke Pressure System Market
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
Fire and Explosion Proof Lights Market
Fire Safety & Protection
Fire Protection Systems for Industrial Cooking Market
Fire Safety & Protection
Europe Passive Fire Protection Market
Fire Safety & Protection
Portable Fire Extinguisher Market