
 Fire Alarm Systems Market | 2026-2036
Fire Alarm Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Alarm Systems Market Analysis
Data center operators is unwinding the historical dominance of hospital and university procurement in advanced fire detection. Johnson Controls leverages its captive channel through Johnson Controls-Hitachi to sustain installed-base upgrade revenue across North American commercial portfolios. Siemens AG anchors European specification pipelines through EN 54-certified addressable platforms that dominate rail and airport tenders. Hochiki Corporation competes on manufacturing scale in photoelectric sensor supply, extending its position across Southeast Asian infrastructure builds.
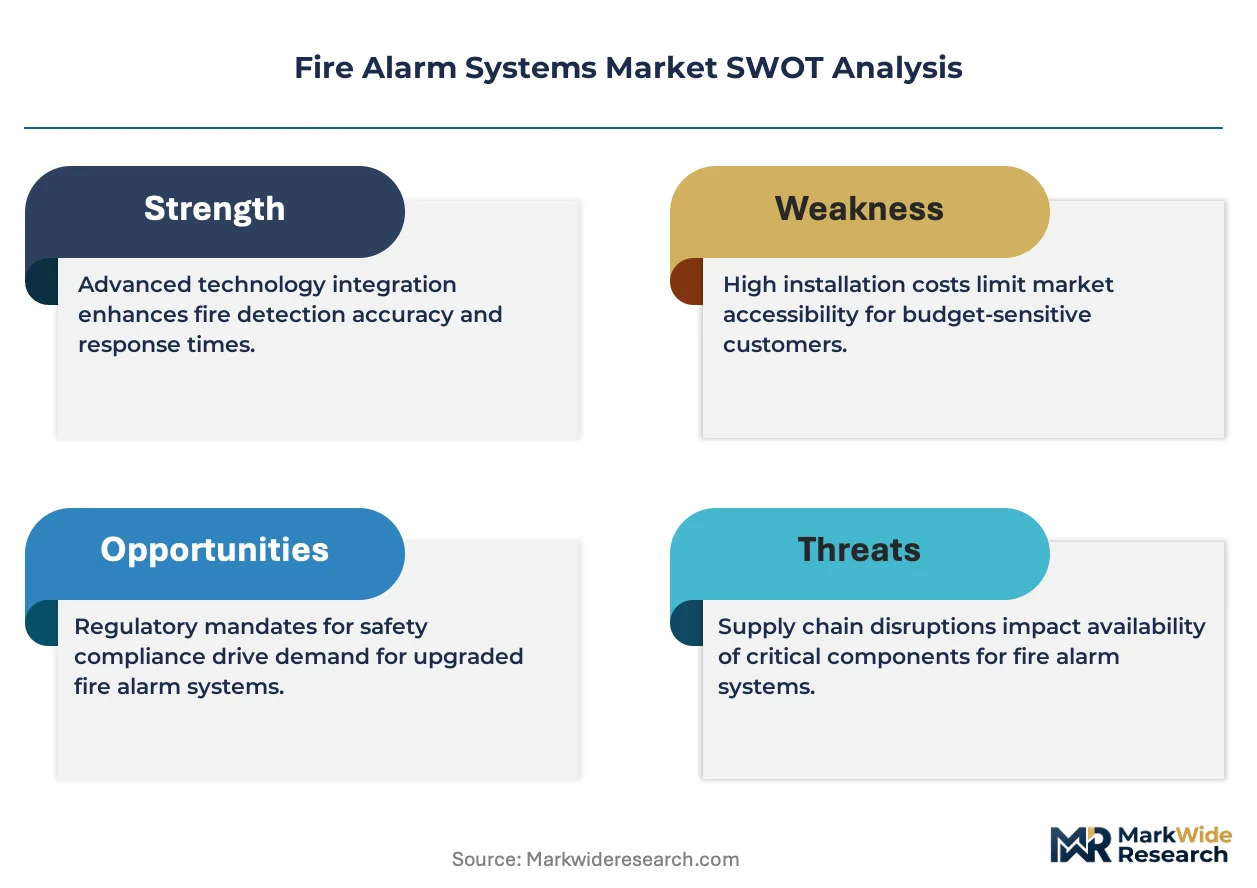
Fire alarm systems encompass detection, notification, and control assemblies engineered to UL 268 sensitivity thresholds for smoke particulate and NFPA 72 audibility requirements in occupied spaces, with primary purpose of life safety assurance and property protection through early warning and automated suppression triggering. Addressable technology leads product architecture as loop-isolation intelligence reduces false dispatch burden for municipal fire departments, while wireless segments capture fastest expansion where asbestos abatement costs prohibit hardwired retrofit in legacy educational facilities. IoT-enabled monitoring is concentrating margin pools in recurring service contracts rather than one-time hardware installation across hospitality and retail verticals.
NFPA 72 in the United States, EN 54 across EU member states, and BIS IS 2189 in India collectively tighten product certification requirements that shape manufacturer R&D allocation and market access timelines. The EPA's evolving stance on perfluorinated compounds in detector housings is forcing material substitution roadmaps across supplier engineering teams. Stakeholders must monitor divergence between regional certification protocols as smart sensor interoperability standards remain unsettled.
Market Dynamics
NFPA 72's 2022 edition mandates tighter integration between fire alarm networks and building automation systems, forcing wholesale replacement of legacy standalone panels across US commercial real estate and compressing procurement cycles for integrated platforms.
Growth Catalysts
- Addressable loop architecture:Municipal fire departments in the United States prioritize systems with individual device identification to reduce false dispatch costs. This specification pull accelerates obsolescence of conventional zone-based panels in multi-tenant office buildings.
- Data center buildouts:Hyperscale cloud operators in Northern Virginia, Frankfurt, and Singapore specify aspirating smoke detection with sub-60-second alarm verification to protect server rack densities exceeding 30 kW per cabinet.
- NFPA 72 wireless provisions:The 2022 code edition permits battery-powered devices in retrofit applications where asbestos abatement would exceed hardware costs, unlocking replacement demand in 1970s-era educational facilities across the United States.
Market Restraints
- Photoelectric sensor supply concentration:Southeast Asian manufacturing clusters dominate optical chamber production, exposing integrators to lead time volatility when regional logistics corridors face congestion.
- Perfluorinated compound restrictions:EPA scrutiny of PFAS in detector housings forces engineering teams to validate alternative thermoplastics without compromising UL 268 smoke entry performance.
- Copper and rare earth input costs:Addressable system cabling and neodymium magnets in notification appliances face commodity price swings that compress hardware margins for mid-tier distributors.
Strategic Opportunities
- India infrastructure builds:BIS IS 2189 certification requirements for new commercial construction in Mumbai and Bangalore create specification windows for EN 54-equivalent platforms adapted to tropical humidity conditions.
- IoT-enabled service contracts:Cloud-connected panel monitoring shifts revenue from one-time installation to recurring monthly fees, with hospitality chains in the United States piloting predictive maintenance subscriptions.
- Multi-sensor convergence:Combined smoke-heat-CO detection in single addressable heads reduces device count per square foot, appealing to cost-sensitive school district procurement in Texas and Florida.
Industry Challenges
- Legacy protocol fragmentation:Proprietary communication buses from 1990s-era installed bases resist integration with open BACnet/IP networks, forcing costly gateway deployments or full rip-and-replace decisions.
- Certification timeline compression:UL 268 7th Edition's revised sensitivity testing protocols extend product validation cycles by four to six months, delaying revenue recognition for manufacturers with pipeline dependencies.
- Cross-trained technician scarcity:Fire alarm installation requires dual competency in low-voltage electronics and sprinkler system interlock logic, creating labor bottlenecks in high-growth metropolitan construction markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Alarm Systems Market |
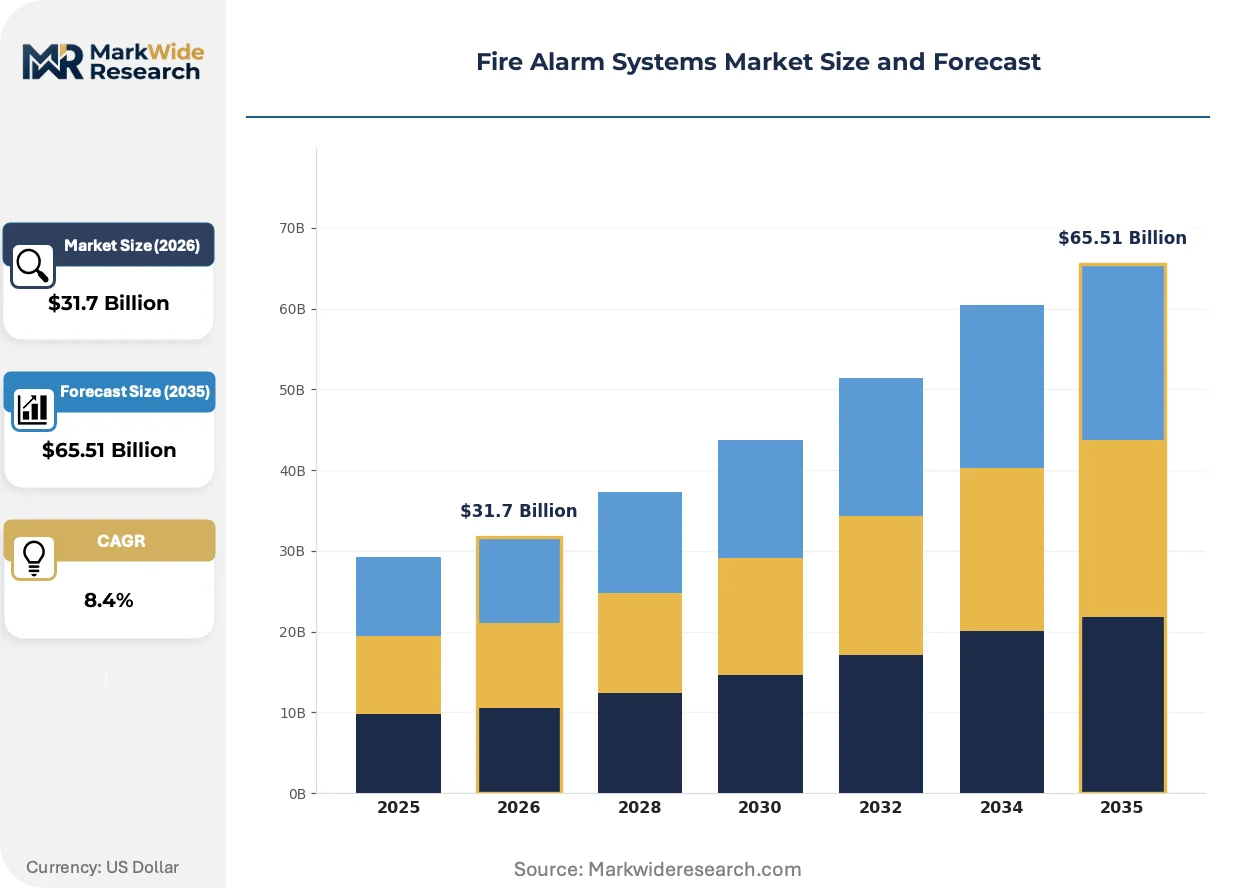
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $65.51 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Addressable, Wireless, Hybrid Installation Type: New Construction, Retrofitting, Industrial, Commercial End User: Hospitality, Education, Healthcare, Retail Technology: IOT, Smart Sensors, Photoelectric, Ionization |
| Companies Covered | Honeywell International, Johnson Controls, Siemens AG, Robert Bosch GmbH, Carrier Global Corporation, Eaton Corporation, Hochiki Corporation, Halma plc, Gentex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Alarm Systems Market Emerging Trajectories
Wireless mesh networking and cloud-native monitoring platforms are compressing the traditional divide between life safety hardware and building operations software, embedding fire systems within broader facility intelligence stacks.
Aspirating very early smoke detection apparatus (VESDA) is supplanting spot-type photoelectric heads in mission-critical environments. Data center operators in Ashburn, Virginia and Frankfurt am Main specify dual-stage aspiration with artificial intelligence-based particle classification to distinguish between dust intrusion and actual combustion signatures. This technology is supplanting redundant spot detector arrays, reducing device density per white floor while extending maintenance intervals through centralized filter monitoring.
EPA's evolving PFAS restrictions are reshaping material science roadmaps across detector housing supply chains. Engineering teams must validate glass-reinforced polyamide substitutes that maintain UL 94 V-0 flammability ratings without perfluorinated additives, compressing product refresh timelines for manufacturers with legacy tooling investments. US-based commercial real estate portfolios face accelerated replacement obligations as state-level compound bans outpace federal harmonization.
Buyer preference is consolidating around subscription-based monitoring contracts rather than capital-intensive hardware ownership. Hospitality REITs and retail property managers in the United States negotiate multi-site service agreements that bundle installation, 24/7 central station monitoring, and regulatory inspection documentation into per-square-foot pricing. This procurement model compresses distributor margins on equipment while concentrating recurring revenue with national monitoring providers and their technology partners.
Fire Alarm Systems Market Segmentation
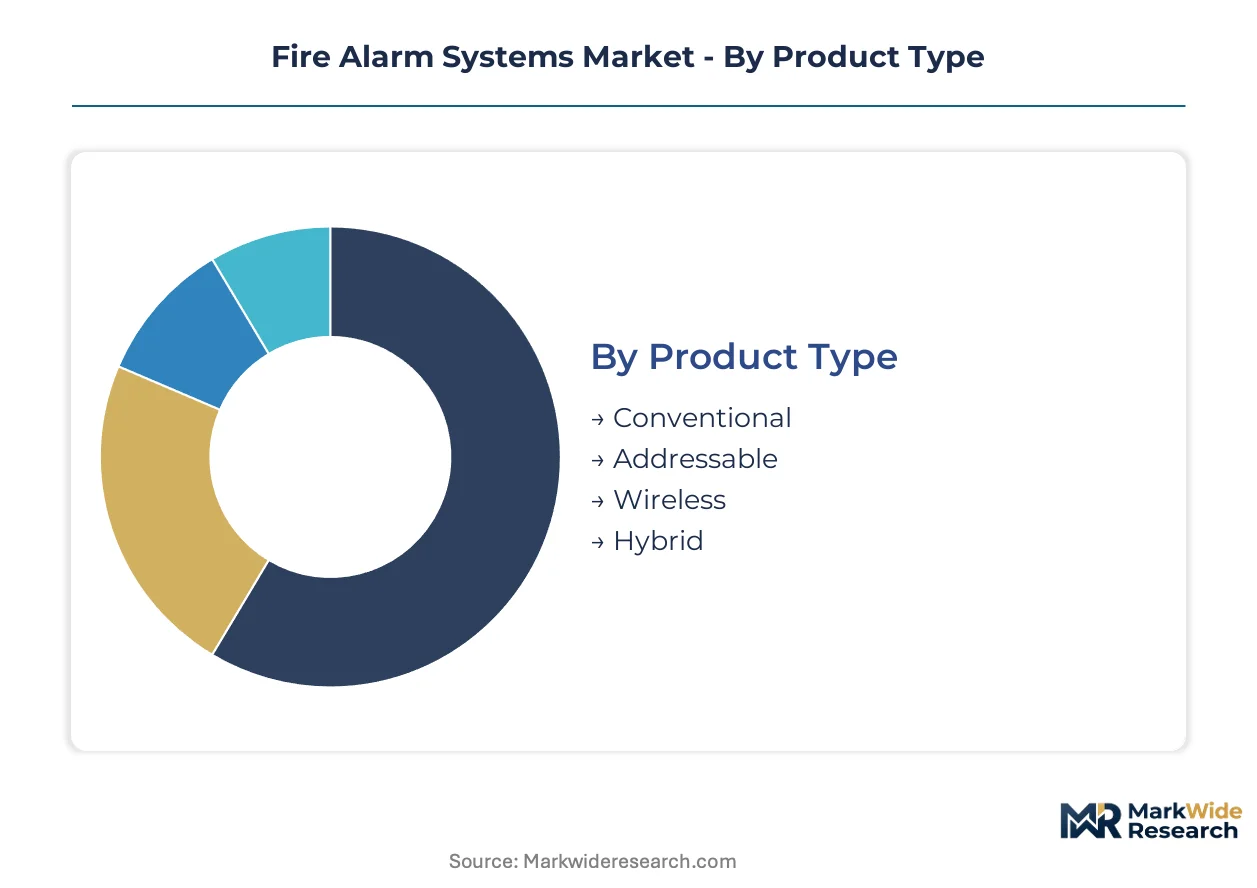
Fire alarm system procurement varies sharply across building vintages, regulatory jurisdictions, and life-safety risk profiles. Segment boundaries determine specification pipelines, certification requirements, and service contract structures for manufacturers and integrators.
Product Type:
Addressable systems dominate export shipments to data center and rail infrastructure markets, while conventional panels retain domestic share in cost-sensitive municipal and small commercial installations.
- Addressable:Loop-isolation intelligence enables individual device identification and reduces false dispatch burdens for municipal fire departments. Demand concentrates in multi-tenant office buildings across the United States where NFPA 72 mandates tighter building automation integration.
- Wireless:Battery-powered mesh networks eliminate asbestos abatement costs in 1970s-era educational retrofits. Procurement is accelerating fastest in United States school districts where hardwired installation would exceed hardware expenditure.
- Conventional:Zone-based architecture serves small commercial and residential applications with simpler wiring topologies. Domestic procurement in India and Southeast Asia favors these systems for cost-sensitive infrastructure builds.
- Hybrid:Mixed conventional-addressable configurations bridge legacy upgrades without full panel replacement. Demand clusters in European commercial real estate portfolios with phased renovation timelines.
Addressable holds installed capacity. Wireless is rotating up the share rankings.
Installation Type:
Retrofitting commands premium pricing per device due to asbestos containment and occupancy disruption costs, while new construction offers volume scale through specification-at-design.
- New Construction:Specification-at-design enables integrated fire-BMS architectures from slab pour. Demand concentrates in hyperscale data center builds across Northern Virginia, Frankfurt, and Singapore where aspirating detection is specified during MEP coordination.
- Retrofitting:Legacy panel replacement faces asbestos abatement and occupancy scheduling constraints. Procurement in United States educational facilities is unlocking as NFPA 72 wireless provisions reduce infrastructure demolition requirements.
- Industrial:Harsh-environment housings and explosion-proof ratings serve petrochemical and manufacturing footprints. Specification pipelines in Germany and the Netherlands favor EN 54-certified platforms with IP65 ingress protection.
- Commercial:Multi-tenant office and retail installations balance aesthetic concealment with audibility requirements. Hospitality REITs in the United States are piloting subscription-based monitoring contracts alongside hardware installation.
New Construction anchors volume throughput. Retrofitting is climbing the fastest on value-per-device metrics.
End User:
Healthcare and education procurement operates through extended public bidding cycles, while hospitality and retail favor bundled service contracts with national monitoring providers.
- Healthcare:Patient-sleeping occupancy mandates voice evacuation and visual notification appliances per NFPA 72. Hospital procurement in the United States prioritizes UL 268 7th Edition sensitivity compliance for smoke detection in HVAC zones.
- Education:K-12 and university facilities face 1970s-era legacy replacement obligations. United States school districts in Texas and Florida are specifying multi-sensor smoke-heat-CO heads to reduce device density per square foot.
- Hospitality:24/7 occupancy patterns and brand-risk exposure drive central station monitoring penetration. United States hotel chains are negotiating multi-site service agreements with per-square-foot pricing structures.
- Retail:Big-box and mall installations balance open-ceiling detection coverage with shrinkage-conscious aesthetic constraints. Procurement favors wireless retrofit where tenant improvement budgets limit infrastructure investment.
Healthcare holds specification complexity. Hospitality is gaining share fastest through recurring revenue conversion.
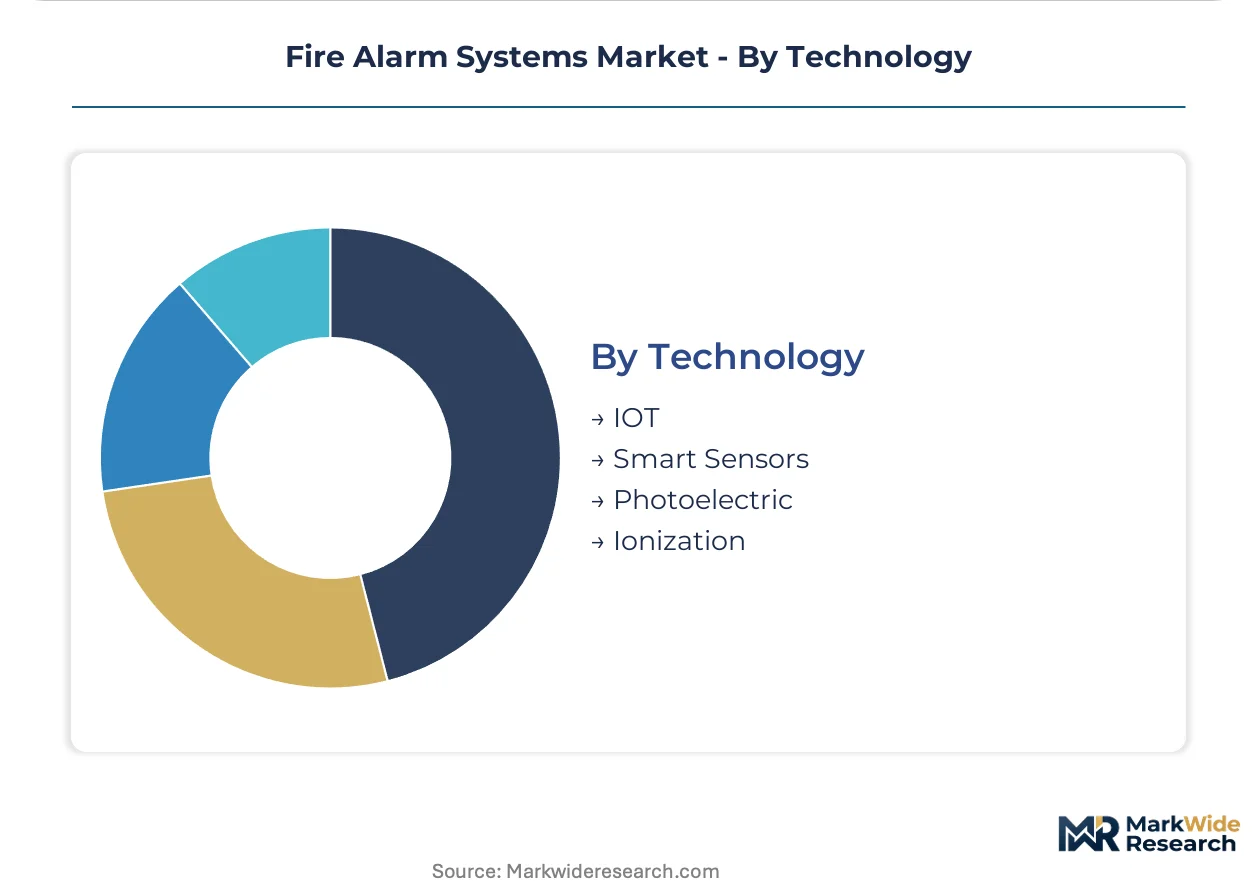
Technology:
Photoelectric sensors dominate manufactured volume through Southeast Asian optical chamber supply chains, while IoT platforms concentrate margin in software-enabled service contracts.
- Photoelectric:Light-scattering detection of smoke particulate serves standard commercial and residential applications. Manufacturing concentrates in Southeast Asian clusters, exposing integrators to logistics corridor congestion risks.
- IOT:Cloud-connected panel monitoring enables predictive maintenance and remote diagnostics. United States hospitality and retail verticals are shifting procurement from capital hardware to recurring monthly service fees.
- Smart Sensors:Multi-criteria detection combining smoke, heat, and CO sensing in single addressable heads. Cost-sensitive school districts in the United States favor reduced device count per coverage zone.
- Ionization:Americium-241 based detection persists in legacy installations but faces replacement pressure. Regulatory scrutiny of radioactive source handling is accelerating obsolescence in European and North American markets.
Photoelectric anchors unit shipments. IOT is rotating up the share rankings on margin contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center operators and educational facility managers concentrate procurement authority across distinct national markets, each shaped by local code enforcement and infrastructure investment cycles.
United States
Hyperscale cloud operators in Northern Virginia and Texas drive specification for aspirating detection systems with sub-60-second verification protocols. NFPA 72's 2022 edition mandates tighter building automation integration, compressing replacement cycles for legacy standalone panels. Municipal fire departments in California and Florida prioritize addressable loop architectures to reduce false dispatch costs.
Germany
Rail infrastructure tenders and airport expansions in Frankfurt and Munich anchor demand for EN 54-certified addressable platforms. The country's national building regulator enforces strict flammability standards for detector housings, accelerating material substitution away from perfluorinated compounds. Industrial clusters in North Rhine-Westphalia specify explosion-proof ratings for petrochemical applications.
India
BIS IS 2189 certification requirements for new commercial construction in Mumbai and Bangalore create specification windows for adapted platforms. The Bureau of Indian Standards tightens product validation timelines, extending market access procedures for foreign manufacturers. Infrastructure builds in Telangana and Gujarat favor cost-sensitive conventional systems for volume deployment.
Singapore
Data center builds in the Jurong and Tuas districts specify dual-stage aspiration with AI-based particle classification to protect high-density server racks. The country's national fire safety regulator enforces tropical humidity adaptations for imported detection equipment. Smart city infrastructure rollouts in the central business district integrate fire networks with building management platforms.
United Kingdom
Healthcare procurement through the National Health Service mandates voice evacuation systems for patient-sleeping occupancies. The country's national standards body maintains alignment with EN 54 while adapting to post-regulatory divergence. Commercial real estate in London and Manchester faces retrofit obligations in aging stock built before addressable technology adoption.
Fire Alarm Systems Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with captive distribution channels and specialized life safety pure-plays with manufacturing scale advantages. The vendor base concentrates around three strategic archetypes: building technology integrators leveraging installed-base upgrade revenue, component specialists dominating optical sensor supply, and fire safety pure-plays competing on certification breadth. Competitive dynamics center on vertical integration into monitoring services and geographic expansion through specification capture in data center and rail infrastructure tenders.
Among the building technology conglomerates, Johnson Controls and Siemens AG exemplify the integrated-platform archetype, each leveraging established specification relationships to sustain upgrade revenue across commercial portfolios. Hochiki Corporation occupies a position within the manufacturing-specialist tier, competing on scale in photoelectric sensor production for Southeast Asian infrastructure builds. These three anchors illustrate how competitive positioning depends on channel control, certification breadth, and manufacturing geography rather than product differentiation alone.
| Leading Market Players |
|---|
| Honeywell International |
| Johnson Controls |
| Siemens AG |
| Robert Bosch GmbH |
| Carrier Global Corporation |
| Eaton Corporation |
| Hochiki Corporation |
| Halma plc |
| Gentex Corporation |
| Others |
Supply Flow & Price Mechanics
Photoelectric sensor manufacturing scale in Southeast Asian clusters establishes cost floors that propagate through addressable system pricing tiers. Dense optical chamber production in Malaysia and Thailand concentrates supplier leverage, while copper cabling and neodymium magnet costs in notification appliances introduce commodity-linked volatility that compresses hardware margins at the distribution tier.
Pricing Analysis
Cost-plus contracts with copper and rare-earth indexation dominate procurement between mid-tier distributors and panel manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates UL 268 7th Edition-certified aspirating systems from conventional zone-based panels and entry-grade conventional configurations. Price differentiation hinges on certification grade and after-sales service bundling, with hospitality REITs showing lowest sensitivity due to subscription-model conversion while Texas school districts exhibit acute pressure on per-device expenditure. Cost compression in standard-tier addressable hardware is intensifying because neodymium magnet supply volatility feeds through to notification appliance production.
Supply Chain Analysis
Port congestion on the Shenzhen-Los Angeles trade lane elevates inbound logistics costs for optical chamber imports. Manufacturing concentrates in Malaysia, Thailand, and Vietnam for photoelectric sensor housings, while copper cabling draws from Chilean and Peruvian concentrate refined in Chinese fabrication plants. Supply chain risk centers on single-source vulnerability for neodymium magnet supply from Chinese separation facilities. Distribution runs through captive channels at building technology conglomerates and open distribution for mid-tier integrators serving municipal and educational procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fire alarm systems are shifting from standalone hardware sales toward platform-economics structures where BACnet/IP interoperability and cloud-native monitoring create winner-take-most dynamics. The NFPA 72 2022 edition's building automation integration mandate accelerates this ecosystem consolidation.
For Market Incumbents: Shield installed-base upgrade revenue by deepening backward integration into IoT-enabled service contracts before national monitoring providers capture recurring fee pools. Prioritize certification investment in BIS IS 2189 adaptations for Mumbai and Bangalore specification windows, as emerging entrant pure-plays threaten EN 54-equivalent platform positioning in tropical humidity applications. For New Entrants and Emerging Players: Predictive maintenance subscription gaps in United States hospitality chains offer white-space entry where incumbent building technology conglomerates under-serve mid-scale REITs with standardized per-square-foot pricing. Target wireless retrofit procurement in 1970s-era Florida educational facilities, deploying battery-powered mesh networks through direct regional integrator partnerships rather than national distribution. For Investors and Strategic Acquirers: Cloud-native monitoring pure-plays with established central station relationships represent the most defensible acquisition archetype as recurring revenue concentration accelerates. Long-term viability rests on software-enabled service contract penetration rather than hardware shipment volume. Watch for state-level PFAS compound bans outpacing federal harmonization as the inflection signal requiring portfolio rebalancing toward glass-reinforced polyamide-ready manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| IoT-Enabled Service Contract Expansion | Shifts revenue from hardware installation to recurring monthly fees across hospitality portfolios. |
| Multi-Sensor Convergence Development | Reduces device count per square foot for cost-sensitive Texas and Florida school districts. |
| BIS IS 2189 Certification Investment | Unlocks specification windows in Mumbai and Bangalore commercial construction tenders. |
| PFAS-Free Material Substitution | Validates glass-reinforced polyamide housings ahead of state-level compound bans. |
| Wireless Mesh Network Deployment | Eliminates asbestos abatement costs in 1970s-era United States educational retrofits. |
Methodological Framework
A spread of perspectives from fire system integrators, municipal fire department procurement officers, data center facility managers, and hospitality REIT operations directors converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from NFPA code revision documentation, UL 268 certification records, SEC 10-K filings from building technology conglomerates, and customs data on photoelectric sensor import volumes. Bottom-up triangulation across addressable panel shipment estimates and top-down validation through construction spending attribution anchored volume and value outputs.
Segmentation dimensions modeled span product architecture (addressable, wireless, conventional, hybrid), installation type (new construction, retrofitting, industrial, commercial), end-user vertical (healthcare, education, hospitality, retail), and technology tier (photoelectric, IoT-enabled, smart sensor, ionization). CAGRs were derived from regression analysis against construction permit flows and regulatory compliance deadlines across the projection horizon. Industry-specific forecast inputs include hyperscale data center buildout pipelines and NFPA 72 adoption curve assumptions.
Forecasts assume regulatory continuity in NFPA 72 enforcement patterns, EN 54 certification requirements, and BIS IS 2189 validation timelines; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated PFAS restrictions disrupting detector housing supply, copper price spikes affecting addressable cabling costs, and cross-trained technician scarcity delaying installation throughput. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Protection Systems for Industrial Cooking Market
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
Fire Safety Equipment Market
Fire Safety & Protection
Global Fire Extinguisher Cylinders Market
Fire Safety & Protection
Automatic Fire Ball Extinguisher Market
Fire Safety & Protection
Deflagration Flame Arresters Market
Fire Safety & Protection
Earthing Lightning Protection System Market
Fire Safety & Protection
Fire Door Market
Fire Safety & Protection
North America Fire Protection Water Storage Tanks Market
Fire Safety & Protection
Fire Resistant Glass Market
Fire Safety & Protection
Flame Detector System Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
UAE Fire Protection System Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
Fire Suppression Equipment Market