
 Smoke Detector Market | 2026-2036
Smoke Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Smoke Detector Market Intelligence
Commercial facility managers is unwinding the historical dominance of homeowner-driven replacement cycles. Honeywell International Inc. leverages its building automation ecosystem to anchor large-scale fire safety contracts across North America. Siemens AG competes through integrated digital platforms that tie smoke detection into broader facility management systems. Johnson Controls International PLC sustains manufacturing scale advantages in hardwired interconnected systems for multi-tenant properties.
A smoke detector is an autonomous fire safety device incorporating optical, ionization, or air-sampling sensors to identify combustion particulates, typically operating at sensitivity thresholds calibrated to UL 268 or EN 54-7 standards and emitting audible alerts at 85 decibels minimum to enable occupant evacuation. Photoelectric smoke detectors dominate residential retrofits due to superior performance with smoldering fires and reduced false-alarm rates versus ionization units. Aspirating smoke detectors command premium positioning in data centers and cleanroom industrial facilities where early warning sensitivity justifies higher installed costs. Smart smoke alarm technology is displacing conventional battery-operated units as interoperability with home automation platforms becomes a standard procurement criterion.
The US National Fire Protection Association's NFPA 72 standard and the European Union's Construction Products Regulation frame mandatory installation and performance benchmarks that shape product certification requirements and market access conditions. China's Ministry of Emergency Management enforces GB 4715 compliance for domestic manufacturing, creating divergent testing protocols that fragment supplier qualification burdens. Stakeholders must monitor evolving wireless protocol standards and interoperability mandates as municipalities begin requiring connected alarm networks that report directly to emergency dispatch systems.
Market Dynamics
Wireless interconnectivity mandates in North America and Europe are collapsing the standalone battery-operated segment while forcing suppliers to requalify entire product portfolios for mesh-network compatibility and cloud-reporting protocols.
Growth Catalysts
- NFPA 72 wireless mandate:US jurisdictions now require interconnected alarms in new construction and major renovations, eliminating standalone units from permitted projects.
- Photoelectric sensor superiority:Smoldering-fire detection performance and reduced false-alarm rates are driving replacement of ionization technology in residential retrofits.
- Data center construction:Aspirating smoke detection systems command premium positioning in hyperscale facilities where early warning sensitivity justifies installed cost premiums.
Market Restraints
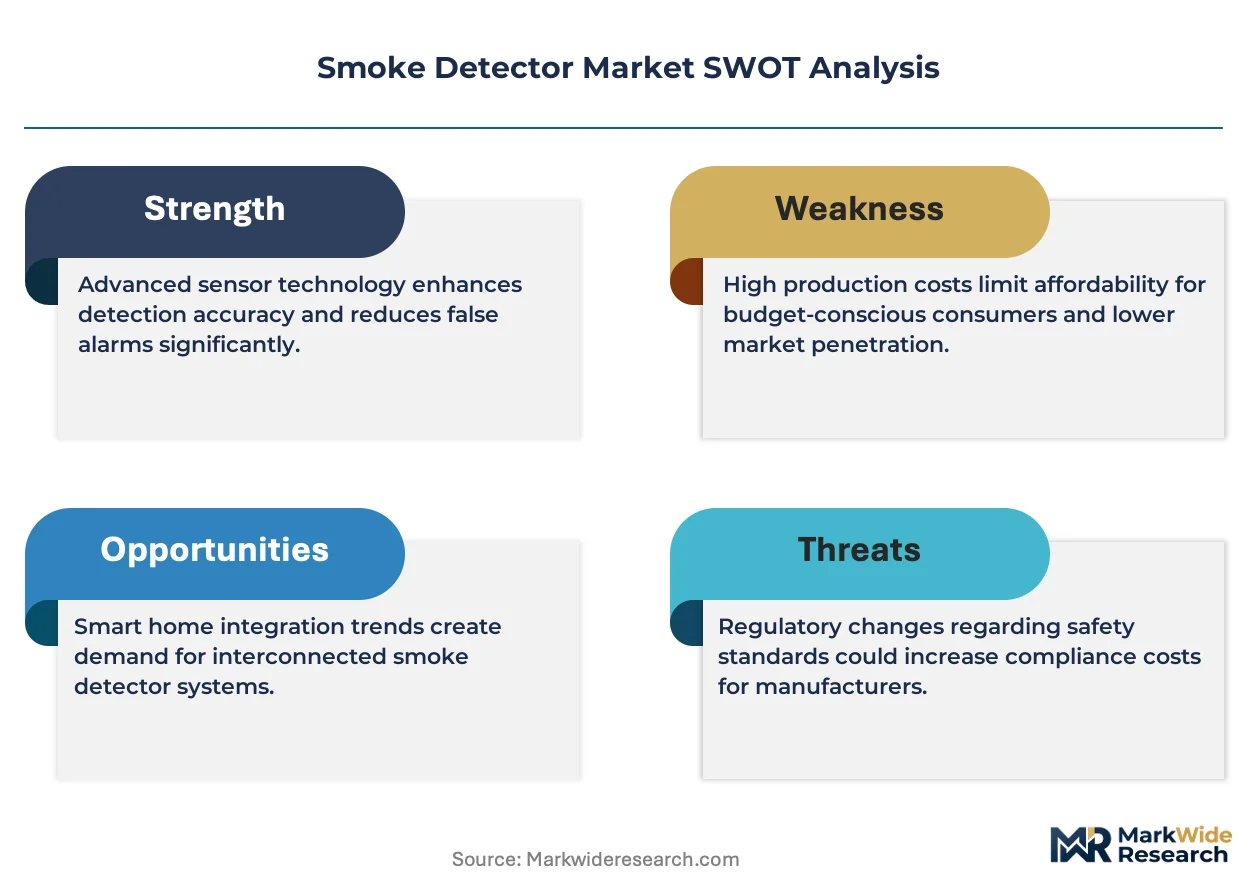
- Semiconductor input volatility:RF chipsets and MEMS sensors for smart alarms face concentrated foundry capacity in Taiwan, creating supply bottlenecks.
- GB 4715 fragmentation:China's divergent testing protocols force redundant certification cycles for manufacturers serving both domestic and export markets.
- Installation labor constraints:Electrician shortages in Germany and the United States delay hardwired interconnected system deployments in multi-tenant properties.
Strategic Opportunities
- India building code modernization:Urban development authorities in Mumbai and Delhi are drafting mandatory smoke alarm provisions for high-rise residential towers.
- Matter protocol convergence:Unified smart home interoperability standards enable single-SKU strategies across Amazon Alexa, Google Home, and Apple HomeKit ecosystems.
- Emergency dispatch integration:Municipalities in California and Texas are piloting direct alarm-to-dispatch connectivity, creating subscription revenue streams for monitoring services.
Industry Challenges
- UL 268 Edition 7 recertification:Revised sensitivity and false-alarm testing protocols require engineering redesigns and extended approval timelines for legacy product lines.
- Legacy system interoperability:Property managers face integration complexity when retrofitting smart alarms into existing hardwired networks with incompatible voltage and signaling standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoke Detector Market |
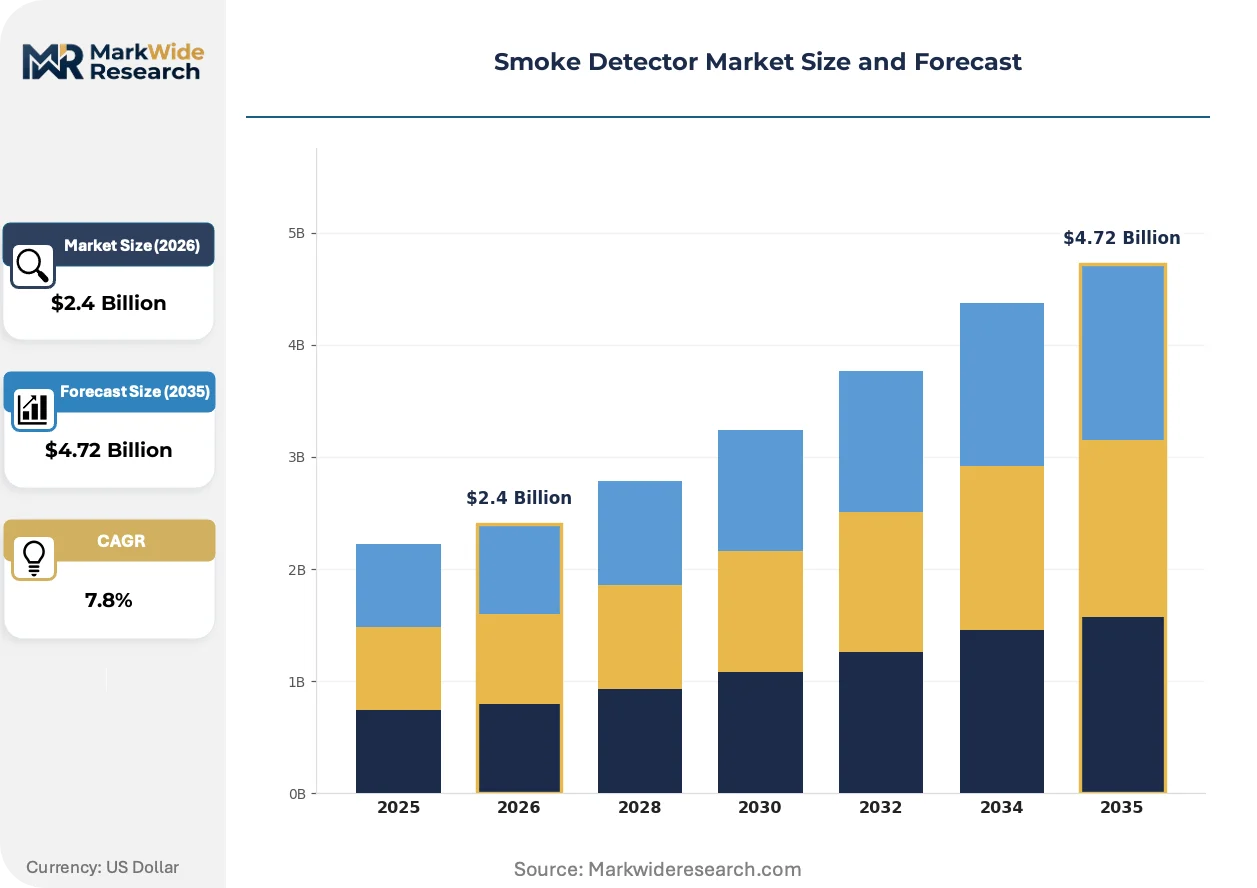
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ionization Smoke Detector, Photoelectric Smoke Detector, Dual Sensor Smoke Detector, Aspirating Smoke Detector Technology: Wireless, Hardwired, Battery Operated, Interconnected, Smart Smoke Alarm Application: Commercial Buildings, Residential Properties, Industrial Facilities, Educational Institutions End User: Facility Managers, Homeowners, Safety Inspectors, Property Developers |
| Companies Covered | Honeywell International Inc., Siemens AG, Johnson Controls International PLC, Robert Bosch GmbH, Hochiki Corporation, Carrier Global (Kidde), Resideo Technologies Inc., Halma plc, Mircom Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoke Detector Market Strategic Shifts & Innovations
Sensor fusion architectures and edge-computing capabilities are redefining detection accuracy thresholds while compressing hardware form factors and enabling predictive maintenance business models.
Multi-criteria detection technology combining photoelectric, thermal, and carbon monoxide sensing is miniaturizing into single-chamber designs that reduce false alarms through algorithmic cross-verification. Large-scale commercial landlords in the United States are specifying these units for Class A office renovations. The technology is miniaturizing enclosure sizes by forty percent versus discrete-sensor configurations, enabling concealed ceiling installations where aesthetics constrain device visibility.
The European Union's Construction Products Regulation is tightening CE marking requirements for smoke alarm radio-frequency emissions and electromagnetic compatibility. Manufacturers must now submit updated technical documentation demonstrating compliance with EN 54-7 amendments covering wireless functionality. German facility management contractors are responding by consolidating procurement around suppliers with in-house Notified Body relationships, compressing vendor shortlists for public-sector tenders.
Facility managers are unbundling alarm hardware from long-term monitoring contracts, shifting toward capital-expenditure purchases with software-subscription overlays. This pattern disrupts traditional fire-safety integrators who bundled installation, equipment, and monitoring into ten-year agreements. The shift is most visible in United States healthcare properties where Johnson Controls and Honeywell compete for open-architecture specifications that allow third-party monitoring selection.
Smoke Detector Market Segmentation
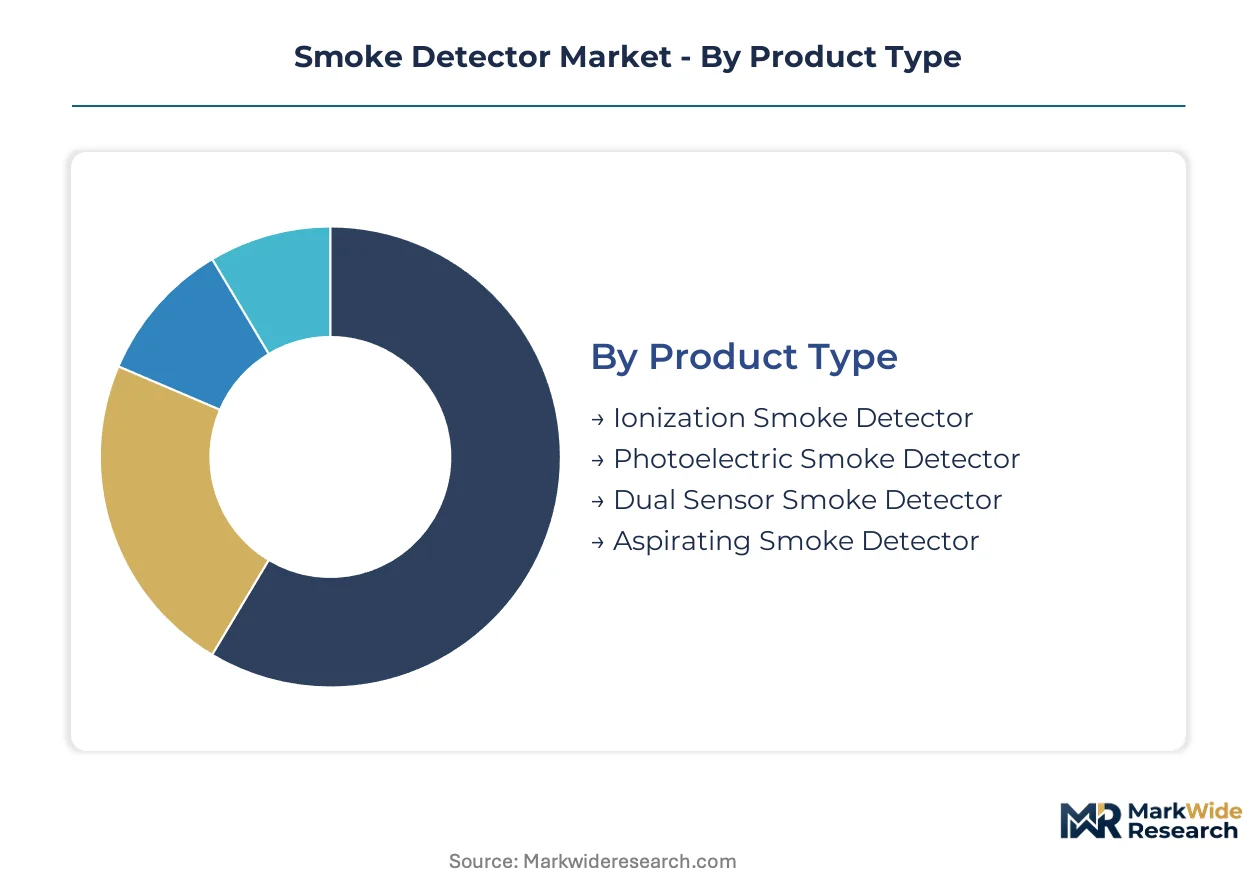
Smoke detector segmentation reveals how substitution pressures reshape procurement patterns across product categories. Technology mandates and interoperability standards force distinct migration paths for each segment, with regulatory deadlines compressing upgrade timelines unevenly.
Product Type:
Ionization smoke detectors face the most acute substitution threat as building codes phase out their standalone deployment in favor of photoelectric and multi-sensor alternatives.
- Ionization Smoke Detector:These units employ americium-241 to detect fast-flaming fires through radioactive ionization of air between charged plates. Residential retrofits in the United States are accelerating replacement cycles as NFPA 72 jurisdictions blacklist standalone ionization units from new permits.
- Photoelectric Smoke Detector:A light source and photodiode chamber detect smoldering-fire particulates with superior false-alarm resistance. Germany's facility management contractors specify these for multi-tenant housing renovations where reduced nuisance alarms lower maintenance call volumes.
- Dual Sensor Smoke Detector:Combined photoelectric and ionization chambers address both flaming and smoldering fire signatures within single enclosures.
- Aspirating Smoke Detector:Networked pipe systems draw air samples into centralized laser-detection chambers for hyperscale data center applications.
Photoelectric technology anchors the volume base while aspirating systems gain share at the steepest rate in premium commercial installations.
Technology:
Cost tier stratification separates professional hardwired installations from consumer-grade battery alternatives, with smart alarms commanding intermediate positioning through subscription overlay models.
- Wireless:Mesh-network protocols enable battery-powered interconnection without conduit installation, reducing retrofit labor costs in existing residential structures. California municipalities specify these for aging housing stock where hardwired infrastructure proves cost-prohibitive.
- Hardwired:120V AC supply with battery backup delivers the reliability baseline for commercial code compliance. Electrician shortages in the United States and Germany constrain deployment velocity in multi-tenant properties despite regulatory mandates.
- Battery Operated:Standalone 9V or lithium-cell units dominate legacy residential penetration where grandfather clauses delay upgrade requirements.
- Interconnected:Hardwired or wireless signal-linking ensures whole-building alarm synchronization, now mandatory across most North American jurisdictions.
- Smart Smoke Alarm:Wi-Fi or Thread-enabled devices integrate with home automation platforms and offer remote monitoring capabilities.
Hardwired systems retain the largest installed base while smart alarms climb the fastest as Matter protocol convergence reduces ecosystem fragmentation.
Application:
Volume concentration in residential properties contrasts with margin concentration in specialized industrial environments where detection sensitivity justifies premium positioning.
- Commercial Buildings:Class A office and retail specifications demand addressable systems with centralized monitoring integration. Large-scale landlords in the United States unbundle hardware from monitoring contracts, shifting procurement toward capital-expenditure purchases with software overlays.
- Residential Properties:Single-family and multi-family housing accounts for the highest unit volumes, driven by retrofit cycles and new construction codes. China's urban development authorities in Beijing and Shanghai are drafting mandatory provisions for high-rise towers.
- Industrial Facilities:Harsh-environment specifications with explosion-proof enclosures serve petrochemical and manufacturing plants.
- Educational Institutions:Dormitory and classroom installations prioritize voice-evacuation compatibility and mass-notification system integration.
Residential applications anchor the volume base while industrial facilities gain share at the steepest rate through aspirating system penetration.
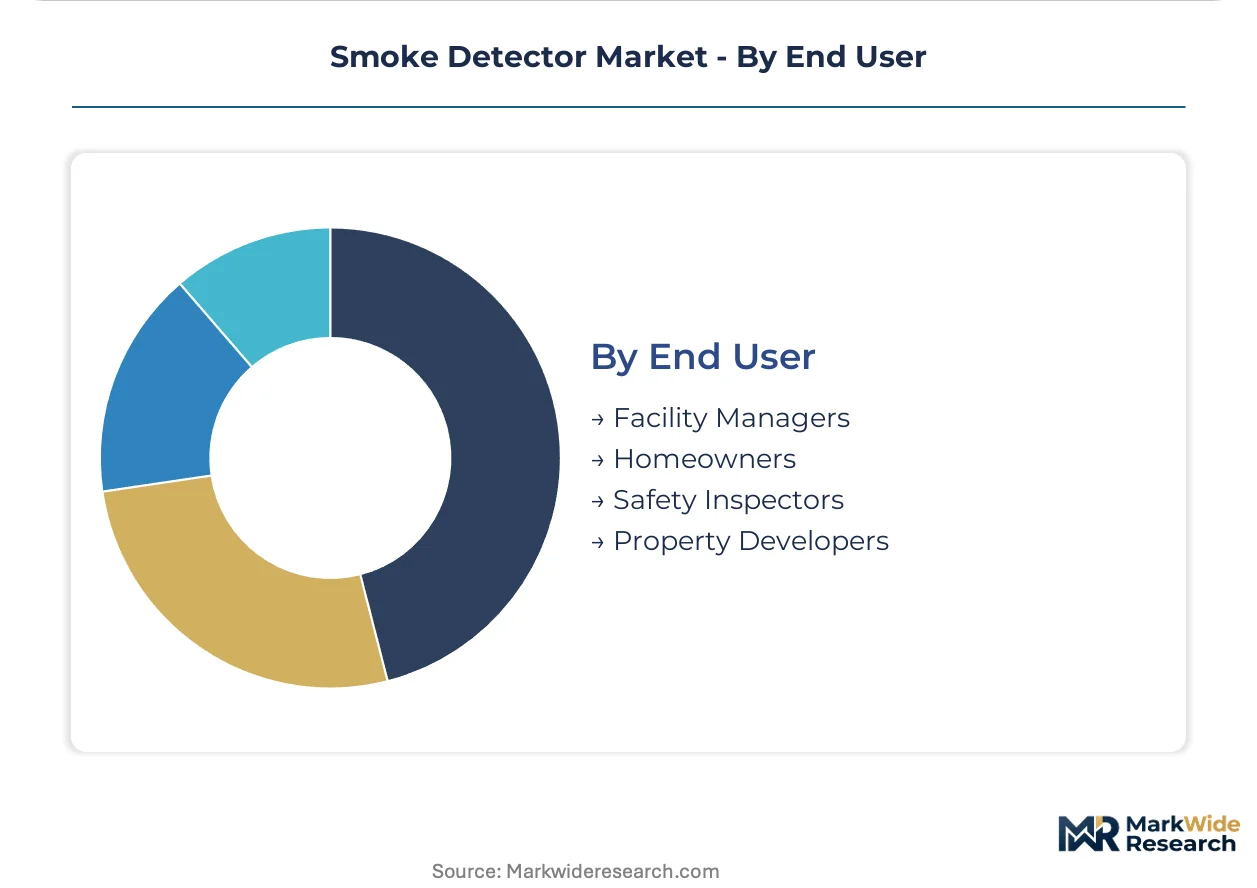
End User:
Procurement authority is shifting from homeowners toward institutional purchasers with centralized specification power and long-term contract leverage.
- Facility Managers:Commercial and institutional property operators consolidate purchasing across portfolios, favoring suppliers with building automation ecosystem integration. Honeywell and Siemens compete for these specifications through digital platform bundling.
- Homeowners:Individual purchasers drive replacement cycles in existing housing stock, increasingly selecting smart alarms with DIY installation compatibility. Retail channel concentration in the United States favors brands with Amazon and big-box hardware store placement.
- Safety Inspectors:Regulatory enforcement personnel influence specification through code interpretation and compliance verification authority.
- Property Developers:New construction decisions are locked during design phase, with pre-wired interconnected systems specified to minimize future retrofit liability.
Facility managers anchor the volume base in commercial segments while property developers gain influence at the steepest rate as new construction accelerates code-compliant pre-installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex anchors trans-Pacific electronics flows that feed North American smart smoke alarm assembly. Germany's Rhine-Main corridor channels industrial components into European distribution networks. China's Yangtze River Delta concentrates photoelectric sensor foundry capacity.
United States
Residential retrofit cycles and multi-tenant construction drive unit demand across California and Texas metros. The NFPA 72 standard mandates interconnected alarms in new construction and major renovations. Electrician shortages in Dallas-Fort Worth and Phoenix delay hardwired system deployments despite code deadlines.
Germany
Facility management contractors consolidate procurement for multi-tenant housing renovations in Berlin and Hamburg. The Construction Products Regulation tightens CE marking requirements for radio-frequency emissions and electromagnetic compatibility. North Rhine-Westphalia's industrial corridor hosts testing laboratories that compress vendor qualification timelines for public-sector tenders.
China
Urban development authorities in Beijing and Shanghai draft mandatory smoke alarm provisions for high-rise residential towers. The Ministry of Emergency Management enforces GB 4715 compliance for domestic manufacturing. Shenzhen's electronics cluster supplies MEMS sensors and RF chipsets to regional alarm assemblers facing export-market certification burdens.
Japan
Metropolitan Tokyo's aging housing stock accelerates wireless retrofit installations where hardwired infrastructure proves cost-prohibitive. METI guidelines shape fire safety equipment procurement for commercial facilities. Osaka-Kansai industrial districts manufacture compact photoelectric chambers for regional and Southeast Asian export markets.
India
Mumbai and Delhi urban development authorities draft mandatory provisions for high-rise residential towers. BIS certification requirements create compliance thresholds for both domestic manufacturers and importers. Bangalore's electronics manufacturing clusters assemble battery-operated units for price-sensitive tier-two city penetration.
Smoke Detector Market Key Industry Players
Concentration sits with diversified industrial conglomerates that leverage building automation ecosystems to anchor large-scale contracts. Three to five global players control premium commercial specifications through integrated digital platforms. Mid-tier specialists compete on retrofit compatibility and regional certification speed. Dominant competitive moves include strategic partnerships with facility management platforms and portfolio diversification into adjacent environmental sensing.
Within the building automation tier, Honeywell International Inc., Siemens AG, and Johnson Controls International PLC exemplify scale-driven positioning. Honeywell leverages its North American distribution density to secure multi-year fire safety contracts. Siemens anchors European specifications through digital platform bundling that ties detection into broader facility management systems. Johnson Controls sustains manufacturing scale advantages in hardwired interconnected systems for multi-tenant properties.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Johnson Controls International PLC |
| Robert Bosch GmbH |
| Hochiki Corporation |
| Carrier Global (Kidde) |
| Resideo Technologies Inc. |
| Halma plc |
| Mircom Group |
| Others |
Cost & Logistics Intelligence
UL 268 Edition 7 recertification requirements gate both supplier qualification timelines and price stratification across photoelectric, ionization, and multi-sensor product tiers. Manufacturers bearing extended approval cycles and engineering redesign costs pass these through to premium positioning for addressable systems with cloud-reporting capabilities.
Pricing Analysis
Volume-discount tiering separates aspirating systems for hyperscale data centers from battery-operated residential units and hardwired interconnected commercial installations. Price differentiation rests on UL 268 certification grade and after-sales monitoring service bundling. Cost compression in the standalone battery segment intensifies because of wireless interconnectivity mandates displacing legacy units. Facility managers exhibit the lowest price sensitivity given lifecycle cost framing, while homeowners in retrofit markets drive aggressive unit-cost negotiation.
Supply Chain Analysis
Taiwan and South Korea anchor RF chipset and MEMS sensor foundry capacity feeding smart alarm assembly operations. Raw material dependencies span americium-241 for ionization chambers, photodiode arrays for photoelectric detection, and laser modules for aspirating systems. Single-source vulnerability concentrates in Taiwan semiconductor fabrication, exposing suppliers to geopolitical disruption. Distribution runs through building automation integrators and electrical wholesale channels serving commercial contractors and retail hardware chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smoke detector market sits in early-cycle expansion as NFPA 72 wireless mandates accelerate replacement of standalone units across North American jurisdictions. Smart alarm penetration in residential retrofits remains below thirty percent, creating runway for interoperability-driven upgrades.
For Market Incumbents: Compound platform stickiness through deeper integration with facility management software ecosystems. Expand in-house Notified Body relationships to compress CE marking timelines for European tenders. Counter emerging specialist entrants by locking multi-year service contracts with large-scale commercial landlords.
For New Entrants and Emerging Players: Differentiate on Matter protocol-native architectures that eliminate ecosystem fragmentation for DIY homeowners. Target India's high-rise residential tower modernization in Mumbai and Delhi where mandatory provisions are drafting. Pursue direct-to-consumer channels with subscription monitoring overlays rather than competing for commercial integrator shelf space.
For Investors and Strategic Acquirers: GB 4715 recalibration reshapes the acquisition landscape by fragmenting supplier qualification burdens between domestic and export-facing Chinese manufacturers. Five-to-ten year viability favors targets with dual-certification capabilities spanning UL 268 and EN 54-7. Watch California and Texas municipal pilot programs for direct alarm-to-dispatch connectivity as inflection indicators for subscription revenue model validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Enables single-SKU strategies across Amazon Alexa, Google Home, and Apple HomeKit ecosystems. |
| Backward Integration into MEMS Sensors | Reduces Taiwan foundry dependency for RF chipsets in smart alarm production. |
| Emergency Dispatch Integration Partnership | Captures recurring subscription revenue through direct municipal alarm reporting pilots. |
| Multi-Criteria Sensor Miniaturization | Forty percent enclosure reduction enables concealed ceiling installations in Class A offices. |
| Regional Certification Laboratory Acquisition | Compresses vendor qualification timelines for German public-sector tenders under tightened CE marking. |
Research Approach
Initial hypotheses were tested against primary input from fire safety engineering directors, facility management procurement leads, electrical contractor operations managers, and smart home platform integration specialists and refined through secondary validation. Sources included NFPA 72 code interpretation documents, UL 268 Edition 7 testing protocols, EN 54-7 amendment filings, and building permit databases across California, Texas, and Germany. Bottom-up unit shipment modeling triangulated against top-down construction spending allocation by building type.
Variance decomposition across product type, technology tier, application vertical, and end-user procurement authority shaped the analytical framework over the projection horizon. CAGRs derived from segment-level penetration curves calibrated to regulatory deadline schedules and retrofit cycle assumptions. Industry-specific inputs incorporated electrician labor availability constraints in Dallas-Fort Worth and Phoenix, plus GB 4715 testing protocol divergence effects on Chinese manufacturer export capacity.
The analysis sits within stated boundaries; outcomes outside sustained NFPA 72 jurisdiction enforcement or accelerated Matter protocol adoption would require recalibration. Forecasts reflect assumptions on wireless chipset supply normalization and municipal dispatch integration pilot scalability. Recalibration cycles align with material shifts in building code amendment schedules and semiconductor foundry capacity allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Firefighting Hose Market
Fire Safety & Protection
Australia Emergency Lighting Market
Fire Safety & Protection
Fire and Rescue Helmets Market
Fire Safety & Protection
United States Fire Sprinklers Market
Fire Safety & Protection
Europe Passive Fire Protection Market
Fire Safety & Protection
US Fire Safety Equipment Market
Fire Safety & Protection
North America Fire Extinguisher Market
Fire Safety & Protection
Fire Protection Systems Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Smoke Pressure System Market
Fire Safety & Protection
Fire Fighting Foam Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
Global Flame Detector Market
Fire Safety & Protection
Fire Suppression Market
Fire Safety & Protection
Global Fixed Firefighting Misting System Market