
 Smart Barrier Gate Market | 2026-2036
Smart Barrier Gate Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Barrier Gate Market Insights
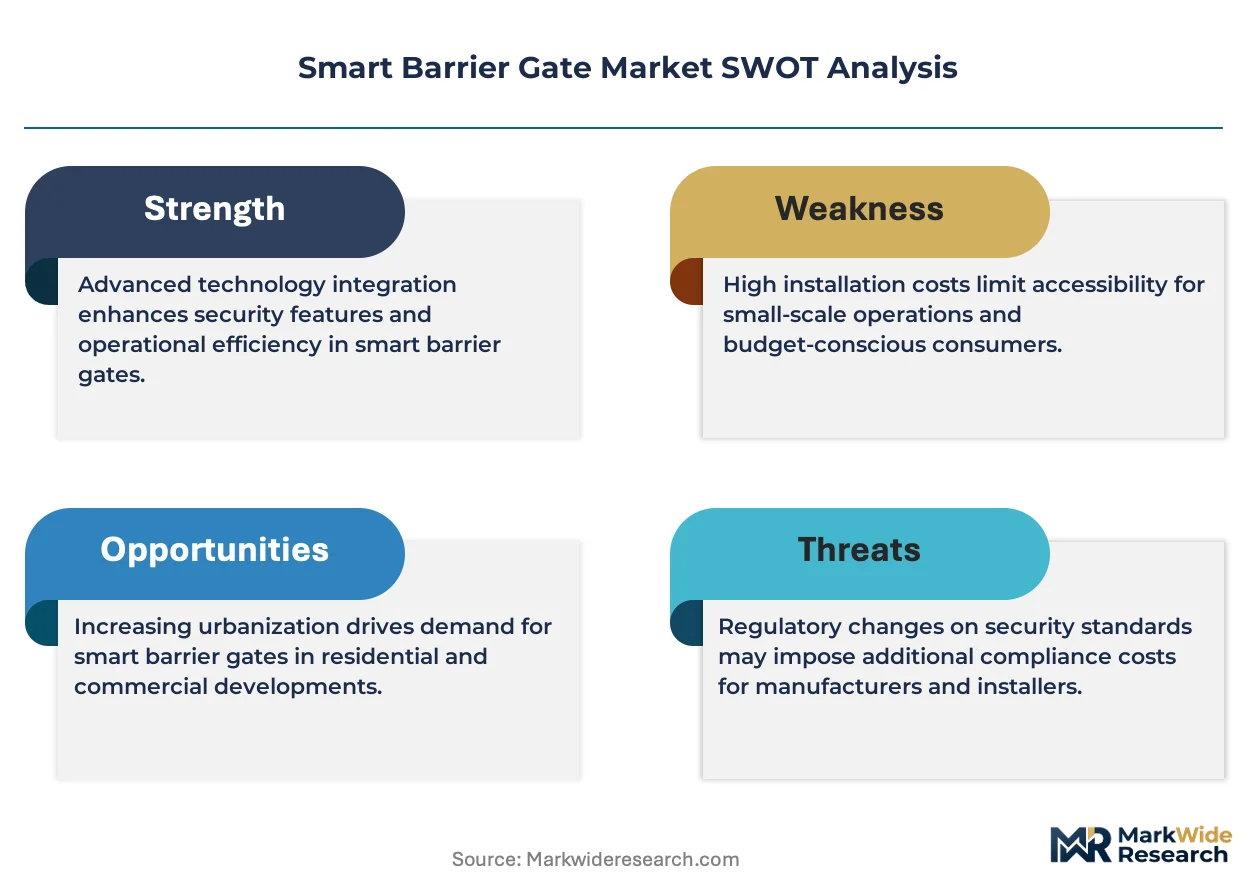
The capital-intensity divergence between electromechanical specialists and hydraulic legacy players is unwinding competitive stability across the smart barrier gate landscape. FAAC leverages its Italian manufacturing base to sustain integrated servo-motor production lines that reduce third-party dependency. Bft Automation anchors its position through deep R&D investment in brushless DC motor platforms. Came competes aggressively on price in Southern European municipal contracts while maintaining certification breadth.
A smart barrier gate constitutes an electromechanical access control apparatus typically spanning three to six meters in boom length, deploying torque motors rated between 80 and 300 Newton-meters to regulate vehicular entry at speeds from two to six seconds per open cycle. Its primary commercial purpose centers on credential-verified throughput management across high-frequency traffic nodes. Automatic barrier systems lead volume deployment due to their compatibility with existing loop detector infrastructure, while RFID-based barriers capture expanding share in commercial buildings where fleet credentialing demands non-stop passage. Camera-based systems and license plate recognition technology concentrate margin pools through software recurring revenue attachments.
F-Gas Regulation in Europe and CE marking under the Machinery Directive shape product design mandates, forcing hydraulic fluid elimination and mandating fail-safe electromechanical architectures with redundant position sensors. The US NHTSA and FAA issue facility security directives that determine barrier crash-rating requirements for federal installations and airport perimeters. Stakeholders must monitor evolving cybersecurity standards for IoT-enabled mobile app integration as credential spoofing risks migrate from physical token theft to digital channel exploitation.
Market Dynamics
Electromechanical actuation is decomposing the hydraulic legacy installed base across European and North American traffic infrastructure, as F-Gas Regulation mandates and NHTSA security directives force hardware replacement cycles at airports, industrial sites, and municipal parking systems.
Growth Catalysts
- Airport perimeter hardening:FAA facility security directives mandate crash-rated barriers at federal aviation installations, driving specification upgrades across US commercial airport networks.
- CE marking under Machinery Directive:Fail-safe electromechanical architectures with redundant position sensors are now compulsory for European market access, eliminating hydraulic fluid systems from new tenders.
- Brushless DC motor platforms:Italian and German automation specialists have achieved cost parity with hydraulic alternatives, accelerating replacement demand in high-cycle commercial parking applications.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium dependency on Chinese processing infrastructure exposes servo-motor manufacturers to input cost volatility and export restriction risk.
- Electromechanical torque limitations:Current brushless DC platforms top out below 400 Newton-meters, constraining deployment at heavy-industry sites requiring six-meter boom spans with high wind-loading.
- Cybersecurity compliance friction:IoT-enabled mobile credentialing introduces GDPR and state-level data protection audit burdens that extend sales cycles by 4-8 months for cloud-connected barrier systems.
Strategic Opportunities
- Indian smart city integration:Municipal parking automation tenders under the Ministry of Housing and Urban Affairs are specifying RFID-integrated barriers for congestion pricing pilots in Bengaluru, Mumbai, and Delhi.
- License plate recognition convergence:Camera-based barriers fused with edge-AI video analytics are capturing margin pools through software recurring revenue attachments in commercial building fleet management.
- US Infrastructure Investment and Jobs Act:Federal transit security grants are funding automated access control upgrades at bus depots, rail yards, and port terminals, creating specification pathways for crash-rated electromechanical systems.
Industry Challenges
- Mechatronics talent scarcity:Servo-motor calibration and redundant sensor integration require specialized firmware engineers that barrier OEMs struggle to recruit outside Stuttgart, Turin, and Detroit metropolitan clusters.
- Legacy loop detector incompatibility:Electromechanical barrier controllers often conflict with 1980s-era inductive loop infrastructure, forcing costly trenching and cable replacement at retrofit sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Barrier Gate Market |
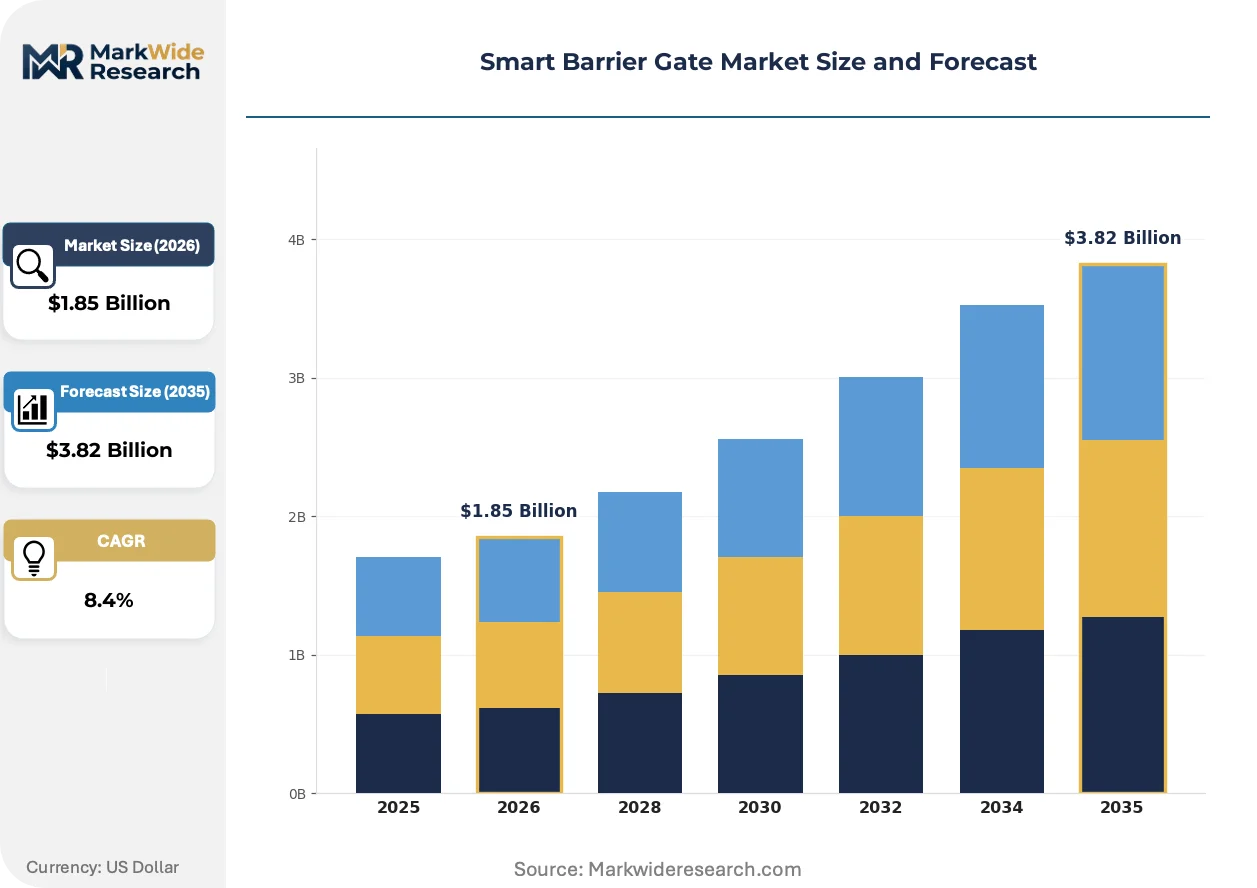
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Barrier, Automatic Barrier, Vehicle-Activated Barrier, RFID-Based Barrier Technology: Infrared Sensors, Camera-based Systems, License Plate Recognition, Mobile App Integration End User: Commercial Buildings, Residential Complexes, Airports, Industrial Sites Installation Type: Fixed Installation, Portable Installation, Semi-permanent Installation, Integrated Systems |
| Companies Covered | FAAC, Bft Automation, Came, Parklio, AGSI, Parking BOXX, Smart Access Solutions, Avon Barrier, SystemHUB Distribution Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Barrier Gate Market Trends and Innovations
Hardware-software decoupling is redefining value capture in access control, as electromechanical platforms become commoditized vessels for credentialing software, video analytics, and predictive maintenance subscriptions.
Servo-driven barrier mechanisms are decomposing the traditional bundled product-service model. These systems convert electrical input to precise torque output through closed-loop position feedback, eliminating hydraulic fluid maintenance. Airport authorities and commercial parking operators in Germany and the Netherlands are specifying them for 24/7 duty cycles exceeding 5,000 operations daily. The technology is decomposing aftermarket service revenue pools by enabling remote diagnostics and predictive component replacement via IoT connectivity.
European F-Gas Regulation is accelerating hydraulic phase-out across industrial access applications. The framework bans fluorinated greenhouse gases in stationary equipment, classifying hydraulic fluids with high global warming potential as restricted substances. German industrial site operators and French municipal parking authorities are responding by specifying electromechanical alternatives with IP65 environmental sealing and integrated heating elements for cold-climate reliability.
Fleet credentialing demands are compressing barrier procurement evaluation criteria. Commercial building operators and logistics park developers now prioritize non-stop passage capability over capital cost, favoring RFID and license plate recognition integration over ticket-dispensing automatic barriers. This behavioral shift is most visible in Dutch distribution hub clusters and Singaporean commercial precincts, where throughput metrics dominate technical specifications.
Smart Barrier Gate Market Segmentation
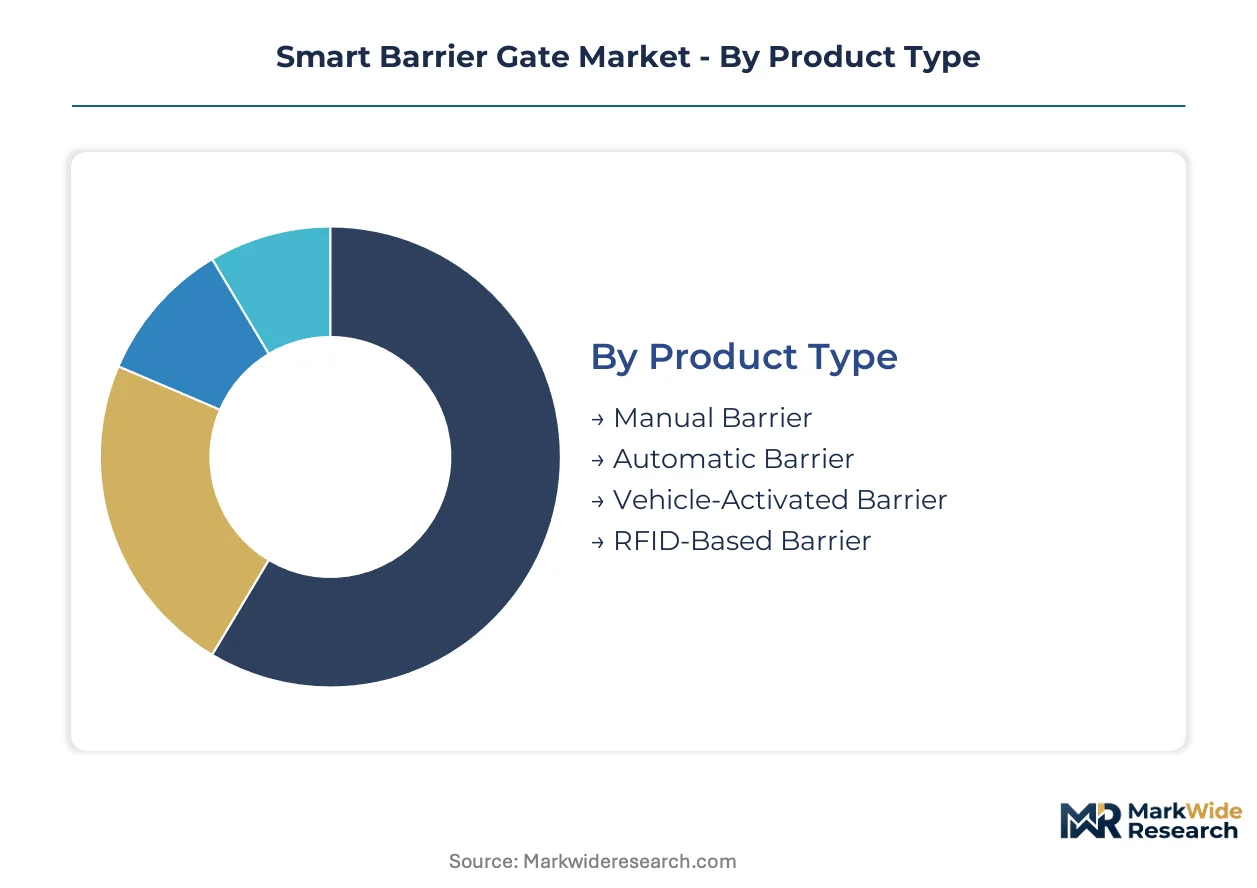
Segmentation in smart barrier gates reveals where hardware commoditization ends and software value capture begins. Product architecture choices determine compatibility with legacy traffic infrastructure, while technology integration depth separates price-competitive municipal tenders from high-margin commercial deployments.
Product Type:
Margin pools concentrate in systems that minimize manual intervention and maximize credentialing flexibility. Automatic barriers dominate volume, but RFID-based variants command premium positioning through fleet management software attachments.
- Manual Barrier:Spring-assisted or counterweighted boom mechanisms requiring physical operator engagement. Demand persists at rural industrial sites in Germany and temporary construction perimeters where electrical infrastructure is unavailable.
- Automatic Barrier:Loop-detector or push-button actuated systems with electromechanical torque motors rated 80-300 Newton-meters. These systems capture the bulk of municipal parking automation in the Netherlands and commercial building deployments across Singapore.
- Vehicle-Activated Barrier:Inductive loop or pressure sensor triggers eliminating manual credential presentation. Logistics parks in the US and distribution hubs in India specify these for high-frequency truck throughput.
- RFID-Based Barrier:Long-range credential readers enabling non-stop passage at 15-25 km/h. Commercial building operators in Dubai and corporate campuses in Switzerland prioritize these for executive fleet management and subscription revenue integration.
Automatic barriers hold installed capacity. RFID-based barriers are rotating up the share rankings.
Technology:
Technology layering determines recurring revenue potential and cybersecurity audit exposure. Camera-based systems and license plate recognition concentrate margin through software subscriptions, while infrared sensors remain cost-optimized hardware plays.
- Infrared Sensors:Photoelectric beam interruption detectors for vehicle presence verification. These sensors dominate budget-conscious municipal tenders in India and retrofit applications where camera infrastructure is uneconomical.
- Camera-based Systems:Edge-computing video analytics with AI-powered object classification. German airport authorities and Dutch commercial parking operators specify these for predictive maintenance and remote diagnostics integration.
- License Plate Recognition:Optical character recognition engines with 95%+ accuracy under variable lighting. Revenue concentrates in congestion pricing pilots in London and Stockholm, where software-as-a-service billing models attach to hardware deployments.
- Mobile App Integration:Bluetooth Low Energy or NFC credentialing with cloud-based access logging. US commercial building operators and Singaporean residential complexes face 4-8 month sales cycle extensions due to GDPR and state-level data protection compliance friction.
Camera-based systems anchor premium positioning. License plate recognition is climbing the fastest.
End User:
End-use concentration tracks infrastructure investment cycles and regulatory security mandates. Airports and industrial sites drive specification upgrades, while residential applications compete on capital cost minimization.
- Commercial Buildings:Office towers and retail complexes prioritizing throughput metrics over upfront expenditure. Dutch distribution hub clusters and Singaporean commercial precincts specify RFID and license plate recognition for fleet credentialing dominance.
- Residential Complexes:Gated communities and multi-unit dwellings with moderate cycle frequency requirements. These deployments concentrate in Indian smart city pilots under the Ministry of Housing and Urban Affairs, where cost sensitivity favors automatic barriers over integrated credentialing.
- Airports:FAA facility security directives mandate crash-rated barriers at federal aviation installations. US commercial airport networks and German regional airports specify electromechanical systems with redundant position sensors for 24/7 perimeter hardening.
- Industrial Sites:Manufacturing plants and logistics yards requiring IP65 sealing and cold-climate reliability. French municipal parking authorities and German industrial operators respond to F-Gas Regulation by eliminating hydraulic fluid systems from new tenders.
Industrial sites retain specification authority. Airports are expanding most quickly.
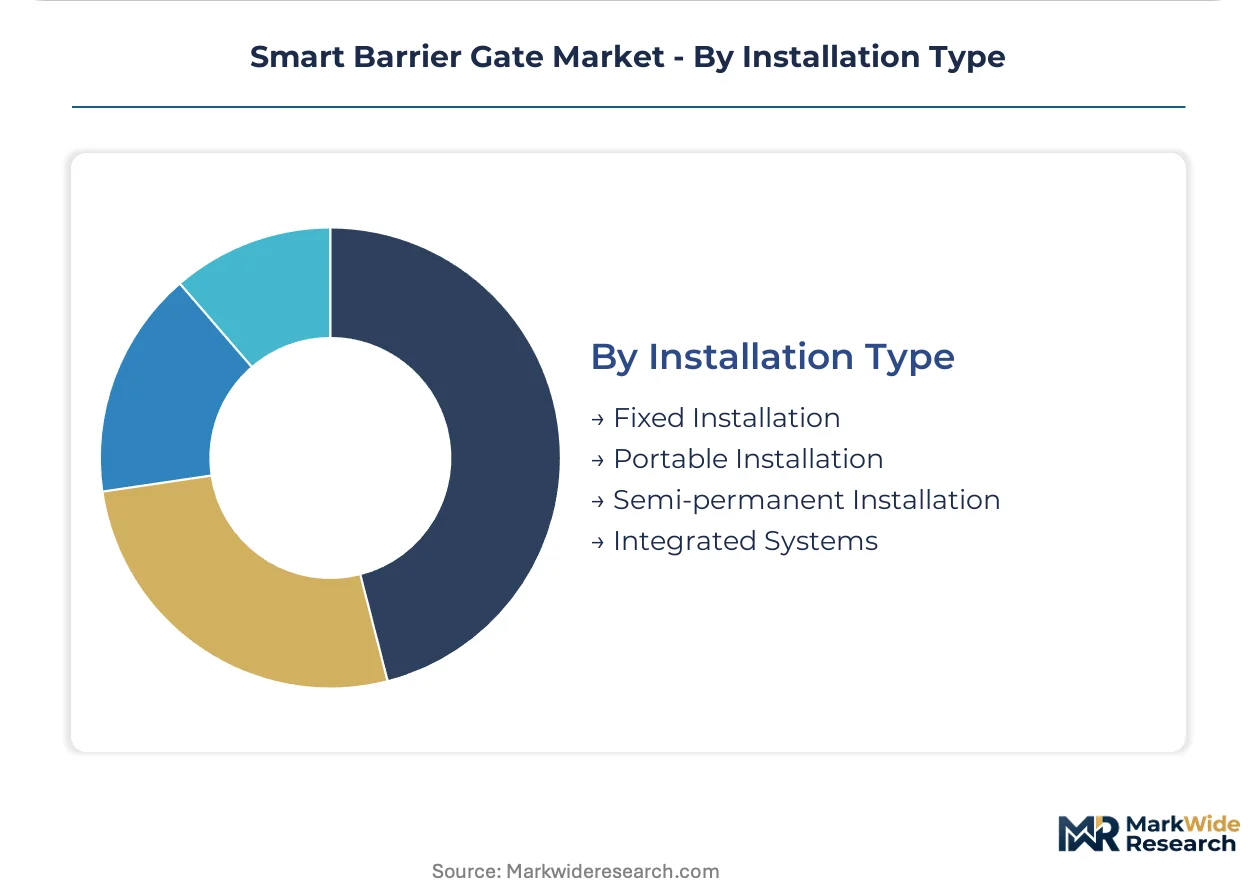
Installation Type:
Installation flexibility determines addressable market breadth and service revenue durability. Fixed installations anchor replacement cycles, while portable and semi-permanent variants capture temporary event and construction demand.
- Fixed Installation:Permanent foundation-mounted barriers with embedded electrical and network infrastructure. These systems dominate airport perimeters in the US and industrial site automation in Germany, where 15-20 year asset lifecycles justify trenching investment.
- Portable Installation:Battery-powered or solar-charged units with rapid deployment capability. Event management operators in the UK and temporary construction site managers in Australia specify these for 30-90 day deployment windows.
- Semi-permanent Installation:Surface-mounted barriers with removable anchoring for seasonal or project-based use. Municipal parking authorities in France and festival organizers in Belgium utilize these for flexible congestion management.
- Integrated Systems:Barrier hardware fused with access control software, video management, and building management system connectivity. US federal transit security grants under the Infrastructure Investment and Jobs Act fund these at bus depots and rail yards.
Fixed installation maintains deployment volume. Integrated systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers command pricing premiums through CE-certified electromechanical platforms, while Indian municipal tenders compress margins through volume-focused RFID specifications. This asymmetry shapes procurement patterns across high-specification and cost-optimized deployment zones.
United States
FAA facility security directives mandate crash-rated barriers at federal aviation installations, driving specification upgrades across commercial airport networks. NHTSA issues facility hardening guidelines that determine barrier performance standards for federal infrastructure. Dallas-Fort Worth and Atlanta airport authorities are replacing legacy hydraulic systems with electromechanical alternatives featuring redundant position sensors.
Germany
Industrial site automation and smart city parking integration are accelerating replacement cycles in manufacturing heartlands. F-Gas Regulation bans fluorinated greenhouse gases in stationary equipment, eliminating hydraulic fluid systems from new tenders. Stuttgart and Munich metropolitan clusters concentrate demand for IP65-sealed barriers with integrated heating elements for cold-climate reliability.
Netherlands
Distribution hub operators prioritize throughput metrics over capital cost, favoring RFID and license plate recognition for fleet credentialing. CE marking under the Machinery Directive mandates fail-safe electromechanical architectures for market access. Rotterdam port terminals and Eindhoven logistics parks specify servo-driven mechanisms for 24/7 duty cycles exceeding 5,000 operations daily.
India
Municipal parking automation tenders under the Ministry of Housing and Urban Affairs are specifying RFID-integrated barriers for congestion pricing pilots. BIS certification requirements shape product compliance for electromechanical imports. Bengaluru, Mumbai, and Delhi smart city programs concentrate demand for cost-optimized automatic barriers over integrated credentialing systems.
Singapore
Commercial building operators and residential complexes face extended sales cycles due to data protection compliance friction for IoT-enabled mobile credentialing. The country's national cybersecurity agency issues guidelines for connected infrastructure that extend procurement timelines. Marina Bay financial district and Changi business park developments specify camera-based barriers with edge-AI video analytics for predictive maintenance integration.
Smart Barrier Gate Market Competitive Landscape
Concentration sits with Italian and German electromechanical specialists who control integrated servo-motor production. The vendor base stratifies across three tiers: premium CE-certified platforms, mid-range RFID-integrated systems, and price-competitive automatic barriers. Strategic archetypes include integrated manufacturers with captive motor production, software-anchored platform providers, and regional fabricators serving municipal tenders. Dominant competitive moves center on backward integration into rare earth magnet supply chains and technology licensing partnerships for license plate recognition engines.
Within the integrated manufacturing tier, FAAC leverages its Italian base to sustain production lines that reduce third-party dependency. Bft Automation anchors its position through investment in brushless DC motor platforms. Came occupies a position in Southern European municipal contracts while maintaining certification breadth for cross-border tenders.
| Leading Market Players |
|---|
| FAAC |
| Bft Automation |
| Came |
| Parklio |
| AGSI |
| Parking BOXX |
| Smart Access Solutions |
| Avon Barrier |
| SystemHUB Distribution Inc. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Italian and German servo-motor manufacturing clusters shapes both supply concentration and price floors for electromechanical barrier platforms. CE marking compliance costs and rare earth magnet input volatility propagate through tiered pricing structures, compressing margins at volume-focused municipal tenders while sustaining premiums at airport and industrial specifications.
Pricing Analysis
The customization-premium spread separates configured-to-order CE-certified platforms from standard automatic barrier SKUs. Three-tier pricing structure across premium, standard, and economy levels dominates: premium tiers attach predictive maintenance subscriptions and redundant sensor architectures for FAA-mandated airport deployments; standard tiers serve Dutch commercial parking operators with RFID integration; economy tiers supply Indian smart city tenders with basic loop-detector compatibility. Cost compression in economy tiers is intensifying because Chinese rare earth processing export restrictions elevate servo-motor input costs. Municipal procurement teams in India exhibit highest price sensitivity; German industrial site operators demonstrate lowest sensitivity due to F-Gas Regulation compliance deadlines.
Supply Chain Analysis
China and Germany anchor rare earth magnet processing and precision servo-motor manufacturing respectively. Neodymium and dysprosium feedstock draws from Chinese separation and refining infrastructure; German OEMs in Stuttgart and Munich metropolitan clusters perform final motor assembly and firmware integration. Single-source vulnerability concentrates in Chinese rare earth export licensing. Distribution runs through barrier OEM direct sales for airport and industrial accounts; municipal tenders route through regional systems integrators and parking infrastructure specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart barrier gate market functions as a service-attach opportunity where predictive maintenance subscriptions and license plate recognition software tiers expand faster than hardware replacement cycles. Recurring revenue from edge-AI video analytics and cloud credentialing platforms now determines vendor valuation multiples.
For Market Incumbents: Shield installed base relationships by embedding IoT connectivity before third-party software providers capture the diagnostics layer. CE marking renewal investments and captive rare earth magnet inventory buffers defend against Chinese export restriction risk. Backward integration into brushless DC motor production preserves margin control as electromechanical platforms commoditize.
For New Entrants and Emerging Players: CE certification fast-track through Machinery Directive compliance partnerships unlocks European municipal tender eligibility faster than full self-certification timelines. White-space concentrates in Indian smart city congestion pricing pilots and US Infrastructure Investment and Jobs Act transit security grants. License plate recognition software licensing from established computer vision providers accelerates time-to-revenue versus in-house AI development.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electromechanical specialists with integrated servo-motor production and software subscription attach rates above hardware-only peers. Five-to-ten year viability hinges on cybersecurity compliance capabilities for IoT-enabled credentialing. The signal to watch is GDPR enforcement intensity against cloud-connected barrier deployments extending sales cycles beyond hardware-only competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Captive neodymium sourcing insulates FAAC and Bft Automation from Chinese export volatility. |
| License Plate Recognition Engine Licensing | Camera-based barrier margins concentrate through Stockholm congestion pricing SaaS billing models. |
| Cybersecurity Certification Investment | Singapore national cybersecurity agency compliance extends procurement timelines but locks out uncertified rivals. |
| RFID Integration for Fleet Credentialing | Dutch distribution hub throughput metrics prioritize non-stop passage capability over capital cost minimization. |
| Predictive Maintenance Platform Launch | German airport 24/7 duty cycles exceeding 5,000 daily operations generate recurring diagnostics revenue. |
Research Methodology
Cross-validation between primary interviews with airport security directors, municipal parking procurement managers, industrial site maintenance engineers, and barrier OEM product strategists anchors the qualitative findings. Secondary validation draws from FAA facility security directive filings, CE marking Machinery Directive documentation, BIS certification records for Indian imports, and EIA energy infrastructure grant disclosures. Bottom-up unit deployment modeling and top-down infrastructure investment flow analysis triangulate market sizing across the analysis window.
Sensitivity analysis around rare earth magnet price volatility and cybersecurity compliance timeline scenarios shapes the analytical framework. Segmentation dimensions span product architecture (manual, automatic, RFID-based), technology integration depth (infrared, camera-based, license plate recognition, mobile app), end-use concentration (commercial buildings, residential complexes, airports, industrial sites), and installation type (fixed, portable, semi-permanent, integrated systems). CAGRs derive from replacement cycle analysis of hydraulic-to-electromechanical conversion and smart city infrastructure deployment schedules. Forecast inputs include F-Gas Regulation phase-out deadlines and Infrastructure Investment and Jobs Act transit security grant allocation patterns.
Decision-makers should treat outputs as directional under assumptions of continued CE marking enforcement and stable Chinese rare earth export policy; material deviation would warrant model refresh. Recalibration cycles align with material shifts in European regulatory stringency and US federal infrastructure appropriation levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Security Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Face Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Public Address and Voice Alarm Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Process Safety System Market
Safety Equipment and Personal Protective Equipment (PPE)
Cryogenic PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Road Flares Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Explosion Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Hazard and Safety Indicator Control Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Hazmat Suits Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Emergency Oxygen Deployment Systems Market