
 Global Emergency Notification Software Market | 2026-2036
Global Emergency Notification Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Emergency Notification Software Market Foresight
Modular bundling of crisis communication with incident management and evacuation software is pivoting buyer choice away from standalone alert tools. Everbridge leverages its integrated platform architecture to anchor enterprise contracts across corporate offices and critical infrastructure operators. Motorola Solutions competes through specialized hardware-software convergence in public safety deployments. AlertMedia differentiates with streamlined SaaS delivery targeting mid-market workplace safety buyers.
Emergency notification software comprises digital platforms that orchestrate multi-channel message dissemination—SMS, voice, email, desktop alerts, and digital signage—triggered by predefined threat thresholds or manual activation, with latency targets typically under sixty seconds from alert initiation to device receipt. Its primary commercial purpose is to minimize human casualty and operational downtime during critical events through automated population targeting and two-way status confirmation. Cloud-based deployment leads volume adoption due to elastic scalability and reduced capital burden, while hybrid architectures capture margin pools from government agencies and healthcare facilities with segmented data sovereignty requirements. Mass notification remains the mature revenue base, though incident management and risk assessment modules represent the fastest-expanding attach rates as buyers seek unified command workflows.
The EU AI Act, GDPR, and ISO 22320 framework collectively shape product standards by mandating algorithmic transparency in automated threat detection and cross-border data governance for multinational alert systems. The FCC in the United States enforces Wireless Emergency Alert technical specifications that gate market access for public safety vendors. Stakeholders must monitor convergence between cybersecurity certification requirements and emergency notification procurement specifications as attack surfaces expand across interconnected critical infrastructure networks.
Market Dynamics
Modular platform convergence is compressing procurement cycles as corporate buyers abandon standalone alert tools for integrated crisis management suites. Vendors now compete on workflow breadth rather than channel speed alone.
Growth Catalysts
- Critical Infrastructure Modernization:Government agencies in the United States, Germany, and Japan are mandating multi-channel notification systems for energy grids and transportation networks. Federal procurement budgets for resilience technology are expanding.
- GDPR Cross-Border Data Mandates:The EU AI Act and GDPR are forcing multinational corporations to consolidate vendor relationships under compliant platforms. Procurement teams now prioritize vendors with EU sovereign data architecture.
- Workplace Safety Liability Expansion:Corporate legal departments are driving adoption of two-way confirmation systems to demonstrate duty-of-care compliance. Mid-market employers represent the fastest-expanding buyer segment.
Market Restraints
- Hybrid Deployment Cost Structure:On-premise data sovereignty requirements in healthcare and defense segments inflate total cost of ownership by 40-60% versus cloud-native alternatives. Capital constraints limit mid-market penetration.
- Telecom Carrier Concentration:SMS delivery reliability depends on concentrated carrier partnerships in North America and Western Europe. Single-point failures in carrier infrastructure cascade to notification latency.
- Legacy System Integration Friction:Existing physical security and access control systems use proprietary protocols. API standardization gaps extend deployment timelines by 6-12 months for enterprise installations.
Strategic Opportunities
- India Smart City Infrastructure:The country's urban resilience initiatives are creating first-mover advantages for vendors offering localized language support and edge deployment. State-level disaster management authorities are consolidating procurement.
- AI-Generated Threat Detection:Convergence of machine learning with sensor networks is enabling predictive alert triggering before human verification. Early deployments in manufacturing and chemical processing are proving latency advantages.
- Outcome-Based Service Contracts:Corporate risk officers are negotiating performance-linked pricing tied to incident response time guarantees. This shifts vendor compensation from seat licenses to operational outcomes.
Industry Challenges
- Cybersecurity Certification Timeline:FedRAMP and ISO 27001 compliance cycles extend 14-18 months for cloud platforms. Accelerated procurement demands from federal agencies create delivery bottlenecks.
- Interoperability Standard Fragmentation:The absence of unified protocols between competing mass notification systems forces buyers into single-vendor lock-in. Industry working groups under OASIS and NIST are progressing slowly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Emergency Notification Software Market |
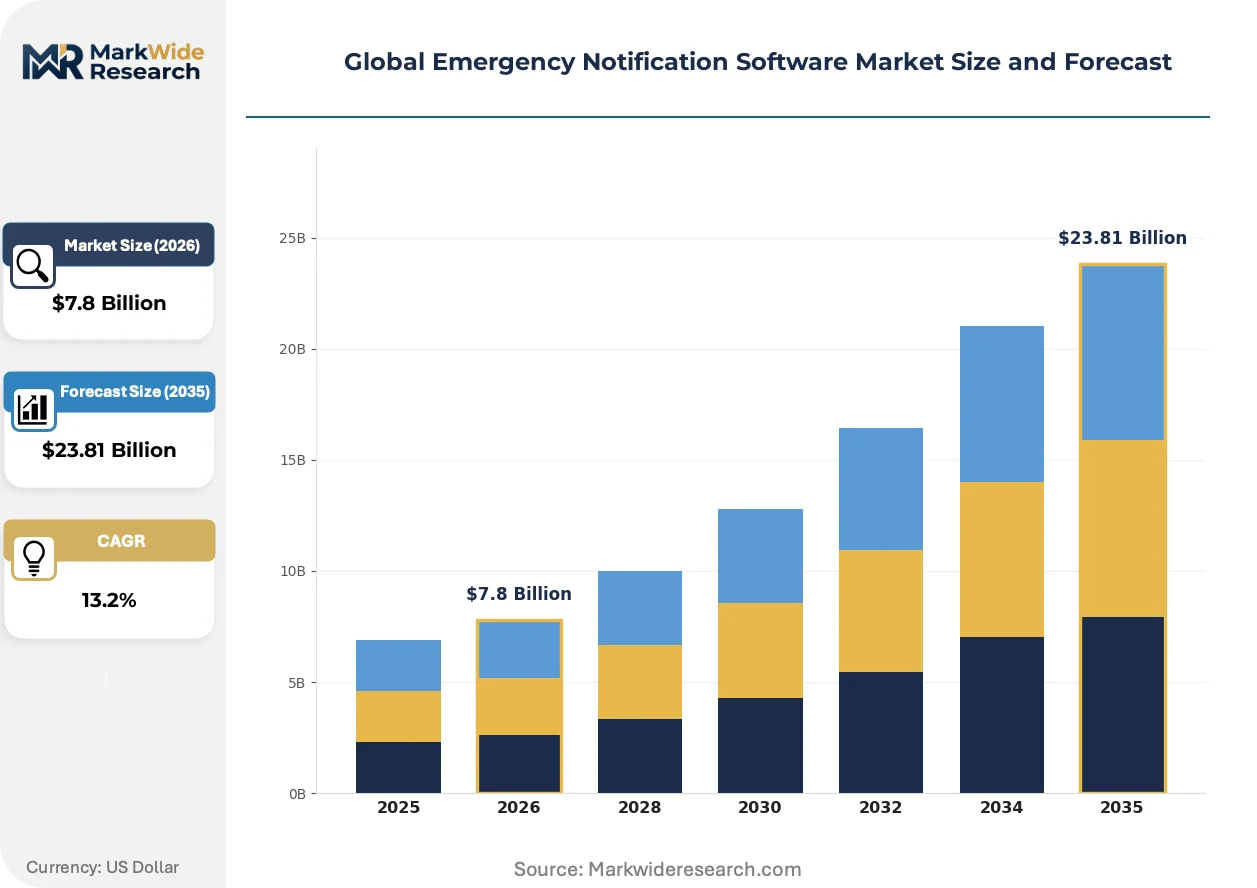
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $23.81 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution/Offering: Mass Notification, Incident Management, Crisis Communication, Alert Systems, Evacuation Software, Risk Assessment Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Hosted, Managed Services Application: Natural Disaster Response, Workplace Safety, Public Safety, Campus Security, Transportation Alerts, Event Management End User: Government Agencies, Educational Institutions, Corporate Offices, Emergency Service Providers, Healthcare Facilities, Critical Infrastructure Operators |
| Companies Covered | Everbridge, OnSolve, Honeywell International, Motorola Solutions, AlertMedia, Singlewire Software, BlackBerry AtHoc, Siemens AG, Alertus Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Emergency Notification Software Market Shifts & Advancements
Artificial intelligence is embedding into threat detection workflows, compressing the interval between anomaly identification and population alert. Platform vendors are racing to integrate predictive capabilities before regulatory mandates crystallize.
Unified command software is unifying incident management, mass notification, and evacuation planning into single-pane workflows. Corporate security operations centers in the United States and Germany are adopting these suites at accelerating pace. The technology is unifying procurement decisions around platform breadth rather than point-solution performance.
The EU AI Act is mandating algorithmic transparency documentation for automated threat classification systems. Vendors must now maintain audit trails explaining why specific alerts triggered. European critical infrastructure operators are responding by demanding explainable AI modules in procurement specifications, compressing competitive advantage for black-box detection systems.
Buyer committees are consolidating vendor relationships to reduce cybersecurity audit burden. Fortune 500 risk officers are replacing fragmented point solutions with enterprise-wide platform contracts. This concentration is most visible in United States healthcare systems, where CISOs are eliminating redundant notification tools to streamline HIPAA compliance documentation.
Global Emergency Notification Software Market Segmentation
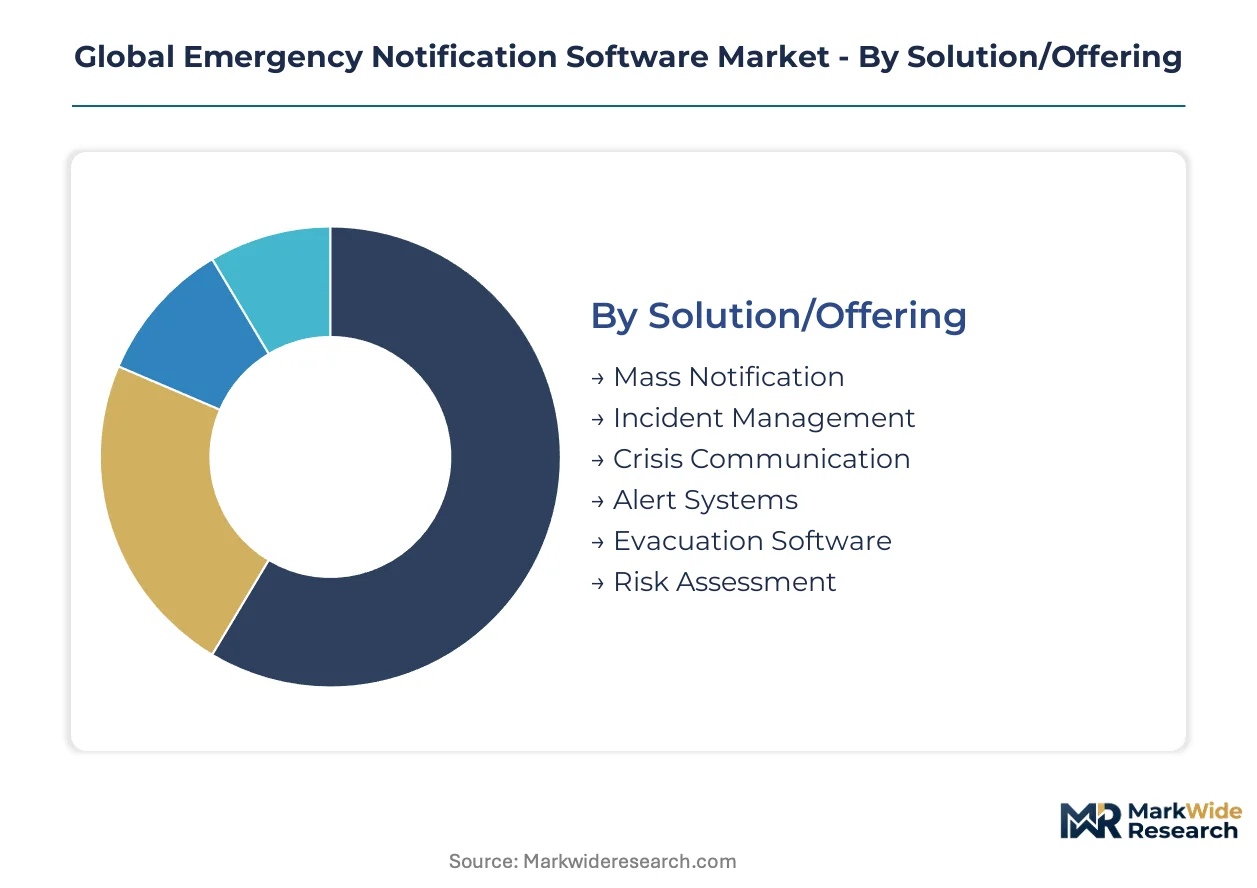
Emergency notification software vendors structure product portfolios around deployment flexibility and integration depth. Buyer procurement committees evaluate segments through the lens of regulatory compliance, legacy system compatibility, and total cost of ownership across multi-year contracts.
Solution/Offering:
Corporate risk officers prioritize workflow breadth over point-solution performance when selecting crisis communication platforms.
- Mass Notification:Core functionality orchestrates multi-channel message dissemination across SMS, voice, email, and digital signage with sub-sixty-second latency targets. United States federal agencies and German critical infrastructure operators anchor demand through mandates for population-wide alert capabilities.
- Incident Management:Unified command modules integrate threat assessment, resource dispatch, and status tracking into single-pane workflows. Corporate security operations centers in the United States and Germany are consolidating procurement around these suites to reduce vendor fragmentation.
- Crisis Communication:Two-way confirmation systems enable duty-of-care documentation for workplace safety liability compliance.
- Alert Systems:Automated triggering mechanisms connect sensor networks to population notification without human intervention.
- Evacuation Software:Route optimization and assembly point coordination modules attach to broader platform contracts.
- Risk Assessment:Predictive analytics layers are gaining procurement traction in manufacturing and chemical processing environments.
Mass notification leads on scale; incident management leads on momentum.
Deployment:
Data sovereignty requirements and capital availability split buyer preferences across architecture types.
- Cloud-Based:Elastic scalability and reduced upfront capital burden dominate mid-market corporate adoption. GDPR cross-border data mandates are forcing European multinational corporations to scrutinize vendor data residency architectures more intensively.
- Hybrid:Segmented architectures satisfy healthcare and defense sector requirements for on-premise sensitive data processing. Japanese government agencies and United States healthcare facilities pay 40-60% total cost of ownership premiums for sovereignty compliance.
- On-Premise:Complete data control for classified environments and air-gapped critical infrastructure networks.
- SaaS:Subscription pricing aligns vendor compensation with operational outcomes rather than perpetual licenses.
- Hosted:Dedicated single-tenant infrastructure addresses multi-tenant security concerns without full on-premise burden.
- Managed Services:Outsourced alert operations and 24/7 monitoring for organizations lacking internal security operations center capacity.
Cloud-based deployment captures volume leadership; hybrid architectures command margin premiums.
Application:
Regulatory mandates and liability exposure create divergent procurement urgency across use cases.
- Workplace Safety:Two-way confirmation systems demonstrate duty-of-care compliance for corporate legal departments. Mid-market employers in the United States represent the steepest expansion trajectory as liability frameworks tighten.
- Public Safety:FCC Wireless Emergency Alert specifications and EENA 112 standards gate market access for government-facing vendors. Municipal and federal procurement budgets in the United States and Germany are expanding for resilience technology.
- Natural Disaster Response:Seismic, flood, and wildfire early warning integration with automated population targeting.
- Campus Security:K-12 and higher education institutions consolidate notification with access control and video management systems.
- Transportation Alerts:Aviation, rail, and maritime operators require specialized integration with operational technology networks.
- Event Management:Temporary crowd safety for sports, entertainment, and convention venues with rapid deployment requirements.
Public safety anchors procurement scale; workplace safety is climbing the fastest.
End User:
Budget authority and compliance complexity determine segment attractiveness for vendor sales organizations.
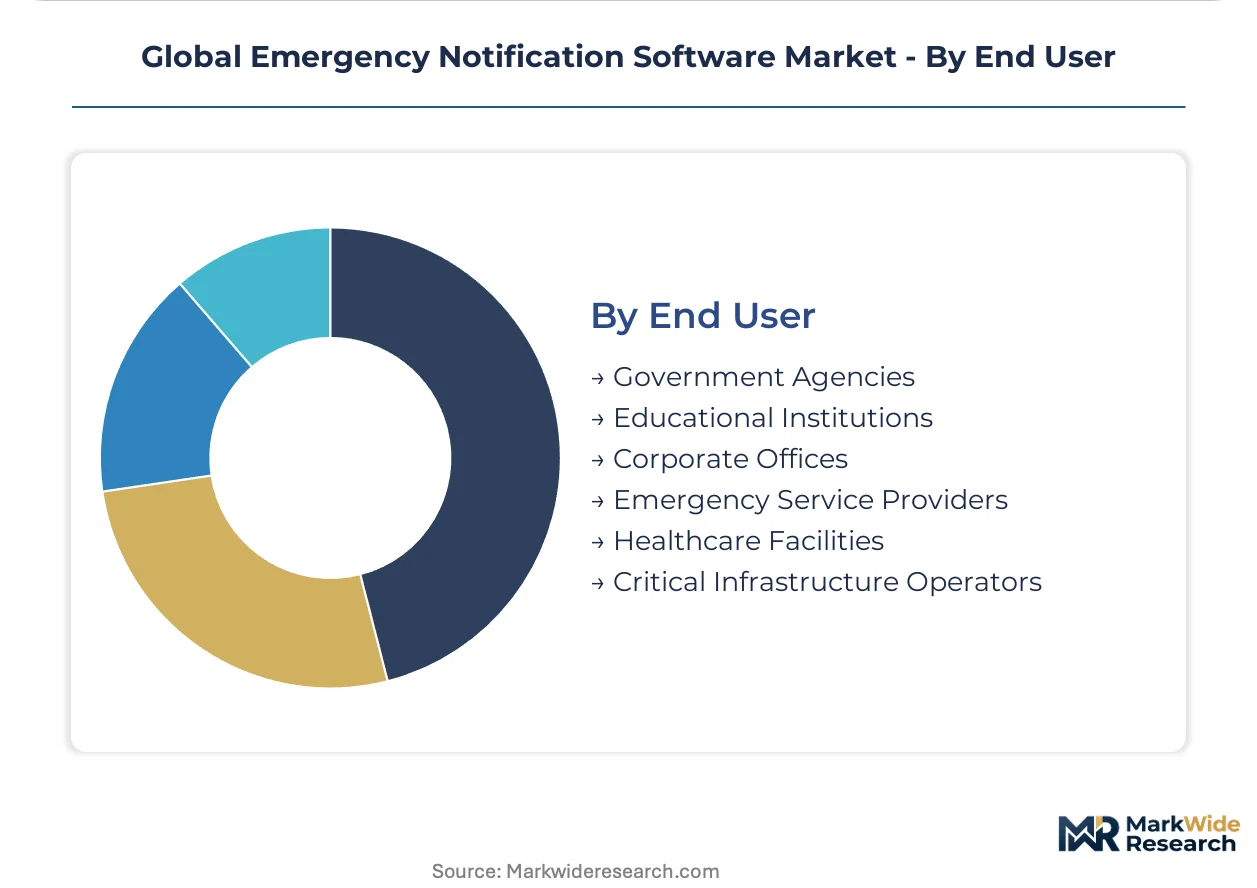
- Corporate Offices:Fortune 500 risk officers are eliminating fragmented point solutions for enterprise-wide platform contracts. Healthcare system CISOs in the United States prioritize HIPAA compliance documentation streamlining.
- Government Agencies:Critical infrastructure modernization mandates in the United States, Germany, and Japan are expanding federal procurement for energy grid and transportation network protection.
- Educational Institutions:Campus-wide safety integration spanning emergency notification, access control, and mental health intervention systems.
- Emergency Service Providers:Fire, police, and ambulance dispatch coordination with cross-jurisdictional interoperability requirements.
- Healthcare Facilities:Patient, staff, and visitor notification with stringent data protection and uptime requirements.
- Critical Infrastructure Operators:Energy, water, and telecommunications providers facing NERC CIP and sector-specific resilience mandates.
Government agencies dominate contract value; corporate offices are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The emergency notification software industry traces its commercial origins to post-9/11 homeland security investments in the United States, where federal mandates for population-wide alert systems first established scalable multi-channel dissemination architectures that later diffused to allied nations.
United States
Federal procurement for critical infrastructure protection drives enterprise-scale deployments across energy grids and transportation networks. The FCC enforces Wireless Emergency Alert technical specifications that gate vendor participation in public safety markets. Corporate security operations centers in Texas and California anchor the fastest-growing segment for unified command platforms that integrate incident management with mass notification.
Germany
Critical infrastructure operators modernize resilience frameworks under national cybersecurity directives for energy and water utilities. The EU AI Act and GDPR mandate algorithmic transparency in automated threat detection systems, reshaping procurement criteria toward explainable AI modules. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate demand from manufacturing and chemical processing facilities deploying predictive alert triggering.
Japan
Government agencies prioritize segmented data sovereignty architectures for defense and healthcare applications, accepting 40-60% total cost of ownership premiums over cloud-native alternatives. METI coordinates national resilience technology standards for earthquake and tsunami early warning integration. Tokyo and Osaka metropolitan authorities consolidate procurement for smart city emergency response coordination.
India
State-level disaster management authorities are consolidating vendor relationships under urban resilience initiatives for smart city infrastructure. The country's national telecommunications regulator mandates localized language support for population-scale alert systems. Mumbai and Bangalore represent first-mover concentrations for edge deployment configurations serving multilingual metropolitan populations.
United Kingdom
Corporate risk officers in financial services and healthcare sectors drive consolidation from fragmented point solutions toward enterprise-wide platform contracts. National data protection frameworks align with GDPR cross-border governance requirements for multinational alert system operations. London and Southeast England concentrate demand from Fortune 500 European headquarters streamlining cybersecurity audit burdens.
Global Emergency Notification Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integration depth and workflow breadth. The market structure divides between consolidated enterprise platform vendors and specialized point-solution providers serving mid-market niches. Three archetypes dominate: integrated crisis management suites, hardware-software convergence specialists, and streamlined SaaS delivery platforms. Competitive dynamics center on strategic partnerships for carrier infrastructure access and portfolio diversification into predictive analytics modules.
Within the integrated platform tier, Everbridge and Motorola Solutions exemplify contrasting geographic and architectural positioning. AlertMedia occupies a position within the streamlined delivery archetype targeting mid-market workplace safety procurement. These three anchors represent the spectrum from enterprise-wide contract consolidation to specialized SaaS deployment, each sitting within distinct buyer committee evaluation frameworks based on regulatory complexity and legacy system integration requirements.
| Leading Market Players |
|---|
| Everbridge |
| OnSolve |
| Honeywell International |
| Motorola Solutions |
| AlertMedia |
| Singlewire Software |
| BlackBerry AtHoc |
| Siemens AG |
| Alertus Technologies |
| Others |
Supply & Pricing Matrix
Horizontal integration into carrier infrastructure partnerships anchors supply positioning and pricing power for emergency notification vendors. Cloud-native platforms leverage elastic compute contracts to compress delivery costs, while hybrid architectures tether to sovereign data center investments that inflate total cost of ownership by 40-60% for healthcare and defense buyers.
Pricing Analysis
Subscription-based SaaS tiers dominate vendor compensation structures across the emergency notification software landscape. Price differentiation rests on integration complexity and GDPR compliance certification tiers, with enterprise-wide platform contracts commanding premiums over standalone alert tools. Cost compression in mid-market segments intensifies as AlertMedia and comparable streamlined providers compete on seat-license economics. Corporate risk officers at Fortune 500 healthcare systems demonstrate lowest price sensitivity due to HIPAA documentation streamlining imperatives, while state-level disaster management authorities in India and emerging markets exhibit highest sensitivity to upfront capital burden.
Supply Chain Analysis
Regional distribution centers for cloud infrastructure concentrate in the United States, Germany, and Japan to satisfy data sovereignty mandates. The vendor ecosystem draws from hyperscaler compute resources, telecom carrier SMS gateways, and edge deployment hardware for seismic and sensor network integration. Single-source vulnerability runs through concentrated North American and Western European carrier partnerships, where infrastructure failures cascade to notification latency. Distribution runs through direct enterprise sales organizations for unified command platforms and channel partner networks for mid-market SaaS delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The emergency notification software market functions as a regulatory compounder where the EU AI Act's algorithmic transparency mandates are accelerating procurement cycles for explainable AI modules.
For Market Incumbents: Deploy FedRAMP certification investments as a competitive moat against emerging cloud-native entrants. Motorola Solutions and Everbridge should deepen carrier infrastructure exclusivity agreements to defend SMS delivery reliability advantages. Consolidation of fragmented point-solution vendors into unified platform architectures addresses buyer committee demands for streamlined cybersecurity audit documentation. For New Entrants and Emerging Players: Telecom carrier partnerships in India offer first-mover positioning before state-level disaster management authorities complete vendor consolidation. Target mid-market workplace safety procurement in United States healthcare systems where HIPAA compliance documentation requirements favor specialized SaaS delivery over enterprise platform complexity. Edge deployment configurations with localized language support unlock smart city infrastructure contracts in Mumbai and Bangalore metropolitan authorities. For Investors and Strategic Acquirers: Consolidation pressure builds where vendor fragmentation forces Fortune 500 risk officers to maintain redundant notification tools for cybersecurity compliance. Long-term viability favors integrated crisis management suites with predictive analytics attach rates over standalone alert specialists. The signal to watch is outcome-based contract penetration, where performance-linked pricing tied to incident response guarantees shifts vendor compensation from seat licenses to operational results.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies incident management, mass notification, and evacuation planning into single-pane workflows for corporate security operations centers. |
| Strategic Partnership | Secures exclusive carrier infrastructure access to defend SMS delivery reliability against telecom concentration risks. |
| Acquisition of Specialist Firm | Captures predictive analytics capabilities for AI-generated threat detection in manufacturing and chemical processing environments. |
| Geographic Expansion | Establishes edge deployment configurations with localized language support for India smart city infrastructure procurement. |
| Product Launch | Introduces explainable AI modules satisfying EU AI Act algorithmic transparency mandates for European critical infrastructure operators. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each regional cluster. The research combines structured interviews with corporate risk officers, CISOs at healthcare systems, government procurement officials, and platform engineering leads with secondary validation through FCC enforcement documentation, EU AI Act regulatory filings, and METI resilience technology standards. SEC 10-K disclosures from publicly traded vendors, hyperscaler capex reports, and trade data on telecom infrastructure investment support bottom-up and top-down triangulation across deployment models and end-user segments.
Rate-of-change decomposition separates volume expansion from pricing trajectory across the analysis window. The analytical framework models segmentation dimensions including deployment architecture, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derive from installed base growth assumptions, attach rate projections for incident management and risk assessment modules, and replacement cycle dynamics for legacy standalone alert systems. Forecast inputs incorporate FedRAMP certification timelines, GDPR cross-border data mandate compliance costs, and workplace safety liability framework expansion patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cybersecurity certification bottlenecks, telecom carrier consolidation, and interoperability standard fragmentation under OASIS and NIST working groups. Forecasts reflect documented assumptions about regulatory enforcement intensity and enterprise procurement committee consolidation behavior. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Global Emergency Beacon Transmitter Market
Emergency and Disaster Management
Lifeboat Market
Emergency and Disaster Management
Hazard Control Market
Emergency and Disaster Management
Disaster Restoration Services Market
Emergency and Disaster Management
Global Emergency Medical Service (EMS) Products Market
Emergency and Disaster Management
Homeland Security and Emergency Management Market
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
Incident and Emergency Management Market
Emergency and Disaster Management
Emergency and Disaster Response Market
Emergency and Disaster Management
Intelligent Evacuation System Market
Emergency and Disaster Management
EHS Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
Asia-Pacific Process Safety Services Market
Emergency and Disaster Management
Crisis Emergency and Incident Management Platform Market