
 Finance Lease Market | 2026-2036
Finance Lease Market Size, Share, and Industry Trends Forecast 2026-2036
Finance Lease Market Intelligence
Modular lease bundling that wraps maintenance, insurance, and residual-value guarantees into a single contract is realigning how corporate fleet managers evaluate total cost of ownership. Wells Fargo Bank leverages its commercial banking footprint to anchor large-ticket equipment programs for mid-market manufacturers. LeasePlan sustains competitive positioning through specialized fleet-management technology that controls vehicle lifecycle costs across multiple European markets.
A finance lease constitutes a non-cancelable contractual arrangement where the lessor transfers substantially all risks and rewards of asset ownership to the lessee, with lease payments structured to recover the full asset cost plus a lessor margin over the contract term. The instrument functions primarily as a debt-financing alternative that preserves lessee liquidity while permitting depreciation claims and interest deductions. Full service lease structures command the deepest margin pools by embedding maintenance and administrative services into the base rate, whereas capital lease arrangements dominate in heavy machinery deployments where ownership transfer at term end carries residual upside. Contract length segmentation reveals accelerating demand for flexible-duration instruments that accommodate project-based capital cycles in construction and energy infrastructure.
US banking regulators including the OCC and Federal Reserve shape finance lease volumes through capital-reserve treatment under Basel III standardized approaches, while the SEC's lease-accounting disclosure mandates under ASC 842 alter corporate demand patterns by forcing on-balance-sheet recognition for most arrangements. European lessors navigate EBA prudential guidelines and IFRS 16 alignment requirements that compress net-interest margins but expand the addressable market among transparency-focused corporate treasuries. Stakeholders must monitor evolving central-bank liquidity policies and cross-border tax-treaty interpretations that determine where lease structuring achieves optimal after-tax economics.
Market Dynamics
Basel III capital adequacy rules are compressing bank balance-sheet capacity and redirecting lessor activity toward off-balance-sheet securitization structures, fundamentally altering how fleet operators and manufacturers access lease financing.
Growth Catalysts
- Basel III standardized approaches:US banking regulators including the OCC and Federal Reserve treat finance leases favorably under risk-weighted asset calculations, pushing commercial banks toward lease origination over direct lending.
- Fleet electrification mandates:German automotive leasing corridors around Stuttgart and Munich are absorbing accelerated demand for battery-electric vehicle bundles as corporate sustainability targets harden.
- Residual value guarantee technology:Predictive analytics platforms now price end-of-term asset values with greater precision, expanding addressable markets for full-service lease structures in construction equipment.
Market Restraints
- Interest rate volatility:Central bank policy shifts in the US and Eurozone expose lessors to duration mismatches between fixed-rate lease receivables and floating-rate funding.
- Concentrated lessor geography:German banking groups dominate European automotive lease origination, creating systemic exposure to regional economic contraction.
- Accounting standard friction:IFRS 16 and ASC 842 force on-balance-sheet recognition that eliminates off-balance-sheet appeal for certain corporate treasury functions.
Strategic Opportunities
- Indian infrastructure build-out:National highway expansion and port modernization projects generate underpenetrated demand for heavy machinery finance leases among mid-tier contractors.
- Maintenance bundling convergence:Integration of telematics platforms with predictive service scheduling enables outcome-based contracts that capture margin pools previously held by third-party service providers.
- EU Green Deal alignment:Sustainable finance taxonomy incentives reward lessors financing low-carbon asset classes, creating regulatory tailwinds for electric commercial vehicle portfolios.
Industry Challenges
- Residual value modeling talent:Shortages of quantitative analysts capable of pricing secondary market equipment values across volatile commodity cycles constrain portfolio expansion.
- Legacy system integration:Mid-market lessors struggle to connect proprietary lease administration platforms with emerging open-banking payment infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finance Lease Market |
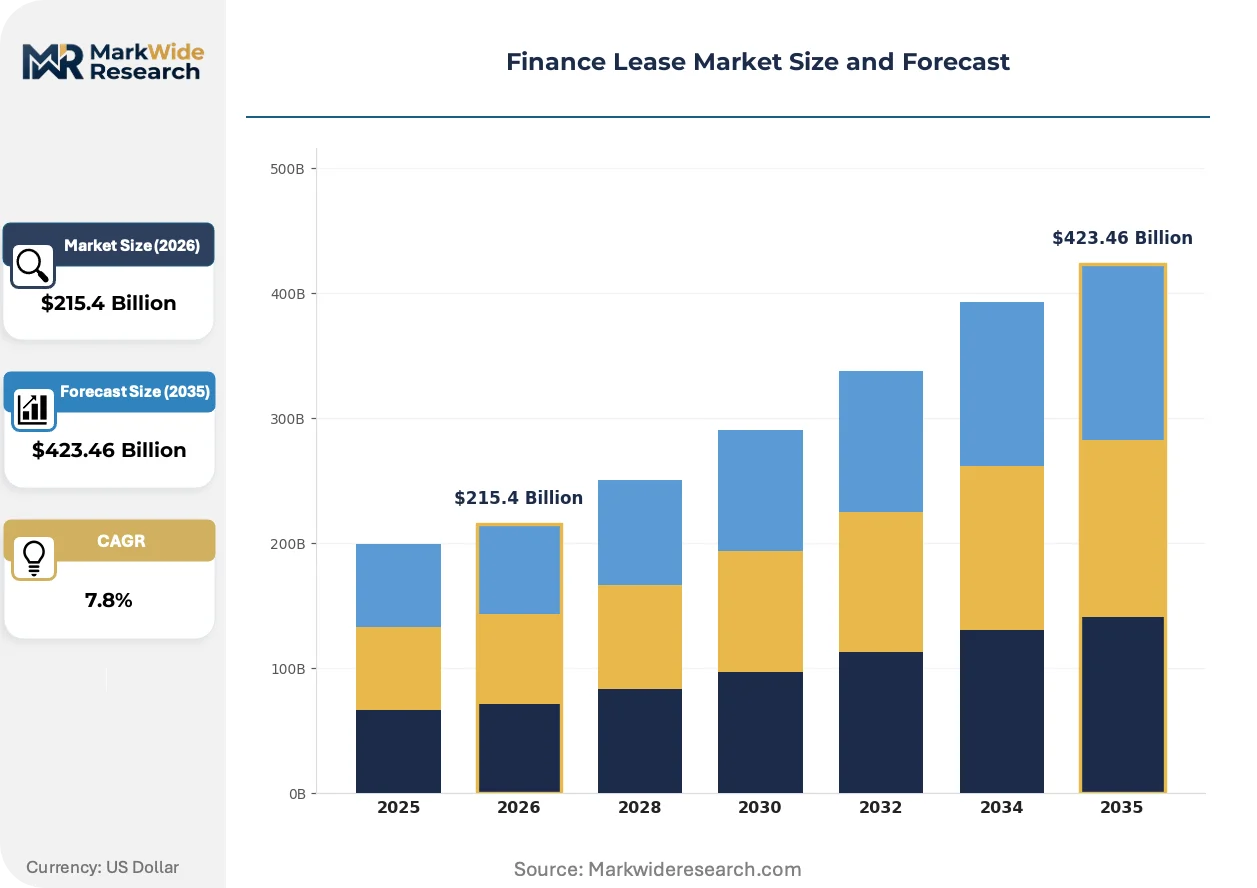
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $423.46 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Service Lease, Tax Lease, Operating Lease, Capital Lease End User: Corporations, Governments, Non-profits, Educational Institutions Asset Type: Vehicles, Machinery, Equipment, Real Estate Contract Length: Short-term, Medium-term, Long-term, Flexible |
| Companies Covered | Wells Fargo Bank, LeasePlan, Sumitomo Mitsui Finance and Leasing, North Star Leasing, Arval, BNP Paribas, Fifth Third Bank, Crest Capital, HSBC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finance Lease Market Strategic Shifts & Innovations
Digital lease origination platforms are compressing underwriting timelines from weeks to days, forcing incumbent lessors to restructure front-office operations around API-driven credit decisioning and automated documentation workflows.
Blockchain-based smart contract infrastructure is integrating immutable lease payment records with real-time asset location tracking. North American logistics fleet operators are adopting these platforms fastest, drawn by automated penalty enforcement and transparent sublease authorization. The technology is integrating previously siloed lessor functions—credit, operations, and remarketing—into unified data architectures that compress administrative cost bases.
The SEC's ASC 842 lease accounting standard forces public filers to recognize right-of-use assets and liabilities, eliminating off-balance-sheet treatment that historically drove operating lease demand. Corporate treasuries are responding by shortening lease terms and negotiating purchase options to minimize balance-sheet footprint. Heavy machinery deployments in US energy infrastructure show the most pronounced term compression as project sponsors optimize leverage ratios.
Subscription-style consumption models are displacing traditional term-based structures in IT equipment and medical device leasing. Corporate procurement functions now prioritize usage elasticity over ownership transfer rights, compressing average contract durations and expanding mid-term upgrade clauses. This pattern concentrates in US healthcare systems and technology services verticals where asset obsolescence cycles accelerate.
Finance Lease Market Segmentation
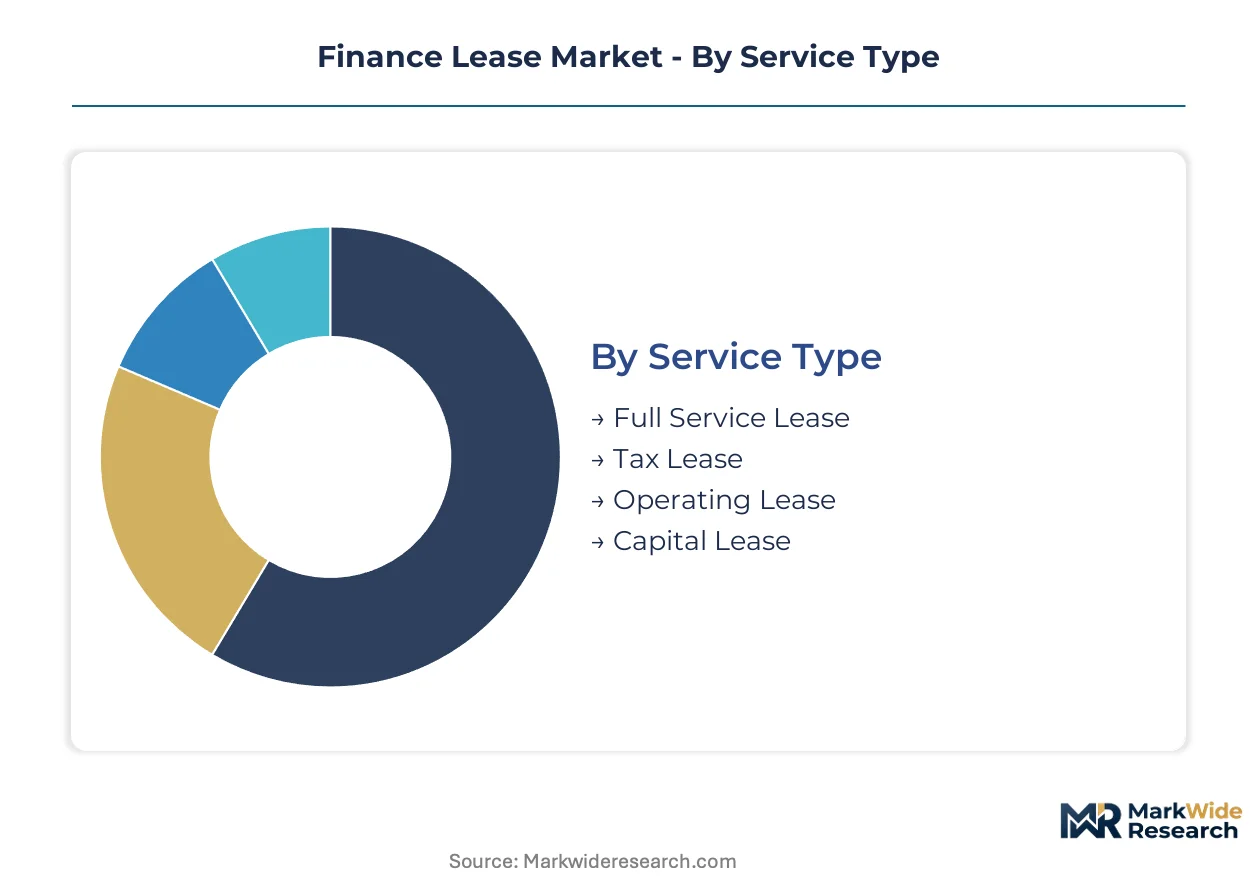
Finance lease segmentation reveals how lessors align contract structures with asset lifecycle economics and lessee liquidity requirements. Upgrade cycles and replacement timing vary dramatically across asset classes, creating divergent demand patterns for bundled services and duration flexibility.
Service Type:
Replacement cycle urgency determines which service bundles capture lessee preference across different asset categories.
- Full Service Lease:Wraps maintenance, insurance, and residual value guarantees into a single contractual rate. Fleet operators in North American logistics corridors favor this structure for commercial vehicle deployments where uptime reliability outweighs ownership economics.
- Capital Lease:Transfers substantially all ownership risks and rewards to the lessee, functioning as secured debt financing. Heavy machinery deployments in energy infrastructure and construction favor this instrument where depreciation claims and end-of-term purchase options align with project sponsor tax positions.
- Operating Lease:Preserves off-balance-sheet treatment for certain lessee structures, though ASC 842 and IFRS 16 have compressed its accounting advantages. Corporate treasuries with strict leverage covenants still deploy this for short-asset-cycle equipment.
- Tax Lease:Structures payment streams to optimize tax attribute utilization between lessor and lessee. Specialized lessors with deep tax capacity dominate origination in aviation and rail equipment where accelerated depreciation schedules create substantial value.
Full Service Lease sits at the top of the volume ranking, with Capital Lease climbing the fastest as infrastructure project finance expands.
End User:
Procurement sophistication and balance-sheet flexibility create distinct service requirements across lessee categories.
- Corporations:Drive the majority of finance lease origination volume. Mid-market manufacturers in the US Midwest leverage Wells Fargo commercial banking relationships to structure large-ticket equipment programs with embedded maintenance.
- Governments:Municipal and federal entities utilize tax-exempt lease structures for infrastructure assets. State-level transportation departments favor medium-term vehicle leases with flexible renewal clauses tied to budget appropriation cycles.
- Non-profits:Access below-market financing through qualified 501(c)(3) lease structures. Healthcare systems deploy subscription-style models for medical device fleets where technology obsolescence cycles compress replacement timing.
- Educational Institutions:Structure capital leases for campus infrastructure and IT equipment. University procurement functions prioritize usage elasticity over ownership transfer rights in technology deployments.
Corporations maintain the dominant share of origination volume, while Educational Institutions are expanding most quickly as campus modernization accelerates.
Asset Type:
Physical durability and secondary market liquidity determine residual value risk allocation between lessor and lessee.
- Vehicles:Automotive leasing corridors around Stuttgart and Munich absorb accelerated demand for battery-electric bundles as corporate sustainability targets harden. Predictive analytics platforms now price end-of-term vehicle values with greater precision.
- Machinery:Construction and agricultural equipment leases concentrate in German banking group portfolios. Residual value modeling talent shortages constrain expansion into volatile commodity cycle exposures.
- Equipment:IT hardware and medical device leasing shows pronounced term compression as subscription-style consumption models displace traditional structures. US healthcare systems prioritize mid-term upgrade clauses.
- Real Estate:Long-duration finance leases function as synthetic ownership for corporate facilities. Structures typically incorporate purchase options and renewal rights tied to occupancy planning horizons.
Vehicles lead asset-type origination volume, with Equipment gaining share fastest as technology obsolescence accelerates replacement cycles.
Contract Length:
Capital deployment horizons and project financing requirements shape duration preferences across lessee segments.
- Medium-term:Three-to-five year structures dominate corporate fleet and standard equipment deployments. This duration balances lessee flexibility with lessor yield requirements across most asset categories.
- Long-term:Seven-to-ten year or longer contracts align with infrastructure asset economics. Real estate and heavy industrial machinery favor this horizon where asset economic life extends across multiple business cycles.
- Short-term:Under-three-year arrangements accommodate project-based capital cycles in construction and event-driven equipment needs. Premium pricing reflects higher administrative and remarketing costs.
- Flexible:Duration-adjustable contracts with extension or termination options respond to uncertain demand environments. Energy infrastructure sponsors utilize these structures where project timelines face regulatory or permitting variability.
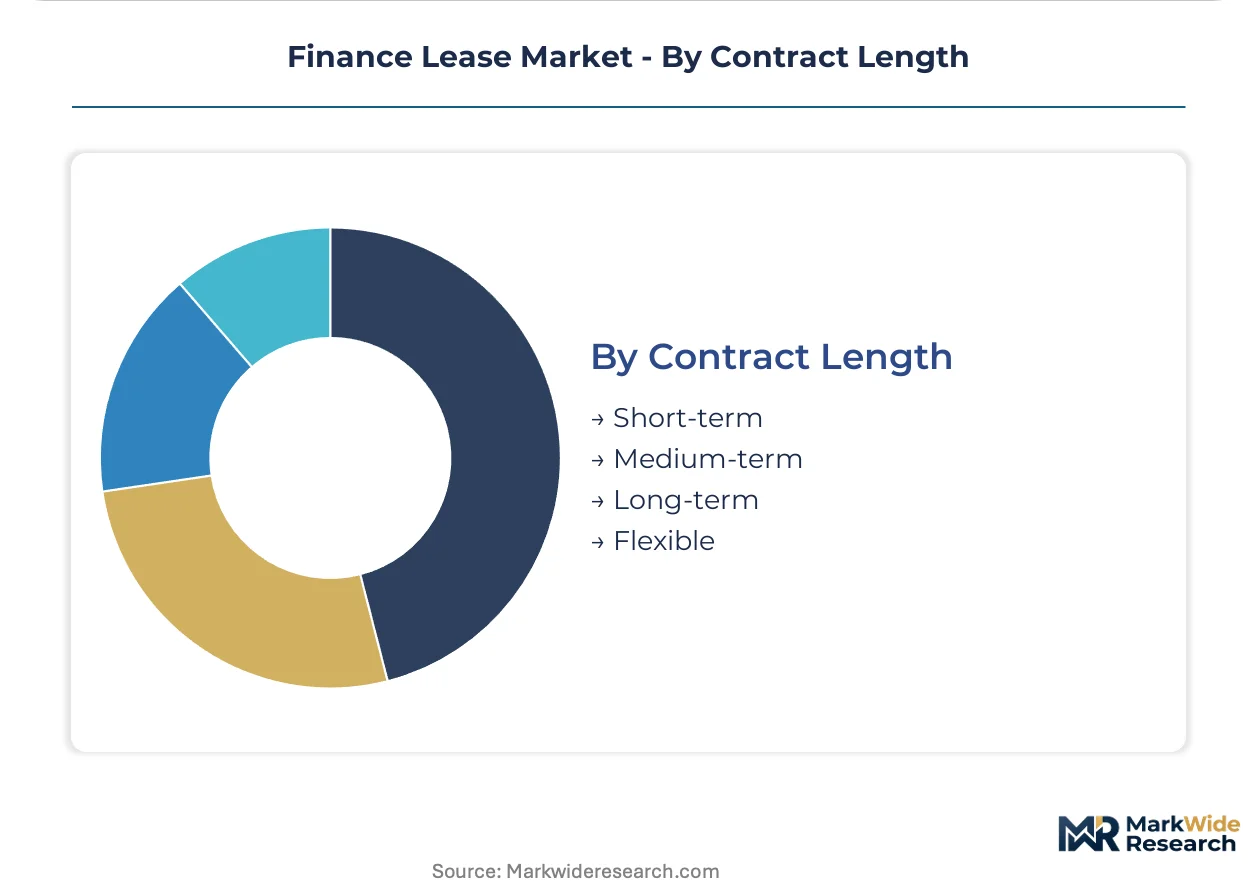
Medium-term contracts hold the volume leadership position, with Flexible structures showing the steepest expansion trajectory as project finance uncertainty increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finance leasing traces its modern commercial roots to post-war equipment financing in the United States, where manufacturers pioneered off-balance-sheet structures to accelerate capital deployment. The instrument subsequently migrated to European banking centers and Asian industrial corridors, adapting to local regulatory and tax architectures.
United States
Mid-market manufacturers in the Midwest corridor drive substantial lease origination volume through commercial banking relationships. The OCC and Federal Reserve shape capital-reserve treatment under Basel III standardized approaches, favoring lease structures over direct lending for risk-weighted asset calculations. Fleet operators across North American logistics corridors are expanding bundled maintenance-plus-lease packages for commercial vehicle deployments.
Germany
Automotive leasing corridors around Stuttgart and Munich absorb accelerated demand for battery-electric vehicle bundles as corporate sustainability targets harden. The EBA prudential guidelines and IFRS 16 alignment requirements compress net-interest margins but expand addressable markets among transparency-focused corporate treasuries. German banking groups dominate European automotive lease origination, creating systemic exposure to regional economic contraction.
Japan
Industrial machinery lessors serve precision manufacturing clusters in the Chubu and Kansai regions where equipment refresh cycles demand flexible financing. METI oversight of financial leasing activities ensures prudential standards align with broader banking sector stability frameworks. Tokyo-based lessors anchor cross-border equipment programs for Southeast Asian infrastructure build-outs.
India
National highway expansion and port modernization projects generate underpenetrated demand for heavy machinery finance leases among mid-tier contractors. The RBI regulates non-banking financial companies engaged in leasing activities through prudential norms on asset classification and provisioning. Maharashtra and Gujarat industrial corridors host emerging lessor operations targeting construction equipment procurement.
United Kingdom
Corporate treasuries in London and the Southeast utilize finance leases for IT infrastructure and fleet assets where ASC 842 and IFRS 16 disclosure mandates have reshaped contract structuring preferences. The FCA and Prudential Regulation Authority supervise lessor conduct under overlapping regulatory remits. Scottish energy infrastructure sponsors employ flexible-duration instruments where project timelines face regulatory variability.
Finance Lease Market Key Industry Players
The competitive structure tilts toward diversified banking conglomerates with captive leasing arms. Tier-one commercial banks leverage balance-sheet scale and existing corporate relationships to originate large-ticket equipment programs. Mid-market specialists compete through sector-specific expertise and bundled service offerings. Dominant competitive moves include portfolio diversification across asset classes and strategic partnerships with original equipment manufacturers.
Within the banking-centric tier, Wells Fargo Bank and BNP Paribas exemplify institutions that anchor large-ticket equipment programs through commercial banking footprints. LeasePlan occupies a position among fleet-management specialists with technology platforms controlling vehicle lifecycle costs across European markets. Sumitomo Mitsui Finance and Leasing represents the Asia-Pacific banking group archetype with industrial equipment origination capabilities spanning multiple regional markets.
| Leading Market Players |
|---|
| Wells Fargo Bank |
| LeasePlan |
| Sumitomo Mitsui Finance and Leasing |
| North Star Leasing |
| Arval |
| BNP Paribas |
| Fifth Third Bank |
| Crest Capital |
| HSBC Group |
| Others |
Cost & Logistics Intelligence
EU Green Deal taxonomy alignment gates qualified supply access and premium-tier pricing power for lessors financing battery-electric vehicle bundles, forcing non-compliant originators into compressed-margin standard tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by residual value guarantee depth and telematics integration density. Price differentiation rests on Basel III risk-weighting advantages and bundled maintenance sophistication. Cost compression in standard tiers intensifies because German banking groups crowd mid-market automotive origination. Fleet operators with sustainability mandates show lowest price sensitivity; mid-tier contractors in Indian infrastructure corridors exhibit highest.
Supply Chain Analysis
Freight cost volatility from Red Sea disruptions and Panama Canal constraints is reshaping equipment lessor procurement timelines for heavy machinery deployed across North American logistics corridors. Manufacturing concentrates in Germany, Japan, and the United States for precision automotive and industrial equipment. Raw material feeds from lithium carbonate, high-strength steel, and semiconductor components face single-source vulnerability in East Asian processing nodes. Distribution runs through captive lessor platforms and commercial banking networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on predictive residual value analytics compressing loss-given-default rates and premium-tier electrification bundles capturing regulatory arbitrage.
For Market Incumbents: Acquire telematics-enabled fleet management platforms to embed predictive maintenance pricing and defend against fintech lease origination disruptors. Deepen backward integration into battery-electric vehicle remarketing channels. Prioritize certification investment in EU Green Deal taxonomy alignment to sustain premium-tier access. For New Entrants and Emerging Players: OEM captive finance arms represent the most penetrable channel partner type for mid-market manufacturers underserved by Wells Fargo commercial banking relationships. Target Indian infrastructure contractors in Maharashtra and Gujarat corridors with flexible-duration heavy machinery structures. Deploy API-driven credit decisioning to compress underwriting timelines against legacy lessor workflows. For Investors and Strategic Acquirers: Roll-up economics work for regional fleet-management specialists because ASC 842 disclosure mandates fragment corporate treasury procurement across multiple lessor relationships. Five-to-ten year viability favors platforms with proprietary residual value modeling capabilities. Watch central bank liquidity policy shifts as inflection indicators for securitization volume capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Residual Value Guarantee Technology Investment | Predictive analytics platforms expand addressable markets for full-service lease structures in construction equipment. |
| Telematics Platform Integration | Real-time asset tracking enables outcome-based contracts capturing margin pools from third-party service providers. |
| EU Green Deal Taxonomy Alignment | Sustainable finance incentives reward lessors financing low-carbon asset classes with regulatory tailwinds. |
| Securitization Structure Development | Off-balance-sheet vehicles redirect lessor activity as Basel III compresses bank balance-sheet capacity. |
| Flexible-Duration Contract Innovation | Adjustable terms accommodate project-based capital cycles in energy infrastructure facing permitting variability. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined through triangulation. Fleet procurement directors, commercial banking relationship managers, residual value quant analysts, and OEM captive finance heads provided structured interviews. Secondary validation drew from SEC lease disclosure filings, EBA prudential guideline updates, RBI non-banking financial company regulatory circulars, and customs equipment import data. Bottom-up lease origination volume estimates reconciled against top-down banking sector asset growth.
Rate-of-change decomposition across the analysis window separated volume growth into fleet expansion, contract duration shifts, and bundled service penetration. Segmentation dimensions modeled include service type, asset class, contract length flexibility, and lessee credit tier. CAGRs derived from regression against macroeconomic indicators and regulatory policy trajectories. Forecast inputs incorporated central bank liquidity policy paths and battery-electric vehicle residual value depreciation curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to interest rate volatility and cross-border tax-treaty reinterpretations. Forecasts reflect documented assumptions about Basel III implementation consistency and IFRS 16 enforcement uniformity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Loan Management Software Market
Loans and Leasing
India Car Loan Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
UK Home Equity Lending Market
Loans and Leasing
Qatar Mortgage/Loan Brokers Market
Loans and Leasing
United States Digital Lending Market
Loans and Leasing
Japan Auto Loan Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
Digital Lending Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
US Home Equity Lending Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
Global Automotive Fleet Leasing Market
Loans and Leasing
Asia-Pacific Motorcycle Loan Market