
 Global Financial Accounting Advisory Services Market | 2026-2036
Global Financial Accounting Advisory Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Financial Accounting Advisory Services Market Analysis
The EU Corporate Sustainability Reporting Directive is broadening the scope of mandatory assurance and disclosure obligations across capital markets. Deloitte leverages its global network of sustainability specialists to anchor advisory workflows tied to CSRD implementation. PwC competes through integrated ESG reporting platforms that span climate risk quantification and financial statement linkage. EY differentiates by embedding carbon accounting directly into statutory audit processes for European multinational clients.
Financial accounting advisory services encompass technical assistance for complex recognition, measurement, and presentation decisions under applicable reporting frameworks, including IFRS 15 revenue criteria, lease capitalization under IFRS 16, and fair value hierarchy classifications per IFRS 13. The primary commercial purpose centers on reducing restatement risk, accelerating close cycles, and satisfying capital provider demands for decision-useful information. Financial Reporting engagements sustain premium pricing due to technical scarcity around instrument valuation and consolidation architecture. Project-based models dominate SME penetration where episodic transformation needs outweigh standing advisory relationships.
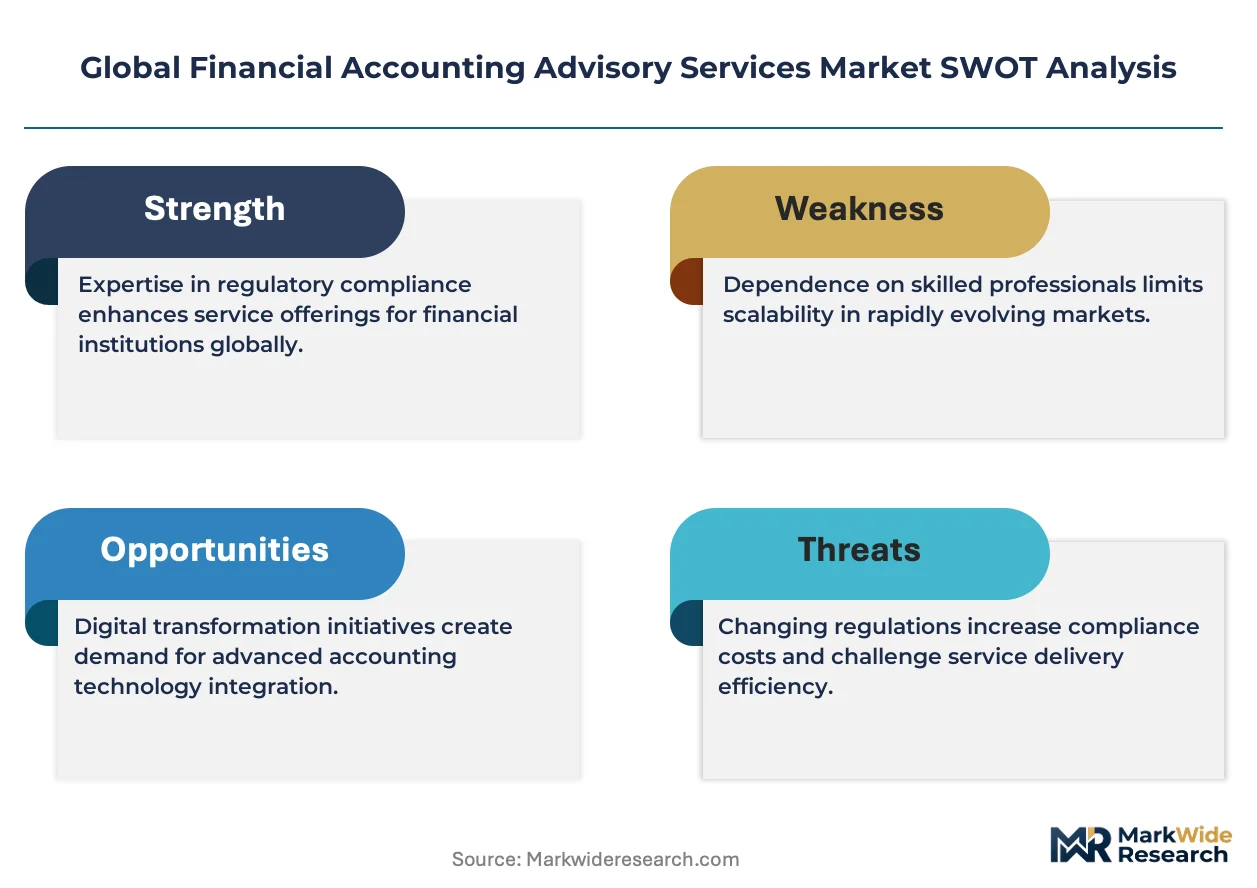
The SEC, EMA, and FASB collectively shape demand through disclosure mandates, enforcement priorities, and standards convergence agendas that expand the perimeter of professional judgment required in financial statements. EU Green Deal taxonomy alignment and SEC climate rules are forcing issuers to source external technical partners capable of bridging sustainability metrics with audited financial data. Stakeholders must monitor the trajectory of mandatory assurance requirements for sustainability disclosures as the boundary between traditional audit and advisory services continues to blur.
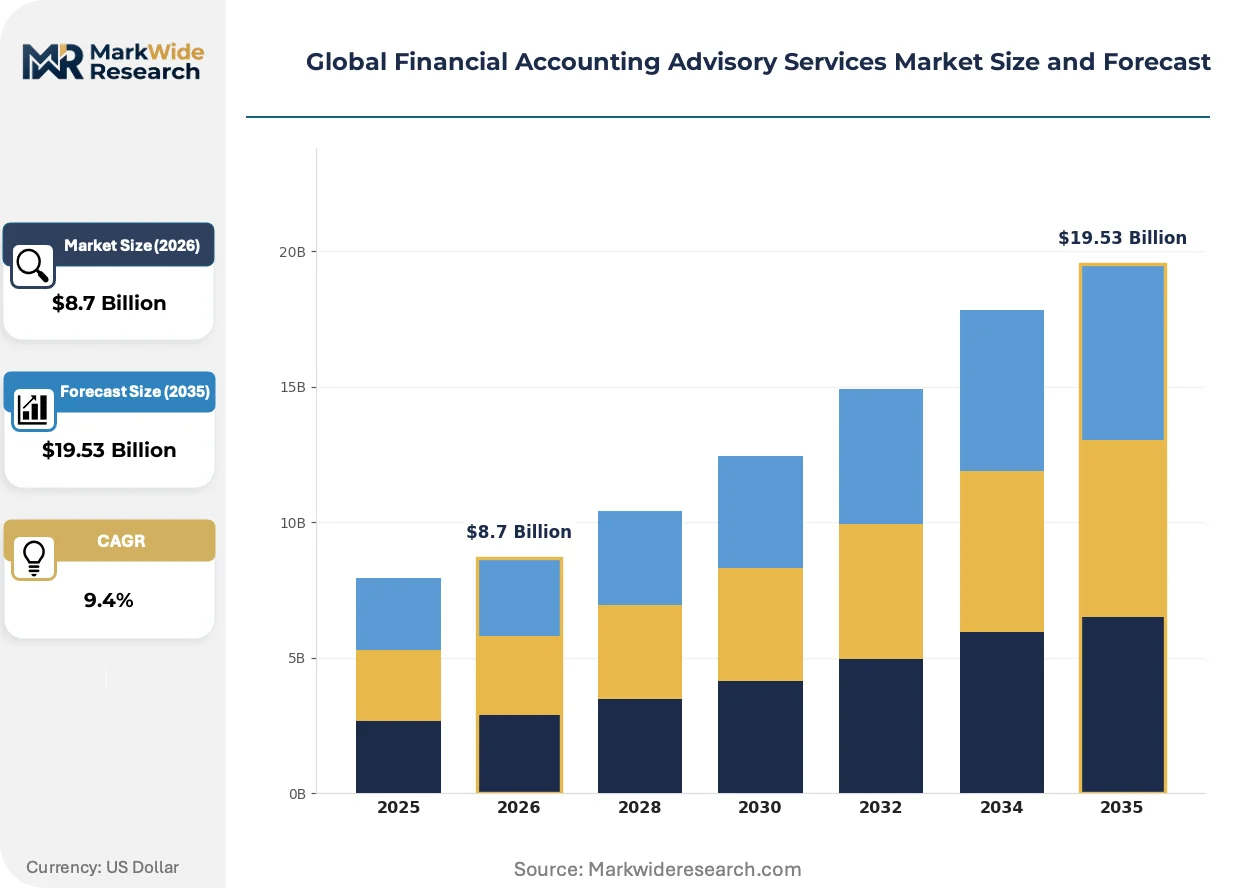
Market Dynamics
The convergence of sustainability mandates with core financial reporting is compressing the traditional boundary between audit and advisory functions, forcing firms to rebuild service architectures around integrated disclosure requirements.
Growth Catalysts
- CSRD Implementation:The EU Corporate Sustainability Reporting Directive mandates third-party assurance for ESG disclosures, creating sustained demand for external technical partners capable of bridging sustainability metrics with statutory audit processes.
- SEC Climate Rules:The United States Securities and Exchange Commission's disclosure requirements for climate-related financial risks are compelling public issuers to source specialized expertise for scenario analysis and materiality assessments.
- IFRS Convergence Pressure:Multinational corporations operating across jurisdictions face escalating complexity in revenue recognition under IFRS 15 and lease capitalization under IFRS 16, driving episodic advisory engagements.
Market Restraints
- Talent Scarcity:The shallow pool of professionals possessing dual competency in instrument valuation and sustainability accounting limits service expansion and inflates compensation costs for technical specialists.
- Regulatory Fragmentation:Divergent timelines between EU Green Deal taxonomy alignment and SEC climate disclosure implementation create compliance architecture conflicts for cross-border issuers.
- Project-Based Volatility:SME reliance on episodic transformation engagements rather than standing advisory relationships produces revenue unpredictability and client acquisition cost concentration.
Strategic Opportunities
- India Market Entry:SEBI's evolving disclosure framework for listed companies and the RBI's climate risk guidance for banks are creating first-mover advantages for advisory firms establishing local sustainability practices.
- Carbon Accounting Integration:Convergence of statutory audit software with emissions quantification platforms enables bundled service offerings that capture margin from both compliance and advisory workflows.
- Assurance Market Expansion:Mandatory assurance requirements for sustainability disclosures across EU member states are opening regulated service lines previously reserved for statutory audit firms.
Industry Challenges
- Skills Architecture:Firms struggle to recruit professionals fluent in both fair value hierarchy classifications under IFRS 13 and physical climate risk modeling for financial statements.
- Technology Integration:Legacy ERP systems at client organizations resist seamless incorporation of ESG data streams, extending implementation timelines and eroding project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Financial Accounting Advisory Services Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Audit, Tax Advisory, Compliance, Financial Reporting Client Type: Corporations, SMEs, Government Agencies, Non-profits Industry Vertical: Financial Services, Manufacturing, Technology, Healthcare Engagement Model: Project-based, Retainer, On-demand, Consulting |
| Companies Covered | Deloitte, PwC, EY, KPMG, BDO, Grant Thornton, RSM, Crowe, Mazars, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Financial Accounting Advisory Services Market Emerging Trajectories
Advisory workflows are being rebuilt around real-time data ingestion and automated disclosure generation, compressing the traditional quarterly close cycle and elevating continuous monitoring capabilities.
Cloud-native consolidation platforms is unifying multi-entity reporting across disparate ERP environments. Mid-market corporations in Germany and the Netherlands are adopting these tools fastest, replacing spreadsheet-dependent close processes. The technology is unifying previously siloed statutory and management reporting functions into single-source architectures.
Japan's METI has issued supplementary guidance linking TCFD-aligned disclosures to consolidated financial statements. This regulatory pressure is forcing Japanese multinational issuers to restructure internal reporting hierarchies and source external technical validation. Automotive and electronics manufacturers with extensive Southeast Asian supply chains face the steepest compliance burden.
Subscription-based advisory retainers are displacing hourly billing for recurring compliance support. Private equity portfolio companies in the United Kingdom and Ireland are consolidating vendor relationships under multi-year contracts with embedded technology licenses. This procurement evolution is visible most acutely among asset managers preparing for SFDR Article 8 and 9 fund classifications.
Global Financial Accounting Advisory Services Market Segmentation
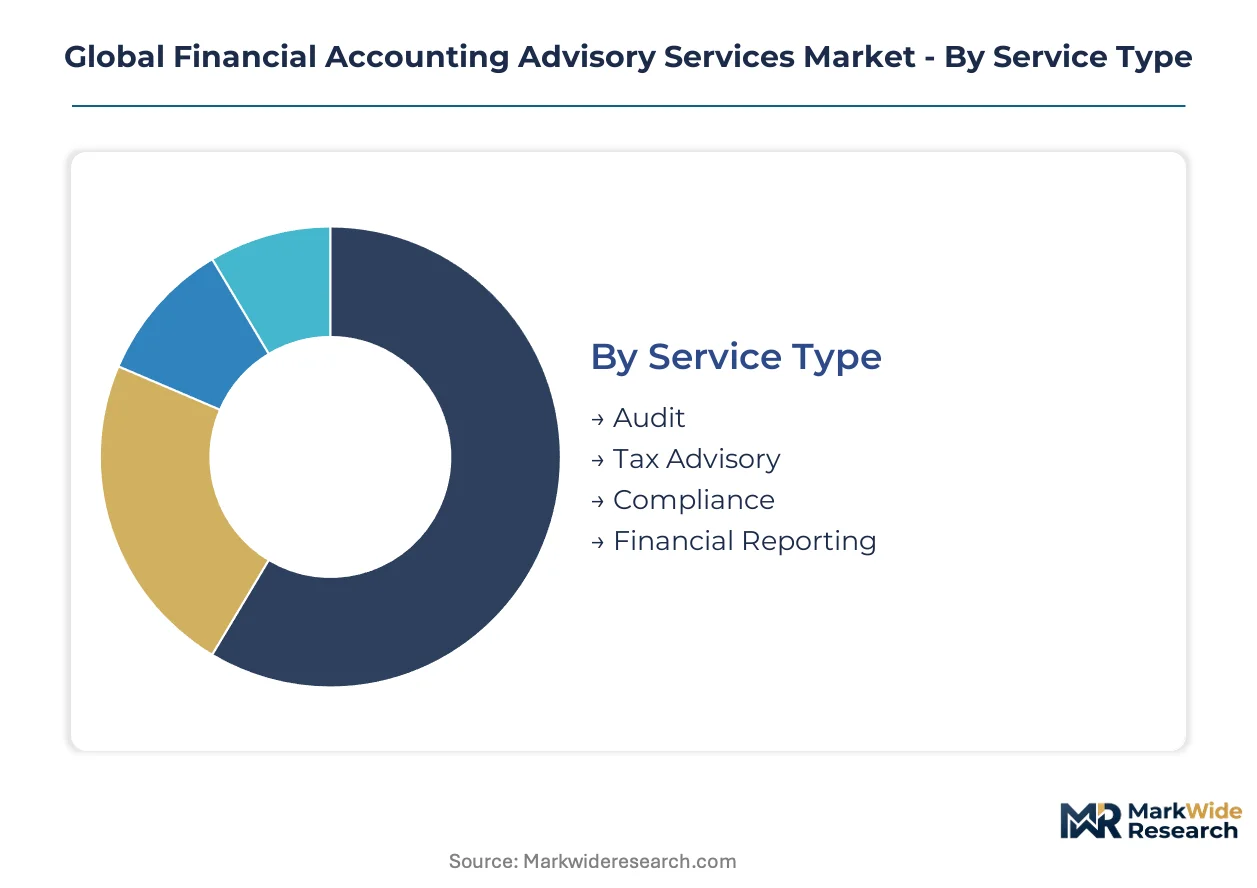
Service architecture in financial accounting advisory varies dramatically by integration depth. Some segments operate as embedded functions within broader audit relationships, while others function as standalone procurement decisions with distinct vendor selection criteria.
Service Type:
Standalone advisory services command premium positioning, whereas compliance-linked offerings embed more deeply into recurring audit workflows.
- Audit:Statutory audit services form the anchor relationship that cross-sells advisory capabilities. Demand concentrates among publicly listed issuers in the United States facing SEC enforcement priorities, with CSRD implementation in Europe expanding assurance obligations for sustainability disclosures.
- Financial Reporting:Technical assistance for complex recognition and measurement decisions under IFRS and US GAAP frameworks. Corporations in Germany and Japan source external expertise for lease capitalization under IFRS 16 and revenue criteria under IFRS 15, driven by convergence pressure across jurisdictions.
- Tax Advisory:Structuring support for cross-border transactions and transfer pricing documentation.
- Compliance:Regulatory filing preparation and disclosure obligation management.
Volume placements concentrate in Audit; the faster expansion belongs to Financial Reporting.
Client Type:
Procurement scale and relationship continuity diverge sharply across client categories, reshaping vendor economics and service packaging.
- Corporations:Multinational issuers maintain standing advisory relationships spanning multiple jurisdictions. Demand clusters among EU-headquartered firms navigating CSRD assurance requirements and US public companies responding to SEC climate disclosure rules, with retainer-based models dominating procurement.
- SMEs:Mid-market enterprises rely on episodic transformation engagements rather than continuous advisory support. Project-based pricing prevails in the United Kingdom and Ireland, where private equity portfolio companies consolidate vendor relationships under multi-year contracts.
- Government Agencies:Public sector procurement follows rigid tender processes with extended vendor qualification timelines.
- Non-profits:Grant-dependent organizations prioritize cost containment over technical sophistication in advisory selection.
Revenue concentration sits with Corporations; SMEs are climbing the fastest as subscription-based retainers displace hourly billing.
Industry Vertical:
Sector-specific regulatory exposure and transaction complexity determine advisory intensity and pricing power across verticals.
- Financial Services:Banks and insurers face the steepest compliance burden from climate risk quantification and ESG-linked financial disclosures. Institutions in Japan with extensive Southeast Asian supply chains restructure internal reporting hierarchies to align METI guidance with consolidated financial statements.
- Technology:Software and platform companies navigate complex revenue recognition for subscription models and multi-element arrangements. Cloud-native consolidation platforms attract fastest adoption among mid-market technology firms in Germany and the Netherlands.
- Manufacturing:Industrial firms require carbon accounting integration with statutory audit processes for EU Green Deal taxonomy alignment.
- Healthcare:Pharmaceutical and device companies manage fair value hierarchy classifications for R&D assets and contingent consideration.
Advisory intensity peaks in Financial Services; Technology verticals are gaining share fastest on digital transformation mandates.
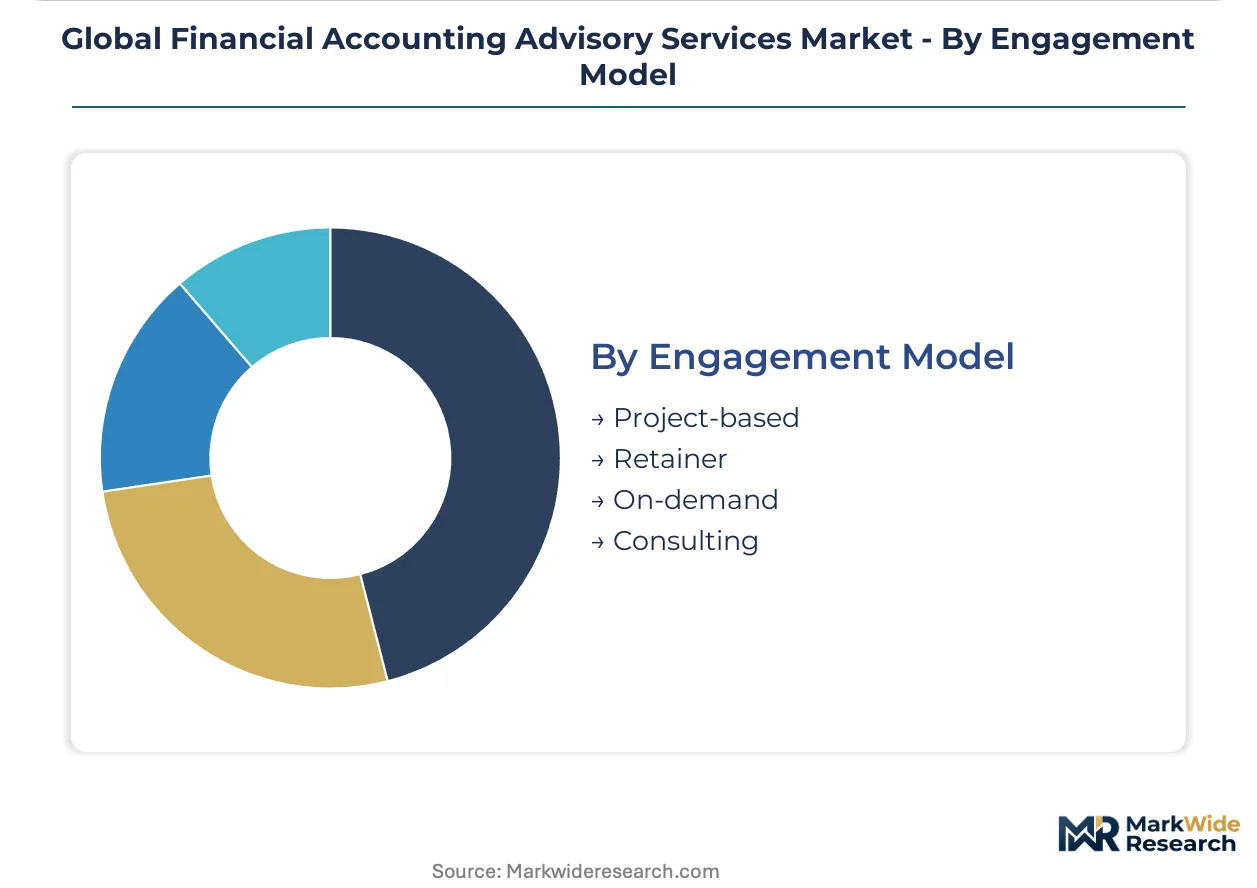
Engagement Model:
Commercial structure shapes margin stability and client lifetime value across service delivery architectures.
- Retainer:Recurring compliance support contracts embed advisory firms deeply into client operations. Asset managers in the United Kingdom preparing for SFDR Article 8 and 9 fund classifications consolidate vendor relationships under multi-year agreements with embedded technology licenses.
- Project-based:Episodic transformation engagements address specific inflection points such as ERP implementation or standards adoption. German and Dutch mid-market corporations adopt cloud-native consolidation platforms through discrete procurement cycles.
- Consulting:Strategic advisory on M&A transactions and restructuring events.
- On-demand:Ad-hoc technical validation for specific judgment calls or regulatory inquiries.
Margin stability favors Retainer arrangements; Project-based models are expanding most quickly as SME penetration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the largest advisory services consumption, while talent production clusters in the United Kingdom and Germany. Cross-border complexity drives premium pricing in London and New York. Regulatory divergence between jurisdictions creates specialized demand pockets.
United States
SEC climate disclosure rules compel public issuers to source external expertise for scenario analysis and materiality assessments. The IRA's clean energy tax provisions require sophisticated carbon accounting integration. New York and Chicago host the densest concentrations of sustainability-linked advisory practices.
Germany
EU Green Deal taxonomy alignment forces industrial firms to restructure carbon accounting workflows. BaFin's enforcement priorities for financial institutions elevate demand for integrated ESG assurance. Frankfurt and Munich anchor the largest advisory talent pools for IFRS 16 lease capitalization.
United Kingdom
SFDR Article 8 and 9 fund classifications drive asset managers to consolidate vendor relationships under multi-year contracts. The FCA's sustainability disclosure requirements expand assurance obligations for investment firms. London's City district concentrates subscription-based advisory retainers for private equity portfolio companies.
Japan
METI's supplementary guidance linking TCFD-aligned disclosures to consolidated financial statements restructures internal reporting hierarchies. The country's central bank's climate risk guidance for financial institutions elevates external validation needs. Tokyo and Osaka automotive manufacturers face the steepest compliance burden for Southeast Asian supply chain disclosures.
India
SEBI's evolving disclosure framework for listed companies creates first-mover advantages for advisory firms establishing local sustainability practices. The RBI's climate risk guidance for banks expands external technical partnership requirements. Mumbai and Bangalore concentrate the fastest-growing advisory talent pools for cross-border transaction support.
Global Financial Accounting Advisory Services Market Vendor Landscape
The competitive structure tilts toward consolidated global networks with deep regulatory relationships. Four professional services networks capture the majority of premium engagements across jurisdictions. Two strategic archetypes dominate: integrated audit-advisory hybrids and standalone technical specialists. Competitive moves center on sustainability practice buildouts and technology platform acquisitions.
Within the integrated network tier, Deloitte, PwC, and EY exemplify the audit-anchored advisory model. These firms leverage statutory audit relationships to cross-sell complex financial reporting and ESG assurance services. Their global footprints allow seamless coordination across CSRD implementation in Europe and SEC climate rule compliance in North America. Technical scarcity around instrument valuation and carbon accounting sustains their pricing power.
| Leading Market Players |
|---|
| Deloitte |
| PwC |
| EY |
| KPMG |
| BDO |
| Grant Thornton |
| RSM |
| Crowe |
| Mazars |
| Others |
Supply Flow & Price Mechanics
Certification-tier divergence between statutory audit firms and standalone advisory boutiques manifests in both fee structures and talent sourcing configurations. Premium engagements command retainer-based pricing anchored by CSRD assurance mandates, while project-based SME segments compete on episodic transformation pricing. This bifurcation reshapes supply chain choices as integrated networks prioritize regulatory relationship depth over cost efficiency.
Pricing Analysis
Margin tightening in mid-market project tiers reflects talent scarcity for dual-competency specialists spanning IFRS 13 valuation and carbon accounting. Three-tier pricing structure across premium assurance, standard compliance, and economy transformation levels dominates procurement. Cost-down pressure on standalone advisory boutiques accelerates because retainer-based models at integrated firms capture recurring revenue. Asset managers preparing for SFDR classifications show least price sensitivity; private equity portfolio companies exhibit highest.
Supply Chain Analysis
India's domestic-content mandates for SEBI-registered advisory practices are reshaping sourcing toward Mumbai and Bangalore talent clusters. Professional services delivery draws from United Kingdom, Germany, and India as primary supply nodes. Raw material dependencies center on qualified accountants, sustainability specialists, and cloud-native consolidation software licenses. Single-source vulnerability concentrates in ESG assurance credential pipelines. Distribution runs through direct partner relationships and technology-embedded multi-year contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The competitive structure favors consolidation as regulatory complexity forces sub-scale players toward exit or acquisition. Talent scarcity and technology investment requirements create insurmountable barriers for fragmented boutiques.
For Market Incumbents: To counter standalone advisory boutiques undercutting on project pricing, deepen regulatory relationship moats through CSRD implementation partnerships in Germany and SEC climate rule advisory in the United States. Prioritize carbon accounting software acquisitions that embed advisory workflows into statutory audit platforms. For New Entrants and Emerging Players: Enter via SEBI disclosure framework advisory for Indian listed companies, the most penetrable geography given evolving local mandates and limited incumbent presence. Target mid-market technology firms in Germany and the Netherlands adopting cloud-native consolidation platforms. Lead with specialized IFRS 16 lease capitalization expertise as differentiated entry wedge. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier networks possessing regulatory licenses but lacking sustainability practice scale, given mandatory assurance expansion across EU member states. Long-term viability hinges on advisory-retainer share exceeding project-dependency. Monitor SEBI and RBI guidance publication velocity as inflection signal for India market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Accounting Integration | Bundles emissions quantification with statutory audit workflows for EU Green Deal taxonomy alignment. |
| Regulatory License Acquisition | Captures mandatory assurance market opening previously reserved for statutory audit firms under CSRD. |
| Cloud-Native Platform Deployment | Compresses quarterly close cycles for German and Dutch mid-market corporations replacing spreadsheets. |
| Sustainability Practice Buildout | Addresses SEC climate disclosure rules requiring scenario analysis expertise for US public issuers. |
| India Market Entry | Establishes local presence before SEBI disclosure framework matures and incumbent positions harden. |
Methodological Framework
SEC filings, EU regulatory databases, and professional services firm disclosure documents formed the secondary backbone for market sizing and competitive positioning. Primary interviews with financial reporting directors, sustainability assurance leads, regulatory affairs specialists at Big Four networks, and procurement officers at multinational issuers validated demand trajectories. Bottom-up and top-down triangulation reconciled segment-level estimates against aggregate market figures.
Bottom-up modeling built service-line revenues from disclosed headcount, billing rate assumptions, and utilization benchmarks across audit, financial reporting, and ESG assurance segments. Top-down validation cross-checked against regulatory filing volumes, CSRD implementation timelines, and SEC climate rule adoption curves. Segmentation dimensions spanned service type, client category, industry vertical, engagement model, and geographic regulatory cluster. CAGRs derived from regression analysis of historical advisory spending against regulatory mandate intensity indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under CSRD implementation delays or SEC rule rollback scenarios. Projections reflect assumptions around mandatory assurance scope expansion and sustainability disclosure standardization velocity. Talent supply constraints and technology platform adoption curves present material revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Bookkeeper Software Market
Accounting and Taxation Services
Small Business Accounting Software Market
Accounting and Taxation Services
Spain Accounting Software Market
Accounting and Taxation Services
Forensic Accounting Market
Accounting and Taxation Services
Accounting Software Market
Accounting and Taxation Services
Global Sales Tax Compliance Software Market
Accounting and Taxation Services
Global Fund Accounting Software Market
Accounting and Taxation Services
Crypto Tax Software Market
Accounting and Taxation Services
India Accounting Professional Services Market
Accounting and Taxation Services
Germany Accounting Software Market
Accounting and Taxation Services
Global Business Accounting Software Market
Accounting and Taxation Services
Asia-Pacific Accounting & Budgeting Software Market
Accounting and Taxation Services
Integrated Accounting Software Market
Accounting and Taxation Services
India Forensic Accounting Market
Accounting and Taxation Services
UK Forensic Accounting Market
Accounting and Taxation Services
South Korea Forensic Accounting Market