
 Loan Management Software Market | 2026-2036
Loan Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Loan Management Software Market Foresight
Fintech software development in Estonia is restructuring how European lenders approach core banking modernization. Mambu leverages a composable banking architecture to sustain cloud-native deployment advantages across continental Europe. Finastra anchors its position through extensive correspondent banking networks and treasury connectivity. Temenos competes on the strength of its universal banking platform scaled across tier-one institutions.
Loan management software comprises integrated technology platforms that automate origination, servicing, and collections workflows for consumer, commercial, and mortgage credit. These systems typically embed real-time credit decisioning engines, API-layer connectivity to credit bureaus, and configurable workflow orchestration to satisfy jurisdictional compliance requirements. Cloud-based deployment now leads product type preference as financial institutions seek elastic infrastructure without captive data center overhead. Loan origination and loan servicing solutions command the deepest margin pools within the solution category, while risk management modules are gaining fastest traction among mortgage lenders facing heightened stress-testing obligations.
The European Banking Authority's open banking framework and the United States FFIEC examination standards shape product roadmaps by mandating audit trails, data portability, and third-party risk oversight. GDPR and state-level US privacy laws impose granular consent management and cross-border data restriction requirements that vendors must architect around. Stakeholders should monitor how central bank digital currency pilots and embedded finance regulatory sandboxes reshape lender technology procurement criteria.
Market Dynamics
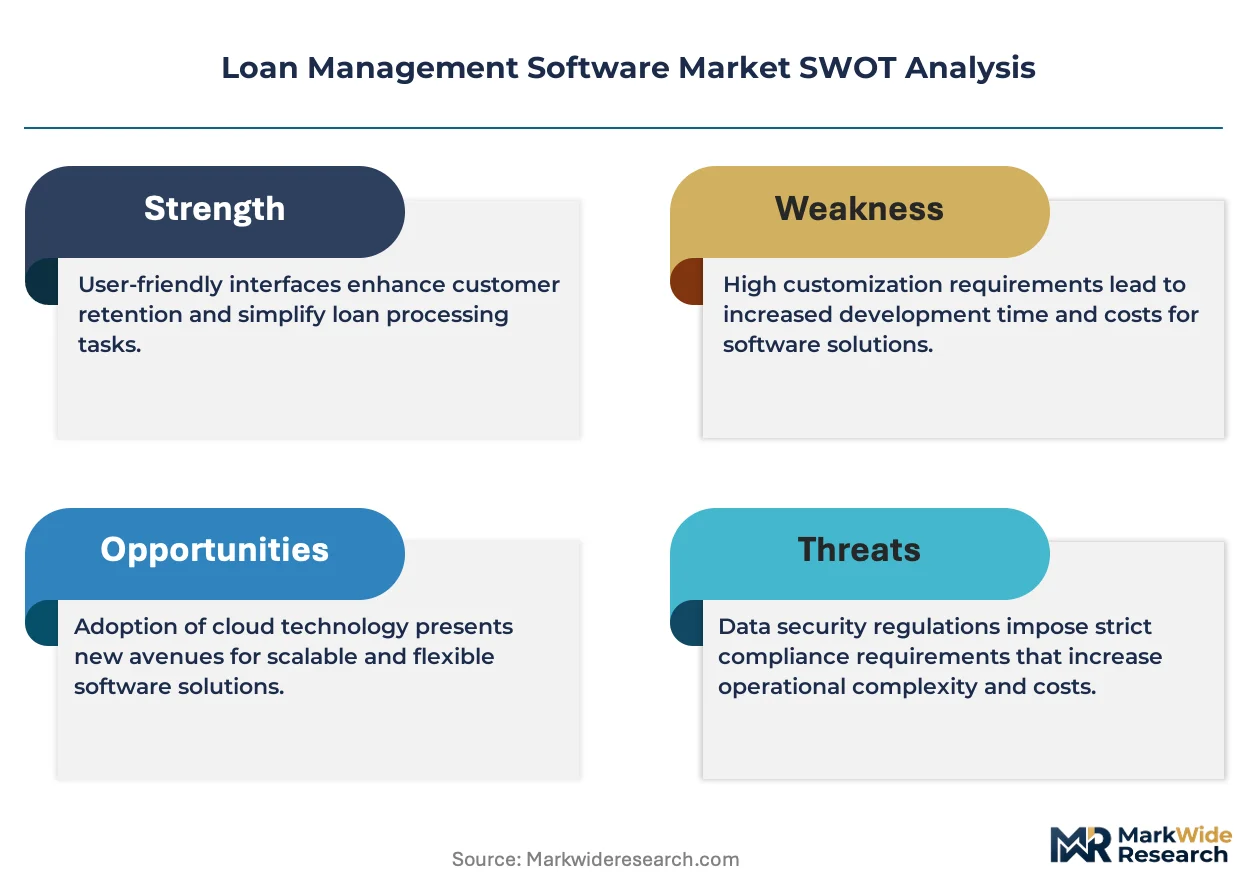
Cloud-native architecture is compressing deployment timelines for loan management platforms, forcing incumbent vendors to re-platform or cede mid-market share to composable banking specialists. This structural shift is redistributing margin pools from perpetual license vendors toward subscription-based API-first providers.
Growth Catalysts
- Open Banking API Mandates:The European Banking Authority's framework compels lenders to expose standardized interfaces, creating procurement urgency for middleware-capable loan platforms.
- Credit Union Consolidation:North American cooperative lenders are pooling technology budgets to replace aging core systems, generating concentrated demand for multi-tenant servicing solutions.
- Embedded Finance Integration:Non-bank platforms—auto dealers, healthcare providers, e-commerce marketplaces—are white-labeling origination workflows, expanding addressable market beyond traditional financial institutions.
Market Restraints
- Data Residency Compliance:GDPR and emerging state-level US privacy statutes fragment cloud deployment options, forcing redundant infrastructure in multiple jurisdictions.
- Core System Entrenchment:Tier-one banks operate on decades-old COBOL architectures where loan module replacement carries catastrophic operational risk.
- Specialized Talent Scarcity:DevOps engineers with both financial services domain knowledge and Kubernetes expertise command compensation premiums that inflate implementation costs.
Strategic Opportunities
- Central Bank Digital Currency Pilots:The European Central Bank and Federal Reserve experimentation programs will require programmable loan contracts with real-time settlement hooks.
- Mortgage Stress-Testing Automation:Regulatory capital requirements for interest rate risk are driving demand for integrated asset-liability management modules.
- Alternative Data Scoring:Cash-flow underwriting using open banking transaction streams enables thin-file borrower segments previously excluded from automated decisioning.
Industry Challenges
- Interoperability Debt:Point-solution vendors face escalating integration costs connecting to heterogeneous core banking systems across client portfolios.
- Audit Trail Fragmentation:Jurisdictional variations in FFIEC examination standards versus EBA technical standards force product engineering bifurcation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loan Management Software Market |
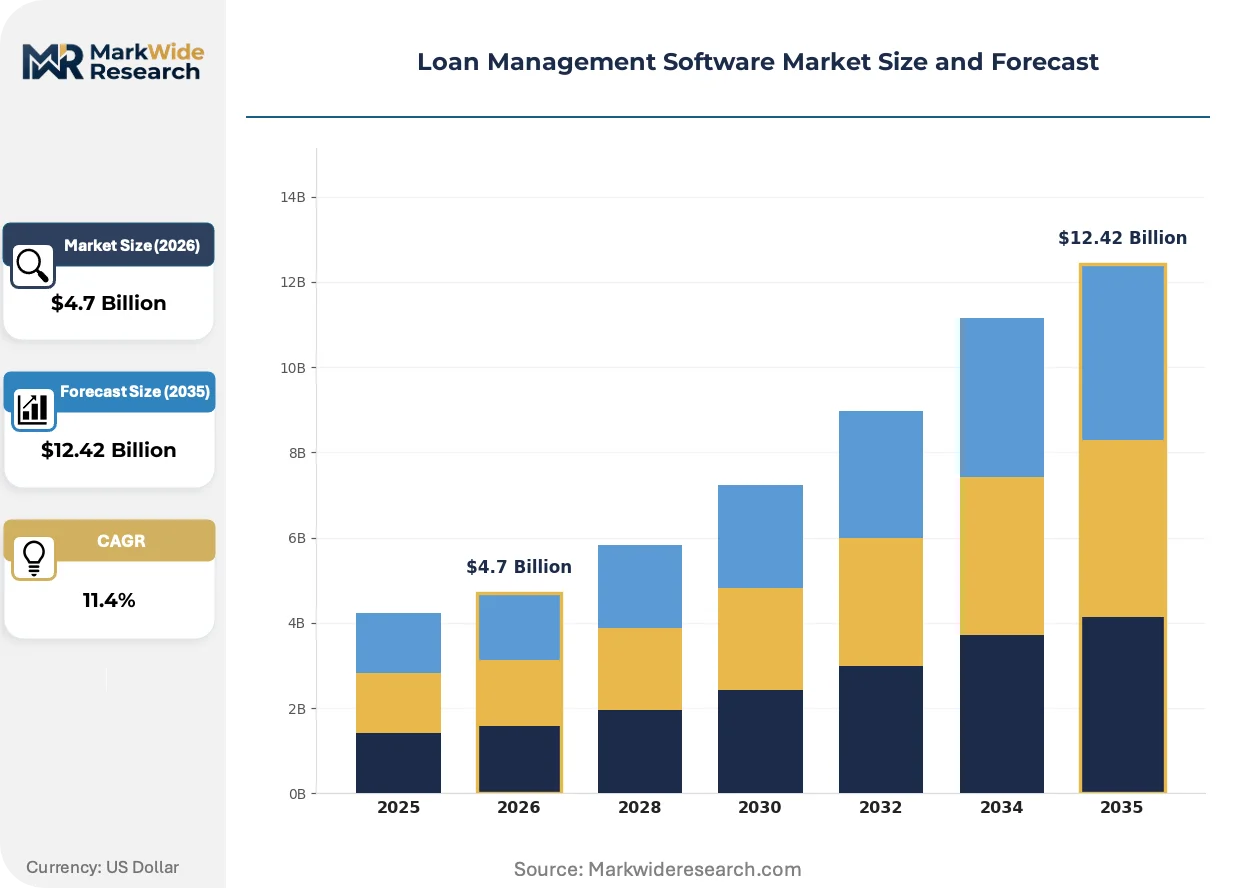
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web-Based, Cloud-Based, On-Premise, Mobile Applications End User: Financial Institutions, Credit Unions, Banks, Mortgage Lenders Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Site Solution: Loan Origination, Loan Servicing, Risk Management, Compliance Management |
| Companies Covered | HES FinTech, TurnKey Lender, Mambu, ABLE Platform, LendFoundry, LoanPro, Finastra, Sopra Banking Software, Temenos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loan Management Software Market Shifts & Advancements
Distributed ledger infrastructure is penetrating loan servicing operations, restructuring how collateral tracking and securitization workflows execute. This technological insertion is compressing settlement cycles and challenging incumbent custody arrangements.
Blockchain-based smart contract protocols are decentralizing escrow and payment distribution functions previously centralized in servicing shops. Mid-size mortgage lenders in Germany and the United Kingdom are piloting these systems for fractionalized loan participation structures. The technology is decentralizing trust mechanisms, reducing correspondent banking dependencies in cross-border syndication.
The EU AI Act's risk-based classification framework is mandating algorithmic explainability for automated credit decisioning above defined thresholds. Vendors must now embed model interpretability layers and human-in-the-loop overrides for high-risk lending categories. Subprime auto and buy-now-pay-later segments face the steepest compliance engineering burden.
Subscription pricing for origination platforms is displacing per-loan transaction fees among fintech lenders seeking predictable unit economics. This shift compresses vendor revenue visibility while accelerating customer acquisition among capital-constrained challengers. The United States exhibits the fastest adoption velocity, particularly in venture-backed consumer lending verticals.
Loan Management Software Market Segmentation
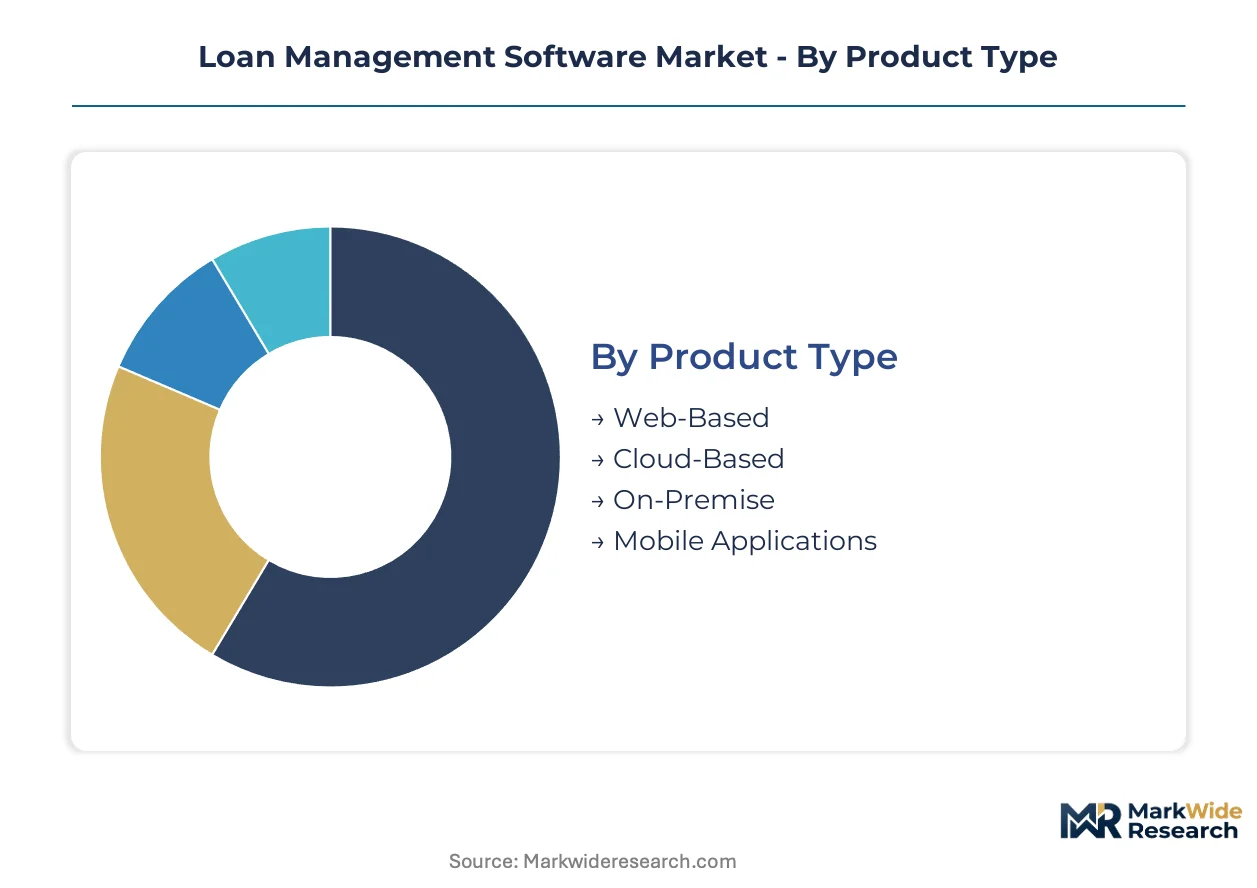
Loan management software procurement patterns diverge sharply by institutional maturity and regulatory exposure. Deployment architecture and solution depth separate tier-one banks from emerging fintech challengers. Understanding these fault lines reveals where margin pools concentrate and which segments face commoditization pressure.
Product Type:
Buyers in this category differentiate by IT infrastructure legacy and capital intensity for data center ownership.
- Cloud-Based:Multi-tenant SaaS architectures deliver elastic compute for seasonal origination volumes without captive server investment. German and United Kingdom lenders are migrating core servicing workloads here to satisfy GDPR data residency through EU-sovereign cloud zones.
- Web-Based:Browser-accessible platforms with lighter client-side requirements suit credit union consolidation scenarios where IT headcount is constrained. North American cooperative lenders favor these for rapid deployment across merged entity networks.
- On-Premise:Perpetual-license deployments persist among tier-one banks with COBOL core dependencies requiring air-gapped loan modules.
- Mobile Applications:Native iOS and Android origination interfaces target field-based relationship managers at commercial lending divisions.
Cloud-Based leads volumes today; Mobile Applications is gaining share fastest.
End User:
Institutional type determines compliance burden sophistication and integration complexity tolerance.
- Banks:Universal and commercial banks require modular architectures that interoperate with treasury, payments, and trade finance systems. Stress-testing automation for interest rate risk drives procurement of asset-liability management modules.
- Credit Unions:Cooperative structures in the United States and Canada are pooling technology budgets to replace aging core systems, generating concentrated demand for multi-tenant servicing solutions with shared compliance engineering.
- Financial Institutions:Captive finance arms of auto manufacturers and equipment lessors need white-label origination workflows for embedded finance integration.
- Mortgage Lenders:Specialized originators face heightened capital requirements for interest rate risk, driving demand for integrated hedging and servicing capabilities.
Banks dominate revenue concentration; Credit Unions show the steepest expansion trajectory.
Deployment:
Infrastructure sovereignty requirements fragment procurement patterns across jurisdictional boundaries.
- Public Cloud:Shared infrastructure from hyperscale providers offers lowest unit economics for fintech lenders with venture-backed growth mandates. United States consumer lending verticals exhibit fastest adoption velocity here.
- Private Cloud:Single-tenant dedicated environments satisfy German and French supervisory requirements for critical financial infrastructure separation from multi-tenant workloads.
- Hybrid Cloud:Burst capacity configurations let mortgage servicers retain sensitive borrower data on-premises while offloading batch processing to public infrastructure.
- On-Site:Fully captive data centers persist where central bank audit protocols mandate physical control over loan ledger systems.
Public Cloud commands the largest installed base; Private Cloud is climbing the fastest.
Solution:
Workflow depth and regulatory touchpoint density separate high-margin modules from commodity functionality.
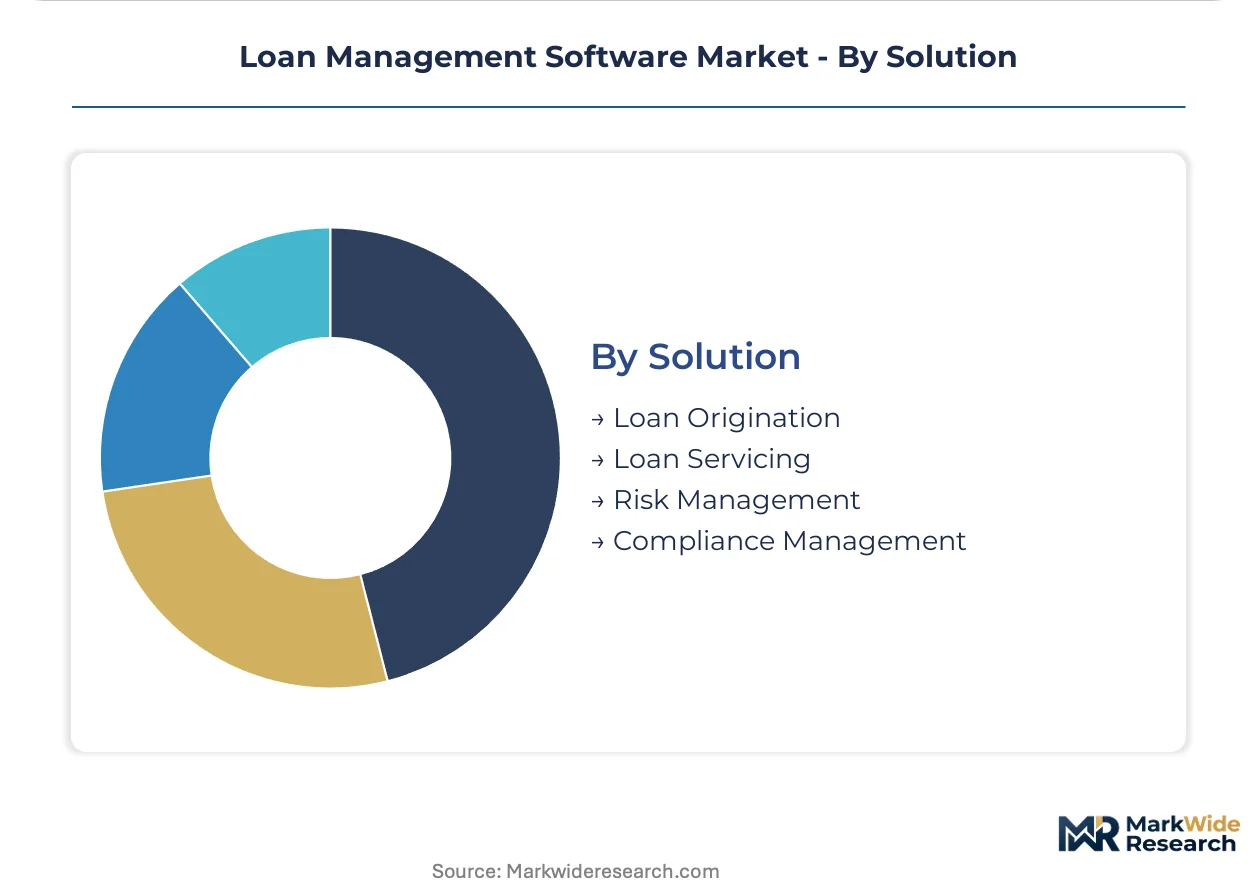
- Loan Origination:Automated decisioning engines with real-time credit bureau API connectivity and configurable workflow orchestration for jurisdictional compliance. Subscription pricing is displacing per-loan transaction fees among capital-constrained challengers.
- Loan Servicing:Payment processing, escrow administration, and collections workflows generate recurring revenue streams with high switching costs. Blockchain-based smart contract protocols are decentralizing escrow functions previously centralized here.
- Risk Management:Model interpretability layers and human-in-the-loop overrides for high-risk lending categories face EU AI Act compliance engineering mandates.
- Compliance Management:Audit trail generation for FFIEC examination standards and EBA technical standards with granular consent management for cross-border data restrictions.
Loan Servicing anchors revenue stability; Risk Management is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor deployment strategies as GDPR compliance costs in the European Union diverge from United States data governance frameworks. Cloud infrastructure investments are migrating toward jurisdictions offering supervisory clarity for financial software operations.
United States
Credit union consolidation across the Upper Midwest and Southeast is generating concentrated procurement for multi-tenant servicing platforms. The FFIEC examination standards mandate granular audit trails that elevate compliance engineering costs for vendors. Dallas and Charlotte financial services clusters host implementation teams serving cooperative lenders replacing legacy core systems.
Germany
Private cloud deployments dominate as BaFin supervisory requirements mandate critical infrastructure separation from multi-tenant workloads. The EU AI Act's risk-based classification framework compels algorithmic explainability investments for automated credit decisioning. Frankfurt's fintech corridor anchors development activity for programmable loan contracts tied to central bank digital currency pilots.
United Kingdom
Open banking API mandates from the Financial Conduct Authority accelerate middleware procurement for interoperability compliance. Mortgage stress-testing automation requirements drive demand for integrated asset-liability management modules. London's regulatory technology cluster concentrates vendors embedding model interpretability layers for high-risk lending categories.
Canada
Provincial credit union federations in Ontario and British Columbia are pooling technology budgets for cloud-native core replacements. OSFI capital adequacy guidelines shape procurement criteria for integrated risk management modules. Toronto's financial services hub hosts implementation specialists serving cooperative lenders with constrained IT headcount.
India
RBI guidelines on digital lending platforms are accelerating adoption of automated origination workflows among non-bank financial companies. The central bank's regulatory sandbox framework permits controlled experimentation with alternative data scoring models. Mumbai and Bangalore technology corridors concentrate development talent for cash-flow underwriting using open banking transaction streams.
Loan Management Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue composable banking architectures and API-first delivery models. The vendor landscape segments across three maturity tiers: legacy core system incumbents with correspondent banking networks, cloud-native specialists with subscription pricing, and vertical-focused challengers targeting embedded finance integration. Strategic differentiation concentrates on M&A activity consolidating mid-market servicing capabilities and technology licensing arrangements accelerating geographic expansion without direct implementation investment.
Among European-headquartered platform providers, Mambu and Temenos occupy positions reflecting divergent architectural philosophies. Mambu exemplifies the composable banking archetype with cloud-native deployment advantages across continental jurisdictions. Temenos anchors the universal banking platform segment scaled across tier-one institutions with extensive treasury connectivity requirements. Finastra sits within the correspondent banking specialist tier, leveraging established networks to maintain servicing workflow integration density.
| Leading Market Players |
|---|
| HES FinTech |
| TurnKey Lender |
| Mambu |
| ABLE Platform |
| LendFoundry |
| LoanPro |
| Finastra |
| Sopra Banking Software |
| Temenos |
| Others |
Supply & Pricing Matrix
Cloud compute cost indices from hyperscale providers cascade through loan management software supply chains, compressing subscription tiers as infrastructure savings propagate from IaaS layers into SaaS pricing structures for mid-market lenders.
Pricing Analysis
Direct-to-bank enterprise discounts anchor the upper tier, while distributor margins of twelve to eighteen percent inflate mid-market procurement costs. SaaS subscription tiers stratify across premium API-first configurations, standard multi-tenant deployments, and economy web-based packages. Price differentiation hinges on GDPR certification grade and customization depth for jurisdictional compliance. Pricing pressure stems from open-source core banking alternatives eroding perpetual license valuations. Credit unions exhibit highest price sensitivity; tier-one banks prioritize integration reliability over unit cost.
Supply Chain Analysis
Specialized engineering talent supply rests on Estonia, India, and Poland as primary development corridor sources. Cloud infrastructure components draw from hyperscale data center networks across Germany, Ireland, and the United States. Kubernetes orchestration expertise and financial services domain knowledge constitute critical input dependencies. Supply chain risk centers on single-source vulnerability for COBOL modernization specialists nearing retirement. Distribution runs through systems integrators and direct vendor implementation teams serving regional financial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Loan management software procurement operates as a geographic-arbitrage play where GDPR compliance engineering costs in Germany diverge from lighter-touch state-level privacy frameworks in the United States, creating deployment cost spreads of forty to sixty percent for equivalent functionality.
For Market Incumbents: Anticipate composable banking specialists eroding mid-market share through faster API-layer integration. Defensive consolidation of servicing workflow capabilities in credit union-heavy geographies like the Upper Midwest preserves recurring revenue streams. Investment in EU AI Act model interpretability tooling addresses emerging compliance engineering mandates before challengers capture standardization rents. For New Entrants and Emerging Players: Credit union technology pooling in Ontario and British Columbia offers the most penetrable white-space entry point. Embedded finance integration for auto dealer captive finance arms provides second-mover advantage in white-label origination workflows. Channel partnerships with regional systems integrators accelerate implementation velocity without captive professional services buildout. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-tenant servicing capabilities overlap across merged cooperative lender portfolios. Long-term viability favors vendors with programmable contract architectures positioned for central bank digital currency settlement hooks. Acquisition target archetypes include vertical-focused challengers with embedded finance integration density. The signal to watch is regulatory sandbox participation rates as leading indicators of procurement criteria shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-layer connectivity to open banking frameworks satisfies EBA mandates across EU jurisdictions. |
| Acquisition of Specialist Firm | COBOL modernization capabilities address tier-one bank core system entrenchment barriers. |
| Geographic Expansion | EU-sovereign cloud zones enable GDPR-compliant servicing workloads for German lenders. |
| Product Launch | Model interpretability layers embed EU AI Act compliance for high-risk lending categories. |
| Strategic Partnership | Central bank digital currency pilot participation positions vendors for programmable contract demand. |
Research Methodology
Direct dialogue with CTOs at tier-one banks, credit union technology committees, fintech platform engineers, and regulatory compliance officers grounded qualitative insights. Secondary validation drew from FFIEC examination guidance, EBA technical standards documentation, SEC 10-K filings of listed financial software vendors, and hyperscaler infrastructure capex disclosures. Bottom-up deployment volume estimates triangulated against top-down IT spending benchmarks across the analysis window.
Segment-level outputs reflect modeled trajectories across deployment architecture, institutional type, solution depth, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted adoption curves incorporating open banking mandate compliance deadlines and credit union consolidation timelines. Forecast inputs included central bank digital currency pilot progression rates and EU AI Act implementation phase schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory sandbox outcomes and core banking modernization failure rates at tier-one institutions. Forecasts reflect documented assumptions about interoperability standard adoption velocity and GDPR enforcement consistency. A small set of named triggers—CBDC settlement protocol standardization, subprime auto lending regulatory classification shifts, and hyperscale cloud pricing recalibration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Global Automotive Rental and Leasing Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
Montenegro Home Mortgage Finance Market
Loans and Leasing
Digital Lending Platform Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Europe Home Mortgage Finance Market
Loans and Leasing
Refinancing Market
Loans and Leasing
Global Healthcare Equipment Leasing Market
Loans and Leasing
USA Home Loan Market
Loans and Leasing
Europe Auto Loan Market
Loans and Leasing
Peer-To-Peer Lending Market
Loans and Leasing
Asset-Based Lending Market
Loans and Leasing
China Home Loan Market
Loans and Leasing
Europe Mortgage Lending Market
Loans and Leasing
United States Car Loan Market
Loans and Leasing
Global Automotive Fleet Leasing Market