
 Mexico Home Equity Lending Market | 2026-2036
Mexico Home Equity Lending Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Home Equity Lending Market Foresight
Buyer concentration among existing homeowners is realigning toward first-time property holders entering the equity release market. MEXLend leverages its specialized cross-border documentation expertise to serve foreign nationals purchasing in coastal zones. Fairway Independent Mortgage sustains operational scale through correspondent lending relationships with Mexican depository institutions. Bank of America competes by extending its US-based client relationships into Baja California and Jalisco retirement corridors.
Home equity lending encompasses secured credit facilities collateralized by residential real property where the outstanding mortgage balance remains subordinate to the first-lien obligation, typically structured with loan-to-value thresholds between seventy and eighty percent. These instruments primarily finance property improvements, education expenditures, or liability consolidation for borrowers with established payment histories. Fixed-rate products dominate origination volumes among risk-averse retirees seeking predictable amortization schedules, while variable-rate structures attract investors exploiting short-term arbitrage between borrowing costs and rental yields. Online lending platforms represent the fastest-expanding distribution channel as digital onboarding reduces notarization burdens and accelerates collateral appraisal workflows.
Banco de Mexico monetary policy frameworks and Comision Nacional Bancaria y de Valores prudential standards jointly govern capital reserve requirements and consumer disclosure protocols for secured residential lending. CNBV transparency mandates shape product standardization by requiring standardized total annual cost disclosures that facilitate cross-lender comparison. Stakeholders must monitor how central bank benchmark rate trajectories alter the relative attractiveness of fixed versus floating rate structures and corresponding prepayment risk profiles.
Market Dynamics
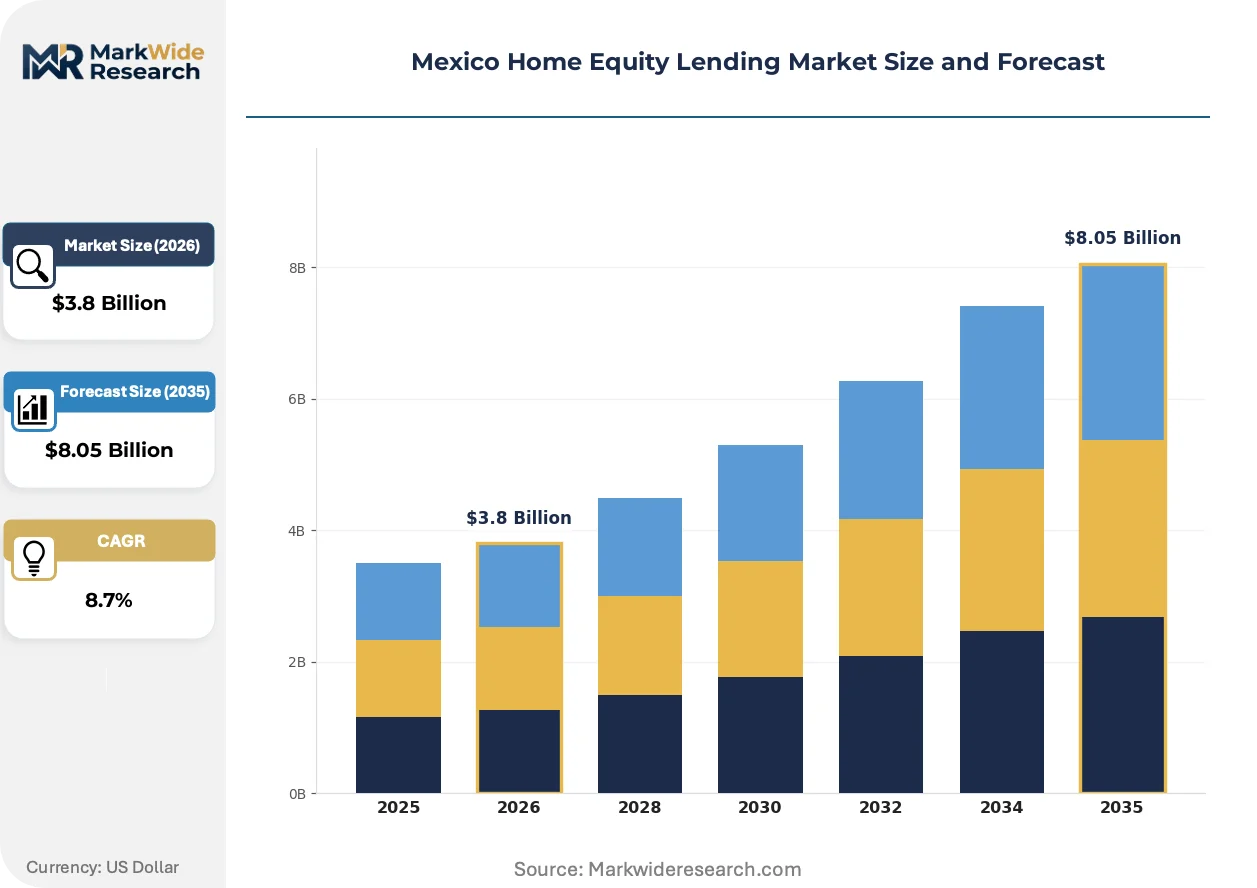
Banco de Mexico's benchmark rate trajectory is compressing origination margins and forcing lenders to restructure product portfolios toward fixed-rate instruments, fundamentally altering competitive positioning across the secured residential credit landscape.
Growth Catalysts
- CNBV Transparency Mandates:Standardized total annual cost disclosures enable direct cross-lender comparison, accelerating borrower decision velocity and reducing origination friction.
- Digital Onboarding Infrastructure:Automated collateral appraisal workflows and electronic notarization reduce processing cycles from weeks to days, capturing demand from time-sensitive renovation borrowers.
- Middle-Income Property Renovation Demand:Households in Mexico City and State of Mexico seek financing for residential improvements, creating sustained origination volume in high-LTV corridors.
Market Restraints
- Variable-Rate Exposure Concentration:Banco de Mexico policy tightening exposes portfolios to payment shock risk, constraining product availability for income-sensitive borrowers.
- First-Lien Subordination Complexity:Senior mortgage holder consent requirements and inter-creditor agreement negotiations extend time-to-fund beyond borrower tolerance thresholds.
- Collateral Valuation Volatility:Residential price dispersion across Mexican coastal zones and interior markets complicates consistent LTV underwriting standards.
Strategic Opportunities
- Foreign National Coastal Financing:Cross-border documentation specialization unlocks origination volume from US and Canadian retirees purchasing in Baja California and Jalisco corridors.
- Correspondent Lending Channel Expansion:Partnerships with Mexican depository institutions enable foreign lenders to access local funding capacity without branch infrastructure.
- Fixed-Rate Product Innovation:Duration-matched funding structures and interest rate hedging instruments address retiree demand for predictable amortization schedules.
Industry Challenges
- Appraiser Certification Bottlenecks:Limited pool of CNBV-registered property valuers extends collateral verification timelines, constraining digital platform velocity promises.
- Legacy Core System Integration:Mexican depository institutions operate on outdated loan origination platforms that resist API connectivity with fintech distribution partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Home Equity Lending Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Fixed Rate, Variable Rate, Home Improvement, Debt Consolidation Borrower Type: First-Time Homeowners, Existing Homeowners, Investors, Retirees Loan Term: Short-Term, Medium-Term, Long-Term, Flexible Term Distribution Channel: Online Lending Platforms, Traditional Banks, Credit Unions, Mortgage Brokers |
| Companies Covered | Fairway Independent Mortgage, MEXLend, Longbridge Financial LLC, Bank of America, MEX Home, American Advisors Group, Liberty Home Equity Solutions, LoanDepot LLC, High Tech Lending, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Home Equity Lending Market Shifts & Advancements
Digital distribution infrastructure is compressing origination economics and enabling non-bank entrants to capture market share from traditional depository institutions. Three converging developments are restructuring competitive dynamics.
Automated valuation models powered by satellite imagery and municipal transaction databases are consolidating property appraisal workflows. Mid-sized lenders in Mexico City adopt these tools to reduce per-loan underwriting costs. The technology is consolidating appraisal vendor relationships into platform-scale partnerships that exclude smaller regional valuers.
Banco de Mexico's macroprudential reserve requirements for variable-rate exposures tighten capital treatment for floating products. Lenders restructure portfolios toward fixed-rate instruments with longer-duration funding. Jalisco and Baja California retirement corridors see accelerated fixed-rate origination as foreign nationals seek payment certainty.
Direct-to-consumer digital platforms disintermediate traditional mortgage broker networks that historically dominated borrower acquisition. Coastal zone property buyers now initiate applications through mobile-optimized interfaces. This channel compression is most visible in Quintana Roo and Nayarit where foreign purchaser concentration supports specialized platform economics.
Mexico Home Equity Lending Market Segmentation
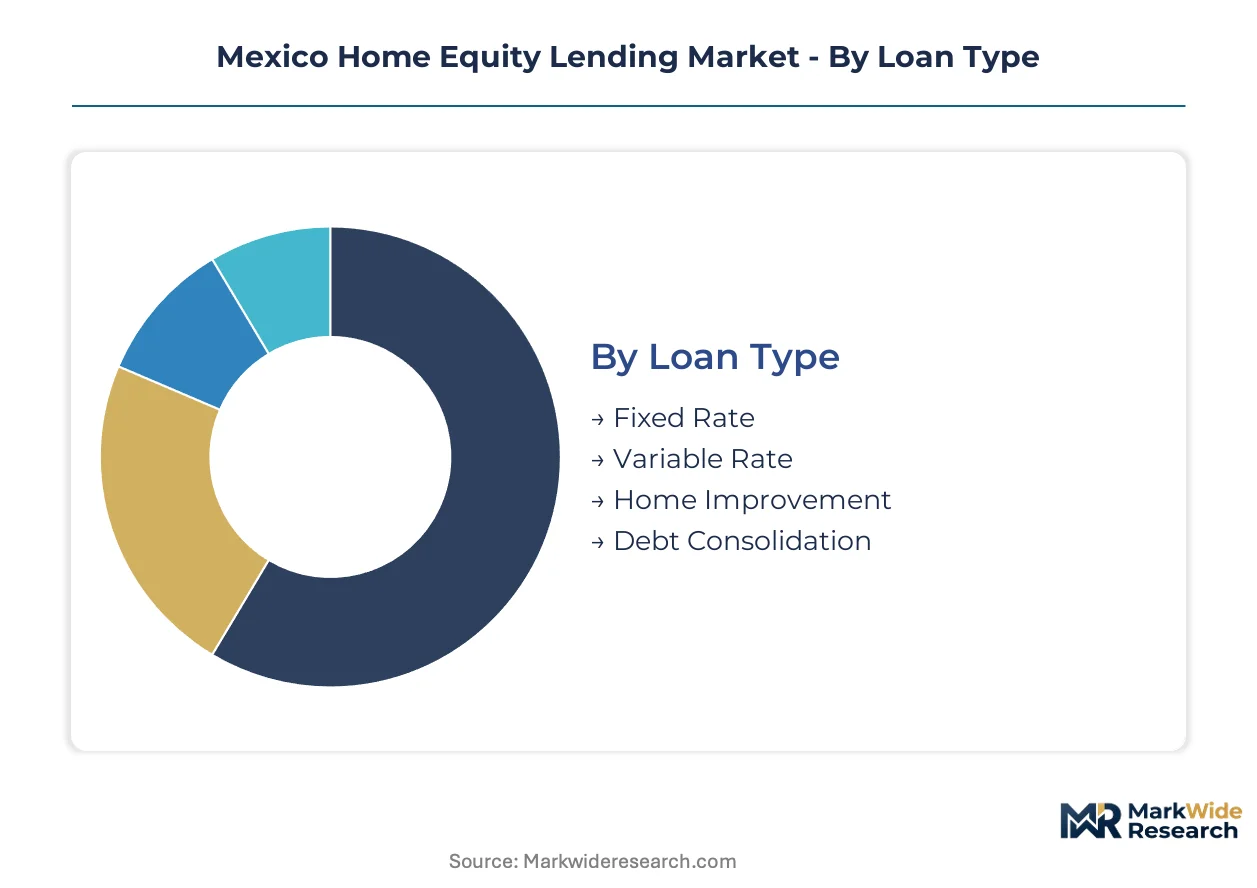
Mexico Home Equity Lending Market segmentation reveals how regulatory capital treatment and borrower risk profiles interact to shape product availability. Distinct origination economics emerge across loan structures, with Banco de Mexico policy transmission varying sharply by segment.
Loan Type:
CNBV disclosure mandates apply uniformly, yet Banco de Mexico macroprudential reserve requirements create divergent capital burdens across rate structures and use-of-proceeds categories.
- Fixed Rate:Duration-matched funding structures lock borrowing costs for the full amortization schedule. Retirees in Mexico City and State of Mexico corridors favor these instruments for payment predictability amid monetary policy uncertainty.
- Variable Rate:Benchmark-tied structures reprice with Banco de Mexico rate adjustments, exposing borrowers to payment shock. Investors exploiting rental yield arbitrage concentrate demand in high-appreciation coastal zones despite tightening reserve requirements.
- Home Improvement:Proceeds finance residential renovation and property enhancement. Middle-income households in high-LTV corridors drive origination volume.
- Debt Consolidation:Liability restructuring applications require enhanced income verification. CNBV consumer protection protocols mandate extended cooling-off periods.
Leading the category by volume: Fixed Rate. Growing fastest: Home Improvement.
Borrower Type:
Credit bureau scoring thresholds and payment history requirements stratify approval rates across demographic cohorts, with foreign nationals facing additional documentation burdens.
- First-Time Homeowners:Entry-level borrowers with limited equity accumulation. Digital onboarding platforms reduce friction for this credit-thin segment.
- Existing Homeowners:Established property holders with documented payment histories. This cohort commands preferential LTV thresholds in Mexico City metropolitan area.
- Investors:Rental yield-focused borrowers seeking leverage against multiple properties. Variable-rate products attract this segment in Baja California and Jalisco retirement corridors.
- Retirees:Fixed-income borrowers prioritizing amortization certainty. Pension-backed repayment structures require specialized underwriting.
Dominant by origination value: Existing Homeowners. Expanding most quickly: First-Time Homeowners.
Loan Term:
Duration selection interacts with borrower life stage and income stability, with longer maturities commanding duration-matched funding premiums.
- Short-Term:Five-to-seven year structures for liquidity bridge financing. Investors favor these for rapid equity release.
- Medium-Term:Ten-to-fifteen year amortization schedules balance payment affordability with total interest cost. Middle-income renovation borrowers cluster here.
- Long-Term:Twenty-to-thirty year structures minimize periodic payments. Retirees seeking legacy planning instruments drive coastal zone demand.
- Flexible Term:Prepayment-option structures with recasting provisions. CNBV disclosure mandates require explicit total-cost scenarios.
Highest volume concentration: Medium-Term. Steepest expansion trajectory: Flexible Term.
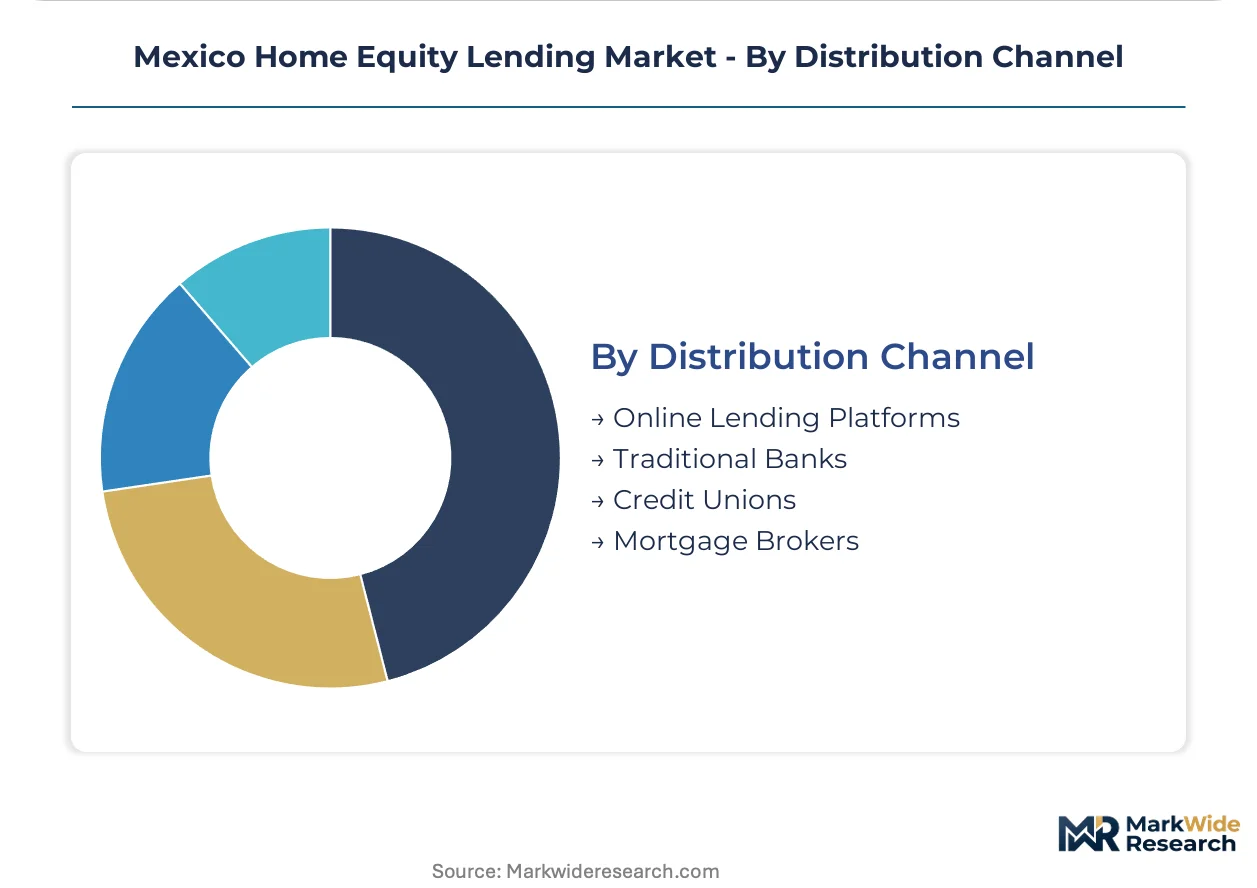
Distribution Channel:
Channel economics determine origination cost structures, with digital platforms compressing per-loan expenses while correspondent relationships extend geographic reach.
- Online Lending Platforms:Automated collateral appraisal and electronic notarization reduce processing cycles. Quintana Roo and Nayarit foreign purchasers initiate applications through mobile-optimized interfaces.
- Traditional Banks:Deposit-funded balance sheet lending with branch-based origination. Mexico City and State of Mexico maintain concentration of physical infrastructure.
- Credit Unions:Member-owned institutions with community-based underwriting. Limited presence in coastal foreign-purchaser markets.
- Mortgage Brokers:Intermediary networks facing disintermediation pressure from direct-to-consumer platforms. Regulatory licensing requirements vary by state jurisdiction.
Leading by transaction count: Traditional Banks. Gaining share fastest: Online Lending Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential property collateral quality varies sharply across Mexican sub-markets, with metropolitan centers offering superior loan-to-value support while coastal corridors attract cross-border capital flows.
Mexico City Metro
Established homeowners in Benito Juárez and Miguel Hidalgo boroughs command preferential LTV thresholds exceeding seventy-five percent. Banco de México benchmark rate adjustments transmit immediately to variable-rate originations here. Digital onboarding platforms concentrate technical infrastructure in this corridor to capture renovation-driven demand from middle-income households.
Jalisco
Lake Chapala and Puerto Vallarta retirement zones attract fixed-rate product demand from US and Canadian purchasers seeking payment certainty. CNBV disclosure mandates apply uniformly to foreign-national applications, extending documentation timelines. Correspondent lending partnerships with Guadalajara-based depository institutions extend funding capacity without branch infrastructure.
Nuevo León
Monterrey's industrial employment base supports stable debt-service ratios among existing homeowners. The state's central bank policy transmission operates through regional banking networks with concentrated variable-rate exposure. Appraiser certification bottlenecks extend collateral verification timelines despite automated valuation model adoption.
Baja California
Ensenada and Rosarito coastal markets specialize in cross-border documentation for foreign retirees. Bank of America extends US-based client relationships into this corridor. First-lien subordination complexity with US-originated primary mortgages constrains product structuring flexibility.
Yucatán Peninsula
Mérida's emerging property market attracts investor demand for rental yield arbitrage. Variable-rate structures dominate despite Banco de México policy tightening. Limited CNBV-registered valuer presence extends appraisal timelines beyond digital platform velocity promises.
Mexico Home Equity Lending Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital distribution and cross-border specialization. The vendor base organizes around three strategic archetypes: US-based lenders extending client relationships southward, specialized cross-border documentation servicers, and Mexican depository institutions with deposit-funded balance sheets. Dominant competitive moves include correspondent lending partnerships that bypass branch infrastructure requirements and fixed-rate product innovation targeting retiree payment certainty preferences.
Within the cross-border specialization tier, MEXLend and MEX Home occupy positions anchored by coastal zone documentation expertise. Fairway Independent Mortgage and Bank of America exemplify the US-relationship-extension archetype, leveraging existing client portfolios to originate in Baja California and Jalisco corridors. Longbridge Financial LLC sits within the fixed-rate product innovation segment, addressing duration-matched funding demand from retirement corridor borrowers.
| Leading Market Players |
|---|
| Fairway Independent Mortgage |
| MEXLend |
| Longbridge Financial LLC |
| Bank of America |
| MEX Home |
| American Advisors Group |
| Liberty Home Equity Solutions |
| LoanDepot LLC |
| High Tech Lending |
| Others |
Supply & Pricing Matrix
Fixed-rate premium positioning versus variable-rate commodity availability splits the Mexico home equity lending market into divergent origination economics, with payment-certainty bundling commanding duration-matched funding premiums while benchmark-tied structures face compressed margins from Banco de Mexico reserve requirements. This bifurcation concentrates pricing power among lenders with access to long-duration liabilities, while variable-rate specialists absorb capital cost volatility through correspondent relationships with deposit-funded institutions.
Pricing Analysis
Warranty-style payment protection bundling separates premium fixed-rate offerings from unbundled variable-rate products in the Mexico market. Three-tier pricing structure across premium, standard, and economy levels reflects duration-matched funding costs, CNBV compliance certification tiers, and geographic delivery complexity to coastal appraisal zones. Pricing pressure stems from central bank policy tightening that elevates variable-rate capital reserves, squeezing margins on floating products. Retirees in Jalisco and Baja California corridors demonstrate lowest price sensitivity for payment certainty, while middle-income renovation borrowers in Mexico City exhibit highest elasticity to rate spreads.
Supply Chain Analysis
CNBV-registered appraiser certification gates collateral verification capacity, constraining digital platform velocity promises and extending time-to-fund for coastal zone originations. Funding supply concentrates in Mexico, the United States, and Canada, with correspondent relationships drawing from Guadalajara-based depository institutions and US relationship-extension lenders. Raw material dependencies include residential property collateral pipelines, mortgage servicing rights, and duration-matched bond funding. Single-source vulnerability runs through limited CNBV-registered valuer pools. Distribution runs through direct-to-consumer digital platforms, traditional branch networks, and correspondent lending partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
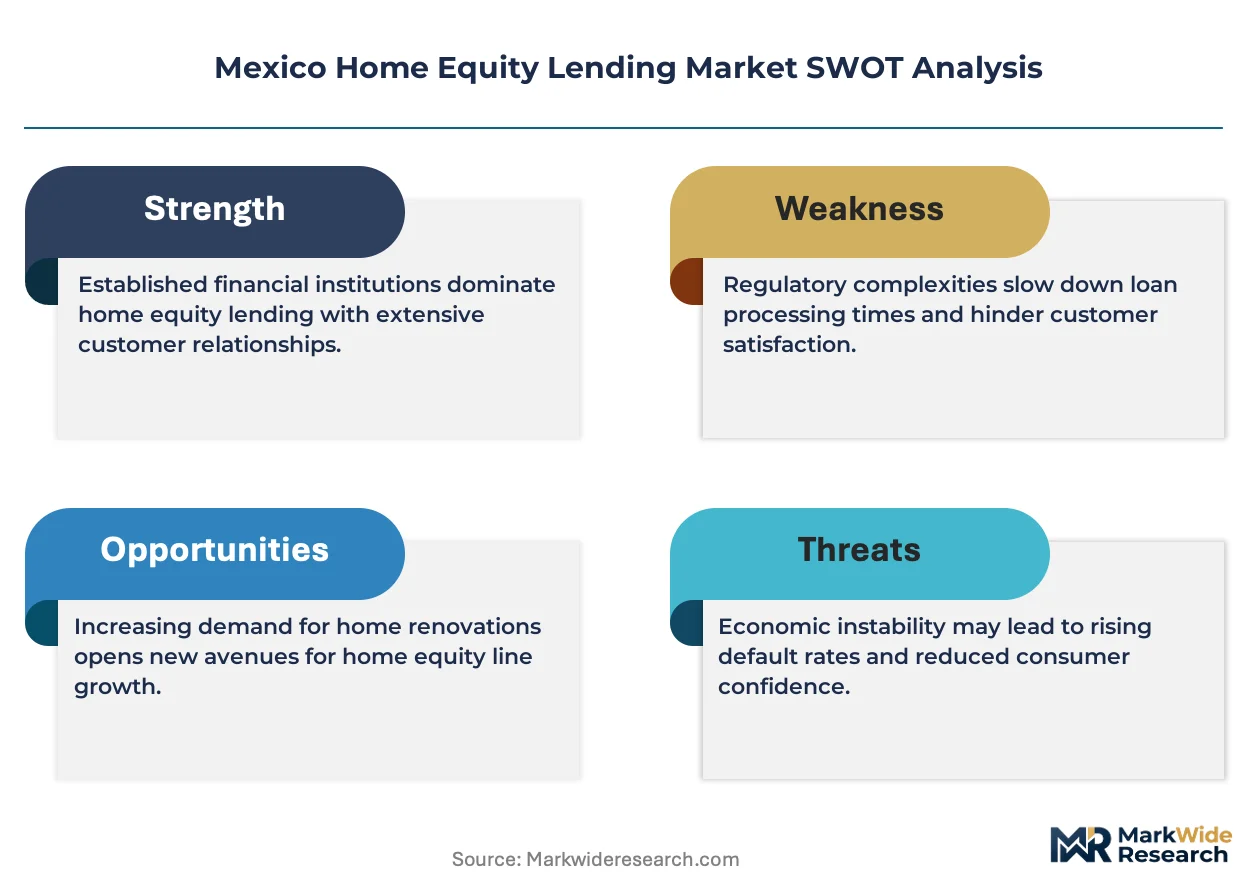
The Mexico home equity lending market operates as a supply-constrained origination environment where CNBV-registered appraiser bottlenecks prop pricing premiums for lenders with expedited collateral verification capabilities.
For Market Incumbents: Extend fixed-rate product innovation into retirement corridors to capture duration-matched funding demand from US and Canadian purchasers seeking payment certainty. Consolidate correspondent lending partnerships with Guadalajara-based depository institutions to secure local funding capacity without branch infrastructure investment. Defend against digital platform disintermediation by embedding automated valuation models that compress appraisal cycles below fintech competitor timelines. For New Entrants and Emerging Players: Automated collateral appraisal technology-first wedge unlocks white-space origination volume in Quintana Roo and Nayarit where foreign purchaser concentration supports specialized platform economics. Target first-time homeowners in Mexico City metropolitan area through mobile-optimized interfaces that reduce documentation friction for credit-thin borrowers. Pursue cross-border documentation specialization as the most penetrable competitive angle, leveraging electronic notarization to accelerate fund disbursement against traditional broker networks. For Investors and Strategic Acquirers: Re-rating potential sits with correspondent lending specialists given Banco de Mexico policy trajectory favoring fixed-rate portfolio restructuring. Long-term viability across the analysis window favors lenders with integrated digital onboarding and coastal zone documentation expertise. Target acquisition archetypes include CNBV-registered appraisal platform operators and duration-hedging capability holders. Monitor central bank benchmark rate stabilization as the inflection signal for variable-rate product reactivation.| Strategic Initiative | Industry Significance |
|---|---|
| Correspondent Lending Partnership | Accesses Guadalajara deposit base without branch infrastructure investment requirements. |
| Fixed-Rate Product Innovation | Addresses retiree demand for payment certainty in Baja California and Jalisco corridors. |
| Automated Valuation Model Deployment | Compresses collateral verification timelines below CNBV-registered appraiser bottleneck constraints. |
| Cross-Border Documentation Specialization | Captures US and Canadian foreign national origination volume in coastal retirement zones. |
| Digital Platform Integration | Disintermediates traditional mortgage broker networks through mobile-optimized borrower acquisition. |
Research Methodology
CNBV regulatory filings, Banco de Mexico monetary policy communications, and Mexican banking association statistical releases formed the secondary backbone for market sizing and origination volume estimation. Primary interviews with home equity lending executives, CNBV compliance officers, correspondent banking relationship managers, and coastal zone mortgage brokers validated product structure assumptions and borrower segmentation boundaries. Bottom-up origination volume triangulation against top-down credit bureau disclosure aggregates ensured cross-verification of market estimates.
Bottom-up modeling of loan origination volumes by rate structure, borrower type, and distribution channel fed into aggregate market value construction across the analysis window. Segmentation dimensions included fixed versus variable rate, first-time versus existing homeowner, short-term versus long-term maturity, and digital platform versus traditional bank channel. CAGRs were derived from regression-adjusted origination trends incorporating Banco de Mexico policy rate trajectories and residential property value appreciation assumptions for Mexico City and coastal corridor sub-markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained central bank tightening or abrupt collateral valuation corrections in coastal zones. Model outputs reflect assumptions regarding CNBV disclosure mandate compliance costs and correspondent lending partnership stability. A model refresh is warranted upon material change in Banco de Mexico benchmark rate trajectory or CNBV macroprudential reserve requirement adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
Florida Digital Lending Market
Loans and Leasing
Automobile Rental and Leasing Market
Loans and Leasing
Alternative Lending Platform Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
Cash Advance Services Market
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
Premium Finance Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
Russia Auto Loan Market
Loans and Leasing
US Home Equity Lending Market
Loans and Leasing
Montenegro Home Mortgage Finance Market
Loans and Leasing
Alternative Lending Market