
 North America Insurance Telematics Market | 2026-2036
North America Insurance Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Insurance Telematics Market Analytics
Fleet buyer concentration among large commercial auto insurers is consolidating around telematics-enabled usage-based insurance programs. Progressive Corporation leverages its Snapshot platform to sustain direct-channel dominance in personal auto telematics. State Farm Mutual Automobile Insurance Company anchors its market position through captive agency distribution integrated with driving behavior data. Cambridge Mobile Telematics competes on smartphone-based data collection, eliminating hardware friction for mid-market carriers.
Insurance telematics encompasses the integrated capture, transmission, and analysis of vehicle operational data—speed, acceleration, braking intensity, mileage, and time-of-day patterns—to inform risk-based insurance pricing and loss prevention. Systems typically combine GPS receivers, accelerometers, and cellular modems transmitting encrypted data to cloud-based actuarial engines for real-time scoring. The software segment leads margin capture, with platforms processing multi-source data streams commanding recurring licensing structures. Smartphone-based installation is displacing aftermarket hardware as the fastest-growing deployment mode, reducing carrier customer acquisition costs while expanding addressable policyholder bases. Data analytics services represent the emerging margin pool, with predictive modeling layers commanding premium positioning as carriers seek claims severity reduction.
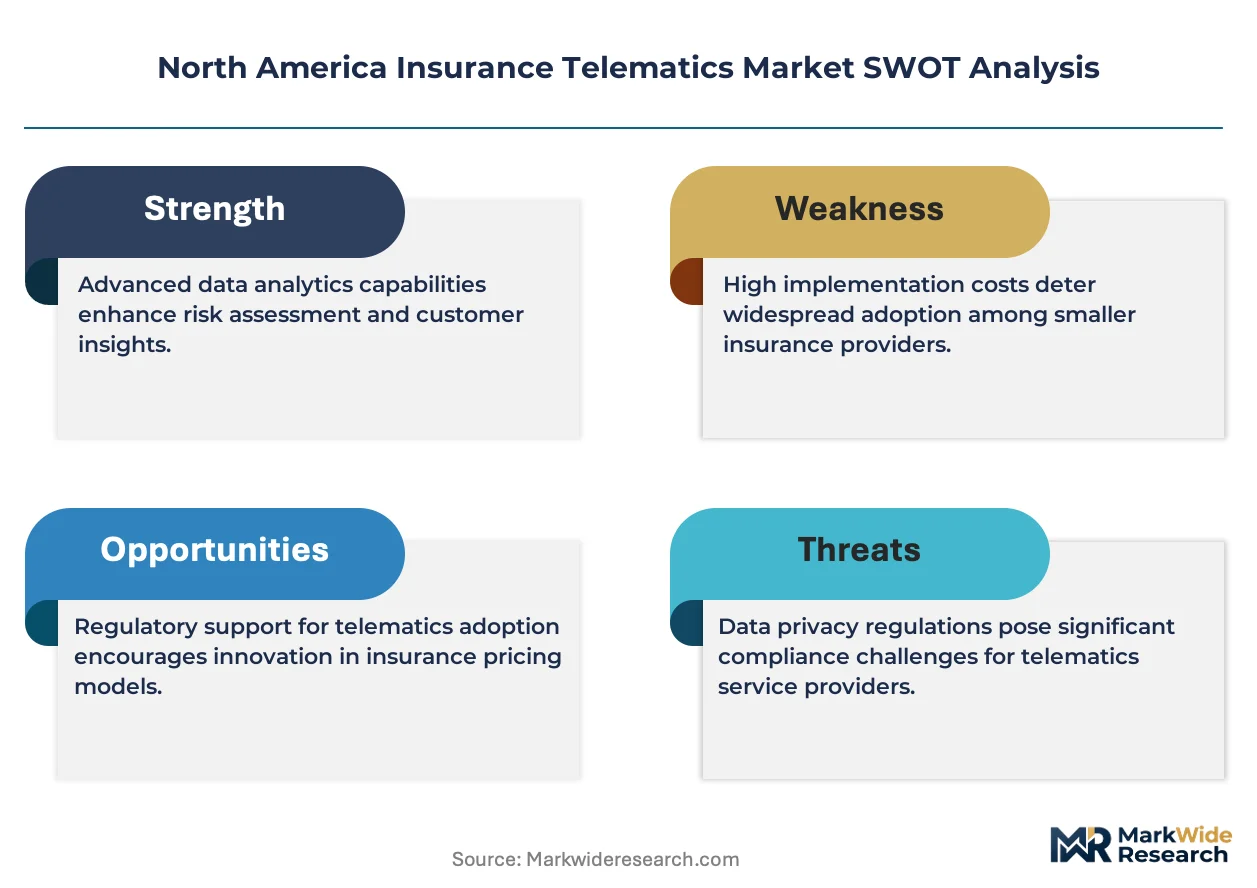
The National Association of Insurance Commissioners coordinates state-level regulatory frameworks governing telematics data use in rate filings, while state insurance departments enforce privacy consent requirements that shape product design. The California Department of Insurance and New York Department of Financial Services maintain distinct prior-approval regimes that delay market entry for novel pricing algorithms. Stakeholders must monitor evolving state-by-state regulatory divergence in data retention limits and algorithmic transparency mandates to align platform investment with enforceable deployment timelines.
Market Dynamics
Smartphone-based data collection is absorbing hardware-dependent deployment models across North American personal auto lines, compressing carrier customer acquisition costs while expanding addressable policyholder bases beyond traditional telematics adopters.
Growth Catalysts
- State-level usage-based insurance frameworks:Regulators in Texas and Ohio have streamlined prior-approval processes for telematics-informed rate filings, accelerating carrier product launches.
- Fleet electrification mandates:California's Advanced Clean Trucks regulation is generating demand for integrated battery-state and driving-behavior monitoring in commercial auto portfolios.
- 5G cellular module cost curves:Hardware economics for embedded modems have shifted threshold pricing, enabling mid-market carriers to launch competitive programs.
Market Restraints
- Silicon supply concentration:GPS receiver and accelerometer chip fabrication concentrates in East Asian foundries, exposing North American hardware vendors to geographic supply risk.
- State privacy consent fragmentation:Divergent data retention limits across California, New York, and Texas force carriers to maintain multiple platform configurations.
- Actuarial talent scarcity:The intersection of predictive modeling and insurance pricing expertise remains structurally undersupplied relative to carrier hiring targets.
Strategic Opportunities
- Canadian provincial expansion:Ontario and Quebec regulatory frameworks are converging toward US state implementation patterns, creating contiguous market entry paths.
- Commercial fleet loss prevention services:Real-time collision avoidance alerts and driver coaching represent unbundled revenue streams beyond premium pricing.
- Usage-based homeowners convergence:Smart home sensor data integration with auto telematics platforms enables cross-line policy bundling and retention mechanics.
Industry Challenges
- Legacy policy administration integration:Carriers with decades-old core systems face API complexity and data mapping friction when connecting telematics platforms to rating engines.
- Algorithmic transparency documentation:State insurance departments increasingly require explainable AI documentation for telematics scoring models, extending actuarial filing preparation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Insurance Telematics Market |
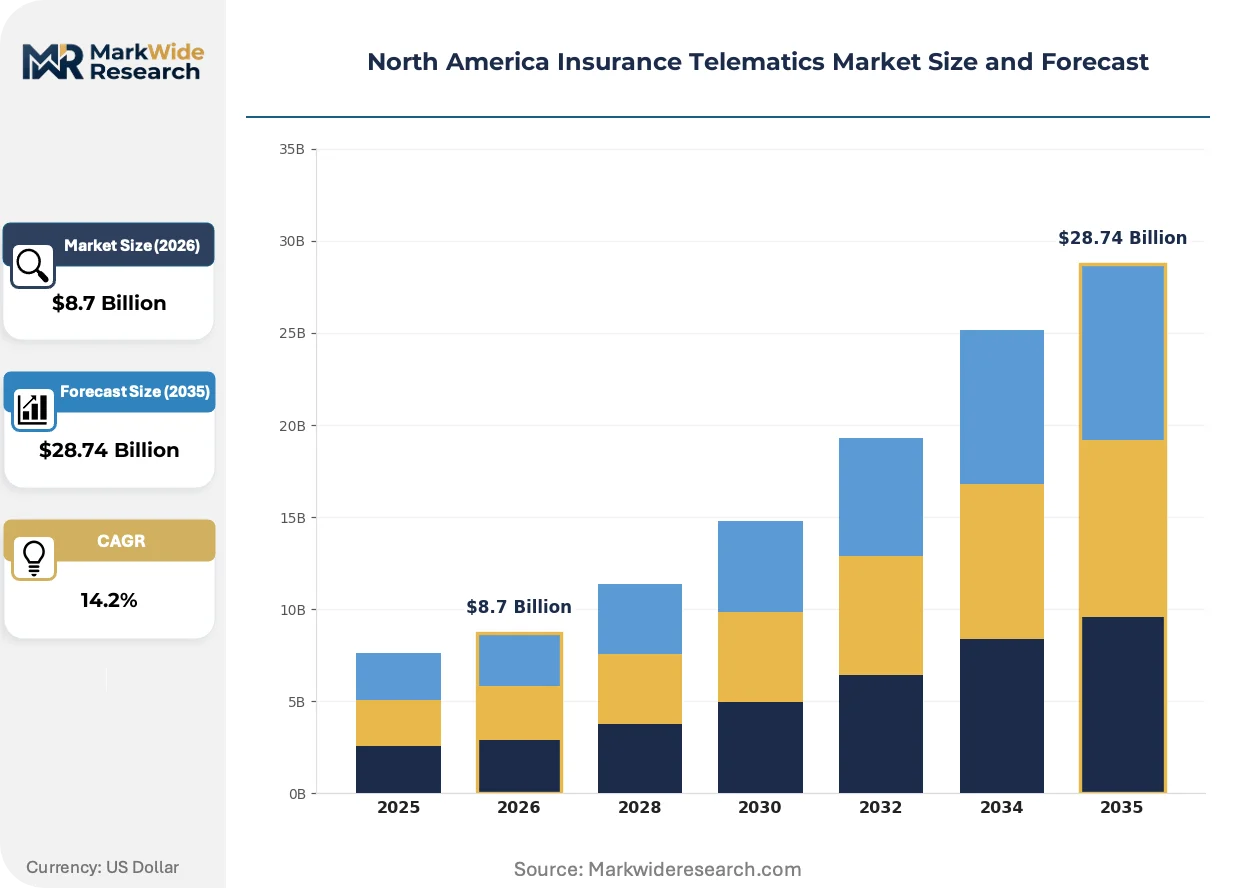
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Data Analytics End User: Insurance Providers, Fleet Managers, Individual Consumers, Vehicle Manufacturers Installation: OEM, Aftermarket, Plug-and-Play, Smartphone-based Technology: GPS, Cellular, Bluetooth, Telematics Cloud |
| Companies Covered | Progressive Corporation, State Farm Mutual Automobile Insurance Company, Allstate Corporation, Nationwide Mutual Insurance Company, GEICO, Liberty Mutual, Cambridge Mobile Telematics, Octo Telematics, LexisNexis Risk Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Insurance Telematics Market Evolving Landscape
Data analytics layers are commanding premium positioning as carriers prioritize claims severity reduction over simple risk selection, reshaping vendor competitive dynamics toward predictive modeling capabilities.
Smartphone-based telematics is absorbing aftermarket hardware installation as the dominant deployment mode in personal auto lines. Mid-market carriers lacking capital for device subsidies are adopting Cambridge Mobile Telematics-style SDK integrations. The technology is absorbing hardware logistics costs while expanding first-party data capture for carriers previously dependent on third-party scoring.
The National Association of Insurance Commissioners has issued draft guidance on algorithmic accountability for telematics-informed pricing, creating compliance preparation cycles across state-regulated carriers. The framework requires documentation of proxy discrimination testing and model retraining protocols. Personal auto carriers in California and New York are front-loading legal and actuarial resources to meet anticipated filing standards.
Fleet managers are consolidating vendor relationships around integrated safety and insurance platforms, displacing point-solution telematics providers. Large commercial auto buyers now demand unified driver behavior scoring, claims management, and risk engineering services. This procurement consolidation is most visible among US-based trucking and last-mile delivery operators with multi-state route networks.
North America Insurance Telematics Market Segmentation
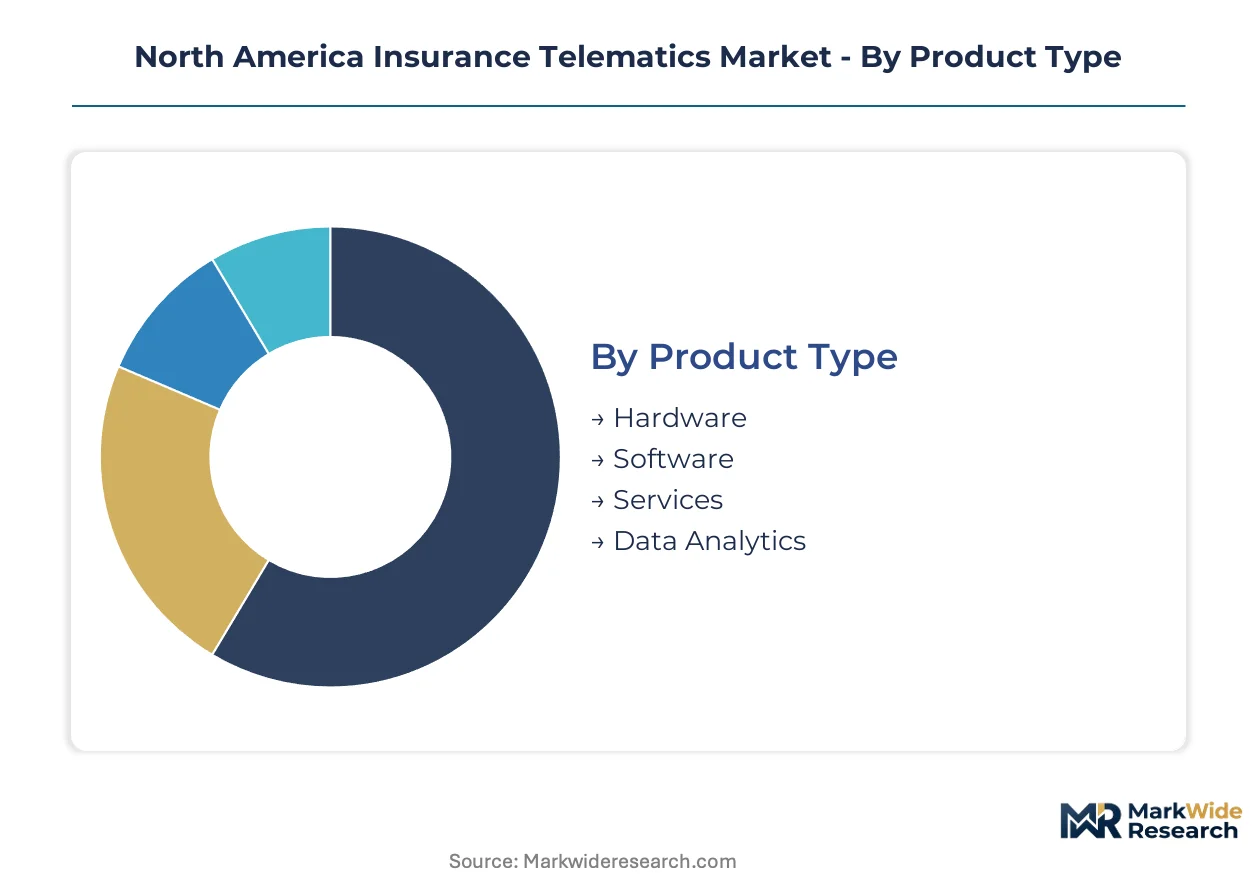
Telematics market segmentation reflects divergent cost structures, deployment velocities, and data sovereignty requirements across carrier IT architectures. Product mix and installation modality choices directly determine customer acquisition economics and regulatory compliance burdens for insurance providers.
Product Type:
Carrier budget tiers and technical maturity separate buyers into hardware-dependent legacy operators versus software-native entrants seeking recurring revenue models.
- Hardware:GPS receivers, accelerometers, and cellular modems constitute the physical data capture layer. Fleet managers in Texas and Ohio dominate procurement volumes, drawn by integrated vehicle diagnostics and real-time location tracking for commercial auto portfolios.
- Software:Cloud-native platforms processing encrypted telemetry streams command premium licensing structures. Personal auto carriers in California and New York prioritize these solutions to compress prior-approval filing timelines with state insurance departments.
- Services:Implementation consulting and system integration support carrier legacy policy administration migration.
- Data Analytics:Predictive modeling layers for claims severity reduction attract mid-market carriers seeking competitive differentiation.
Volume sits with Hardware; growth tilts toward Software.
End User:
Procurement sophistication and regulatory exposure vary sharply between institutional buyers with captive risk engineering teams and individual policyholders lacking technical literacy.
- Insurance Providers:National carriers with multi-state filings drive platform standardization requirements. Progressive and State Farm anchor North American demand, leveraging telematics data for direct-channel pricing and captive agency distribution respectively.
- Fleet Managers:Commercial auto buyers with multi-state route networks consolidate vendor relationships around unified safety and insurance platforms. Last-mile delivery operators in California generate concentrated demand through the state's Advanced Clean Trucks regulation.
- Individual Consumers:Personal auto policyholders adopt smartphone-based monitoring for premium discounts.
- Vehicle Manufacturers:OEMs embed telematics modules at factory assembly for captive insurance partnerships.
Insurance Providers capture the largest revenue pool; Fleet Managers are expanding most quickly.
Installation:
Deployment friction and customer acquisition cost structures differentiate hardware-intensive legacy approaches from zero-touch digital alternatives.
- Smartphone-based:SDK integrations eliminate device logistics and expand addressable bases beyond traditional telematics adopters. Mid-market carriers lacking capital for hardware subsidies favor this modality for personal auto lines.
- OEM:Factory-embedded modems enable seamless data capture from vehicle delivery. Premium vehicle segments in the United States concentrate demand, with manufacturers integrating battery-state monitoring for electrification compliance.
- Aftermarket:Post-purchase hardware installation serves legacy fleet retrofits.
- Plug-and-Play:Self-installed OBD-II devices balance cost and functionality for small commercial operators.
Aftermarket retains installed base; Smartphone-based climbs the fastest.
Technology:
Data transmission reliability and platform integration complexity separate established cellular architectures from emerging connectivity protocols.
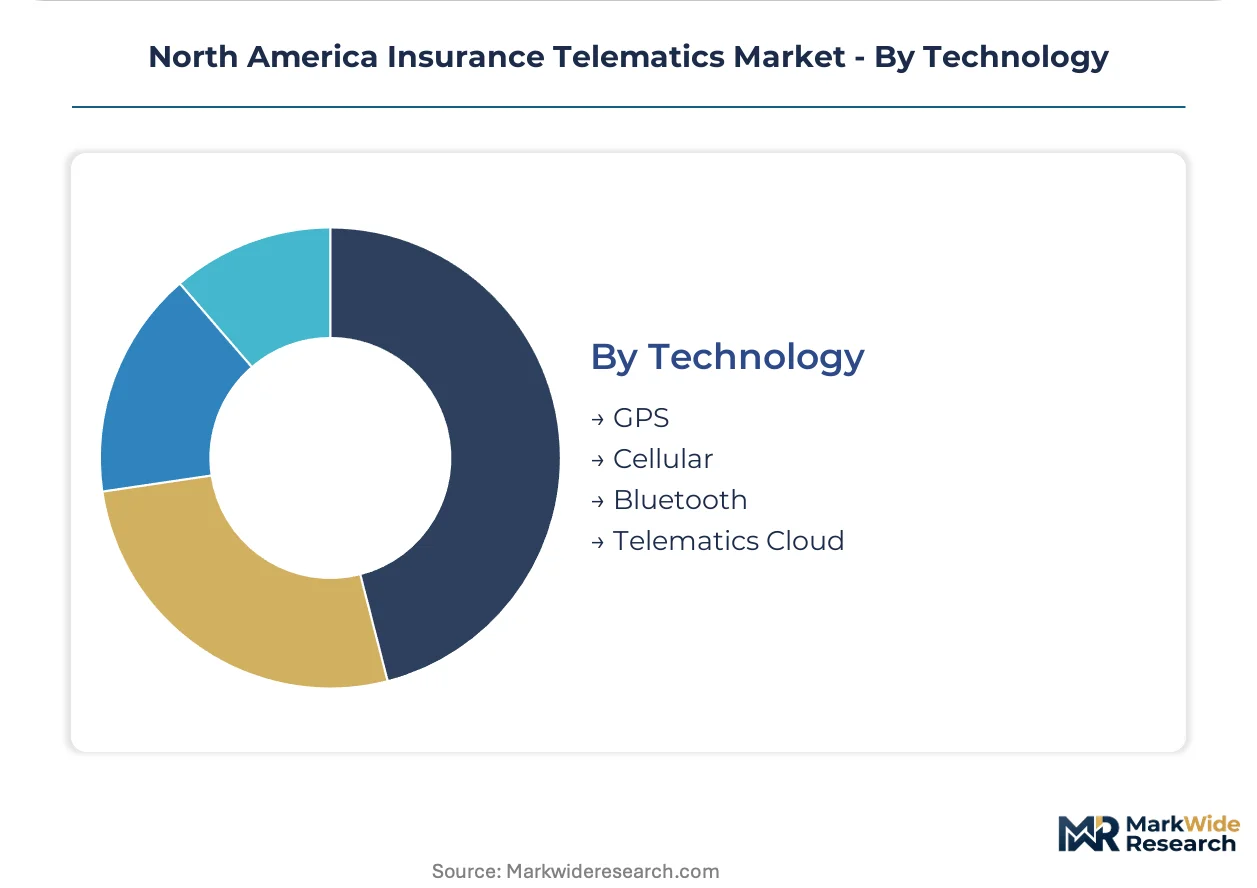
- Cellular:4G and 5G modems provide encrypted, real-time data transmission to cloud-based actuarial engines. Carrier adoption concentrates in the United States, where 5G module cost curves have shifted threshold pricing for mid-market program launches.
- GPS:Satellite positioning systems anchor location-based risk scoring and stolen vehicle recovery. Commercial auto lines in Texas and Ohio leverage GPS data for mileage-verified usage-based insurance filings.
- Bluetooth:Short-range connectivity supports smartphone-to-vehicle data handoff.
- Telematics Cloud:Centralized data aggregation platforms enable multi-source stream processing.
GPS maintains broadest deployment; Cellular gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's data analytics talent pools and Detroit's automotive engineering clusters anchor North American telematics development, with regulatory divergence across state and provincial boundaries shaping deployment timelines.
United States
Texas and Ohio regulators have streamlined prior-approval processes for telematics-informed rate filings, accelerating carrier product launches. The National Association of Insurance Commissioners coordinates state-level frameworks governing data use in insurance pricing. California's Advanced Clean Trucks regulation drives integrated battery-state monitoring demand among commercial fleet operators in the Los Angeles Basin.
Canada
Ontario and Quebec regulatory frameworks are converging toward US state implementation patterns, creating contiguous market entry paths for platform vendors. The country's national insurance regulator maintains distinct data retention requirements that force carriers to maintain separate platform configurations. Toronto's financial services cluster hosts emerging telematics analytics capabilities serving both domestic carriers and US market entrants.
Mexico
Mexico City Metro's commercial fleet density generates concentrated demand for usage-based insurance among last-mile delivery operators. The country's national insurance and surety institutions commission oversees telematics data integration into compulsory auto liability coverage. Nuevo León's manufacturing corridor attracts embedded telematics module production for captive insurance partnerships with OEM assembly plants.
North America Insurance Telematics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smartphone-based deployment models that eliminate hardware friction. The market exhibits tiered concentration around national carriers with captive distribution networks and specialized telematics platform vendors serving mid-market insurers. Three strategic archetypes dominate: direct-channel insurers with proprietary data platforms, agency-network carriers integrating telematics into captive distribution, and software-native vendors offering SDK-based deployment. Competitive dynamics center on strategic partnerships between carriers and technology providers, alongside portfolio diversification into commercial fleet loss prevention services.
Among US-based national carriers, Progressive Corporation and State Farm Mutual Automobile Insurance Company anchor the direct-channel and agency-network archetypes respectively. Cambridge Mobile Telematics occupies a position exemplifying the smartphone-native platform tier, eliminating hardware logistics for capital-constrained mid-market insurers. These three entities represent the dominant competitive vectors shaping vendor selection criteria and platform investment cycles across North American personal and commercial auto lines.
| Leading Market Players |
|---|
| Progressive Corporation |
| State Farm Mutual Automobile Insurance Company |
| Allstate Corporation |
| Nationwide Mutual Insurance Company |
| GEICO |
| Liberty Mutual |
| Cambridge Mobile Telematics |
| Octo Telematics |
| LexisNexis Risk Solutions |
| Others |
Value Network & Pricing Analysis
Fleet buyer concentration among large commercial auto insurers anchors pricing power toward volume-based SaaS licensing structures, compressing per-unit margins for hardware vendors while elevating recurring revenue multiples for cloud-native platform providers.
Pricing Analysis
Volume concentrates in hardware-dependent legacy deployments across Texas and Ohio commercial fleets, while margin capture tilts toward software platforms serving California and New York carriers navigating prior-approval filing timelines. Price differentiation rests on regulatory certification tier—platforms with documented algorithmic transparency command premium positioning—and deployment velocity, where smartphone-native solutions bypass hardware logistics premiums. Pricing pressure stems from 5G module cost compression enabling mid-market carrier program launches. Small commercial operators exhibit highest price sensitivity, captive national carriers least.
Supply Chain Analysis
Reverse-logistics flows for OBD-II device refurbishment and smartphone SDK reactivation create secondary supply channels for mid-market carriers lacking capital for fresh hardware procurement. GPS receiver and accelerometer chip fabrication concentrates in Taiwan, South Korea, and China, drawing from silicon wafer and rare earth magnet inputs. Single-source vulnerability in East Asian foundries exposes North American hardware vendors to geographic concentration risk. Distribution runs through carrier-direct procurement for national accounts and telematics platform vendor aggregators serving regional insurers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American insurance telematics has become a vertical-integration race, with platform vendors pursuing captive data analytics capabilities and carriers building in-house scoring engines to reduce third-party licensing dependencies.
For Market Incumbents: Deepen proprietary data platform investments to defend against smartphone-native SDK entrants eroding hardware-dependent revenue streams. Secure captive supply agreements with 5G modem fabricators to preempt silicon allocation constraints. Anchor distribution through state-level regulatory pre-approval relationships that delay competitor filings. For New Entrants and Emerging Players: Launch via smartphone-based deployment models targeting mid-market carriers in Canadian provincial markets where regulatory frameworks are converging toward US patterns. Penetrate Ontario and Quebec before national carriers consolidate platform standardization requirements. Prioritize SDK integration speed over feature depth. For Investors and Strategic Acquirers: Distressed-cycle entries favor data analytics specialists with California and New York regulatory filing experience during carrier consolidation phases. Long-term viability hinges on predictive modeling differentiation beyond basic telematics scoring. Monitor state insurance department algorithmic transparency mandate timelines as inflection indicators for platform vendor valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Smartphone SDK Integration | Eliminates hardware logistics costs for mid-market carriers lacking device subsidy capital. |
| State Regulatory Pre-Approval | Accelerates product launch timelines in Texas and Ohio streamlined filing environments. |
| Algorithmic Transparency Documentation | Meets California and New York Department of Financial Services emerging filing standards. |
| Commercial Fleet Loss Prevention Bundling | Creates unbundled revenue streams beyond premium pricing for last-mile delivery operators. |
| Canadian Provincial Market Entry | Exploits Ontario and Quebec regulatory convergence toward US implementation patterns. |
Research Methodology
Independent corroboration across carrier actuarial executives, state insurance department filing officers, fleet procurement managers, and telematics platform engineers underwrites the qualitative findings. Primary interviews with commercial auto underwriting leads and personal lines pricing directors combined with secondary validation from NAIC regulatory guidance documents, state insurance department rate filing databases, and carrier annual statement disclosures. Bottom-up carrier program deployment tallies and top-down addressable policyholder base estimates triangulate market sizing.
Rate-of-change decomposition separates hardware unit volume trajectories from software licensing value expansion across the analysis window. Segmentation dimensions modeled include product type, end user archetype, installation modality, and underlying connectivity technology. CAGRs derive from carrier adoption curve analysis and regulatory timeline probability weighting. Forecast inputs incorporate 5G module cost curve assumptions and state-level privacy consent fragmentation scenarios.
The model assumes a particular technology adoption path; alternative pathways for embedded OEM telematics would alter the outlook. Forecasts reflect carrier IT modernization budget assumptions and state regulatory coordination trajectories. Practitioners should monitor NAIC algorithmic accountability guidance finalization and silicon supply allocation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
Latin America AI in Insurance Market
Insurance Technology
Artificial Intelligence in Insurtech Market
Insurance Technology
Germany AI in Insurance Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
P and C Insurance Software Market
Insurance Technology
Japan AI in Insurance Market
Insurance Technology
Insurance Fraud Detection Market
Insurance Technology
Europe Insurtech Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
Global Insurance Telematics Market
Insurance Technology
Singapore Insurtech Market
Insurance Technology
Global Commercial Insurance Software Market
Insurance Technology
Asia-Pacific P&C Insurance Software Market
Insurance Technology
Middle East and Africa Insurtech Market
Insurance Technology
Global Blockchain in Insurance Market