
 India Car Loan Market | 2026-2036
India Car Loan Market Size, Share, and Industry Trends Forecast 2026-2036
India Car Loan Market Insights
Tamil Nadu's auto finance corridor is fragmenting as NBFCs and banks compete for dealership tie-ups and direct-to-consumer digital channels. State Bank of India leverages its rural branch network to anchor small-town penetration. HDFC Bank competes through pre-approved loan offerings and integrated auto marketplace platforms. ICICI Bank differentiates via API-led partnerships with fintech aggregators for instant eligibility checks.
A car loan is a secured or unsecured credit instrument collateralized by the vehicle title, featuring fixed or floating interest rates tied to benchmark lending rates such as the repo-linked lending rate, with tenures spanning twelve to eighty-four months and loan-to-value ratios typically ranging from eighty to one hundred percent for new vehicles. Its commercial purpose is to bridge the affordability gap between consumer savings and vehicle acquisition costs, enabling asset ownership while generating interest income for lenders. Secured loans dominate portfolio composition due to lower risk weights and collateral recovery mechanisms, while floating rate products are gaining traction as borrowers seek protection against rate cycle volatility. Non-banking financial companies sustain faster disbursement velocities than commercial banks, though the latter control lower-cost deposit-funded capital pools.
RBI's co-lending framework and priority sector lending mandates shape capital flows toward underserved borrower segments, while SEBI regulations govern NBFC fundraising through public bond issuances. The central bank's digital lending guidelines and data privacy standards are tightening Know Your Customer and consent architecture requirements. Stakeholders must monitor evolving regulatory capital norms and the competitive intensity of fintech-bank partnerships as determinants of sustainable origination economics.
Market Dynamics
Digital underwriting platforms are fragmenting lender-borrower relationships across Maharashtra, Gujarat, and Tamil Nadu, compressing loan approval cycles from days to minutes while RBI's co-lending framework redistributes capital risk between banks and NBFCs.
Growth Catalysts
- Priority Sector Lending Norms:RBI mandates direct 40% of adjusted net bank credit toward priority sectors, channeling institutional capital into vehicle finance for rural and semi-urban borrowers previously excluded from formal credit.
- API-Led Fintech Integration:Real-time eligibility verification through bank-fintech partnerships collapses documentation requirements, accelerating conversion rates among first-time buyers in tier-2 and tier-3 cities.
- Automotive Cluster Proximity:Manufacturing concentration in Chennai, Pune, and Ahmedabad generates captive demand from dealership employees, component suppliers, and logistics operators seeking fleet financing.
Market Restraints
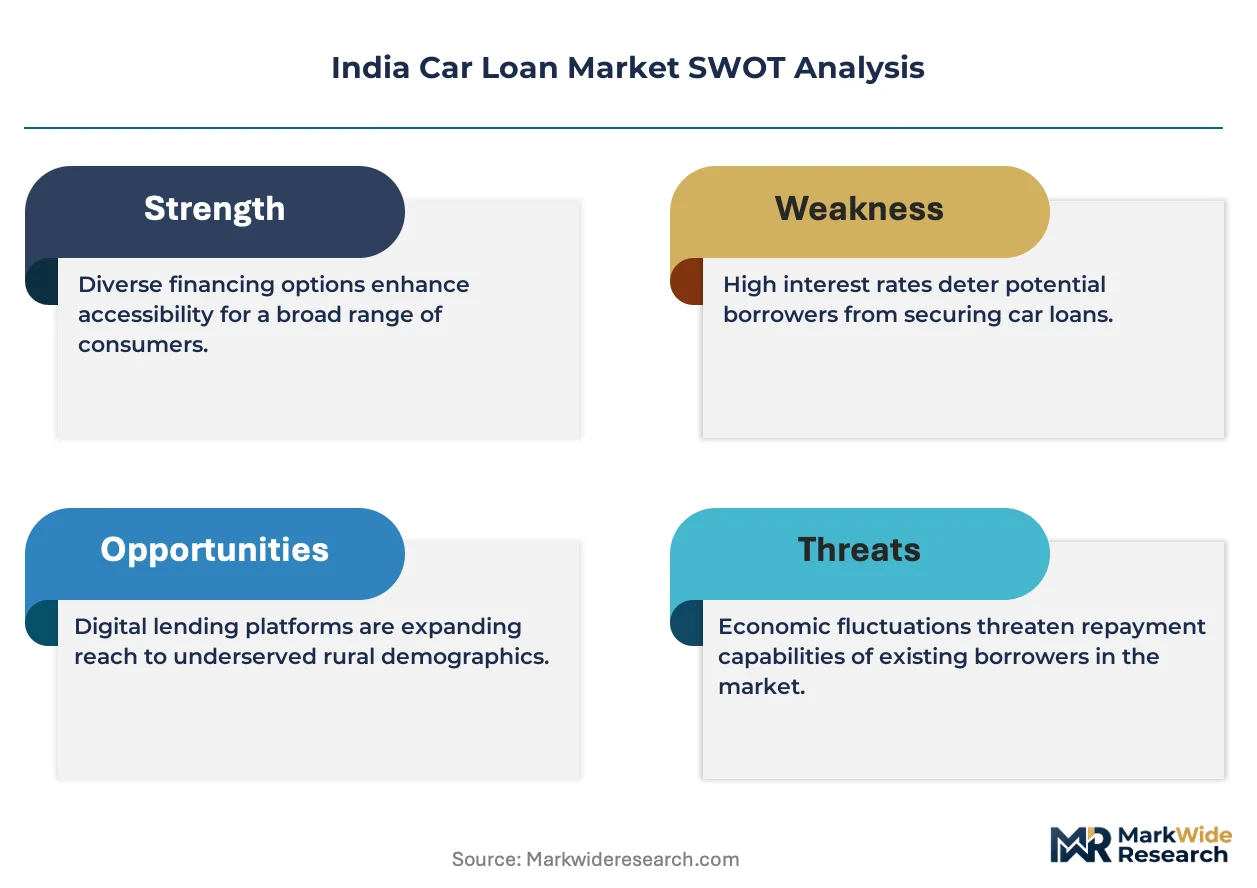
- Repo Rate Volatility:Floating rate products indexed to RBI's repo-linked lending rate expose borrowers to EMI shock during monetary tightening cycles, elevating portfolio delinquency risk.
- Used Vehicle Valuation Opacity:Absence of standardized residual value benchmarks for pre-owned cars constrains secured lending appetite, limiting NBFC penetration in the second-hand segment.
- Data Localization Compliance:RBI's digital lending guidelines mandate on-shore storage of borrower consent records, inflating cloud infrastructure costs for fintech-originated platforms.
Strategic Opportunities
- Kerala and Karnataka Underpenetration:Southern states outside Tamil Nadu exhibit lower auto finance penetration relative to vehicle ownership rates, offering whitespace for direct-to-consumer digital acquisition.
- Electric Vehicle PLI Convergence:Production-linked incentive schemes for EV manufacturing create aligned financing demand as OEMs localize battery and powertrain assembly.
- Embedded Finance at Point of Sale:Dealership-integrated loan origination through tablet-based underwriting captures borrowers at maximum purchase intent, displacing branch-led application workflows.
Industry Challenges
- Legacy Core Banking Integration:Tier-2 NBFCs face middleware complexity connecting modern API stacks to decades-old loan management systems, delaying real-time disbursement capabilities.
- Field Investigation Talent Scarcity:Rural vehicle finance requires physical asset verification and income assessment skills that digital platforms cannot fully automate, creating hiring bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Car Loan Market |
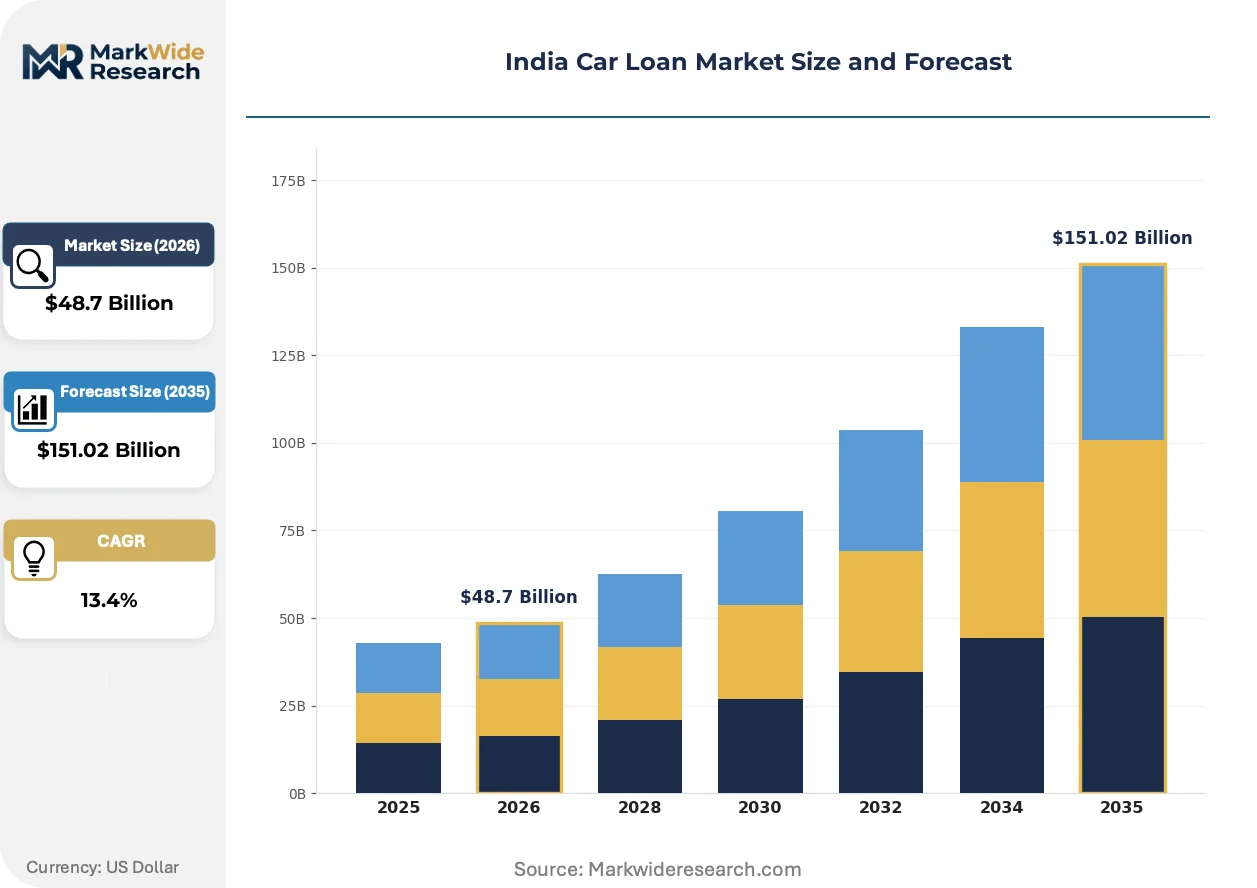
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $151.02 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Secured Loan, Unsecured Loan, Fixed Rate Loan, Floating Rate Loan Borrower Profile: First-Time Buyers, Repeat Buyers, Corporate Buyers, Government Employees Lending Institution: Commercial Banks, Non-Banking Financial Companies, Credit Unions, Peer-to-Peer Lending Repayment Tenure: Short-Term Tenure, Medium-Term Tenure, Long-Term Tenure, Flexible Tenure |
| Companies Covered | State Bank of India, HDFC Bank, ICICI Bank, Axis Bank, Kotak Mahindra Bank, Mahindra & Mahindra Financial Services, Shriram Finance, Cholamandalam Investment and Finance Company, Toyota Financial Services India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Car Loan Market Trends and Innovations
Artificial intelligence is reconstructing credit decisioning at the intersection of alternative data ingestion and regulatory sandbox experimentation, compressing the traditional bank-NBFC capability gap.
Alternative credit scoring is migrating from bureau-dependent models toward cash-flow analysis of Unified Payments Interface transaction histories. Fintech aggregators serving gig economy drivers and informal sector borrowers deploy machine learning on real-time income patterns. This shift is collapsing reliance on formal tax documentation for eligibility determination.
RBI's digital lending guidelines and data privacy standards are tightening consent architecture requirements for borrower data usage. Lenders must now maintain granular audit trails of explicit permission for each data element accessed. NBFCs with fintech partnerships face the steepest compliance recalibration as they retrofit legacy workflows.
Direct-to-consumer channel preference is displacing dealership-mediated loan origination among urban salaried segments. Smartphone-native borrowers in Bengaluru and Hyderabad initiate applications through bank super-apps before visiting showrooms, reversing the traditional discovery sequence. OEM captive finance units are responding by embedding pre-approval tools within vehicle configurator interfaces.
India Car Loan Market Segmentation
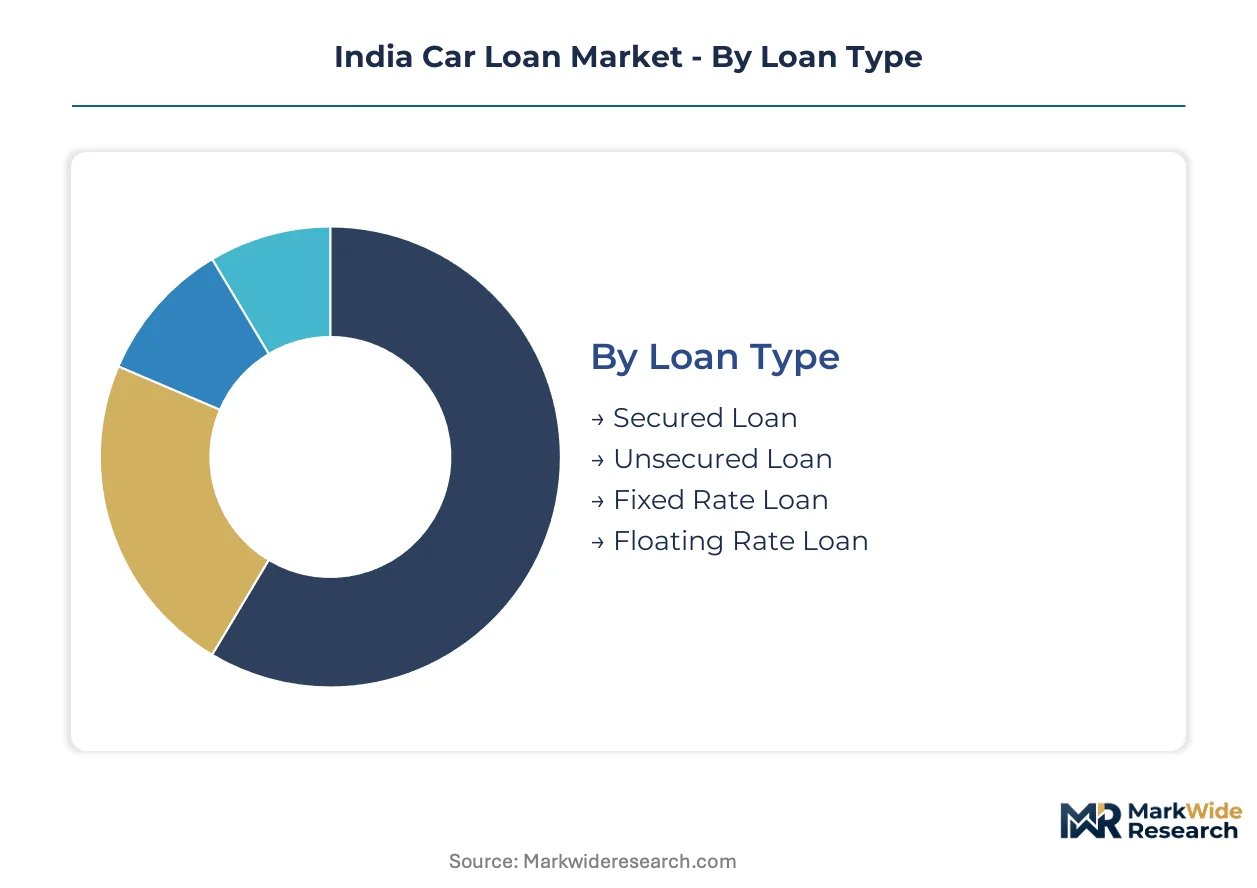
India's car loan market fragments along four distinct axes that determine origination economics, risk weighting, and servicing intensity. Lenders calibrate product design, underwriting protocols, and collection infrastructure based on collateral structure, borrower vintage, capital source, and amortization schedules. Each segment carries differentiated after-sales-service demands that shape operational cost structures across Maharashtra, Gujarat, and Tamil Nadu.
Loan Type:
After-sales-service intensity varies sharply by collateral and rate structure, with secured products requiring asset verification protocols while floating rate loans demand ongoing EMI recalculation infrastructure.
- Secured Loan:Vehicle title serves as primary collateral with hypothecation registration under the Motor Vehicles Act. Demand concentrates in Tamil Nadu's manufacturing corridor where formal employment documentation supports standardized loan-to-value ratios of 80-100 percent for new vehicles.
- Floating Rate Loan:Interest obligations track RBI's repo-linked lending rate with quarterly reset clauses. Maharashtra's salaried borrower segments in Mumbai and Pune exhibit concentration here as they seek protection against rate cycle volatility through transparent benchmark linkage.
- Unsecured Loan:Clean credit extended against bureau scores and income verification without asset charge. Gujarat's informal sector borrowers in Surat and Vadodara access this format where vehicle titles remain encumbered by existing obligations.
- Fixed Rate Loan:Rate locked at origination through full tenure eliminates reset risk. Budget-conscious buyers in tier-3 cities prefer this structure for predictable household cash flow planning.
By volume, Secured Loan leads. By growth pace, Floating Rate Loan is expanding most quickly.
Borrower Profile:
Cost tier differentiation separates acquisition economics, with first-time buyers demanding intensive documentation support while corporate buyers enable standardized bulk processing.
- First-Time Buyers:Borrowers without prior credit history requiring alternative data scoring through UPI transaction analysis. Karnataka and Kerala exhibit rising concentration as digital platforms penetrate beyond Tamil Nadu's established auto finance corridor.
- Repeat Buyers:Seasoned borrowers with established repayment records accessing pre-approved limits and relationship pricing. Gujarat's Ahmedabad cluster shows density here among component supplier employees upgrading vehicles.
- Corporate Buyers:Fleet acquisition by logistics operators, ride-hailing aggregators, and employee transport providers. Maharashtra's e-commerce fulfillment networks generate concentrated demand for commercial vehicle financing.
- Government Employees:Salary-linked repayment through employer deduction mandates with low delinquency characteristics. Tamil Nadu's state government workforce anchors this segment through salary account tie-ups with public sector banks.
By volume, First-Time Buyers lead. By growth pace, Corporate Buyers are gaining share fastest.
Lending Institution:
Application context determines channel preference, with commercial banks serving established salary earners while NBFCs capture informal income segments.
- Commercial Banks:Deposit-funded institutions leveraging priority sector lending mandates and lower cost of capital. State Bank of India's rural branch network anchors small-town penetration across Maharashtra's hinterland.
- Non-Banking Financial Companies:Faster disbursement velocity through specialized auto loan divisions with field investigation capabilities. HDFC Bank's pre-approved offerings and ICICI Bank's API-led fintech partnerships exemplify competitive positioning here.
- Credit Unions:Member-owned cooperatives serving specific occupational or geographic communities with relationship-based underwriting. Limited penetration concentrated in Kerala's cooperative banking stronghold.
- Peer-to-Peer Lending:Platform-mediated individual lending with algorithmic matching of borrower profiles to lender risk appetites. Regulatory constraints under RBI's digital lending guidelines constrain scale.
By volume, Commercial Banks lead. By growth pace, Non-Banking Financial Companies show the steepest expansion trajectory.
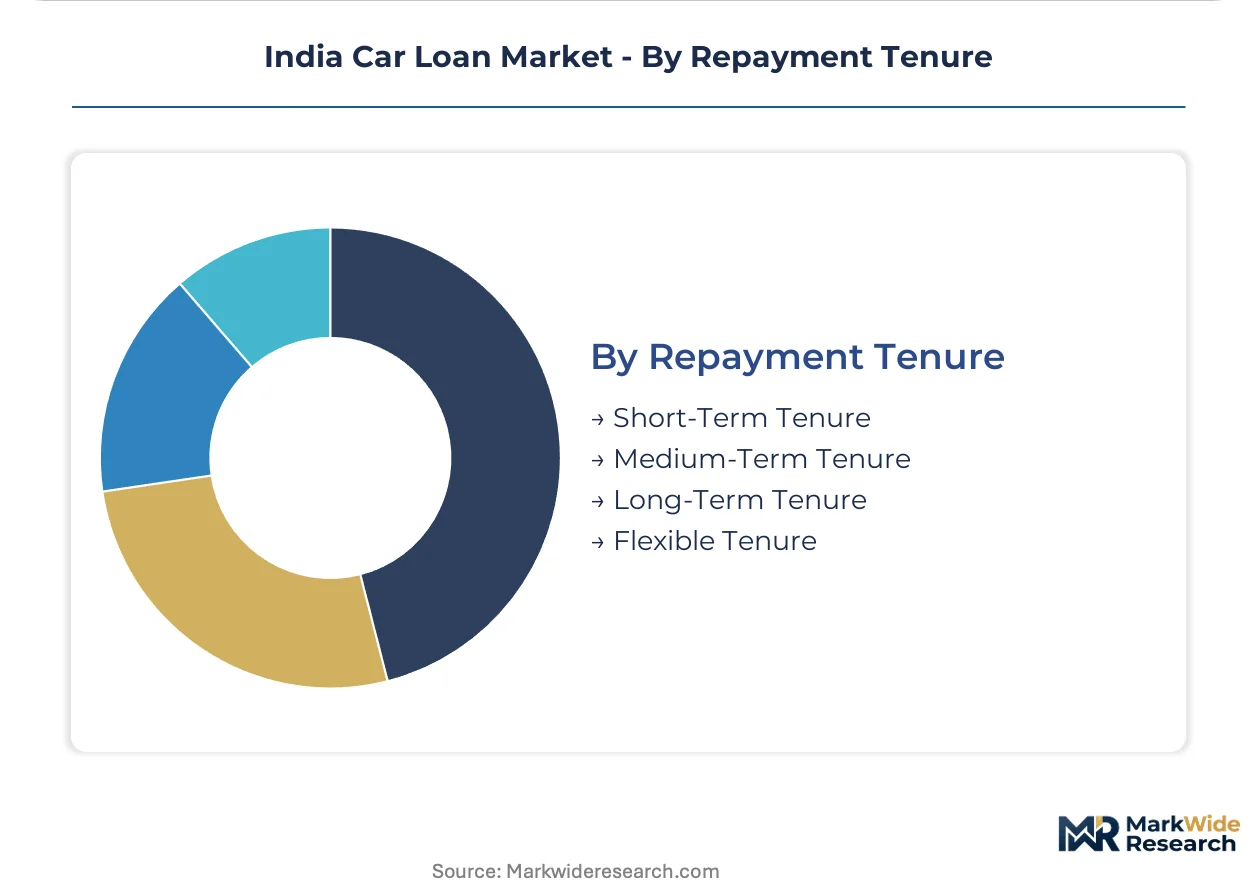
Repayment Tenure:
Maturity profile alignment with vehicle replacement cycles and borrower income stability shapes portfolio duration risk.
- Medium-Term Tenure:36-60 month amortization matching standard vehicle warranty periods and typical ownership horizons. Dominates Maharashtra and Gujarat where salaried employment supports consistent EMI servicing.
- Long-Term Tenure:61-84 month structures reducing monthly obligation for price-sensitive buyers. Tamil Nadu's first-time buyer segments in tier-2 cities access higher vehicle segments through extended amortization.
- Short-Term Tenure:12-35 month rapid amortization for used vehicle purchases and top-up loans. Corporate fleet operators in Ahmedabad prefer this structure for faster asset turnover.
- Flexible Tenure:Step-up or balloon structures aligning with seasonal income patterns. Agricultural and trading community borrowers in Gujarat's Saurashtra region utilize harvest-linked repayment schedules.
By volume, Medium-Term Tenure leads. By growth pace, Flexible Tenure is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dedicated Freight Corridor's western and eastern spurs are reconfiguring vehicle distribution patterns across India's industrial heartland, accelerating credit demand in corridor-adjacent districts.
Maharashtra
Mumbai's salaried workforce and Pune's automotive engineering clusters generate concentrated demand for floating-rate products tied to RBI's repo-linked lending rate. The state's priority sector lending quotas channel bank capital into rural Marathwada and Vidarbha. Nagpur's logistics hub anchors fleet financing for e-commerce fulfillment networks expanding eastward toward the DFC.
Gujarat
Ahmedabad's component supplier ecosystems and Surat's diamond trading communities sustain repeat-buyer and informal-income segments respectively. The state's PLI scheme for electric vehicle manufacturing is drawing OEM assembly investments that will require aligned captive finance capacity. Mundra Port's container throughput underwrites import-dependent premium vehicle distribution to Rajasthan and Madhya Pradesh hinterlands.
Tamil Nadu
Chennai's OEM concentration creates captive demand from dealership employees and tier-1 suppliers accessing medium-term secured products. The state's government employee salary deduction mandates anchor low-delinquency portfolios for public sector banks. Coimbatore's SME manufacturing belt is emerging as a whitespace for direct-to-consumer digital acquisition outside the established Chennai corridor.
Karnataka
Bengaluru's technology workforce exhibits channel-inversion behavior, initiating loan applications through bank super-apps before showroom visits. The state's underpenetration relative to vehicle ownership rates offers expansion terrain for API-led fintech partnerships. Hubli-Dharwad's tier-2 manufacturing base is attracting NBFC field investigation investments previously concentrated in Tamil Nadu.
Kerala
The state's cooperative banking heritage limits commercial bank penetration, creating structural whitespace for credit unions and member-owned institutions. Gulf remittance-dependent households in Malappuram and Kozhikode districts favor flexible tenure products aligned to seasonal NRI income flows. Kochi's port infrastructure supports used vehicle imports from the Middle East that require specialized residual value underwriting.
India Car Loan Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with faster disbursement velocity but narrower capital access. The market structures around three tiers: public sector banks with branch density advantages, private banks with digital pre-approval infrastructure, and NBFCs with specialized auto loan divisions and field investigation capabilities. Strategic archetypes include deposit-funded universal banks, capital-market-dependent specialists, and OEM-captive finance units. Dominant competitive moves encompass API-led fintech partnerships for instant eligibility verification and co-lending framework participation to redistribute balance sheet risk.
Within the public sector tier, State Bank of India anchors rural penetration through its branch network across Maharashtra's hinterland. Among private banks, HDFC Bank and ICICI Bank occupy positions at the digital integration frontier; HDFC Bank exemplifies pre-approved loan architecture while ICICI Bank represents API-led aggregator partnerships for real-time underwriting. These three institutions collectively illustrate the competitive tension between physical infrastructure and digital acquisition channels reshaping origination economics.
| Leading Market Players |
|---|
| State Bank of India |
| HDFC Bank |
| ICICI Bank |
| Axis Bank |
| Kotak Mahindra Bank |
| Mahindra & Mahindra Financial Services |
| Shriram Finance |
| Cholamandalam Investment and Finance Company |
| Toyota Financial Services India |
| Others |
Pricing and Supply Chain Analysis
Repo rate volatility exposure determines both the spread between fixed and floating rate loan pricing tiers and the geographic shape of lender supply chains across Maharashtra, Gujarat, and Tamil Nadu. RBI's quarterly repo-linked lending rate resets compress margins on floating products while channeling capital toward secured, fixed-rate structures in tier-2 and tier-3 cities where borrower price sensitivity concentrates.
Pricing Analysis
Volume-discount tiering structures dominate origination economics, with relationship pricing for repeat buyers and corporate fleet operators separating from standardized retail rates for first-time borrowers. Price differentiation rests on credit bureau scores and formal employment documentation, with government salary deduction mandates commanding the narrowest spreads. Cost compression in the unsecured segment is intensifying because fintech aggregators collapse documentation overhead. First-time buyers in Karnataka and Kerala exhibit the highest price sensitivity; corporate fleet operators in Maharashtra's logistics corridors show the least.
Supply Chain Analysis
Tariff exposure on semiconductor components for embedded finance hardware dominates supply chain risk planning for dealership-integrated underwriting platforms. Capital deployment draws from three concentrated sources: public sector bank deposit bases across rural Maharashtra, NBFC bond issuances regulated by SEBI, and co-lending frameworks redistributing risk between banks and non-banks. Single-source vulnerability sits with cloud infrastructure providers facing RBI's data localization mandates. Distribution runs through three channels: direct-to-consumer super-apps, OEM-captive finance at point of sale, and dealership-mediated origination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's car loan market is a high-growth disruption justified by RBI's co-lending framework and digital lending guidelines compressing approval cycles from days to minutes. The regulatory inflection is redistributing capital risk and tightening consent architecture requirements simultaneously.
For Market Incumbents: Entrench rural penetration through State Bank of India's branch network density in Maharashtra's hinterland while retrofitting legacy core banking systems to API-led fintech partnerships. The threat of direct-to-consumer channel inversion by smartphone-native borrowers in Bengaluru demands pre-approval infrastructure investment. Vertical integration into embedded finance at dealership point of sale is the critical lever. For New Entrants and Emerging Players: Kerala and Karnataka's underpenetration relative to vehicle ownership rates offers whitespace for API-led aggregator partnerships outside Tamil Nadu's established auto finance corridor. The most penetrable segment is Coimbatore's SME manufacturing belt for direct-to-consumer digital acquisition. Hubli-Dharwad's tier-2 manufacturing base supports field investigation investments. Target gig economy drivers and informal sector borrowers through UPI transaction-based alternative scoring. For Investors and Strategic Acquirers: RBI's co-lending framework reshapes the acquisition landscape by privileging balance sheet partnerships over pure origination platforms. Long-term viability over a multi-year horizon favors NBFCs with specialized auto loan divisions and existing dealership tie-ups. Acquisition target archetype: tier-2 NBFCs with field investigation capabilities in underpenetrated southern states. The signal to watch is OEM captive finance unit expansion into EV-aligned financing as PLI schemes localize battery assembly.| Strategic Initiative | Industry Significance |
|---|---|
| API-Led Fintech Partnership | Real-time eligibility verification through bank-fintech collaborations collapses documentation requirements for first-time buyers. |
| Co-Lending Framework Participation | RBI-mandated risk redistribution between banks and NBFCs channels institutional capital into underserved borrower segments. |
| Embedded Finance at Point of Sale | Dealership-integrated tablet-based underwriting captures borrowers at maximum purchase intent, displacing branch workflows. |
| Alternative Credit Scoring Deployment | Machine learning on UPI transaction histories enables gig economy driver and informal sector borrower eligibility determination. |
| EV-Aligned Captive Finance Buildout | Production-linked incentive convergence for electric vehicle manufacturing creates aligned financing demand as OEMs localize assembly. |
Research Methodology
Initial hypotheses were tested against primary input from auto loan division heads, dealership operations managers, fintech platform engineers, and RBI regulatory affairs specialists and refined through secondary validation. Primary interviews combined with RBI circulars, SEBI NBFC disclosure filings, NHB housing finance data, and automotive production cluster reports. Bottom-up origination volume estimates triangulated against top-down priority sector lending flow analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass loan type, borrower profile, lending institution, and repayment tenure alongside regional production cluster proximity. CAGRs were derived through trend extrapolation of digital adoption curves and regulatory capital deployment shifts. Forecast inputs included UPI transaction growth trajectories and EV manufacturing localization timelines under PLI schemes.
Macroeconomic conditions sit as an overlay; deviation in repo rate cycles, rural income growth, or semiconductor import costs would shift the trajectory. Forecasts reflect assumptions about regulatory continuity and fintech partnership scalability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Online Payday Loans Market
Loans and Leasing
Automotive Finance Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
Debt Financing Market
Loans and Leasing
UK Car Loan Market
Loans and Leasing
Europe Auto Loan Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
France Auto Loan Market
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
Refinancing Market
Loans and Leasing
China Mortgage/Loan Brokers Market
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
United States Digital Lending Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
US Factoring Services Market