
 Commercial Lending Market | 2026-2036
Commercial Lending Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Lending Market Analysis
Spread income from traditional term lending is narrowing as non-bank competitors and capital markets disintermediate core corporate borrowers. JPMorgan Chase leverages its balance sheet scale to dominate syndicated and investment-grade lending. PNC Bank anchors its growth in middle-market specialization across the Southeast and Midwest. Truist differentiates through integrated treasury management and commercial real estate expertise in the Mid-Atlantic and Sun Belt corridors.
Commercial lending encompasses secured and unsecured credit facilities extended to business entities, characterized by risk-based pricing tied to credit ratings, collateral coverage ratios typically ranging from 75% to 90%, and covenant structures monitoring debt service coverage and leverage thresholds. Its primary purpose channels capital toward productive investment, liquidity management, and operational expansion across the enterprise lifecycle. Term loans and lines of credit capture the deepest margin pools, while equipment financing accelerates fastest as manufacturers pursue fleet modernization and automation. Small business lending remains structurally fragmented, creating openings for technology-enabled originators with automated underwriting capabilities.
The Federal Reserve, OCC, and FDIC collectively shape capital adequacy, stress testing protocols, and resolution planning mandates that constrain large bank lending capacity and compliance costs. The SEC governs disclosure requirements for loan securitizations and collateralized loan obligations that compete with bank balance sheet capacity. Stakeholders must monitor how regulatory capital treatments evolve for high-volatility commercial real estate and leveraged lending exposures, as these classifications directly affect return thresholds and portfolio allocation decisions across the banking system.
Market Dynamics
Basel III endgame capital requirements are compressing bank balance sheet capacity and redirecting middle-market credit origination toward non-bank lenders and private credit funds.
Growth Catalysts
- Small business working capital demand:Equipment modernization cycles and inventory expansion needs are pulling incremental credit utilization from manufacturing and logistics borrowers across the United States.
- Automated underwriting platforms:Machine learning credit scoring is collapsing origination costs and enabling technology-enabled lenders to serve structurally fragmented small business segments previously deemed uneconomical.
- SEC loan securitization frameworks:Collateralized loan obligation markets are deepening secondary liquidity and allowing originators to recycle capital into new production.
Market Restraints
- Basel III risk-weight recalibration:Higher capital charges for high-volatility commercial real estate exposures are constraining large bank appetite for construction and development lending.
- Interest rate volatility transmission:Rapid benchmark rate movements are compressing net interest margins and forcing repricing lag risks onto floating-rate portfolios.
- Direct lending fund saturation:Private credit deployment capacity in middle-market syndications is crowding traditional bank participations and compressing arrangement fees.
Strategic Opportunities
- Integrated treasury management bundling:Cross-selling cash management, FX hedging, and payment services alongside credit facilities is deepening borrower stickiness and stabilizing deposit bases.
- Equipment finance automation specialization:Fleet modernization demand from manufacturing and logistics verticals is creating dedicated origination verticals with collateral monitoring technology.
- Regional bank consolidation white space:Scale-driven merger activity among community banks is creating service gaps that specialized middle-market lenders can capture in Southeast and Midwest corridors.
Industry Challenges
- Commercial real estate appraisal capacity constraints:Qualified valuation professionals for complex property types are in short supply, extending due diligence timelines and closing cycles.
- Legacy core banking integration:Incumbent loan origination systems require costly middleware development to connect with modern API-based credit decisioning platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Lending Market |
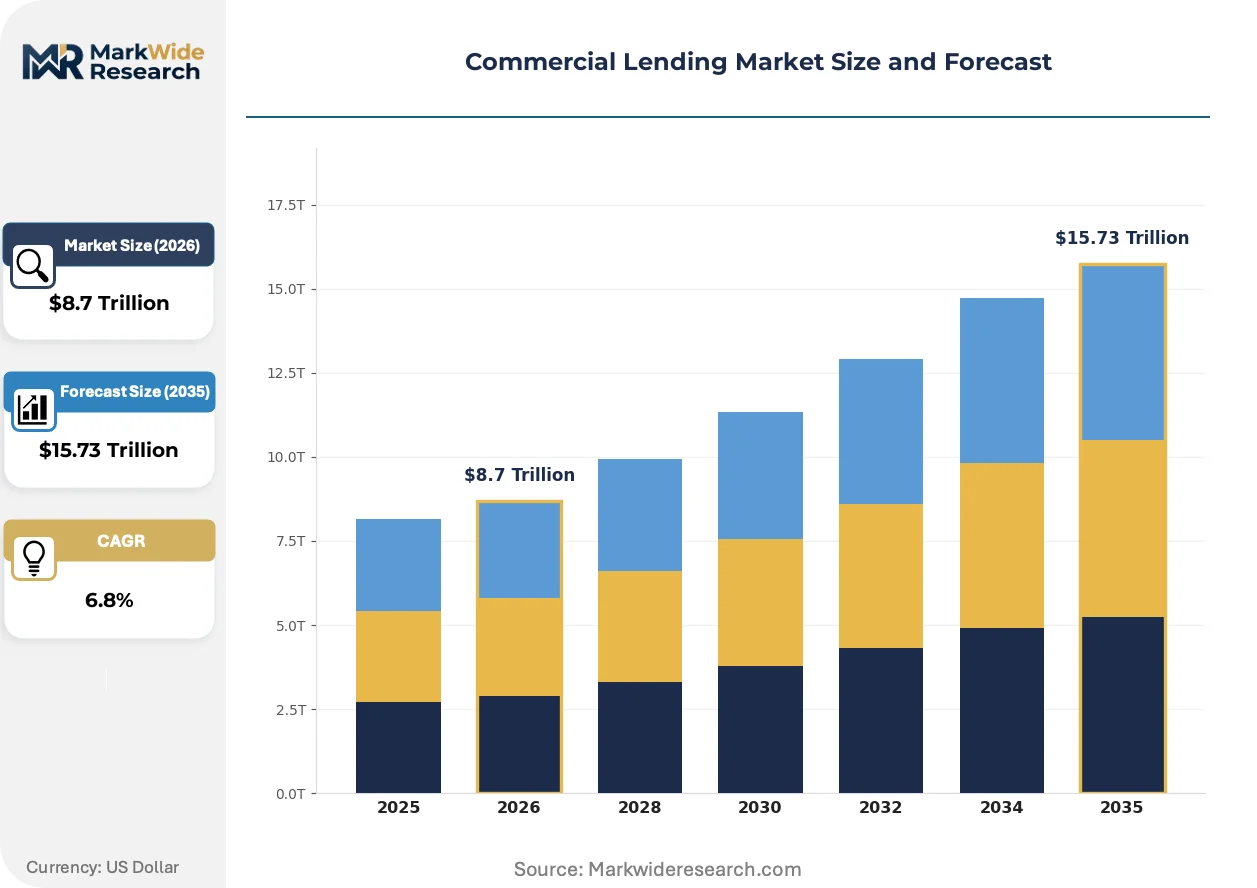
| Market Size in 2026 | $8.7 Trillion |
| Market Size in 2035 | $15.73 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Term Loans, Lines of Credit, Equipment Financing, Commercial Mortgages Customer Type: Small Businesses, Corporations, Non-Profits, Partnerships Industry Vertical: Healthcare, Education, Manufacturing, Retail Purpose: Expansion, Working Capital, Equipment Purchase, Refinancing |
| Companies Covered | Citibank, PNC Bank, JPMorgan Chase, KeyBank, Truist, Bank of America, U.S. Bank, Regions Bank, Wells Fargo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Lending Market Emerging Trajectories
Credit origination infrastructure is undergoing platform modernization as artificial intelligence and open banking data streams reshape underwriting economics and borrower acquisition strategies.
Alternative data integration is migrating from experimental pilot programs to production-grade credit decisioning engines. Fintech-enabled originators are embedding cash flow analytics from accounting software and payment processors into real-time risk monitoring. This capability is compressing the information advantage that traditional relationship banking held over transaction-based competitors.
The Federal Reserve, OCC, and FDIC are harmonizing stress testing protocols for commercial real estate concentrations. Large regional banks must now submit granular loan-level data on office and multifamily exposures. Institutions with elevated construction loan concentrations are preemptively shrinking origination targets to avoid regulatory scrutiny.
Borrowers are unbundling relationship banking and selecting credit providers through competitive bidding platforms. Middle-market treasury departments are running parallel RFP processes for credit facilities, cash management, and hedging services rather than consolidating with incumbent banks. This behavior is most pronounced among private equity-sponsored portfolio companies with sophisticated capital markets access.
Commercial Lending Market Segmentation
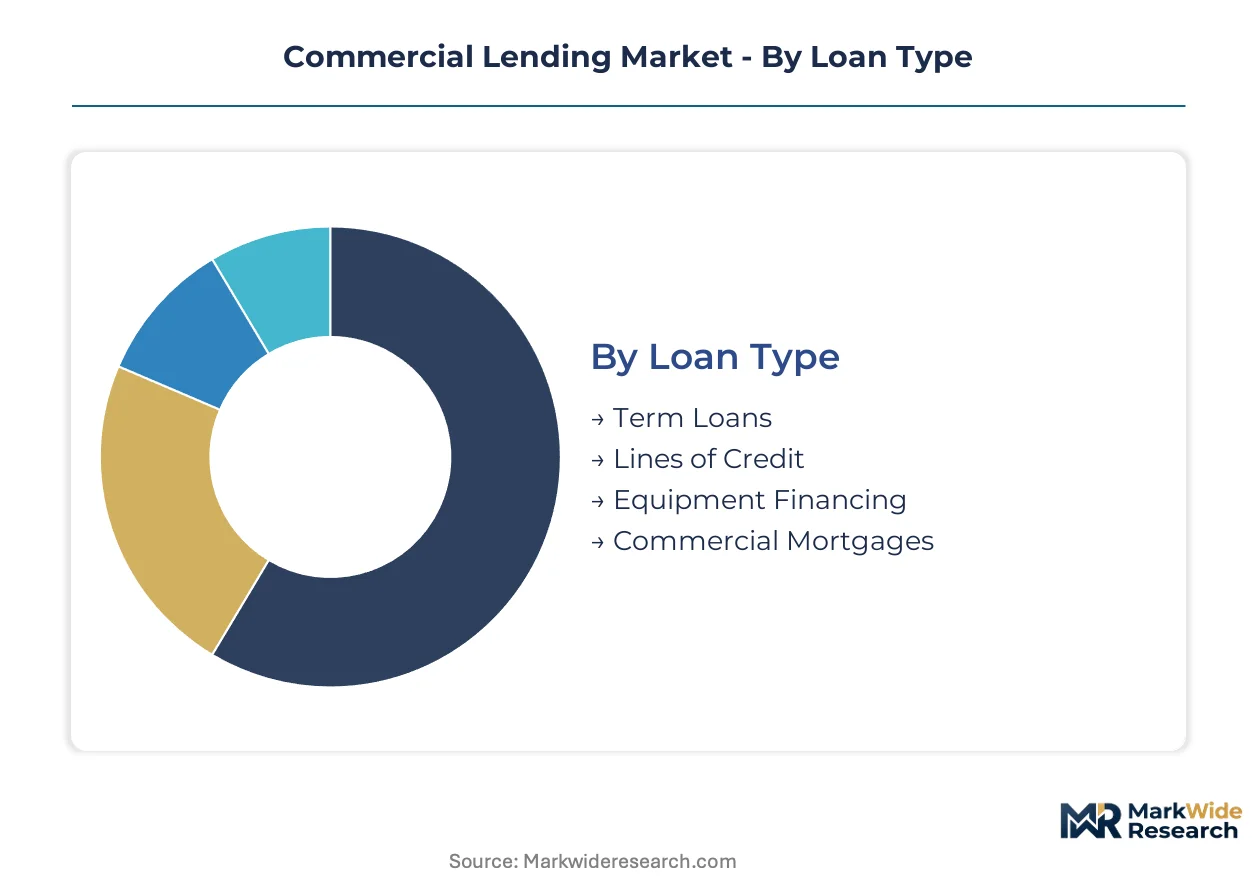
Commercial lending segmentation reveals how capital deployment strategies diverge across borrower profiles, collateral structures, and end-use applications. Lenders calibrate risk-weighting, covenant intensity, and pricing frameworks based on these dimensional splits.
Loan Type:
Borrowers select credit instruments based on cash flow predictability, asset ownership status, and duration of capital need.
- Term Loans:Fixed-maturity facilities with amortizing principal schedules, typically secured by general corporate assets or specific collateral pools. Demand concentrates among middle-market manufacturers in the United States seeking multi-year capital for facility expansion and automation investments, constrained by Basel III risk-weight recalibration on longer-duration exposures.
- Lines of Credit:Revolving facilities providing liquidity buffers against receivable cycles and inventory fluctuations. Regional logistics operators across the Southeast and Midwest draw heavily on these structures to manage working capital seasonality, though commitment fees erode utilization economics during low-rate environments.
- Equipment Financing:Collateral-specific lending secured by machinery, vehicles, and production assets with residual value monitoring.
- Commercial Mortgages:Real estate-backed term facilities for acquisition, construction, and refinancing of income-producing properties.
The dominant share belongs to Term Loans, while Equipment Financing is closing the gap fastest.
Customer Type:
Risk assessment protocols vary sharply across organizational complexity and financial disclosure depth.
- Small Businesses:Borrowers with annual revenues under $50 million, often owner-operated with limited audited financials. Technology-enabled originators using automated underwriting platforms are capturing share in this segment across fragmented metropolitan markets, displacing community bank relationships previously protected by information asymmetry.
- Corporations:Public and large private entities with investment-grade or leveraged credit profiles. Syndicated lending to corporate borrowers concentrates among money-center institutions competing on balance sheet scale and arrangement fee compression.
- Non-Profits:Mission-driven organizations including healthcare systems, universities, and cultural institutions with irregular revenue streams.
- Partnerships:Professional service firms, family offices, and investment vehicles with pass-through tax structures.
Corporations command the deepest liquidity pools, yet Small Businesses are expanding credit utilization most rapidly.
Industry Vertical:
Sector-specific regulatory exposure and cyclical sensitivity drive portfolio allocation decisions.
- Healthcare:Hospital systems, physician practice groups, and medical device manufacturers with reimbursement-dependent revenue models. Borrowing demand from healthcare verticals concentrates in the United States amid consolidation of independent practices into platform networks, though Medicare reimbursement uncertainty constrains long-term leverage appetite.
- Manufacturing:Capital-intensive producers with heavy equipment collateral and export-linked revenue streams. Equipment modernization cycles and reshoring initiatives are pulling incremental credit demand from manufacturing borrowers across industrial corridors in Ohio, Michigan, and Texas.
- Education:K-12 districts, private universities, and vocational training providers with enrollment-driven economics.
- Retail:Brick-and-mortar and omnichannel operators with inventory-heavy balance sheets and consumer discretionary exposure.
Manufacturing anchors portfolio construction by volume, while Healthcare is climbing the fastest on demographic tailwinds.
Purpose:
Stated use-of-proceeds shapes collateral requirements, covenant structures, and lender monitoring intensity.
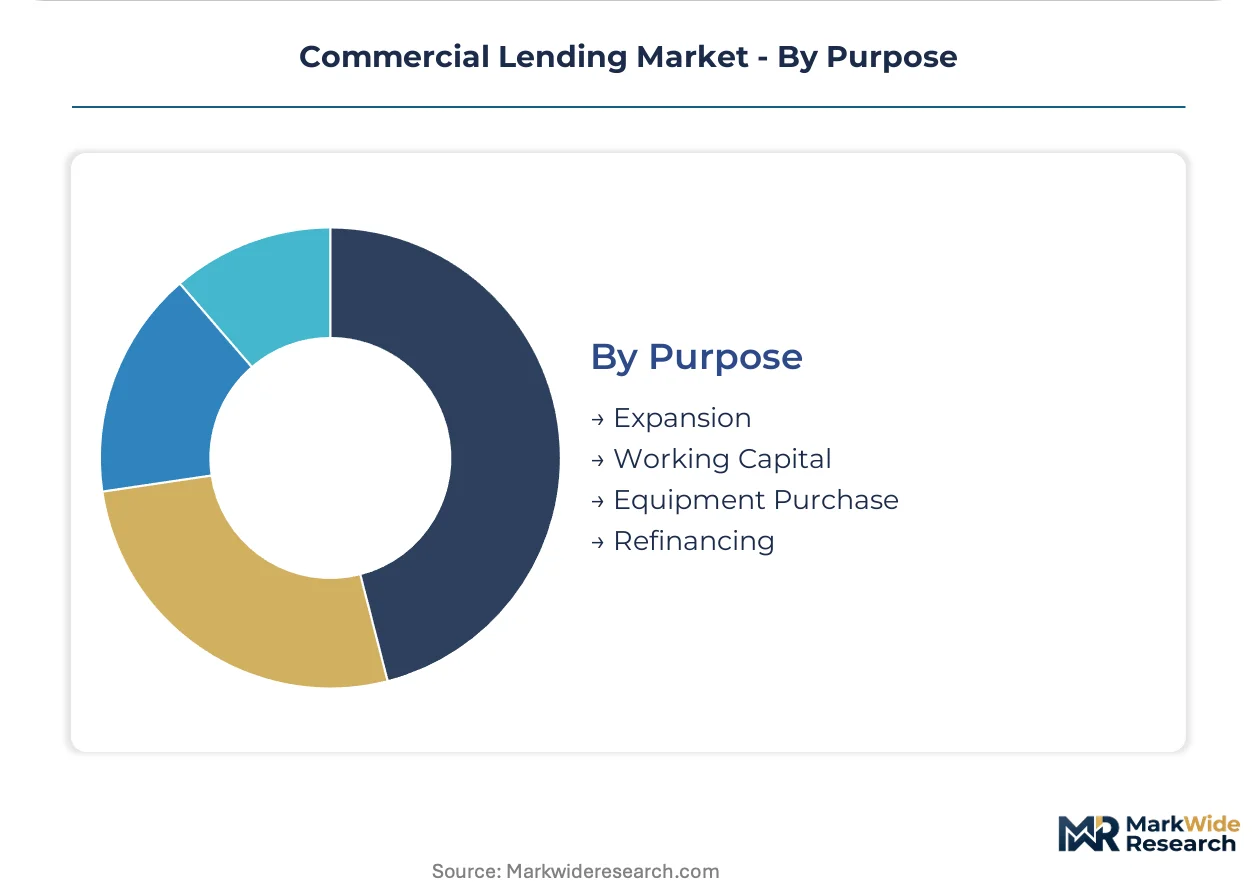
- Expansion:Greenfield development, acquisition financing, and market entry capital with execution risk profiles. Private equity-sponsored portfolio companies in the United States deploy expansion credit to consolidate fragmented verticals, though direct lending fund saturation is compressing arrangement fees in competitive auctions.
- Working Capital:Short-term liquidity for inventory builds, receivable growth, and seasonal operations. Treasury departments at middle-market corporations are unbundling working capital facilities from relationship banks, running competitive RFP processes that favor specialized asset-based lenders.
- Equipment Purchase:Asset-specific financing tied to fleet modernization and automation investments.
- Refinancing:Liability management transactions extending maturities, reducing coupons, or extracting collateral value.
Refinancing dominates current origination pipelines, while Equipment Purchase is gaining share fastest on automation investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in commercial lending concentrates among small business borrowers in fragmented metropolitan markets, while corporate treasury departments at investment-grade issuers demonstrate the least elasticity. Regional banks face divergent competitive pressures based on local deposit franchise strength and non-bank penetration depth.
United States
Middle-market manufacturers in Ohio, Michigan, and Texas are pulling incremental credit demand for equipment modernization and reshoring initiatives. The Federal Reserve, OCC, and FDIC collectively shape capital adequacy and stress testing protocols that constrain large bank lending capacity. Regional banks and money-center institutions in the Southeast and Midwest corridors compete intensely for middle-market share.
Germany
Industrial machinery producers and automotive suppliers drive working capital facility utilization amid export-linked revenue volatility. The country's central bank and BaFin enforce stringent risk-weighting standards that elevate capital charges for longer-duration corporate exposures. Manufacturing clusters in Bavaria and Baden-Württemberg anchor syndicated lending activity for Mittelstand exporters.
United Kingdom
Private equity-sponsored portfolio companies deploy expansion credit to consolidate fragmented verticals, though direct lending fund saturation compresses arrangement fees. The Prudential Regulation Authority and Financial Conduct Authority govern disclosure requirements for loan securitizations. London-based treasury operations at multinational corporations unbundle relationship banking through competitive RFP processes.
Japan
Capital-intensive producers with heavy equipment collateral seek multi-year term facilities for facility automation investments. METI industrial policy and Bank of Japan monetary frameworks influence regional bank portfolio construction. Manufacturing concentrations in the Chubu region around Nagoya sustain dedicated equipment finance origination verticals.
India
Small business borrowers with annual revenues under $50 million expand credit utilization for working capital and inventory expansion needs. The Reserve Bank of India calibrates risk-weighted asset calculations for commercial real estate and leveraged lending exposures. Technology-enabled originators in Maharashtra and Karnataka deploy automated underwriting platforms to capture structurally fragmented segments.
Commercial Lending Market Vendor Landscape
Capability concentration sits with specialized middle-market lenders possessing integrated treasury management expertise; scale advantage sits with money-center institutions commanding balance sheet depth for syndicated transactions. The market structure reveals a tiered competitive field where regional banks defend deposit-funded relationships against private credit funds and fintech-enabled originators. Three archetypes dominate: integrated commercial banking platforms, equipment finance specialists, and technology-driven direct lenders. Competitive moves center on regional consolidation to capture white-space markets and API-based platform modernization to collapse origination costs.
Among integrated commercial banking platforms, JPMorgan Chase exemplifies scale-driven syndicated lending dominance, while PNC Bank occupies a position as a middle-market specialist across the Southeast and Midwest. Truist represents the integrated treasury management archetype with commercial real estate expertise in the Mid-Atlantic and Sun Belt corridors. These three institutions anchor the competitive landscape through distinct geographic and segment positioning rather than undifferentiated product overlap.
| Leading Market Players |
|---|
| Citibank |
| PNC Bank |
| JPMorgan Chase |
| KeyBank |
| Truist |
| Bank of America |
| U.S. Bank |
| Regions Bank |
| Wells Fargo |
| Others |
Supply Flow & Price Mechanics
Capital deployment concentration among United States money-center institutions and regional banks directly determines where origination fee pools accumulate across the commercial lending value chain. Balance sheet scale at JPMorgan Chase and PNC Bank anchors pricing power in syndicated and middle-market segments respectively.
Pricing Analysis
Recurring servicing revenue from treasury management cross-sells and commitment fees drives lifetime borrower value beyond upfront arrangement fees. Three-tier pricing structure across relationship-based, transaction-based, and automated underwriting channels separates incumbent banks from fintech-enabled originators from direct lending funds. Price differentiation hinges on covenant intensity and collateral monitoring sophistication. Pricing pressure stems from direct lending fund saturation crowding middle-market syndications. Small business borrowers in fragmented metropolitan markets exhibit highest price sensitivity; investment-grade corporate treasury departments show least elasticity.
Supply Chain Analysis
Origination capacity concentrates at JPMorgan Chase, PNC Bank, and Truist alongside technology-enabled platforms and private credit funds. Capital sources draw from United States regional bank deposit franchises, money-center balance sheets, and institutional investor commitments to collateralized loan obligations. Key dependencies include Federal Reserve benchmark rates, FDIC deposit insurance pricing, and Basel III risk-weight calibrations. Supply chain risk centers on regulatory capital treatment shifts for high-volatility commercial real estate exposures. Distribution runs through direct sales forces, correspondent banking networks, and competitive bidding platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial lending operates as a service-attach opportunity where integrated treasury management and automated underwriting capabilities expand faster than traditional term loan spreads. Recurring fee income from cash management and FX hedging layers grows disproportionately to net interest margin capture.
For Market Incumbents: Harden deposit franchise defenses against fintech-enabled originators by embedding API-based credit decisioning into legacy core banking infrastructure. Consolidate middle-market share through regional bank acquisition in Southeast and Midwest corridors where scale-driven merger activity creates service gaps. Prioritize certification investment in automated underwriting platforms to match technology-enabled competitors' origination cost structures.
For New Entrants and Emerging Players: Pursue equipment finance automation specialization targeting manufacturing and logistics verticals in Ohio, Michigan, and Texas where fleet modernization demand outpaces incumbent appraisal capacity. Capture small business segments with annual revenues under $50 million through machine learning credit scoring that collapses acquisition costs previously deemed uneconomical. Deploy embedded finance partnerships with accounting software and payment processors as primary go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward technology-enabled originators with production-grade alternative data integration and automated underwriting infrastructure. Long-term viability across the analysis window favors platforms combining balance sheet capacity with API-based distribution rather than pure balance sheet lenders or narrow fintech point solutions. Monitor Basel III endgame implementation timelines as inflection indicator for risk-weight recalibration impacts on bank portfolio construction.
| Strategic Initiative | Industry Significance |
|---|---|
| API-Based Platform Integration | Connects legacy core banking systems to modern credit decisioning engines at PNC Bank and Truist. |
| Automated Underwriting Scale-Up | Collapses origination costs for small business segments using machine learning cash flow analytics. |
| Treasury Management Bundling | Deepens borrower stickiness through cross-sold cash management and FX hedging services. |
| Regional Consolidation | Captures white-space markets in Southeast and Midwest corridors where community bank mergers create gaps. |
| Equipment Finance Specialization | Builds dedicated origination verticals with collateral monitoring technology for manufacturing borrowers. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with commercial banking executives, credit officers, treasury management specialists, and private credit fund managers alongside secondary validation. Primary fieldwork captured origination practices, covenant structures, and competitive positioning at regional banks and money-center institutions. Secondary sources encompassed Federal Reserve Senior Loan Officer Opinion Surveys, OCC call report data, FDIC institution directories, and SEC filings for loan securitization disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from regulatory capital adequacy reports.
Forecast inputs considered loan type segmentation across term loans, lines of credit, equipment financing, and commercial mortgages alongside customer type splits and industry vertical concentrations. Deployment models included relationship-based, transaction-based, and automated underwriting channels across geographic adoption patterns. CAGRs were derived through regression analysis of credit utilization trends against macroeconomic indicators. Industry-specific inputs incorporated Basel III risk-weight evolution scenarios and private credit deployment capacity saturation curves.
Sensitivities concentrate around Federal Reserve monetary policy trajectories, regulatory capital treatment revisions for commercial real estate, and technology-enabled origination platform adoption rates. Forecasts reflect assumptions on bank balance sheet capacity constraints and non-bank lender market share capture. Quarterly review of Senior Loan Officer Opinion Survey results and FDIC call report trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Alternative Financing Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
China Auto Loan Market
Loans and Leasing
Europe Used Car Financing Market
Loans and Leasing
Global Mortgage Lender Market
Loans and Leasing
Alternative Lending Platform Market
Loans and Leasing
Syndicated Loans Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
Global Revenue-Based Financing Market
Loans and Leasing
Micro Lending Market
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
Consumer Credit Market
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
United States Material Handling Leasing and Financing Market