
 Sustainable Finance Market | 2026-2036
Sustainable Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Finance Market Analysis
EU Taxonomy alignment is bifurcating the competitive landscape between qualified green instrument issuers and conventional financiers. JPMorgan Chase & Co. leverages its balance sheet scale to underwrite sustainability-linked loans across multiple jurisdictions. BlackRock, Inc. dominates passive ESG fund construction through its iShares platform. BNP Paribas anchors European green bond origination with dedicated sustainable banking divisions in Paris and Brussels.
Sustainable finance encompasses capital allocation mechanisms that integrate environmental, social, and governance criteria into investment decisions, pricing, and risk assessment, utilizing frameworks such as the Green Bond Principles and Sustainability-Linked Loan Principles to verify impact claims. Its primary commercial purpose channels institutional and retail capital toward projects delivering measurable climate or social outcomes while managing transition risk in portfolios. Green bonds within the Investment Strategy dimension lead issuance volume as sovereign and supranational borrowers tap institutional appetite for labeled debt. The Asset Class segment shows equities capturing retail flows through exchange-traded vehicles, while fixed income retains the dominant share of institutional mandates. Client Type dynamics reveal corporates driving sustainability-linked loan demand as CFOs embed ESG targets into covenant structures.
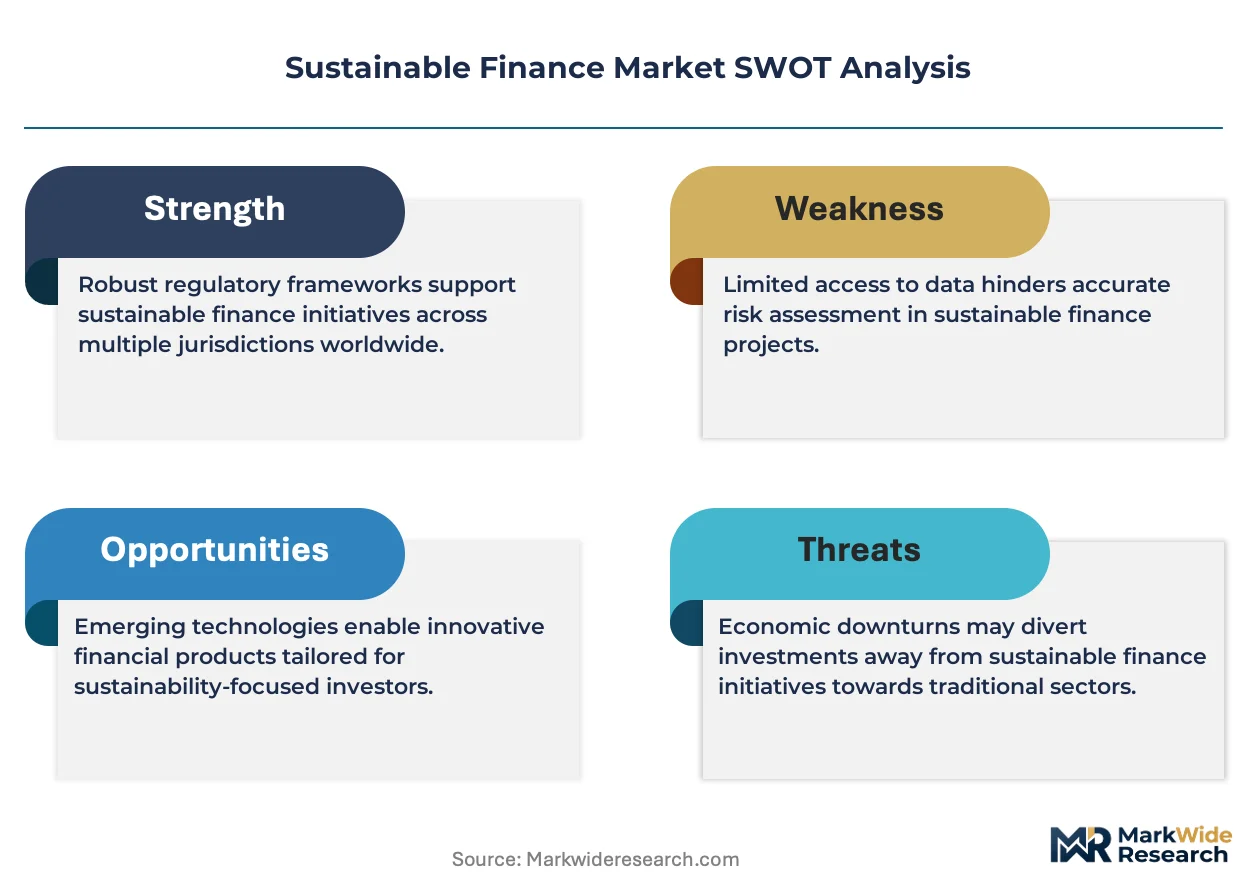
The EU Green Deal and CSRD impose granular disclosure obligations on financial market participants operating across Europe, forcing product redesign and data infrastructure investment. The SEC climate disclosure rules and FINRA guidance shape US market access for labeled instruments, while China's green bond catalog under PBoC and CSRC oversight defines eligible project categories for domestic and offshore issuance. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance fragmentation that raises structuring costs and limits cross-border distribution.
Market Dynamics
EU Taxonomy alignment is bifurcating the competitive landscape between qualified green instrument issuers and conventional financiers, forcing treasury departments to rebuild capital allocation frameworks around climate benchmarks rather than traditional risk-return metrics.
Growth Catalysts
- CSRD Disclosure Mandates:The EU Corporate Sustainability Reporting Directive compels financial market participants to granularly disclose ESG metrics, creating mandatory demand for taxonomy-aligned products and data infrastructure.
- Sustainability-Linked Loan Principles:CFOs embed ESG targets directly into covenant structures, linking borrowing costs to verified climate outcomes and driving standardization across corporate credit facilities.
- KfW Development Bank Channels:Germany's state-owned promotional bank concentrates institutional capital deployment into certified sustainable instruments, establishing a template for sovereign-backed green finance intermediation.
Market Restraints
- Regulatory Fragmentation:Divergence between EU Taxonomy, China's PBoC green bond catalog, and SEC climate disclosure rules raises cross-border structuring costs and limits instrument portability.
- Verification Bottlenecks:Scarcity of accredited second-party opinion providers creates issuance backlogs, particularly for sustainability-linked loans requiring target calibration.
- Data Infrastructure Gaps:Legacy portfolio management systems lack embedded ESG analytics, forcing expensive middleware investments before taxonomy alignment becomes operationally feasible.
Strategic Opportunities
- Biodiversity Credit Markets:Emerging nature-based financial instruments offer uncorrelated exposure beyond carbon, with the Taskforce on Nature-related Financial Disclosures establishing disclosure frameworks.
- Transition Finance Taxonomy:EU regulators are developing criteria for financing emissions-intensive sectors' decarbonization pathways, opening labeled capital flows to heavy industry borrowers.
- Retail ESG Distribution:Exchange-traded fund platforms are compressing fee structures and democratizing access, with robo-advisory channels capturing first-time sustainable investors.
Industry Challenges
- Greenwashing Litigation Exposure:Ambiguous impact claims expose issuers and underwriters to securities fraud actions, demanding forensic-level documentation of use-of-proceeds.
- Climate Scenario Modeling Talent:Shortage of quantitative analysts capable of integrating NGFS transition pathways into credit risk frameworks constrains product innovation velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Finance Market |
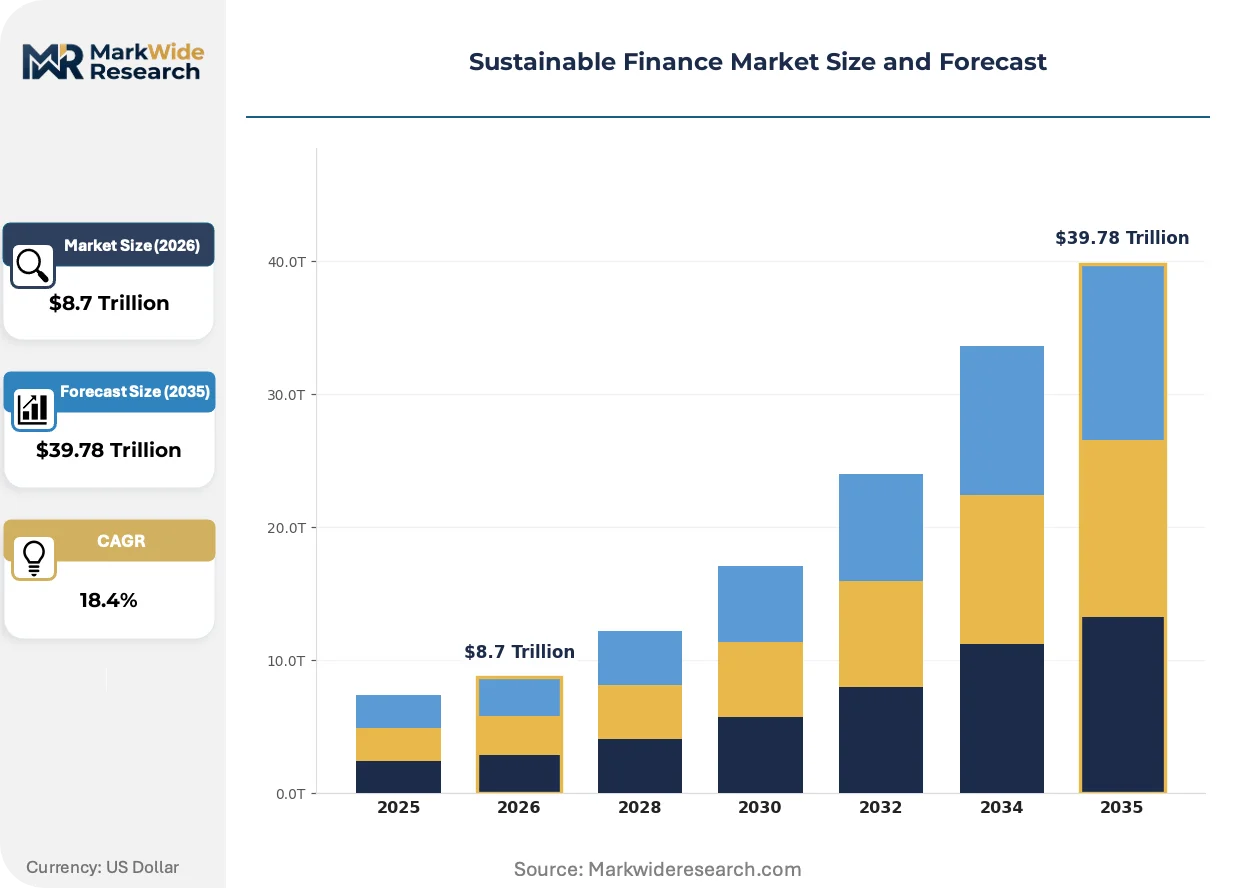
| Market Size in 2026 | $8.7 Trillion |
| Market Size in 2035 | $39.78 Trillion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Impact Investing, Ethical Banking, Green Bonds, Socially Responsible Investing Asset Class: Equities, Fixed Income, Real Estate, Commodities Client Type: Institutional Investors, Retail Investors, Corporates, NGOs Fund Structure: Public Funds, Private Funds, Closed-End Funds, Exchange-Traded Funds |
| Companies Covered | BlackRock, Inc., JPMorgan Chase & Co., Morgan Stanley, Goldman Sachs, BNP Paribas, HSBC Holdings plc, Amundi, ING, UBS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Finance Market Emerging Trajectories
Distributed ledger infrastructure is compressing settlement cycles and enabling fractional ownership of green bond coupons, while machine learning applications automate ESG data ingestion across previously unstructured disclosure formats.
Blockchain-based bond registries are miniaturizing minimum ticket sizes for green fixed income, enabling retail participation in instruments historically reserved for institutional mandates. Sovereign issuers in Southeast Asia pilot tokenized frameworks to broaden their investor base. This technology is miniaturizing the capital-raising threshold, fragmenting traditional book-running concentration among bulge-bracket underwriters.
The SEC's climate disclosure rules reshape liability frameworks for US-domiciled asset managers, mandating Scope 3 emissions quantification and scenario analysis in fund prospectuses. Litigation risk is concentrating among mid-tier private equity sponsors lacking in-house climate analytics. Product teams respond by embedding third-party verification into pre-issuance workflows, extending due diligence timelines.
Asset owners now stipulate Paris Agreement alignment in investment policy statements, displacing passive ESG screening with active engagement mandates. Pension funds and insurance liabilities drive this specification, particularly in Nordic markets where fiduciary duty interpretations have evolved. Consultants report mandate proliferation accelerating fastest among Dutch and Danish institutional allocators.
Sustainable Finance Market Segmentation
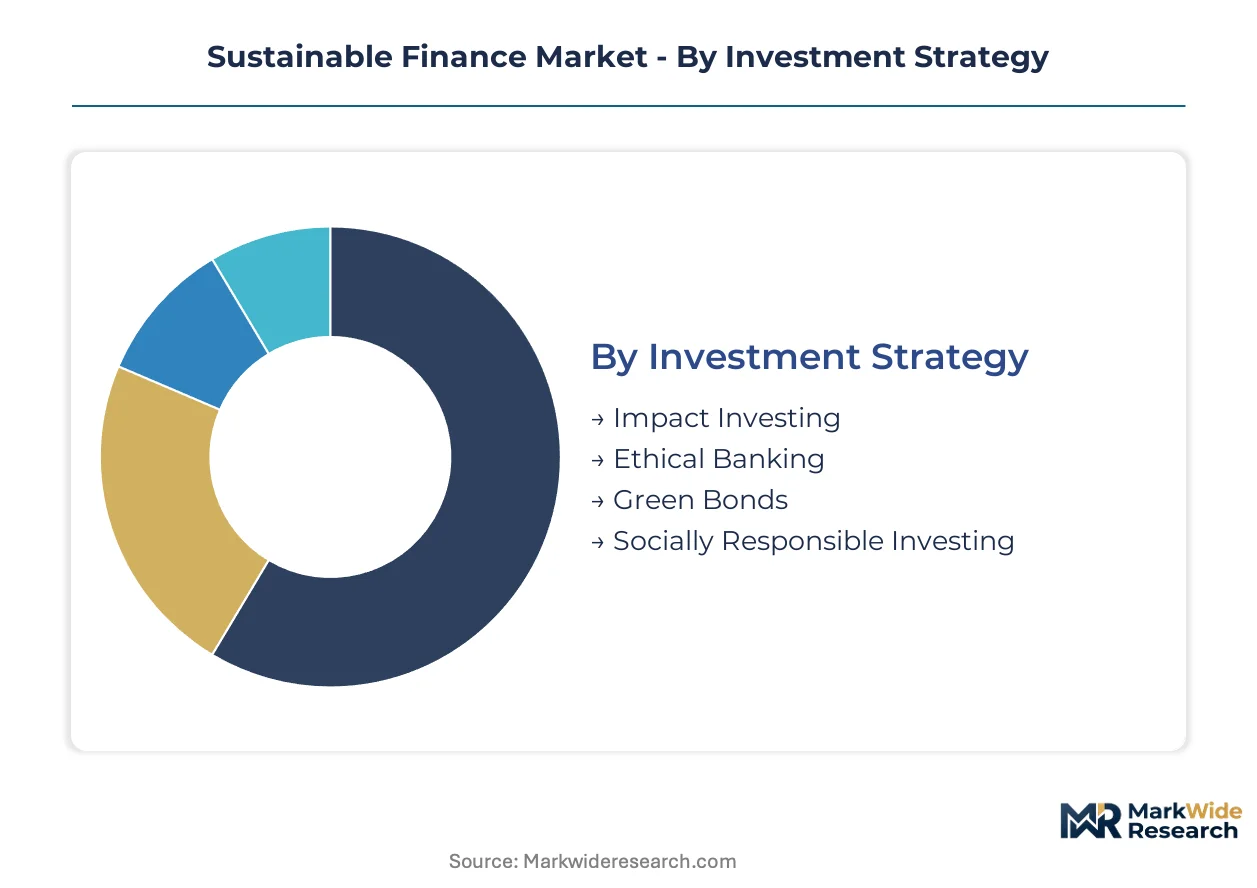
Sustainable finance segmentation reveals how capital flows bifurcate between labeled instruments demanding rigorous verification and conventional products retrofitting ESG overlays. Treasury departments now route allocations through taxonomy-aligned channels, compressing distribution economics for non-compliant structures.
Investment Strategy:
Channel mix varies sharply: Green bonds flow through institutional book-running desks, while impact investing concentrates in private wealth advisory and dedicated fund platforms.
- Green Bonds:Labeled debt instruments with use-of-proceeds ring-fencing verified against Green Bond Principles. German KfW development bank channels sovereign and supranational issuance into institutional portfolios, with EU Taxonomy alignment now mandatory for European distribution.
- Impact Investing:Direct capital deployment targeting measurable environmental or social outcomes alongside financial returns. Demand concentrates in Dutch and Danish pension fund mandates where fiduciary duty interpretations now require Paris Agreement alignment documentation.
- Ethical Banking:Deposit and lending products screening against exclusionary criteria like weapons or fossil fuels. Retail distribution dominates through cooperative banking networks in Germany and France.
- Socially Responsible Investing:Broad ESG integration across public equities and fixed income using negative or positive screens. Robo-advisory platforms in the US and UK are compressing fee structures and democratizing access.
Green bonds dominate installed base. Impact investing is where expansion concentrates.
Asset Class:
Cost tier stratification separates premium-priced labeled instruments from conventional products retrofitting ESG analytics.
- Fixed Income:Green bonds, sustainability-linked loans, and transition finance instruments commanding liquidity premiums in institutional portfolios. BNP Paribas anchors European origination through dedicated sustainable banking divisions in Paris and Brussels.
- Equities:ESG-integrated public equity mandates and thematic funds tracking clean energy or water scarcity. BlackRock's iShares platform dominates passive construction, capturing retail flows through exchange-traded vehicles.
- Real Estate:Green building certifications and energy efficiency retrofits financing through mortgage-backed securities and REIT structures. EU Energy Performance Certificate ratings now determine collateral eligibility for ECB refinancing operations.
- Commodities:Carbon credits, renewable energy certificates, and emerging biodiversity offsets. Singapore and London exchanges are piloting standardized spot and futures contracts for nature-based instruments.
Fixed income retains dominant institutional share. Equities represent the steepest expansion trajectory among retail channels.
Client Type:
Volume concentration sits with institutional mandates, though customer acquisition costs are compressing fastest in retail digital channels.
- Corporates:CFOs embedding ESG targets into covenant structures through sustainability-linked loans. JPMorgan Chase underwrites multi-jurisdictional facilities linking borrowing costs to verified climate outcomes.
- Institutional Investors:Pension funds, insurance liabilities, and sovereign wealth funds stipulating Paris Agreement alignment in investment policy statements. Nordic markets lead mandate proliferation.
- Retail Investors:First-time sustainable investors entering through robo-advisory and ETF platforms with sub-20 basis point fee structures. Millennial and Gen Z demographics drive account opening velocity.
- NGOs:Mission-aligned endowments and development finance institutions deploying patient capital into blended finance structures. Concessional tranches de-risk commercial participation in emerging market projects.
Institutional investors dominate AUM. Corporates are where product innovation concentrates.
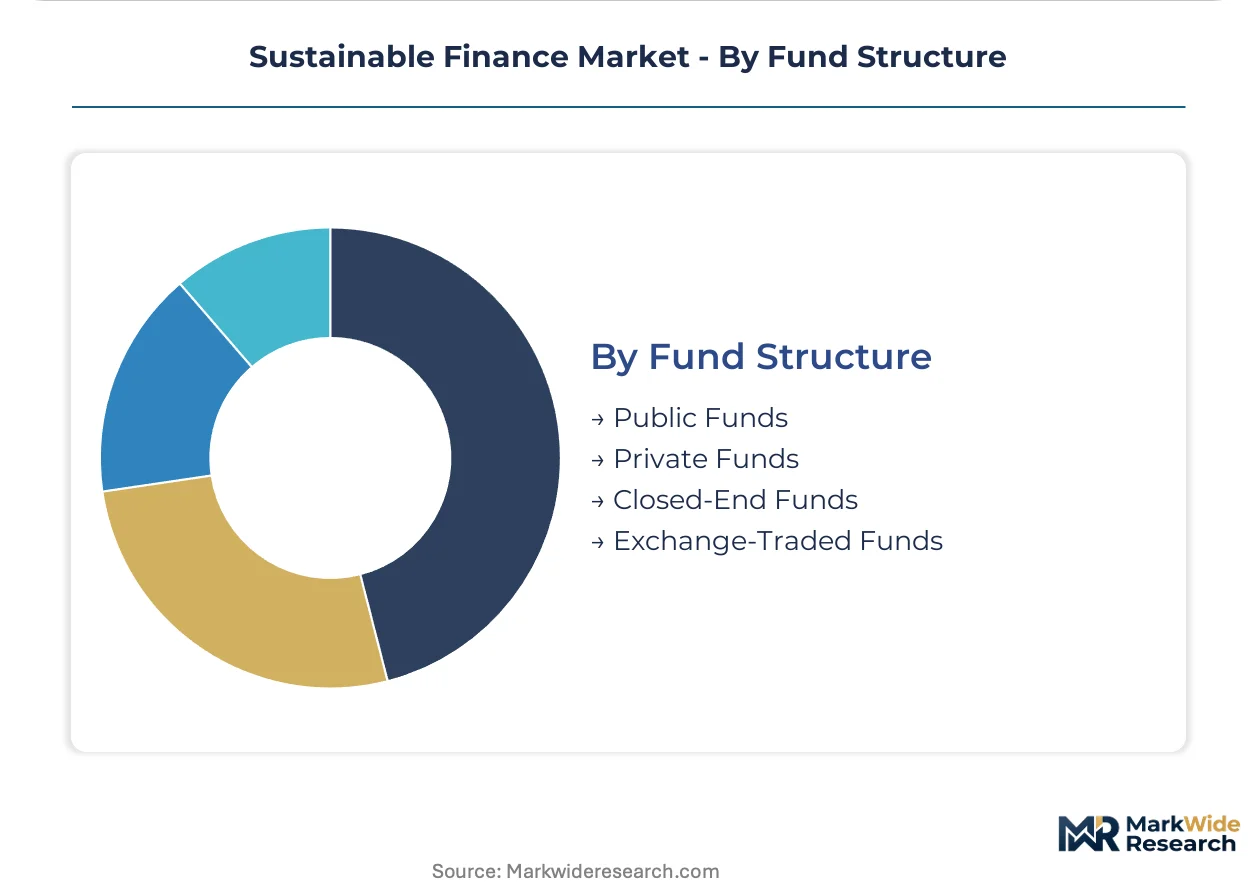
Fund Structure:
Maturity curves separate liquid daily-dealt vehicles from locked-capital structures enabling long-dated impact measurement.
- Exchange-Traded Funds:Passive ESG-screened equity and fixed income baskets with intraday liquidity and compressed expense ratios. European UCITS and US 1940 Act structures dominate cross-border distribution.
- Private Funds:Closed-end limited partnerships targeting direct infrastructure, private equity, and venture impact strategies. Ten-year-plus horizons accommodate project-level outcome verification.
- Public Funds:Mutual fund wrappers with daily liquidity and regulated disclosure regimes. SEC climate disclosure rules and EU SFDR Level 2 technical standards reshape prospectus requirements.
- Closed-End Funds:Listed investment trusts and interval funds holding illiquid sustainable infrastructure assets. Discount-to-NAV volatility creates tactical entry points for yield-focused allocators.
Exchange-traded funds dominate retail distribution. Private funds are where capital formation concentrates for climate infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal subsidies and national green bond programs are redirecting institutional capital flows across major financial centers. Sovereign development banks in Germany, France, and China channel deployment into taxonomy-aligned instruments. Regulatory divergence between jurisdictions is fragmenting cross-border distribution economics.
Germany
KfW development bank concentrates sovereign green bond issuance into institutional portfolios, with EU Taxonomy alignment now mandatory for European distribution. The country's national banking regulator enforces granular ESG disclosure standards under CSRD technical specifications. Frankfurt's financial district anchors continental sustainable debt origination, with dedicated sustainable banking divisions expanding headcount.
United States
Pension funds and insurance liabilities stipulate Paris Agreement alignment in investment policy statements, displacing passive ESG screening. SEC climate disclosure rules mandate Scope 3 emissions quantification and scenario analysis in fund prospectuses. New York's asset management corridor dominates sustainability-linked loan underwriting across multiple jurisdictions.
China
Dual carbon goals under PBoC and CSRC oversight define eligible project categories for domestic and offshore green bond issuance. The country's green bond catalog channels institutional capital into renewable energy and clean transportation infrastructure. Shanghai's financial district pilots tokenized green bond frameworks to broaden retail investor participation.
France
BNP Paribas anchors European green bond origination through dedicated sustainable banking divisions in Paris and Brussels. The country's national securities regulator enforces SFDR Level 2 technical standards on fund prospectus disclosure. Paris competes with Frankfurt for continental sustainable finance talent, with robo-advisory platforms compressing fee structures for retail ESG access.
United Kingdom
Robo-advisory platforms and exchange-traded fund vehicles democratize sustainable investing through sub-20 basis point fee structures. The Financial Conduct Authority shapes market access for labeled instruments through climate disclosure guidance. London's asset management cluster captures Nordic institutional mandates demanding Paris Agreement alignment documentation.
Sustainable Finance Market Vendor Landscape
Listed leaders compete with private specialists across balance sheet scale and geographic coverage dimensions. The market structure concentrates around bulge-bracket underwriters with dedicated sustainable banking divisions and asset managers with passive ESG fund platforms. Strategic archetypes include balance-sheet-driven universal banks, index-constructing asset managers, and regional specialists with taxonomy-aligned origination capabilities. Dominant competitive moves encompass M&A for ESG data infrastructure and strategic partnerships for second-party opinion verification.
Among US-based universal banks, JPMorgan Chase & Co. and Morgan Stanley exemplify the balance-sheet-driven archetype, underwriting multi-jurisdictional sustainability-linked loan facilities. BlackRock, Inc. occupies a distinct position within the index-constructing tier, dominating passive ESG fund construction through its iShares platform. BNP Paribas represents the European regional specialist model, anchoring continental green bond origination with dedicated sustainable banking divisions in Paris and Brussels.
| Leading Market Players |
|---|
| BlackRock, Inc. |
| JPMorgan Chase & Co. |
| Morgan Stanley |
| Goldman Sachs |
| BNP Paribas |
| HSBC Holdings plc |
| Amundi |
| ING |
| UBS |
| Others |
Supply Flow & Price Mechanics
Tokenized settlement infrastructure replacing traditional custodial intermediaries simultaneously compresses transaction costs and redistributes pricing power toward technology-enabled originators, while fragmenting the geographic concentration of book-running activity across Singapore, Frankfurt, and Shanghai.
Pricing Analysis
Taxonomy alignment tier (EU Taxonomy-compliant versus conventional ESG-labeled) creates the primary spread between green bond instruments, with verified use-of-proceeds structures commanding liquidity premiums in institutional portfolios. Pricing stratifies across premium certified green bonds, standard sustainability-linked loans, and economy-tier conventional debt with retrofitted ESG overlays. Cost compression in the standard tier is intensifying because verification bottlenecks and second-party opinion scarcity extend issuance timelines. Corporate treasury departments exhibit the highest price sensitivity, while Nordic pension funds demonstrate inelastic demand for Paris Agreement-aligned documentation.
Supply Chain Analysis
Port congestion along Asia-Europe trade lanes and container availability constraints at Singapore and Rotterdam hubs elevate settlement friction for cross-border green bond clearing. Geographic supply concentration centers on Germany for sovereign green bond origination, France for supranational sustainable banking infrastructure, and China for renewable energy project finance deployment. Raw material dependencies encompass carbon credit verification services, ESG data analytics platforms, and second-party opinion provider capacity. Single-source vulnerability sits with the limited roster of accredited verification bodies. Distribution runs through institutional book-running desks, dedicated sustainable banking divisions, and emerging retail robo-advisory channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sustainable finance incumbents face substitution pressure from decentralized finance protocols and tokenized bond platforms that disintermediate traditional underwriting economics, demanding defensive repositioning around verification capabilities and regulatory licensing.
For Market Incumbents: Consolidate second-party opinion provider relationships and proprietary ESG data infrastructure to defend against fintech-enabled disintermediation. Build captive supply of climate scenario modeling talent through targeted acquisition of quantitative analytics boutiques. Expand balance sheet commitment to sustainability-linked loan origination in jurisdictions with converging disclosure standards.
For New Entrants and Emerging Players: Lead with biodiversity credit market infrastructure and nature-based financial instruments as white-space categories beyond saturated carbon markets. Target transition finance taxonomy applications for emissions-intensive sector borrowers excluded from pure green bond eligibility. Deploy robo-advisory distribution partnerships to capture first-time retail sustainable investors at sub-20 basis point fee structures.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier private equity sponsors lacking in-house climate analytics capabilities and facing concentrated SEC climate disclosure litigation exposure. Long-term viability across the analysis window favors platforms with embedded regulatory compliance infrastructure and multi-jurisdictional licensing. Monitor Taskforce on Nature-related Financial Disclosures framework adoption velocity as inflection indicator for biodiversity instrument liquidity.
| Strategic Initiative | Industry Significance |
|---|---|
| Second-Party Opinion Provider Acquisition | Captures scarce verification capacity essential for EU Taxonomy-aligned issuance. |
| Tokenized Bond Registry Development | Enables fractional ownership and retail participation in Frankfurt and Shanghai pilots. |
| Transition Finance Taxonomy Certification | Opens labeled capital flows to steel and cement sector borrowers under emerging EU criteria. |
| Robo-Advisory Platform Partnership | Compresses customer acquisition costs for millennial and Gen Z sustainable investor segments. |
| Climate Scenario Modeling Talent Acquisition | Addresses quantitative analyst shortage constraining NGFS transition pathway integration. |
Methodological Framework
The analysis maps green bond origination, sustainability-linked loan structuring, impact investing fund platforms, and ESG data infrastructure, each validated through primary interviews with sustainable banking division heads, corporate treasury officers, pension fund mandate specialists, and second-party opinion providers, combined with secondary validation against EU SFDR regulatory filings, SEC climate disclosure rulemakings, Green Bond Principles annual reports, and central bank green bond purchase program disclosures, with bottom-up instrument-level data triangulated against top-down macro capital flow estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical framework modeling across investment strategy, asset class, client type, and fund structure dimensions plus regional regulatory cluster segmentation. CAGRs were derived through regression analysis of historical issuance velocity and forward-looking policy implementation timelines, incorporating EU Green Deal subsidy trajectories, CSRD disclosure mandate phase-ins, and KfW development bank deployment patterns as industry-specific forecast inputs.
Underlying assumptions cover sustained regulatory convergence between EU Taxonomy and emerging transition finance criteria, with deviation risk concentrated in regulatory fragmentation between jurisdictions and verification provider capacity constraints. Forecasts reflect these documented conditions, with outcomes outside this envelope requiring model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Oil and Gas Risk Management Market
Risk Management and Compliance
Global Regulatory Reporting and Compliance Market
Risk Management and Compliance
Risk Assessment Software Market
Risk Management and Compliance
Loan Compliance Management Software Market
Risk Management and Compliance
Global Asset Integrity Management Market
Risk Management and Compliance
Risk Analytics Market
Risk Management and Compliance
China Enterprise Risk Management Market
Risk Management and Compliance
Global Liquidity Asset Liability Management Solutions Market
Risk Management and Compliance
Risk-Based Monitoring Software Market
Risk Management and Compliance
Surety Market
Risk Management and Compliance
Vendor Risk Management Market
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market
Risk Management and Compliance
Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Europe Sustainable Finance Market
Risk Management and Compliance
Europe Strategy Consulting Market
Risk Management and Compliance
Clinical Risk Grouping Solutions Market