
 Europe Motorcycle Loan Market | 2026-2036
Europe Motorcycle Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Motorcycle Loan Market Insights
Aftermarket service revenue is rewriting how European lenders capture lifetime customer value. Santander Consumer Bank leverages its pan-European dealer network to embed maintenance bundles within loan contracts. BNP Paribas Personal Finance sustains margin through co-branded credit cards tied to fuel and insurance spend. Crédit Agricole Consumer Finance anchors its rural dominance by financing farm-adjacent utility motorcycles through regional cooperative branches.
A motorcycle loan is a secured or unsecured credit instrument collateralized by a two-wheeled motorized vehicle with engine displacement typically ranging from 50cc to over 1000cc, structured with fixed or variable interest amortization across 24 to 72 months, primarily enabling consumer acquisition of personal transportation or commercial fleet assets. New motorcycle loans carry the largest principal volumes, though electric motorcycle financing is expanding fastest as battery costs decline and EU CO2 standards tighten. Lease financing occupies a narrow but profitable niche among corporate fleet buyers seeking off-balance-sheet treatment, while unsecured personal loans compete at the subprime margin where traditional asset-backed structures exclude thin-file applicants.
The European Banking Authority's consumer credit directive and national central banks' interest rate policies shape origination volumes and pricing floors across eurozone and non-eurozone markets alike. ESG disclosure requirements under CSRD are pressuring lenders to segment green asset pools and report financed emissions from internal combustion portfolios. Stakeholders must monitor how the EU AI Act's credit-scoring provisions will reshape automated underwriting for thin-file riders and gig-economy delivery operators.
Market Dynamics
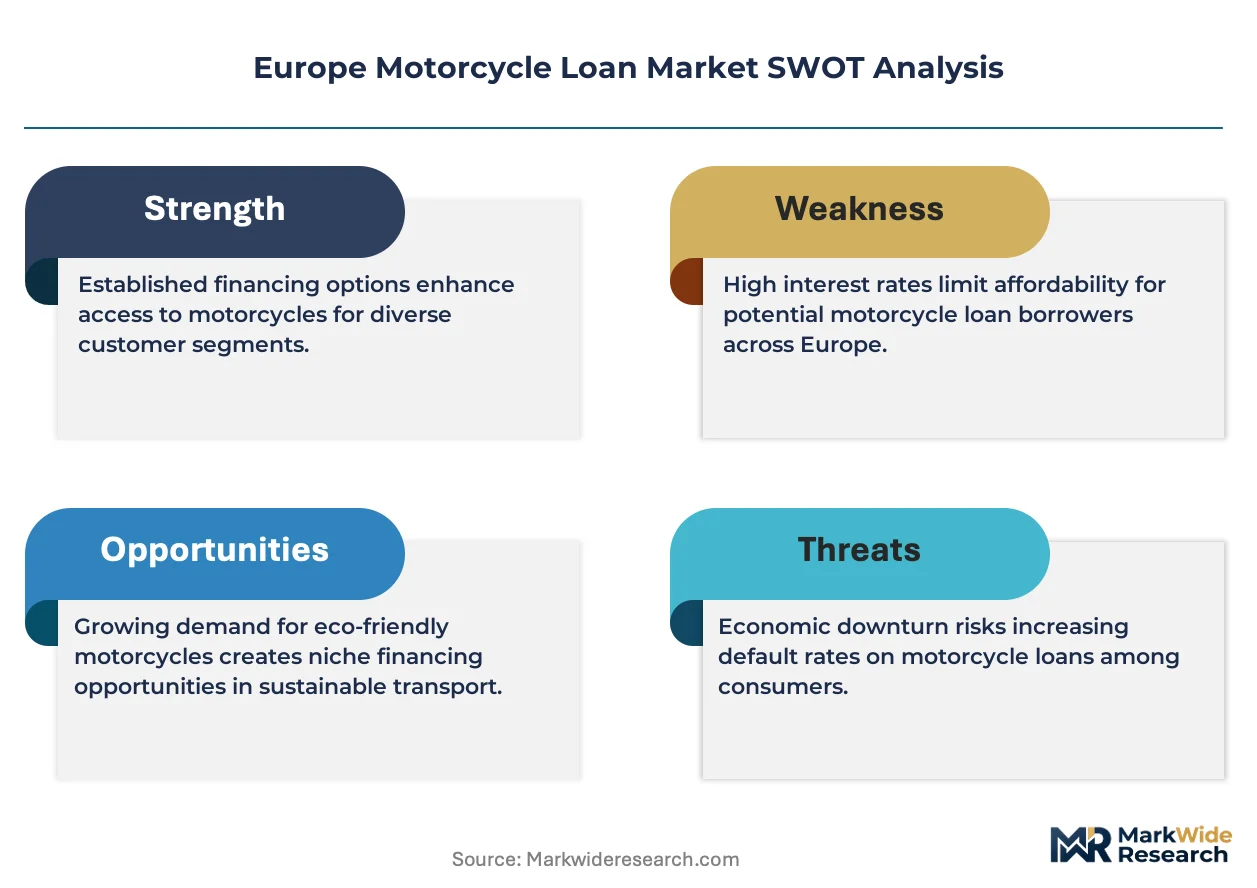
EU Green Deal mandates are forcing motorcycle lenders to restructure loan portfolios around electric vehicle collateral, compressing residual value assumptions for internal combustion assets while opening new underwriting categories for battery-powered two-wheelers.
Growth Catalysts
- EU CO2 Standards:Tightening fleet emission targets are redirecting dealer floorplan finance toward zero-emission motorcycle inventory, accelerating lender product development for electric collateral.
- Gig-Economy Delivery Expansion:Food delivery platforms in Paris, Berlin, and Milan are scaling commercial motorcycle fleets, driving demand for fleet financing products with usage-based repayment structures.
- Battery Cost Decline:Lithium-ion pack prices are compressing electric motorcycle sticker prices toward parity with combustion equivalents, expanding addressable borrower pools for secured asset finance.
Market Restraints
- Residual Value Uncertainty:Rapid technology turnover in electric powertrains is eroding confidence in long-dated loan-to-value ratios for battery motorcycles.
- Interest Rate Sensitivity:European Central Bank policy tightening has lifted consumer credit pricing floors, squeezing margin on fixed-rate motorcycle installment contracts.
- Thin-File Underwriting:The EU AI Act's credit-scoring provisions are constraining automated risk assessment for gig-economy riders with non-standard income documentation.
Strategic Opportunities
- Poland and Romania:Underpenetrated rural motorcycle markets offer white space for regional cooperative lenders to replicate Crédit Agricole's farm-adjacent utility vehicle model.
- Embedded Insurance Bundles:Telematics-enabled usage-based coverage integrated within loan contracts is opening recurring revenue streams beyond interest income.
- CSRD Green Asset Pools:ESG disclosure requirements are creating first-mover advantage for lenders who segment and securitize electric motorcycle receivables as certified green instruments.
Industry Challenges
- Data Architecture Fragmentation:Legacy core banking systems at mid-tier lenders lack API connectivity to dealer management platforms, delaying real-time loan origination.
- Skills Gap in Battery Valuation:Underwriting teams lack technical capacity to assess lithium-ion degradation curves, complicating collateral appraisal for electric motorcycle finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Motorcycle Loan Market |
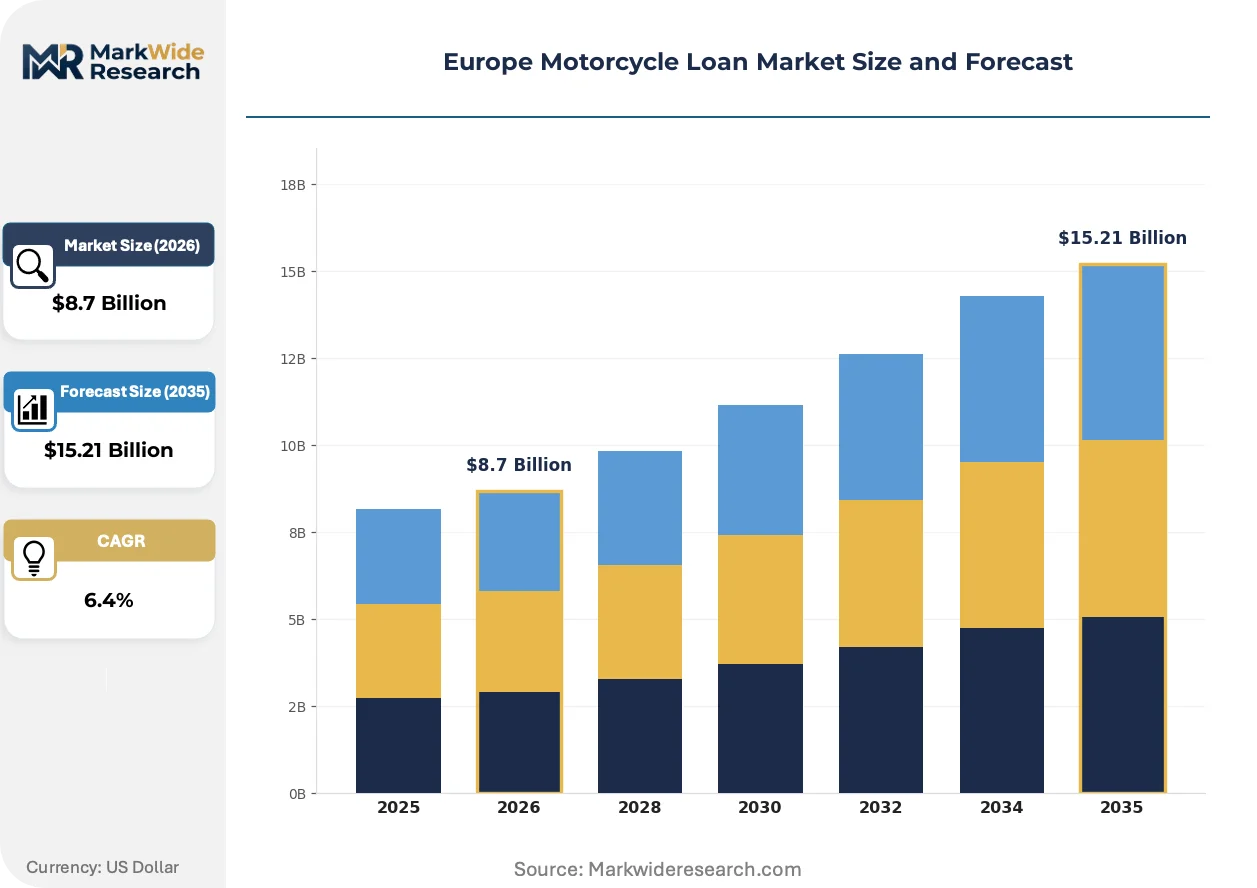
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: New Motorcycles, Used Motorcycles, Electric Motorcycles, Cruiser Motorcycles End User: Individual Buyers, Dealerships, Corporate Fleets, Rental Services Loan Type: Secured Loans, Unsecured Loans, Lease Financing, Personal Loans Interest Rate Model: Fixed Rate, Variable Rate, Hybrid Rate, Promotional Offerings |
| Companies Covered | Santander Consumer Bank, BNP Paribas Personal Finance, Crédit Agricole Consumer Finance, Volkswagen Financial Services, Yamaha Motor Finance, TARGOBANK, Honda Financial Services, Cofidis, BMW Financial Services, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Motorcycle Loan Market Trends and Innovations
Digital origination platforms and embedded finance architectures are compressing the motorcycle purchase journey from dealership visit to fund disbursement, collapsing traditional bank-branch intermediation.
Telematics-integrated loan contracts are rendering obsolete static collateral monitoring. Devices that transmit real-time location, battery health, and rider behavior data to lenders are enabling dynamic risk pricing. Santander Consumer Bank and BNP Paribas Personal Finance are piloting usage-adjusted interest rates for commercial fleet borrowers.
The EU AI Act's provisions on automated credit decisions are mandating human-in-the-loop overrides for algorithmic scoring of thin-file applicants. Lenders must rebuild underwriting workflows to document explainability trails. France and Germany are seeing the earliest compliance implementations, with national banking supervisors issuing granular technical guidance.
Subscription-style mobility contracts are displacing conventional ownership finance among urban commuters in Milan and Barcelona. Riders pay all-inclusive monthly fees covering vehicle, maintenance, insurance, and battery swap access. This model shifts lender relationships from discrete loan origination toward continuous service provisioning, demanding new balance sheet and customer lifetime value calculations.
Europe Motorcycle Loan Market Segmentation
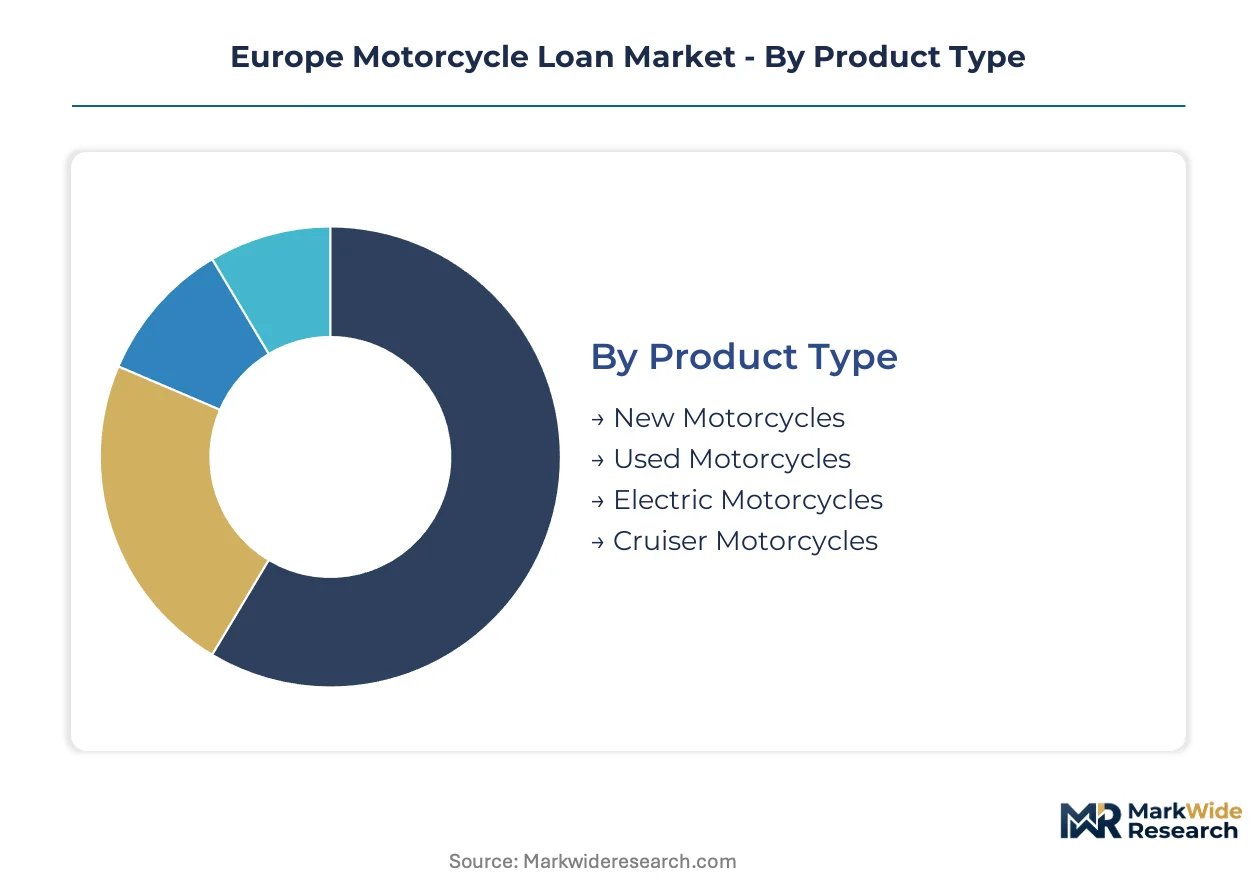
Segmentation in the Europe Motorcycle Loan Market reveals how collateral risk, borrower profiles, and rate structures fragment origination strategies across national banking systems. Lenders calibrate product design to electric vehicle residual value uncertainty, gig-economy income documentation gaps, and dealer floorplan concentration in France, Germany, and Italy.
Product Type:
Cost tier stratification separates premium collateral from volume-driven used-asset origination, with powertrain technology introducing new valuation methodologies.
- New Motorcycles:Factory-fresh internal combustion and electric models carry manufacturer warranty backing, reducing lender collateral risk. Santander Consumer Bank and BNP Paribas Personal Finance concentrate dealer floorplan capacity in Paris, Berlin, and Milan showrooms where EU CO2 compliance deadlines accelerate inventory turnover.
- Electric Motorcycles:Battery-electric two-wheelers with lithium-ion packs require specialized degradation curve assessment absent from traditional motorcycle underwriting. Crédit Agricole Consumer Finance pilots telematics-integrated loan contracts in French rural markets to monitor real-time battery health and adjust residual value assumptions dynamically.
- Used Motorcycles:Pre-owned internal combustion assets trade on established depreciation schedules across European secondary markets.
- Cruiser Motorcycles:Heavy-displacement leisure bikes appeal to discretionary borrowers with stronger credit profiles in German and Italian markets.
New Motorcycles holds installed capacity. Electric Motorcycles is rotating up the share rankings.
End User:
Customer type fragmentation splits origination between retail branch networks, dealer captive finance, and fleet management platforms serving platform economy logistics.
- Individual Buyers:Retail consumers purchasing for personal transportation or leisure use standard income documentation and credit bureau scoring. French and German urban commuters face tightening low-emission zone access rules that redirect demand toward electric motorcycle collateral requiring adjusted loan-to-value ratios.
- Corporate Fleets:Food delivery platforms and last-mile logistics operators seek usage-based repayment structures tied to vehicle utilization. Berlin-based fleet managers negotiate with Santander Consumer Bank for telematics-linked contracts where monthly payments fluctuate with mileage and battery swap frequency.
- Dealerships:Dealer floorplan finance supports inventory holding costs for multi-brand showrooms.
- Rental Services:Short-term mobility providers in Barcelona and Milan experiment with subscription-style contracts displacing conventional ownership finance.
Individual Buyers holds installed capacity. Corporate Fleets is rotating up the share rankings.
Loan Type:
Security structure determines capital treatment and pricing floors, with asset-backed instruments dominating secured finance and unsecured products capturing thin-file margin.
- Secured Loans:Collateralized credit instruments with motorcycle asset registration give lenders priority claim and repossession rights. Italian and Spanish lenders embed maintenance bundles and telematics monitoring to protect residual value on long-dated 60-72 month contracts.
- Lease Financing:Operating lease structures provide off-balance-sheet treatment for corporate fleet buyers seeking accounting flexibility. German commercial borrowers utilize lease products to manage electric motorcycle technology turnover risk as EU battery standards evolve.
- Unsecured Loans:Personal credit without asset collateral competes at subprime margin where traditional secured structures exclude non-standard income profiles.
- Personal Loans:General-purpose consumer credit repurposed for motorcycle acquisition lacks collateral registration and asset-specific covenants.
Secured Loans holds installed capacity. Lease Financing is rotating up the share rankings.
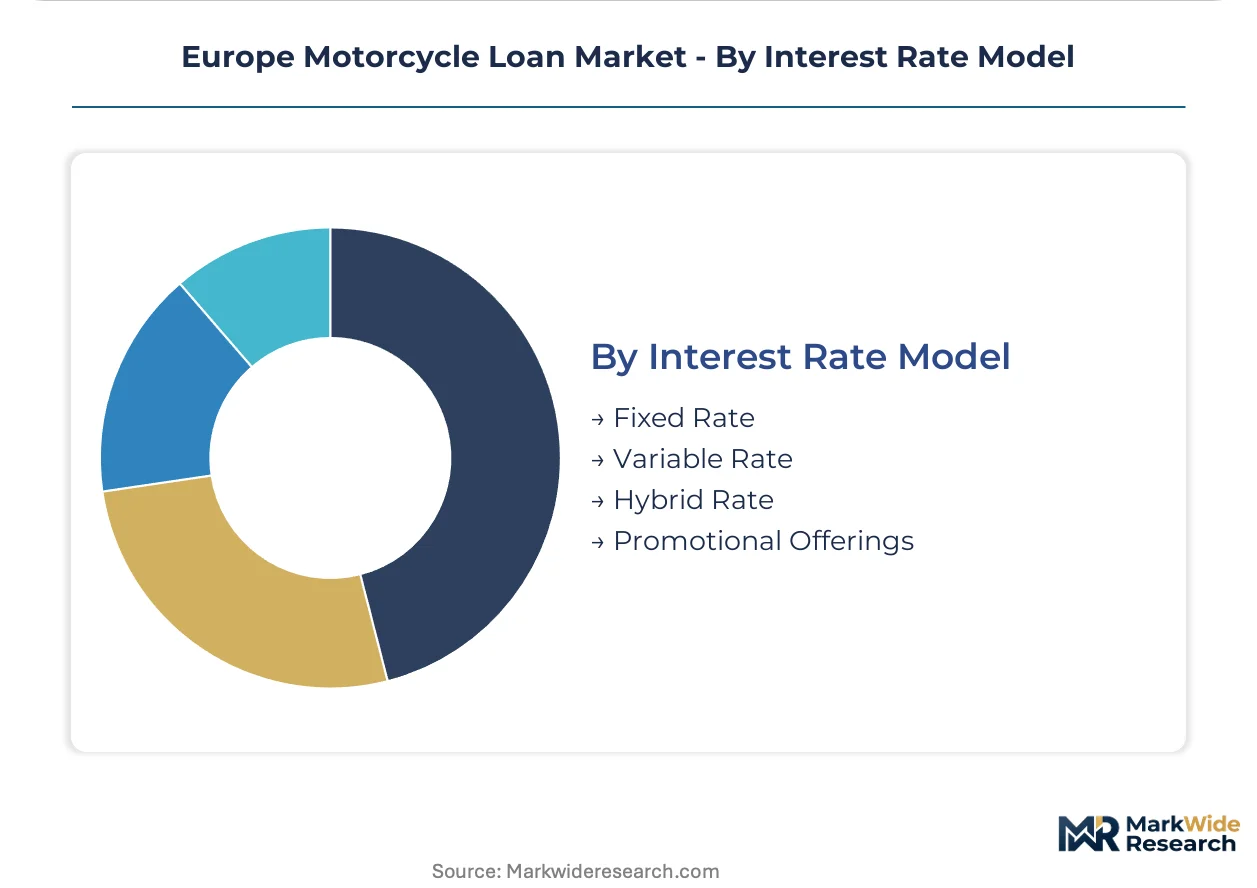
Interest Rate Model:
Rate structure maturity spans fixed-rate installment tradition through dynamic pricing experiments responding to central bank policy and collateral risk telemetry.
- Fixed Rate:Predetermined interest amortization across 24-72 month terms dominates European motorcycle installment lending. French and German borrowers favor payment certainty as European Central Bank tightening compresses lender margins on originated fixed-rate books.
- Variable Rate:Euribor-linked pricing transfers interest rate risk to borrowers but exposes lenders to prepayment acceleration when policy rates decline.
- Hybrid Rate:Fixed-initial periods transitioning to variable structures attempt rate risk allocation balance.
- Promotional Offerings:Manufacturer-subsidized zero-percent campaigns move volume through dealer networks at compressed lender yield.
Fixed Rate holds installed capacity. Variable Rate is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dealer floorplan finance concentrates in Paris, Berlin, and Milan showrooms where multi-brand networks hold inventory backing from captive lenders. National banking supervisors in France, Germany, and Italy enforce divergent consumer credit pricing floors that fragment cross-border product standardization.
Germany
Commercial fleet buyers in Berlin and Hamburg negotiate telematics-linked lease structures for electric motorcycle technology turnover protection. The KBA enforces type-approval standards that compress residual value windows for internal combustion collateral. Bavaria-based manufacturers anchor floorplan demand through captive finance subsidiaries.
France
Parisian urban commuters face tightening low-emission zone access rules that redirect demand toward battery-electric two-wheelers requiring adjusted loan-to-value ratios. The CNIL interprets GDPR provisions that constrain automated underwriting data collection for thin-file gig-economy riders. Crédit Agricole's regional cooperative branches dominate rural utility motorcycle origination through farm-adjacent collateral expertise.
Italy
Milan and Rome food delivery platforms scale commercial motorcycle fleets driving demand for usage-based repayment products. The Bank of Italy's consumer credit supervision mandates human-in-the-loop overrides for algorithmic scoring under EU AI Act anticipation. Lombardy dealerships concentrate multi-brand inventory finance where Santander Consumer Bank holds floorplan capacity.
Spain
Barcelona rental services experiment with subscription-style mobility contracts displacing conventional ownership finance among urban commuters. The CNMV coordinates with national banking supervisors on ESG disclosure alignment for green asset pool segmentation. Catalonia-based fleet managers pilot battery-swap integrated loan structures.
Netherlands
Randstad corridor commuters confront congestion charging schemes that accelerate electric motorcycle adoption through tax-advantaged lease products. The Dutch central bank's interest rate transmission squeezes fixed-rate installment margins for traditional collateral. Amsterdam-based fintech platforms embed insurance bundles within digital origination workflows.
Europe Motorcycle Loan Market Competitive Landscape
Pan-European dealer networks and national cooperative banking systems split the market between scale-driven captive finance and relationship-driven regional lending. Consolidation pressures concentrate floorplan capacity among three strategic archetypes: automotive-captive lenders, consumer finance specialists, and agricultural-cooperative banks. Portfolio diversification into telematics-integrated contracts and green asset securitization represents the dominant competitive move alongside geographic expansion into underpenetrated Eastern European markets.
Within the automotive-captive tier, Volkswagen Financial Services and BMW Financial Services exemplify manufacturer-backed lenders leveraging brand-specific residual value expertise. Santander Consumer Bank anchors the consumer finance specialist archetype through pan-European dealer network penetration. Crédit Agricole Consumer Finance occupies the cooperative banking position with rural utility motorcycle dominance through regional branch infrastructure.
| Leading Market Players |
|---|
| Santander Consumer Bank |
| BNP Paribas Personal Finance |
| Crédit Agricole Consumer Finance |
| Volkswagen Financial Services |
| Yamaha Motor Finance |
| TARGOBANK |
| Honda Financial Services |
| Cofidis |
| BMW Financial Services |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion battery cell manufacturing concentration in South Korea and Japan feeds directly into electric motorcycle collateral valuation methodologies, compressing lender margins when pack costs decline while amplifying residual value risk when supply tightens.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across European motorcycle lending, separating premium electric collateral with telematics integration from standard internal combustion assets and economy-tier used-vehicle origination. Price differentiation rests on battery health certification grade and bundled after-sales service depth. Pricing pressure stems from European Central Bank rate transmission squeezing fixed-rate installment yields. Corporate fleet buyers in Berlin and Milan show least price sensitivity due to usage-based contract structures, while subprime individual borrowers in secondary French markets face the tightest affordability constraints.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk for battery-electric motorcycle components, particularly lithium-ion cells and power electronics. Manufacturing concentration centers on China, South Korea, and Japan for critical inputs including cathode materials, semiconductor controllers, and thermal management systems. Single-source vulnerability persists for advanced battery management systems tethered to specific cell chemistries. Distribution runs through captive finance subsidiaries of Bavaria-based and Lombardy-based manufacturers into authorized dealer networks across Paris, Berlin, and Milan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Motorcycle Loan Market tracks a cyclical recovery anchored to EU CO2 compliance deadlines accelerating electric vehicle inventory turnover and refinancing demand across dealer floorplan networks.
For Market Incumbents: Entrench dealer floorplan dominance through telematics-integrated contract architectures that lock in multi-year service revenue streams. Threats from fintech platforms with API-native origination demand urgent legacy core banking modernization. Capacity addition in Polish and Romanian rural markets through cooperative banking partnerships offers defensive geographic diversification against margin compression in saturated Western European corridors. For New Entrants and Emerging Players: Establish a beachhead in battery-swap integrated subscription financing for Barcelona and Milan urban mobility providers. White space concentrates in telematics-enabled usage-based products for gig-economy delivery fleets where incumbent lenders lack automated underwriting infrastructure. Go-to-market leverage rests on partnership with battery-swap network operators rather than traditional dealer channel dependence. For Investors and Strategic Acquirers: Capital is best deployed toward regional cooperative lenders with farm-adjacent utility motorcycle expertise and underutilized branch infrastructure across Eastern Europe. Long-term viability over the next decade hinges on electric collateral underwriting capability and green asset pool segmentation for CSRD-compliant securitization. Watch electric motorcycle registration penetration in Paris low-emission zones as the inflection signal for portfolio rotation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Integrated Contract Deployment | Enables dynamic residual value adjustment for battery-electric collateral through real-time health monitoring. |
| Green Asset Pool Securitization | Positions electric motorcycle receivables for CSRD-compliant ESG disclosure and certified green instrument status. |
| Cooperative Bank Network Expansion | Replicates Crédit Agricole's rural utility model in underpenetrated Polish and Romanian agricultural regions. |
| API-Native Origination Platform | Compresses dealership-to-disbursement timelines against legacy core banking systems at mid-tier lenders. |
| Embedded Insurance Bundle Integration | Captures recurring telematics-enabled usage-based coverage revenue beyond interest income streams. |
Research Methodology
Desk research of European Banking Authority consumer credit directives, national central bank interest rate policy filings, and dealer floorplan disclosure documents preceded structured interviews with captive finance subsidiary executives, cooperative banking regional directors, fintech platform CTOs, and gig-economy fleet procurement managers. Secondary validation drew from EU Green Deal regulatory texts, CSRD implementation guidance, and electric vehicle registration databases across France, Germany, and Italy. Bottom-up origination volume modeling triangulated against top-down addressable market sizing from automotive production and consumer credit bureau aggregates.
Assumptions held fixed include EU CO2 standard compliance deadlines and European Central Bank policy rate trajectories across the projection horizon, while electric motorcycle battery cost curves and gig-economy platform fleet expansion rates were varied under sensitivity scenarios. Segmentation dimensions modeled encompass collateral type, end-user category, loan security structure, and interest rate mechanism alongside powertrain technology transition pathways. CAGRs were synthesized from fitted trend extrapolation cross-checked against industry stakeholder growth expectations. Key forecast inputs included lithium-ion pack price elasticity and low-emission zone geographic expansion schedules.
Sensitivities concentrate around European Central Bank rate reversal timing, electric powertrain residual value volatility, and EU AI Act automated underwriting compliance costs. Forecasts reflect documented assumptions subject to revision from regulatory interpretation shifts or battery technology disruption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Auto Finance Market
Loans and Leasing
Consumer Credit Market
Loans and Leasing
Europe Crowd Lending and Crowd Investing Market
Loans and Leasing
North America Syndicated Loans Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
India Used Car Financing Market
Loans and Leasing
France Mortgage/Loan Brokers Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
US Mortgage/Loan Brokers Market
Loans and Leasing
Peer-To-Peer Lending Market
Loans and Leasing
UK Mortgage / Loan Broker Market
Loans and Leasing
Florida Digital Lending Market
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
Asia-Pacific Used Car Financing Market