
 Entertainment Insurance Market | 2026-2036
Entertainment Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Entertainment Insurance Market Analysis
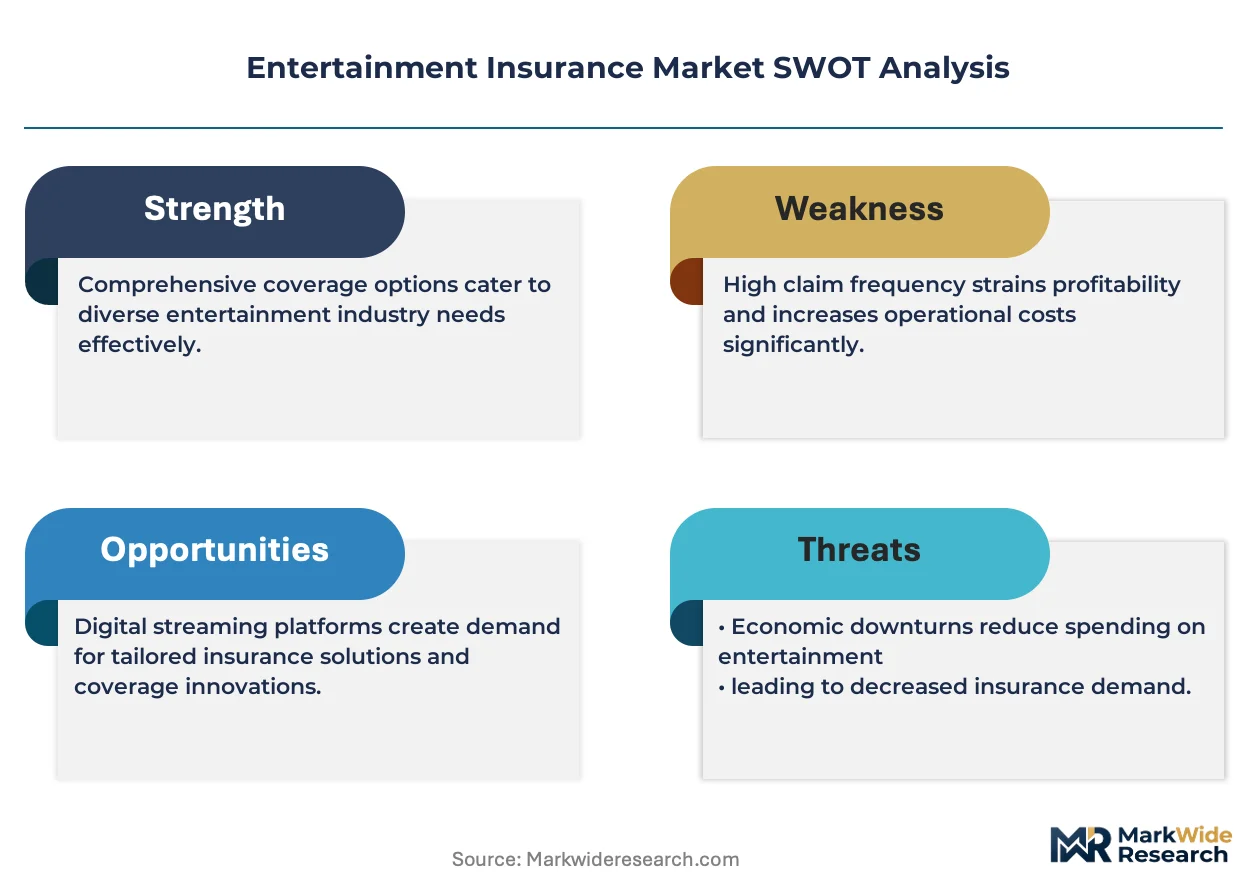
Cloud-based risk analytics is decoupling entertainment insurance pricing from traditional manual underwriting. Chubb leverages proprietary catastrophe modeling to price event cancellation policies for major music festivals. Hiscox anchors its competitive position through specialized film production coverage targeting independent producers and documentary filmmakers.
Entertainment insurance encompasses specialized property and casualty coverage designed to protect film, television, live event, and media production assets against financial loss from production delays, equipment damage, liability claims, and talent unavailability; policies typically incorporate cast insurance, negative film coverage, and extra expense provisions with deductibles scaled to budget tiers. Film production policies command the largest premium pool given the capital intensity of theatrical and streaming releases, while event cancellation coverage has emerged as the fastest-expanding segment as festival organizers seek protection against weather, terrorism, and pandemic-related disruptions. Broker-assisted distribution still dominates placement for complex international co-productions, though online platforms are gaining traction for standardized equipment and short-term liability products.
US state insurance commissioners and Lloyd's of London syndicates jointly govern market access through surplus lines eligibility and admitted carrier capital requirements, while EU Solvency II frameworks constrain how European underwriters reserve for long-tail entertainment liability. The US Federal Aviation Administration and national aviation regulators in production-heavy jurisdictions impose strict unmanned aerial vehicle certification standards that directly affect drone cinematography coverage terms. Stakeholders must monitor how generative AI content creation tools reshape intellectual property risk profiles and force revisions to errors and omissions policy language.
Market Dynamics
Streaming platforms are decoupling entertainment insurance demand from traditional theatrical release cycles, creating year-round production volatility that strains traditional underwriting calendars and forces carriers to build continuous-deployment pricing engines.
Growth Catalysts
- EU AI Act compliance mandates:Productions deploying generative AI tools for script development or synthetic talent now require expanded errors and omissions coverage, creating new policy riders across European co-productions.
- Drone cinematography certification:The US FAA's Part 107 unmanned aerial vehicle licensing expansion has normalized aerial filming risks, enabling standardized hull and liability coverage for previously uninsurable low-altitude shots.
- London surplus lines concentration:Lloyd's syndicate specialization in cast non-appearance and weather interruption policies provides capacity depth that admitted carriers cannot match for high-budget international shoots.
Market Restraints
- Talent health verification opacity:Cast medical disclosure gaps create adverse selection pools where high-risk performers concentrate in policies lacking real-time biometric monitoring.
- California wildfire season extension:Location shoot property coverage in Los Angeles County faces rolling six-month moratoriums as fire risk models recalibrate burn probability curves.
- Completion bond substitution:Bank-backed completion guarantees for independent films are displacing traditional production insurance for sub-$5 million budgets, compressing premium volume at the market base.
Strategic Opportunities
- Saudi Arabia production incentive zones:NEOM and AlUla filming hubs lack mature local insurance infrastructure, creating first-mover advantage for carriers establishing admitted carrier partnerships with the country's national regulator.
- Parametric weather triggers:Index-based rainfall and temperature thresholds are integrating with event cancellation policies, enabling instant payout mechanisms that bypass traditional loss adjustment delays.
- Virtual production stage adoption:LED volume technology convergence with real-time rendering is reducing location-dependent risk exposure, allowing carriers to price volume-stage shoots as controlled studio environments rather than variable on-location exposures.
Industry Challenges
- Underwriter specialization scarcity:The market lacks sufficient professionals trained simultaneously in film production workflows and casualty actuarial methods, creating quoting bottlenecks for complex international co-productions.
- Generative IP contamination:Training data provenance disputes in synthetic media creation are forcing errors and omissions policy rewrites without established case law precedents to anchor coverage language.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Entertainment Insurance Market |
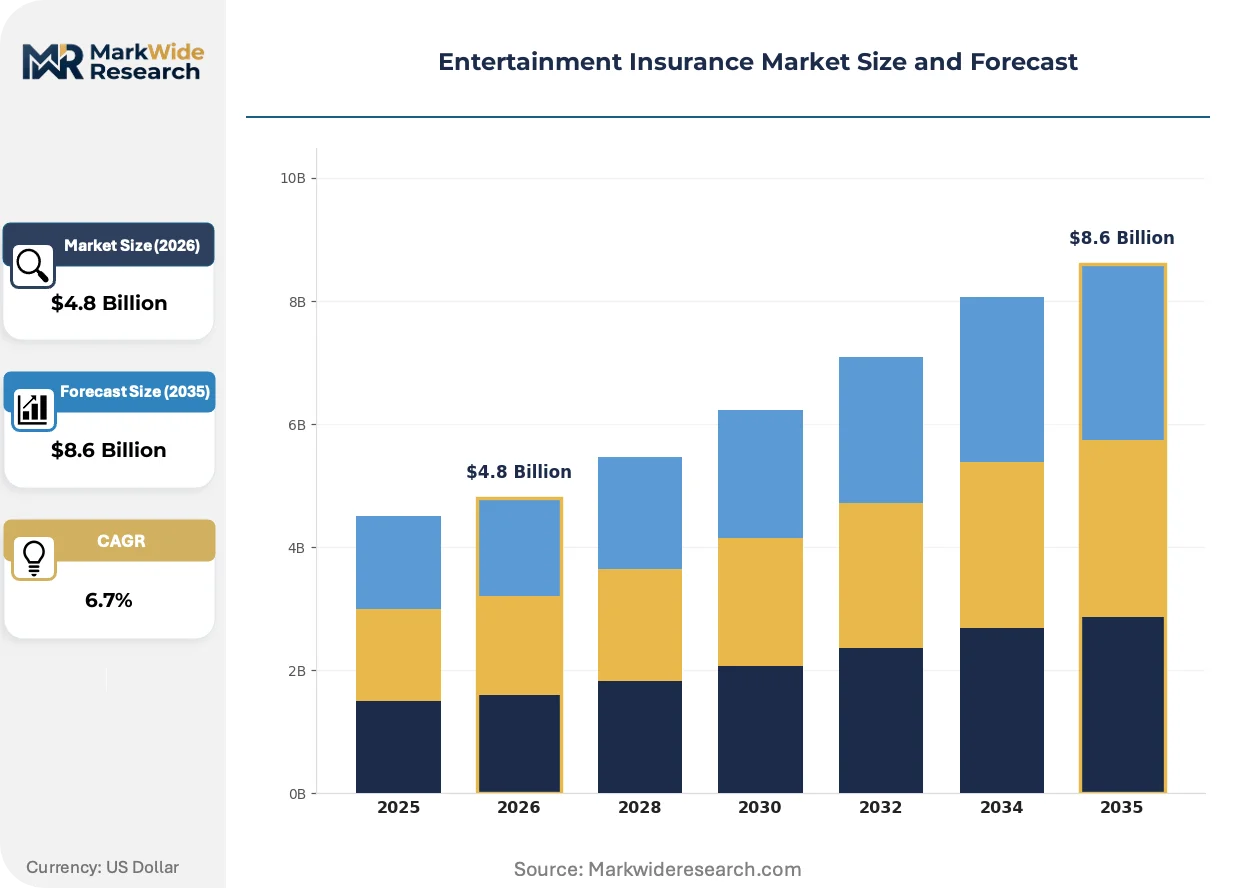
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Film Production, Event Cancellation, Equipment Insurance, Liability Coverage Client Type: Producers, Event Organizers, Distributors, Talent Agencies Coverage Area: Domestic, International, Regional, Local Service Model: Online, Broker-assisted, Direct, Custom |
| Companies Covered | Allianz, Chubb, AXA, Hiscox, Arthur J. Gallagher & Co., Marsh, Aon, Hub International, Beazley, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Entertainment Insurance Market Emerging Trajectories
Real-time production data streams are compressing the gap between risk occurrence and coverage adjustment, enabling dynamic policy structures that respond to shooting conditions rather than static declarations.
Telematics-equipped camera packages are integrating location tracking, shock detection, and environmental sensors into equipment coverage. Major rental houses in Los Angeles and London are adopting these connected asset systems, allowing carriers to shift from annual aggregate policies to usage-based premium calculations tied to actual deployment intensity and terrain severity.
The US FAA's Remote ID mandate for unmanned aerial vehicles is standardizing drone registration and flight logging requirements. Productions operating under Part 107 waivers must now maintain broadcast transponder compliance, which insurers are using to verify pilot certification currency and restrict coverage to auditable flight paths rather than blanket territorial permissions.
Buyers are consolidating placement decisions through entertainment-focused wholesale brokers who bundle cast, equipment, and general liability into packaged programs. This channel compression is most visible in the independent documentary sector, where producers previously sourced coverage through disparate specialty markets now negotiate single-source policies through aggregator platforms that standardize submission data formats across multiple Lloyd's syndicates.
Entertainment Insurance Market Segmentation
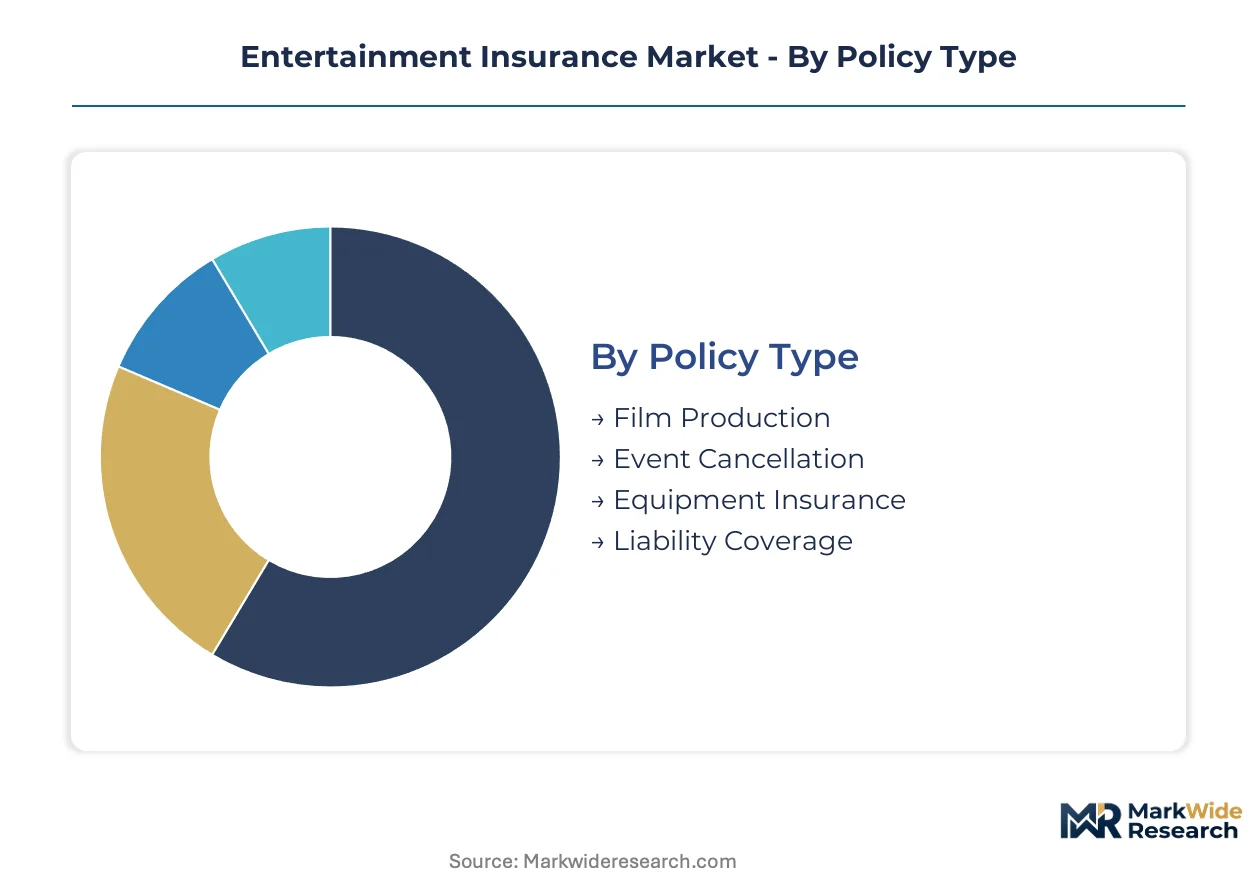
Entertainment insurance segmentation reflects divergent risk profiles across production types, client sophistication levels, and geographic exposure scales. Carriers calibrate pricing engines and capital reserves differently for each dimension, creating distinct competitive arenas within the broader market.
Policy Type:
Supply concentration in Lloyd's syndicate capacity shapes how each policy type reaches market, with admitted carriers ceding complex risks to surplus lines specialists.
- Film Production:Wrap-up policies bundle cast non-appearance, negative film, and extra expense coverage into unified structures. Los Angeles County studio backlots and streaming platform original content budgets drive premium concentration in high-budget theatrical and episodic production.
- Event Cancellation:Weather, terrorism, and pandemic triggers now incorporate parametric payout mechanisms for instant settlement. Festival organizers in live entertainment corridors are expanding coverage adoption fastest as event scale and financial exposure intensify.
- Equipment Insurance:Connected asset telematics enable usage-based premium calculations tied to deployment intensity.
- Liability Coverage:General and excess liability protects against third-party injury and property damage claims during production.
Film production absorbs the bulk of installed capacity; event cancellation is expanding most quickly.
Client Type:
Cost tier differentiation separates sophisticated institutional buyers from transactional purchasers, with broker relationships and policy customization depth varying sharply across the spectrum.
- Producers:Studio and independent production companies require wrap-up policies spanning multiple risk categories. International co-productions demand broker-assisted placement through Lloyd's syndicates for cast and completion coverage.
- Event Organizers:Music festivals and sporting events seek cancellation protection with parametric triggers. Large-scale event operators in major metropolitan corridors are consolidating placement through wholesale entertainment brokers.
- Distributors:Content licensing entities need errors and omissions coverage for intellectual property exposure.
- Talent Agencies:Representation firms secure contractual liability and personal accident coverage for client rosters.
Producers command the deepest broker relationships; event organizers are gaining share fastest as live entertainment rebounds.
Coverage Area:
Geography determines regulatory overlay complexity, with multi-jurisdictional shoots requiring navigation of FAA, EU AI Act, and local aviation authority frameworks simultaneously.
- Domestic:Single-country policies adhere to admitted carrier regulations and state insurance commissioner oversight. US productions benefit from standardized FAA Part 107 drone certification integration.
- International:Cross-border shoots face surplus lines eligibility requirements and multiple regulator compliance layers.
- Regional:Multi-country coverage within defined territories suits co-production treaties.
- Local:Single-municipality policies serve location-specific short-term productions.
Domestic coverage holds the largest policy count; international placement is climbing the fastest as streaming platforms globalize content supply chains.
Service Model:
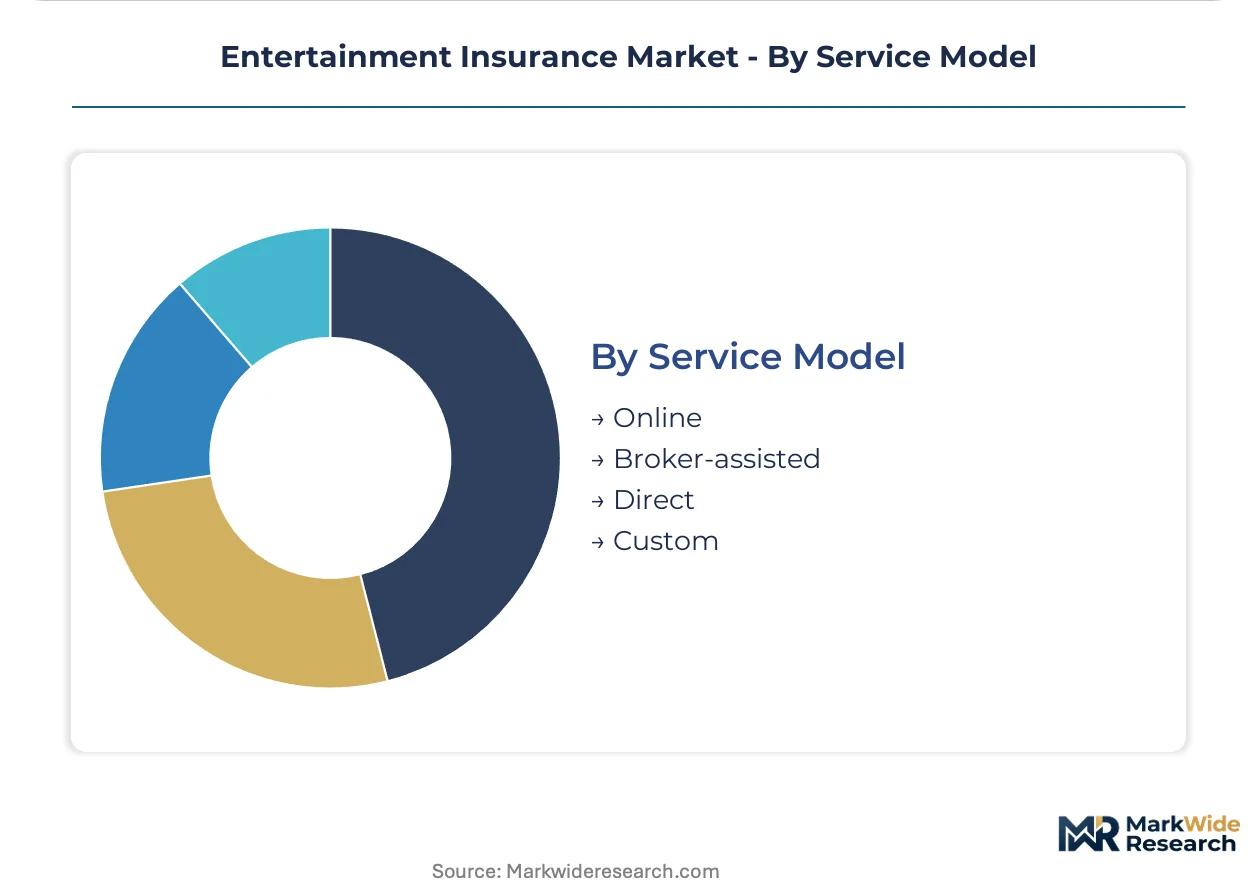
Customer type and transaction complexity dictate channel selection, with technology-enabled platforms capturing standardized risks while complex placements remain broker-dependent.
- Online:Digital platforms deliver instant quotes for equipment and short-term liability coverage. Standardized submission formats now aggregate independent documentary producers through aggregator interfaces.
- Broker-assisted:Wholesale entertainment brokers bundle cast, equipment, and general liability into packaged programs. Complex international co-productions require specialized intermediaries with Lloyd's market access.
- Direct:Carrier-producer relationships bypass intermediaries for large studio accounts.
- Custom:Bespoke policy structures address unique risk profiles in virtual production and synthetic media creation.
Broker-assisted distribution retains the premium volume base; online platforms are gaining share fastest in standardized equipment and short-tail liability segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand clusters in jurisdictions with dense production infrastructure and mature regulatory frameworks for risk transfer. Streaming platform original content budgets concentrate premium volume in established filming hubs, while emerging incentive zones reshape geographic placement patterns.
United States
Los Angeles County studio backlots and Georgia's production tax credits drive wrap-up policy volume. The FAA's Part 107 unmanned aerial vehicle certification standardizes drone cinematography coverage terms. New York City's episodic television corridor absorbs significant cast non-appearance capacity.
United Kingdom
Lloyd's of London syndicates anchor international co-production placement through surplus lines specialization. The Prudential Regulation Authority and Financial Conduct Authority govern carrier capital adequacy for entertainment liability reserves. Pinewood Studios and Shepperton facilities generate concentrated equipment and general liability exposure.
Germany
Bavaria Film and Studio Babelsberg sustain Central European production insurance demand. BaFin oversight shapes admitted carrier participation in high-budget international shoots. Munich-based broadcasters and streaming commissioning entities expand errors and omissions coverage for content licensing.
France
The Centre national du cinéma's production support schemes stimulate policy demand for qualifying domestic features. EU AI Act compliance mandates reshape errors and omissions language for generative AI-assisted productions. Paris-based post-production houses concentrate negative film and media liability exposure.
Saudi Arabia
NEOM and AlUla filming incentive zones lack mature local insurance infrastructure, forcing placement through London surplus lines. The Saudi Central Bank and national regulator develop admitted carrier frameworks for production risk transfer. Riyadh-based content commissioning creates emerging demand for tailored coverage structures.
Entertainment Insurance Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with admitted carriers ceding complex risks to Lloyd's syndicates and surplus lines intermediaries. The market exhibits tiered concentration: global multiline insurers anchor high-budget theatrical placement, while niche underwriters capture independent documentary and festival cancellation segments. Three archetypes dominate—syndicate specialists with Lloyd's market access, wholesale brokers bundling multi-line programs, and technology-enabled platforms standardizing equipment coverage. Competitive moves center on parametric product development and broker-aggregator platform partnerships.
Among global multiline carriers, Allianz and Chubb occupy positions as scale-driven capacity providers for studio-level production programs. Hiscox exemplifies the specialist archetype, anchoring competitive positioning in independent film and documentary segments through tailored underwriting expertise. These named entities represent distinct strategic postures rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Allianz |
| Chubb |
| AXA |
| Hiscox |
| Arthur J. Gallagher & Co. |
| Marsh |
| Aon |
| Hub International |
| Beazley |
| Others |
Supply Flow & Price Mechanics
Actuarial talent concentration in London and Los Angeles creates labor-cost differentials that widen pricing-tier spreads between Lloyd's syndicate specialists and admitted carriers serving routine production risks.
Pricing Analysis
High-volume standardized equipment coverage operates on thin margins while complex international co-production placement commands substantial broker-assisted premiums. Price differentiation hinges on Lloyd's market access depth and real-time risk monitoring capability. Cost compression in the independent documentary segment intensifies as aggregator platforms consolidate submission volumes. Streaming platform buyers exhibit lowest price sensitivity given budget scale, while festival organizers face acute premium pressure from parametric coverage alternatives.
Supply Chain Analysis
Freight logistics for telematics-equipped camera packages between Los Angeles rental houses and international location shoots add measurable cost layers to equipment coverage pricing. Capital reserves concentrate in the United Kingdom, the United States, and Bermuda. Reinsurance capacity draws from London market specialists and Bermuda-based catastrophe underwriters. Single-source vulnerability sits with Lloyd's syndicate capacity for cast non-appearance and weather interruption policies. Distribution runs through wholesale entertainment brokers bundling multi-line programs for complex placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The entertainment insurance market sits in a technology-transition phase as cloud-based risk analytics and parametric triggers displace manual underwriting and traditional loss adjustment workflows.
For Market Incumbents: Lock in proprietary data advantages by deepening integration with production management software platforms before synthetic media creation tools fragment intellectual property risk assessment. Expand catastrophe modeling capabilities for event cancellation coverage as climate volatility intensifies. Prioritize certification investment in EU AI Act compliance frameworks to capture European co-production placement. For New Entrants and Emerging Players: Saudi Arabian production incentive zones represent the most penetrable geography given immature local insurance infrastructure and surging NEOM and AlUla filming activity. Independent documentary producers offer accessible entry through standardized equipment and short-term liability products. Pursue direct online platform distribution to bypass entrenched wholesale broker relationships. For Investors and Strategic Acquirers: Re-rating potential sits with parametric product specialists given instant payout mechanism adoption across festival cancellation coverage. Long-term viability favors carriers with demonstrated Lloyd's market access and proprietary production risk data assets. Monitor FAA Remote ID mandate compliance rates as an inflection indicator for drone cinematography coverage standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Instant payout mechanisms bypass traditional loss adjustment delays for festival organizers. |
| Cloud-Based Risk Analytics Platform | Chubb's proprietary catastrophe modeling enables dynamic pricing for event cancellation policies. |
| Saudi Arabia Admitted Carrier Partnership | First-mover advantage in NEOM and AlUla filming hubs lacking mature local infrastructure. |
| Telematics-Equipped Asset Integration | Connected camera packages shift coverage from annual aggregate to usage-based premium calculations. |
| EU AI Act Compliance Certification | Expanded errors and omissions riders capture European generative AI-assisted production demand. |
Methodological Framework
SEC filings, Lloyd's market data, and FAA regulatory databases formed the secondary backbone, supplemented by primary interviews with entertainment underwriters, production risk managers, and wholesale broker specialists. Bottom-up and top-down triangulation validated premium volume estimates across policy type and client segments. Stakeholder conversations with streaming platform executives and festival organizers informed demand-side assumptions.
Bottom-up modeling anchored volume projections in individual production budget tiers and policy penetration rates, while top-down validation cross-checked against aggregate carrier capacity deployment. Segmentation dimensions included policy type, client sophistication tier, geographic exposure scale, and service model channel. CAGRs derived from trend extrapolation of streaming content budgets and live entertainment recovery trajectories. Forecast inputs incorporated FAA Part 107 waiver expansion rates and EU AI Act implementation timelines.
Revisions become necessary when generative IP contamination disputes establish case law precedents or when California wildfire moratoriums extend beyond current actuarial assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Europe Embedded Insurance Market
Insurance
Global Vehicle Insurance Market
Insurance
Denmark Property and Casualty Insurance Market
Insurance
Asia-Pacific Family Floater Health Insurance Market
Insurance
Global Sports Insurance Market
Insurance
Russia Property and Casualty Insurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
France Liability Insurance Market
Insurance
UAE Property and Casualty Insurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Aircraft Insurance Market
Insurance
Asia-Pacific Usage-Based Insurance Market
Insurance
Cybersecurity Insurance Market
Insurance
Canada Property and Casualty Insurance Market
Insurance
UK Dental Insurance Market