
 Asia-Pacific Motorcycle Loan Market | 2026-2036
Asia-Pacific Motorcycle Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Motorcycle Loan Market Insights
Asset-light leasing and pay-per-use project finance is fragmenting traditional ownership-based lending across the Asia-Pacific motorcycle loan landscape. HDFC Bank leverages its rural branch density to sustain dominance in India's semi-urban two-wheeler finance. TVS Credit Services anchors South Indian origination through captive tie-ups with regional manufacturers. Mitsubishi HC Capital Asia Pacific competes via fleet-oriented structures for commercial motorcycle operators across ASEAN markets.
A motorcycle loan constitutes a secured or unsecured credit instrument collateralized by a two-wheeled motor vehicle, typically featuring tenures of twelve to sixty months and interest accrual tied to borrower risk profiles or central bank policy rates. Its primary commercial purpose channels liquidity to individual commuters and fleet operators who lack upfront capital for vehicle acquisition. Secured loans command the deepest margin pools due to collateral recovery mechanisms, while flexible repayment structures attract gig economy riders with irregular income cycles. First-time buyers represent the fastest-expanding customer segment as digital credit scoring expands addressable populations beyond traditional bureau files.
India's RBI prudential norms on retail exposure classification and Indonesia's OJK consumer protection frameworks shape origination standards and disclosure requirements across the region. Thailand's BOT interest rate caps constrain pricing flexibility for unsecured motorcycle credit, compressing returns for non-bank financiers. Stakeholders must monitor how central bank digital currency pilots and open banking mandates in the Philippines and Vietnam recast customer acquisition economics and underwriting data availability.
Market Dynamics
Digital credit scoring is virtualizing traditional branch-based underwriting across the Asia-Pacific motorcycle loan landscape, compressing origination timelines from weeks to minutes while expanding addressable borrower pools beyond formal income documentation.
Growth Catalysts
- Indonesia's OJK consumer protection frameworks:Standardized disclosure requirements reduce information asymmetry between lenders and first-time borrowers, accelerating trust-based credit expansion in urban corridors.
- India's PLI scheme for automotive manufacturing:Tightened credit linkages between assemblers and financiers create captive origination channels with embedded vehicle financing at point of sale.
- Gig economy rider proliferation:Flexible repayment structures aligned with irregular income cycles unlock new borrower segments previously excluded from term-based products.
Market Restraints
- Thailand's BOT interest rate caps:Binding ceilings on unsecured motorcycle credit compress net interest margins for non-bank financiers, constraining capital deployment flexibility.
- Collateral recovery friction:Weak secondary market infrastructure for repossessed two-wheelers in rural Vietnam and the Philippines elevates loss-given-default estimates.
- Central bank digital currency pilots:Uncertain interoperability timelines between sovereign digital currencies and existing loan management systems create technical debt risks.
Strategic Opportunities
- Philippines open banking mandates:Regulatory-driven data portability enables alternative credit scoring using utility payment histories and mobile wallet transaction patterns.
- Asset-light leasing structures:Pay-per-use project finance for commercial fleet operators fragments traditional ownership-based lending in ASEAN urban logistics corridors.
- Vietnam's underpenetrated rural credit:Low formal financial institution density in Mekong Delta provinces creates first-mover advantages for digital-native lenders with agent networks.
Industry Challenges
- Legacy core banking integration:Real-time loan origination platforms face API incompatibility with decades-old loan servicing infrastructure at established regional banks.
- Cross-border data localization:Divergent national requirements for credit bureau information storage complicate regional portfolio management for pan-Asia lenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Motorcycle Loan Market |
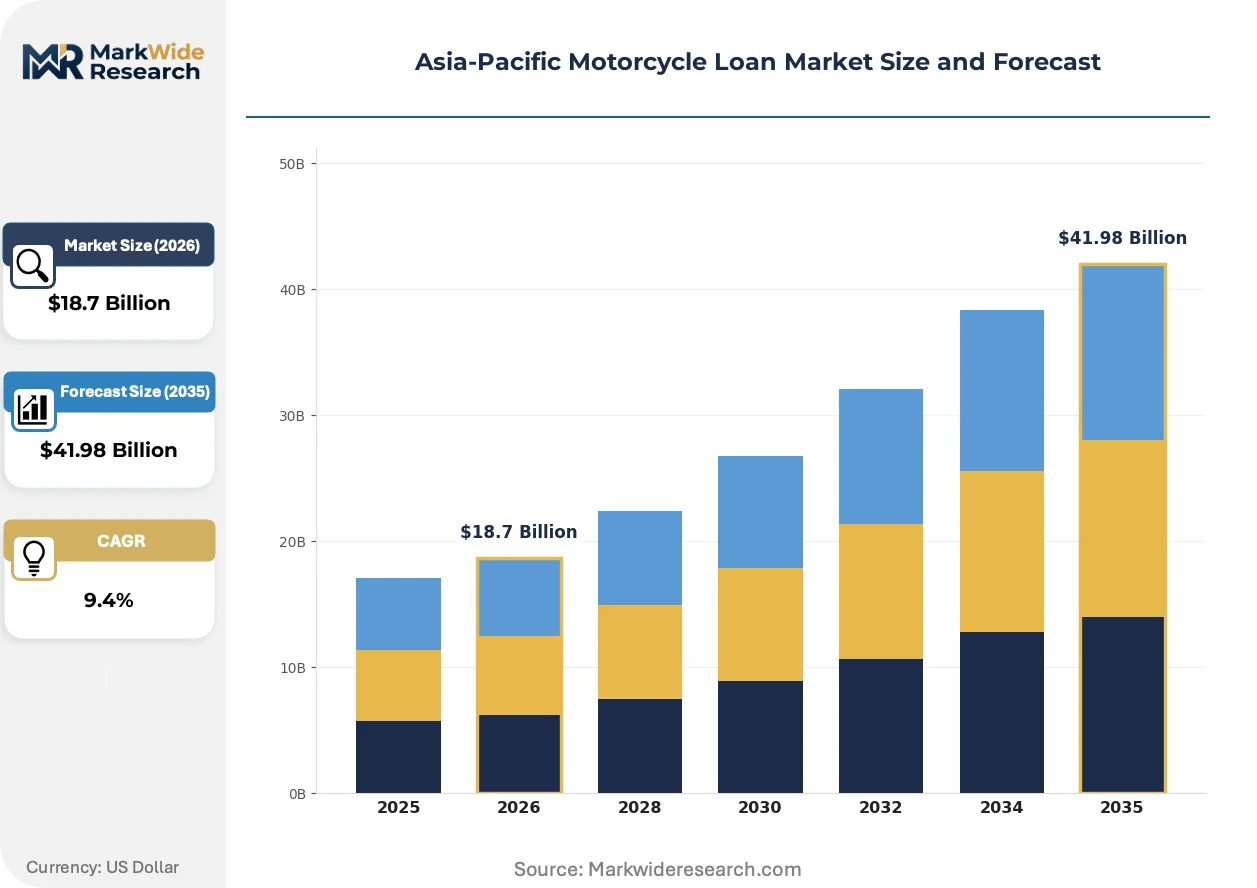
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Personal Loans, Commercial Loans, Secured Loans, Unsecured Loans Customer Segment: First-Time Buyers, Returning Customers, Fleet Operators, Brokers Repayment Structure: EMI, Balloon Payment, Flexible Repayment, One-Time Payment Interest Rate Type: Fixed Rate, Variable Rate, Hybrid Rate, Promotional Rate |
| Companies Covered | China International Capital Corporation, HDFC Bank, Ford Motor Credit Company, BNP Paribas, Bank of China, Toyota Financial Services, Citi Bank, TVS Credit Services, Mitsubishi HC Capital Asia Pacific, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Motorcycle Loan Market Trends and Innovations
Embedded finance architectures are dissolving boundaries between vehicle commerce and credit provision, enabling origination at the precise moment of purchase intent rather than through subsequent application processes.
Alternative data scoring engines are virtualizing traditional bureau-dependent underwriting across Southeast Asian markets. Fintech lenders deploy machine learning models trained on mobile behavioral data, telecom payment patterns, and e-commerce transaction histories. First-time buyers without formal credit files now access secured products previously reserved for established borrowers. This capability is compressing the market share of incumbent financiers reliant on legacy risk assessment infrastructure.
India's RBI prudential norms on retail exposure classification mandate stricter provisioning for subprime motorcycle portfolios. Financiers must hold additional capital reserves against loans to borrowers below specified income thresholds or lacking collateral documentation. Non-banking financial companies with concentrated subprime books face the steepest compliance costs, driving consolidation toward diversified lenders with stronger deposit bases.
Gig economy procurement patterns are fragmenting traditional term-loan structures across last-mile delivery and ride-hailing segments. Fleet operators now demand weekly or daily repayment schedules aligned with revenue realization cycles rather than monthly installments. Indonesian and Vietnamese lenders piloting income-linked products capture rider loyalty from platforms including Gojek and Grab, while conventional products lose relevance among this expanding employment category.
Asia-Pacific Motorcycle Loan Market Segmentation
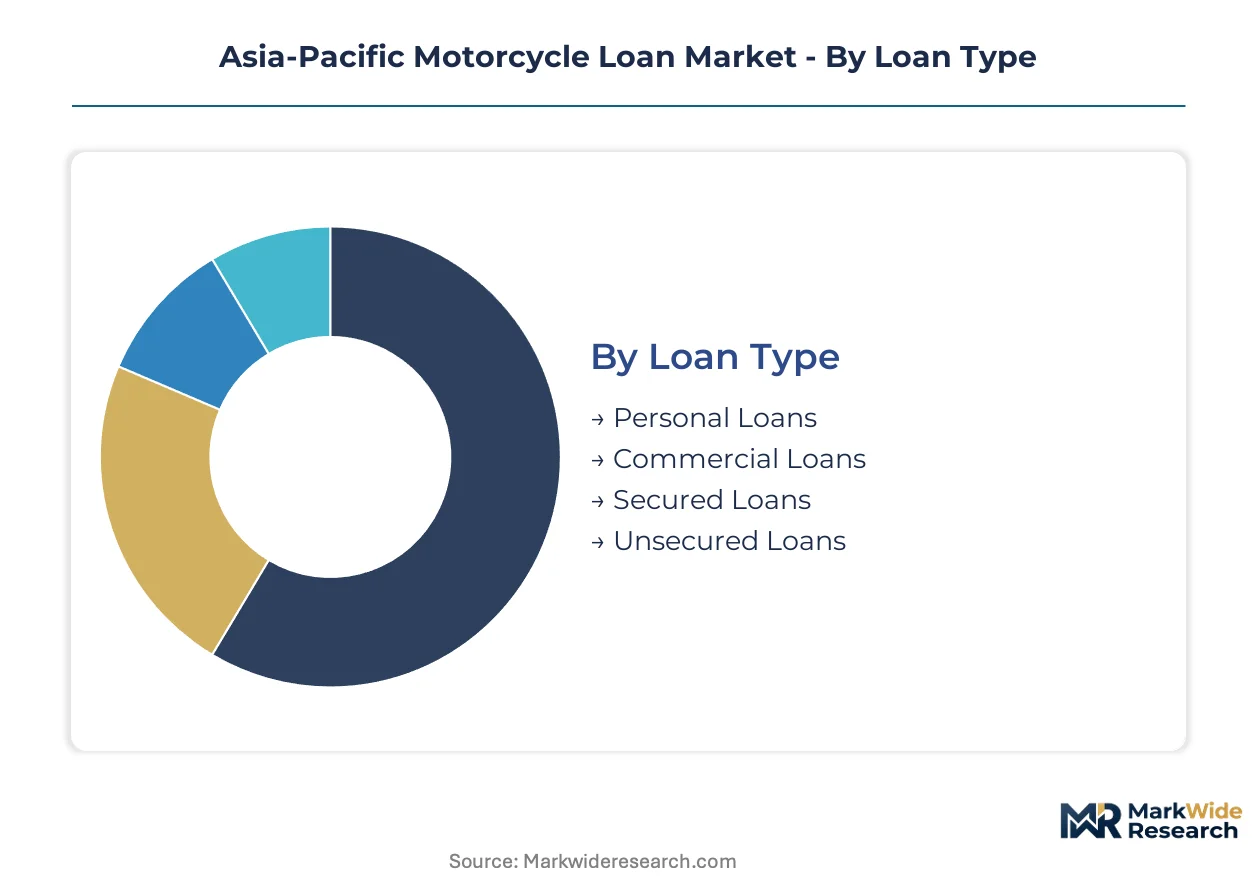
Segmentation reveals how motorcycle loan products align with distinct borrower cash flow patterns and risk profiles across Asia-Pacific markets. Lenders configure product architectures around employment type, collateral availability, and platform integration requirements.
Loan Type:
Maturity spreads from established secured products to emerging unsecured digital offerings.
- Secured Loans:Collateralized by the two-wheeler itself with lien registration against vehicle chassis numbers. Indonesian and Indian assemblers embed these at point-of-sale through captive finance arms, capturing commuter demand in Jakarta and Mumbai urban corridors where formal income documentation exists.
- Personal Loans:Unsecured credit extended for motorcycle acquisition without asset-specific collateral. Demand concentrates among salaried employees in Philippine and Vietnamese metro areas seeking faster disbursement than traditional secured products allow.
- Commercial Loans:Extended to registered businesses for fleet acquisition or operational expansion.
- Unsecured Loans:Rely solely on credit scoring without collateral attachment.
Secured loans handle the majority of throughput; unsecured loans are expanding most quickly on share.
Customer Segment:
Cost tier separates thin-file digital entrants from established relationship borrowers.
- First-Time Buyers:Borrowers without prior formal credit history accessing two-wheeler finance through alternative data scoring. Indonesian OJK disclosure frameworks and Indian digital KYC protocols accelerate origination for this segment previously excluded from bureau-dependent underwriting.
- Fleet Operators:Commercial entities managing multiple vehicles for logistics or ride-hailing platforms. Gojek and Grab procurement partnerships in Indonesia and Vietnam drive demand for income-linked repayment structures aligned with weekly revenue cycles.
- Returning Customers:Repeat borrowers with established repayment histories.
- Brokers:Intermediaries aggregating applications for multiple financiers.
Fleet operators handle the majority of commercial throughput; first-time buyers gain share fastest among retail segments.
Repayment Structure:
Application context determines whether rigid schedules or platform-linked flexibility prevails.
- EMI:Equal monthly installments with fixed principal-plus-interest calculations. Traditional bank and NBFC products across India and Thailand rely on this structure for salaried borrowers with predictable income streams.
- Flexible Repayment:Adjustable schedules accommodating irregular cash flows. Indonesian and Vietnamese gig economy lenders pilot daily or weekly settlement options for last-mile delivery riders whose earnings fluctuate with platform order volumes.
- Balloon Payment:Deferred principal settlement with lower periodic obligations.
- One-Time Payment:Single settlement at term conclusion without periodic amortization.
EMI structures handle the majority of throughput; flexible repayment climbs fastest on share.
Interest Rate Type:
Margin sensitivity drives preference between predictability and indexed exposure.
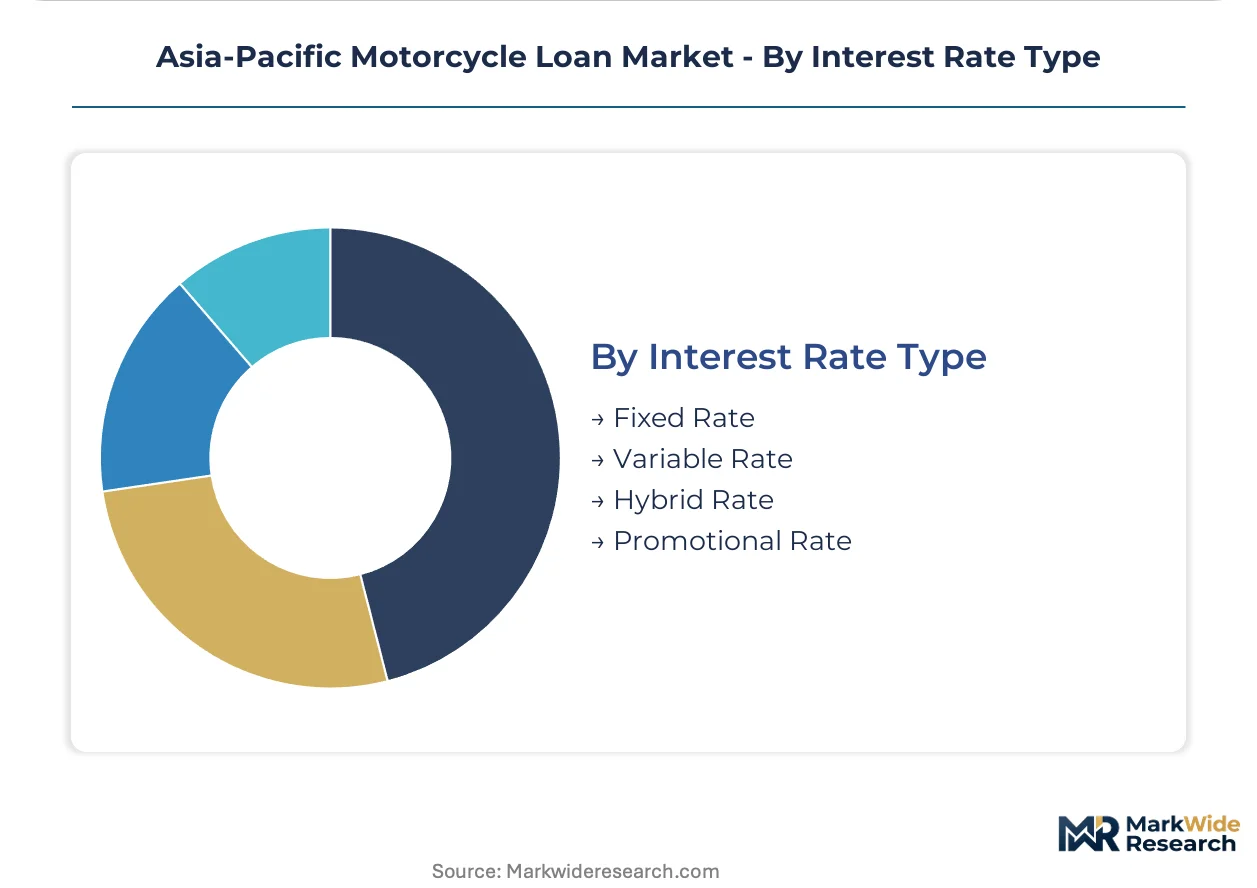
- Fixed Rate:Locked interest obligations throughout loan tenure. Indian borrowers favor these for budgeting certainty amid RBI policy rate volatility, with HDFC Bank and similar deposit-heavy institutions offering competitive pricing.
- Variable Rate:Obligations indexed to central bank policy rates or interbank benchmarks. Thai BOT rate movements directly transmit to motorcycle loan pricing, compressing margins for non-bank financiers when ceilings bind.
- Hybrid Rate:Fixed initial periods transitioning to variable terms.
- Promotional Rate:Subsidized introductory pricing for acquisition campaigns.
Fixed rate products handle the majority of throughput; variable rate structures gain share fastest in rate-sensitive markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for automotive manufacturing tightens credit linkages between assemblers and financiers across the region. Indonesia's OJK consumer protection frameworks standardize disclosure requirements for first-time borrowers. Thailand's BOT interest rate caps constrain pricing flexibility for unsecured motorcycle credit.
India
Semi-urban origination volumes surge as HDFC Bank leverages rural branch density for two-wheeler finance penetration. RBI prudential norms on retail exposure classification mandate stricter provisioning for subprime portfolios, elevating compliance costs for non-banking financial companies. TVS Credit Services anchors South Indian origination through captive manufacturer tie-ups in Tamil Nadu and Karnataka.
Indonesia
Urban corridor demand concentrates in Jakarta and Surabaya where two-wheelers dominate commuter mobility for first-time buyers. OJK consumer protection frameworks reduce information asymmetry between lenders and borrowers, accelerating trust-based credit expansion. Digital onboarding platforms reduce branch dependency across Java's dense population centers.
Thailand
Binding BOT interest rate ceilings on unsecured motorcycle credit compress net interest margins for non-bank financiers. Salaried employees in Bangkok metro area favor fixed-rate EMI structures for budgeting certainty amid policy rate volatility. Established banks with deposit-heavy funding models sustain pricing advantages over capital-constrained competitors.
Vietnam
Low formal financial institution density in Mekong Delta provinces creates first-mover opportunities for digital-native lenders with agent networks. Central bank digital currency pilots introduce uncertain interoperability timelines with existing loan management systems. Ho Chi Minh City anchors commercial fleet demand from last-mile delivery operators serving platform economies.
Philippines
Open banking mandates enable alternative credit scoring using utility payment histories and mobile wallet transaction patterns. Metro Manila concentrates personal loan demand among salaried employees seeking faster disbursement than secured products allow. Weak secondary market infrastructure for repossessed two-wheelers in rural provinces elevates loss-given-default estimates for portfolio managers.
Asia-Pacific Motorcycle Loan Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the Asia-Pacific motorcycle loan landscape. Deposit-heavy universal banks leverage low-cost funding to undercut non-bank financiers on rate-sensitive secured products. Three archetypes dominate: captive finance arms of automotive assemblers, diversified retail banks with rural distribution, and fleet-oriented commercial lenders. Strategic moves concentrate on embedded finance partnerships at point-of-sale and alternative data scoring platform deployment.
Among India-based diversified lenders, HDFC Bank exemplifies the branch-density archetype with semi-urban penetration strategies. TVS Credit Services occupies a position within the captive finance tier, representing manufacturer-integrated origination models. Mitsubishi HC Capital Asia Pacific anchors the fleet-commercial segment, exemplifying ASEAN-focused commercial motorcycle operator financing structures.
| Leading Market Players |
|---|
| China International Capital Corporation |
| HDFC Bank |
| Ford Motor Credit Company |
| BNP Paribas |
| Bank of China |
| Toyota Financial Services |
| Citi Bank |
| TVS Credit Services |
| Mitsubishi HC Capital Asia Pacific |
| Others |
Pricing and Supply Chain Analysis
Java Sea container freight corridors connecting Indonesian assembly plants to Philippine and Vietnamese distribution hubs transmit bunker fuel surcharges directly into landed motorcycle costs, amplifying price spreads between domestic captive finance products and cross-border unsecured lending. This logistics architecture concentrates pricing power with deposit-heavy universal banks that absorb freight volatility through balance sheet depth, while non-bank financiers pass through cost swings as rate premiums.
Pricing Analysis
Credit scoring sophistication creates the primary spread between secured and unsecured motorcycle loan products across Asia-Pacific markets. HDFC Bank and similar deposit-heavy institutions deploy fixed-rate EMI structures for salaried borrowers with formal income documentation, while fintech lenders command rate premiums for thin-file first-time buyers assessed through alternative data engines. Pricing pressure intensifies in Thailand where BOT interest rate ceilings bind against policy rate movements, compressing margins for capital-constrained non-bank financiers. Fleet operators demonstrate lowest price sensitivity due to platform-linked revenue certainty, while gig economy riders with irregular income cycles face steepest rate premiums.
Supply Chain Analysis
Regulatory divergence between India's RBI provisioning mandates and Indonesia's OJK disclosure frameworks fragments technology vendor compatibility across origination platforms. Motorcycle assemblers in Tamil Nadu and Karnataka anchor secured loan collateral pipelines through captive finance tie-ups, while digital-native lenders in Ho Chi Minh City and Jakarta source underwriting algorithms from specialized fintech providers. Single-source vulnerability concentrates in legacy core banking systems at established regional banks, where API incompatibility with real-time origination platforms creates technical debt accumulation. Distribution runs through embedded finance partnerships at manufacturer dealerships, direct digital channels for unsecured products, and agent networks for rural penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific motorcycle loan market tracks a cyclical recovery pattern as central bank rate cycles normalize and automotive PLI schemes accelerate vehicle replacement demand. Origination volumes correlate with two-wheeler sales momentum, creating synchronized expansion windows for aligned financiers.
For Market Incumbents: Build data moats through exclusive alternative scoring partnerships with telecom operators and mobile wallet providers. HDFC Bank's rural branch density and TVS Credit Services' manufacturer captive relationships demonstrate defensible positioning against digital-native entrants. Incumbents should deepen API integration with legacy core systems to reduce technical debt exposure, while consolidating subprime portfolios to meet RBI prudential provisioning requirements. Central bank digital currency interoperability investments will separate prepared lenders from stranded legacy platforms. For New Entrants and Emerging Players: Pursue Vietnam's Mekong Delta provinces where formal financial institution density remains lowest among major Southeast Asian markets. Digital-native lenders with agent network capabilities capture first-mover advantages in provinces like Can Tho and An Giang where traditional bureau files exclude most potential borrowers. Open banking mandates in the Philippines enable utility payment history scoring as a differentiated entry wedge against incumbent bureau-dependent underwriting. Embedded finance partnerships with regional motorcycle assemblers provide origination scale without proprietary branch infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate-owned non-banking financial companies facing RBI capital reserve pressures against concentrated subprime books. Long-term viability favors diversified lenders with deposit bases and technology platforms capable of serving both secured commuter finance and income-linked gig economy products. The signal to watch is central bank digital currency pilot interoperability announcements, which will recast customer acquisition economics and separate acquisition-ready platforms from technical debt burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Data Scoring Platform Deployment | Machine learning models trained on telecom and mobile wallet patterns expand addressable borrower pools beyond traditional bureau files in Indonesia and Vietnam. |
| Embedded Finance Partnership | Point-of-sale origination integration with TVS and similar assemblers captures purchase-intent moment rather than subsequent application processes. |
| Income-Linked Repayment Structure | Daily and weekly settlement options aligned with Gojek and Grab revenue cycles secure rider loyalty from platform economy expansion. |
| Legacy Core Banking Modernization | API compatibility investments reduce technical debt risks as central bank digital currency pilots demand real-time interoperability. |
| Rural Agent Network Expansion | Agent density in Mekong Delta and similar underpenetrated corridors creates origination scale without branch infrastructure costs. |
Research Methodology
Operator-level perspectives from motorcycle finance heads at universal banks, digital lending platform CTOs, captive finance directors at automotive assemblers, and regulatory affairs leads at non-banking financial companies anchored the qualitative base. These primary interviews combined with secondary validation from RBI circulars, OJK disclosure frameworks, BOT interest rate regulations, and ASEAN automotive production databases. Bottom-up origination volume estimates by country and product type triangulated against top-down two-wheeler sales forecasts and credit penetration benchmarks.
Scenario-bracketing around central bank policy rate trajectories and PLI scheme extension timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include loan type, customer segment, repayment structure, and interest rate type, with additional granularity around platform integration requirements for gig economy products. CAGRs derived from fitted growth curves applied to baseline origination volumes, adjusted for regulatory intervention probabilities and digital adoption S-curves. Forecast inputs incorporated two-wheeler replacement cycles, urban commuter mobility patterns, and fleet operator procurement behaviors.
Sensitivities concentrate around central bank digital currency interoperability timelines, open banking mandate implementation schedules, and PLI scheme continuity decisions. Forecasts reflect assumptions about regulatory technology adoption rates and alternative data scoring accuracy validation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Loan Management Software Market
Loans and Leasing
Europe Auto Loan Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
North America Syndicated Loans Market
Loans and Leasing
Auto Finance Market
Loans and Leasing
North America Motorcycle Loan Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
South Korea Car Loan Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
USA Home Loan Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
Used Car Financing Market
Loans and Leasing
Germany Auto Loan Market