
 UK Home Equity Lending Market | 2026-2036
UK Home Equity Lending Market Size, Share, and Industry Trends Forecast 2026-2036
UK Home Equity Lending Market Analytics
Prime-tier lifetime mortgage products with no-negative-equity guarantees is redrawing competitive boundaries in UK home equity lending. Aviva leverages its insurance heritage to sustain long-dated liability management alongside equity release origination. Lloyds Banking Group anchors retail distribution through its branch network and digital mortgage platform. Pure Retirement specializes in later-life lending, occupying a focused position against diversified banking conglomerates.
Home equity lending denotes secured credit facilities where borrowers extract capital from residential property value exceeding existing mortgage obligations, typically structured as lump-sum advances or drawdown arrangements with rolled-up or serviced interest options. The product serves primarily as a wealth deaccumulation vehicle for asset-rich, income-constrained households and as a debt restructuring tool for homeowners seeking to consolidate unsecured liabilities against lower-cost collateral. Lifetime mortgages dominate product type flows, reflecting structural preference for retention of property occupancy rights among retired homeowners. Second charge loans capture growing traction among income-reduced borrowers facing remortgaging barriers, with margin pools shifting toward advisory-led distribution given Financial Conduct Authority conduct requirements. Online platforms within service type represent the fastest-growing origination channel, though financial advisory intermediation retains dominant share in lifetime mortgage segments due to mandatory guidance frameworks.
The Prudential Regulation Authority sets capital adequacy buffers affecting lenders' risk-weighted asset treatment of equity release exposures, while the Financial Conduct Authority's Consumer Duty mandates outcome-focused product design and fair value assessment across distribution chains. The Equity Release Council standards supplement statutory frameworks with sector-specific no-negative-equity and portability protections. Stakeholders must monitor evolving interest rate trajectories and their compression of loan-to-value advance ratios against sustained property price appreciation assumptions.
Market Dynamics
The Bank of England's prudential standards for mortgage lending are compressing loan-to-value advance ratios while simultaneously mandating enhanced affordability stress-testing across equity release product lines.
Growth Catalysts
- Ageing Demographics:Retired homeowners in England and Wales are expanding the addressable customer base for wealth deaccumulation products as property ownership concentrates among older cohorts.
- FCA Consumer Duty:The Financial Conduct Authority's outcome-focused product design mandates are standardizing fair value assessment across distribution chains, reducing mis-selling risk and building borrower confidence.
- Digital Mortgage Platforms:Online origination channels are capturing advisory-led distribution volume through automated affordability engines and real-time property valuation integration.
Market Restraints
- Interest Rate Volatility:Sustained upward pressure on gilt yields is eroding maximum advance rates for lifetime mortgages, constraining accessible equity sums per transaction.
- Supply Concentration:Origination capacity clusters among a narrow band of authorized lenders with specialized later-life lending permissions, creating queue risk during demand surges.
- Substitution Threat:Downsizing to smaller residential properties competes directly with equity release as a wealth extraction mechanism, particularly in London where transaction liquidity remains elevated.
Strategic Opportunities
- Drawdown Product Innovation:Flexible facility structures allowing phased capital extraction are penetrating underpenetrated segments among income-constrained households in the South East.
- Equity Release Council Standards:Voluntary no-negative-equity and portability protections are creating differentiation pathways for lenders seeking to build trust-based brand positioning.
- Second Charge Expansion:Income-reduced borrowers facing remortgaging barriers in Northern England represent a white space for secured lending products with serviced interest options.
Industry Challenges
- Advisory Capacity Constraints:Mandatory guidance frameworks for lifetime mortgages require specialized later-life lending qualifications that the intermediary sector struggles to scale.
- Legacy System Integration:Incumbent banks face friction connecting equity release origination workflows to core mortgage servicing platforms, delaying product iteration cycles.
- Valuation Model Recalibration:Sustained property price appreciation assumptions embedded in risk models require continuous stress-testing against regional correction scenarios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Home Equity Lending Market |
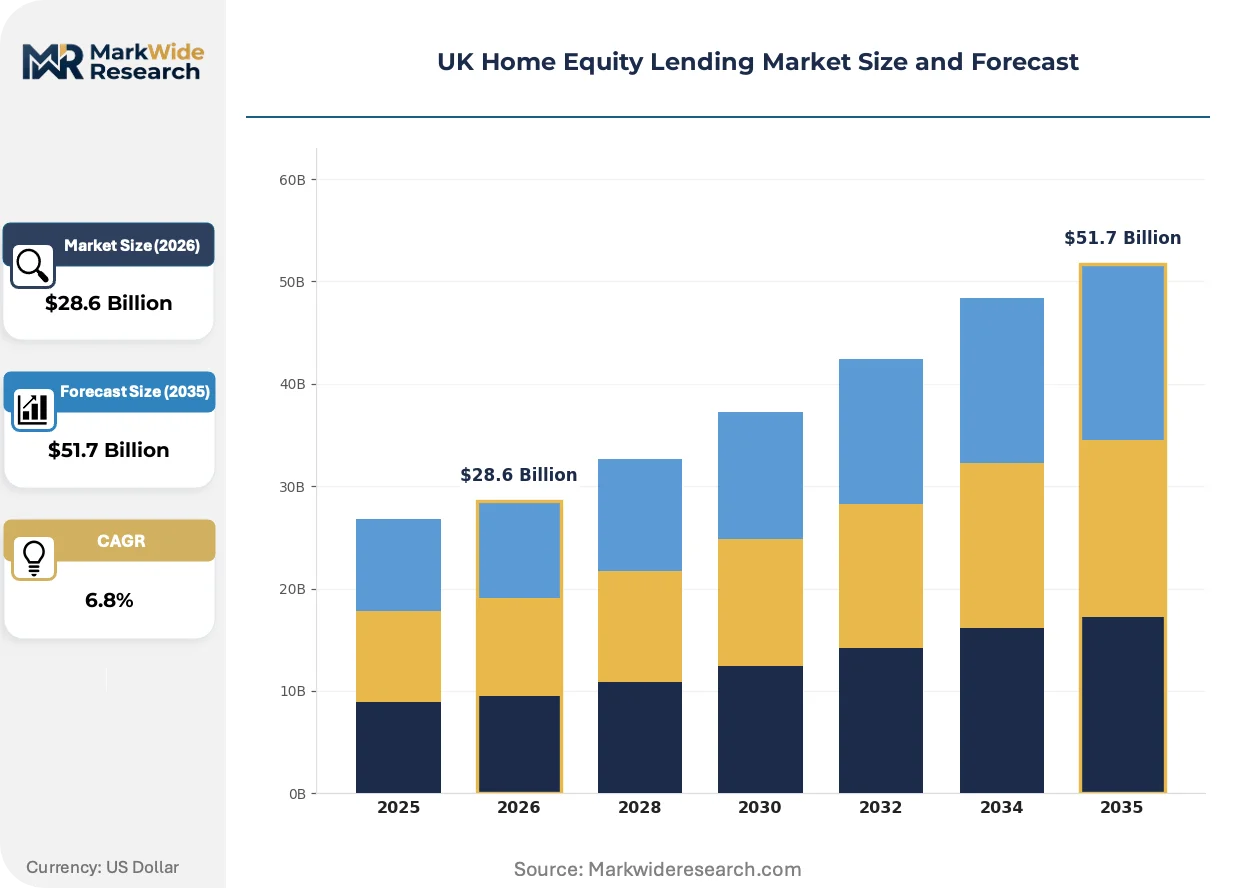
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Second Charge Loans, Lifetime Mortgages, Home Reversion Plans, Equity Release Customer Type: Retired Homeowners, First-Time Buyers, Income-Reduced Borrowers, Buy-to-Let Investors Service Type: Direct Lending, Financial Advisory, Online Platforms, Peer-to-Peer Lending Application: Home Renovation, Debt Consolidation, Retirement Funding, Education Expenses |
| Companies Covered | Aviva, Pure Retirement, Nationwide Building Society, More 2 Life, Selina Finance, Barclays Bank, Legal & General, Hodge Lifetime, Lloyds Banking Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Home Equity Lending Market Evolving Landscape
Digital distribution infrastructure and regulatory outcome mandates are converging to reshape product design, channel economics, and borrower interaction models across UK home equity lending.
Automated property valuation models integrated into online mortgage platforms are displacing traditional surveyor-led desktop assessments for initial eligibility screening. Regional building societies and specialist lenders are adopting these tools to compress origination timelines from weeks to days. This displacement is compressing cost-to-serve metrics while shifting human advisory resources toward complex case structuring.
The Financial Conduct Authority's Consumer Duty framework is mandating explicit fair value demonstration across equity release distribution chains. Lenders must now document outcome metrics including total cost of borrowing and flexibility features relative to alternatives. Lifetime mortgage providers with integrated insurance heritage are responding fastest, embedding guarantees and portability clauses that satisfy enhanced conduct standards.
Advisory intermediation for later-life lending is fragmenting as hybrid service models emerge combining digital self-serve with on-demand human consultation. Borrowers in London and the South East are gravitating toward platforms offering real-time drawdown simulation tools before formal advice engagement. This behavioral shift is most visible among mass-affluent retirees seeking transparency on compound interest accumulation before committing to rolled-up interest structures.
UK Home Equity Lending Market Segmentation
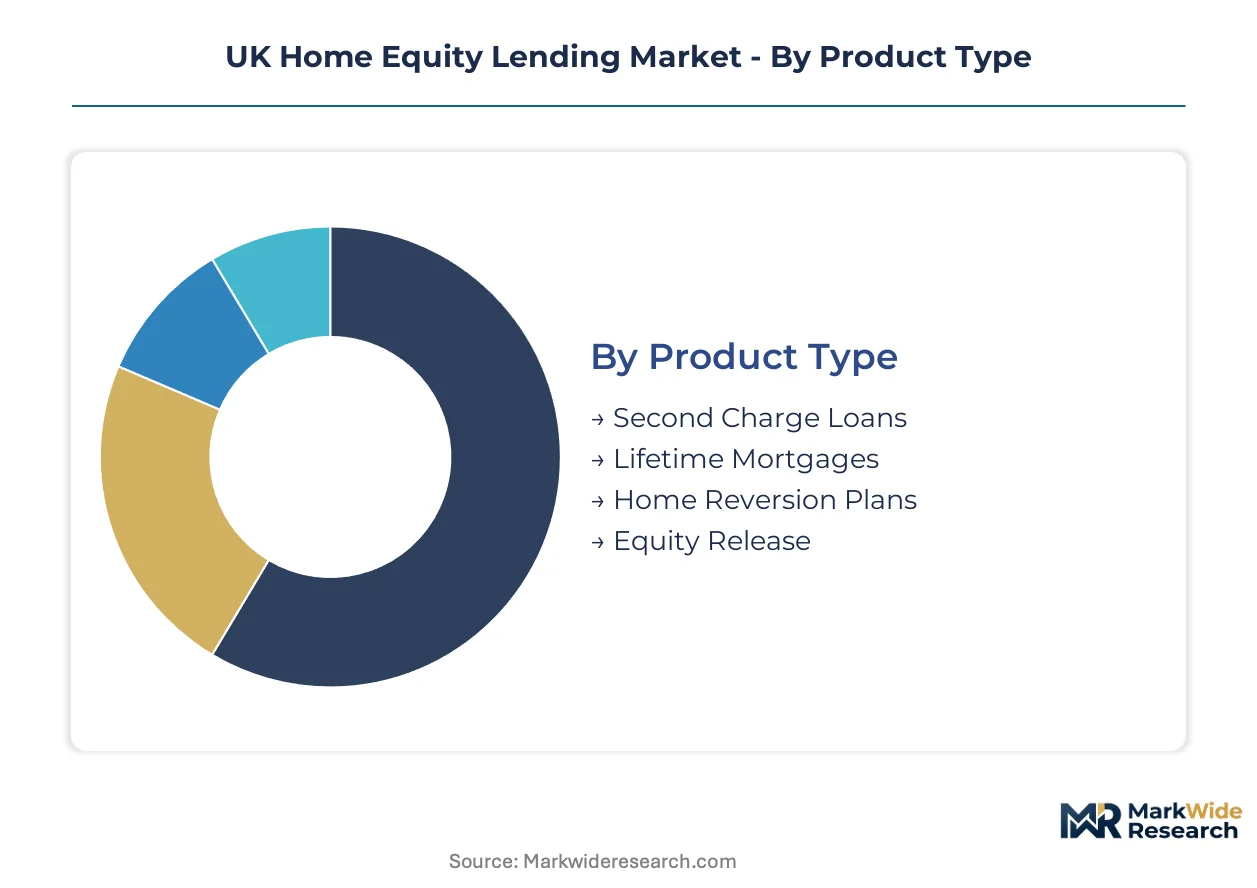
Product architecture and borrower profiles diverge sharply across UK home equity lending, with regulatory frameworks and demographic concentration creating distinct competitive arenas. Channel economics and end-use motivation further stratify origination flows between mass-market and advisory-dependent segments.
Product Type:
Domestic property wealth extraction dominates all product flows, with export-oriented structuring limited to cross-border servicing for UK expatriate borrowers. Cost tiering separates rolled-up interest vehicles from serviced alternatives.
- Lifetime Mortgages:Secured advances with compound interest rolling up against future property sale proceeds, typically featuring no-negative-equity guarantees. Retired homeowners in London and the South East concentrate demand here, drawn by occupancy retention rights and flexible drawdown structures amid elevated property valuations.
- Second Charge Loans:Subordinate secured credit ranking behind existing first-charge mortgages, preserving primary lender priority. Income-reduced borrowers across Northern England gravitate toward this product when remortgaging barriers emerge, prioritizing serviced interest options over rolled-up alternatives.
- Home Reversion Plans:Partial or full property ownership transfer to providers in exchange for lump-sum or income payments, with tenancy rights retained.
- Equity Release:Umbrella category encompassing regulated later-life lending products governed by Equity Release Council standards and FCA Consumer Duty mandates.
Lifetime mortgages command the established base. The steepest expansion runs through second charge loans.
Customer Type:
Volume concentration tracks ageing demographics and housing tenure patterns, with application motivation varying by life stage and liquidity constraints.
- Retired Homeowners:Asset-rich, income-constrained households deaccumulating property wealth to fund consumption or care needs. England and Wales dominate this segment as property ownership concentrates among older cohorts, with regulatory guidance frameworks mandating specialized advisory engagement.
- Income-Reduced Borrowers:Households experiencing earnings compression seeking debt restructuring against residential collateral. These customers cluster in former industrial regions where employment transitions strain unsecured debt servicing capacity.
- First-Time Buyers:Emerging entrants to property ownership occasionally leveraging family equity transfers for deposit funding.
- Buy-to-Let Investors:Portfolio landlords extracting capital from investment properties for further acquisition or leverage optimization.
Retired homeowners anchor origination volumes. Income-reduced borrowers are climbing the fastest as macroeconomic pressure extends across working-age cohorts.
Service Type:
Distribution economics stratify between high-touch advisory models and automated platform origination, with regulatory intensity dictating channel selection by product complexity.
- Financial Advisory:Intermediary-led placement through qualified later-life lending specialists, mandatory for lifetime mortgage origination. Advisory capacity constraints create queue risk during demand surges, particularly where specialized qualifications limit intermediary scaling.
- Online Platforms:Digital origination channels integrating automated valuation models and real-time affordability engines. Mass-affluent retirees in the South East gravitate toward hybrid models combining self-serve simulation with on-demand consultation.
- Direct Lending:Bank branch and proprietary digital channel origination by deposit-taking institutions with integrated mortgage servicing platforms.
- Peer-to-Peer Lending:Alternative finance structures connecting retail investors with secured borrowers outside traditional banking intermediation.
Financial advisory retains dominant share in regulated later-life products. Online platforms are gaining share fastest as digital infrastructure compresses cost-to-serve metrics.
Application:
End-use motivation shapes product selection between wealth deaccumulation and liability management objectives, with geographic concentration reflecting regional property value disparities.
- Debt Consolidation:Restructuring unsecured liabilities into secured facilities at lower cost of borrowing. This application concentrates among income-reduced borrowers in Northern England and the Midlands where unsecured debt burdens intersect with property equity availability.
- Retirement Funding:Supplementing pension income or funding long-term care through property wealth extraction. London and South East retirees dominate flows here, unlocking larger absolute sums against elevated property valuations.
- Home Renovation:Capital improvements to residential properties, occasionally combining equity release with energy efficiency upgrades.
- Education Expenses:Intergenerational wealth transfers funding tuition or property deposits for family members.
Debt consolidation anchors transaction volumes in absolute terms. Retirement funding is expanding most quickly as demographic ageing accelerates across England and Wales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK home equity lending market operates as a closed domestic system with minimal cross-border flow, concentrating origination capacity within England and Wales where ageing property-owning cohorts drive demand. Scotland and Northern Ireland represent smaller addressable markets with distinct regulatory frameworks and valuation methodologies.
London and South East
Elevated residential property values unlock the largest absolute equity sums per transaction nationwide. The Financial Conduct Authority's Consumer Duty mandates shape product design across advisory networks concentrated in Greater London. Wealth management clusters in the City and Canary Wharf anchor specialist later-life lending advisory capacity.
Midlands
Industrial heritage cities including Birmingham and Leicester host income-reduced borrower segments seeking debt consolidation against established housing equity. The Bank of England's prudential standards for mortgage lending apply uniform affordability stress-testing across the region. Coventry and Nottingham building societies maintain active origination presence in second charge lending.
North England
Former manufacturing centers in Manchester, Leeds and Sheffield concentrate demand for serviced-interest second charge products among borrowers facing remortgaging barriers. The Equity Release Council's voluntary standards supplement statutory consumer protections. Newcastle and Liverpool retain specialist advisory capacity despite lower average property valuations.
Scotland
Distinct property law frameworks under the Scottish legal system require specialized product documentation and conveyancing processes. The Scottish Government's devolved housing policy influences equity release uptake patterns. Edinburgh and Glasgow concentrate advisory intermediation serving asset-rich retired homeowners.
Wales
Rural property markets and coastal retirement destinations create dispersed demand patterns with lower average transaction values than English counterparts. The Financial Conduct Authority maintains consistent regulatory oversight across the England-Wales border. Cardiff anchors the principal advisory capacity serving South Wales equity release demand.
UK Home Equity Lending Market Competitive Landscape
Listed banking groups compete with private specialist lenders across distribution reach and product specialization. The sector structures around three tiers: diversified deposit-taking institutions with integrated mortgage platforms, insurance-origin lenders managing long-dated liabilities, and focused later-life specialists without balance sheet diversification. Strategic moves concentrate on digital platform integration and advisory network expansion.
Among diversified banking conglomerates, Lloyds Banking Group and Barclays Bank occupy positions defined by retail branch density and proprietary digital origination channels. Aviva exemplifies the insurance-origin archetype, leveraging liability management expertise alongside equity release origination. Pure Retirement anchors the specialist tier with focused later-life lending operations against diversified competitors.
| Leading Market Players |
|---|
| Aviva |
| Pure Retirement |
| Nationwide Building Society |
| More 2 Life |
| Selina Finance |
| Barclays Bank |
| Legal & General |
| Hodge Lifetime |
| Lloyds Banking Group |
| Others |
Value Network & Pricing Analysis
Capacity utilization across specialized later-life lending platforms shapes origination economics and price floors across UK home equity lending. Scale advantages concentrate among insurance-origin lenders managing long-dated liabilities alongside equity release origination, compressing unit costs for no-negative-equity guarantee products while smaller authorized lenders face higher regulatory compliance burdens per transaction.
Pricing Analysis
Retired homeowners anchor pricing structures across lifetime mortgage products, with rolled-up interest vehicles commanding premium positioning against serviced-interest alternatives. Price differentiation rests on guarantee tiering—no-negative-equity protections versus portability clauses—and advisory channel density, with London and South East borrowers absorbing higher absolute costs against elevated property valuations. Pricing pressure stems from gilt yield volatility eroding maximum advance rates, constraining accessible equity sums per transaction. Income-reduced borrowers in Northern England exhibit highest price sensitivity, gravitating toward second charge products with lower arrangement fees.
Supply Chain Analysis
Just-in-time origination dominates advisory-led distribution, though digital platforms are building strategic stockpiles of automated valuation model capacity to compress eligibility timelines. Geographic supply concentration clusters in England—London, Birmingham, and Manchester anchor specialist advisory networks—while Wales and Scotland rely on thinner intermediary density. Raw material dependencies center on property valuation data feeds, credit bureau integrations, and compliance technology stacks. Single-source vulnerability runs through centralized automated valuation model providers, with distribution running through financial advisory intermediation for regulated products and direct-to-consumer platforms for second charge alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK home equity lending is entering a cyclical recovery phase as ageing demographics across England and Wales expand the addressable customer base for wealth deaccumulation products.
For Market Incumbents: Shield origination capacity against advisory queue risk by accelerating digital platform integration that preserves mandatory guidance frameworks. Build defensive moats through deeper backward integration into property valuation infrastructure, reducing reliance on third-party automated valuation model providers. Consolidate advisory network relationships in London and the South East where elevated property values unlock largest absolute equity sums. For New Entrants and Emerging Players: Hybrid digital-advisory service gaps in Northern England present white-space entry points where incumbent banks under-serve income-reduced borrowers facing remortgaging barriers. Target second charge loan origination in former manufacturing centers like Manchester and Leeds, where serviced-interest products address debt consolidation demand. Pursue go-to-market angles through regional building society partnerships rather than proprietary branch buildout. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialist later-life lenders with focused operations against diversified banking conglomerates facing legacy system friction. Long-term viability over a 5-10 year window rests on regulatory technology investment and advisory capacity scaling. Target acquisition archetypes include digital-native platforms with automated affordability engines. Watch interest rate trajectory stabilization as inflection indicator for loan-to-value advance ratio recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | Automated valuation models compress origination timelines from weeks to days for mass-affluent retirees. |
| Advisory Network Expansion | Specialized later-life lending qualifications address mandatory guidance capacity constraints across England and Wales. |
| No-Negative-Equity Product Enhancement | Equity Release Council standard compliance builds trust-based positioning against non-adherent competitors. |
| Second Charge Market Entry | Serviced-interest products capture income-reduced borrowers in Northern England facing remortgaging barriers. |
| Regulatory Technology Investment | FCA Consumer Duty outcome documentation satisfies fair value assessment mandates across distribution chains. |
Research Methodology
A spread of perspectives from equity release product managers, financial advisory specialists, building society lending directors, and regulatory compliance officers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against Bank of England prudential guidance, Financial Conduct Authority Consumer Duty documentation, Equity Release Council standards, and property transaction data from HM Land Registry. Bottom-up origination flow analysis triangulated against top-down market sizing from mortgage servicing platform disclosures.
Segmentation dimensions modeled include product type architecture, customer life-stage profiles, distribution channel economics, and geographic property value clusters across the projection horizon. CAGRs were derived from trend extrapolation of ageing demographic trajectories, interest rate scenario stress-testing, and advisory capacity scaling assumptions. Industry-specific forecast inputs incorporated loan-to-value advance ratio sensitivity to gilt yield movements and regional property price appreciation differentials between London, South East, and Northern England markets.
Underlying assumptions cover sustained property ownership concentration among older cohorts, with deviation risk concentrated in interest rate volatility and regional housing market correction scenarios. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
China Mortgage/Loan Brokers Market
Loans and Leasing
India Auto Loan Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
Alternative Lending Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Used Car Financing Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
France Mortgage/Loan Brokers Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Latin America Motorcycle Loan Market
Loans and Leasing
India Car Loan Market
Loans and Leasing
Europe Used Car Financing Market
Loans and Leasing
Global Healthcare Equipment Leasing Market