
 Qatar Mortgage/Loan Brokers Market | 2026-2036
Qatar Mortgage/Loan Brokers Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Mortgage/Loan Brokers Market Insights
Buyer concentration among Qatar's expatriate professional class is hardening as population inflows to Doha and Lusail outpace citizen household formation. Qatar National Bank leverages its branch network to originate directly while sustaining broker partnerships for non-salaried clients. Commercial Bank of Qatar anchors its broker channel in the commercial loans segment, competing with Masraf Al Rayan's Shariah-compliant refinancing products. Doha Bank differentiates through digital pre-approval tools that reduce broker processing cycles.
Mortgage/loan brokers function as intermediaries that match borrowers with lenders, assessing credit profiles, structuring repayment terms, and managing documentation flows through Qatar Central Bank reporting systems. Their commercial purpose centers on reducing search costs in a market where Islamic and conventional products carry divergent profit-rate calculations and fee structures. Residential loans command the largest share of broker activity, though refinancing is accelerating as earlier fixed-rate mortgages reset against rising base rates. First-time buyers generate the highest per-case broker commissions, while balloon payment structures concentrate among investor clients purchasing rental units in Msheireb Downtown.
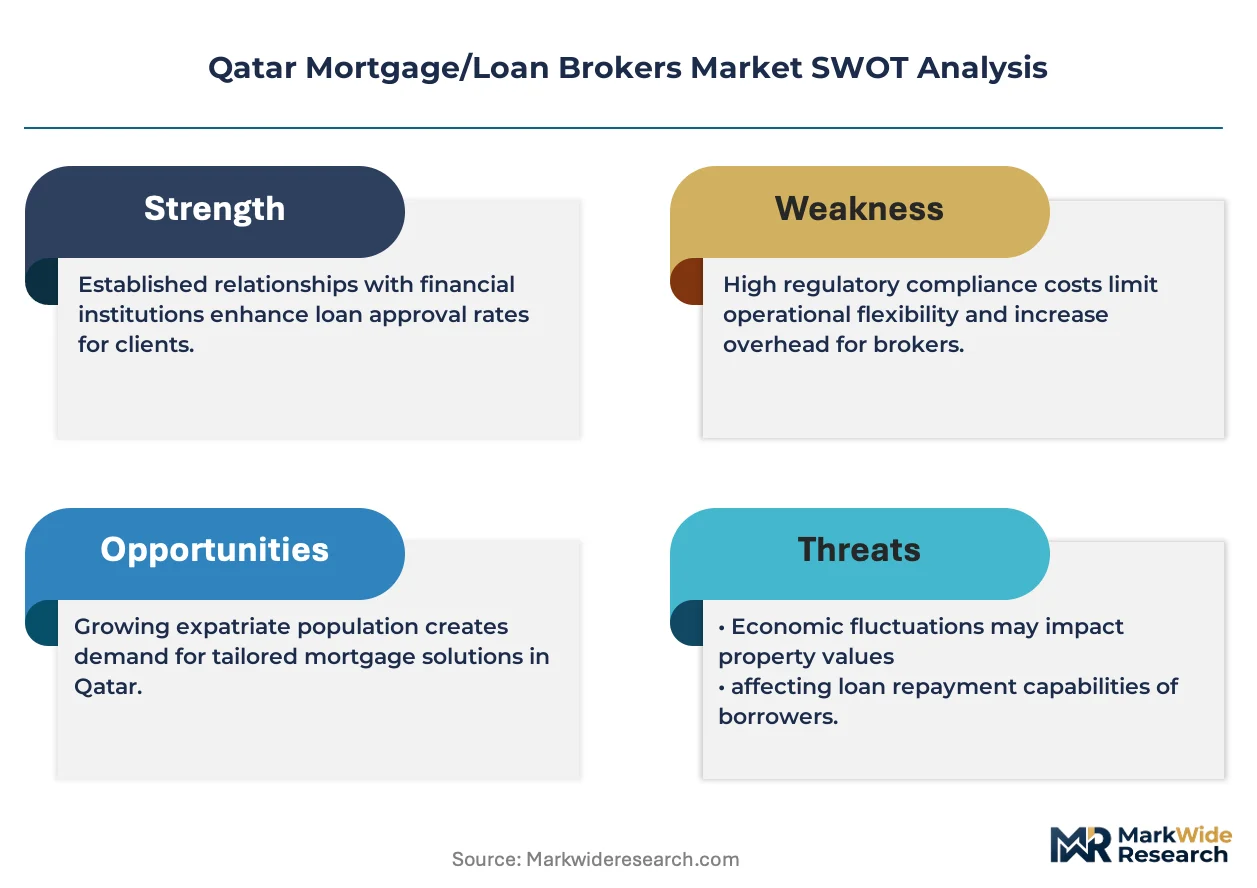
The Qatar Central Bank governs maximum loan-to-value ratios and debt-burden thresholds, directly constraining broker-eligible deal flow. Shariah compliance standards administered by the Qatar Financial Centre Regulatory Authority and AAOIFI guidelines shape product design for Islamic banks including Qatar Islamic Bank and Masraf Al Rayan. Stakeholders must monitor whether regulatory pressure to centralize credit scoring through the Qatar Credit Bureau displaces the broker's traditional role in risk assessment and lender matching.
Market Dynamics
Qatar Central Bank's loan-to-value caps are compressing origination margins while simultaneously redirecting borrower flow toward broker-assisted refinancing channels as rate resets accelerate.
Growth Catalysts
- Expatriate professional inflows:Population growth in Doha and Lusail is expanding the first-time buyer segment, with residential property demand in West Bay and The Pearl-Qatar driving broker commission pools.
- Digital mortgage platform integration:Broker adoption of Qatar Central Bank reporting system APIs is reducing documentation processing cycles and accelerating pre-approval throughput.
- Shariah-compliant refinancing products:Masraf Al Rayan's profit-rate structures are capturing investor clients seeking balloon payment arrangements for rental units in Msheireb Downtown.
Market Restraints
- Debt-burden threshold constraints:Qatar Central Bank maximum DTI ratios are structurally capping broker-eligible deal flow for mid-income expatriate households.
- Islamic-conventional product divergence:Divergent profit-rate calculations and fee structures between Shariah-compliant and conventional lenders fragment broker matching efficiency.
- Direct bank channel competition:Qatar National Bank's branch network origination capacity captures salaried client segments that previously filtered through broker channels.
Strategic Opportunities
- Off-plan property financing:West Bay and Lusail development pipelines are creating concentrated demand for construction-phase mortgage structuring expertise.
- Credit bureau integration services:Qatar Credit Bureau centralization creates white space for brokers offering enhanced risk assessment layering above automated scoring.
- Non-salaried client specialization:Self-employed expatriate segments underserved by direct bank channels represent commission rate premiums for specialized broker intermediation.
Industry Challenges
- Regulatory compliance velocity:Qatar Financial Centre Regulatory Authority AAOIFI guideline updates require continuous product knowledge refresh across broker networks.
- Technology platform fragmentation:Doha Bank's proprietary digital pre-approval tools create integration friction for multi-lender broker operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Mortgage/Loan Brokers Market |
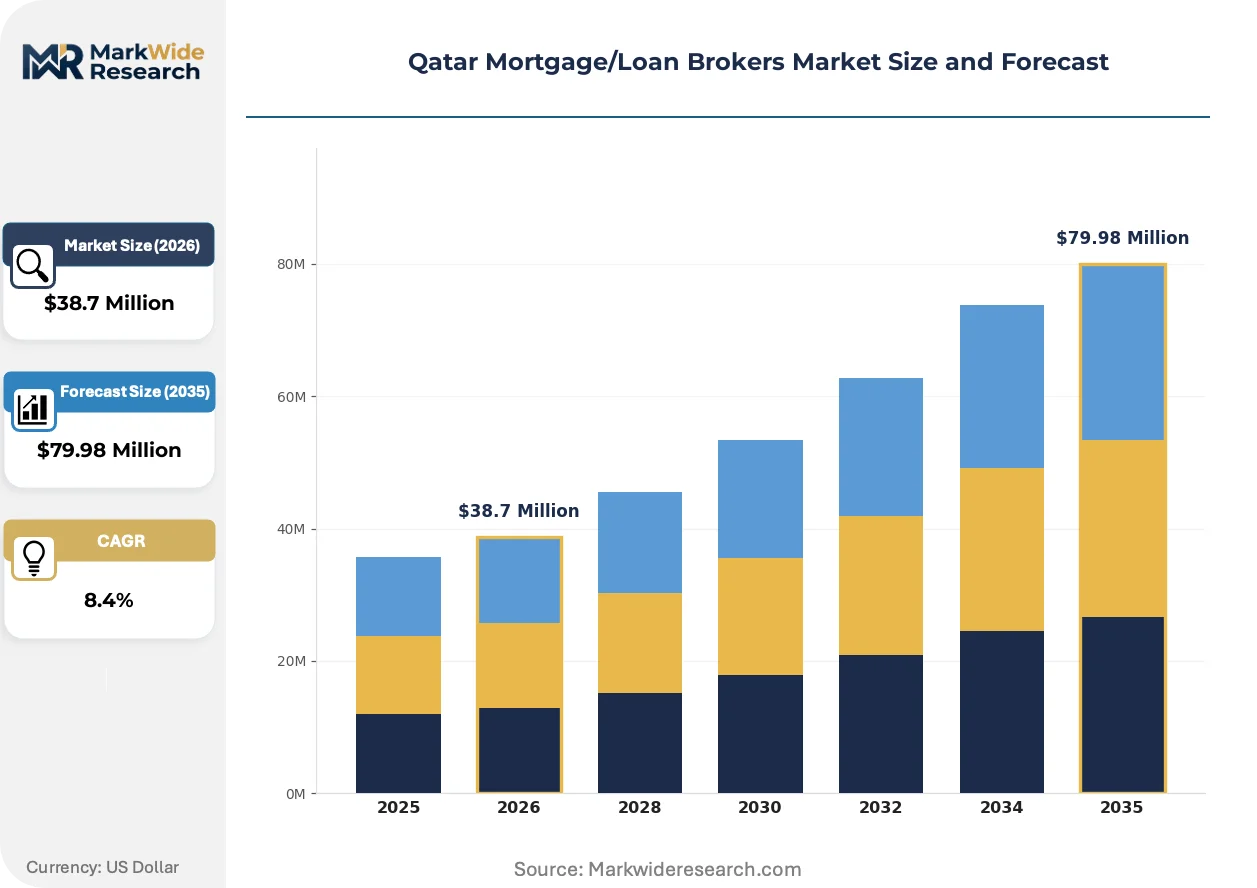
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $79.98 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Loans, Commercial Loans, Refinancing, Debt Consolidation Customer Type: First-Time Buyers, Homeowners, Investors, Corporates Loan Type: Fixed Rate, Variable Rate, Interest-Only, Balloon Payment Deposit Requirement: Low Deposit, No Deposit, Standard Deposit, High Deposit |
| Companies Covered | Qatar National Bank, Commercial Bank of Qatar, Doha Bank, Masraf Al Rayan, Qatar Islamic Bank, Ahli Bank, Qatar International Islamic Bank, Al Khaliji Commercial Bank, Barwa Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Mortgage/Loan Brokers Market Trends and Innovations
Digital origination platforms are compressing traditional broker value chains while regulatory data centralization is redefining risk assessment roles across Qatar's mortgage intermediary sector.
Artificial intelligence-driven credit scoring is converging with Qatar Credit Bureau data feeds to automate borrower-lender matching that previously required manual broker intervention. First-time buyers in Doha are adopting these platforms at accelerating rates. The structural consequence is compressing commissionable processing cycles toward documentation management rather than risk assessment.
Qatar Central Bank's tightened loan-to-value caps are mandating larger down payment buffers for residential purchases in West Bay and The Pearl-Qatar. The industrial consequence is shifting origination volume toward refinancing as earlier fixed-rate mortgages reset. Investor clients purchasing rental units are most affected, with broker channels responding by specializing in balloon payment restructuring.
Buyer concentration among Qatar's expatriate professional class is hardening as population inflows to Doha and Lusail outpace citizen household formation. Direct bank channels are capturing salaried segments through branch networks, while broker intermediation is retreating toward complex cases requiring multi-lender comparison. This pattern is most visible in the first-time buyer segment, where commission premiums persist despite digital platform encroachment.
Qatar Mortgage/Loan Brokers Market Segmentation
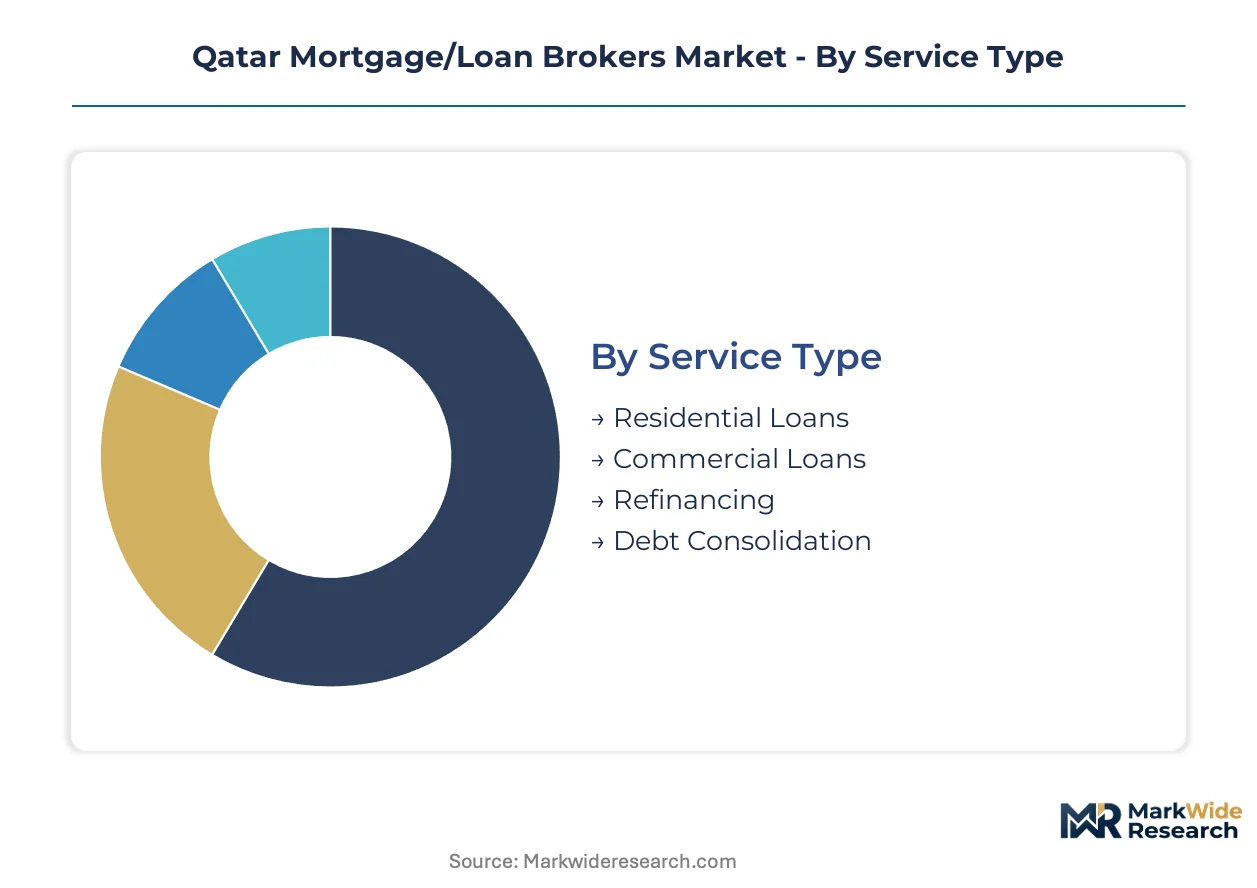
Segmentation in Qatar's mortgage brokerage market determines commission structures, documentation complexity, and regulatory compliance pathways. Each dimension carries distinct risk profiles and lender matching requirements that shape broker specialization strategies across Doha and Lusail.
Service Type:
Standardized transaction processing dominates residential origination while commercial and refinancing services demand bespoke structuring expertise across Qatar Central Bank reporting frameworks.
- Residential Loans:Off-plan property financing in West Bay and The Pearl-Qatar requires construction-phase milestone disbursement management. First-time expatriate buyers in Lusail are concentrating demand here as population inflows accelerate.
- Commercial Loans:Income-producing property assessments and corporate guarantor verification create elongated documentation cycles. Commercial Bank of Qatar anchors this segment through broker partnerships for non-salaried clients.
- Refinancing:Rate reset acceleration is redirecting borrower flow toward broker-assisted restructuring.
- Debt Consolidation:Multi-liability bundling for mid-income households faces Qatar Central Bank debt-burden threshold constraints.
Leading the category by volume: Residential Loans. Expanding most quickly: Refinancing.
Customer Type:
Commission premiums concentrate among complex cases requiring multi-lender comparison rather than salaried segments captured by direct bank channels.
- First-Time Buyers:Expatriate professionals in Doha generate the highest per-case broker commissions due to documentation intensity and lender education requirements. Qatar National Bank's branch network competes aggressively for this segment.
- Homeowners:Equity release and renovation financing in established districts like Msheireb Downtown favors relationship-driven broker retention.
- Investors:Rental unit purchasers favor balloon payment structures requiring specialized Shariah-compliant product matching.
- Corporates:Facility structuring for employee housing programs demands treasury coordination and bulk rate negotiation.
Dominant by revenue concentration: First-Time Buyers. Steepest expansion trajectory: Investors.
Loan Type:
Product divergence between Islamic and conventional lenders fragments matching efficiency while creating specialization opportunities in profit-rate calculation methodologies.
- Fixed Rate:Earlier fixed-rate mortgages resetting against rising base rates are compressing origination margins while redirecting volume toward refinancing channels.
- Variable Rate:Qatar Central Bank policy rate linkage creates repricing transparency preferred by salaried expatriates in Lusail.
- Interest-Only:Limited availability under Qatar Central Bank prudential guidelines restricts broker-eligible deal flow.
- Balloon Payment:Masraf Al Rayan's Shariah-compliant structures capture investor clients seeking rental yield optimization in Msheireb Downtown.
Commanding current volume: Fixed Rate. Gaining share fastest: Balloon Payment.
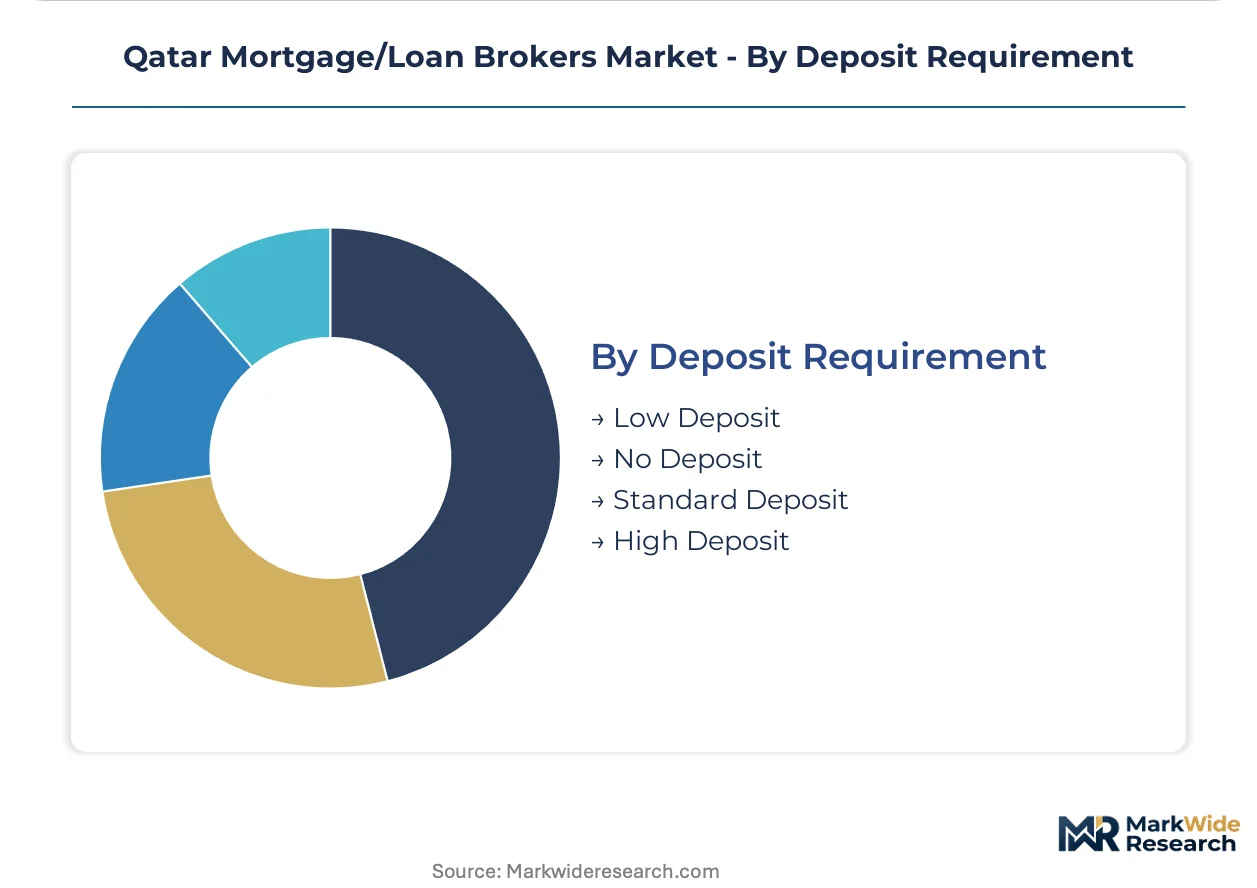
Deposit Requirement:
Qatar Central Bank loan-to-value caps are mandating larger down payment buffers, segmenting broker-eligible borrowers by liquidity access and reshaping origination toward high-deposit clients.
- Low Deposit:Qatar Central Bank maximum LTV ratios structurally constrain broker deal flow for mid-income expatriate households.
- No Deposit:Near-extinct product category following regulatory tightening.
- Standard Deposit:Conventional 20-25% down payment structures align with Qatar National Bank's salaried client origination.
- High Deposit:Ultra-high-net-worth segments in The Pearl-Qatar bypass traditional broker channels through private banking relationships.
Leading by transaction count: Standard Deposit. Shrinking fastest: No Deposit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for mortgage brokerage services concentrates in Qatar's metropolitan corridor. Expatriate professionals settling in Doha and Lusail are driving first-time buyer volumes. The Qatar Central Bank's regulatory framework shapes broker operations nationwide.
Doha
Expatriate professionals from Europe and South Asia dominate residential property searches in West Bay and Msheireb Downtown. The Qatar Central Bank's loan-to-value caps constrain maximum borrowing thresholds for mid-income households. Broker channels concentrate in the financial district, serving clients seeking refinancing as earlier fixed-rate mortgages reset.
Lusail
First-time buyers purchasing off-plan properties in Lusail Marina and Fox Hills are expanding broker commission pools. The Qatar Financial Centre Regulatory Authority administers Shariah compliance standards for Islamic product distribution. Construction-phase financing demands are clustering broker expertise around milestone disbursement management.
Al Wakrah
Mid-income expatriate families are seeking affordable housing alternatives south of Doha proper. Debt-burden ratio requirements from the Qatar Central Bank limit eligible deal flow for this segment. Local broker offices are positioning for spillover demand as Lusail price points escalate.
The Pearl-Qatar
Ultra-high-net-worth investors favor balloon payment structures for rental yield optimization on luxury units. AAOIFI guidelines shape profit-rate calculations for Masraf Al Rayan's Shariah-compliant products. Private banking relationships increasingly bypass traditional broker channels in this sub-market.
Al Khor
Industrial zone employees and energy sector workers are generating nascent residential mortgage demand. The Qatar Credit Bureau's centralized scoring systems are reducing manual broker intervention in risk assessment. Limited broker presence creates white space for digital platform expansion.
Qatar Mortgage/Loan Brokers Market Competitive Landscape
Doha-based institutions anchor one tier; specialists in Islamic finance hold differentiated positions in product structuring. The market presents a consolidated structure with tiered service capabilities across conventional and Shariah-compliant channels. Three archetypes dominate: universal banks with captive brokerage networks, Islamic banks with certified product specialists, and independent intermediaries focused on complex cases. Competitive moves center on digital pre-approval tool deployment and strategic partnerships for non-salaried client acquisition.
Among Doha-based financial institutions, Qatar National Bank, Commercial Bank of Qatar, and Masraf Al Rayan occupy anchor positions within their respective archetypes. Qatar National Bank exemplifies the universal bank model with branch network origination capacity. Commercial Bank of Qatar represents the conventional specialist approach through broker channel anchoring in commercial segments. Masraf Al Rayan sits within the Islamic finance tier, with profit-rate structures capturing investor demand for specialized refinancing products.
| Leading Market Players |
|---|
| Qatar National Bank |
| Commercial Bank of Qatar |
| Doha Bank |
| Masraf Al Rayan |
| Qatar Islamic Bank |
| Ahli Bank |
| Qatar International Islamic Bank |
| Al Khaliji Commercial Bank |
| Barwa Bank |
| Others |
Pricing and Supply Chain Analysis
Licensed mortgage broker concentration in Doha's financial district creates labor-cost differentials that widen pricing-tier spreads between premium advisory services and standardized transaction processing. Qatar Central Bank compliance certification requirements segment the workforce, with certified Islamic finance specialists commanding rate premiums against conventional loan processors.
Pricing Analysis
Volume concentrates in standardized residential origination while margins persist in complex refinancing restructuring. Three-tier pricing structure across premium advisory, standard processing, and economy digital-only levels separates bespoke Shariah-compliant structuring from automated pre-approval workflows. Pricing pressure stems from Qatar National Bank's branch network capturing salaried segments through direct origination. First-time buyers show highest price sensitivity; ultra-high-net-worth investors in The Pearl-Qatar demonstrate lowest sensitivity due to private banking alternatives.
Supply Chain Analysis
Qatar Financial Centre Regulatory Authority local-content mandates are reshaping sourcing toward domestically licensed compliance officers and Qatar Central Bank-certified risk assessors. Human capital draws from Qatar, UAE, and Saudi Arabia's Islamic finance training institutes. Technology infrastructure rests on proprietary banking APIs, Qatar Credit Bureau data feeds, and document management platforms. Single-source vulnerability concentrates in Qatar Central Bank reporting system access. Distribution runs through broker offices clustered in Doha's financial district and Lusail Marina development zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's mortgage brokerage market operates as a supply-constrained story where Qatar Central Bank licensing bottlenecks prop pricing for certified intermediaries. Capacity limitations in Shariah-compliant product expertise sustain margin premiums.
For Market Incumbents: Hedge against digital platform encroachment by deepening proprietary data integration with Qatar Credit Bureau systems and securing exclusive referral partnerships with non-salaried client specialists. Vertical integration into construction-phase milestone disbursement management for West Bay and Lusail off-plan properties defends commission pools against bank direct channels. For New Entrants and Emerging Players: Independent digital mortgage platforms represent the most penetrable channel partner type for market entry, particularly targeting mid-income expatriate households in Al Wakrah underserved by established broker networks. White space concentrates in self-employed client specialization and Al Khor industrial zone coverage where broker presence remains thin. For Investors and Strategic Acquirers: Re-rating potential sits with specialized Islamic finance brokerages given Qatar Financial Centre Regulatory Authority AAOIFI guideline expansion accelerating demand for certified profit-rate structuring expertise. Long-term viability favors acquisition targets with embedded Qatar Central Bank compliance infrastructure and construction-phase financing capabilities. Watch Qatar Credit Bureau centralization progress as inflection indicator for automated scoring displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Qatar Credit Bureau API Integration | Reduces documentation cycles through automated risk assessment layering above centralized scoring. |
| Shariah Certification Investment | Captures investor demand for AAOIFI-compliant balloon payment restructuring in Msheireb Downtown. |
| Non-Salaried Client Specialization | Targets self-employed expatriate segments generating commission premiums outside bank direct channels. |
| Construction-Phase Financing Expertise | Aligns broker capabilities with West Bay and Lusail off-plan property pipeline disbursement demands. |
| Digital Pre-Approval Platform Deployment | Compresses processing cycles for first-time buyers while preserving advisory margins on complex cases. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across mortgage broker principals, Qatar Central Bank compliance officers, Islamic finance product managers at Masraf Al Rayan and Qatar Islamic Bank, and real estate developers in Doha and Lusail. Secondary sources included Qatar Central Bank statistical bulletins, Qatar Financial Centre Regulatory Authority guideline releases, Qatar Credit Bureau disclosure frameworks, and property registration data from the Ministry of Justice. Bottom-up transaction volume estimates triangulated against top-down market sizing from banking sector disclosures.
Granularity-level modeling operated at service-type, customer-type, and loan-type intersections, with geographic segmentation across Doha, Lusail, Al Wakrah, The Pearl-Qatar, and Al Khor sub-markets. CAGRs derived from regression analysis against expatriate population inflows, Qatar Central Bank policy rate trajectories, and construction pipeline milestones. Forecast inputs incorporated Qatar Credit Bureau penetration rates and digital platform adoption curves among first-time buyers.
Caveats apply where Qatar Central Bank loan-to-value cap adjustments or Qatar Credit Bureau scoring algorithm updates could materially shift the outlook. Forecasts reflect assumptions around expatriate population stability and construction-phase financing demand continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Battery Leasing Service Market
Loans and Leasing
Europe Home Mortgage Finance Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
Montenegro Home Mortgage Finance Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Automobile Rental and Leasing Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
India Car Loan Market
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
Russia Auto Loan Market
Loans and Leasing
Vehicle Leasing Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
Asia-Pacific Mortgage/Loan Brokers Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
South Korea Car Loan Market