
 United States Digital Lending Market | 2026-2036
United States Digital Lending Market Size, Share, and Industry Trends Forecast 2026-2036
United States Digital Lending Market Analytics
Small enterprise borrowing is hardening as the fastest-expanding end-use vertical, displacing pure consumer origination in platform strategies. SoFi leverages its bank charter to sustain lower funding costs against non-depository competitors. Upstart anchors its position through AI-driven credit decisioning that extends beyond FICO-centric underwriting. Marcus by Goldman Sachs competes on brand strength and balance sheet depth, though it navigates strategic uncertainty following parent-company restructuring.
United States digital lending encompasses the automated origination, underwriting, and disbursement of credit through web-based interfaces and mobile applications, relying on API-connected data sources, machine learning risk models, and real-time identity verification to replace traditional branch-based processes. Its primary commercial purpose is reducing origination friction and marginal cost per loan while expanding credit access to thin-file borrowers. Personal loans and business loans occupy the deepest margin pools, with the former benefiting from consolidation of high-interest revolving debt and the latter capturing working-capital demand from digitally native SMBs. AI-driven solutions represent the fastest-growing technology segment as lenders deploy alternative data signals for default prediction.
The Consumer Financial Protection Bureau shapes demand through enforcement of fair lending algorithms and emerging open banking rules, while the SEC and state banking regulators constrain marketplace lending structures through investor-protection and licensing requirements. The OCC's fintech charter framework and patchwork state-level usury laws create divergent market access conditions across jurisdictions. Stakeholders must monitor how the CFPB's Section 1033 rulemaking on consumer data portability reshapes competitive moats built on proprietary data aggregation.
Market Dynamics
Embedded finance APIs are collapsing the boundary between banking infrastructure and non-financial platforms, forcing lenders to compete for distribution inside software ecosystems rather than through direct consumer acquisition.
Growth Catalysts
- Open Banking Data Portability:The CFPB's Section 1033 rulemaking mandates consumer-permissioned data sharing, eroding incumbent advantages built on proprietary credit files and enabling alternative underwriting models.
- SMB Embedded Finance:Vertical SaaS platforms in construction, healthcare, and logistics are integrating working-capital products at the point of invoice generation, capturing demand before traditional lenders reach borrowers.
- Real-Time Payments Infrastructure:The FedNow network's expansion eliminates settlement friction for loan disbursement and repayment, compressing origination-to-funding timelines from days to minutes.
Market Restraints
- State Usury Fragmentation:Patchwork interest-rate caps across California, New York, and Illinois create compliance complexity that prevents standardized national product offerings.
- Deposit Funding Disadvantage:Non-bank lenders face persistent cost-of-funds gaps against chartered institutions, squeezing net interest margins during rate volatility.
- Algorithmic Fair-Lending Scrutiny:The CFPB's adverse-action notification requirements for AI-driven credit decisions impose documentation burdens that slow model deployment cycles.
Strategic Opportunities
- Credit-Invisible Population:Thin-file borrowers in Texas and Florida—concentrated in gig-economy and immigrant communities—represent untapped origination volume for cash-flow-based underwriting.
- Climate-Resilient Lending:IRA-linked green-energy financing products for residential solar and efficiency retrofits open federally subsidized margin pools with lower default correlation.
- Payroll-API Integration:Direct connection to ADP, Gusto, and Rippling employment data streams enables income verification without borrower friction, reducing fraud and abandonment rates.
Industry Challenges
- Model Risk Management Talent:Shortage of quantitative analysts capable of validating machine-learning credit engines to regulatory standards delays product launches.
- Core Banking Integration Complexity:Legacy loan-servicing systems at mid-tier banks resist API connectivity, forcing expensive middleware development for partnership channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Digital Lending Market |
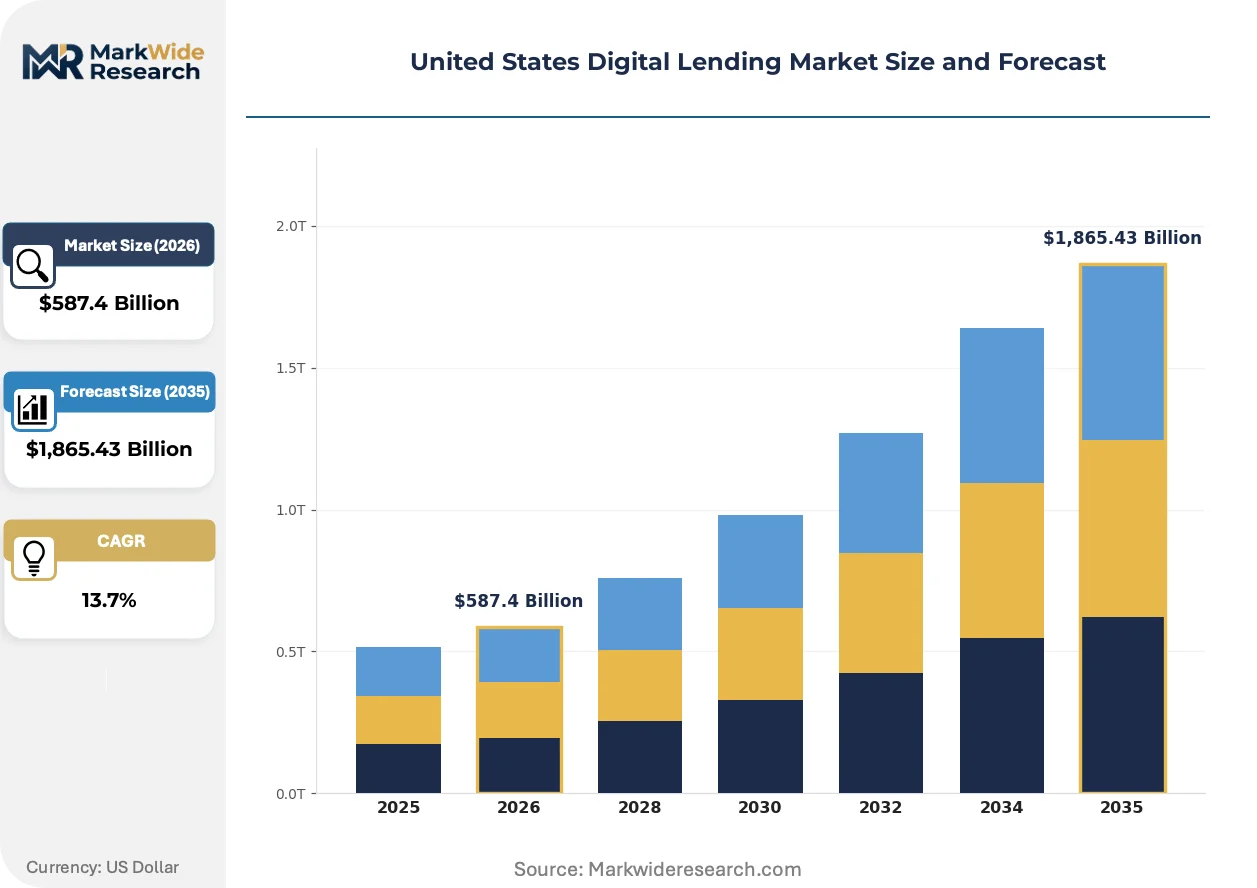
| Market Size in 2026 | $587.4 Billion |
| Market Size in 2035 | $1,865.43 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Loans, Business Loans, Student Loans, Mortgage Loans End User: Consumers, Small Enterprises, Large Corporations, Financial Institutions Technology: Mobile Applications, Online Platforms, AI-Driven Solutions, Blockchain Technology Service Type: Direct Lending, Peer-to-Peer Lending, Marketplace Lending, Online Loan Services |
| Companies Covered | Affirm, Marcus by Goldman Sachs, SoFi, Avant, LendingTree, LendingClub, OnDeck, Rocket Mortgage, Upstart, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Digital Lending Market Evolving Landscape
Artificial intelligence is penetrating every stage of the credit lifecycle, from acquisition targeting through collections, creating divergence between AI-native platforms and legacy processors still reliant on rules-based automation.
Machine-learning credit decisioning is rewriting the economics of subprime origination. These models ingest rent payments, utility histories, and cash-flow velocity to score borrowers outside FICO's reach. Subprime auto and personal lenders are deploying these systems fastest, cutting loss rates by identifying behavioral patterns invisible to traditional bureau data. The structural consequence is a compression of risk-based pricing bands, narrowing spreads between prime and near-prime tiers.
The CFPB's fair-lending algorithm enforcement is tightening documentation requirements for automated underwriting. Lenders must now produce adverse-action explanations for AI-driven denials that satisfy Equal Credit Opportunity Act standards. This regulatory pressure falls heaviest on marketplace lenders using black-box ensemble models, forcing migration toward interpretable architectures or human-in-the-loop review layers that slow throughput.
Borrowers are abandoning direct-to-lender applications in favor of comparison-marketplace intermediaries. Platforms like Credit Karma and LendingTree aggregate pre-qualified offers, commoditizing lender brands and compressing customer-acquisition costs to near-zero for dominant aggregators. This channel shift concentrates origination power in platforms controlling search visibility, most visible in California and Florida where digital-native consumers research extensively before committing.
United States Digital Lending Market Segmentation
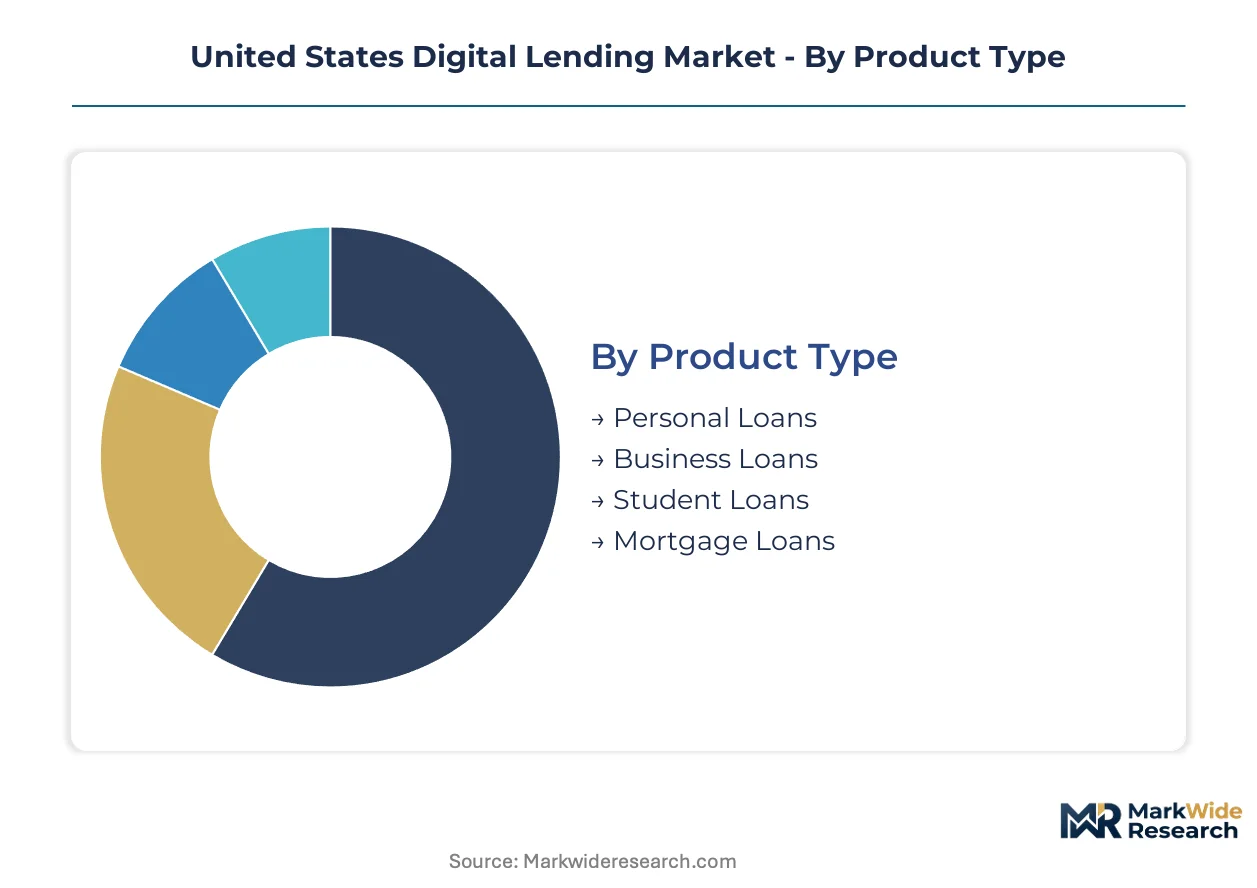
Segmentation reveals how digital lenders allocate capital across product architectures, customer risk profiles, and technology stacks. Each dimension carries distinct regulatory obligations and margin structures that shape platform economics.
Product Type:
Personal loans and business loans carry lighter federal chartering burdens than mortgage products, which face strict CFPB qualified-mortgage rules and state-level licensing reciprocity requirements.
- Personal Loans:Unsecured credit for debt consolidation and medical expenses dominates origination volume. Demand concentrates in Texas and Florida where thin-file borrowers seek alternatives to payday products.
- Business Loans:Working-capital products for SMBs integrate into QuickBooks and Shopify workflows. California's high fintech density drives adoption of revenue-based financing structures.
- Student Loans:Refinancing of federal education debt carries Department of Education compliance overhead. Volume has contracted as federal forbearance programs reduced refinance incentives.
- Mortgage Loans:Digital origination requires state-by-state mortgage banker licensing and TRID disclosure precision. Texas and Florida purchase markets sustain the deepest addressable pools.
Leading the category by volume: Personal Loans. Growing fastest: Business Loans.
End User:
Customer type determines underwriting data sources and acquisition channel economics, with small enterprises commanding premium pricing due to higher lifetime value and stickier platform relationships.
- Consumers:Individual borrowers access credit through mobile-first interfaces with FICO-plus-alternative-data scoring. Abandonment rates drop when income verification connects to payroll APIs.
- Small Enterprises:SMB borrowers in construction and healthcare verticals embed financing into SaaS invoice workflows. Embedded distribution in Texas and Florida captures demand before traditional banks respond.
- Large Corporations:Treasury departments deploy supply-chain finance and revolving credit facilities through proprietary banking portals. Custom API integration requirements extend sales cycles.
- Financial Institutions:Banks and credit unions white-label digital origination infrastructure to modernize legacy systems. Compliance documentation demands slow vendor selection processes.
Small Enterprises claim the steepest expansion trajectory as vertical SaaS distribution matures. Consumers retain the largest absolute origination base.
Technology:
Technology choice shapes capital efficiency, with AI-driven solutions demanding model-risk-management talent and blockchain deployments facing regulatory uncertainty around smart-contract enforceability.
- Mobile Applications:Native iOS and Android interfaces dominate consumer acquisition in California and Florida. Push-notification engagement drives repeat origination at lower CAC.
- Online Platforms:Browser-based origination retains strength in B2B segments where document upload and multi-user approval workflows matter. Desktop conversion rates exceed mobile for loans above $50,000.
- AI-Driven Solutions:Machine-learning underwriting ingests cash-flow velocity and rent-payment history to score credit-invisible populations. CFPB adverse-action rules impose documentation burdens on black-box models.
- Blockchain Technology:Smart-contract loan origination and tokenized loan syndication remain experimental. SEC and state regulators have not clarified securities treatment of decentralized lending protocols.
AI-Driven Solutions gain share fastest as lenders compete on approval speed. Mobile Applications anchor the largest deployment base.
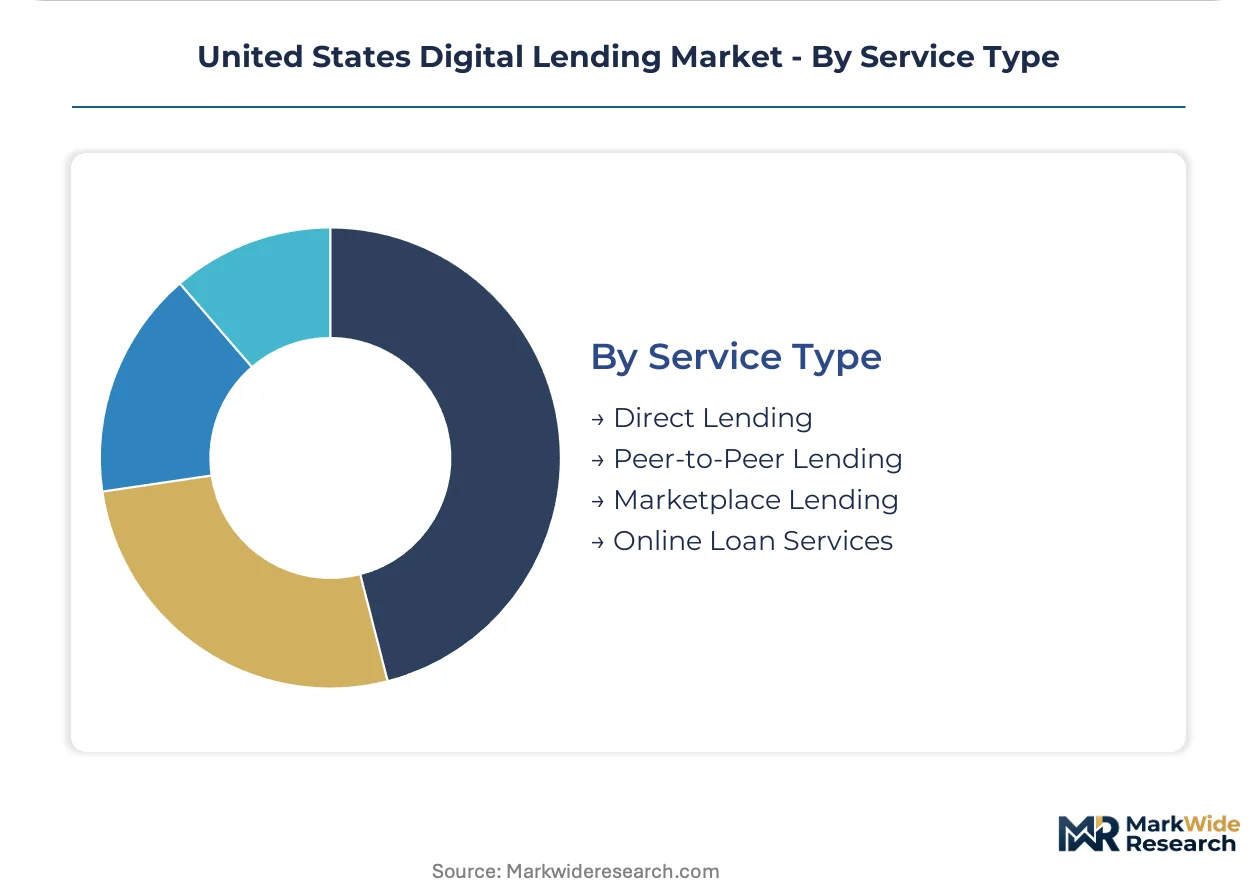
Service Type:
Service architecture determines balance-sheet exposure and regulatory classification, with marketplace lenders navigating SEC investor-protection rules that direct lenders avoid through deposit funding.
- Direct Lending:Balance-sheet origination by chartered banks and credit unions leverages lower cost of funds. SoFi's bank charter exemplifies the funding advantage.
- Peer-to-Peer Lending:Retail investor participation in loan funding has contracted as institutional capital dominates platforms. State usury caps limit product standardization.
- Marketplace Lending:Platform-mediated origination with third-party capital requires SEC registration and state lending licenses. Upstart's AI underwriting anchors competitive differentiation.
- Online Loan Services:Aggregator and comparison-site intermediation commoditizes lender brands. Credit Karma's pre-qualified offer engine concentrates consumer search behavior.
Direct Lending leads by deployed capital. Marketplace Lending climbs fastest as embedded finance APIs expand distribution reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zone tax incentives in Texas and Florida concentrate fintech infrastructure investment, drawing platform headquarters and engineering talent to Austin, Miami, and Dallas-Fort Worth corridors where state regulatory climates favor digital banking innovation.
Texas
Gig-economy workers and immigrant entrepreneurs in Houston and Dallas generate thin-file credit demand that cash-flow-based underwriting serves. The Texas Department of Banking maintains a fintech-friendly licensing framework that accelerates marketplace lender market entry. Austin's venture capital density supports embedded finance startups integrating lending into construction and logistics SaaS platforms.
Florida
Retiree debt consolidation and small-business working capital needs drive personal and commercial loan origination across Miami-Dade and Tampa Bay metros. State usury thresholds permit broader product standardization than California or New York, reducing compliance fragmentation. Miami's emerging status as a Latin American fintech hub attracts cross-border lending infrastructure investment.
California
Silicon Valley payroll-API providers and Los Angeles consumer-fintech density create upstream and downstream lending innovation clusters. The California Department of Financial Protection and Innovation enforces stricter usury interpretations than federal baseline, compressing margin structures for non-bank lenders. San Francisco's concentration of AI underwriting talent drives model development for alternative credit scoring.
New York
Wall Street institutional capital and regulatory sophistication make Manhattan the dominant marketplace lending securitization center. The New York State Department of Financial Services applies BitLicense-level scrutiny to fintech charters, extending licensing timelines. Brooklyn and Queens immigrant communities present credit-invisible borrower pools for rent-payment-history underwriting models.
Illinois
Chicago's middle-market commercial banking heritage translates into B2B embedded finance adoption in manufacturing and healthcare verticals. The Illinois Department of Financial and Professional Regulation coordinates with the CFPB on open banking compliance implementation. The city's payroll processor concentration enables direct employment-data connectivity for income verification APIs.
United States Digital Lending Market Competitive Landscape
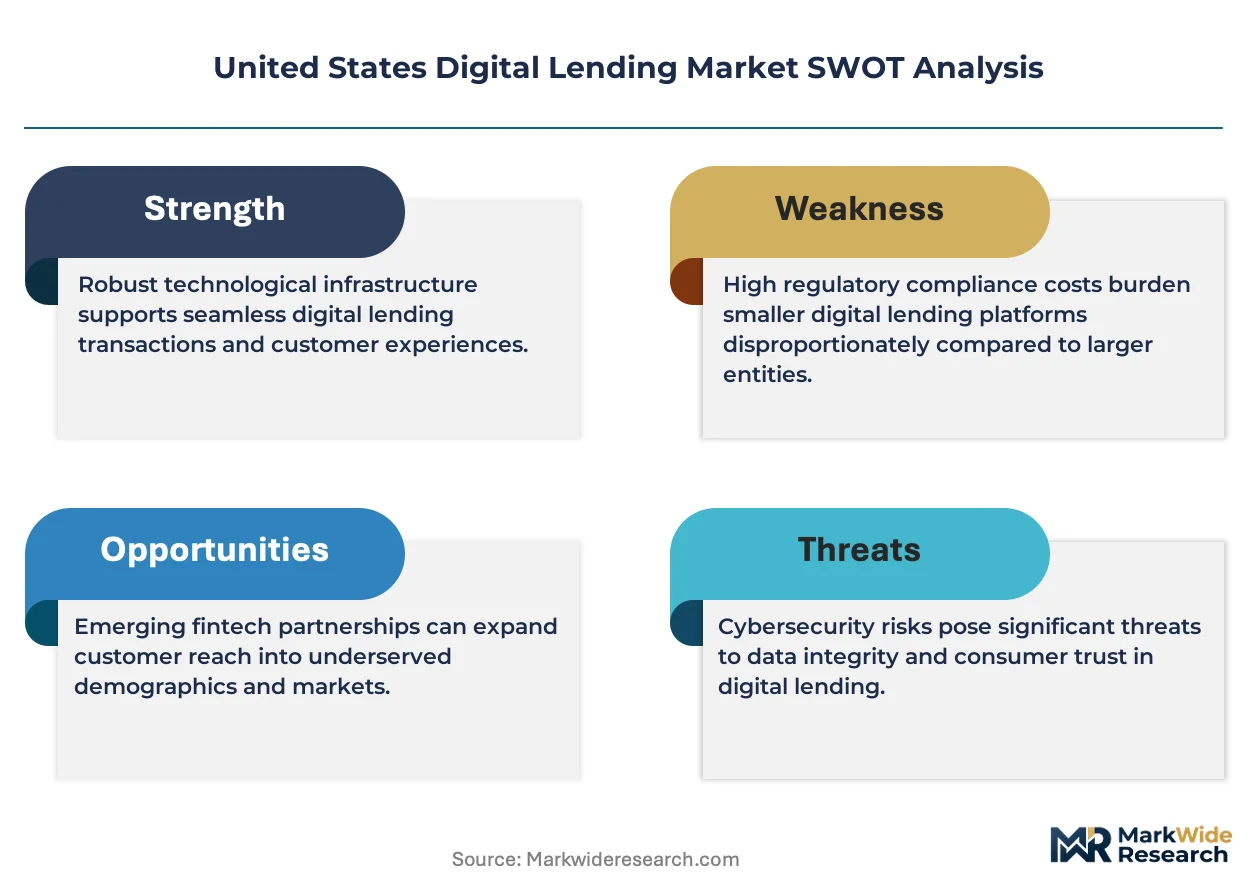
Branded specialists and contract manufacturers split share differently across segments, with chartered banks commanding funding-cost advantages and marketplace platforms winning on distribution velocity. The vendor base organizes around three strategic archetypes: deposit-funded institutions leveraging balance-sheet depth, AI-native underwriters competing on approval speed, and embedded-finance intermediaries capturing SaaS-integrated demand. Consolidation pressure intensifies as M&A activity concentrates origination scale and strategic partnerships embed lending into vertical software workflows.
Among the deposit-funded tier, SoFi and Marcus by Goldman Sachs exemplify chartered-institution positioning that compresses cost-of-funds spreads against non-bank competitors. Upstart occupies the AI-native archetype, its machine-learning underwriting representing the interpretability-versus-performance tension that CFPB fair-lending enforcement intensifies. LendingTree and LendingClub sit within the marketplace and peer-to-peer channels where aggregator economics commoditize lender brands and institutional capital displaces retail investor participation.
| Leading Market Players |
|---|
| Affirm |
| Marcus by Goldman Sachs |
| SoFi |
| Avant |
| LendingTree |
| LendingClub |
| OnDeck |
| Rocket Mortgage |
| Upstart |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up marketplace lenders concentrate origination infrastructure in Texas and Florida, compressing cost-of-funds spreads through balance-sheet scale while passing funding savings to prime borrowers as rate competition intensifies.
Pricing Analysis
Short lead-time funding commands rate premiums in the subprime personal loan tier, where borrowers prioritize disbursement speed over basis-point savings. Three-tier pricing structure across prime, near-prime, and subprime credit bands reflects FICO-plus-alternative-data scoring sophistication. Pricing pressure stems from deposit-funded institutions leveraging bank charters to undercut non-bank cost structures. Small enterprises show lowest price sensitivity due to embedded finance convenience, while thin-file consumers in Texas and Florida shop aggressively across comparison marketplaces.
Supply Chain Analysis
Reverse-logistics flows for loan documentation and identity verification center on API-connected data aggregators that recycle borrower information across multiple lender platforms. Origination technology draws from California's AI underwriting talent clusters, Texas's embedded finance SaaS developers, and New York's securitization infrastructure. Single-source vulnerability concentrates in payroll-API providers like ADP and Gusto, where connectivity interruptions stall income verification. Distribution runs through vertical SaaS platforms in construction and healthcare, bypassing traditional direct-to-consumer acquisition channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States digital lending market is becoming a vertical-integration race, with players pursuing upstream control over payroll-API data sources and downstream capture of embedded finance distribution to lock in origination economics.
For Market Incumbents: Cement deposit-funding advantages through bank charter expansion or credit union partnership structures, neutralizing the cost-of-funds gap that non-bank competitors face. Acquire AI underwriting talent in San Francisco and Austin to maintain approval-speed leadership against interpretable-model regulatory requirements. The CFPB's adverse-action documentation rules threaten black-box ensemble deployments.
For New Entrants and Emerging Players: AI-native cash-flow scoring offers entry into thin-file immigrant and gig-economy segments in Houston and Miami where traditional FICO coverage fails. Target construction and logistics vertical SaaS platforms in Texas for embedded working-capital products before incumbent banks establish API partnerships. Lead with payroll-API income verification to reduce fraud abandonment and accelerate time-to-yes.
For Investors and Strategic Acquirers: CFPB Section 1033 open-banking rulemaking finalization is the leading indicator that proprietary data moats will erode, shifting competitive advantage toward distribution control and underwriting speed. Favor platforms with embedded finance API penetration in high-growth verticals over pure direct-to-consumer originators. Monitor FedNow real-time payment adoption rates as a signal for disbursement-speed commoditization pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Bank Charter Acquisition | Deposit funding access compresses cost-of-funds spreads against marketplace competitors. |
| Payroll-API Integration | Direct ADP and Gusto connectivity eliminates borrower friction in income verification workflows. |
| Vertical SaaS Partnership | Embedded finance placement in QuickBooks and Shopify captures SMB demand before bank response. |
| AI Model Interpretability Investment | CFPB adverse-action compliance accelerates migration from black-box to explainable underwriting architectures. |
| Real-Time Payment Infrastructure | FedNow connectivity reduces origination-to-funding timelines from days to minutes for competitive differentiation. |
Research Methodology
Document review covered CFPB rulemaking dockets, SEC marketplace lending registration filings, and FedNow service deployment announcements, complemented by interviews with chief risk officers at digital lending platforms, open-banking compliance leads at data aggregators, and embedded finance partnership directors at vertical SaaS providers. Secondary validation drew from the Federal Reserve's Consumer Credit Panel, the Conference of State Bank Supervisors licensing databases, and earnings disclosures from chartered and non-bank lenders. Bottom-up origination volume estimates triangulated against top-down consumer credit flow data from the Federal Reserve Bank of New York.
Historical loan origination trajectories cross-referenced against panel input from platform executives and venture capital investors with fintech portfolio exposure. Segmentation modeling spanned product type, end-user category, technology deployment, and service architecture across the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory implementation timelines and embedded finance penetration curves. Forecast inputs incorporated CFPB Section 1033 compliance cost assumptions and real-time payment infrastructure adoption rates.
Several conditions sit outside the modeled scope, including state-level usury law changes, federal student loan policy shifts, and cryptocurrency-collateralized lending regulatory clarity. Forecasts reflect assumptions about open-banking data portability implementation and AI fair-lending enforcement intensity. Practitioners should monitor CFPB adverse-action guidance updates and FedNow transaction volume growth for early signals of competitive dynamics revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Used Car Financing Market
Loans and Leasing
Europe Auto Loan Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
US Home Equity Lending Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
Europe Home Mortgage Finance Market
Loans and Leasing
US Factoring Services Market
Loans and Leasing
US Mortgage/Loan Brokers Market
Loans and Leasing
Europe Syndicated Loans Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
Loan Management Software Market
Loans and Leasing
Cash Advance Services Market
Loans and Leasing
India Home Loan Market