
 Global Automotive Fleet Leasing Market | 2026-2036
Global Automotive Fleet Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Fleet Leasing Market Analysis
The capital-intensity divergence between full-service platform operators and asset-light brokers is unwinding competitive stability in fleet leasing. ALD Automotive leverages its captive finance relationships and multi-country servicing infrastructure to sustain pricing power across European corporate accounts. LeasePlan anchors its position through proprietary telematics platforms that control total cost of ownership calculations for multinational clients. Element Fleet Management dominates North American commercial fleet segments through maintenance-leasing bundling and centralized procurement systems.
Automotive fleet leasing denotes the contractual provision of vehicle fleets by lessors who retain asset ownership while lessees pay periodic fees covering depreciation, maintenance, and administrative services, with contracts typically specifying mileage thresholds, residual value guarantees, and service level agreements. The arrangement transfers balance sheet risk from operating companies to specialized financiers while embedding predictive maintenance algorithms and fuel management protocols. Operational lease structures command the largest revenue pool due to their prevalence among corporations seeking off-balance-sheet treatment and bundled service predictability. Full-service leasing represents the fastest-expanding service model as telematics integration and electrification maintenance complexity push fleet managers toward comprehensive outsourcing. Short-term leasing occupies niche margin pools in seasonal industries and project-based logistics where asset flexibility outweighs per-unit cost efficiency.
The EU Green Deal and its F-Gas Regulation for vehicle air conditioning systems, alongside the US EPA tailpipe emission standards and NHTSA corporate average fuel economy rules, are reshaping lessor procurement criteria toward zero-emission vehicle portfolios. EMA guidelines on commercial driver health monitoring and ISO fleet safety management standards further embed compliance costs into lease rate structures. Fleet managers must monitor battery residual value uncertainty and charging infrastructure coverage gaps as electrification commitments lock in long-dated asset decisions.
Market Dynamics
The electrification of commercial vehicle fleets is compressing residual value forecasting horizons and forcing lessors to rebuild underwriting models around battery degradation curves rather than traditional engine lifecycle economics.
Growth Catalysts
- EU Green Deal CO2 mandates:Binding emission targets for commercial vehicles are compelling corporate fleet managers to accelerate lease renewals toward zero-emission portfolios ahead of ownership depreciation cycles.
- Last-mile logistics expansion:E-commerce fulfillment networks across Germany, the United Kingdom, and the Netherlands are converting owned delivery van fleets to operational lease structures to match asset life with contract volatility.
- Predictive maintenance algorithms:Embedded telematics platforms now enable lessors to price maintenance risk with precision previously unavailable, expanding addressable market segments to mid-size fleets.
Market Restraints
- Lithium-ion battery cost volatility:Raw material price swings for cobalt and nickel directly compress lessor margins on electric vehicle portfolios where battery replacement represents the dominant residual risk.
- Charging infrastructure geographic gaps:Uneven fast-charging coverage across rural corridors in France, Spain, and Italy limits lessee operational flexibility and extends asset recovery timelines for lessors.
- F-Gas Regulation compliance costs:The EU's phasedown of hydrofluorocarbon refrigerants in vehicle air conditioning systems adds retrofit and certification expenses that embed into lease rate structures without corresponding revenue uplift.
Strategic Opportunities
- India commercial fleet formalization:The country's PLI scheme for automotive manufacturing is drawing multinational lessors to establish captive finance operations serving the unorganized logistics sector's transition to structured leasing.
- Battery residual value insurance products:Convergence of telematics data streams with actuarial modeling enables lessors to offer guaranteed buyback programs that transfer degradation risk to third-party underwriters.
- ISO 55000 fleet asset management adoption:Multinational corporations implementing standardized physical asset governance frameworks are outsourcing entire fleet lifecycle management to full-service lessors with certified compliance capabilities.
Industry Challenges
- Electrification technician scarcity:The shortage of certified high-voltage battery diagnosticians and repair specialists extends maintenance turnaround times and inflates service level agreement penalties.
- Legacy fleet management system integration:Established telematics platforms from incumbent lessors resist API interoperability with emerging charging network management software, fragmenting data visibility for lessees operating mixed-powertrain fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Fleet Leasing Market |
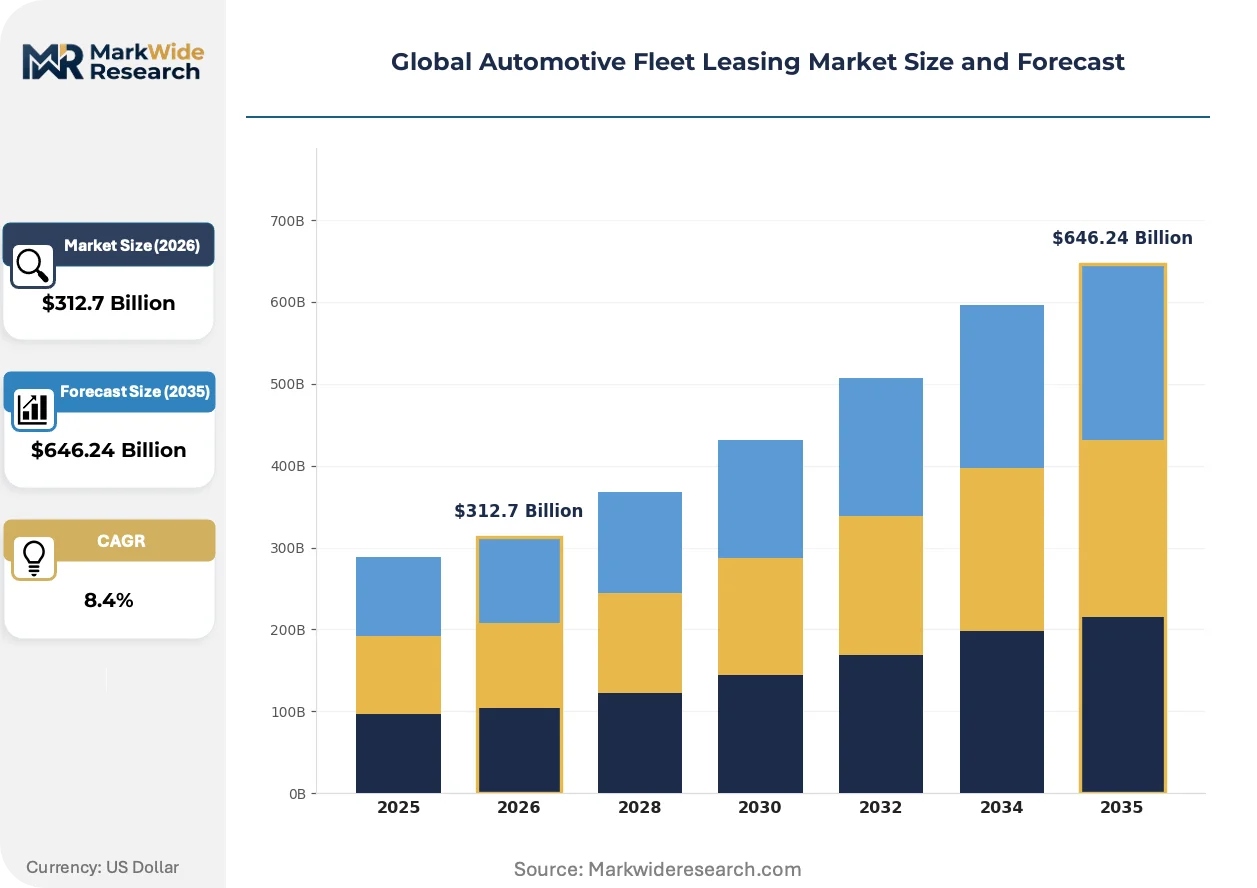
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $646.24 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Cars, Trucks, Vans, SUVs Lease Type: Operational Lease, Financial Lease, Closed-End Lease, Open-End Lease Client Type: Small Businesses, Corporations, Government Agencies, Nonprofits Service Model: Full-Service Leasing, Maintenance Leasing, Mileage Leasing, Short-Term Leasing |
| Companies Covered | ALD Automotive, LeasePlan, Arval, Enterprise Holdings, Hertz, Avis Budget Group, Sixt Leasing, Europcar, Element Fleet Management, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Fleet Leasing Market Emerging Trajectories
Telematics-enabled usage-based pricing models are displacing fixed-mileage contracts across premium fleet segments, embedding real-time driving behavior data directly into rate calculations and residual value adjustments.
Artificial intelligence-driven predictive maintenance is fragmenting traditional service bundling economics. Machine learning models analyzing engine telemetry, brake wear patterns, and tire pressure anomalies now enable lessors to unbundle maintenance from base lease rates and price coverage at individual vehicle level. Large pharmaceutical and medical device sales fleets in Germany and Switzerland are adopting these granular contracts to match service costs with actual utilization intensity rather than fleet-wide averages.
The US EPA tailpipe emission standards and NHTSA corporate average fuel economy rules are tightening in parallel, creating a regulatory pincer that eliminates compliance flexibility for lessors holding mixed-powertrain portfolios. Fleet managers must now procure zero-emission vehicles at scale to avoid penalties that would erode lease portfolio returns. California's Advanced Clean Trucks regulation is transmitting compliance pressure through national lessor procurement decisions, affecting vehicle allocation to Texas and Florida operations.
Subscription-style short-term fleet access is displacing traditional multi-year operational leases in project-based industries. Construction and event logistics operators in the United Kingdom and Australia now prefer 3-6 month rolling contracts with embedded vehicle swap rights over fixed-term commitments. This demand compression forces lessors to absorb higher remarketing frequency and residual value volatility in exchange for premium per-month rates.
Global Automotive Fleet Leasing Market Segmentation
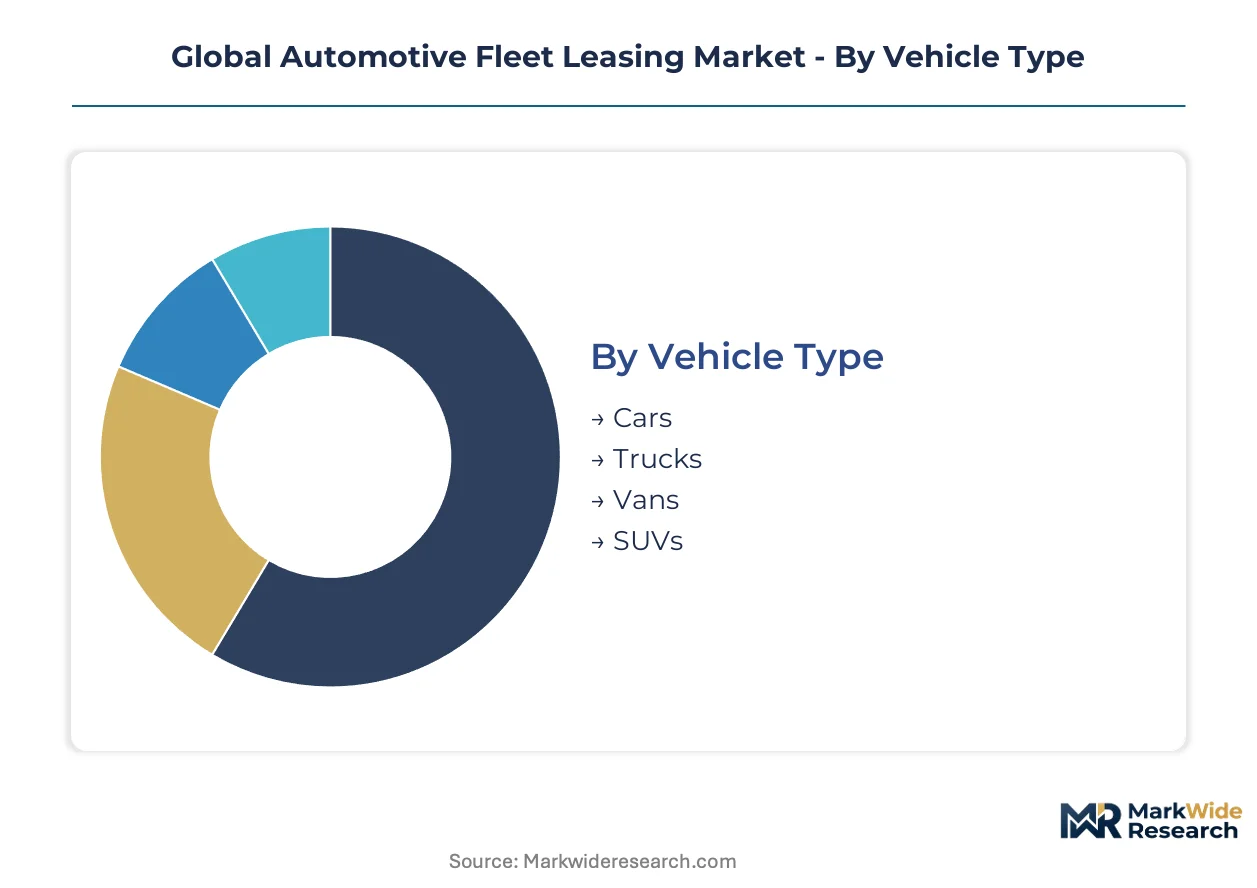
Fleet leasing segmentation reveals how lessors align contract structures with divergent asset risk profiles and regulatory compliance burdens across vehicle categories and client sophistication levels.
Vehicle Type:
EU Green Deal CO2 mandates and US EPA tailpipe standards differentiate procurement economics by vehicle class, with emission thresholds tightening fastest for commercial van and truck categories.
- Cars:Sedan and hatchback fleets dominate corporate employee mobility programs in Germany and Switzerland, where ISO fleet safety standards and EMA commercial driver health guidelines embed compliance costs into lease rate calculations for mid-size enterprises.
- Trucks:Heavy-duty commercial vehicle leasing concentrates in North American long-haul corridors and German freight corridors, with NHTSA corporate average fuel economy rules forcing accelerated zero-emission procurement timelines that compress residual value forecasting horizons.
- Vans:Last-mile delivery operators across the United Kingdom and Netherlands favor operational lease structures for compact commercial vans to match asset life with contract volatility in e-commerce fulfillment networks.
- SUVs:Executive fleet segments in Switzerland and Austria show concentrated demand for premium SUV leasing where bundled maintenance and telematics integration justify higher per-unit rates.
Cars handle the majority of throughput; trucks are gaining share fastest as logistics electrification mandates intensify.
Lease Type:
Accounting treatment and residual risk allocation separate lease structures, with off-balance-sheet preferences driving divergence between corporate treasury strategies and small business ownership retention.
- Operational Lease:Lessors retain full ownership and residual risk while bundling maintenance, insurance, and administrative services, making this structure dominant among German and French corporations seeking predictable operating expenditures and balance sheet efficiency under EU accounting standards.
- Financial Lease:Lessees assume depreciation risk and typically record assets on-balance-sheet, appealing to US-based mid-market firms in Texas and Florida that prioritize ownership transfer at contract completion over service bundling.
- Closed-End Lease:Fixed residual value guarantees protect lessees from market volatility, attracting risk-averse government agencies in Canada and Australia with strict procurement compliance requirements.
- Open-End Lease:Lessees bear residual value risk with greater mileage flexibility, serving project-based industries in the United Kingdom where construction and event logistics demand short-term asset access with swap rights.
Operational lease commands the dominant revenue pool; full-service operational structures are expanding most quickly as electrification maintenance complexity rises.
Client Type:
Procurement sophistication and contract scale determine service bundling depth, with multinational corporations extracting premium telematics integration unavailable to fragmented small business accounts.
- Small Businesses:Price-sensitive operators across India's unorganized logistics sector and Australia's regional freight networks favor basic financial leases with minimal service inclusion, though PLI scheme formalization is drawing structured leasing penetration.
- Corporations:Multinational enterprises in Germany and Switzerland implement ISO 55000 fleet asset management frameworks, outsourcing entire lifecycle management to full-service lessors with certified compliance capabilities and multi-country servicing infrastructure.
- Government Agencies:Public sector fleets in the United States and Canada face NHTSA and EPA procurement mandates that accelerate zero-emission vehicle adoption through centralized operational lease contracts with residual value guarantees.
- Nonprofits:Mission-driven organizations prioritize cost predictability over asset flexibility, concentrating in European markets where EU Green Deal emission targets align with organizational sustainability commitments.
Corporations generate the dominant contract value; small businesses are the fastest-growing client tier as emerging market formalization accelerates.
Service Model:
Telematics maturity and electrification maintenance complexity are fragmenting traditional bundling economics, with predictive algorithms enabling granular pricing previously unavailable to mid-size fleets.
- Full-Service Leasing:Comprehensive outsourcing covering acquisition, maintenance, fuel management, and remarketing dominates among pharmaceutical sales fleets in Germany and Switzerland, where AI-driven predictive maintenance models price coverage at individual vehicle level rather than fleet-wide averages.
- Maintenance Leasing:Service-only contracts layered over lessee-owned assets appeal to specialized operators in France and Spain with in-house procurement capabilities but insufficient technical staff for high-voltage battery maintenance.
- Mileage Leasing:Usage-based pricing models with embedded telematics are displacing fixed-mileage contracts across premium segments in the United Kingdom, with real-time driving behavior data feeding directly into rate calculations and residual value adjustments.
- Short-Term Leasing:Subscription-style 3-6 month rolling contracts with vehicle swap rights serve construction and event logistics in Australia, forcing lessors to absorb higher remarketing frequency in exchange for premium per-month rates.
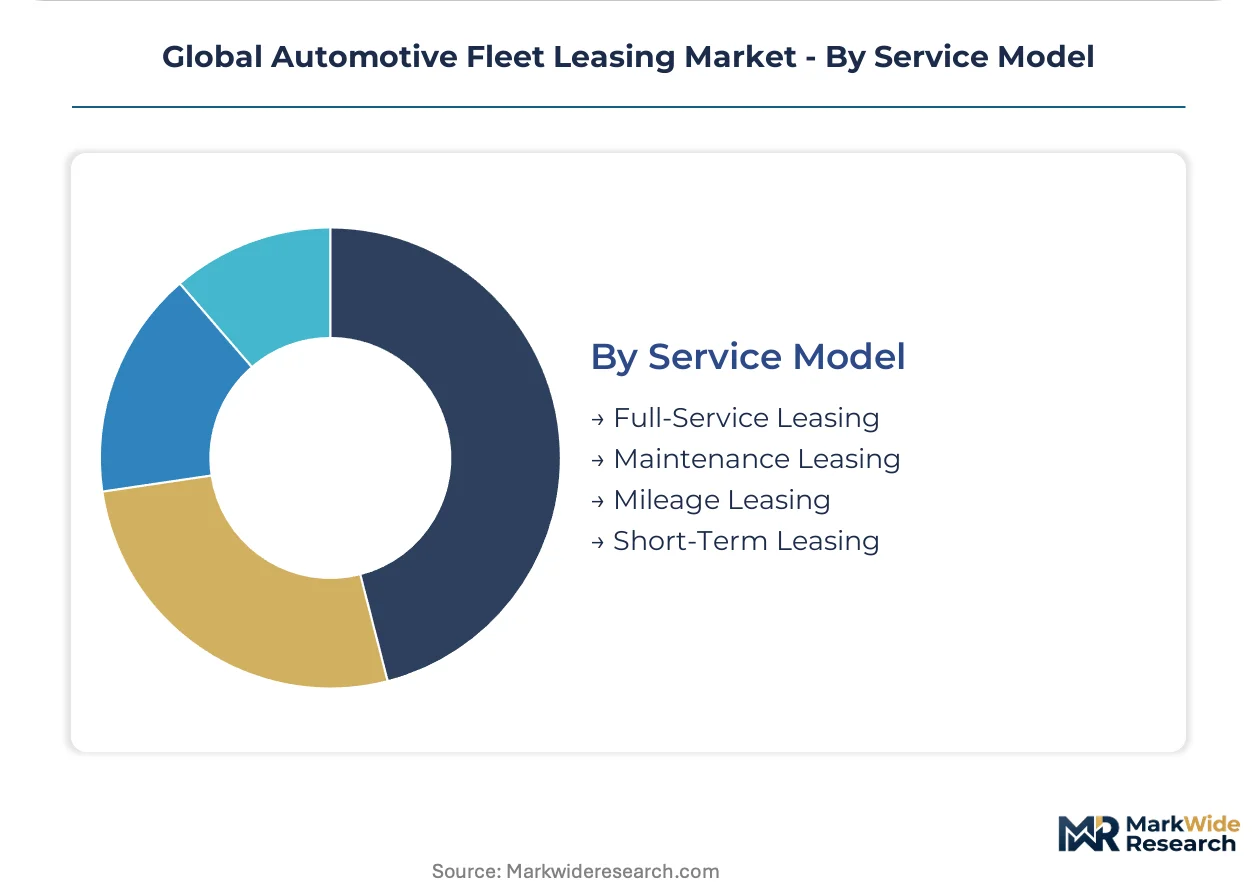
Full-service leasing captures the largest revenue share; short-term structures are climbing the fastest as project-based industries reject multi-year commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes fleet leasing as a balance-sheet efficiency tool for corporate treasury departments, while the United States treats it as a procurement mechanism for logistics operators seeking maintenance bundling. India approaches the product as a formalization pathway for unorganized commercial transport. This consumption-mix differential shapes how lessors configure service bundles and residual risk models across markets.
United States
Long-haul freight corridors and last-mile delivery networks drive commercial van and truck leasing demand across Texas and Florida. NHTSA corporate average fuel economy rules and EPA tailpipe emission standards force accelerated zero-emission procurement timelines. California's Advanced Clean Trucks regulation transmits compliance pressure through national lessor allocation decisions, affecting vehicle distribution to Texas and Florida operations.
Germany
Corporate fleet renewal cycles favor operational lease structures over outright ownership among mid-size enterprises and multinational headquarters. EU Green Deal CO2 mandates for commercial vehicles accelerate electrification commitments ahead of traditional depreciation cycles. The Rhine-Ruhr industrial corridor and Stuttgart automotive cluster concentrate full-service leasing demand from pharmaceutical sales fleets and manufacturing logistics operations.
United Kingdom
E-commerce fulfillment networks across Greater London and the Midlands convert owned delivery van fleets to operational lease structures. The F-Gas Regulation phases down hydrofluorocarbon refrigerants in vehicle air conditioning systems, adding retrofit costs that embed into lease rate structures. Construction and event logistics operators in Manchester and Birmingham prefer short-term rolling contracts with vehicle swap rights over fixed-term commitments.
India
The unorganized logistics sector in Maharashtra and Gujarat transitions toward structured leasing as the PLI scheme for automotive manufacturing draws multinational lessor investment. The country's national automotive regulator enforces commercial vehicle safety standards that formalize fleet management practices. Mumbai and Ahmedabad industrial zones concentrate emerging demand for captive finance operations serving small freight operators.
Australia
Project-based industries in New South Wales and Victoria drive subscription-style short-term fleet access with 3-6 month rolling contracts. The country's national transport safety authority enforces commercial driver fatigue management standards that embed compliance monitoring into lease service bundles. Sydney and Melbourne construction logistics clusters absorb higher remarketing frequency in exchange for premium per-month rates and asset flexibility.
Global Automotive Fleet Leasing Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding multi-country servicing infrastructure and captive finance relationships that sustain pricing power across corporate accounts. The specialist tier fragments across telematics-enabled maintenance providers and regional asset-light brokers competing on transaction velocity. Three archetypes dominate: full-service platform operators bundling predictive maintenance algorithms, financial lease providers prioritizing ownership transfer economics, and short-term subscription specialists serving project-based industries. Consolidation pressure manifests through telematics platform acquisitions and charging infrastructure partnerships rather than horizontal merger activity.
Among Europe-based integrated lessors, ALD Automotive and LeasePlan exemplify the full-service platform archetype through multi-country servicing infrastructure and proprietary telematics capabilities. Element Fleet Management anchors the North American commercial fleet segment. These three occupy positions where scale-driven procurement systems and centralized maintenance bundling create defensive moats against asset-light broker competition.
| Leading Market Players |
|---|
| ALD Automotive |
| LeasePlan |
| Arval |
| Enterprise Holdings |
| Hertz |
| Avis Budget Group |
| Sixt Leasing |
| Europcar |
| Element Fleet Management |
| Others |
Supply Flow & Price Mechanics
Multi-country servicing infrastructure and captive finance relationships at scale operators like ALD Automotive compress per-unit cost bases while elevating price floors for asset-light brokers competing on transaction velocity. This scale concentration permits bundled service premiums in German corporate accounts while forcing margin compression among regional specialists lacking centralized procurement systems.
Pricing Analysis
After-sales revenue from predictive maintenance algorithms and residual value guarantees now drives lifetime value more than base lease rates. Three-tier pricing structure across premium full-service, standard operational, and economy financial lease levels stratifies by telematics integration depth and electrification readiness. Pricing pressure stems from lithium-ion battery cost volatility compressing margins on electric vehicle portfolios. Small freight operators in India's unorganized logistics sector exhibit highest price sensitivity, while multinational pharmaceutical sales fleets in Switzerland accept premium rates for ISO 55000-certified compliance capabilities.
Supply Chain Analysis
Inventory lead times for high-voltage battery systems and specialized electrification components now exceed traditional engine lifecycle procurement cycles by significant margins. Vehicle manufacturing concentrates in Germany, China, and Mexico, with battery cell production anchored in South Korea and Japan. Raw material dependencies for cobalt, nickel, and lithium carbonate expose lessors to commodity price swings. Single-source vulnerability for certified high-voltage battery diagnosticians extends maintenance turnaround times. Distribution runs through centralized procurement systems at integrated lessors and fragmented broker networks serving regional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet leasing functions as a service-attach opportunity where predictive maintenance algorithms and charging infrastructure management expand recurring revenue faster than vehicle hardware margins. Full-service bundling now captures value previously lost to third-party service providers.
For Market Incumbents: Compound pricing power through deeper captive finance relationships and multi-country servicing infrastructure expansion. Consolidate telematics platform capabilities to defend against asset-light brokers exploiting API fragmentation. Prioritize certified high-voltage technician training programs to reduce service level agreement penalty exposure.
For New Entrants and Emerging Players: Anchor in India's PLI scheme formalization corridor serving Maharashtra and Gujarat small freight operators transitioning from unorganized ownership. Target battery residual value insurance products where telematics data convergence enables guaranteed buyback programs. Deploy direct digital channels bypassing incumbent dealer networks.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-service platform operators with ISO 55000 certification capabilities and proprietary telematics infrastructure. Long-term viability favors integrated lessors with backward integration into charging infrastructure partnerships. Watch electrification procurement mandate acceleration across EU Green Deal jurisdictions as portfolio allocation inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Embedded predictive maintenance algorithms enable individual vehicle-level pricing previously unavailable to mid-size fleets. |
| Charging Infrastructure Partnership | Strategic alliances with fast-charging network operators close geographic coverage gaps limiting rural corridor asset recovery. |
| Battery Supply Agreement | Long-term cobalt and nickel offtake contracts hedge raw material volatility compressing electric vehicle portfolio margins. |
| ISO 55000 Certification Program | Standardized physical asset governance frameworks attract multinational corporations outsourcing entire fleet lifecycle management. |
| Geographic Manufacturing Footprint | Captive finance operations in India and Southeast Asia capture formalizing logistics sector transition from unorganized ownership. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with fleet procurement directors, telematics platform engineers, captive finance executives, and aftermarket service heads; and secondary validation through vehicle production databases, IHS Markit registration data, SEC filings from listed lessors, and EU regulatory mandate documentation. Bottom-up fleet size estimates by vehicle class and propulsion architecture triangulated against top-down market value reconstruction.
Across the projection horizon, the analytical framework modeled segmentation dimensions including vehicle type, lease structure, client sophistication tier, and service bundling depth. CAGRs derived from historical trajectory analysis adjusted for electrification procurement mandate acceleration and emerging market formalization patterns. Forecast inputs incorporated battery degradation curve modeling and charging infrastructure deployment timelines by national corridor.
Material uncertainties — regulatory mandate acceleration or delay, battery residual value volatility, and charging infrastructure coverage gaps — sit outside the modeled envelope. Forecasts reflect documented assumptions about electrification adoption curves and technician certification expansion rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Asset-Based Lending Market
Loans and Leasing
Auto Finance Market
Loans and Leasing
Asia-Pacific Car Loan Market
Loans and Leasing
UK Home Equity Lending Market
Loans and Leasing
Global Automotive Rental and Leasing Market
Loans and Leasing
India Home Loan Market
Loans and Leasing
France Mortgage/Loan Brokers Market
Loans and Leasing
North America Mortgage/Loan Brokers Market
Loans and Leasing
North America Motorcycle Loan Market
Loans and Leasing
Unsecured Business Loans Market
Loans and Leasing
UK Mortgage / Loan Broker Market
Loans and Leasing
Asia-Pacific Mortgage/Loan Brokers Market
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
Debt Financing Market
Loans and Leasing
France Auto Loan Market