
 Japan Auto Loan Market | 2026-2036
Japan Auto Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Auto Loan Market Insights
JIS Q 27001 information security certification is reorganizing which lenders qualify for direct manufacturer partnerships. Toyota Financial Services leverages its captive finance structure to sustain preferential access to dealership networks. Mitsubishi UFJ Financial Group anchors wholesale funding advantages through its megabank balance sheet. ORIX Corporation differentiates via diversified leasing-to-loan conversion programs across commercial fleets.
Japan auto loans constitute secured and unsecured credit instruments collateralized by vehicle titles, with loan-to-value ratios typically ranging from 70% to 90% depending on borrower credit tiers and vehicle depreciation curves; their commercial purpose centers on enabling vehicle acquisition while generating interest income and origination fee revenue for lenders. Dealer financing occupies the dominant margin pool due to captive finance arms controlling point-of-sale access, while fixed-rate products lead volume as borrowers seek payment predictability amid monetary policy transitions. Used car buyer segments show structural acceleration as vehicle lifespans extend and certified pre-owned programs expand.
METI vehicle electrification directives and FSA consumer lending guidelines jointly shape product design, interest rate disclosure standards, and green loan eligibility criteria across Japanese auto finance. The Banking Act and Money Lending Business Act impose borrower protection protocols that constrain aggressive underwriting practices. Stakeholders must monitor how JFSA digital lending sandbox approvals and carbon-neutral vehicle subsidy shifts redistribute competitive advantage between traditional banks and non-bank specialists.
Market Dynamics
Vehicle electrification mandates from METI are restructuring lender-borrower relationships across Japan, forcing traditional auto finance products to accommodate battery-electric vehicle depreciation curves and green loan eligibility criteria that diverge sharply from internal combustion engine collateralization practices.
Growth Catalysts
- FSA Digital Lending Sandbox:Regulatory approvals for algorithmic credit scoring are expanding non-bank participation in point-of-sale financing. Digital-first lenders now qualify for direct manufacturer partnerships previously reserved for megabank subsidiaries.
- Tokyo-Osaka Urban Corridors:First-time buyer concentration in these prefectures sustains fixed-rate product demand as younger borrowers prioritize payment predictability over rate optimization. Dealer financing networks concentrate origination volume along these transport arteries.
- Certified Pre-Owned Programs:Extended vehicle lifespans and manufacturer-backed used car warranties are accelerating loan origination in secondary markets. Lenders are developing specialized LTV models for depreciated asset collateral.
Market Restraints
- Negative Interest Rate Legacy:Prolonged Bank of Japan monetary easing compressed net interest margins across deposit-funded lenders. Margin recovery lags policy normalization, constraining aggressive pricing for market share.
- Captive Finance Concentration:Toyota Financial Services and Honda Finance control dominant dealership network access. Independent lenders face structural exclusion from point-of-sale origination at volume-brand retailers.
- JIS Q 27001 Certification Barriers:Information security compliance costs disproportionately burden mid-tier regional banks. Certification requirements favor megabank and captive scale advantages in direct manufacturer partnerships.
Strategic Opportunities
- Kyushu and Tohoku Underpenetration:Rural prefectures exhibit lower auto loan density relative to vehicle registration rates. Regional non-bank specialists can establish branch-light digital origination models outside Tokyo-Osaka corridors.
- Commercial Fleet Electrification:METI carbon-neutral vehicle subsidies create dedicated green loan products for logistics operators. Leasing-to-loan conversion structures align with corporate fleet procurement cycles.
- Blockchain Title Registration:Distributed ledger integration with vehicle registration systems is compressing collateral verification timelines. Early adopters gain operational efficiency in secured lending documentation.
Industry Challenges
- EV Residual Value Uncertainty:Battery degradation modeling lacks standardized depreciation curves. Lenders struggle to price risk for collateral where secondary market liquidity remains untested.
- Legacy Core System Integration:Mainframe-dependent regional banks face technical debt in deploying real-time digital origination. API connectivity with dealership management systems requires substantial middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Auto Loan Market |
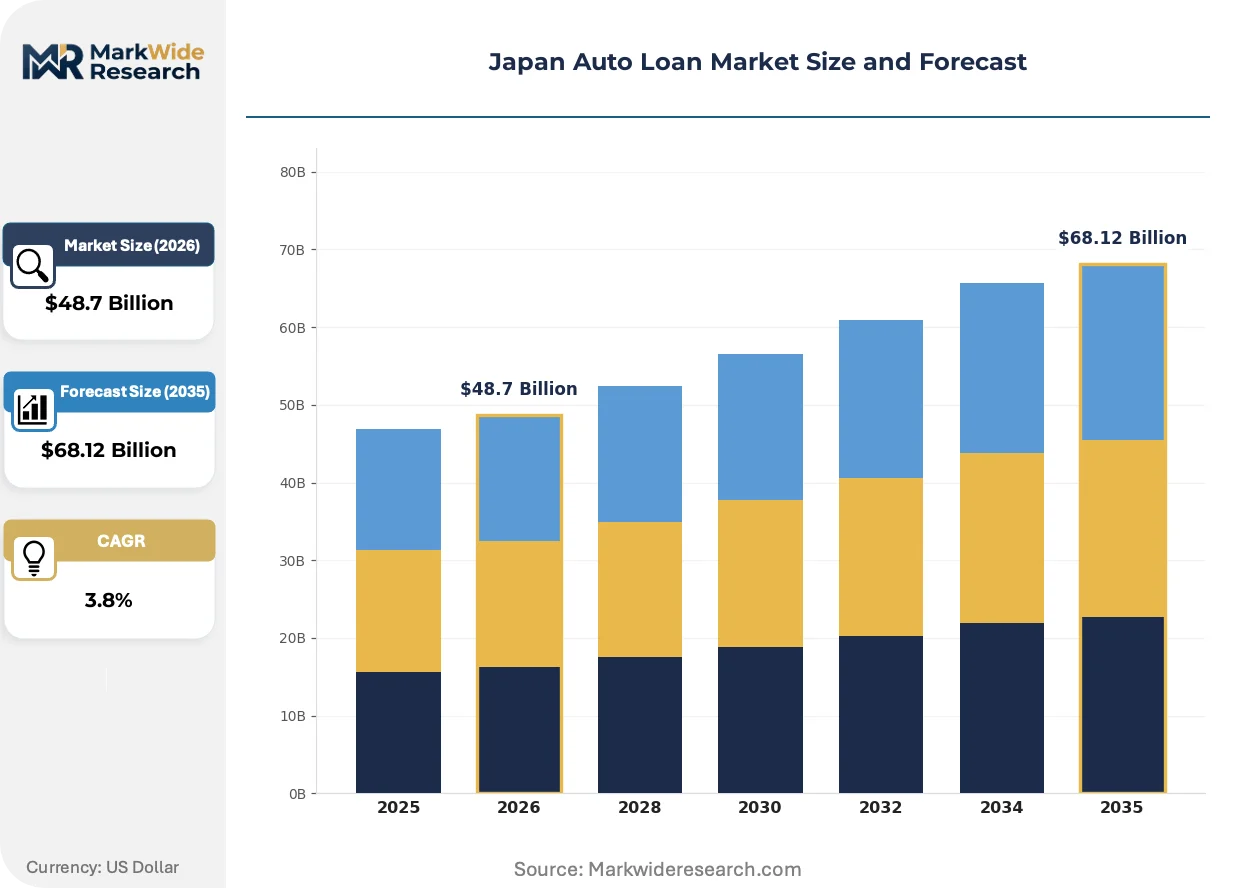
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $68.12 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Secured Loans, Unsecured Loans, Personal Loans, Dealer Financing Borrower Profile: First-Time Buyers, Existing Owners, Business Customers, Used Car Buyers Interest Rate Type: Fixed Rate, Variable Rate, Discounted Rate, Floating Rate Payment Plan: Monthly Installments, Quarterly Payments, Balloon Payment, Deferred Payment |
| Companies Covered | Toyota Financial Services Corporation, Nissan Financial Services Co., Ltd., Honda Financial Services, Orient Corporation, Mitsubishi UFJ Financial Group, Sumitomo Mitsui Financial Group, Mizuho Financial Group, ORIX Corporation, Bank of Kyoto, Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Auto Loan Market Trends and Innovations
Digital origination platforms are compressing loan approval timelines from days to minutes, forcing incumbent lenders to reconstruct customer acquisition infrastructure around mobile-first interfaces rather than branch-based relationship banking.
Embedded finance APIs are miniaturizing the auto loan origination process into dealership point-of-sale systems. Tier-2 and Tier-3 dealers in Hokkaido and Shikoku are adopting white-label lending modules at accelerating rates. This technology is miniaturizing the traditional role of branch-based loan officers into software-mediated credit decisions that execute during vehicle configuration.
METI's vehicle electrification directives now mandate standardized battery health disclosure in used vehicle transactions. The policy creates collateral transparency obligations that reshape LTV calculation methodologies for secondary market financing. Certified pre-owned programs in Kanagawa and Aichi prefectures are restructuring documentation requirements to comply.
Subscription-to-ownership conversion models are fragmenting traditional auto loan demand into shorter-term mobility contracts. Urban millennials in Tokyo and Osaka increasingly initiate vehicle relationships through flexible-term leases that convert to purchase. Fleet operators in Osaka Prefecture now pilot these structures for commercial vehicle procurement before committing to secured term debt.
Japan Auto Loan Market Segmentation
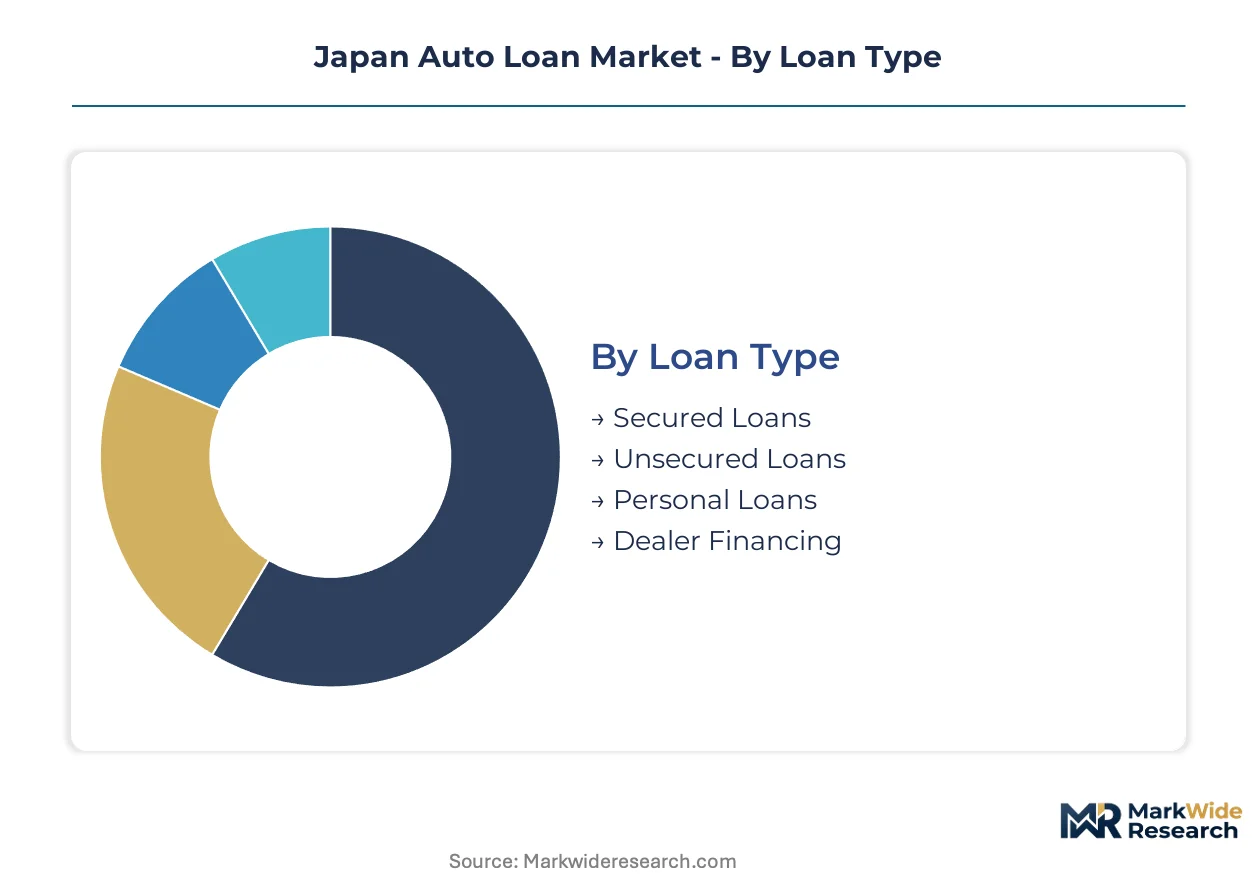
Auto loan segmentation in Japan determines which lender types control origination economics. Channel access varies sharply across loan structures, borrower profiles, and payment terms, with captive finance arms and megabank subsidiaries dominating specific segment-channel pairings.
Loan Type:
Channel concentration diverges sharply across collateralization structures, with dealer-captive networks controlling secured origination while independent non-banks penetrate unsecured niches.
- Secured Loans:Vehicle title collateralization dominates Tokyo-Osaka corridor origination through manufacturer-captive finance arms. Toyota Financial Services and Honda Finance leverage dealership exclusivity to sustain preferential point-of-sale access.
- Unsecured Loans:Signature-based credit instruments bypass collateral registration complexity. Regional banks and digital-first non-banks compete in this segment through mobile origination platforms outside captive-controlled dealer networks.
- Personal Loans:General-purpose consumer credit repurposed for vehicle acquisition flows through branch-based relationship banking.
- Dealer Financing:Point-of-sale captive products integrate directly with vehicle configuration systems at volume-brand retailers.
By volume, Secured Loans lead. By growth pace, Dealer Financing is ahead.
Borrower Profile:
Customer lifecycle positioning determines origination channel selection, with first-time buyer acquisition concentrating through digital interfaces and fleet operators accessing specialized commercial desks.
- First-Time Buyers:Credit-thin younger borrowers in urban prefectures drive fixed-rate product demand through mobile-first platforms. FSA digital lending sandbox approvals enable algorithmic scoring for this previously underserved segment.
- Existing Owners:Repeat borrowers with established credit histories access preferential rates through relationship banking channels.
- Business Customers:Corporate fleet operators in Osaka Prefecture utilize leasing-to-loan conversion structures aligned with procurement cycles.
- Used Car Buyers:Secondary market participants benefit from METI-mandated battery health disclosure standards for electrified vehicles.
First-Time Buyers command the largest origination volume. Used Car Buyers are expanding most quickly.
Interest Rate Type:
Monetary policy transition risk shapes borrower preferences, with payment predictability commanding premium pricing in rate-sensitive segments.
- Fixed Rate:Rate-locked terms dominate Tokyo-Osaka urban corridors where younger borrowers prioritize budget certainty over optimization. Negative interest rate legacy compression constrains lender pricing flexibility.
- Variable Rate:Benchmark-linked structures appeal to rate-sensitive borrowers with refinancing capability.
- Discounted Rate:Promotional pricing tied to manufacturer incentive programs flows through captive finance channels.
- Floating Rate:Short-term benchmark exposure concentrates in commercial fleet refinancing.
Fixed Rate products lead by volume. Variable Rate offerings are gaining share fastest.
Payment Plan:
Cash flow engineering differentiates lender product suites, with balloon structures aligning commercial fleet economics and deferred terms capturing seasonal income borrowers.
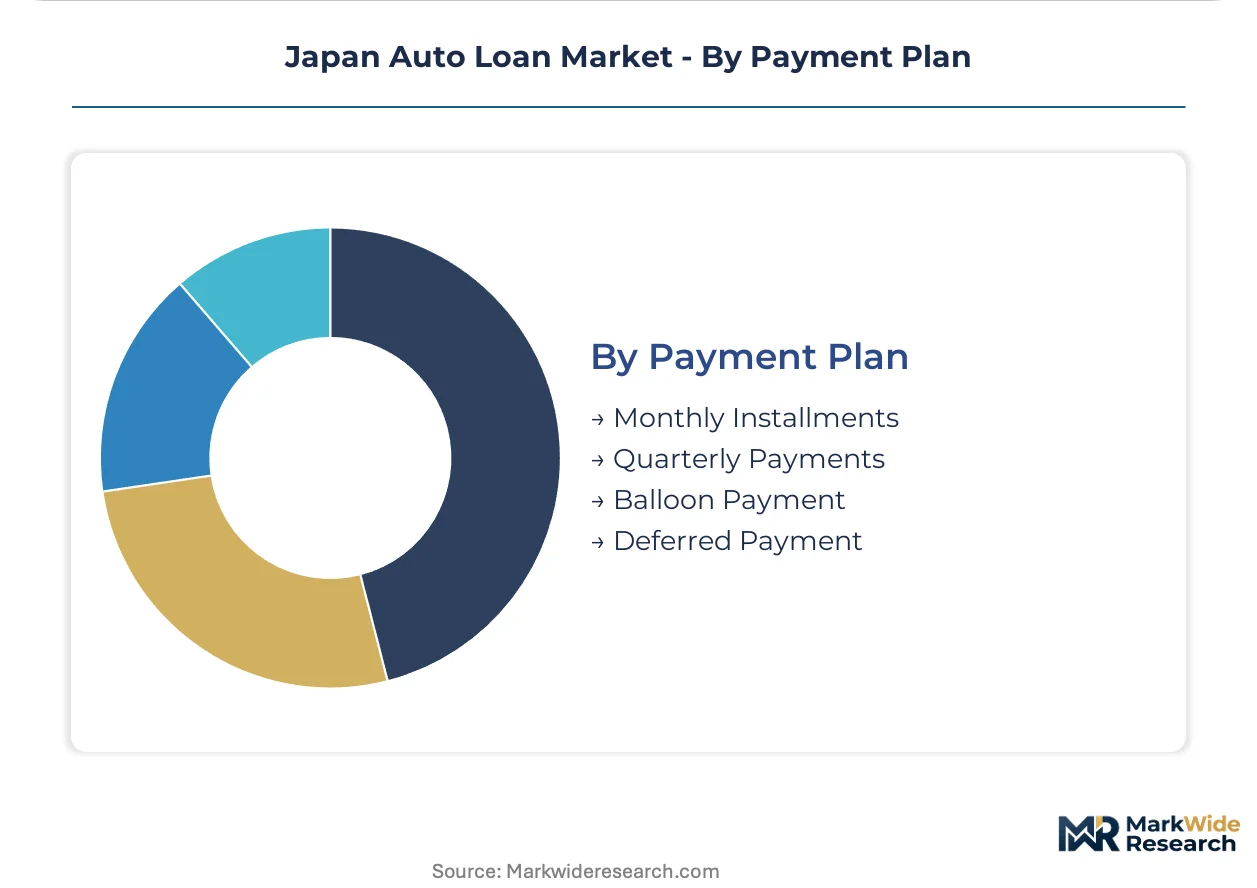
- Monthly Installments:Standard amortization structures dominate retail origination through all channels.
- Quarterly Payments:Seasonal cash flow alignment targets agricultural and tourism-dependent borrowers in Kyushu and Hokkaido.
- Balloon Payment:Residual value financing structures concentrate in commercial fleet electrification programs leveraging METI carbon-neutral subsidies.
- Deferred Payment:Grace period structures attract bonus-dependent salary workers in manufacturing-heavy Aichi and Kanagawa prefectures.
Monthly Installments lead by volume. Balloon Payment plans show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI vehicle electrification subsidies and FSA digital lending approvals are redistributing origination volume across Japan's prefectural markets, with urban corridors consolidating fixed-rate demand while rural regions present branch-light expansion targets.
Kanto/Tokyo
First-time buyer concentration in Tokyo, Kanagawa, and Saitama prefectures sustains fixed-rate product dominance through mobile-first platforms. METI green loan eligibility criteria channel electrified vehicle financing through captive dealer networks concentrated in the capital region. Toyota Financial Services and Honda Finance anchor point-of-sale origination across Greater Tokyo dealership clusters.
Kansai/Osaka
Commercial fleet operators in Osaka, Kyoto, and Hyogo prefectures drive leasing-to-loan conversion structures aligned with corporate procurement cycles. FSA digital lending sandbox approvals enable algorithmic credit scoring for logistics sector borrowers. ORIX Corporation leverages its diversified platform to capture fleet electrification demand across the Kansai industrial belt.
Chubu/Nagoya
Manufacturing-heavy Aichi and Gifu prefectures generate deferred payment product demand from bonus-dependent salary workers at Toyota and supplier networks. JIS Q 27001 certification requirements filter direct manufacturer partnerships toward megabank subsidiaries with compliance scale. Mitsubishi UFJ Financial Group anchors wholesale funding advantages through regional branch density.
Kyushu
Lower auto loan density relative to vehicle registration rates creates digital origination opportunities for non-bank specialists in Fukuoka and Saga prefectures. Quarterly payment structures align with agricultural and tourism-dependent seasonal cash flows. Regional lenders face JIS Q 27001 compliance cost barriers that favor branch-light market entry models.
Hokkaido
Tier-2 and Tier-3 dealers in Sapporo and Asahikawa are adopting embedded finance APIs for white-label lending modules. Extended vehicle lifespans accelerate certified pre-owned program expansion in secondary markets. Battery health disclosure mandates for electrified used vehicles reshape LTV calculations for depreciated asset collateral.
Japan Auto Loan Market Competitive Landscape
Player mix skews toward captive finance arms and megabank subsidiaries, with dealer network exclusivity creating tiered origination access. Toyota Financial Services and Honda Finance control dominant point-of-sale channels at volume-brand retailers. Three archetypes define competitive positioning: manufacturer-captive lenders with dealership exclusivity, megabank subsidiaries with balance sheet scale, and diversified non-bank specialists with leasing conversion capabilities. Strategic moves concentrate on digital origination platform deployment and green loan product development for electrified vehicle segments.
Within the captive finance tier, Toyota Financial Services Corporation and Nissan Financial Services Co., Ltd. represent manufacturer-integrated origination models that leverage point-of-sale exclusivity. Among diversified non-bank specialists, ORIX Corporation occupies a position exemplifying leasing-to-loan conversion expertise across commercial fleet segments. Mitsubishi UFJ Financial Group anchors the megabank subsidiary archetype through wholesale funding advantages and JIS Q 27001 compliance scale.
| Leading Market Players |
|---|
| Toyota Financial Services Corporation |
| Nissan Financial Services Co., Ltd. |
| Honda Financial Services |
| Orient Corporation |
| Mitsubishi UFJ Financial Group |
| Sumitomo Mitsui Financial Group |
| Mizuho Financial Group |
| ORIX Corporation |
| Bank of Kyoto, Ltd. |
| Others |
Pricing and Supply Chain Analysis
Fixed-rate contract structures dominate Tokyo-Osaka corridor origination, locking in predictable funding costs for deposit-funded lenders while capping margin recovery potential as Bank of Japan policy normalization lags. This contractual rigidity binds pricing power to wholesale funding access, megabank balance sheet scale, and captive finance dealership exclusivity.
Pricing Analysis
Certification level under JIS Q 27001 creates the primary spread between megabank subsidiaries and regional competitors in direct manufacturer partnerships. Three-tier pricing structure across premium captive products, standard bank offerings, and economy non-bank alternatives stratifies by point-of-sale access and balance sheet depth. Cost compression in variable-rate tiers is intensifying because FSA digital lending sandbox approvals expand algorithmic scoring competition. First-time buyers in urban prefectures show highest price sensitivity, while commercial fleet operators prioritize payment flexibility over rate optimization.
Supply Chain Analysis
Port congestion at Yokohama and container availability constraints on Asia-Japan trade lanes elevate inbound documentation costs for vehicle collateral verification systems. Wholesale funding draws from Tokyo money markets, megabank interbank networks, and corporate bond issuance concentrated among Mitsubishi UFJ Financial Group and Sumitomo Mitsui Financial Group. Single-source vulnerability exists in dealer management system software controlled by Toyota Financial Services and Honda Finance. Distribution runs through captive-controlled dealership networks, independent broker channels, and emerging embedded finance APIs at Tier-2 retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan auto lending sits in early-cycle expansion as METI electrification mandates and FSA digital lending approvals accelerate product innovation and borrower segment penetration beyond traditional captive-dominated channels.
For Market Incumbents: Shield point-of-sale exclusivity through accelerated JIS Q 27001 certification investment and deeper API integration with dealership management systems. Defensive consolidation of wholesale funding advantages becomes critical as negative interest rate legacy compression constrains pricing flexibility against digital-first entrants. Vertical integration into battery health verification services for used electrified vehicle collateral reinforces LTV model differentiation. For New Entrants and Emerging Players: Differentiate on algorithmic credit scoring capabilities validated through FSA digital lending sandbox approvals to penetrate first-time buyer segments in Tokyo-Osaka corridors. White-space targets cluster in Kyushu and Tohoku rural prefectures where auto loan density lags vehicle registration rates and JIS Q 27001 compliance costs burden regional banks. Branch-light digital origination models with quarterly payment structures aligned to agricultural cash flows offer viable go-to-market positioning. For Investors and Strategic Acquirers: Capital is best deployed toward diversified non-bank specialists with leasing-to-loan conversion expertise and commercial fleet electrification exposure across the analysis window. Acquisition target archetypes include regional non-banks with established rural branch networks and embedded finance API platforms serving Tier-2 dealer segments. The signal to watch is FSA expansion of digital lending sandbox approvals to algorithmic scoring for thin-file borrowers, which would accelerate competitive displacement of deposit-funded incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Green Loan Product Development | METI carbon-neutral vehicle subsidies channel dedicated electrified vehicle financing through compliant lender balance sheets. |
| Digital Origination Platform Deployment | FSA sandbox approvals enable algorithmic credit scoring that compresses approval timelines from days to minutes. |
| JIS Q 27001 Certification Investment | Information security compliance unlocks direct manufacturer partnerships previously reserved for megabank subsidiaries. |
| Leasing-to-Loan Conversion Structuring | Commercial fleet procurement cycles align with corporate borrower cash flow engineering requirements. |
| Blockchain Title Registration Integration | Distributed ledger connectivity with vehicle registration systems compresses collateral verification timelines. |
Research Methodology
Operator-level perspectives from auto finance product managers, dealership operations directors, FSA regulatory affairs specialists, and commercial fleet procurement officers anchored the qualitative base. Secondary validation drew from Bank of Japan monetary policy statements, METI electrification subsidy disclosures, FSA consumer lending guidelines, and vehicle registration databases. Bottom-up origination volume modeling triangulated against top-down macroeconomic scenario analysis.
Sensitivity analysis across interest rate trajectory assumptions, electrification adoption curves, and digital lending penetration rates informed projection robustness. Segmentation dimensions modeled encompass loan type, borrower profile, interest rate structure, and payment plan configuration alongside regional prefectural clustering. CAGRs derived from historical origination velocity patterns adjusted for policy transition effects and technology adoption S-curves. Forecast inputs included battery-electric vehicle depreciation curve development and embedded finance API adoption rates at Tier-2 dealerships.
The analysis sits within stated boundaries; outcomes outside sustained Bank of Japan policy normalization, METI subsidy continuity, and FSA regulatory sandbox expansion would require recalibration. Forecasts reflect documented assumptions regarding electrified vehicle residual value stabilization and dealer network exclusivity persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
US Auto Loan Market
Loans and Leasing
Asia-Pacific Car Loan Market
Loans and Leasing
NPL Servicing Market
Loans and Leasing
Brazil Home Equity Lending Market
Loans and Leasing
Loan Management Software Market
Loans and Leasing
Battery Leasing Service Market
Loans and Leasing
Asia-Pacific Used Car Financing Market
Loans and Leasing
Payday Loans Market
Loans and Leasing
Embedded Lending Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
Europe Syndicated Loans Market
Loans and Leasing
North America Mortgage/Loan Brokers Market
Loans and Leasing
Europe Used Car Financing Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
Unsecured Business Loans Market